
 Immunocytokines Market | 2026-2036
Immunocytokines Market Size, Share, and Industry Trends Forecast 2026-2036
Immunocytokines Market Outlook
A shift from single-source cytokine supply to multi-source antibody-cytokine fusion partnerships is hardening across the immunocytokines landscape. Philogen S.p.A. anchors its position through proprietary tumor-targeting platforms in Europe. Merck KGaA leverages integrated biologics manufacturing to sustain cytokine payload scale. Novartis competes via deep oncology pipeline assets that extend into cytokine engineering.
Immunocytokines are engineered biologics combining antibody-mediated targeting with cytokine signaling, typically constructed as fusion proteins where tumor-specific monoclonal antibodies carry interleukin or interferon payloads to concentrate immune activation at disease sites. Their primary purpose centers on redirecting systemic cytokine toxicity into localized anti-tumor responses, improving therapeutic indices beyond what unconjugated cytokines achieve. The bi-specific antibodies segment leads current clinical development pipelines due to dual-targeting flexibility, while cytokine fusion proteins represent the fastest-growing category as manufacturers refine linker stability and payload release kinetics. Subcutaneous injection delivery dominates patient preference and outpatient economics, though intravenous infusion retains share in hospital-based oncology administration.
FDA breakthrough therapy designation and EMA priority medicines pathways compress development timelines and reshape market access dynamics for immunocytokine developers. ISO 10993 biocompatibility standards and ICH Q5D cell-line qualification requirements govern manufacturing quality and cross-border supply eligibility. Stakeholders must monitor evolving FDA guidance on complex biologic characterization as agency expectations for cytokine payload consistency tighten.
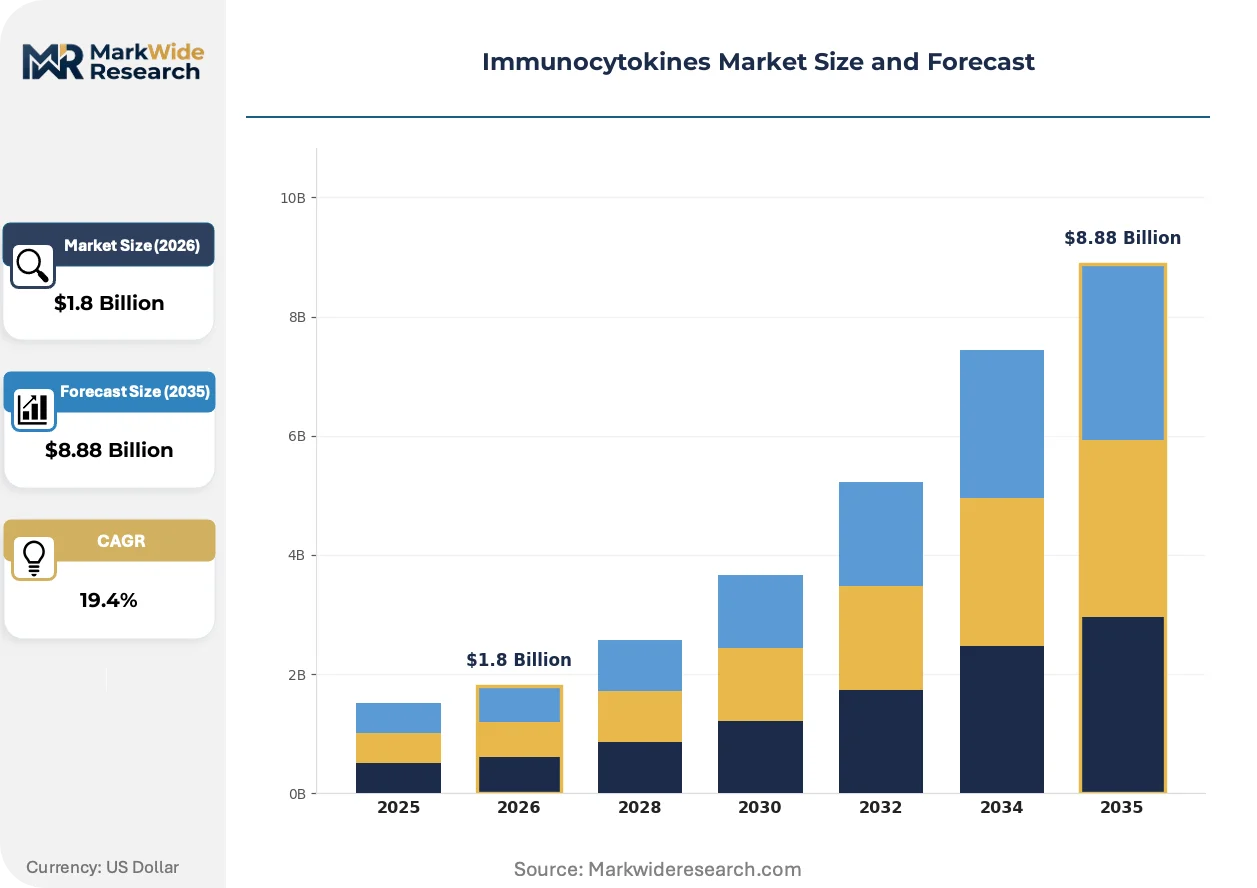
Market Dynamics
FDA accelerated approval pathways compress development timelines from 12-15 years toward 7-10 years for immunocytokine candidates, while manufacturing scale-up bottlenecks for cytokine payload production create supply-side friction that favors integrated biologics manufacturers over virtual development shops.
Growth Catalysts
- Breakthrough Therapy Designation:FDA's expedited review pathway compresses Phase III initiation timelines and attracts venture capital toward cytokine fusion platforms. Developers leverage this mechanism to secure earlier revenue recognition.
- Academic Medical Center Expansion:Oncology departments at university-affiliated hospitals build dedicated immuno-oncology infusion centers. These facilities generate real-world evidence that supports regulatory submissions and payer negotiations.
- Subcutaneous Delivery Innovation:Formulation advances in half-life extension and viscosity reduction enable outpatient administration. Patient preference for home-based injection drives reimbursement policy evolution toward ambulatory coverage.
Market Restraints
- Cytokine Payload Supply Concentration:Commercial-scale interleukin-2 and interferon-alpha production concentrates among three contract manufacturing organizations. This geographic clustering in the United States and Switzerland creates single-source vulnerability.
- ICH Q5D Cell-Line Qualification Burden:Regulatory requirements for master cell bank documentation and viral clearance validation extend IND-to-Phase-I timelines by 18-24 months. Smaller developers lack internal quality infrastructure to manage these submissions.
- Unconjugated Cytokine Substitution:High-dose IL-2 regimens maintain niche utility in melanoma and renal cell carcinoma where checkpoint inhibitors fail. These legacy protocols compete for the same patient populations and investigator attention.
Strategic Opportunities
- Japan's PMDA Sakigake Pathway:Japan's priority review system for innovative biologics offers 12-month approval timelines for first-in-class immunocytokines. Developers can establish early commercial presence before US market entry.
- Solid Tumor Microenvironment Targeting:Tumor-associated antigen platforms redirect cytokine signaling toward pancreatic, ovarian, and triple-negative breast malignancies. These indications show limited checkpoint inhibitor response and represent addressable white space.
- ISO 10993 Biocompatibility Harmonization:Converging international standards for device-biologic combination products simplify multi-region filing strategies. Manufacturers can leverage single toxicology packages across FDA, EMA, and PMDA submissions.
Industry Challenges
- Cytokine Engineering Talent Scarcity:Protein scientists with dual expertise in antibody Fc engineering and cytokine half-life modulation command premium compensation. The limited academic pipeline constrains team expansion at emerging developers.
- Linker Stability Validation:Premature payload release in systemic circulation drives dose-limiting toxicities that terminate clinical programs. Analytical methods for in vivo stability assessment remain non-standardized across CRO networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunocytokines Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Bi-specific Antibodies, Cytokine Fusion Proteins, Cytokines Application: Oncology, Autoimmunity, Infectious Diseases, Neurological Disorders Therapy Area: Cancer Immunotherapy, Chronic Inflammatory Conditions, Viral Infections, Autoimmune Disorders Delivery Mode: Subcutaneous Injection, Intravenous Infusion, Intramuscular Injection, Oral Delivery |
| Companies Covered | Philogen S.p.A., Nektar Therapeutics, ImmunityBio Inc., F. Hoffmann-La Roche AG, Xilio Therapeutics, Merck KGaA, ImmunoGen, Novartis, Synthekine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunocytokines Market Strategic Shifts
Bi-specific antibody architectures are displacing monospecific formats across late-stage pipelines, while regulatory convergence on complex biologic characterization standards is compressing the competitive advantage window for first movers.
Masked cytokine technologies deploy protease-cleavable shields that silence systemic activity until tumor-specific enzyme exposure. Oncology-focused biotechs license these platforms from specialized tool developers at accelerating pace. This delivery architecture is expanding into autoimmune applications where localized immune suppression replaces systemic immunosuppression.
EMA's priority medicines (PRIME) designation now requires mandatory patient-reported outcome integration from Phase II onward. Immunocytokine developers must build electronic clinical outcome assessment infrastructure earlier in development. European academic medical centers lead this adaptation, creating competitive separation from US sites slower to implement digital endpoint capture.
Hospital pharmacy committees increasingly demand total cost-of-care evidence beyond drug acquisition price. Immunocytokine manufacturers must produce real-world data on infusion center utilization, adverse event management, and comparative effectiveness against standard-of-care regimens. This evidentiary burden concentrates in US integrated delivery networks where pharmacy benefit managers consolidate purchasing authority.
Immunocytokines Market Segmentation
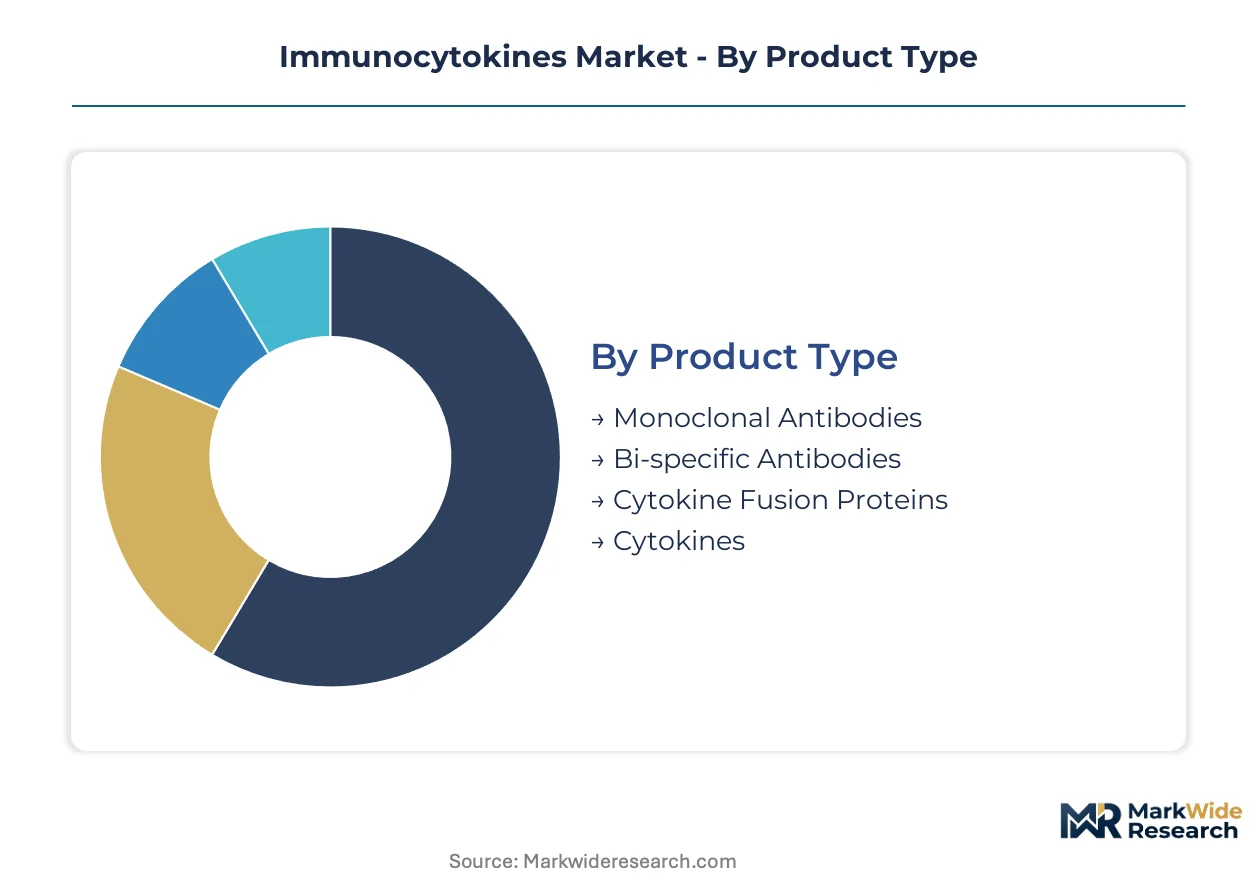
Immunocytokine architectures fragment across molecular formats, disease indications, and administration routes that each impose distinct manufacturing, regulatory, and reimbursement requirements. Developers must align platform selection with target biology and healthcare delivery infrastructure.
Product Type:
Antibody engineering sophistication determines payload stability, tumor penetration depth, and systemic clearance rates across molecular formats.
- Bi-specific Antibodies:Dual-targeting architectures engage tumor antigens while simultaneously recruiting effector cells through CD3 or cytokine receptor domains. Academic medical centers in the United States concentrate demand for these formats in Phase II/III trials. Manufacturing complexity limits supply to integrated biologics facilities with mammalian cell culture expertise.
- Cytokine Fusion Proteins:Recombinant constructs tether interleukin or interferon payloads to antibody fragments via engineered linkers. Outpatient oncology clinics in Germany and Switzerland drive preference for subcutaneous-ready formulations with extended half-life. Linker stability validation remains the critical quality attribute determining clinical program survival.
- Monoclonal Antibodies:Established manufacturing infrastructure and well-characterized regulatory pathways support commercial scale. Contract development organizations in Switzerland maintain surplus capacity for cytokine-conjugated variants.
- Cytokines:Unconjugated interleukin-2 and interferon-alpha retain niche utility in melanoma and renal cell carcinoma regimens where checkpoint inhibitors fail. High-dose protocols compete for investigator attention and hospital pharmacy budget allocation.
Bi-specific antibodies lead on scale; cytokine fusion proteins lead on momentum.
Application:
Disease biology and immune microenvironment characteristics dictate cytokine payload selection and dosing strategy.
- Oncology:Solid tumor indications with limited checkpoint inhibitor response—pancreatic, ovarian, triple-negative breast—represent addressable white space. FDA breakthrough therapy designation accelerates development timelines for tumor-targeting platforms. Academic medical center expansion creates dedicated infusion infrastructure for combination regimens.
- Autoimmunity:Masked cytokine technologies enable localized immune suppression without systemic immunosuppression. European sites lead patient-reported outcome integration required under EMA PRIME designation.
- Infectious Diseases:Cytokine immunotherapy augments host response in viral and fungal infections where antimicrobial resistance limits standard options. Hospital-based administration dominates this segment.
- Neurological Disorders:Blood-brain barrier penetration challenges constrain cytokine delivery to central nervous system targets. Blood-brain barrier penetration challenges constrain cytokine delivery to central nervous system targets. Specialized formulation partnerships concentrate among tool developers in Boston and Basel.
Oncology commands revenue concentration; autoimmunity demonstrates the steepest expansion trajectory.
Therapy Area:
Immune mechanism and patient population size shape investment prioritization across therapeutic domains.
- Cancer Immunotherapy:Tumor-associated antigen platforms redirect cytokine signaling toward immune-cold malignancies. Phase III trial infrastructure in the United States, Germany, and Japan generates regulatory-grade evidence.
- Chronic Inflammatory Conditions:Sustained cytokine exposure risks tolerance induction; masked payload technologies address this limitation. PMDA Sakigake pathway offers accelerated entry for first-in-class candidates in Japan.
- Viral Infections:Cytokine adjuvants enhance vaccine immunogenicity in immunocompromised populations. Pandemic preparedness programs in the United States and United Kingdom fund platform development.
- Autoimmune Disorders:IL-2 low-dose regimens promote regulatory T-cell expansion in type 1 diabetes and systemic lupus erythematosus. Subcutaneous delivery innovation enables home administration.
Cancer immunotherapy anchors commercial scale; chronic inflammatory conditions gain share fastest.
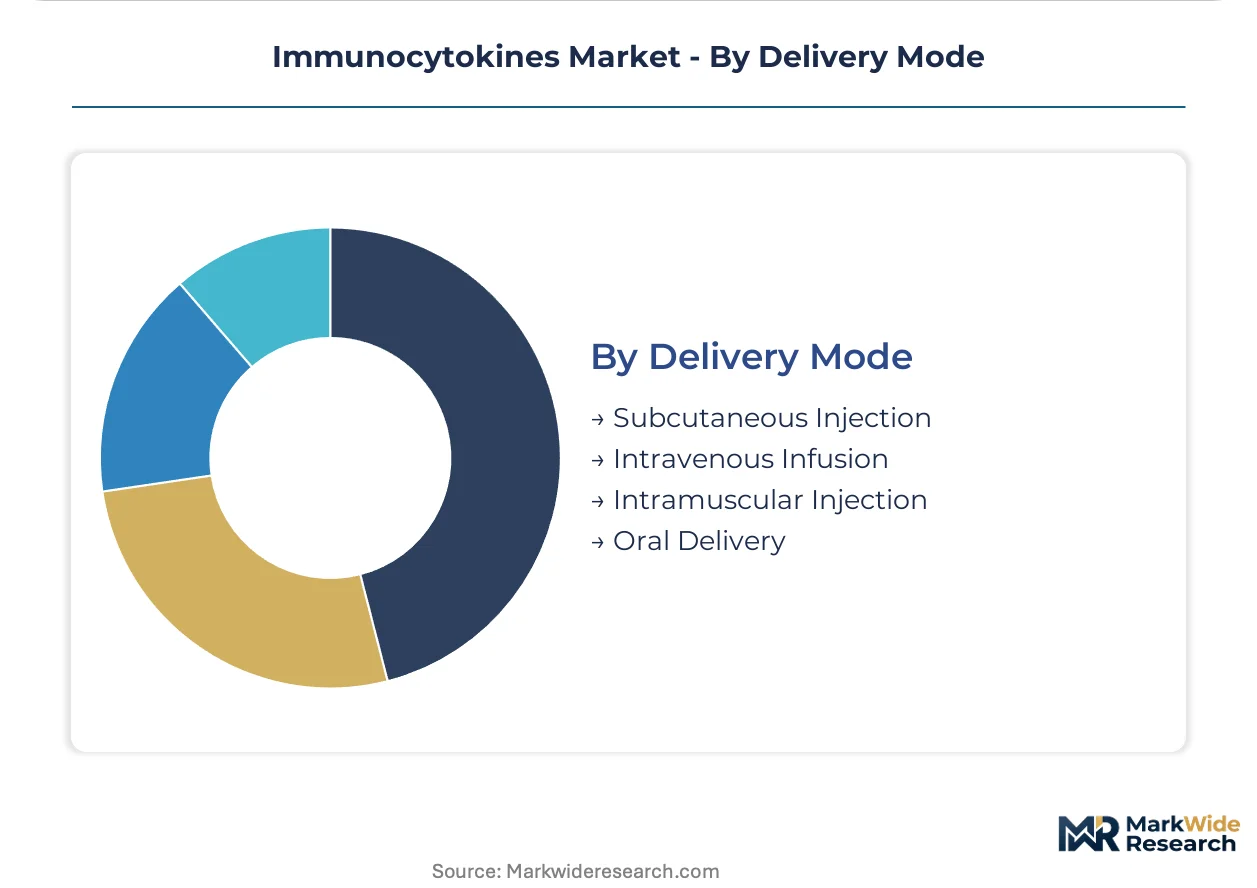
Delivery Mode:
Route of administration determines healthcare setting, reimbursement coding, and patient adherence economics.
- Subcutaneous Injection:Formulation advances in half-life extension and viscosity reduction enable outpatient and home-based administration. United States integrated delivery networks drive reimbursement policy evolution toward ambulatory coverage.
- Intravenous Infusion:Hospital-based oncology administration retains share for high-dose cytokine regimens requiring monitoring. Infusion center utilization data increasingly supports payer negotiations.
- Intramuscular Injection:Vaccine adjuvant applications leverage established cold chain infrastructure. Military and public health stockpiling programs in the United States and United Kingdom create demand concentration.
- Oral Delivery:Gastrointestinal degradation and hepatic first-pass metabolism limit bioavailability. Specialized formulation developers in Israel and California pursue permeation enhancers and enteric coatings.
Subcutaneous injection dominates patient preference; intravenous infusion retains hospital pharmacy commitment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Boston anchors clinical development velocity for immunocytokine platforms, with FDA breakthrough therapy designations concentrating Phase III infrastructure across specific national markets. Manufacturing scale and reimbursement density determine regional competitive position.
United States
Academic medical centers in Boston, New York, and San Francisco generate real-world evidence supporting payer negotiations. FDA accelerated approval pathways compress development timelines toward seven-to-ten-year windows. Philadelphia and Research Triangle Park clusters house contract manufacturing organizations specializing in cytokine payload production.
Germany
Outpatient oncology clinics in Munich and Heidelberg drive subcutaneous formulation preference for extended half-life products. EMA priority medicines designation mandates patient-reported outcome integration from Phase II onward. The Rhine-Main biotech corridor concentrates antibody-cytokine fusion partnerships.
Switzerland
Integrated biologics manufacturers in Basel maintain surplus mammalian cell culture capacity for cytokine-conjugated variants. Swissmedic harmonizes ISO 10993 biocompatibility standards with FDA expectations for multi-region filings. The Zurich-Lausanne axis specializes in linker stability validation analytics.
Japan
PMDA Sakigake pathway offers twelve-month approval timelines for first-in-class immunocytokines targeting pancreatic and ovarian malignancies. Tokyo and Osaka academic hospitals build dedicated immuno-oncology infusion infrastructure. METI funding supports cytokine engineering talent development programs.
United Kingdom
London and Cambridge clusters pursue masked cytokine technologies for autoimmune applications with localized immune suppression. MHRA alignment with EMA post-Brexit enables parallel submission strategies for complex biologics. The Oxford-Arc biotech network specializes in tumor-associated antigen platform development.
Immunocytokines Market Competitive Environment
Global majors compete with regional champions across manufacturing scale and regulatory access, with integrated biologics manufacturers holding supply-side advantages over virtual developers. The competitive structure fragments across three tiers: large-cap pharmaceutical conglomerates with deep oncology pipelines, mid-cap biotech specialists in tumor-targeting platforms, and emerging developers licensing masked cytokine technologies. Strategic moves concentrate on cytokine payload supply security and accelerated pathway navigation.
Within the tumor-targeting specialist tier, Philogen S.p.A. and Xilio Therapeutics exemplify geographically concentrated platform development, while Merck KGaA represents integrated manufacturing scale. These anchors occupy positions across the value chain from proprietary targeting technologies to captive cytokine production capacity, reflecting the industry shift from single-source supply toward multi-source antibody-cytokine fusion partnerships.
| Leading Market Players |
|---|
| Philogen S.p.A. |
| Nektar Therapeutics |
| ImmunityBio Inc. |
| F. Hoffmann-La Roche AG |
| Xilio Therapeutics |
| Merck KGaA |
| ImmunoGen |
| Novartis |
| Synthekine |
| Others |
Value Chain & Pricing Dynamics
Bi-specific antibody premiumization against cytokine fusion protein commoditization manifests in divergent supply chain configurations across the United States and Switzerland. FDA breakthrough therapy designation commands price premiums for dual-targeting architectures, while German outpatient clinics drive volume economics for subcutaneous-ready formulations through extended half-life engineering.
Pricing Analysis
Input-cost pass-through from interleukin-2 and interferon-alpha payload production concentrates pricing power among three contract manufacturing organizations in the United States and Switzerland. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified clinical-grade supply from research-use material and legacy unconjugated cytokine protocols. Pricing pressure stems from high-dose IL-2 substitution in melanoma and renal cell carcinoma where checkpoint inhibitors fail. Academic medical centers exhibit lowest price sensitivity due to dedicated immuno-oncology infusion budgets, while emerging biotech developers face acute cost compression in IND-enabling toxicology phases.
Supply Chain Analysis
Cold-chain logistics costs for cytokine payload stability govern distribution economics between Basel manufacturing hubs and United States clinical sites. Geographic supply concentration centers on Switzerland, the United States, and Germany for mammalian cell culture capacity and linker stability validation analytics. Raw material dependencies include recombinant protein expression media, viral clearance validation reagents, and ISO 10993-certified device components. Single-source vulnerability in commercial-scale interleukin production creates supply chain risk. Distribution runs through integrated delivery networks and hospital pharmacy committees demanding total cost-of-care evidence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in immunocytokines rests on cytokine engineering talent scarcity resolving through automated payload production platforms, while premium-tier shift toward masked cytokine technologies captures autoimmune indication value.
For Market Incumbents: Cement cytokine payload supply security through captive mammalian cell culture capacity or exclusive manufacturing partnerships with Basel-based integrated biologics facilities. Defend against emerging biotechs licensing masked cytokine platforms by accelerating EMA PRIME designation submissions with embedded patient-reported outcome infrastructure. Prioritize linker stability validation investments to terminate competitor programs through superior analytical methods. For New Entrants and Emerging Players: The premium-economy price-point gap in subcutaneous formulation development creates white-space opportunity for half-life extension specialists targeting United States integrated delivery networks. Penetrate solid tumor microenvironment indications—pancreatic, ovarian, triple-negative breast—where checkpoint inhibitor response remains limited. Pursue Japan PMDA Sakigake pathway for twelve-month approval timelines ahead of FDA entry. License masked cytokine technologies from Boston and Basel tool developers to bypass internal protein engineering capability gaps. For Investors and Strategic Acquirers: Consolidation pressure builds where cytokine payload supply concentration meets ICH Q5D cell-line qualification burdens that extend IND-to-Phase-I timelines by eighteen to twenty-four months. Long-term viability favors developers with proprietary tumor-targeting platforms and established academic medical center relationships over virtual shops dependent on contract manufacturing. Target acquisition archetype: mid-cap biotech with Phase II immunocytokine assets and existing FDA breakthrough therapy designation. Watch FDA guidance evolution on complex biologic characterization as inflection signal for regulatory compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Cytokine payload production bottlenecks favor integrated biologics manufacturers with Basel-based mammalian cell culture capacity. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses Phase III initiation timelines and attracts venture capital toward cytokine fusion platforms. |
| Licensing Agreement | Masked cytokine technology licenses from specialized tool developers accelerate autoimmune application entry without internal engineering. |
| Clinical Trial Advancement | Academic medical center expansion in Boston and San Francisco generates real-world evidence supporting payer negotiations. |
| Pipeline Diversification | Tumor-associated antigen platforms redirect cytokine signaling toward pancreatic and ovarian malignancies with limited checkpoint response. |
Study Parameters
Coverage spans the United States, Germany, Switzerland, Japan, and the United Kingdom, with primary inputs from each market's regulatory and clinical infrastructure. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-flow modeling and top-down reimbursement density analysis triangulate market sizing across segments.
Rate-of-change decomposition separates volume drivers from price evolution across the analysis window. Segmentation dimensions modeled include molecular format, disease indication, administration route, therapy area, and regional regulatory cluster. CAGRs derive from patient population projections, treatment-line penetration assumptions, and pricing elasticity by buyer archetype. Forecast inputs incorporate Phase III trial infrastructure concentration, accelerated approval pathway utilization rates, and cytokine payload manufacturing capacity expansion timelines.
Caveats apply where ICH Q5D cell-line qualification burden shifts or FDA guidance on complex biologic characterization tightens unexpectedly, as these could materially shift the outlook for emerging developer viability. Forecasts reflect documented assumptions on regulatory timeline compression and reimbursement policy evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
Benzbromarone API Market
Biopharmaceuticals
Olaparib API Market
Biopharmaceuticals
Global Endocrinology Drugs Market
Biopharmaceuticals
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market
Biopharmaceuticals
Protein Kinase B Inhibitors Market
Biopharmaceuticals
A - Estradiol Market
Biopharmaceuticals
Combination Antibody Therapy Market
Biopharmaceuticals
Polyclonal Antibodies Market
Biopharmaceuticals
Glycosylated Peptide Market
Biopharmaceuticals
China Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Antimycobacterial Drugs Market
Biopharmaceuticals
Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Acitretin Market
Biopharmaceuticals
Rapid Acting Insulin Market
Biopharmaceuticals
Global Recombinant Proteins Market