
 United States Sports Promoter Market | 2026-2036
United States Sports Promoter Market Size, Share, and Industry Trends Forecast 2026-2036
United States Sports Promoter Market Insights
Market Context
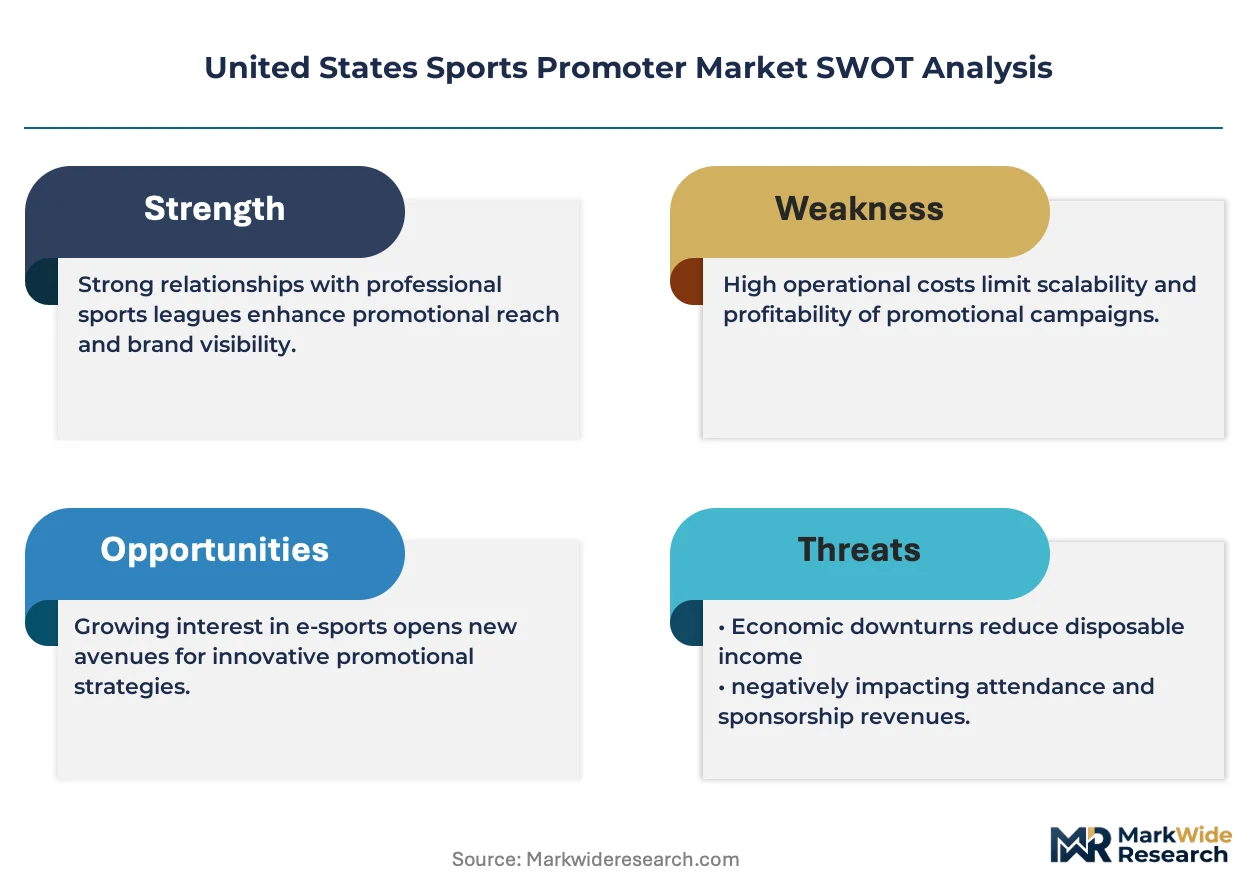
Ticket-plus-experience bundling is repositioning buyer choice in the sports promoter sector, forcing agencies to redesign service packages around hospitality tiers rather than pure access. Endeavor leverages its vertical control over venues, media rights, and talent representation to capture value across the event lifecycle. Spomo Sports sustains its competitive edge through deep specialization in college athletics and emerging sport properties. Baseline Sports anchors its model in regional market density, dominating secondary and tertiary city event calendars where national players maintain lighter footprints.
Technical Definition and Segment Structure
A sports promoter is an intermediary entity that commercializes athletic competition through the financing, organization, marketing, and broadcast distribution of events, typically earning revenue via gate receipts, sponsorship contracts, media rights sales, and merchandise licensing. The function requires coordination across venue operations, athlete contract negotiation, risk underwriting, and compliance with athletic governing body regulations. Event management services command the largest revenue share within the service type dimension, though athlete representation is expanding fastest as NIL rights proliferate across collegiate sports. Commission-based revenue models dominate the market structure, yet retainer fee arrangements are gaining traction among corporate sponsors seeking predictable budget allocation for multi-year partnerships.
Regulatory Framework and Outlook
The NCAA, state legislatures, and the IRS collectively shape market access and compensation structures for sports promoters operating across amateur and professional boundaries. State NIL laws in Texas, California, and Florida have fragmented compliance requirements, forcing promoters to maintain jurisdiction-specific contract templates and disclosure protocols. Stakeholders must monitor emerging federal preemption proposals and evolving athlete unionization efforts that could restructure fee ceilings and representation licensing requirements.
Market Dynamics
State-level NIL legislation is fragmenting athlete representation rules across Texas, California, and Florida, forcing promoters to maintain jurisdiction-specific compliance protocols and contract templates. This regulatory divergence is compressing margin structures while expanding operational complexity for agencies operating across multiple state lines.
Growth Catalysts
- NCAA NIL Policy Liberalization:Expanded athlete compensation rights are creating new revenue streams for representation services and event marketing partnerships across collegiate sports properties.
- Venue Infrastructure Investment:Texas and Florida are deploying public-private financing models for mixed-use stadium developments that expand event capacity and hospitality integration.
- Streaming Distribution Technology:Direct-to-consumer broadcast platforms are lowering barrier-to-entry for niche sport properties and regional promoter content monetization.
Market Restraints
- Insurance Cost Volatility:Event cancellation coverage and athlete injury liability premiums have escalated sharply, compressing net margins on fixed-fee tournament contracts.
- Concentrated Venue Ownership:A limited number of metropolitan stadium operators control prime date availability in Dallas, Los Angeles, and Miami, extracting premium lease terms.
- IRS Unrelated Business Income Rules:Tax treatment ambiguity around collegiate athlete payments creates compliance friction and audit exposure for university-affiliated promoters.
Strategic Opportunities
- Secondary City Event Calendar Gaps:Secondary markets in Ohio, North Carolina, and Arizona show underpenetrated demand for mid-tier professional and exhibition sport properties.
- Name, Image, and Likeness Federal Preemption:Proposed federal NIL standards would harmonize compliance costs and enable scalable national athlete representation platforms.
- Immersive Broadcast Convergence:Integration of augmented reality overlays with traditional linear feeds is opening premium tier pricing for remote viewership experiences.
Industry Challenges
- Multi-State Licensing Complexity:Athlete representation requires maintaining active credentials across divergent state athletic commission requirements, inflating administrative overhead.
- Legacy Ticketing System Integration:Promoters face technical friction merging modern dynamic pricing engines with entrenched venue access control infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Sports Promoter Market |
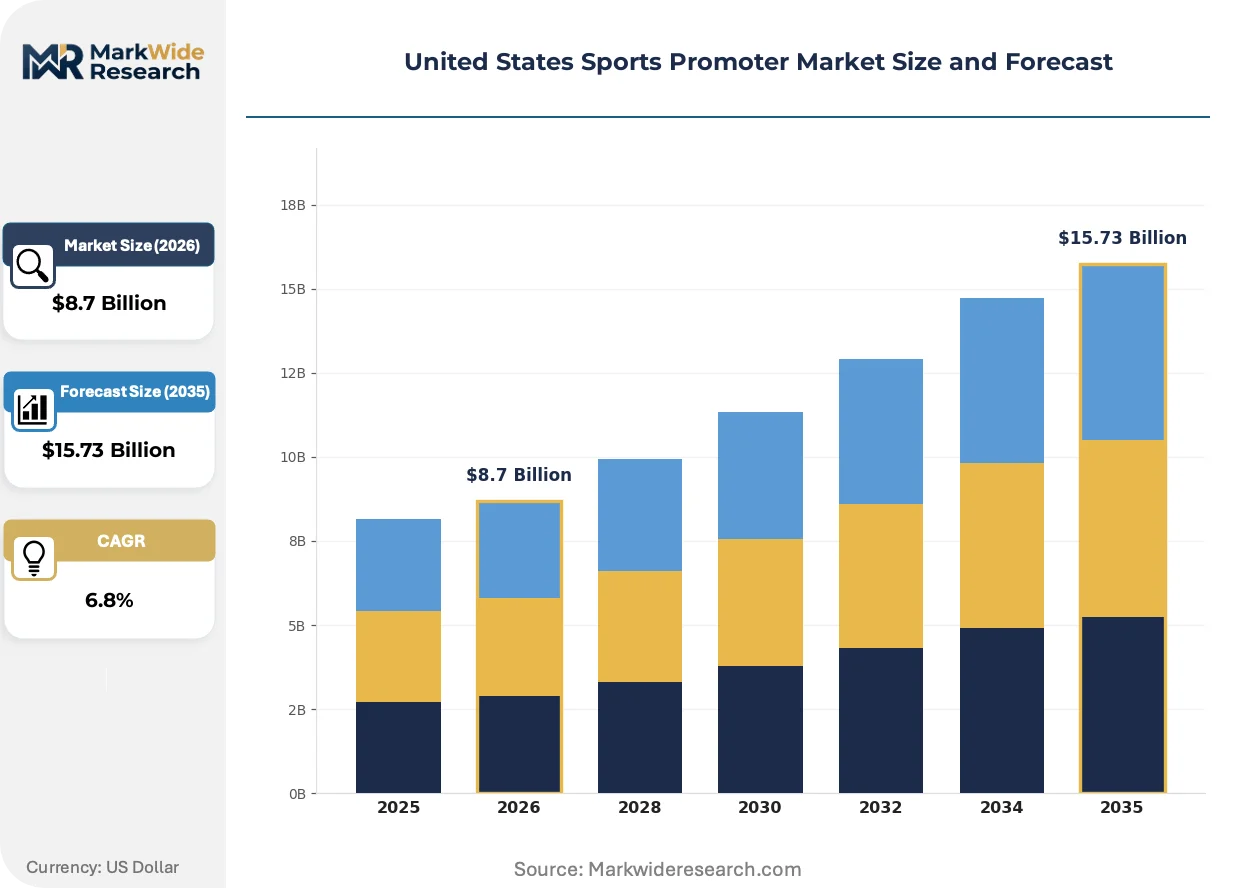
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Event Management, Athlete Representation, Sponsorship Acquisition, Marketing Consultation Client Type: Professional Teams, Individual Athletes, Corporate Sponsors, Non-Profit Organizations Revenue Model: Commission-Based, Retainer Fee, Performance Fee, Fixed Salary Sport Type: Team Sports, Individual Sports, Esports, Adventure Sports |
| Companies Covered | Baseline Sports, Spomo Sports, Endeavor, Sqor Sports, League Network, PRIMETIME Sports & Entertainment, TMFE Group, Bleachr, Genesco Sports Enterprises, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Sports Promoter Market Trends and Innovations
Digital infrastructure is reshaping how sports promoters package, price, and distribute live experiences. Three convergent developments are altering competitive positioning across the sector.
Cloud-based event management platforms are modularizing how promoters coordinate venue logistics, talent travel, and sponsor activation workflows. Mid-sized agencies in Texas and California are adopting these tools fastest, replacing fragmented spreadsheet-based operations. This technology is modularizing service delivery structures and enabling smaller players to bid on complex multi-venue contracts previously reserved for integrated giants.
The NCAA's evolving enforcement posture on booster-funded collectives is creating compliance uncertainty across state lines. Texas and Florida legislators have enacted disclosure requirements that diverge from California's athlete-protection framework, forcing promoters to segment contract structures. Collegiate-focused representation agencies are responding by establishing state-specific legal entities to firewall liability exposure.
Corporate hospitality buyers are unbundling traditional ticket packages and procuring event access through specialized procurement platforms. This disintermediation is compressing promoter margins on premium inventory while shifting buyer relationships toward annual framework agreements. The pattern is most pronounced in technology and financial services verticals concentrated in Northern California and New York metropolitan markets.
United States Sports Promoter Market Segmentation
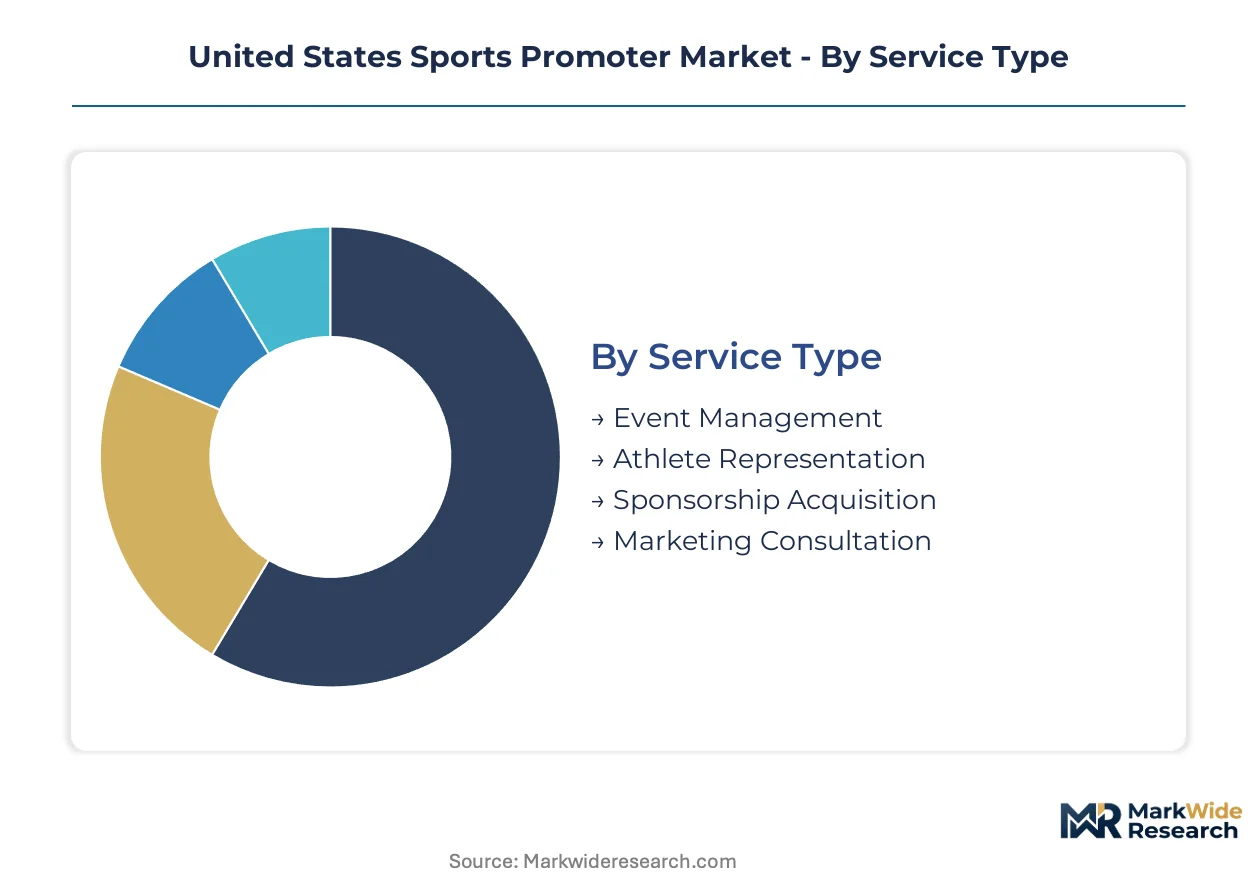
Sports promoter service configurations diverge sharply based on client sophistication and event scale. Promoters redesign their capability stacks around whether the revenue anchor is a single mega-event or a portfolio of recurring properties.
Service Type:
Upgrade cycles in this category track venue technology refreshes and broadcast platform migrations, forcing promoters to retool service bundles every three to five years.
- Event Management:Encompasses venue logistics, talent travel coordination, sponsor activation workflows, and risk underwriting for single or multi-day competitions. Texas and Florida stadium operators drive replacement demand as mixed-use developments expand hospitality integration requirements.
- Athlete Representation:Covers contract negotiation, NIL compliance navigation, and brand partnership structuring for collegiate and professional competitors. California's athlete-protection framework and Texas disclosure mandates fragment contract templates across state lines.
- Sponsorship Acquisition:Secures corporate funding through property valuation, rights packaging, and activation measurement.
- Marketing Consultation:Advises on audience development, digital content strategy, and ticket-plus-experience bundling architecture.
Volume placements concentrate in Event Management; the faster expansion belongs to Athlete Representation.
Client Type:
Cost tier stratification separates enterprise-grade annual retainers from transactional single-event engagements.
- Professional Teams:Require full-service representation spanning media rights sales, stadium naming deals, and player contract advisory. Franchise density in Dallas, Los Angeles, and Miami sustains premium fee structures.
- Individual Athletes:Demand NIL compliance expertise and micro-brand partnership cultivation. State-level legislative divergence elevates compliance costs for representation across Texas, California, and Florida.
- Corporate Sponsors:Procure category exclusivity and hospitality inventory through multi-year framework agreements.
- Non-Profit Organizations:Rely on below-market fee arrangements and cause-marketing activation support.
Revenue concentration sits with Professional Teams; Individual Athletes are climbing the fastest as NIL rights proliferate.
Revenue Model:
Margin profiles vary dramatically based on outcome contingency and duration commitment.
- Commission-Based:Ties promoter compensation to sponsorship dollars secured or athlete contract value negotiated. Corporate sponsors in Northern California and New York markets resist pure commission structures for budget predictability.
- Retainer Fee:Delivers fixed monthly or annual payments for ongoing advisory and representation services. Technology and financial services verticals favor this structure for multi-year partnership planning.
- Performance Fee:Contingent on event attendance thresholds, broadcast ratings, or athlete achievement benchmarks.
- Fixed Salary:Applies to in-house promoter roles at university athletic departments and venue operators.
Commission-Based arrangements dominate current volume; Retainer Fee structures are gaining share fastest among enterprise clients.
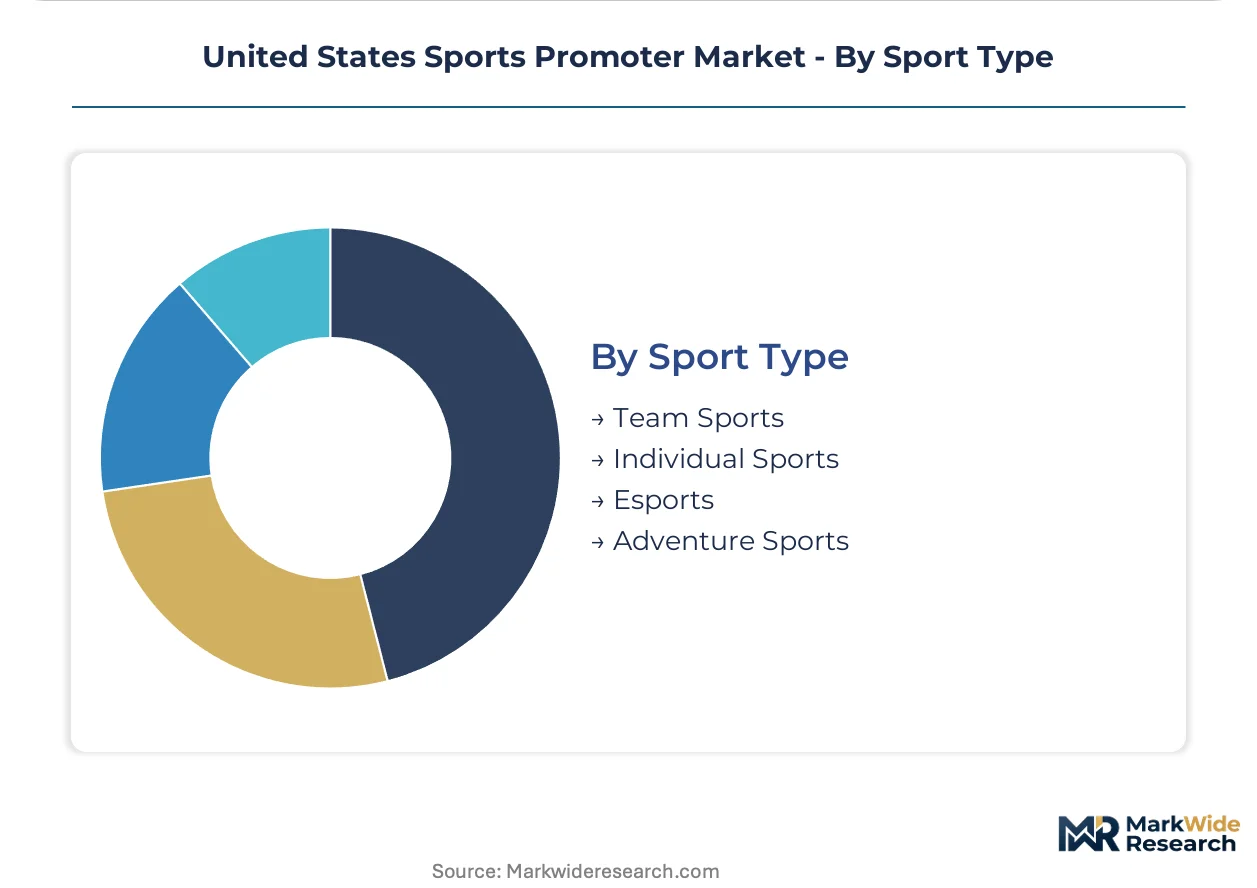
Sport Type:
Application dynamics separate mass-audience properties from niche community-building opportunities.
- Team Sports:Encompasses football, basketball, baseball, and hockey promotions with established broadcast distribution and stadium infrastructure. NFL and NCAA football properties in Texas and Florida command the highest sponsorship premiums.
- Individual Sports:Covers tennis, golf, track and field, and combat sports with athlete-centric marketing models. California's entertainment industry proximity elevates personal brand monetization for individual competitors.
- Esports:Organizes competitive video game tournaments with digital-native audience development and streaming-first distribution.
- Adventure Sports:Includes obstacle racing, extreme skiing, and climbing competitions with experiential tourism integration.
Team Sports anchor current volume placements; Esports registers the steepest expansion trajectory among emerging properties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in Texas and Florida are concentrating sports promoter infrastructure investment through state tax credits and municipal bond financing. These incentive structures accelerate venue development and athlete representation office clustering.
Texas
Franchise density in Dallas-Fort Worth and Houston drives corporate sponsorship procurement at scale. The Texas state legislature mandates NIL disclosure requirements that diverge from neighboring jurisdictions, forcing contract template segmentation. Austin and San Antonio host emerging esports tournament circuits where promoters test immersive broadcast integration.
California
Entertainment industry proximity in Los Angeles elevates individual athlete brand monetization for Olympic and action sports competitors. The state's athlete-protection framework imposes stricter NIL compliance protocols than federal minimums. San Francisco Bay Area technology sponsors dominate hospitality procurement platform adoption, compressing traditional promoter margins on premium inventory.
Florida
Miami and Orlando stadium operators control prime date availability through concentrated venue ownership structures. State-level NIL legislation requires promoter registration with the Department of Business and Professional Regulation, adding administrative overhead. Tampa and Jacksonville secondary markets show underpenetrated demand for mid-tier exhibition properties.
New York Metro
Financial services and technology verticals in Manhattan favor retainer-fee representation structures for budget predictability. New York State's athletic commission maintains distinct licensing requirements for agent representation that complicate multi-state operations. Brooklyn and Queens venue developments are expanding capacity for niche sport properties and collegiate showcase events.
Ohio
Cleveland and Columbus corporate headquarters sustain mid-market sponsorship demand for regional promoter specialists. The state's athletic commission coordinates with NCAA enforcement on booster-funded collective disclosure. Cincinnati's riverfront venue investments are attracting cross-state event migration from Kentucky and Indiana.
United States Sports Promoter Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the United States sports promoter market. The vendor base clusters around three strategic archetypes: vertically integrated entertainment holdings, collegiate-specialized representation boutiques, and regional event management operators. Consolidation pressure intensifies as venue ownership concentrates and NIL compliance costs escalate. Dominant competitive moves include geographic expansion into secondary markets and portfolio diversification across amateur and professional property types.
Within the diversified conglomerate tier, Endeavor anchors vertical control over venues, media rights, and talent representation. Among collegiate-focused specialists, Spomo Sports exemplifies deep specialization in emerging sport properties and athlete NIL navigation. Baseline Sports occupies a position representing regional density operators that dominate secondary city event calendars where national players maintain lighter footprints.
| Leading Market Players |
|---|
| Baseline Sports |
| Spomo Sports |
| Endeavor |
| Sqor Sports |
| League Network |
| PRIMETIME Sports & Entertainment |
| TMFE Group |
| Bleachr |
| Genesco Sports Enterprises |
| Others |
Pricing and Supply Chain Analysis
Vertical integration across venue ownership, media rights, and talent representation anchors pricing power for diversified sports promoters while compressing margins for non-integrated specialists. Endeavor's control over the event lifecycle enables premium fee extraction from corporate sponsors, whereas regional operators face pricing pressure from concentrated stadium lease costs in Dallas, Los Angeles, and Miami.
Pricing Analysis
Short lead-time event procurement commands substantial premiums in the United States sports promoter market as corporate sponsors compete for prime date availability at NFL and NCAA football venues. Three-tier pricing structure across premium hospitality, standard access, and economy ticketing segments dominates service bundling, with differentiation driven by venue location tier and after-sales experiential add-ons. Pricing pressure stems from insurance cost volatility and athlete injury liability premiums compressing net margins on fixed-fee tournament contracts. Technology and financial services verticals in Northern California exhibit lowest price sensitivity due to retainer-fee preference for budget predictability, while non-profit organizations face acute cost constraints.
Supply Chain Analysis
Domestic-content mandates in Texas and Florida Opportunity Zones are reshaping sourcing patterns for venue infrastructure and event technology vendors. Supply concentration centers on domestic stadium operators in Dallas-Fort Worth, Houston, and Miami, with secondary dependencies on California-based broadcast technology providers and New York metropolitan corporate hospitality procurement platforms. Raw material inputs encompass LED display systems, premium seating infrastructure, and cloud-based event management software licenses. Single-source vulnerability runs through concentrated venue ownership structures controlling prime date availability. Distribution runs through direct promoter-to-sponsor relationships for premium inventory, with secondary market aggregation platforms gaining share in mid-tier segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States sports promoter market is becoming a vertical-integration race as players pursue upstream control over venue ownership to secure date availability and extract lease economics from competitors.
For Market Incumbents: Anticipate NIL regulatory fragmentation by establishing state-specific legal entities in Texas, California, and Florida to firewall compliance liability. Pursue backward integration into mixed-use stadium developments through public-private financing models, securing captive venue access while generating lease revenue from rival promoters. Counter corporate hospitality disintermediation by shifting buyer relationships toward annual framework agreements with technology and financial services sponsors. For New Entrants and Emerging Players: Launch via specialized NIL representation boutiques targeting individual collegiate athletes in secondary markets where national players maintain lighter footprints. Exploit underpenetrated demand in Ohio, North Carolina, and Arizona for mid-tier professional and exhibition sport properties. Differentiate through deep specialization in emerging esports tournament circuits and immersive broadcast integration rather than competing head-to-head with integrated conglomerates on mega-events. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified entertainment holdings seeking geographic expansion or collegiate-specialized representation capabilities. Long-term viability favors vertically integrated operators with captive venue access and multi-state NIL compliance infrastructure. Watch federal NIL preemption proposals as the critical inflection signal that would harmonize compliance costs and enable scalable national platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Venue Infrastructure Acquisition | Captive stadium access in Dallas and Miami secures prime date availability against concentrated ownership. |
| State-Specific Legal Entity Formation | Firewall structures isolate Texas and Florida NIL disclosure liability from California athlete-protection mandates. |
| Immersive Broadcast Technology Investment | Augmented reality overlays enable premium tier pricing for remote viewership in Austin esports circuits. |
| Annual Framework Agreement Migration | Retainer-fee structures with Northern California technology sponsors replace transactional commission volatility. |
| Secondary Market Geographic Expansion | Cleveland and Columbus corporate headquarters sustain mid-market sponsorship demand for regional specialists. |
Research Methodology
Independent corroboration across sports promoter executives, collegiate athletic department administrators, corporate sponsorship procurement leads, and venue operations directors underwrites the qualitative findings in this study. Primary fieldwork encompassed structured interviews with NIL compliance officers, athlete representation agents, and mixed-use stadium developers across Texas, California, and Florida. Secondary validation drew from NCAA enforcement guidance documents, state legislative filings, SEC disclosures by publicly traded entertainment holdings, and municipal bond prospectuses for venue infrastructure projects. Bottom-up service segment sizing triangulated against top-down market value estimates derived from sponsorship expenditure tracking and gate receipt aggregation.
Rate-of-change decomposition across the analysis window separated volume expansion from price/mix effects in athlete representation and event management service lines. Segmentation modeling incorporated service type, client sophistication tier, revenue model structure, and sport property category dimensions. CAGRs were derived from historical trajectory analysis adjusted for regulatory inflection points including state NIL legislation enactment and proposed federal preemption. Forecast inputs encompassed venue capacity expansion pipelines, streaming platform subscriber growth curves, and corporate sponsorship budget allocation surveys.
Regulatory reversal on athlete compensation rights, venue financing cost escalation, and corporate hospitality procurement platform consolidation are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions regarding NCAA enforcement posture continuity and state legislative stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Smart Court (Sports) Market
Sports & Fitness Technology
Asia Pacific Sports Team and Clubs Market
Sports & Fitness Technology
Germany Sports Teams and Clubs Market
Sports & Fitness Technology
Sportswear Rental and Rotation Market
Sports & Fitness Technology
Smart Trainers Market
Sports & Fitness Technology
Global Sports Management Software Market
Sports & Fitness Technology
North America Sports Promoter Market
Sports & Fitness Technology
Europe Spectator Sports Market
Sports & Fitness Technology
India Sports Team and Clubs Market
Sports & Fitness Technology
UK Sports Team and Clubs Market
Sports & Fitness Technology
Smart Bike Trainers Market
Sports & Fitness Technology
3D Motion Capture Market
Sports & Fitness Technology
Smart Fitness Trainer Market
Sports & Fitness Technology
Sports App Market
Sports & Fitness Technology
Europe Sports Management Software Market
Sports & Fitness Technology
Smart Fitness Device Market