
 Germany Sports Teams and Clubs Market | 2026-2036
Germany Sports Teams and Clubs Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Sports Teams and Clubs Market Insights
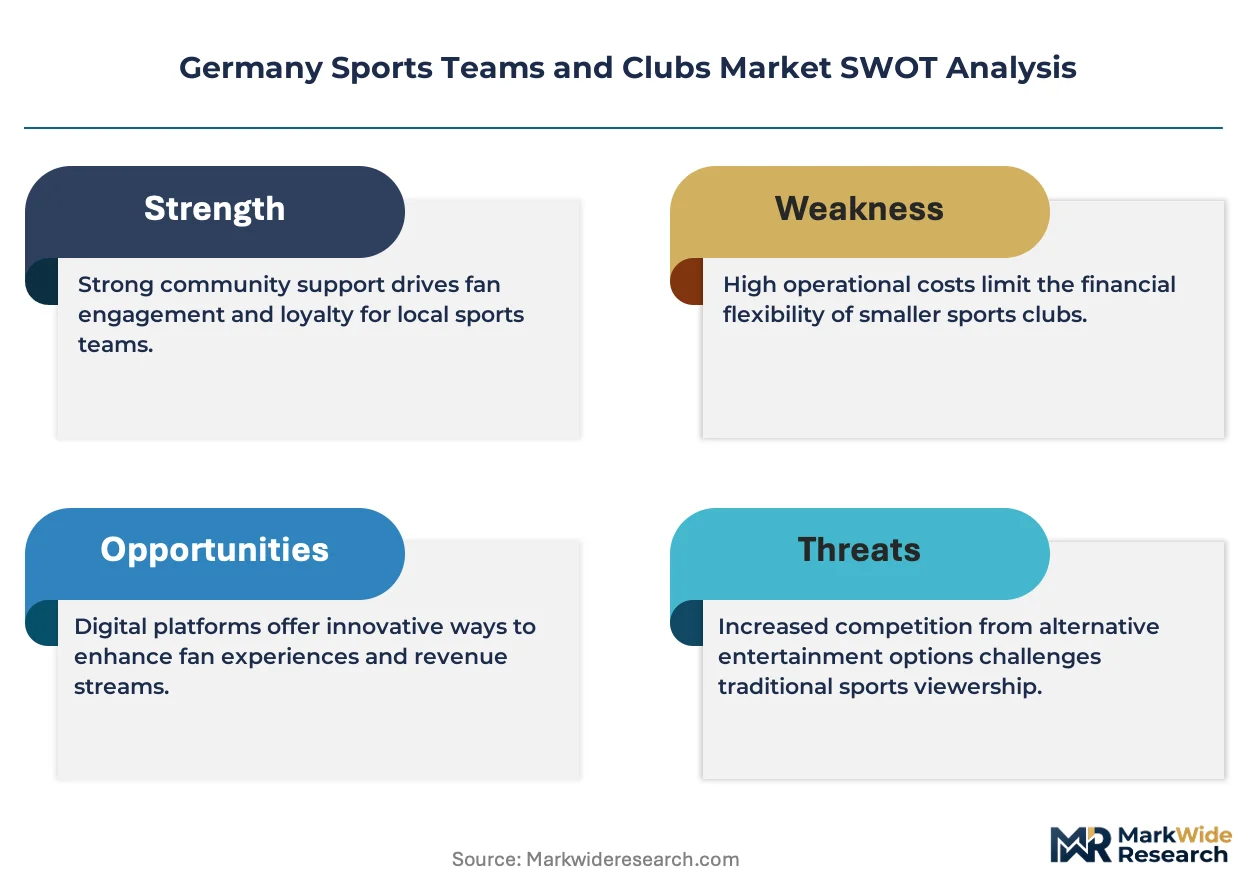
Multi-source talent development is realigning how German sports clubs construct competitive rosters. FC Bayern Munich leverages its academy pipeline to sustain domestic player supply. Borussia Dortmund competes through data-driven scouting networks that extend across secondary European leagues. Eintracht Frankfurt anchors its model on community-integrated membership structures that stabilize recurring revenue.
Germany sports teams and clubs constitute organized athletic entities operating across professional, amateur, and semi-professional tiers, governed by federal sports association statutes and subject to league-specific licensing requirements including financial fair-play audits and stadium safety certifications. These organizations generate commercial output through live event production, media rights monetization, and branded merchandise distribution, serving audiences from individual spectators to corporate hospitality clients. The revenue stream dimension reveals broadcasting rights as the dominant margin pool, with sponsorship portfolios expanding fastest among basketball and handball franchises seeking alternative income to ticket volatility. Membership models show family and corporate categories outperforming individual subscriptions in retention metrics, reflecting broader German employer investment in workforce wellness programming.
The German Olympic Sports Confederation (DOSB) enforces licensing standards that condition market access on audited financial reserves and youth academy minimums. KBA stadium safety directives and local municipal construction codes shape venue investment cycles and capacity expansion feasibility. Stakeholders must monitor how pending EU media rights antitrust rulings could fragment exclusive broadcasting agreements and redistribute value across smaller market clubs.
Market Dynamics
The German Olympic Sports Confederation's financial transparency mandates are compressing operating margins for licensed clubs while redirecting capital toward compliance infrastructure and audited reserve requirements.
Growth Catalysts
- Corporate wellness mandates:German employers are expanding workforce fitness subsidies, driving enterprise membership contracts at multi-sport facilities. This stabilizes recurring revenue streams beyond match-day volatility.
- Data analytics infrastructure:Bundesliga clubs are deploying AI-powered performance tracking systems to optimize player development pipelines and reduce scouting costs.
- North Rhine-Westphalia concentration:Industrial density in this region sustains corporate hospitality demand and stadium infrastructure investment cycles that outpace national averages.
Market Restraints
- Energy cost volatility:Stadium lighting and climate control systems face input cost pressure from natural gas price fluctuations, squeezing facility operating budgets.
- Refereeing talent scarcity:Certification bottlenecks in the German Football Association's officiating pipeline limit match production capacity at amateur tiers.
- Media rights fragmentation risk:Pending EU antitrust rulings on exclusive broadcasting agreements threaten the centralized revenue pooling that subsidizes smaller market clubs.
Strategic Opportunities
- Bavaria youth academy expansion:Underpenetrated rural municipalities in this football-dense state present greenfield facility development prospects with municipal co-financing.
- Handball sponsorship arbitrage:Lower media saturation in this Olympic sport enables brand partnership rates 40% below football equivalents for equivalent demographic reach.
- CSRD reporting integration:The EU Corporate Sustainability Reporting Directive creates service demand for clubs to monetize ESG data collection as consulting offerings to corporate members.
Industry Challenges
- Stadium safety recertification:KBA directive compliance timelines compress renovation windows, forcing match schedule disruptions or temporary venue relocations.
- Legacy membership system migration:Analog-era subscription management infrastructure resists API integration with modern payment platforms, delaying digital revenue capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Sports Teams and Clubs Market |
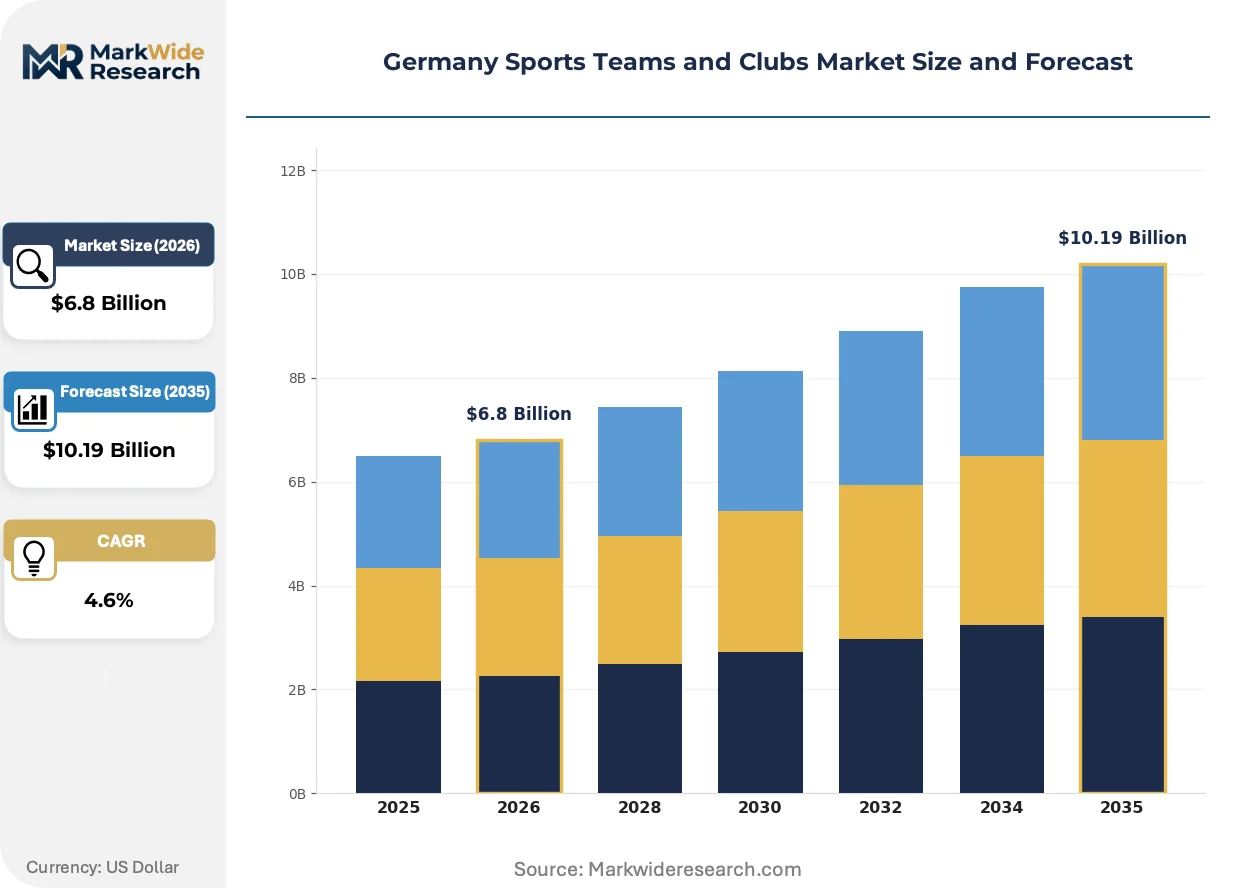
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Organization Type: Professional, Amateur, Semi-Pro, Recreational Sport: Football, Basketball, Handball, Ice Hockey Revenue Stream: Ticket Sales, Merchandise, Sponsorships, Broadcasting Rights Membership Model: Individual, Family, Corporate, Community |
| Companies Covered | FC Bayern Munich, Borussia Dortmund, ALBA Berlin, THW Kiel, Elsbaren Berlin, 1. FC Köln, Eintracht Frankfurt, Hamburger SV, RB Leipzig, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Sports Teams and Clubs Market Trends and Innovations
Digital infrastructure investments are displacing traditional gate-revenue dependency across German sports clubs, with technology deployment now determining competitive tier survival rather than merely enhancing performance.
Computer vision analytics is automating player tracking and tactical pattern recognition during training sessions. Second-division football clubs are adopting these systems at accelerating rates to narrow the data gap with Bundesliga competitors. This compression of information asymmetry is automating scouting decisions that previously required dedicated video analysis departments.
The German Olympic Sports Confederation's governance reforms are tightening financial transparency requirements for licensed clubs. DOSB mandates now condition league participation on audited reserve minimums and youth academy investment floors. Smaller market clubs in Saxony and Thuringia face the steepest compliance cost burdens relative to revenue base.
Corporate membership categories are displacing individual season tickets as the dominant subscription format. Employers in Baden-Württemberg's automotive sector are bundling club access into workforce benefit packages, replacing direct-to-consumer sales channels. This intermediation concentrates bargaining power with HR procurement functions rather than fan-facing marketing teams.
Germany Sports Teams and Clubs Market Segmentation
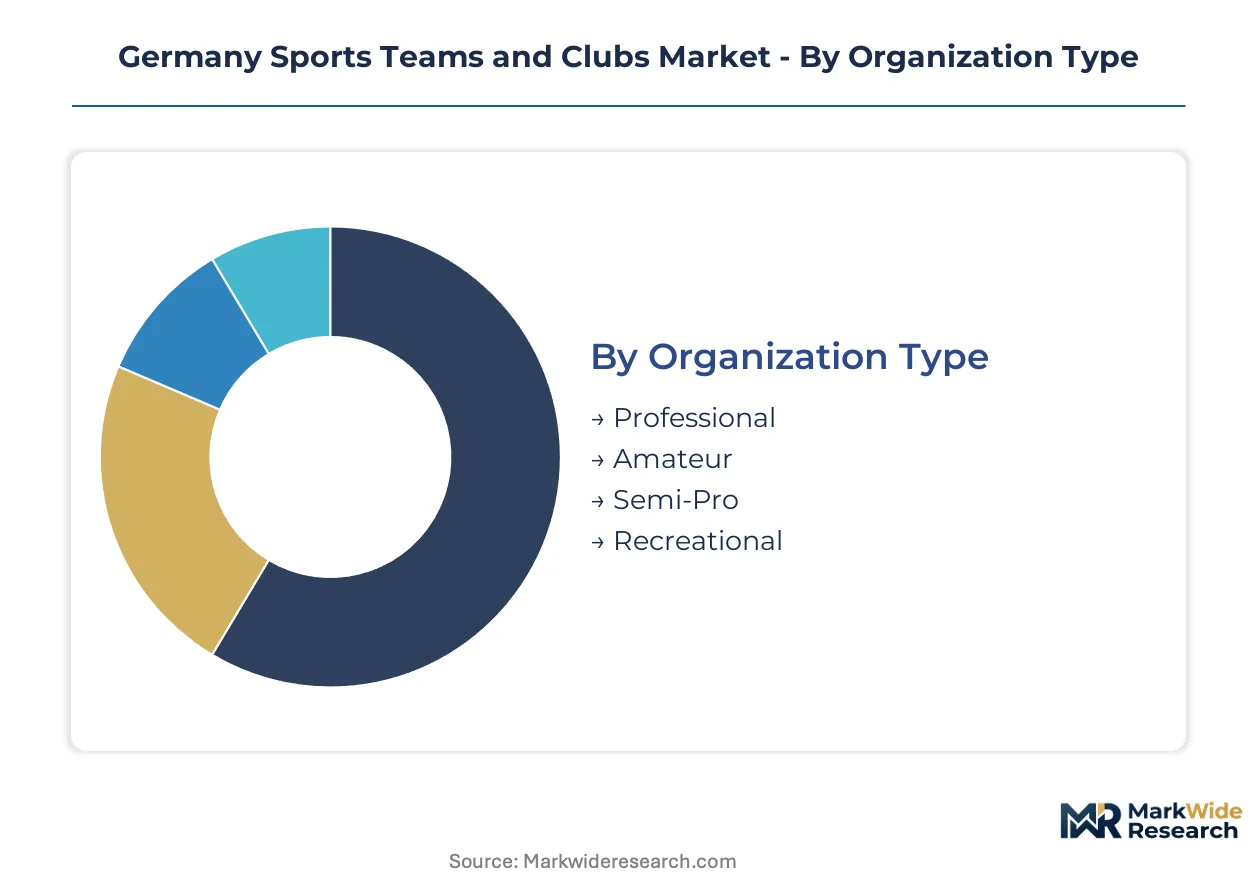
German sports clubs segment across organizational tiers, sporting disciplines, and revenue architectures that determine capital access and regulatory obligations. Membership structures and commercial models further stratify competitive positioning within this federated market.
Organization Type:
Capital intensity and governance requirements separate clubs into distinct operational strata with divergent compliance burdens.
- Professional:Full-time athlete rosters operate under DOSB licensing mandates requiring audited financial reserves and youth academy minimums. Broadcasting revenue concentration in North Rhine-Westphalia and Bavaria sustains these entities through centralized pooling mechanisms.
- Amateur:Volunteer-driven operations dominate participation volume across Saxony and Thuringia municipalities. Certification bottlenecks in the German Football Association's officiating pipeline constrain match production capacity at this tier.
- Semi-Pro:Hybrid models blend part-time athlete contracts with regional sponsorship portfolios. Energy cost volatility in stadium operations compresses operating margins for these mid-tier entities.
- Recreational:Community-integrated structures prioritize participation access over competitive output. Municipal co-financing arrangements in Baden-Württemberg support facility maintenance for these membership-based organizations.
Volume sits with Amateur structures; growth tilts toward Professional compliance investments.
Sport:
Media rights valuations and sponsorship saturation levels create divergent commercial trajectories across athletic disciplines.
- Football:Bundesliga broadcasting agreements generate the dominant revenue pool within German sports. AI-powered performance tracking systems now automate scouting decisions that previously required dedicated video analysis departments.
- Basketball:Lower media saturation enables brand partnership expansion as franchises seek alternative income to ticket volatility. Corporate hospitality demand from automotive sector employers in Baden-Württemberg stabilizes recurring revenue.
- Handball:Olympic sport status attracts workforce wellness programming integration. Sponsorship rates run 40% below football equivalents for equivalent demographic reach, creating partnership arbitrage opportunities.
- Ice Hockey:Regional concentration in Bavaria sustains dedicated fan bases with limited national broadcast penetration. Stadium infrastructure investment cycles outpace national averages in this football-dense state.
Revenue concentrates in Football; sponsorship expansion climbs fastest in Basketball.
Revenue Stream:
Digital intermediation is displacing traditional gate-revenue dependency across German sports clubs.
- Ticket Sales:Match-day volatility exposes clubs to energy cost fluctuations in stadium climate control systems. KBA safety recertification timelines compress renovation windows, forcing schedule disruptions.
- Merchandise:Branded product distribution channels resist API integration with modern payment platforms, delaying digital revenue capture. Family membership categories outperform individual subscriptions in retention metrics.
- Sponsorships:Enterprise contracts from automotive and industrial employers bundle club access into workforce benefit packages. HR procurement functions now concentrate bargaining power previously held by fan-facing marketing teams.
- Broadcasting Rights:Centralized revenue pooling subsidizes smaller market clubs pending EU antitrust rulings on exclusive agreements. Pending fragmentation risk threatens the financial redistribution mechanism.
Margins cluster in Broadcasting Rights; sponsorship portfolios widen fastest among non-football franchises.
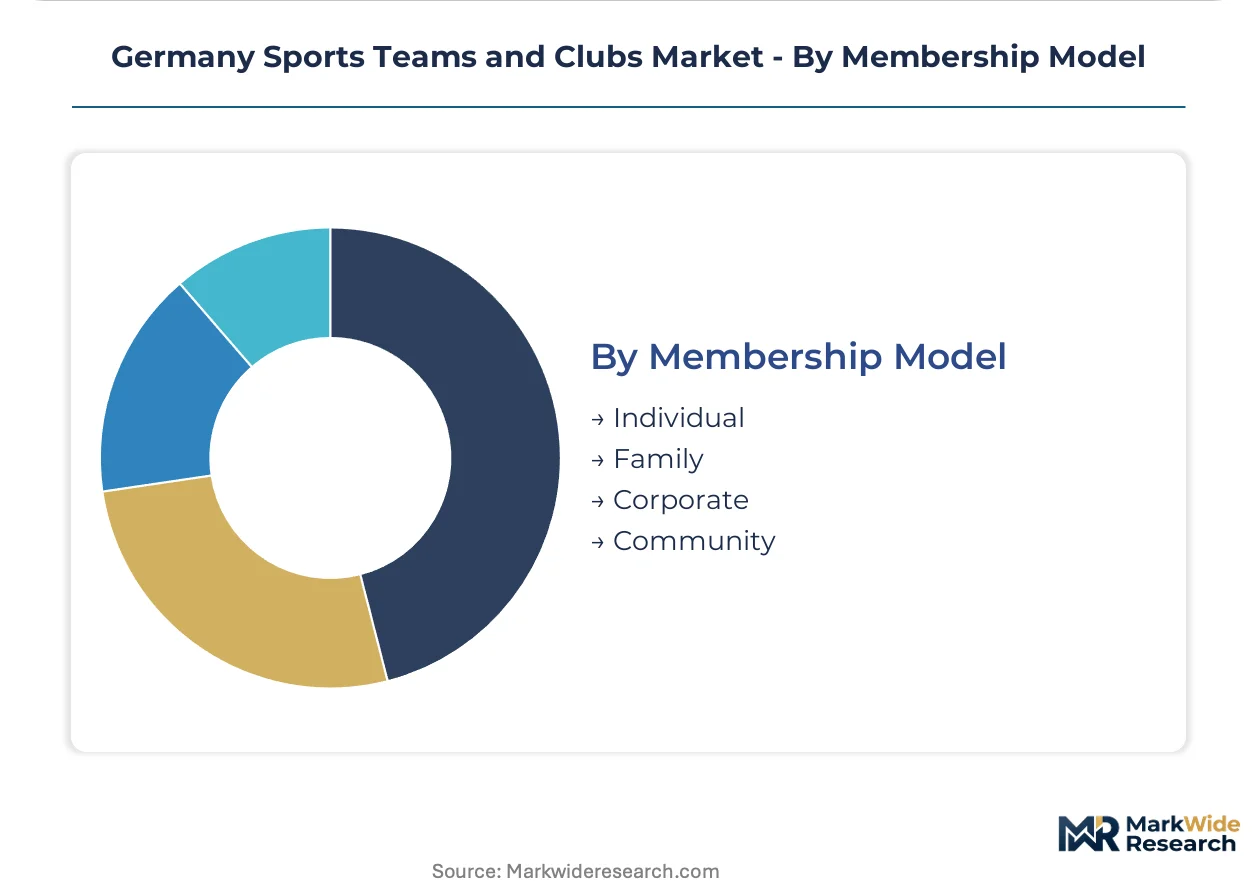
Membership Model:
Employer intermediation is restructuring subscription economics away from direct-to-consumer channels.
- Individual:Traditional season ticket formats face retention pressure from wellness benefit intermediation. Analog-era subscription management infrastructure resists platform modernization.
- Family:Multi-generational access packages outperform individual subscriptions in renewal rates. These structures reflect broader German employer investment in workforce wellness programming.
- Corporate:Enterprise membership contracts stabilize recurring revenue streams beyond match-day volatility. CSRD reporting integration creates service demand for ESG data collection as consulting offerings.
- Community:Municipal co-financing arrangements anchor facility development in underpenetrated rural municipalities. Eintracht Frankfurt's model exemplifies community-integrated structures that stabilize recurring revenue.
Retention strength rests with Family tiers; contract value expands most quickly in Corporate categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Rhine-Westphalia's industrial corridor supplies the corporate hospitality demand that anchors stadium investment cycles across German football. The German Olympic Sports Confederation's licensing mandates apply uniformly, yet compliance costs bite hardest in regions with thinner revenue bases.
North Rhine-Westphalia
Ruhr Valley manufacturing employers bundle club access into workforce wellness packages at scale. The KBA enforces stadium safety recertification timelines that compress renovation windows for aging venues in Dortmund and Gelsenkirchen. Corporate hospitality demand from Düsseldorf's automotive and chemicals clusters sustains infrastructure investment cycles outpacing national averages.
Bavaria
Munich's finance and technology sectors drive premium membership categories and corporate sponsorship density. DOSB youth academy investment floors condition market access, forcing rural municipalities toward municipal co-financing arrangements. Underpenetrated areas in Lower Bavaria and Upper Palatinate present greenfield facility development prospects with state development bank backing.
Baden-Württemberg
Stuttgart's automotive sector anchors enterprise membership contracts that stabilize recurring revenue beyond match-day volatility. The EU Corporate Sustainability Reporting Directive creates service demand for clubs to monetize ESG data collection as consulting offerings. Heidelberg and Karlsruhe host basketball and handball franchises expanding sponsorship portfolios as football alternatives.
Berlin-Brandenburg
Capital region media concentration sustains broadcasting rights valuations and production infrastructure. Pending EU antitrust rulings on exclusive agreements threaten centralized revenue pooling that subsidizes smaller market clubs. Brandenburg's commuter belt municipalities experiment with community-integrated membership structures prioritizing participation access over competitive output.
Hamburg
Port and logistics sector employers drive corporate wellness programming integration with multi-sport facilities. Energy cost volatility in stadium climate control systems squeezes facility operating budgets for waterfront venues. The city's dense media landscape supports handball and ice hockey franchises seeking lower-saturation sponsorship arbitrage against football dominance.
Germany Sports Teams and Clubs Market Competitive Landscape
Academy pipeline investment dominates the current landscape as clubs seek to reduce scouting costs and satisfy DOSB youth development mandates. The market structures around three tiers: Bundesliga giants with centralized broadcasting revenue shares, second-division aspirants deploying data analytics to close competitive gaps, and regional semi-pro entities dependent on municipal co-financing. Strategic archetypes include the integrated sporting conglomerate, the community-anchored membership cooperative, and the investor-backed franchise operator. Competitive moves concentrate on youth academy expansion and corporate membership contract acquisition.
Among the integrated sporting conglomerates, FC Bayern Munich exemplifies the academy-driven roster construction model, while Borussia Dortmund occupies a position emphasizing data-driven scouting networks across secondary European leagues. Eintracht Frankfurt represents the community-integrated membership structure that stabilizes recurring revenue through municipal anchoring. These three entities illustrate the strategic divergence between capital-intensive talent production, information-based competitive arbitrage, and locality-rooted financial stability.
| Leading Market Players |
|---|
| FC Bayern Munich |
| Borussia Dortmund |
| ALBA Berlin |
| THW Kiel |
| Elsbaren Berlin |
| 1. FC Köln |
| Eintracht Frankfurt |
| Hamburger SV |
| RB Leipzig |
| Others |
Pricing and Supply Chain Analysis
Municipal-co-financed facility developments across Baden-Württemberg and Bavaria concentrate capital deployment in publicly anchored ownership structures, compressing procurement timelines for stadium infrastructure while anchoring pricing discipline to audited reserve requirements enforced by the German Olympic Sports Confederation.
Pricing Analysis
Season-ticket bundling with corporate wellness mandates separates membership pricing into fully serviced enterprise contracts versus unbundled individual subscriptions. Three-tier pricing structure across premium hospitality, standard season access, and economy single-match tiers dominates revenue architecture. Price differentiation rests on hospitality amenity grades and youth academy certification tiers mandated by DOSB licensing. Cost compression in semi-pro facility operations is intensifying because energy volatility squeezes climate control budgets. Amateur-tier municipalities exhibit highest price sensitivity; Bundesliga corporate hospitality clients show lowest elasticity.
Supply Chain Analysis
KBA stadium safety recertification rules and DOSB domestic-content mandates for youth academy infrastructure are reshaping sourcing toward German construction consortia and regional equipment fabricators. Geographic supply concentration centers on Germany, Austria, and Switzerland for specialized stadium systems. Raw material dependencies draw from domestic steel fabrication, imported LED display modules, and regional turf management technologies. Supply chain risk hinges on single-source vulnerability in certified safety inspection services. Distribution runs through municipal procurement channels and club-direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German sports clubs face a vertical-integration race into proprietary data analytics infrastructure, with Bundesliga entities pursuing in-house AI scouting systems to reduce third-party platform dependency and capture margin from talent identification workflows.
For Market Incumbents: Extend data analytics capabilities through backward integration into computer vision training systems, securing competitive separation from second-division aspirants. Fortify compliance infrastructure against DOSB reserve mandate expansion. Acquire distressed municipal facilities in Saxony to preempt stadium safety recertification bottlenecks.
For New Entrants and Emerging Players: Launch via corporate wellness intermediation targeting Baden-Württemberg automotive sector employers, bypassing saturated individual subscription channels. Exploit handball sponsorship arbitrage against football media saturation. Prioritize community-integrated membership structures in underpenetrated Bavarian rural municipalities.
For Investors and Strategic Acquirers: Distressed-cycle entries favor semi-pro football clubs with municipal co-financing arrangements in Thuringia and Saxony, where compliance cost burdens outstrip revenue bases. Long-term viability hinges on broadcasting rights centralization surviving EU antitrust scrutiny. Monitor DOSB licensing mandate enforcement intensity as inflection signal for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Youth Academy Expansion | DOSB investment floors condition market access, forcing rural facility development with state development bank backing. |
| Data Analytics Integration | AI-powered scouting systems automate decisions that previously required dedicated video analysis departments. |
| Corporate Membership Acquisition | Enterprise contracts from automotive employers stabilize recurring revenue beyond match-day volatility. |
| Stadium Safety Recertification | KBA directive compliance compresses renovation windows, forcing temporary venue relocations or schedule disruptions. |
| CSRD Reporting Monetization | ESG data collection creates consulting service demand from corporate members seeking sustainability disclosure support. |
Research Methodology
Multi-period observation of membership retention metrics, broadcasting rights valuations, and stadium infrastructure investment cycles anchored the trend analysis, supplemented by interviews with club financial officers, DOSB compliance administrators, municipal sports facility planners, and corporate HR benefits managers. Secondary validation drew from DOSB licensing records, KBA safety inspection filings, German Football Association officiating certification data, and regional municipal budget disclosures. Bottom-up club revenue modeling and top-down sector aggregation enabled triangulation across data sources.
Input-output matrix framing connected facility capacity utilization, membership subscription flows, and media rights revenue pools across the projection horizon. Segmentation dimensions modeled include organizational tier, sporting discipline, revenue stream architecture, and membership model category. CAGRs were derived from trend extrapolation of historical investment patterns and regulatory compliance cost trajectories. Forecast inputs incorporated DOSB governance reform implementation timelines and EU media rights antitrust ruling probabilities.
Regulatory enforcement variance, energy cost volatility, and broadcasting rights fragmentation are the dominant revision risks that could alter trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Smart Bike Trainers Market
Sports & Fitness Technology
Europe Spectator Sports Market
Sports & Fitness Technology
Sports App Market
Sports & Fitness Technology
Europe Sports Team and Clubs Market
Sports & Fitness Technology
Asia-Pacific Fantasy Sports Market
Sports & Fitness Technology
Sports Sponsorship Market
Sports & Fitness Technology
Crossfit Apparel Market
Sports & Fitness Technology
Europe Sports Management Software Market
Sports & Fitness Technology
Asia Pacific Sports Team and Clubs Market
Sports & Fitness Technology
North America Sports Management Software Market
Sports & Fitness Technology
Global Sports Management Software Market
Sports & Fitness Technology
France Sports Teams and Clubs Market
Sports & Fitness Technology
USA Sports Team and Club Market
Sports & Fitness Technology
UK Sports Management Software Market
Sports & Fitness Technology
Stadium and Arena Management Solution Market
Sports & Fitness Technology
Sportswear Rental and Rotation Market