
 India Sports Team and Clubs Market | 2026-2036
India Sports Team and Clubs Market Size, Share, and Industry Trends Forecast 2026-2036
India Sports Team and Clubs Market Insights
Broadcast and digital streaming rights is rewriting revenue allocation across India's sports franchise economy. Chennai Super Kings leverages its Tamil Nadu fan density to sustain merchandise throughput and regional sponsorship premiums. Royal Challenger Bangalore anchors Karnataka's cricket economy through stadium-linked hospitality and brand licensing. Bengaluru FC competes in football's smaller but expanding sponsorship pool, differentiating through youth academy output and community programming.
India sports teams and clubs comprise organized competitive entities spanning franchise-owned professional leagues, amateur associations, and membership-based community clubs, governed by sport-specific federations and operating through athlete contracts, venue leases, and commercial rights agreements. Their primary function centers on assembling competitive rosters, staging events, and monetizing fan engagement through media rights, live attendance, and licensed products. Franchise clubs command the dominant revenue share within team type segmentation, while cricket generates disproportionate sponsorship and broadcasting yield within sport type splits. Broadcasting rights represents the fastest-expanding revenue stream as streaming platforms bid aggressively for exclusive windows, though ticket sales retains margin stability in established metro venues.
The Ministry of Youth Affairs and Sports, Sports Authority of India, and BIS facility standards collectively shape stadium construction timelines, athlete welfare mandates, and broadcast infrastructure specifications. Khelo India funding and state-level sports policies determine grassroots club formation rates and talent pipeline depth. Stakeholders must track emerging state sports legislation and streaming platform exclusivity terms as these will determine which city markets and sport formats capture the next franchise licensing cycle.
Market Dynamics
Broadcast and digital streaming rights are compressing revenue allocation timelines across India's sports franchise economy, forcing clubs to restructure commercial partnerships around exclusive windowing rather than seasonal sponsorship cycles.
Growth Catalysts
- Khelo India funding pipelines:The Sports Authority of India's initiative is expanding grassroots club formation rates and talent identification infrastructure across Maharashtra, Karnataka, and Tamil Nadu.
- Corporate sponsorship migration:Non-cricket sports are drawing fresh brand investment as cricket inventory saturates and football, kabaddi, and athletics offer untapped audience segments.
- Stadium-linked hospitality:Premium seating and experiential packages at Bengaluru and Chennai venues are creating new recurring revenue streams beyond match-day ticketing.
Market Restraints
- Athlete contract inflation:IPL retention auctions and overseas league poaching are compressing franchise margins across cricket and football roster construction.
- Venue lease concentration:Metro stadium availability in Mumbai, Delhi, and Bengaluru is controlled by municipal authorities with inflexible commercial terms.
- Media rights fragmentation:Streaming platform exclusivity windows are splintering audience reach and complicating sponsor valuation metrics.
Strategic Opportunities
- Tier-II city franchise licensing:Jaipur, Kochi, and Guwahati present underpenetrated markets with stadium infrastructure gaps that first-movers can anchor.
- Youth academy monetization:Bengaluru FC and Chennai Super Kings are converting academy output into transfer fees and loan income streams.
- State sports policy tailwinds:Maharashtra and Tamil Nadu incentive schemes for private stadium investment are accelerating venue construction timelines.
Industry Challenges
- Coaching certification bottlenecks:National Sports Federation licensing requirements are delaying academy expansion and foreign coach recruitment.
- Legacy ticketing infrastructure:State association-controlled venues lack integrated digital payment and dynamic pricing systems.
- Cross-sport athlete welfare compliance:BIS facility standards and SAI medical protocols are raising operational overhead for multi-sport club operators.
Report Scope
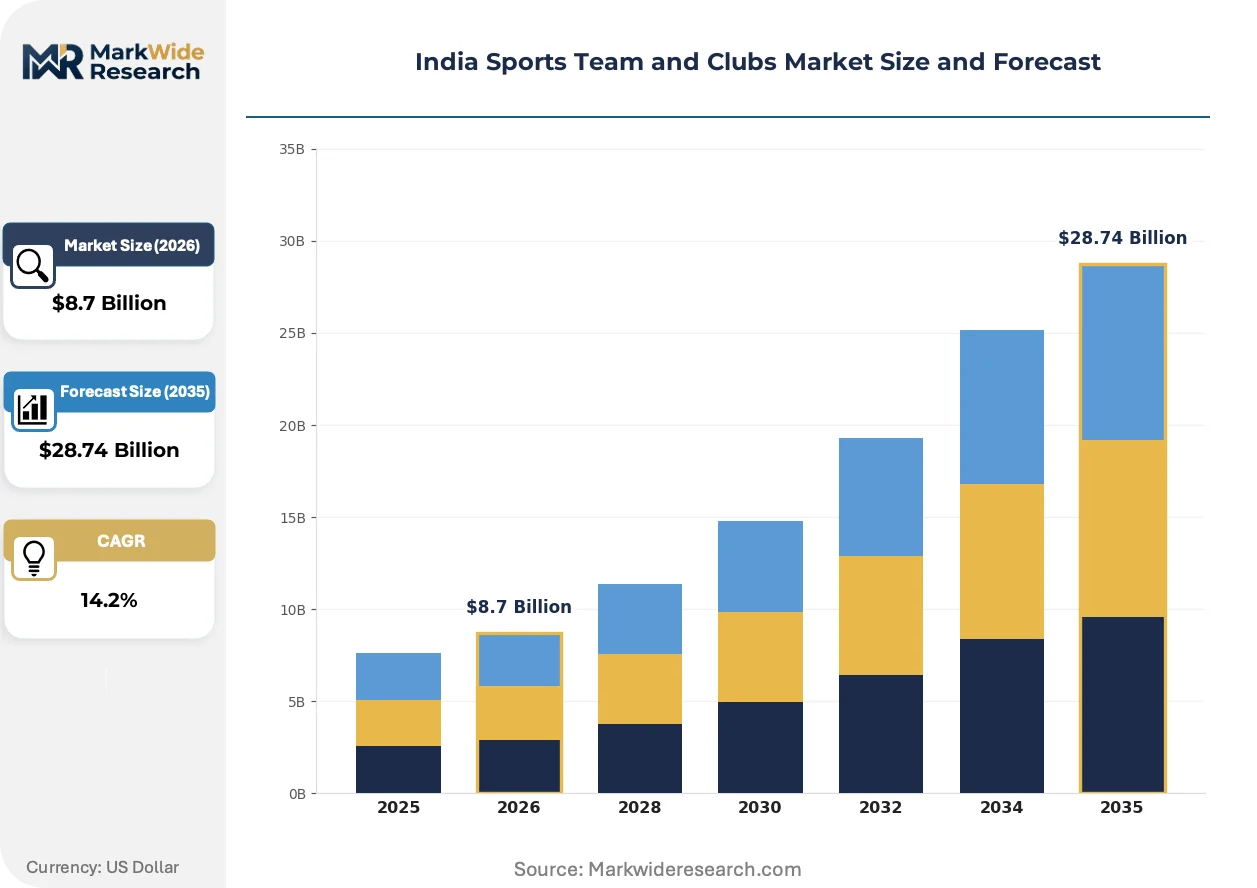
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Sports Team and Clubs Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Team Type: Professional Teams, Amateur Teams, Community Clubs, Franchise Clubs Sport Type: Cricket, Football, Field Hockey, Kabaddi Membership Model: Individual Membership, Family Packages, Corporate Membership, Youth Programs Revenue Stream: Sponsorship, Ticket Sales, Merchandise, Broadcasting Rights |
| Companies Covered | Royal Challenger Bangalore, Chennai Super Kings, Chennaiyin FC, Bengaluru FC, Bombay Presidency Golf Club, Hockey India, Avalanche Motorsports, Basketball Federation of India, Meco Motorsports, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Sports Team and Clubs Market Trends and Innovations
Fan engagement architecture is shifting from broadcast-dependent models toward direct digital monetization, with clubs building proprietary data assets and subscription tiers that bypass traditional media intermediaries.
Artificial intelligence-driven performance analytics is migrating from elite national team deployment to franchise-level roster management. IPL and ISL clubs are adopting biometric tracking and predictive injury modeling. This compression of decision-making cycles is shortening player contract durations and raising transfer market liquidity.
SAI's revised athlete welfare mandates and BIS facility certification requirements are tightening stadium construction specifications. Commercial venue operators must integrate medical recovery infrastructure and broadcast-grade connectivity from the design phase. Maharashtra and Karnataka sports departments are accelerating compliance audits ahead of franchise licensing renewals.
Younger demographics in Tamil Nadu and Karnataka are bypassing linear broadcast entirely for mobile-first consumption. Clubs are responding with short-form content partnerships and influencer-integrated membership drives. This behavioral pivot is most visible in cricket franchise merchandise sales, where direct-to-consumer channels now outpace traditional retail distribution.
India Sports Team and Clubs Market Segmentation
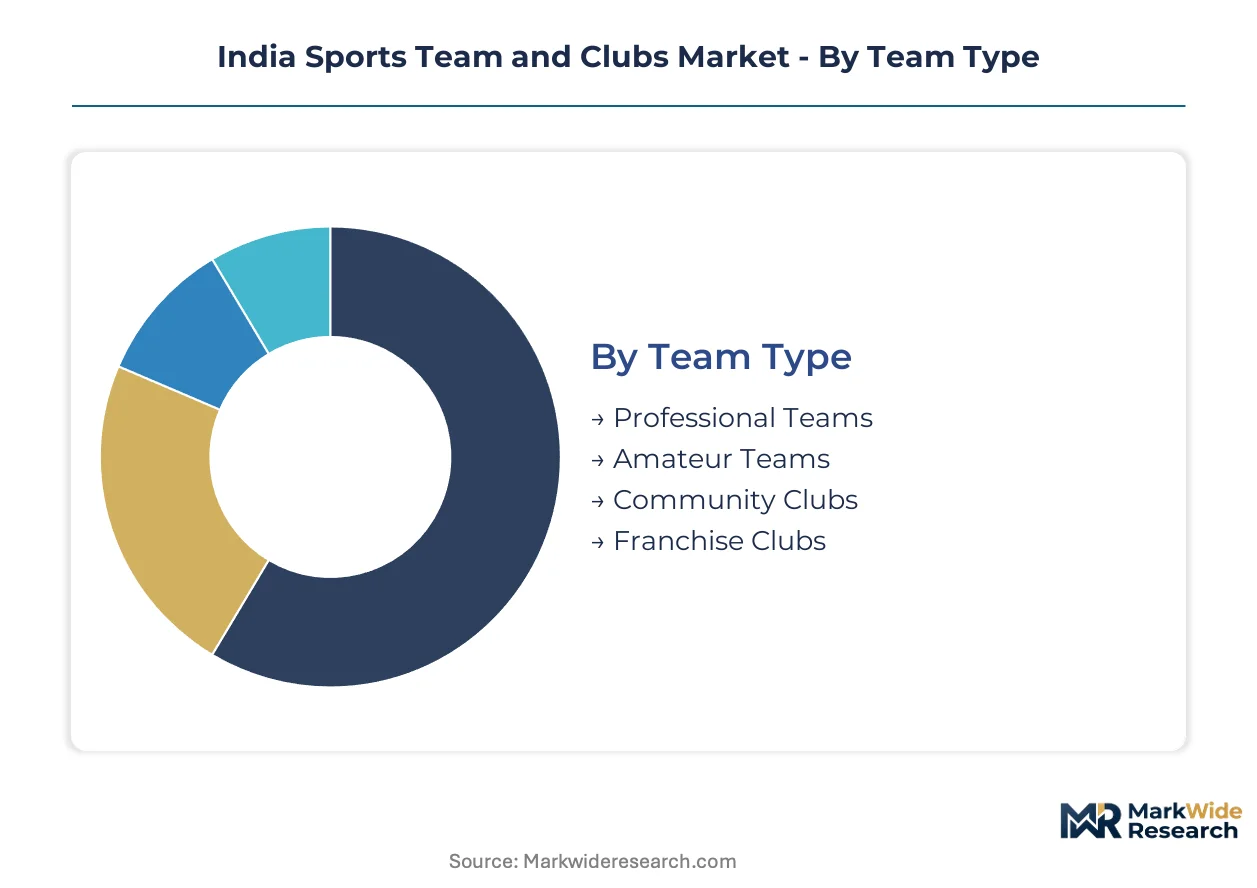
Segmentation in India's sports team and clubs market reveals how revenue flows concentrate through distinct organizational forms and sport-specific monetization channels. Understanding these splits enables stakeholders to align infrastructure investment with actual consumption patterns across membership tiers and media access points.
Team Type:
Cost tier determines capital intensity and revenue ceiling across organizational structures, with franchise models requiring the deepest capital pools.
- Franchise Clubs:Investor-owned entities operating under league licensing agreements with exclusive territorial rights. Maharashtra and Karnataka host the densest concentration of these operations, where corporate ownership structures absorb athlete contract inflation through diversified revenue portfolios.
- Professional Teams:Federated or privately operated squads competing in national leagues without franchise exclusivity. Tamil Nadu's hockey and athletics clubs exemplify this tier, where BIS facility compliance and SAI welfare mandates compress margins but sustain talent pipeline credibility.
- Amateur Teams:Association-governed competitive units relying on state federation subsidies and municipal venue access.
- Community Clubs:Membership-based local entities emphasizing participation over broadcast monetization.
Franchise clubs command the established base. The steepest expansion runs through professional teams as state sports policies incentivize formal league structures beyond cricket.
Sport Type:
Application context shapes sponsorship valuation and stadium infrastructure requirements across competitive disciplines.
- Cricket:Dominant revenue generator with franchise leagues commanding premium broadcast windows and merchandise throughput. IPL retention auctions and overseas league poaching have institutionalized athlete contract inflation as a structural cost.
- Football:ISL and I-League structures are drawing corporate sponsorship migration as cricket inventory saturates, with Bengaluru FC's academy output demonstrating youth-to-first-team monetization pathways.
- Kabaddi:Pro Kabaddi League has validated non-cricket broadcast viability through compressed match formats suited to mobile consumption.
- Field Hockey:Federation-governed structure limits franchise licensing potential despite historical national significance and SAI infrastructure investment.
Cricket commands the established base. The steepest expansion runs through football as streaming platforms bid for exclusive rights to younger demographics.
Membership Model:
Customer type segmentation reveals how clubs convert engagement depth into recurring revenue stability versus transactional match-day income.
- Corporate Membership:B2B packages bundling hospitality, branding rights, and talent access. Mumbai and Delhi enterprises drive demand here, using club associations for client entertainment and employee engagement programs.
- Family Packages:Multi-generational access tiers with youth academy priority enrollment. Karnataka clubs have pioneered this structure, linking parental subscription to junior development pathways.
- Individual Membership:Single-adult access with tiered benefits based on tenure and event attendance.
- Youth Programs:Age-segmented training subscriptions with progression ladders into competitive squads.
Corporate membership commands the established base. The steepest expansion runs through youth programs as Khelo India funding deepens grassroots club formation.
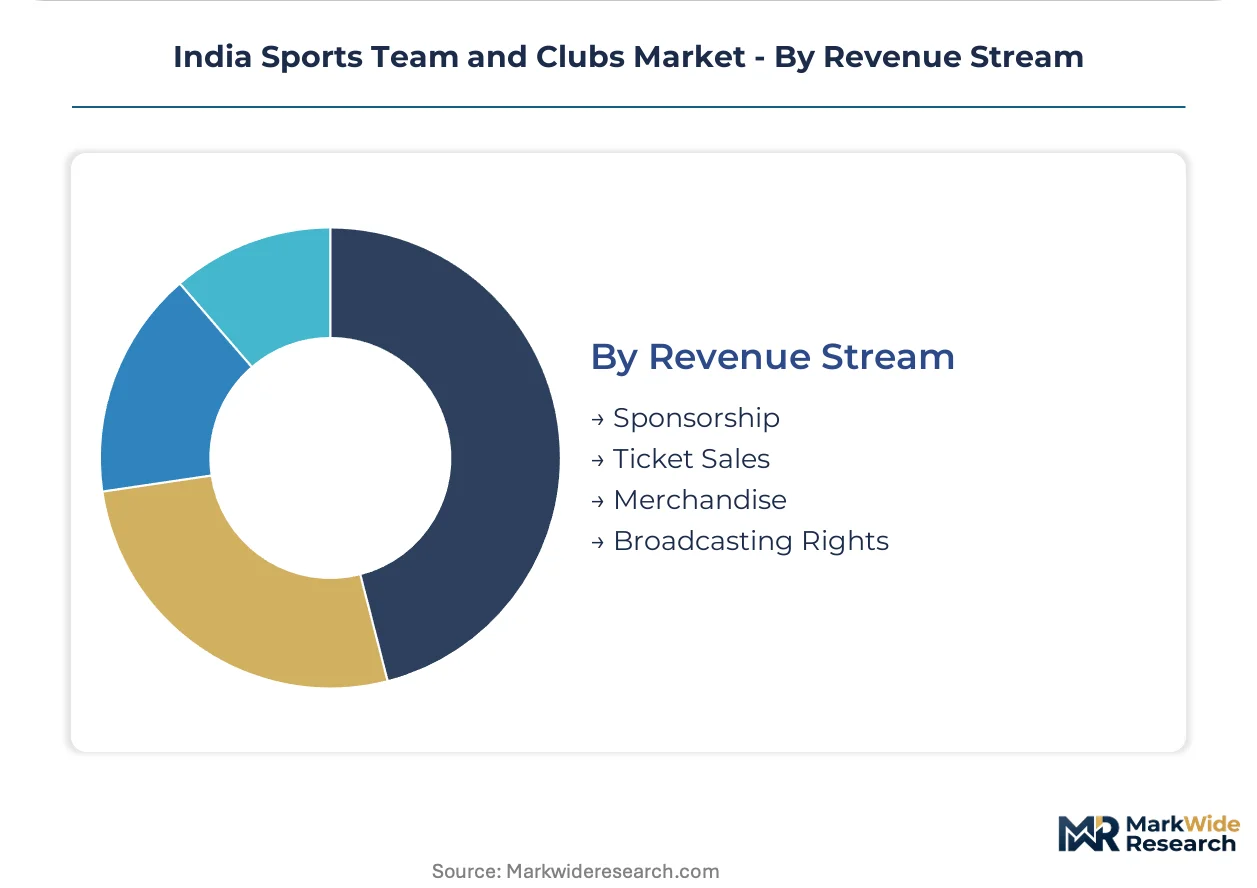
Revenue Stream:
Maturity stage differentiates between established transactional channels and emerging digital monetization architectures.
- Broadcasting Rights:Streaming platform exclusivity windows are compressing revenue allocation timelines and forcing clubs to restructure commercial partnerships around windowing rather than seasonal cycles.
- Sponsorship:Brand partnerships spanning jersey placement, stadium naming, and digital integration. Non-cricket sports are capturing fresh investment as cricket inventory saturates.
- Merchandise:Direct-to-consumer channels now outpace traditional retail distribution in Tamil Nadu and Karnataka, where mobile-first consumption patterns dominate.
- Ticket Sales:Match-day and season pass revenue retains margin stability in established metro venues with integrated digital payment infrastructure.
Sponsorship commands the established base. The steepest expansion runs through broadcasting rights as platform competition intensifies for exclusive content windows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mumbai Metro's operational expansion and the Delhi-Mumbai Industrial Corridor's logistics spine are underwriting Maharashtra's concentration of franchise headquarters and stadium infrastructure investment. Karnataka's Bengaluru-Chennai expressway corridor is compressing travel times for multi-city fan bases and talent scouting networks.
Maharashtra
Mumbai's corporate boardrooms are driving demand for premium hospitality suites and naming rights at Wankhede Stadium and the upcoming Navi Mumbai cricket venue. The state's sports department incentive schemes for private stadium investment are accelerating construction timelines under BIS facility standards. Pune and Nagpur are emerging as secondary franchise licensing targets with underutilized municipal venues.
Karnataka
Bengaluru's technology workforce is generating sustained demand for football season passes and youth academy enrollment at Bengaluru FC. Khelo India funding pipelines through the Sports Authority of India are deepening grassroots club formation in Mysuru and Hubli-Dharwad. The state's sports policy tailwinds are concentrating new franchise launches around the Sree Kanteerava Stadium complex.
Tamil Nadu
Chennai's manufacturing belt enterprises are purchasing corporate membership packages for client entertainment at M. A. Chidambaram Stadium. SAI's revised athlete welfare mandates are tightening medical infrastructure requirements for academy operators in Coimbatore and Madurai. The Tamil Nadu Cricket Association's stadium modernization program is attracting IPL franchise pre-season training camps.
Delhi-NCR
Delhi's government and diplomatic sector demand is sustaining premium pricing for hospitality boxes at Arun Jaitley Stadium and the Jawaharlal Nehru Stadium complex. The National Capital Region's fragmented municipal governance across Delhi, Gurgaon, and Noida is complicating venue lease negotiations for multi-city franchise operators. Faridabad and Ghaziabad are seeing speculative land acquisition for future sports infrastructure.
West Bengal
Kolkata's football heritage is sustaining demand for East Bengal and Mohun Bagan season passes despite cricket's broadcast dominance. The state's sports department is channeling Khelo India allocations into hockey and athletics infrastructure in Siliguri and Durgapur. Salt Lake Stadium's renovation under BIS standards is positioning the venue for multi-sport event hosting and franchise licensing opportunities.
India Sports Team and Clubs Market Competitive Landscape
On the supply side, the industry is fragmented across distinct organizational archetypes with limited operational overlap between franchise-owned leagues and federation-governed structures. Investor-owned entities compete for exclusive territorial rights through league licensing agreements, while state associations retain control over legacy venues and talent identification pipelines. The dominant strategic archetypes include corporate-backed franchise operators, community-rooted membership clubs, and federation-affiliated development academies. Competitive moves center on stadium-linked hospitality expansion and youth academy monetization through transfer fee generation.
Among South India-based franchise operators, Chennai Super Kings and Royal Challenger Bangalore exemplify the corporate-backed archetype with diversified revenue portfolios spanning media rights, merchandise, and regional sponsorship premiums. Bengaluru FC occupies a position within the football-specialist tier, differentiating through academy output and community programming rather than broadcast scale. These entities represent the convergence of territorial exclusivity and vertical integration into talent development infrastructure.
| Leading Market Players |
|---|
| Royal Challenger Bangalore |
| Chennai Super Kings |
| Chennaiyin FC |
| Bengaluru FC |
| Bombay Presidency Golf Club |
| Hockey India |
| Avalanche Motorsports |
| Basketball Federation of India |
| Meco Motorsports |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on municipal stadium authorities determines both pricing tier spreads and supply chain shape across India's sports franchise economy. This concentration forces franchise operators into inflexible lease terms that compress margins at the economy tier while enabling premium hospitality markups at controlled venues.
Pricing Analysis
Volume-discount tiering structures separate corporate hospitality blocks from individual season passes and youth academy enrollments. Price differentiation hinges on BIS facility certification grades and stadium-linked experiential bundling. Cost compression in the amateur team tier is intensifying because Khelo India subsidy pipelines face state-level allocation delays. Corporate membership packages show the lowest price sensitivity, while community club participation fees encounter resistance from cost-conscious family segments in Tier-II cities.
Supply Chain Analysis
Contract-manufacturing concentration for sports merchandise rests with textile clusters in Tirupur, Bangladesh, and Vietnam, while broadcast infrastructure draws from South Korean and Chinese equipment suppliers. Raw material dependencies span polyester performance fabrics, LED display modules, and biometric tracking sensors. Supply chain risk centers on tariff exposure for imported broadcast-grade connectivity hardware. Distribution runs through franchise-owned direct-to-consumer platforms, state association-controlled venue retail, and third-party e-commerce marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's sports team and clubs market represents an early-cycle expansion story, with streaming platform exclusivity bidding creating fresh monetization channels before inventory saturation sets in.
For Market Incumbents: Entrench territorial exclusivity through stadium-linked hospitality expansion and youth academy pipeline control. Acquire or long-term lease municipal venues in Pune and Nagpur before state sports policy incentives attract competing bidders. Athlete contract inflation from IPL retention auctions poses the primary margin threat; counter this with diversified revenue portfolios spanning merchandise direct-to-consumer and regional sponsorship premiums. For New Entrants and Emerging Players: Pursue Tier-II city franchise licensing in Jaipur, Kochi, and Guwahati where stadium infrastructure gaps allow first-movers to anchor venue construction timelines. Football and kabaddi present the most penetrable sport verticals as cricket inventory saturates and corporate sponsorship migrates toward untapped audience segments. A state sports policy alignment go-to-market angle accelerates municipal partnership negotiations and Khelo India funding access. For Investors and Strategic Acquirers: BIS facility certification mandates reshape the acquisition landscape by raising operational overhead barriers for subscale operators. Frame long-term viability around franchise operators with captive venue control and academy-to-first-team monetization pathways. Target acquisition archetypes: corporate-backed clubs with diversified media rights portfolios. The signal to watch is streaming platform consolidation reducing exclusivity bidding intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Stadium Infrastructure Partnership | Municipal lease agreements in Pune and Nagpur unlock captive venue revenue streams under Maharashtra sports policy incentives. |
| Youth Academy Monetization | Bengaluru FC's transfer fee generation from academy output demonstrates scalable talent pipeline economics. |
| Direct-to-Consumer Platform Launch | Chennai Super Kings' mobile-first merchandise channels bypass traditional retail margin compression in Tamil Nadu. |
| Streaming Rights Exclusivity Bid | Platform competition for ISL and Pro Kabaddi League windows captures younger demographics bypassing linear broadcast. |
| Corporate Membership Tier Expansion | Mumbai's manufacturing belt enterprises sustain premium pricing for hospitality boxes at Wankhede Stadium. |
Research Methodology
Desk research of Sports Authority of India annual reports, state sports department policy circulars, and BIS facility standards documentation preceded structured interviews with franchise operations directors, stadium venue managers, sports federation licensing officers, and streaming platform content acquisition leads. Secondary validation drew from TRAI broadcast infrastructure filings, municipal corporation lease records, and Khelo India funding allocation disclosures. Bottom-up revenue modeling across team types and sport verticals was triangulated against top-down market sizing from media rights transaction tracking.
Assumptions held fixed include current BIS certification timelines and state-level sports policy incentive structures, while streaming platform subscriber growth trajectories and corporate sponsorship migration rates were varied across sensitivity scenarios. Segmentation dimensions modeled span franchise versus professional versus amateur organizational forms, cricket versus football versus kabaddi versus hockey sport splits, and corporate versus family versus individual membership tiers. CAGRs were derived from hockey-stick adoption curves for digital streaming penetration and linear extrapolation of Khelo India funding disbursement trends. Forecast inputs incorporated athlete contract inflation indices and stadium construction cost escalations under revised SAI welfare mandates.
Macroeconomic conditions sit as an overlay; deviation in corporate marketing budget cycles and state fiscal health would shift the trajectory of sponsorship inflows and subsidy-dependent grassroots formation. Forecasts reflect these documented assumptions rather than deterministic predictions. Cross-checking against disclosed media rights transaction values and municipal lease rate benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Europe Sports Management Software Market
Sports & Fitness Technology
Racing Apparel Market
Sports & Fitness Technology
Sports Team and Clubs Market
Sports & Fitness Technology
Football Merchandise Market
Sports & Fitness Technology
Smart Swimming Caps Market
Sports & Fitness Technology
Sports Software Market
Sports & Fitness Technology
Smart Trainers Market
Sports & Fitness Technology
Europe Sports Team and Clubs Market
Sports & Fitness Technology
Smart Fitness Trainer Market
Sports & Fitness Technology
North America Sports Management Software Market
Sports & Fitness Technology
USA Sports Team and Club Market
Sports & Fitness Technology
Smart Stadium Market
Sports & Fitness Technology
Europe Spectator Sports Market
Sports & Fitness Technology
Crossfit Apparel Market
Sports & Fitness Technology
United States Sports Promoter Market
Sports & Fitness Technology
Sports Sponsorship Market