
 Asia-Pacific Fantasy Sports Market | 2026-2036
Asia-Pacific Fantasy Sports Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Fantasy Sports Market Outlook
Market Context
KYC verification under India's Central Consumer Protection Authority guidelines is rotating as the primary gating mechanism for platform participation. Dream11 leverages its first-mover scale to sustain dominance across cricket-centric user acquisition. MPL anchors its position through diversified sports coverage beyond cricket into kabaddi and football. FanCode differentiates through integrated live streaming and fantasy overlays that deepen user session duration.
Technical Definition and Structural Segments
Asia-Pacific fantasy sports comprises digital platforms where users assemble virtual teams from real athletes, earning points based on live statistical performance across cricket, football, basketball, and kabaddi contests. These systems operate on real-time data pipelines processing player statistics, injury updates, and weather conditions to score contests and distribute prize pools within minutes of match completion. Mobile App platforms capture the dominant share of engagement time as smartphone penetration outpaces desktop access across Southeast Asian and South Asian markets. Daily Fantasy Sports formats generate the fastest transaction velocity through rapid contest turnover, while Season-Long Fantasy retains higher per-user lifetime value through sustained engagement cycles. Entry Fees constitute the core monetization stream, though Advertisements and Sponsorships expand as operators seek revenue diversification beyond direct user payments.
Regulatory Framework
India's GST Council, the country's central indirect tax regulator, imposes tax obligations on online gaming transactions that reshape operator margin structures and user pricing. TRAI, India's telecommunications authority, governs data localization and platform access standards that affect cross-border fantasy operators. India's state-level gaming commissions, including those in Maharashtra and Karnataka, create fragmented compliance terrain where skill-versus-chance determinations vary by jurisdiction. Stakeholders must monitor evolving state-level classification rulings that determine whether fantasy sports qualify as games of skill exempt from gambling prohibitions or fall under wagering restrictions.
Market Dynamics
India's GST Council imposition of tax obligations on online gaming transactions is compressing operator margins and forcing pricing recalibration across the region's largest fantasy sports economy.
Growth Catalysts
- Smartphone penetration:Southeast Asian and South Asian markets witness mobile-first user acquisition as device affordability expands addressable audiences beyond urban centers.
- TRAI data localization standards:India's telecommunications authority mandates domestic server infrastructure that accelerates platform latency performance and user trust.
- Skill-versus-chance legal frameworks:Indian state-level gaming commissions in Maharashtra and Karnataka issue rulings exempting fantasy sports from gambling prohibitions, legitimizing operator business models.
Market Restraints
- Input cost volatility:Real-time data pipeline licensing fees from cricket boards and football leagues fluctuate with broadcast rights renewal cycles, pressuring content acquisition budgets.
- Regulatory fragmentation:India's state-level gaming commissions produce inconsistent skill-versus-chance determinations that force operators to maintain parallel compliance architectures.
- Payment infrastructure concentration:UPI and wallet provider dominance in India creates single-channel dependency risk for transaction processing.
Strategic Opportunities
- Underpenetrated Southeast Asian markets:Indonesia, Vietnam, and Philippines present mobile-first fantasy sports expansion potential with nascent local operator presence.
- Kabaddi and esports verticals:Indigenous sports and competitive gaming formats attract differentiated user cohorts underserved by cricket-centric incumbents.
- Integrated live streaming overlays:Fantasy platforms converging with broadcast rights holders create session duration expansion through second-screen engagement.
Industry Challenges
- Data science talent scarcity:Real-time scoring algorithm development and predictive analytics functions face recruitment competition from fintech and e-commerce sectors.
- KYC verification latency:India's Central Consumer Protection Authority guidelines impose identity verification bottlenecks that extend user onboarding timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Fantasy Sports Market |
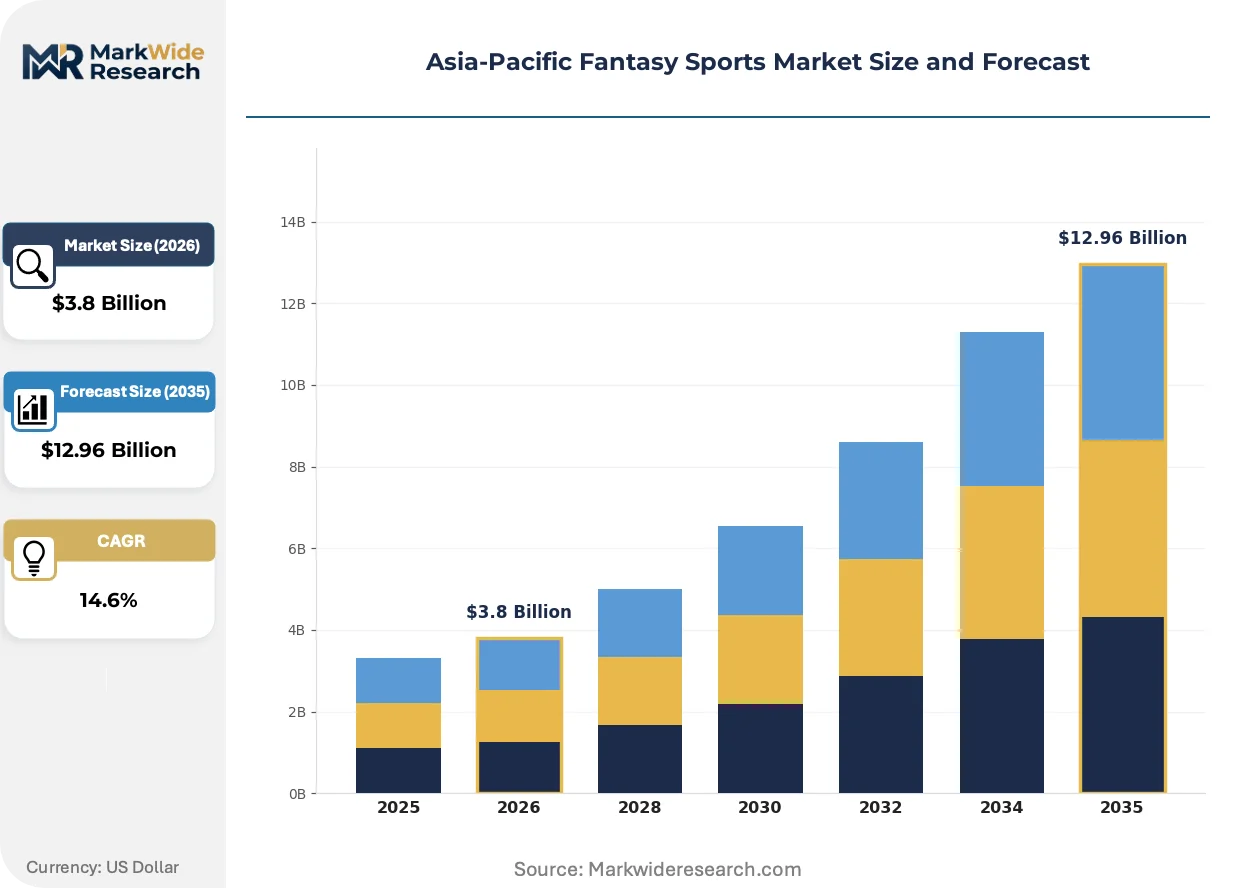
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Web-Based, Mobile App, Hybrid, Others Game Type: Daily Fantasy Sports, Season-Long Fantasy, League-Based Fantasy, Others Player Type: Active Players, Casual Players, Spectators, Beginners Monetization Model: Entry Fees, Advertisements, Subscriptions, Sponsorships |
| Companies Covered | FanCode, HalaPlay, Dream11, Games24x7, PlayUP, MPL, BalleBaazi, My11Circle, MyTeam11, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Fantasy Sports Market Strategic Shifts
Real-time data infrastructure and regulatory classification debates are restructuring how fantasy sports platforms architect their technology stacks and geographic expansion priorities.
AI-powered contest personalization engines are bifurcating user engagement models across the Asia-Pacific fantasy sports landscape. Tier-one operators deploy machine learning to dynamically adjust contest difficulty and prize pool sizing based on individual user skill profiles. Casual player segments receive simplified entry formats while high-frequency users access sophisticated multi-entry tournaments, compressing platform differentiation into algorithmic capability rather than sport coverage breadth.
India's GST Council taxation framework on online gaming is reshaping operator revenue recognition and prize pool structures. The indirect tax obligation forces platforms to absorb margin compression or pass costs to entry fees, altering user price sensitivity calculus. Daily fantasy sports formats face disproportionate impact as transaction velocity amplifies cumulative tax exposure relative to season-long alternatives.
Second-screen consumption patterns during live cricket broadcasts are displacing standalone fantasy app engagement across Indian urban centers. Users increasingly demand integrated experiences where team selection, real-time scoring, and social sharing occur within single interfaces. This behavioral shift pressures pure-play fantasy operators to secure streaming partnerships or develop proprietary broadcast capabilities to retain session share.
Asia-Pacific Fantasy Sports Market Segmentation
Segmentation in Asia-Pacific fantasy sports reveals how platform architecture, engagement duration, user sophistication, and revenue mechanics interact to determine operator profitability. Each dimension carries distinct margin implications as India's regulatory environment and Southeast Asia's mobile infrastructure reshape competitive economics.
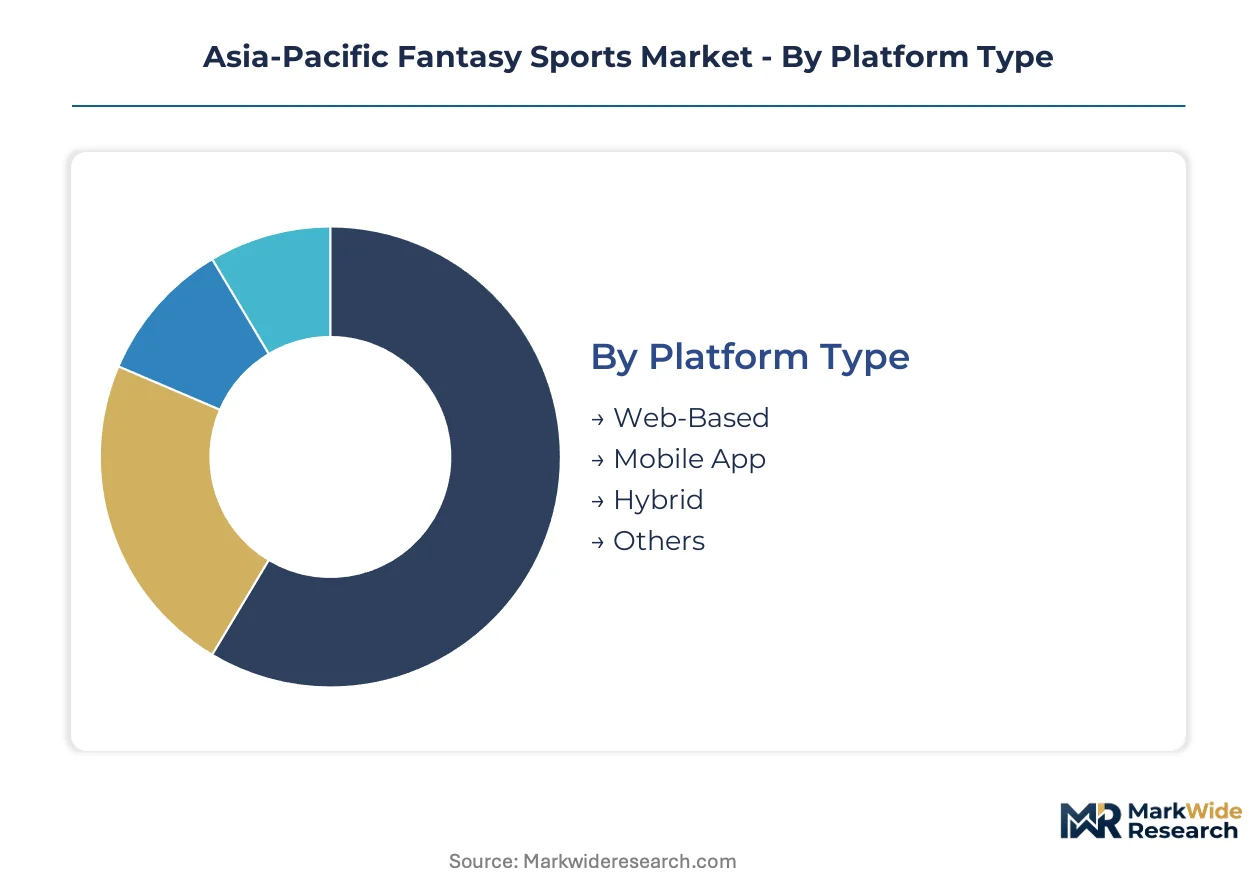
Platform Type:
Margin pools concentrate where latency performance and user acquisition costs diverge most sharply across access modalities.
- Mobile App:Native applications dominate session duration through push notification engagement and biometric payment integration. India's urban young professionals drive concentrated demand as smartphone penetration outpaces desktop infrastructure across Tier-2 and Tier-3 cities. TRAI's data localization mandates accelerate domestic server deployment, compressing latency for real-time scoring updates.
- Web-Based:Browser platforms retain relevance for office-hour access and lower-specification devices where app storage constraints limit adoption. Demand clusters in Indonesia and Philippines enterprise environments where corporate device policies restrict native application installation.
- Hybrid:Progressive web applications bridge functionality gaps through responsive design that adapts to network conditions. Thailand and Vietnam operators deploy hybrid architectures to accommodate variable connectivity across urban-rural divides.
- Others:Messaging-integrated mini-programs and super-app embeds capture fringe engagement through WeChat-style ecosystems in select Southeast Asian markets.
The dominant share belongs to Mobile App platforms, while Hybrid architectures are expanding most quickly as operators seek single-codebase efficiency across fragmented device ecosystems.
Game Type:
Revenue velocity and customer lifetime value trade off fundamentally across temporal engagement structures.
- Daily Fantasy Sports:Rapid contest turnover generates transaction density through same-day entry and settlement cycles. India's cricket calendar concentrates demand around IPL and international fixtures where single-match contests attract high-frequency participation. GST exposure accumulates disproportionately here as entry fee velocity amplifies cumulative tax obligations relative to longer formats.
- Season-Long Fantasy:Extended engagement cycles sustain subscription-like retention through multi-month team management commitments. European football leagues anchor demand in Australia and Southeast Asian expatriate communities where Premier League and Bundesliga following runs deep.
- League-Based Fantasy:Private contest formats among social networks reduce customer acquisition costs through organic viral mechanics. India's kabaddi Pro League and emerging esports tournaments attract cohort-specific engagement outside cricket saturation.
- Others:Prediction markets and prop-bet style formats occupy regulatory gray zones in jurisdictions with ambiguous skill-versus-chance determinations.
Season-Long Fantasy commands the highest per-user lifetime value, though Daily Fantasy Sports is gaining share fastest through India's cricket-centric transaction velocity.
Player Type:
Monetization depth varies inversely with onboarding friction across sophistication tiers.
- Active Players:High-frequency participants generate disproportionate revenue through multi-entry tournament participation and premium contest tiers. India's metropolitan centers concentrate this cohort where fantasy sports literacy and disposable income align.
- Casual Players:Irregular engagement patterns respond to major sporting events and promotional incentive structures. Southeast Asian markets exhibit higher casual ratios as fantasy sports familiarity develops.
- Spectators:Non-paying users provide audience value for advertising monetization and social proof dynamics. Free-to-play contests and prediction games retain this segment for eventual conversion pipelines.
- Beginners:First-time users face KYC verification bottlenecks under India's Central Consumer Protection Authority guidelines that extend onboarding timelines and elevate early-stage churn risk.
Active Players contribute the dominant revenue share, while Casual Players are climbing the fastest as simplified entry formats reduce participation barriers.
Monetization Model:
Direct user payment dependence creates regulatory and pricing vulnerability that diversification strategies seek to mitigate.
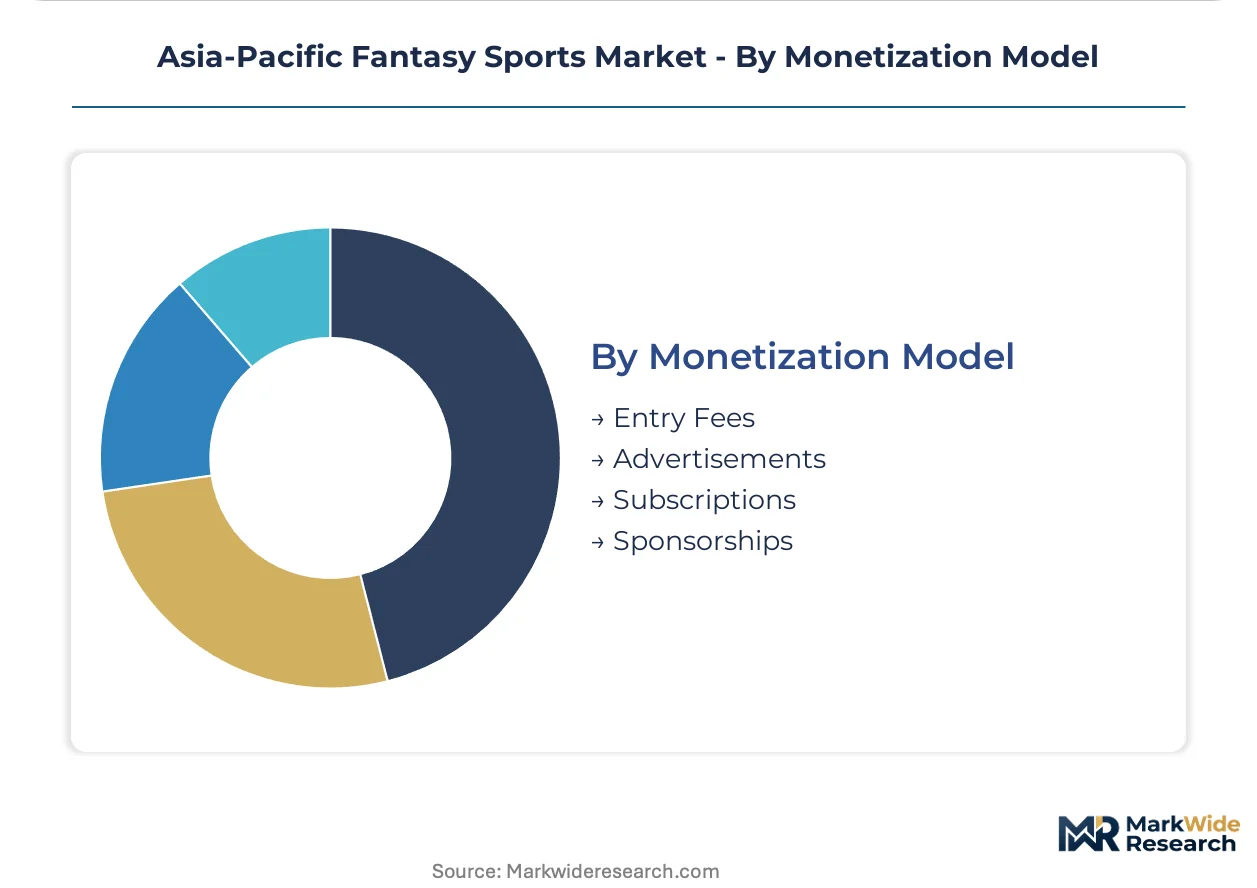
- Entry Fees:Contest participation payments constitute core revenue through percentage-based platform rake structures. India's GST Council taxation directly impacts this stream, forcing absorption or pass-through decisions that alter competitive positioning.
- Advertisements:Brand placement within contest lobbies and scoring interfaces expands as operators seek revenue beyond direct user payments. Sports apparel and fintech advertisers concentrate spend during cricket's high-viewership windows.
- Subscriptions:Premium tier access with enhanced analytics and exclusive contests builds predictable recurring revenue. Australia's mature fantasy market exhibits higher subscription penetration relative to India's transaction-focused economy.
- Sponsorships:League and team partnerships provide integrated brand exposure through jersey placements and broadcast overlay inventory. IPL franchise associations command premium positioning fees from fantasy operators.
Entry Fees retain the dominant share, though Advertisements are expanding most quickly as operators diversify beyond GST-exposed transaction revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's GST Council taxation framework on online gaming transactions is compressing operator margins across the region's largest fantasy sports economy while accelerating compliance investment. Southeast Asian markets present underpenetrated expansion vectors as smartphone penetration outpaces regulatory maturation. Australia's mature fantasy infrastructure sustains subscription-oriented monetization distinct from India's transaction-heavy model.
India
Urban young professionals in Mumbai, Bangalore, and Delhi drive concentrated demand through mobile-first cricket engagement. TRAI's data localization mandates accelerate domestic server deployment, compressing latency for real-time scoring. Maharashtra and Karnataka state gaming commissions issue divergent skill-versus-chance rulings, forcing operators to maintain parallel compliance architectures.
Australia
European football following among expatriate communities anchors season-long fantasy participation with higher per-user lifetime value. The country's telecommunications regulator enforces domestic data residency standards that elevate platform infrastructure investment. Sydney and Melbourne concentrate operator development activity as subscription penetration exceeds regional peers.
Indonesia
Nascent fantasy sports literacy and expanding smartphone affordability create first-mover expansion opportunities for mobile-native platforms. The country's national communications ministry governs digital platform licensing with evolving clarity on skill-based gaming classifications. Jakarta and Surabaya emerge as initial user acquisition targets where football-centric engagement precedes cricket development.
Vietnam
Rapid mobile internet adoption and esports viewership growth generate demand for fantasy overlays on competitive gaming formats. Domestic regulations on online gaming remain in formative stages, creating uncertainty on skill-versus-chance determinations. Ho Chi Minh City and Hanoi concentrate early operator presence through hybrid web-app deployment accommodating variable connectivity.
Philippines
Basketball-centric fantasy participation leverages the country's established sports betting culture and English-language platform accessibility. The national gaming regulator maintains jurisdiction over online wagering activities with ambiguous classification of skill-based formats. Metro Manila serves as the operational hub where corporate device policies favor web-based platform access over native application installation.
Asia-Pacific Fantasy Sports Market Competitive Environment
Listed leaders compete with private specialists across monetization model diversification and geographic expansion vectors. The vendor base concentrates around cricket-centric Indian operators with fragmented presence across Southeast Asian growth markets. Three strategic archetypes dominate: diversified sports coverage platforms, single-sport depth specialists, and integrated streaming-fantasy hybrids. Competitive intensity manifests through broadcast rights partnerships and second-screen experience convergence rather than pure user acquisition spend.
Within the integrated streaming tier, FanCode occupies a position exemplifying session duration expansion through live broadcast overlays. Among diversified coverage specialists, MPL and Dream11 anchor the competitive set through multi-sport engagement models spanning cricket, kabaddi, and football. These operators represent scale-driven archetypes where first-mover positioning sustains user base concentration against emerging challengers.
| Leading Market Players |
|---|
| FanCode |
| HalaPlay |
| Dream11 |
| Games24x7 |
| PlayUP |
| MPL |
| BalleBaazi |
| My11Circle |
| MyTeam11 |
| Others |
Value Chain & Pricing Dynamics
Long-term data licensing contracts with cricket boards and football leagues lock in both real-time feed access and cost visibility for Asia-Pacific fantasy operators, insulating platforms from spot-market volatility in sports statistics pricing while embedding fixed cost obligations that compress margin flexibility during regulatory tax shifts.
Pricing Analysis
Entry fee rake percentages create the primary spread between operator profitability tiers, with premium platforms commanding higher takes through enhanced scoring algorithms and faster settlement cycles. Three-tier pricing structure across high-frequency tournaments, casual entry pools, and free-to-play contests segments users by engagement depth. Cost compression in casual tiers is intensifying because India's GST Council tax obligations force either margin absorption or user-facing price hikes. Casual players exhibit highest price sensitivity, while high-frequency active players tolerate elevated entry fees for sophisticated multi-entry formats.
Supply Chain Analysis
Just-in-time data pipeline architecture leaves minimal buffer against cricket board feed interruptions or server latency spikes during high-traffic tournament windows. Real-time statistics infrastructure concentrates in India, Singapore, and Australia where TRAI-mandated data localization accelerates domestic server deployment. Raw material dependencies span live match data feeds from BCCI and ICC, cloud compute capacity from hyperscalers, and payment gateway integrations through UPI infrastructure. Single-source vulnerability runs through concentrated cricket calendar clustering where IPL and international fixtures create simultaneous demand spikes. Distribution runs through mobile app stores and direct APK downloads bypassing platform fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of data science talent capable of building real-time scoring algorithms and predictive contest personalization engines constrains platform differentiation, forcing operators to compete for machine learning specialists against fintech and e-commerce sectors with deeper compensation pools.
For Market Incumbents: Secure exclusive broadcast rights partnerships before integrated streaming-fantasy hybrids capture second-screen session share, and lock in multi-year data licensing contracts with cricket boards to preempt cost inflation from competitive bidding. Vertical integration into proprietary live streaming infrastructure defends against FanCode-style convergence plays eroding standalone fantasy engagement. For New Entrants and Emerging Players: BIS certification fast-track for payment processing compliance accelerates market entry in India where KYC verification bottlenecks extend onboarding timelines for uncertified competitors. Target underpenetrated kabaddi and esports verticals where cricket-centric incumbents lack sport-specific algorithm depth, and deploy hybrid web-app architectures to capture Southeast Asian markets with variable connectivity. For Investors and Strategic Acquirers: Specialist AI-driven contest personalization shops with proven machine learning talent represent priority acquisition targets as algorithmic capability displaces sport coverage breadth as the primary competitive moat. Long-term viability hinges on regulatory arbitrage resilience across India's fragmented state-level skill-versus-chance determinations. Watch for GST Council rate revisions as the critical inflection signal for operator margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Broadcast Rights Partnership | Locks in second-screen engagement through integrated live streaming overlays during IPL and international cricket fixtures. |
| Multi-Year Data Licensing Contract | Insulates platforms from cricket board fee inflation and secures real-time feed priority during high-traffic tournament windows. |
| AI Contest Personalization Engine | Differentiates user experience through dynamic difficulty adjustment and prize pool sizing based on individual skill profiles. |
| Hybrid Web-App Architecture Deployment | Captures Southeast Asian expansion markets with variable connectivity across Indonesia, Vietnam, and Philippines. |
| Kabaddi and Esports Vertical Launch | Attracts differentiated user cohorts underserved by cricket-centric incumbents in India's Pro Kabaddi League ecosystem. |
Study Parameters
Desk research of cricket board licensing agreements, TRAI regulatory filings, and GST Council taxation frameworks preceded structured interviews with platform product managers, data engineering leads, state gaming commission officials, and sports broadcast rights negotiators. Primary fieldwork across Mumbai, Bangalore, and Delhi validated secondary intelligence on user acquisition costs and retention metrics. Bottom-up sizing of entry fee volumes and top-down cross-check against advertising spend disclosures triangulated market estimates.
Variance decomposition across platform type, game format, and monetization model dimensions shaped the analytical framework over the projection horizon. Modeled segmentation spans mobile app versus web-based access, daily fantasy versus season-long engagement, and entry fee versus advertising revenue streams. CAGRs were derived from smartphone penetration curves, cricket calendar density, and regulatory tax incidence modeling. Forecast inputs incorporated UPI transaction velocity trends and state-level skill-versus-chance ruling trajectories.
Underlying assumptions cover sustained GST rate stability and continued smartphone affordability expansion, with deviation risk concentrated in regulatory reclassification events that could shift fantasy sports into gambling-prohibited categories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
UK Sports Management Software Market
Sports & Fitness Technology
Padel Court Operator Market
Sports & Fitness Technology
3D Motion Capture Market
Sports & Fitness Technology
Europe Sports Team and Clubs Market
Sports & Fitness Technology
Racing Apparel Market
Sports & Fitness Technology
Europe Sports Management Software Market
Sports & Fitness Technology
Germany Sports Teams and Clubs Market
Sports & Fitness Technology
Sports Sponsorship Market
Sports & Fitness Technology
North America Sports Team and Clubs Market
Sports & Fitness Technology
Sportswear Rental and Rotation Market
Sports & Fitness Technology
UK Sports Team and Clubs Market
Sports & Fitness Technology
India Sports Team and Clubs Market
Sports & Fitness Technology
Sports Team and Clubs Market
Sports & Fitness Technology
UK Spectator Sports Market
Sports & Fitness Technology
Europe Spectator Sports Market
Sports & Fitness Technology
Sports Software Market