
 Spices, Dry Mixes and Extracts Packaging Market | 2026-2036
Spices, Dry Mixes and Extracts Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Spices, Dry Mixes and Extracts Packaging Market Insights
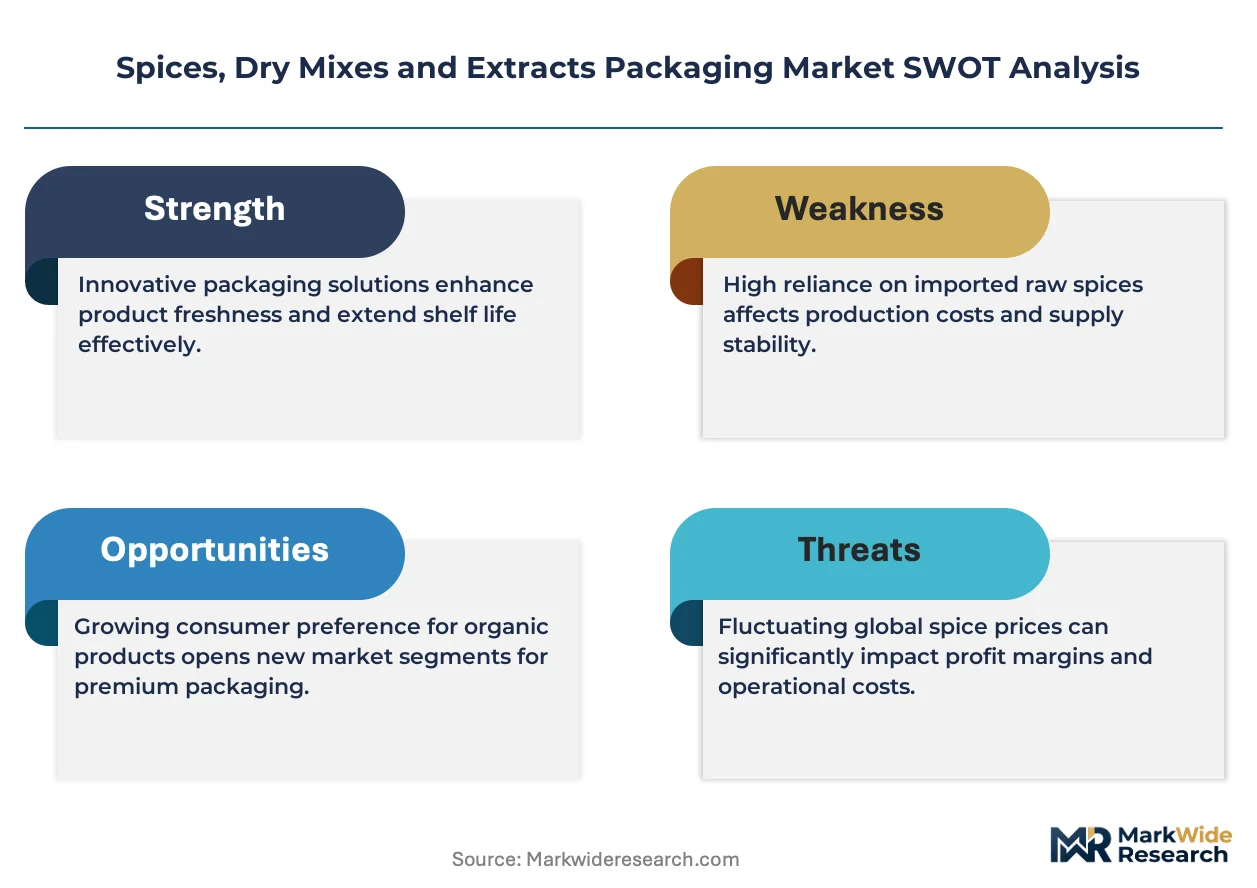
Subscription-based packaging replenishment services for restaurant chains and cloud kitchens is hardening into a distinct revenue layer for converters. Amcor Group GmbH leverages its global film and laminate portfolio to secure multi-year supply contracts with multinational spice brands. Berry Global Group anchors North American capacity through blown film operations optimized for high-barrier seasoning pouches. Mondi Plc differentiates via paper-based barrier solutions that target plastic-reduction commitments in European retail.
Spices, dry mixes and extracts packaging encompasses primary and secondary containment systems engineered to protect volatile aromatic compounds from moisture, oxygen, and ultraviolet degradation, typically employing multilayer coextruded films, metallized substrates, or amber glass with hermetic closure systems to preserve organoleptic properties through shelf life. Pouches capture the fastest expansion as flexible formats reduce material weight and shipping cube for e-commerce spice subscriptions. Glass jars retain premium positioning in retail stores where visual product authenticity commands shelf price separation. Plastic containers dominate food service volumes where durability through commercial kitchen handling outweighs disposal considerations.
The FDA's Food Safety Modernization Act preventive controls and the EU Packaging and Packaging Waste Regulation collectively elevate compliance costs for importers while creating specification advantages for converters with certified quality management systems. India's BIS certification requirements for food-contact materials add a second layer of market access filtering for export-oriented suppliers. Stakeholders must monitor how rapidly evolving extended producer responsibility frameworks in major demand centers reshape total cost of ownership calculations for material choices.
Market Dynamics
The EU Packaging and Packaging Waste Regulation's recyclability mandates are compressing material choice windows for converters while food service labor inflation accelerates portion-controlled format adoption across restaurant chains and cloud kitchens.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability thresholds above 70% by 2030 force converters toward mono-material laminates, opening specification advantages for certified film suppliers.
- Food service labor inflation:Kitchen wage pressures in the United States and Western Europe drive procurement of pre-portioned sachets that reduce prep time and waste for chain operators.
- India's spice processing clusters:Gujarat and Kerala facilities are scaling automated packaging lines to capture export demand for value-added spice blends.
Market Restraints
- Aluminum metallized film supply:Thin-gauge substrate availability concentrates among Asian suppliers, exposing converters to freight volatility and lead time extensions.
- High-barrier mono-material technical ceiling:Current polyethylene and polypropylene structures fail to match metallized polyester oxygen transmission rates for volatile extract oils.
- India BIS certification timelines:Food-contact material testing protocols extend market entry cycles for European and North American film exporters.
Strategic Opportunities
- Subscription replenishment channels:Direct-to-kitchen packaging services for restaurant chains bypass traditional distributor markups and lock in multi-year volume commitments.
- Paper-based barrier convergence:Fiber substrates paired with bio-based coatings target plastic-reduction commitments in German and French retail banners.
- Extended producer responsibility frameworks:France's Citeo and Italy's CONAI eco-modulation fees reward lightweight flexible formats over rigid containers.
Industry Challenges
- Migration testing expertise:Analytical chemists capable of validating compliance with EU 10/2011 food-contact plastics regulations remain scarce among mid-tier converters.
- Legacy equipment retrofit costs:Converting lines engineered for multi-layer structures require capital outlay for sealant layer modifications to run recyclable mono-materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spices, Dry Mixes and Extracts Packaging Market |
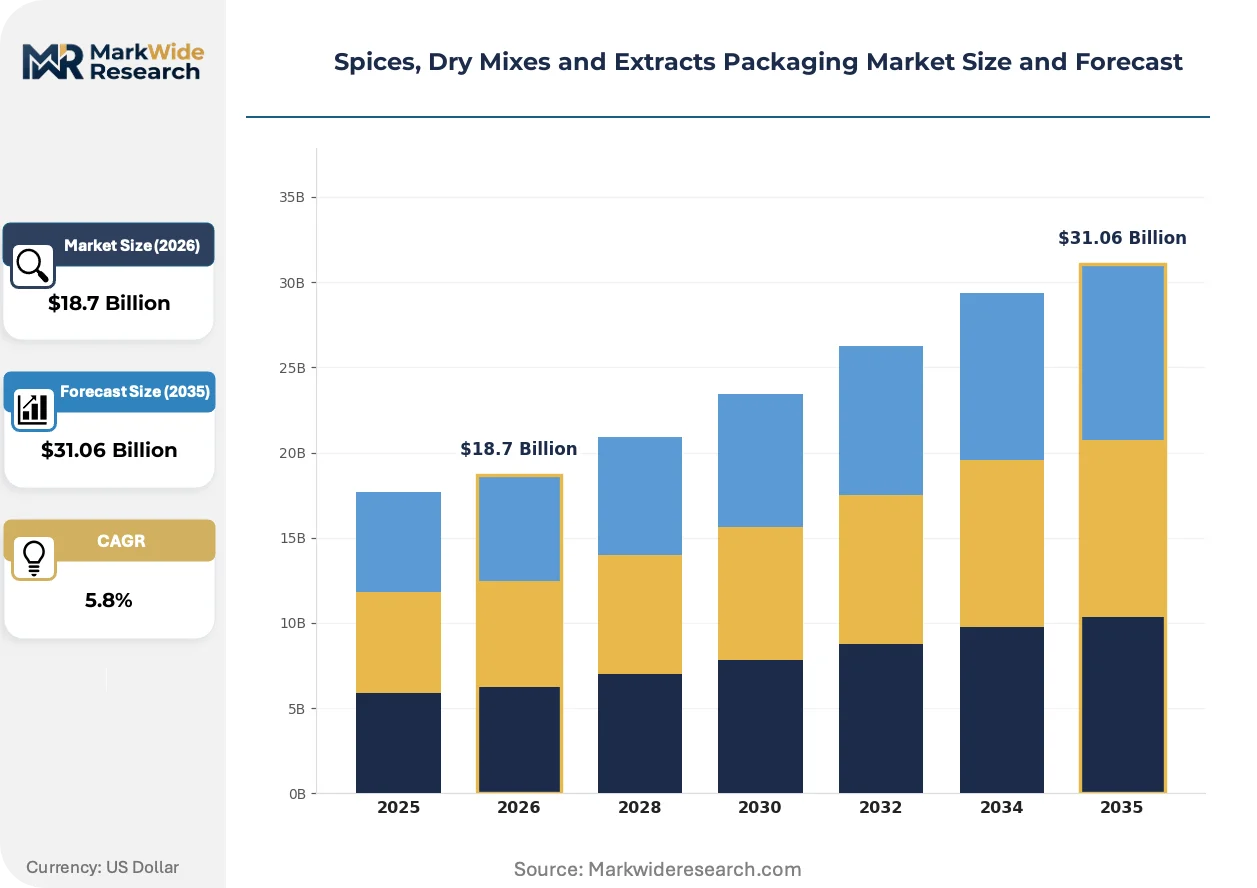
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Glass Jars, Plastic Containers, Pouches, Tin Ties Closure Type: Screw Caps, Flip-top Lids, Zipper Closures, Shrink Bands End User: Retail Stores, Food Service, Online Retail, Industrial Users Material: Glass, Plastic, Paper, Metal |
| Companies Covered | Amcor Group GmbH, Berry Global Group, Winpak Ltd, ALPLA Group, Mondi Plc, Sealed Air Corporation, Sonoco Products Company, Constantia Flexibles, Amcor Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spices, Dry Mixes and Extracts Packaging Market Trends and Innovations
Digital printing and smart packaging integration are compressing minimum order quantities while regulatory pressure on plastic intensity accelerates substrate experimentation across the value chain.
Digital inkjet printing on flexible films is decentralizing short-run spice label production. Regional co-packers serving ethnic grocery channels in the United States and United Kingdom adopt web-to-print workflows that collapse lead times from weeks to days. Brand owners are fragmenting SKU portfolios without inventory risk, enabling hyper-localized blends for diaspora populations.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant fluorochemical coatings from paper spice sachets. German and Dutch converters accelerate testing of bio-based barrier coatings derived from alginate and chitosan. Premium retail segments absorb price premiums for certified plastic-free packaging while food service buyers delay adoption pending performance validation.
Cloud kitchen operators are consolidating procurement through integrated packaging-and-ingredient platforms. Mumbai and Bangalore-based kitchen aggregators negotiate bundled contracts that specify portion-controlled sachet formats as a condition of supplier onboarding. This behavior concentrates buying power among fewer decision-makers and compresses converter margins through volume-commitment pricing.
Spices, Dry Mixes and Extracts Packaging Market Segmentation
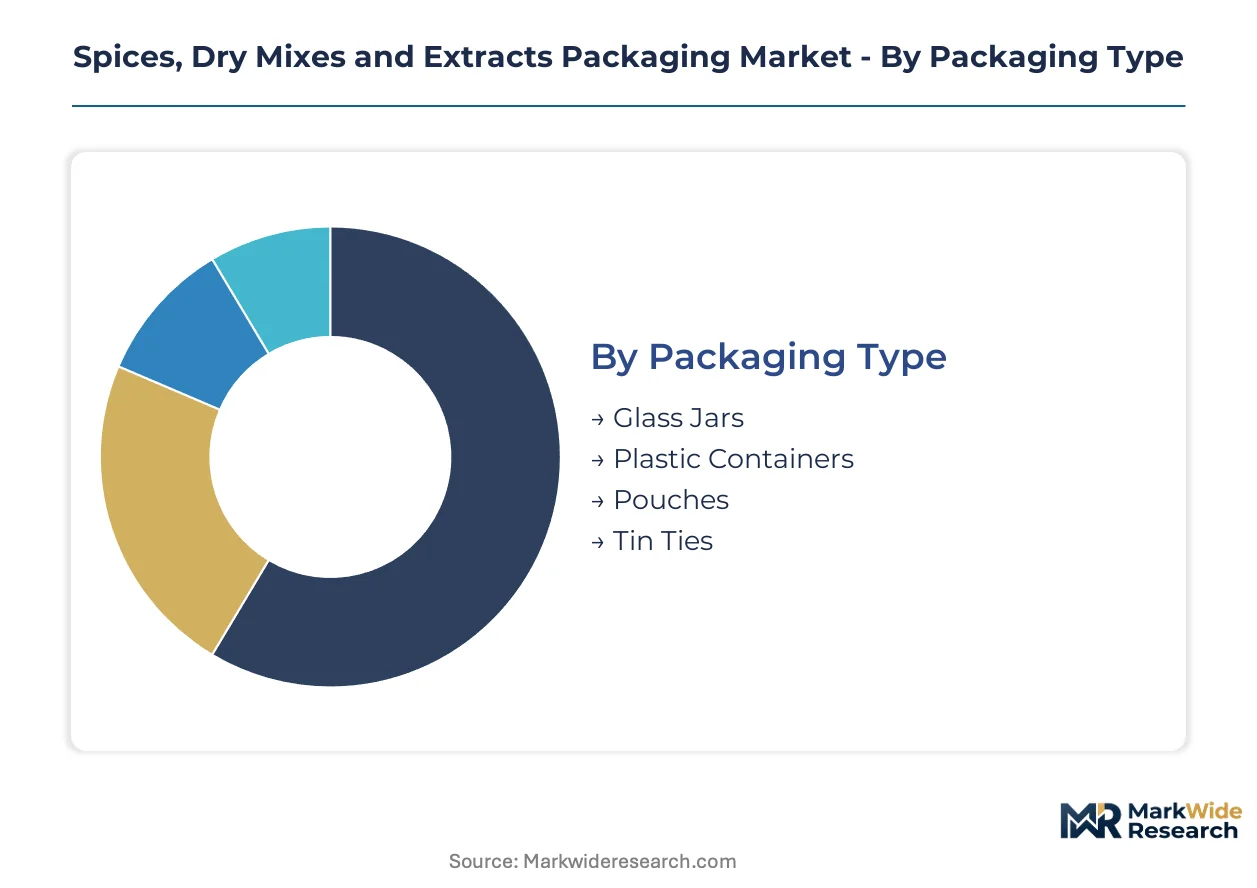
Segmentation in spices, dry mixes and extracts packaging reflects divergent certification burdens across formats. Glass jars demand FDA and EFSA compliance for hermetic seals, while flexible pouches navigate EU Packaging and Packaging Waste Regulation recyclability thresholds. Material selection directly determines which regulatory pathways converters must certify against.
Packaging Type:
Glass jars carry the heaviest certification load through FDA's 21 CFR 177.1520 for food-contact substances and EFSA's migration testing protocols, while pouches face intensifying scrutiny under extended producer responsibility frameworks.
- Pouches:Multilayer coextruded films or metallized laminates engineered for oxygen and moisture barrier protection. Demand concentrates in United States cloud kitchen procurement and Indian export processing facilities in Gujarat, driven by food service labor cost inflation and e-commerce shipping efficiency requirements.
- Glass Jars:Amber or clear soda-lime glass with hermetic metal lug closures, specified for volatile essential oil stability. Premium retail positioning in German and French supermarkets commands shelf price separation where visual authenticity drives consumer selection.
- Plastic Containers:High-density polyethylene or polypropylene rigid formats with tamper-evident features, specified for commercial kitchen durability.
- Tin Ties:Paperboard structures with metal wire closures, limited to dry spice sachets with lower barrier requirements.
Leading the category by volume: Plastic containers. Expanding most quickly: Pouches.
Closure Type:
Closure selection tracks end-use handling intensity, with screw caps and flip-top lids dominating food service durability specifications while zipper closures capture retail convenience positioning.
- Screw Caps:Continuous thread metal or plastic closures with induction seal liners, specified for glass jar hermeticity. Metal lug variants face EU REACH compliance for heavy metal content in sealing compounds.
- Zipper Closures:Press-to-close polyethylene profiles integrated into flexible pouch top seals, enabling resealability for multi-use retail formats. Demand concentrates in United Kingdom ethnic grocery channels and United States subscription spice services.
- Flip-top Lids:Hinged polypropylene closures specified for single-hand operation in commercial kitchen environments.
- Shrink Bands:PVC or PET-G heat-shrinkable sleeves providing tamper evidence, subject to state-level extended producer responsibility fees in California and Maine.
Dominating food service procurement: Screw caps. Gaining share fastest: Zipper closures.
End User:
End user segmentation separates specification authority between procurement teams optimizing for total cost of ownership versus brand managers prioritizing shelf differentiation.
- Food Service:Chain restaurant and cloud kitchen operators specifying portion-controlled sachets and bulk dispensers. Procurement concentrates through Mumbai and Bangalore kitchen aggregator platforms bundling packaging with ingredient supply.
- Retail Stores:Supermarket and specialty spice brand owners specifying premium glass jar formats with label differentiation. German retail banners drive paper-based barrier adoption through plastic-reduction commitments.
- Online Retail:Direct-to-consumer subscription services specifying lightweight flexible formats optimized for parcel shipping cube efficiency.
- Industrial Users:Food manufacturers procuring bulk spice and extract containment for further processing into finished products.
Generating highest volume throughput: Food service. Steepest expansion trajectory: Online retail.
Material:
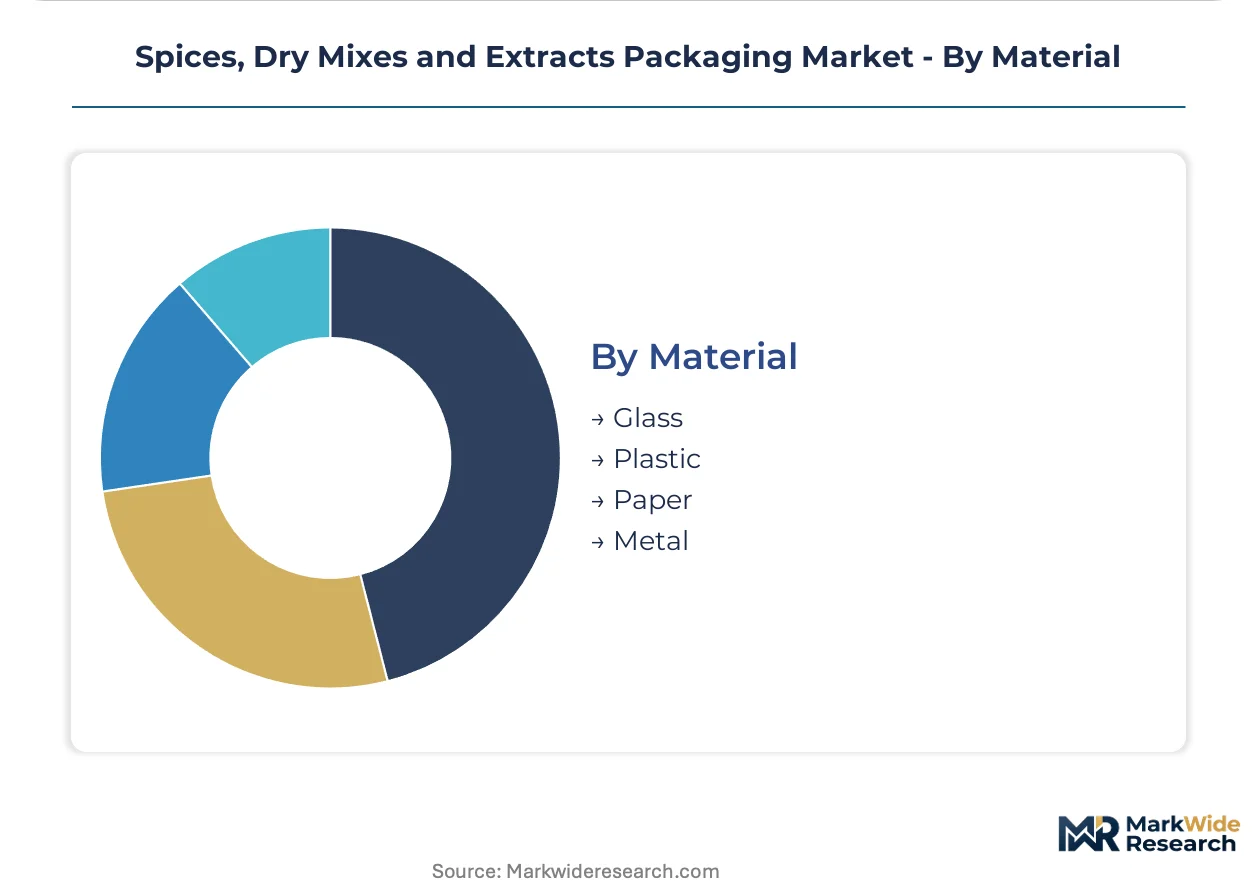
Material certification pathways diverge sharply, with glass and metal facing minimal food-contact regulatory burden while plastics navigate EU 10/2011 compliance and paper substrates confront PFAS elimination deadlines.
- Plastic:Polyethylene, polypropylene, polyester, and polyamide films in mono-layer or coextruded structures. BIS certification requirements for Indian market entry extend testing timelines for European and North American exporters.
- Paper:Kraft or glassine substrates with bio-based barrier coatings replacing fluorochemical treatments. German and Dutch converters accelerate alginate and chitosan coating validation under REACH PFAS restrictions.
- Glass:Soda-lime or borosilicate formats with minimal regulatory burden beyond heavy metal content limits in colored variants.
- Metal:Tinplate or aluminum structures for specialty extract containment, limited by thin-gauge substrate supply concentration among Asian suppliers.
Highest regulatory compliance cost: Plastic. Fastest substrate transition: Paper.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India processes the majority of traded spices while the United States and Germany consume the highest-value packaged formats. This production-consumption divide shapes regional investment patterns across the value chain.
United States
Cloud kitchen operators in New York and Los Angeles drive procurement of portion-controlled sachets as kitchen labor costs climb. FDA's Food Safety Modernization Act preventive controls elevate compliance costs for imported flexible films. Chicago and Dallas distribution hubs concentrate spice packaging converter capacity to serve national food service chains.
Germany
Retail banners in Berlin and Munich demand paper-based barrier solutions under plastic-reduction commitments. REACH restrictions on per- and polyfluoroalkyl substances eliminate fluorochemical coatings from spice sachets. Hamburg and Düsseldorf converters accelerate alginate and chitosan coating validation for bio-based alternatives.
India
Export-oriented processing facilities in Gujarat and Kerala scale automated packaging lines for value-added spice blends. BIS certification requirements for food-contact materials extend market entry timelines for European film suppliers. Mumbai and Bangalore kitchen aggregators bundle packaging procurement with ingredient supply contracts.
United Kingdom
Ethnic grocery channels in London and Birmingham adopt web-to-print workflows for hyper-localized spice labels. Extended producer responsibility frameworks through packaging recovery notes reshape material cost calculations. Manchester and Leeds co-packers serve diaspora populations with short-run flexible formats.
France
Premium retail positioning in Paris supermarkets commands shelf price separation for glass jar formats. Citeo eco-modulation fees reward lightweight flexible formats over rigid containers. Lyon and Marseille converters target German and French retail plastic-reduction commitments with fiber substrates.
Spices, Dry Mixes and Extracts Packaging Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across material and format specialization. The market structures around three tiers: multinational film and laminate suppliers with global certification portfolios, regional converters serving ethnic grocery and food service niches, and specialty glass and metal container fabricators for premium extract segments. Consolidation pressure intensifies as EU recyclability mandates favor converters with certified quality management systems and migration testing expertise.
Among diversified packaging conglomerates, Amcor Group GmbH and Berry Global Group exemplify scale-driven positions anchored in multi-year supply contracts with multinational spice brands. Mondi Plc occupies a distinct archetype through paper-based barrier solutions targeting European retail plastic-reduction commitments. These three entities represent the strategic spectrum: global laminate dominance, North American blown film optimization, and fiber substrate differentiation.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Berry Global Group |
| Winpak Ltd |
| ALPLA Group |
| Mondi Plc |
| Sealed Air Corporation |
| Sonoco Products Company |
| Constantia Flexibles |
| Amcor Plc |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between EU 10/2011 compliant laminates and uncertified commodity films manifests in both pricing power concentration among accredited converters and supply chain bifurcation toward audited Asian suppliers. Premium-mid-economy pricing differentiation separates food service bulk procurement from retail subscription formats, with compliance burden acting as the primary cost stack separator.
Pricing Analysis
Margin tightening in flexible pouch formats reflects aluminum metallized substrate supply concentration among Asian suppliers and freight volatility exposure. Three-tier pricing structure across premium glass jar, standard multilayer pouch, and economy tin tie formats tracks barrier performance and certification burden. Cost-down pressure on commodity polyethylene structures accelerates as Indian BIS testing timelines extend market entry cycles for European exporters. Food service procurement teams exhibit highest price sensitivity through volume-commitment negotiations, while German retail banners absorb premiums for paper-based barrier validation.
Supply Chain Analysis
Freight cost volatility from thin-gauge metallized film suppliers in China, South Korea, and Taiwan compresses converter margins on trans-Pacific lanes. Raw material dependencies center on polyethylene resin, aluminum substrate, and bio-based coating precursors from alginate and chitosan suppliers. Single-source vulnerability in high-barrier mono-material technical capacity exposes European converters to specification risk. Distribution runs through Mumbai and Bangalore kitchen aggregator platforms bundling packaging with ingredient supply, bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Packaging and Packaging Waste Regulation recyclability mandates are forcing mid-tier converters without migration testing expertise toward acquisition or exit, consolidating competitive control among certified quality management system holders.
For Market Incumbents: Cement specification lock-in through multi-year supply contracts with multinational spice brands leveraging global film and laminate portfolios. Extend backward integration into aluminum metallized substrate supply to defend against Asian supplier lead time volatility. Prioritize certified mono-material laminate R&D to capture EU eco-modulation fee advantages.
For New Entrants and Emerging Players: Cloud kitchen operators in Mumbai and Bangalore represent an underserved buyer archetype consolidating procurement through bundled packaging-and-ingredient platforms. Target ethnic grocery co-packers in London and Birmingham adopting web-to-print workflows for hyper-localized spice labels. Enter via paper-based barrier coating validation partnerships with German and Dutch converters facing REACH PFAS elimination deadlines.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier converters possessing EU 10/2011 migration testing expertise given regulatory compliance scarcity. Long-term viability favors asset-light designers with certified quality management systems over capital-heavy commodity producers. Watch BIS certification timeline compression in India as inflection signal for export-oriented film supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Laminate Scale-Up | Captures EU Packaging and Packaging Waste Regulation recyclability thresholds above 70 percent. |
| Bio-Based Barrier Coating Validation | Targets German retail plastic-reduction commitments under REACH PFAS restrictions. |
| Subscription Replenishment Platform Launch | Bypasses distributor markups through direct-to-kitchen contracts with cloud kitchen aggregators. |
| Migration Testing Capability Acquisition | Addresses analytical chemist scarcity for EU 10/2011 food-contact plastics compliance. |
| Indian BIS Certification Fast-Track | Compresses market entry timelines for European film exporters to Gujarat processing facilities. |
Research Methodology
Independent corroboration across packaging converter executives, food service procurement directors, and regulatory affairs specialists underwrites the qualitative findings. Primary interviews with film and laminate technical directors, spice brand supply chain managers, and kitchen aggregator platform operators combined with secondary validation from EU Packaging and Packaging Waste Regulation filings, BIS certification protocols, and customs trade data. Bottom-up volume modeling triangulates against top-down market sizing across material, format, and end-use segmentation.
Comparable-period anchoring to historical flexible packaging adoption curves and glass jar premiumization trends structured the projection horizon. Segmentation dimensions modeled include packaging type, material substrate, closure system, and end-user procurement authority across food service, retail, and online channels. CAGRs derive from elasticity-adjusted volume projections incorporating labor cost inflation, regulatory compliance cost stacking, and e-commerce shipping efficiency requirements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aluminum metallized film supply disruption and extended producer responsibility fee modulation. Forecasts reflect assumptions around BIS certification timeline stability and EU recyclability threshold enforcement consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Europe Paint Packaging Market
Packaging Materials
Bulb Packaging Market
Packaging Materials
Brightness Enhancement Films Market
Packaging Materials
Fiber Lids Market
Packaging Materials
Polycoated Cup Stock Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
Thailand Packaging Market
Packaging Materials
PET Packaging Market
Packaging Materials
Insulated Box Liner Market
Packaging Materials
Cohesive Packaging Market
Packaging Materials
Hygiene Packaging Market
Packaging Materials
Construction Films Market
Packaging Materials
Coconut Wraps Market
Packaging Materials
Heat Shrink Packaging Market
Packaging Materials
Latin America Single-Use Packaging Market
Packaging Materials
United States Single Use Packaging Market