
 Canada Foodservice Packaging Market | 2026-2036
Canada Foodservice Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Foodservice Packaging Market Outlook
A shift from single-source resin contracts toward multi-material supplier portfolios is rebalancing procurement strategies across Canadian foodservice chains. Huhtamaki Americas Inc. leverages its molded fiber expertise to anchor supply relationships with national quick-service brands. Pactiv Evergreen Inc. competes through integrated North American manufacturing scale that sustains cost parity on thermoformed containers. Novolex differentiates via vertical control over recycled content streams, positioning its film and bag portfolio for compliance-heavy provincial markets.
Canada foodservice packaging encompasses disposable containers, utensils, wraps, and serviceware engineered from plastic resins, paperboard, aluminum foils, or biodegradable polymers such as PLA and bagasse, typically manufactured through thermoforming, injection molding, or pressed-pulp processes to meet food-contact safety and temperature-retention requirements for prepared food distribution. The material dimension shows plastic still dominating volume but biodegradable alternatives capturing the fastest expansion as municipal composting infrastructure spreads across Ontario, Quebec, and British Columbia. Containers lead product-type value pools given their higher unit costs and customization intensity for branded takeout programs, while cutlery and straws face margin compression from regulatory-driven material switches.
Health Canada and the Canadian Food Inspection Agency jointly govern food-contact material safety through Division 23 of the Food and Drugs Regulations, while Environment and Climate Change Canada enforces the proposed single-use plastics prohibition order that directly eliminates certain polystyrene and conventional plastic items from foodservice circulation. Provincial extended producer responsibility frameworks in British Columbia and Ontario further shape demand by assigning end-of-life recovery costs to packaging suppliers. Stakeholders must monitor regulatory divergence between federal ban timelines and provincial recycling mandates to avoid stranded inventory or non-compliant product lines.
Market Dynamics
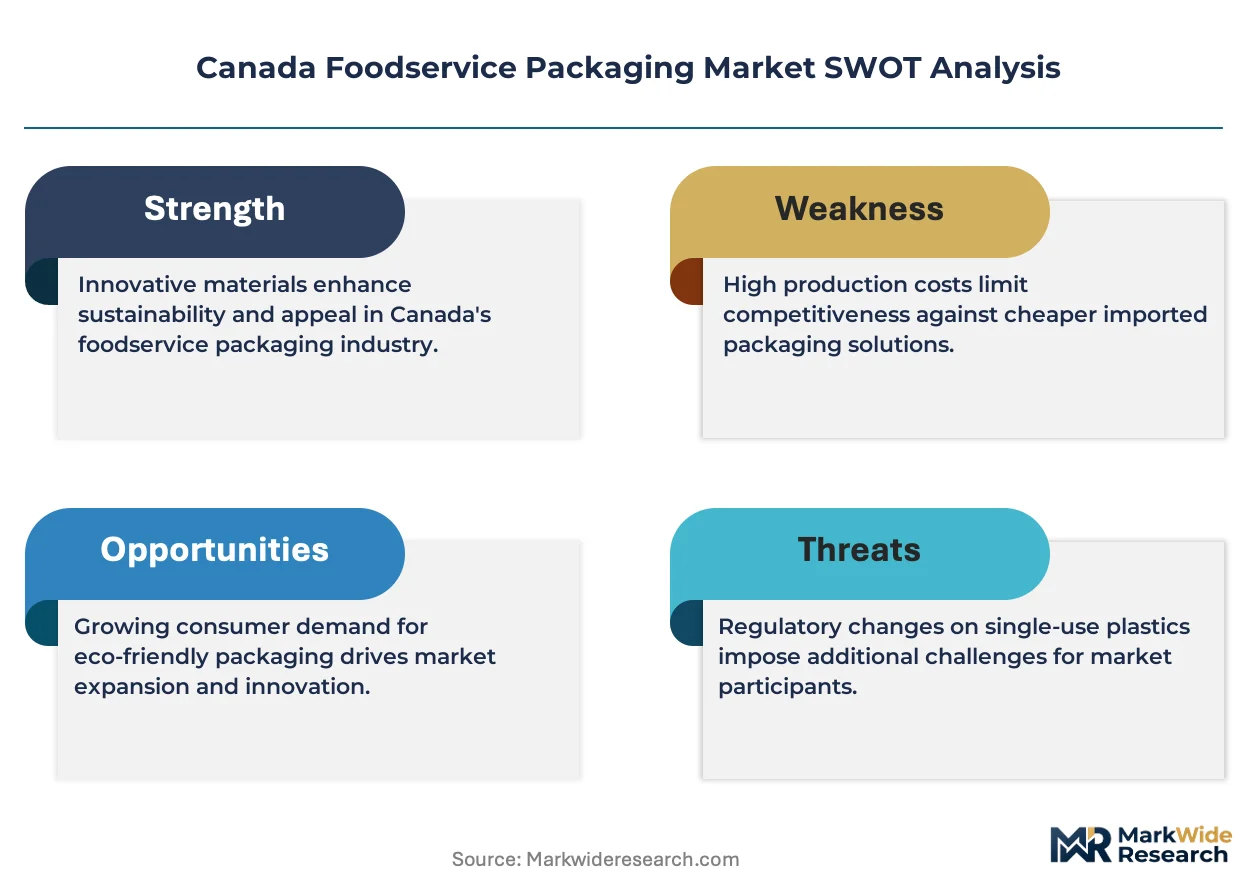
Health Canada's proposed single-use plastics prohibition is compressing demand for conventional polystyrene and redirecting procurement toward fiber-based alternatives, forcing foodservice chains to requalify entire packaging portfolios within compressed timelines.
Growth Catalysts
- Extended Producer Responsibility:British Columbia and Ontario frameworks assign end-of-life recovery costs to suppliers, accelerating investment in recyclable and compostable material streams.
- Molded Fiber Technology:Pressed-pulp processing advances enable cost-competitive production of rigid containers that meet grease-resistance requirements for hot food applications.
- Urban Corridor Density:Greater Toronto Area foodservice concentration creates scale economics for localized biodegradable packaging distribution networks.
Market Restraints
- Resin Price Volatility:Polypropylene and polystyrene input cost swings compress margins on legacy thermoformed container lines still serving transitional accounts.
- Composting Infrastructure Gaps:Municipal facility availability lags in Prairie provinces, limiting addressable market for PLA and bagasse alternatives outside Ontario, Quebec, and British Columbia.
- Performance Trade-offs:Fiber-based lids and containers exhibit inferior leak resistance versus plastic equivalents, constraining adoption for liquid-heavy menu categories.
Strategic Opportunities
- Atlantic Canada Expansion:Halifax and Moncton foodservice corridors remain underpenetrated by biodegradable packaging suppliers, offering first-mover positioning.
- Smart Packaging Integration:Convergence of QR-coded traceability layers with fiber substrates enables chains to communicate sourcing credentials directly to consumers.
- Provincial Ban Acceleration:Quebec's anticipated tightening of single-use plastics timelines creates regulatory tailwind for suppliers with certified compostable portfolios.
Industry Challenges
- Food-Contact Certification Timelines:Health Canada's Division 23 compliance reviews for novel biopolymer formulations extend 12-18 months, delaying product launches.
- Thermoforming Asset Stranding:Capital-intensive plastic forming equipment faces accelerated obsolescence as major chains sunset polystyrene specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Foodservice Packaging Market |
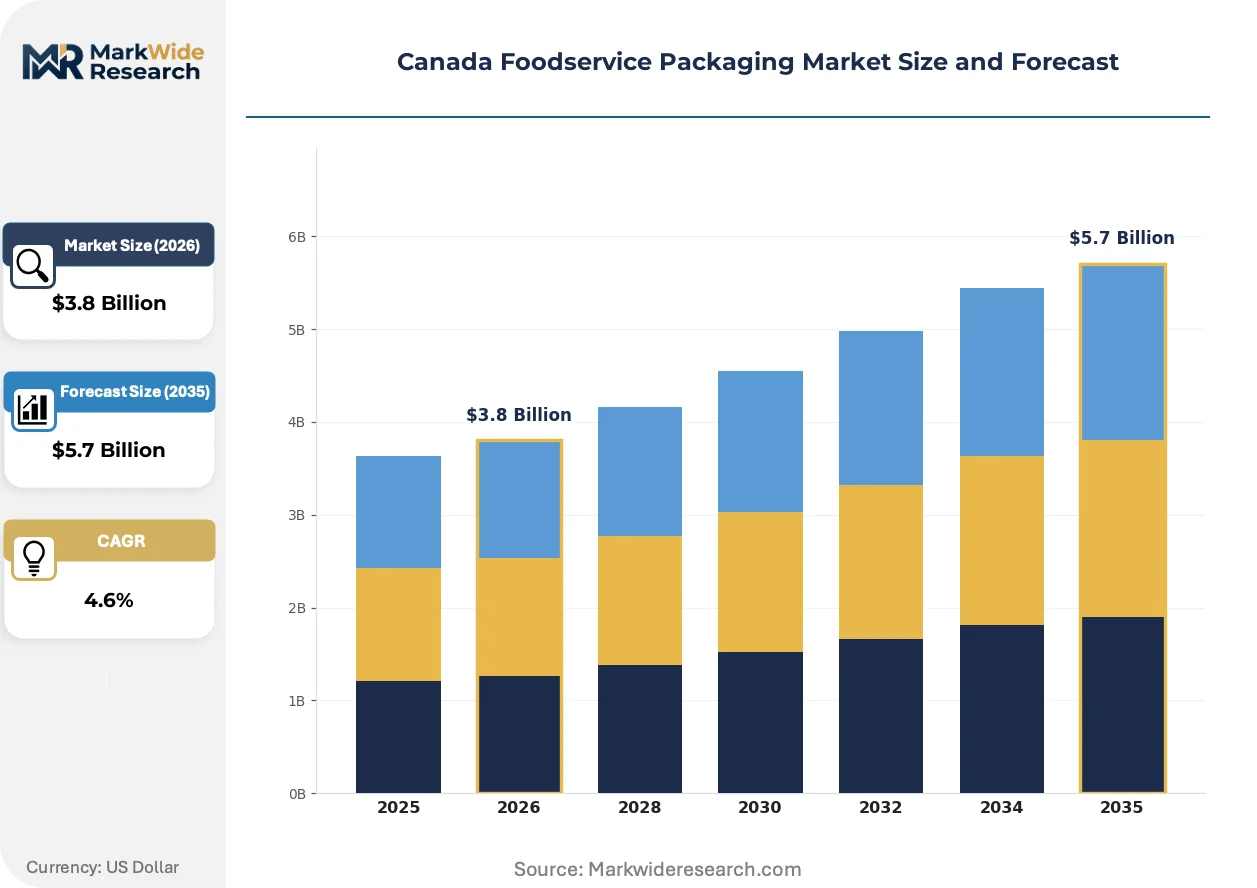
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Cutlery, Straws, Bags Material: Plastic, Paper, Aluminum, Biodegradable End User: Restaurants, Cafes, Catering, Fast Food Distribution Channel: Online, Wholesalers, Retail, Direct Sales |
| Companies Covered | Berry Global Inc., Huhtamaki Americas Inc., Pactiv Evergreen Inc., Ronpak Inc., Genpak Corporation, Dart Container Corporation, Novolex, Plastic Ingenuity Inc., Amhil North America, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Foodservice Packaging Market Strategic Shifts
Material science breakthroughs and regulatory compression are converging to redefine performance benchmarks across Canadian foodservice packaging, with sustainability credentials becoming inseparable from functional specifications in buyer evaluations.
Barrier-coated molded fiber is electrifying the rigid container segment by delivering grease and moisture resistance comparable to plastic at unit economics approaching parity. Quick-service chains across Ontario are adopting these containers for hot sandwich and rice bowl applications at replacement rates exceeding prior fiber generations. The technology is electrifying supplier R&D priorities, redirecting capital from incremental plastic improvements toward pulp chemistry and coating formulation.
Health Canada's single-use plastics prohibition order eliminates conventional polystyrene takeout containers, cutlery, and straws from national circulation, with draft regulations specifying transition deadlines. Foodservice distributors must purge non-compliant inventory and requalify supplier bases before enforcement phases begin. British Columbia's existing provincial ban has positioned Vancouver operators as early responders, with their compliance experience now informing national chain rollout strategies.
Chain-level consolidated procurement is displacing fragmented regional buying patterns as national quick-service brands centralize packaging specifications to secure volume pricing and simplify compliance. Distributors serving independent restaurants face margin compression as direct supplier relationships bypass traditional wholesale channels. This concentration is most visible in the Greater Toronto Area, where three national chains now account for the majority of molded fiber container procurement volume.
Canada Foodservice Packaging Market Segmentation
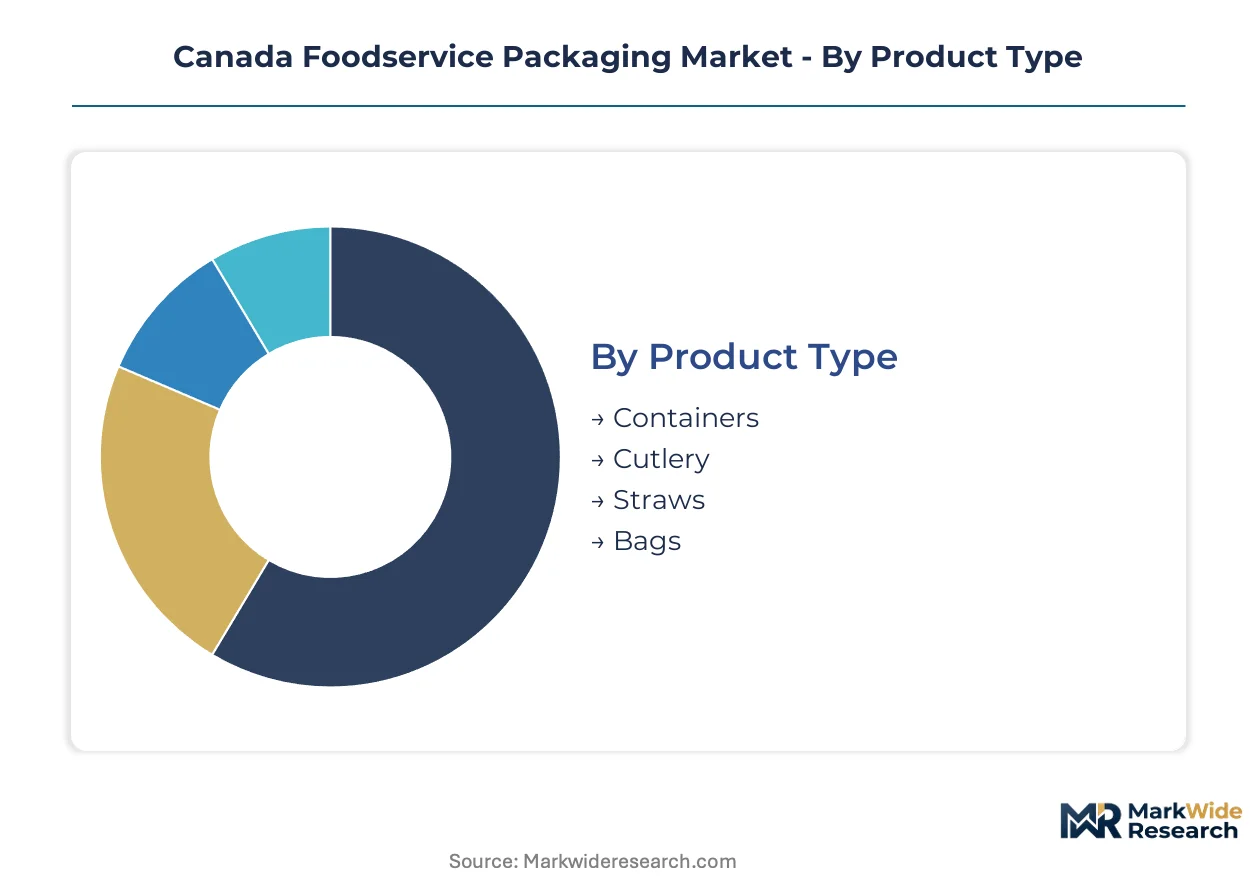
Segmentation in Canadian foodservice packaging reveals how procurement priorities diverge across material specifications, end-use applications, and channel structures. Understanding these splits enables suppliers to align production capacity with the highest-velocity upgrade cycles reshaping buyer behavior.
Product Type:
Replacement cycles vary sharply across product categories, with regulatory bans forcing compressed requalification timelines for certain formats while others enjoy longer specification stability.
- Containers:Rigid vessels manufactured through thermoforming, injection molding, or pressed-pulp processes to hold prepared meals, salads, and hot entrees. Demand concentrates in the Greater Toronto Area as national quick-service chains consolidate procurement for branded takeout programs, with molded fiber variants capturing share from legacy polystyrene as Health Canada's prohibition advances.
- Cutlery:Disposable forks, knives, and spoons engineered from plastic resins, wood, or biopolymers to withstand mechanical stress during food consumption. Ontario and British Columbia foodservice corridors are driving material switches toward wood and CPLA alternatives ahead of provincial enforcement timelines, squeezing margins on conventional plastic lines.
- Straws:Beverage delivery tubes facing the most aggressive regulatory compression under single-use plastics prohibitions.
- Bags:Flexible carryout and food-contact pouches produced from polyethylene, paper, or compostable films.
Containers sits at the top of the volume ranking, with molded fiber variants climbing the fastest as chains purge polystyrene inventories.
Material:
Cost tier positioning determines supplier profitability and customer switching thresholds, with premium biopolymers commanding 2-4x unit economics against commodity resins.
- Plastic:Polypropylene, polystyrene, and polyethylene resins processed through extrusion and thermoforming into rigid containers, films, and cutlery. Fast Food chains in Prairie provinces still rely on plastic for cost-sensitive applications where composting infrastructure remains undeveloped, though volume is contracting under federal pressure.
- Paper:Kraft paperboard and molded pulp substrates formed into bags, wraps, and pressed-fiber containers with barrier coatings for grease resistance. British Columbia operators have advanced furthest in paper adoption due to early provincial ban implementation, with their compliance protocols now scaling to national chain rollouts.
- Aluminum:Rolled foil products for heat retention, grilling applications, and premium presentation formats.
- Biodegradable:PLA, bagasse, and PHA polymers certified for industrial composting, capturing the steepest expansion trajectory as municipal facility networks spread across Ontario, Quebec, and British Columbia.
Plastic retains volume leadership, though biodegradable alternatives are gaining share fastest where infrastructure permits.
End User:
Customer type dictates order fragmentation, with consolidated national accounts demanding direct supplier relationships while independents rely on distributor intermediaries.
- Restaurants:Full-service and casual dining establishments requiring customized packaging for dine-in takeaway and delivery integration. Toronto and Vancouver independent restaurants are consolidating purchasing through foodservice distributors as specifications fragment across fiber, plastic, and hybrid formats.
- Cafes:Coffee-focused operators with specialized needs for hot beverage containment and pastry presentation. British Columbia's early ban exposure has pushed cafe chains toward molded fiber cup carriers and wooden stirrers, establishing procurement templates now migrating eastward.
- Catering:Event and institutional foodservice requiring bulk-format packaging for large-volume distribution.
- Fast Food:Quick-service chains with standardized national specifications and volume purchasing power. Three national brands now dominate molded fiber container procurement in the Greater Toronto Area, bypassing traditional wholesale channels for direct mill relationships.
Fast Food commands the largest contract values, with Restaurants showing the most specification fragmentation.
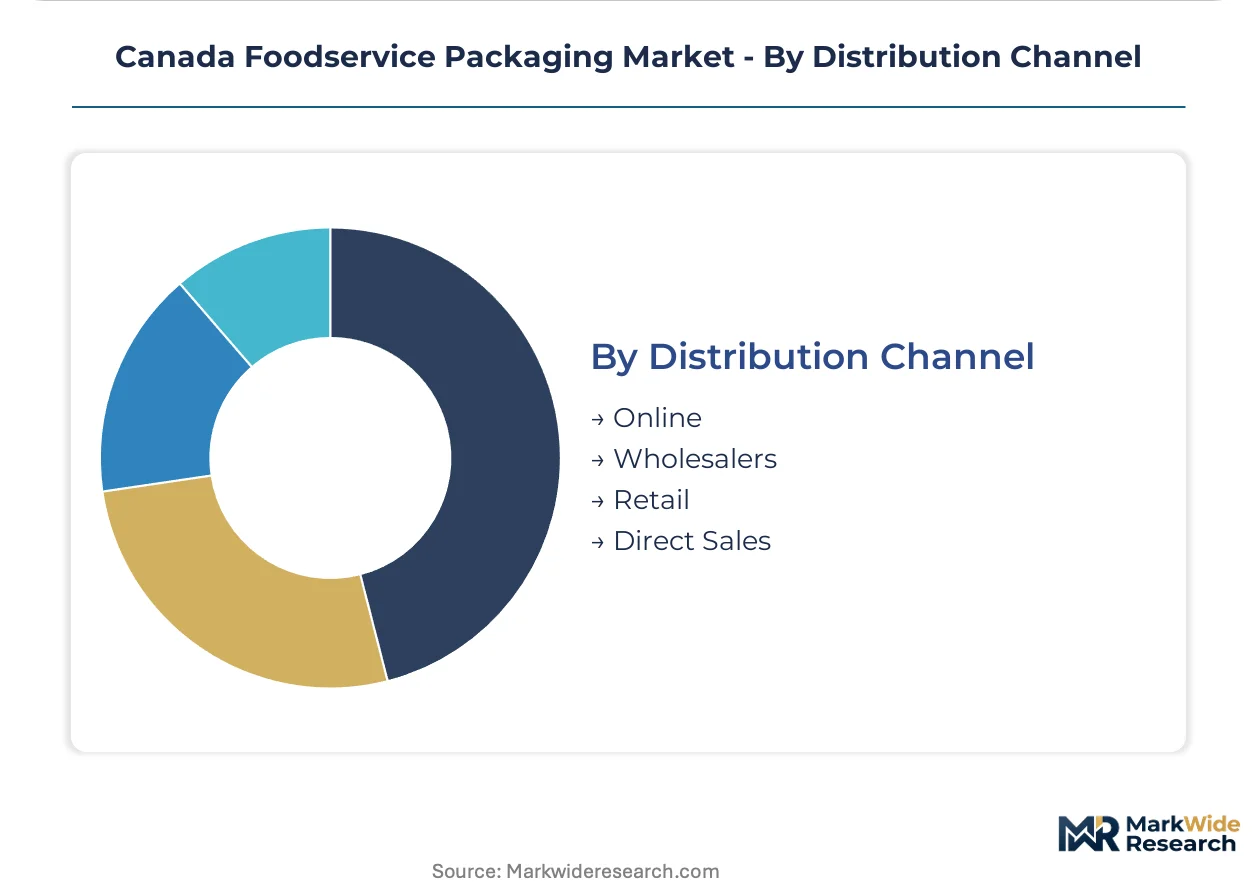
Distribution Channel:
Supply concentration shapes pricing leverage, with direct relationships capturing margin from disintermediated distributor layers.
- Online:Digital procurement platforms enabling small-operator access to standardized SKUs with transparent pricing. Atlantic Canada independents in Halifax and Moncton are adopting online channels faster than traditional foodservice corridors, compensating for weaker local distributor presence.
- Wholesalers:Broadline distributors maintaining inventory breadth across material types for fragmented restaurant bases. Ontario wholesalers face margin compression as national chains consolidate direct supplier relationships, forcing portfolio pivots toward independents and regional chains.
- Retail:Cash-and-carry outlets serving micro-operators and emergency replenishment needs.
- Direct Sales:Manufacturer-to-operator relationships securing volume commitments and co-development partnerships. Quebec's anticipated regulatory tightening is accelerating direct sales investment by compostable suppliers seeking first-mover certification advantages.
Wholesalers still handle the highest transaction count, with Direct Sales expanding most quickly among national accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Toronto Area concentrates the majority of Canadian foodservice packaging procurement volume, with three national quick-service chains driving molded fiber container demand through direct mill relationships. Provincial regulatory divergence between Ontario, British Columbia, and Quebec creates distinct compliance timelines reshaping regional supplier strategies. Municipal composting infrastructure gaps across Prairie provinces and Atlantic Canada fragment addressable markets for biodegradable alternatives.
Ontario
Toronto's foodservice corridor generates the highest molded fiber container procurement volume as national chains consolidate specifications. Health Canada's Division 23 compliance reviews for novel biopolymers create 12-18 month certification delays for suppliers targeting this market. The Greater Toronto Area's urban density enables localized biodegradable packaging distribution networks serving quick-service and casual dining segments.
British Columbia
Vancouver operators advanced furthest in paper and fiber adoption due to early provincial single-use plastics prohibition. The province's extended producer responsibility framework assigns end-of-life recovery costs directly to packaging suppliers. Metro Vancouver's compliance experience now informs national chain rollout strategies migrating eastward to Ontario and Quebec.
Quebec
Montreal foodservice distributors anticipate accelerated regulatory tightening beyond federal timelines, creating first-mover advantages for certified compostable suppliers. The province's municipal composting infrastructure supports PLA and bagasse alternatives at scale unmatched in Prairie markets. Quebec-based procurement centralization mirrors Ontario's chain-level consolidation patterns.
Alberta
Calgary and Edmonton foodservice operators rely on conventional plastic lines where composting facility availability remains limited. Resin price volatility on polypropylene and polystyrene compresses margins for legacy thermoformed container suppliers serving transitional accounts. Alberta's infrastructure gaps constrain biodegradable alternative penetration compared to Ontario and British Columbia.
Atlantic Canada
Halifax and Moncton corridors remain underpenetrated by biodegradable packaging suppliers, offering positioning opportunities for first movers. Atlantic Canada independents adopt online procurement channels faster than traditional foodservice corridors, compensating for weaker local distributor presence. The region's regulatory lag behind Ontario and British Columbia extends specification stability for conventional materials.
Canada Foodservice Packaging Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue compostable certification and barrier-coated fiber specializations. The market exhibits moderate consolidation with three to four national-scale suppliers commanding volume relationships with quick-service chains. Strategic archetypes separate integrated North American manufacturers, recycled-content vertical specialists, and molded fiber technology leaders. Competitive moves concentrate on direct mill relationships bypassing wholesale channels and provincial certification pre-positioning ahead of regulatory enforcement.
Within the integrated manufacturing tier, Huhtamaki Americas Inc. and Pactiv Evergreen Inc. exemplify scale-driven positioning through continental production networks. Novolex occupies a recycled-content specialist position, leveraging upstream control over post-consumer material streams. These three anchors represent distinct competitive vectors: fiber technology depth, thermoformed cost parity, and compliance-oriented vertical integration. Berry Global Inc. and Dart Container Corporation sit within the legacy resin-forming segment facing asset obsolescence pressure from federal prohibition timelines.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Huhtamaki Americas Inc. |
| Pactiv Evergreen Inc. |
| Ronpak Inc. |
| Genpak Corporation |
| Dart Container Corporation |
| Novolex |
| Plastic Ingenuity Inc. |
| Amhil North America |
| Others |
Value Chain & Pricing Dynamics
Health Canada's proposed single-use plastics prohibition is forcing foodservice chains to requalify entire packaging portfolios within compressed timelines, compelling suppliers to absorb certification costs and redirect capital toward fiber-based production lines. This mandated specification shift is compressing margins on legacy thermoformed containers while creating pricing power for certified compostable alternatives.
Pricing Analysis
Input-cost pass-through from resin price volatility on polypropylene and polystyrene is squeezing margins for legacy thermoformed container suppliers serving Prairie province accounts. Three-tier pricing structure across premium, standard, and economy levels separates barrier-coated molded fiber from conventional paper and commodity plastic. Cost compression in the standard tier is intensifying because national chains are consolidating procurement volume for direct mill relationships. Fast Food chains demonstrate lowest price sensitivity due to specification lock-in, while independent Restaurants in Atlantic Canada remain most cost-conscious.
Supply Chain Analysis
Single-source vulnerability sits with Chinese pulp suppliers and US resin producers feeding Canadian thermoforming operations. Raw material dependencies center on bleached kraft pulp, recycled polyethylene terephthalate flake, and polylactic acid resin from Thailand and Nebraska. Tariff exposure on imported molded fiber equipment creates procurement risk for domestic capacity expansion. Distribution runs through Ontario-based wholesalers serving the Greater Toronto Area, with direct sales channels bypassing intermediaries for national chain accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Procurement consolidation toward premium barrier-coated fiber specifications is elevating compliance-certified suppliers above commodity competitors.
For Market Incumbents: Deploy backward integration into recycled pulp streams to secure input cost stability against resin volatility. Lock in direct mill relationships with Ontario and British Columbia quick-service chains before Quebec's anticipated regulatory tightening. Huhtamaki Americas Inc. and Pactiv Evergreen Inc. already anchor national accounts; smaller incumbents must defend share through certification pre-positioning. For New Entrants and Emerging Players: Digital procurement platforms serving Halifax and Moncton foodservice corridors offer lowest competitive density. Atlantic Canada independents adopt online channels faster than traditional corridors, compensating for weaker distributor presence. Target biodegradable bagasse alternatives for cafe chains seeking wooden stirrer and cup carrier bundles. For Investors and Strategic Acquirers: Asymmetric upside sits with compostable certification specialists possessing Health Canada Division 23 pre-approval. Five-to-ten year viability favors suppliers with provincial EPR framework compliance already operational. Watch British Columbia's extended producer responsibility cost assignment as the inflection signal for margin structure shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier-Coated Fiber Capacity Expansion | Ontario quick-service chains require grease-resistant molded fiber for hot entree applications. |
| Health Canada Division 23 Certification Investment | Novel biopolymer formulations face 12-18 month compliance review delays without pre-submission. |
| Direct Mill Relationship Development | National chains in the Greater Toronto Area now bypass traditional wholesale channels. |
| Provincial EPR Framework Pre-Positioning | British Columbia and Ontario assign end-of-life recovery costs to packaging suppliers. |
| Atlantic Canada Distribution Network Buildout | Halifax and Moncton corridors remain underpenetrated by biodegradable packaging suppliers. |
Study Parameters
Multiple input streams — packaging procurement managers at national quick-service chains, pulp chemistry R&D directors, Health Canada regulatory affairs specialists, and Ontario foodservice distributors — were reconciled against customs records, provincial EPR framework filings, and SEC disclosures from North American packaging manufacturers. Bottom-up volume modeling across material specifications and end-use channels was triangulated with top-down value estimates derived from chain-level procurement consolidation patterns.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material type, product format, end-user category, and distribution channel structure. CAGRs were derived from volume trajectory analysis incorporating municipal composting infrastructure rollout schedules and federal prohibition enforcement phasing. Industry-specific forecast inputs center on Health Canada Division 23 certification timelines and provincial extended producer responsibility cost pass-through mechanics.
Regulatory enforcement delays, pulp input cost spikes, and composting infrastructure deployment shortfalls are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about prohibition timeline adherence and chain procurement consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Foodservice Packaging
North America Foodservice Packaging Market
Foodservice Packaging
Foodservice Disposable Packaging Market
Foodservice Packaging
France Disposal Tableware Market
Foodservice Packaging
Italy Disposable Tableware Market
Foodservice Packaging
Compostable Food Service Tray Market
Foodservice Packaging
Compostable Food Service Packaging Market
Foodservice Packaging
United States Disposable Tableware Market
Foodservice Packaging
Foodservice Paper Bags Market
Foodservice Packaging
Food Service Packaging (FSP) Market
Foodservice Packaging
Bar and Prep Faucets Market