
 Canned Food Market | 2026-2036
Canned Food Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Food Market Analysis
Supermarket private-label procurement is tilting toward co-manufacturers with integrated steel sourcing. Thai Union Group leverages vertical integration across Thai fishing fleets and canning plants to sustain cost leadership in seafood. Del Monte Pacific Limited anchors Pacific Rim supply through Philippine and Indonesian processing facilities. Campbell Soup Company competes on brand equity in condensed soups while navigating declining North American center-store traffic.
Canned food denotes thermally stabilized products sealed in hermetically closed containers, typically processed at 116–121°C to achieve commercial sterility with shelf lives exceeding two years. The technique preserves nutrient density while eliminating microbial spoilage vectors for remote distribution and inventory buffering. Metal cans dominate volume due to established recycling infrastructure and oxygen barrier performance, though pouch formats are gaining traction in camping and military ration applications. Fish and meat segments command premium positioning in European retail, while vegetable canning faces margin compression from fresh and frozen alternatives in household channels.
USDA grading standards and FDA low-acid canned food regulations govern thermal processing parameters and facility registration in the United States, while EU F-Gas Regulation and Packaging and Packaging Waste Directive shape container material choices across member states. BIS certification requirements in India and CDSCO food safety protocols constrain import access for non-compliant suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and lining chemistry restrictions that will determine which packaging technologies retain market access.
Market Dynamics
BPA-free lining mandates from the EU F-Gas Regulation and parallel FDA guidance are forcing material transitions across metal can supply chains, compressing margins for converters while creating first-mover advantages for epoxy-phenolic alternative suppliers.
Growth Catalysts
- Emergency preparedness stockpiling:Military procurement programs and civil defense agencies in the United States, Germany, and Japan are expanding multi-year shelf-stable nutrition contracts.
- Southeast Asian export processing:Thai and Indonesian tuna canning clusters are capturing European retail private-label volume through integrated fleet-to-plant operations.
- REACH-compliant coating innovation:Accelerated solvent-free lining chemistry development is unlocking premium positioning in German and French retail channels.
Market Restraints
- Tinplate cost volatility:Steel input fluctuations and energy-intensive electrolytic tinning processes constrain converter margin stability.
- Thai fleet concentration:Skipjack tuna supply chains depend on Songkhla and Samut Sakhon landing volumes, creating weather and quota exposure.
- Retort pouch substitution:Flexible barrier formats are displacing metal cans in military ration and outdoor recreation applications.
Strategic Opportunities
- Indian FSSAI alignment:BIS certification and state-level food safety protocols create import substitution potential for domestic canners in Maharashtra and Gujarat.
- E-commerce direct-to-pantry:Amazon and regional grocery platforms are building ambient fulfillment networks that bypass traditional wholesale distribution.
- Dual-carbon coating convergence:Water-based epoxy and polyester hybrid linings are intersecting with EU Packaging Waste Directive recycling targets.
Industry Challenges
- Thermal process engineering talent:Retort operation and aseptic filling expertise is concentrating at Thai Union and Del Monte Pacific facilities, creating recruitment competition.
- Legacy equipment retrofit timelines:Converting high-speed seaming lines for BPA-free lining chemistry requires 18-24 month validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Food Market |
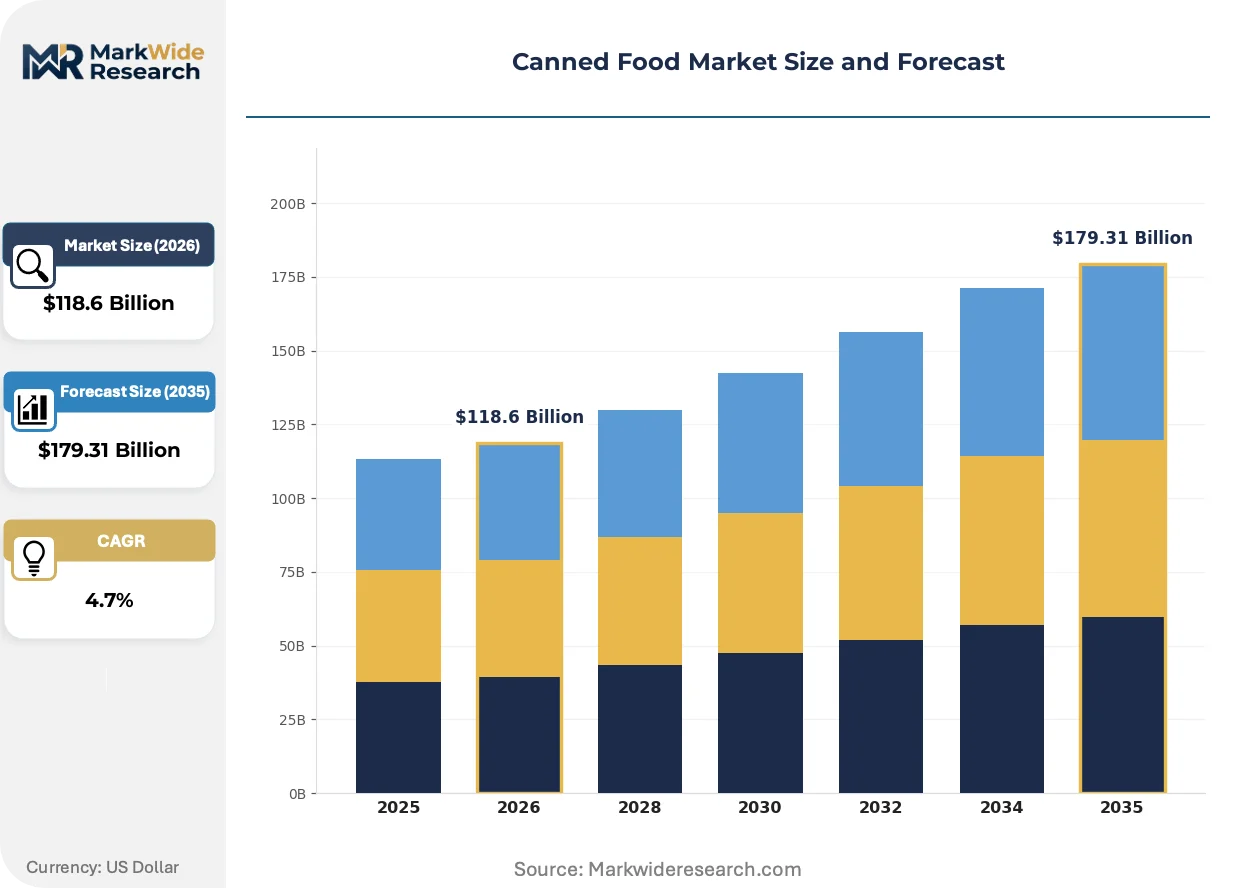
| Market Size in 2026 | $118.6 Billion |
| Market Size in 2035 | $179.31 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetables, Fruits, Fish, Meat Packaging Type: Metal Cans, Glass Jars, Pouches, Tetra Packs Sales Channel: Supermarkets, Online Retailers, Convenience Stores, Wholesalers End User: Households, Restaurants, Cafés, Catering Services |
| Companies Covered | Bolton Group, Thai Union Group, Kraft Heinz Company, Del Monte Pacific Limited, Hormel Foods Corporation, Conagra Brands, Campbell Soup Company, Bonduelle, Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Food Market Emerging Trajectories
Smart manufacturing and regulatory chemistry shifts are compressing product development cycles while reshaping how shelf-stable nutrition reaches institutional and household buyers.
Retort simulation software is digitizing thermal process validation. Campbell Soup and Thai Union are deploying computational fluid dynamics to model lethality distribution, cutting recipe development from twelve weeks to four. This compression is enabling faster private-label response to retailer nutrition claims.
The EU F-Gas Regulation and REACH Annex XVII restrictions on bisphenol derivatives are accelerating epoxy-phenolic and polyester-based lining adoption. German canmakers are retrofitting coating lines ahead of 2026 compliance deadlines. Italian tomato paste exporters face container cost premiums of fifteen to twenty percent during transition.
Direct-to-pantry subscription models are fragmenting traditional wholesale procurement. Military commissaries and disaster relief agencies in the United States are piloting vendor-managed inventory programs with automated replenishment triggers. This shift concentrates volume with converters offering ERP-integrated forecasting capabilities.
Canned Food Market Segmentation
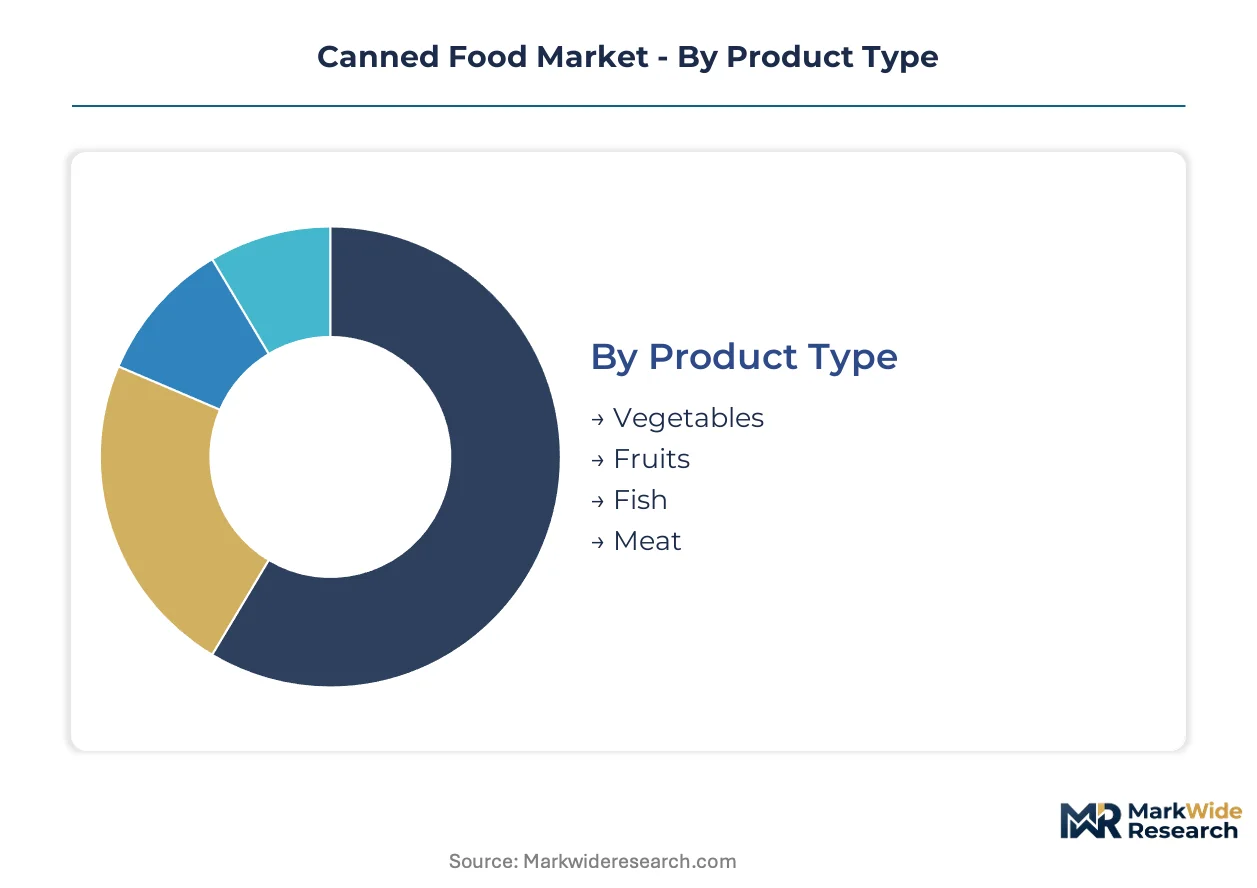
Canned food segmentation reflects divergent shelf-life requirements, thermal processing economics, and channel access constraints. Product and packaging combinations determine margin profiles, while sales channel selection governs geographic reach and inventory velocity.
Product Type:
The use-case spectrum spans from commodity vegetable staples to premium seafood positioning, with thermal processing intensity and raw material sourcing driving cost structures.
- Fish:Skipjack tuna and sardine canning dominates Southeast Asian export volumes, with Thai Union's Songkhla and Samut Sakhon facilities processing for European private-label buyers. EU F-Gas Regulation compliance on BPA-free linings adds fifteen to twenty percent container cost premiums during transition periods.
- Meat:Corned beef and poultry products serve military ration and emergency preparedness contracts in the United States, Germany, and Japan. Shelf-stable protein procurement from civil defense agencies is expanding multi-year stockpile volumes.
- Vegetables:Tomato paste, corn, and legume canning faces margin compression from fresh and frozen alternatives in household channels.
- Fruits:Pineapple and peach segments anchor Philippine and Indonesian processing for Pacific Rim distribution.
Established volume favors fish; emerging adoption favors meat.
Packaging Type:
Cost tier differentiation separates commodity metal formats from premium barrier alternatives, with recycling infrastructure and oxygen transmission rates determining channel fit.
- Metal Cans:Tinplate and aluminum containers retain dominant volume through established recycling infrastructure and superior oxygen barrier performance. Electrolytic tinning processes and steel input fluctuations constrain converter margin stability.
- Pouches:Retortable flexible formats are displacing metal in military ration and outdoor recreation applications. Campbell Soup and Thai Union deploy computational fluid dynamics to compress thermal process validation from twelve weeks to four.
- Glass Jars:Premium positioning in European retail for tomato paste and specialty vegetables.
- Tetra Packs:Aseptic carton formats for liquid and semi-liquid products with shorter shelf-life requirements.
Metal cans command volume scale; pouches are climbing the fastest.
Sales Channel:
Customer type concentration shapes procurement patterns, with institutional buyers prioritizing vendor-managed inventory and households fragmenting across digital and physical touchpoints.
- Supermarkets:Private-label procurement is tilting toward co-manufacturers with integrated steel sourcing. Center-store traffic decline in North America is forcing brand equity plays from Campbell Soup and Del Monte Pacific.
- Online Retailers:Amazon and regional grocery platforms are building ambient fulfillment networks that bypass traditional wholesale distribution. ERP-integrated forecasting capabilities concentrate volume with select converters.
- Convenience Stores:Single-serve and ready-to-eat formats for urban household replenishment.
- Wholesalers:Bulk institutional supply for restaurants, cafés, and catering services with longer payment cycles.
Supermarkets retain procurement scale; online retailers are gaining share fastest.
End User:
Application maturity separates established household consumption from institutional recovery, with margin profiles inverting across volume tiers.
- Households:Center-of-plate vegetable and soup categories face displacement from fresh alternatives. E-commerce direct-to-pantry subscriptions are fragmenting traditional wholesale procurement patterns.
- Restaurants:Ingredient cost management drives canned tomato paste and legume adoption in price-sensitive segments.
- Cafés:Limited menu applications for canned fruits and specialty vegetables.
- Catering Services:Event-based volume with seasonal demand spikes and inventory buffering requirements.
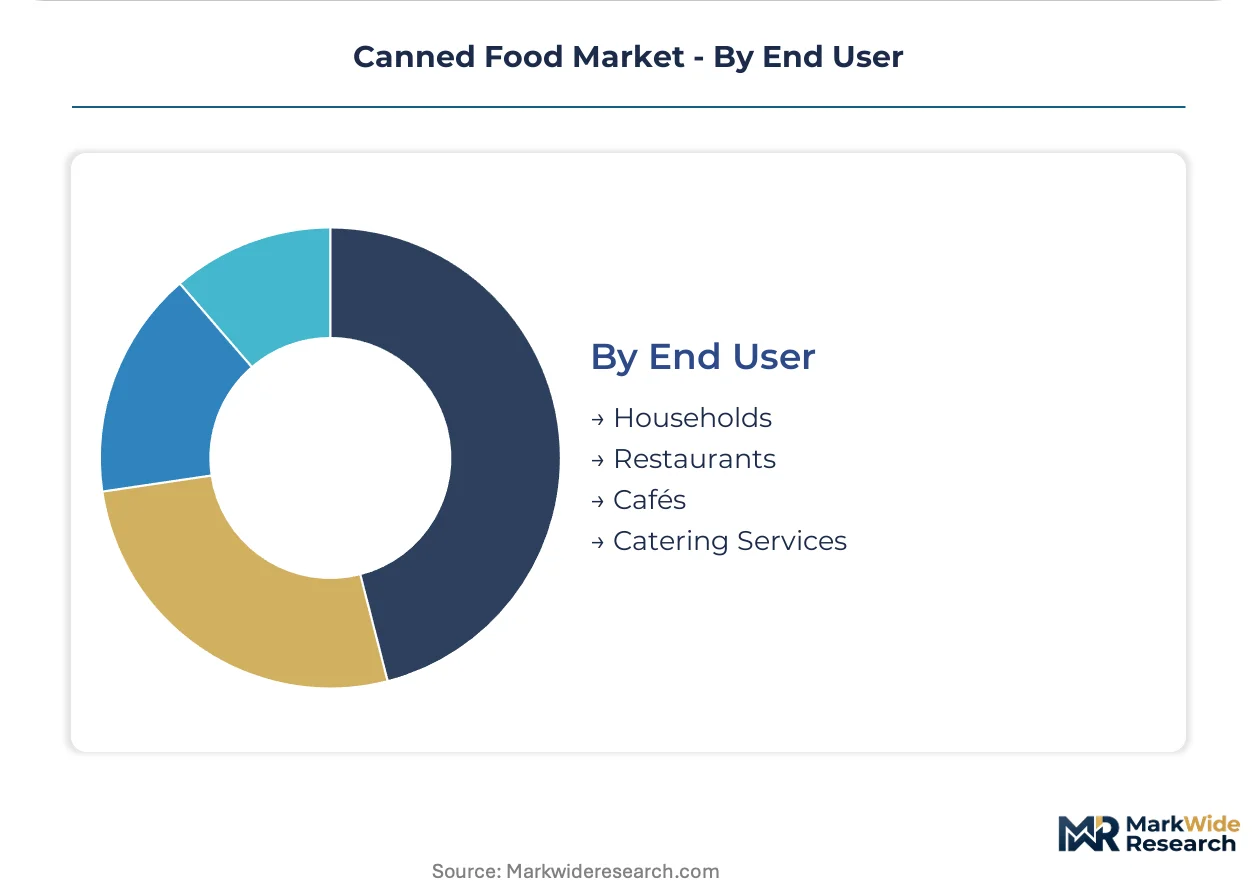
Households anchor consumption volume; catering services show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA low-acid canned food regulations and USDA grading standards govern thermal processing across the United States, while EU F-Gas Regulation and REACH Annex XVII restrictions drive material transitions in European metal can supply chains.
United States
Emergency preparedness stockpiling and military ration procurement anchor institutional demand for shelf-stable proteins. FDA facility registration requirements and thermal processing parameters constrain import access for non-compliant suppliers. Midwest canning clusters in Illinois and Ohio process corn, legumes, and condensed soups for center-store retail distribution.
Germany
REACH-compliant coating innovation and BPA-free lining mandates accelerate epoxy-phenolic alternative adoption in metal can production. EU F-Gas Regulation compliance deadlines compress converter margins while creating first-mover positioning for solvent-free chemistry suppliers. Bavarian and North Rhine-Westphalian canmakers retrofit coating lines ahead of 2026 regulatory thresholds.
Thailand
Skipjack tuna and sardine canning for European private-label buyers drives export-processing zone expansion. Thai Union's vertical integration across Songkhla and Samut Sakhon landing-to-plant operations sustains cost leadership in seafood. Weather volatility and quota exposure in Andaman Sea fishing grounds create supply chain risk concentration.
Philippines
Pineapple and peach canning anchor Pacific Rim fruit processing for North American and Japanese retail channels. Del Monte Pacific Limited leverages integrated Philippine and Indonesian facilities to manage regional supply coverage. Mindanao processing clusters face logistics constraints from archipelagic geography and port capacity limitations.
India
FSSAI alignment and BIS certification requirements create import substitution opportunities for domestic vegetable and legume canners. Maharashtra and Gujarat processing facilities target compliance with state-level food safety protocols to capture institutional procurement contracts. Tomato paste and mango pulp segments concentrate in Nashik and Anand industrial corridors.
Canned Food Market Vendor Landscape
Vertically integrated seafood specialists and brand-equity soup manufacturers split the market between cost-driven export processing and premium retail positioning. Consolidation pressure concentrates volume with converters offering ERP-integrated forecasting and captive raw material sourcing. Three archetypes dominate: fleet-to-plant seafood integrators, center-store brand equity players, and private-label co-manufacturers with integrated steel procurement. Competitive moves center on BPA-free lining retrofit partnerships and direct-to-pantry subscription platform integration.
Among Thai- and Philippine-based seafood integrators, Thai Union Group and Del Monte Pacific Limited exemplify fleet-to-plant vertical control. Campbell Soup Company occupies a position within the North American brand-equity tier, navigating center-store traffic decline through condensed soup portfolio management. These three anchors illustrate divergent strategic responses to regulatory chemistry shifts and channel fragmentation pressures.
| Leading Market Players |
|---|
| Bolton Group |
| Thai Union Group |
| Kraft Heinz Company |
| Del Monte Pacific Limited |
| Hormel Foods Corporation |
| Conagra Brands |
| Campbell Soup Company |
| Bonduelle |
| Nestlé |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European BPA-free lining conversion is compressing converter margins while amplifying pricing power for epoxy-phenolic chemistry suppliers serving German and French retail channels. This utilization squeeze cascades through tinplate procurement decisions, pushing private-label buyers toward integrated steel sourcers and away from fragmented converters.
Pricing Analysis
Italian tomato paste exporters face fifteen to twenty percent container cost premiums against Thai tuna canners during EU F-Gas Regulation transition periods. Three-tier pricing structure across REACH-compliant premium, standard epoxy-phenolic, and legacy BPA-containing economy levels separates German retail channels from Southeast Asian export-processing zones. Cost compression in vegetable canning intensifies because fresh and frozen alternatives erode household channel willingness-to-pay. Military ration procurement demonstrates least price sensitivity due to multi-year stockpile contracting, while supermarket private-label buyers exhibit highest elasticity.
Supply Chain Analysis
Extended payment terms from Thai Union and Del Monte Pacific concentrate working capital demands on Songkhla and Samut Sakhon fleet operators. Raw material flows draw from Indonesian skipjack landings, Philippine pineapple cultivation, and Indian Maharashtra tomato processing. Single-source vulnerability concentrates in Andaman Sea fishing grounds where weather volatility disrupts tuna supply. Distribution runs through European retail private-label networks, North American military commissaries, and emerging Indian FSSAI-compliant institutional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BPA-free lining mandates constitute a regulatory inflection accelerating material transitions and consolidating procurement around chemistry-compliant converters. This disruption rewards first-mover retrofit investments while penalizing legacy equipment-dependent players.
For Market Incumbents: Insulate margin position through captive epoxy-phenolic coating capacity in Germany and Thailand before 2026 compliance deadlines. Secure multi-year military ration contracts to offset center-store traffic decline in North American condensed soup categories. Prioritize ERP-integrated forecasting capabilities to capture direct-to-pantry subscription volume from Amazon and regional grocery platforms. For New Entrants and Emerging Players: Pursue white-space positioning in Indian FSSAI-aligned vegetable and legume canning for Maharashtra and Gujarat institutional procurement. Target underpenetrated retort pouch formats for outdoor recreation and camping applications where metal can displacement creates new demand. Anchor go-to-market strategy through e-commerce ambient fulfillment partnerships bypassing traditional wholesale distribution. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet-to-plant seafood integrators with European private-label relationships and military stockpile contracts. Five-to-ten year viability favors converters with backward integration into steel sourcing and coating chemistry. Watch for BPA-free lining retrofit completion rates as inflection indicator separating compliant first-movers from margin-compressed laggards.| Strategic Initiative | Industry Significance |
|---|---|
| Epoxy-Phenolic Coating Retrofit | EU F-Gas Regulation compliance unlocks German and French retail channel access before deadline thresholds. |
| Fleet-to-Plant Vertical Control | Thai Union's Songkhla integration sustains cost leadership against fragmented Indonesian competitors. |
| Direct-to-Pantry Subscription Launch | Amazon ambient fulfillment networks bypass wholesale margin extraction for household replenishment. |
| Indian FSSAI Certification Investment | BIS alignment captures institutional procurement from Maharashtra and Gujarat processing corridors. |
| Retort Pouch Format Expansion | Flexible barrier displacement in military ration and camping applications opens premium positioning. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA low-acid canned food filings, EU REACH Annex XVII substance restrictions, and Thai fisheries export data. Conversations with canning plant operations managers, retail category buyers, coating chemistry suppliers, and military procurement officers inform operational benchmarks. Secondary validation draws from USDA grading standards documentation, BIS certification registries, and customs trade flow records. Bottom-up facility capacity assessments and top-down regional consumption estimates triangulate market sizing.
Forecast inputs span product type segmentation across fish, meat, vegetables, and fruits; packaging format differentiation between metal cans, pouches, and glass; and channel dynamics across supermarkets, online retailers, and institutional buyers. CAGRs derive from regression analysis against historical volume trajectories, elasticity-adjusted price evolution, and regulatory compliance cost absorption rates. Skipjack tuna quota allocations, steel input cost indices, and e-commerce penetration curves feed scenario-weighted projections.
Sensitivities concentrate around EU F-Gas Regulation enforcement timing, Thai fleet weather disruption frequency, and Indian FSSAI implementation pace across state-level jurisdictions. Forecasts reflect documented assumptions on coating chemistry transition costs and military procurement contract renewal rates. Macroeconomic steel price volatility, regulatory deviation on lining mandates, or technological substitution acceleration in flexible barrier formats would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
Packaged Sprouts Market
Packaged Foods
Private Label Food and Beverage Market
Packaged Foods
On-The-Go Breakfast Cereals Market
Packaged Foods
Food and Beverages Market
Packaged Foods
Canned Legumes Market
Packaged Foods
Instant Beverage Premix Market
Packaged Foods
Europe Free from Food Market
Packaged Foods
Iran Breakfast Cereals Market
Packaged Foods
Asia-Pacific Ready Meals Market
Packaged Foods
Middle-East and Africa Ready-To-Eat Food Market
Packaged Foods
Chewing Gum Market
Packaged Foods
Dinner Ready-To-Eat (RTE) Food Market
Packaged Foods
Spreads Market
Packaged Foods
Global Fruit Spreads Market
Packaged Foods
Wet Pet Food Market