
 Commercial Booster Pumps Market | 2026-2036
Commercial Booster Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Booster Pumps Market Analysis
Wholesale distribution for commercial booster pumps is fragmenting as direct-to-contractor digital platforms and regional system integrators erode traditional two-step channel control. Grundfos leverages its service network density to anchor premium specification positions across Northern European projects. Xylem Inc. competes through IoT-enabled pump management platforms that extend recurring revenue beyond hardware sales. KSB AG specializes in engineered vertical turbine configurations for high-pressure municipal applications.
Commercial booster pumps are pressure-amplification devices designed to maintain consistent flow rates across multi-zone building systems, typically operating between 1.5 and 75 horsepower with cast iron or stainless steel volute housings and mechanical seals rated for continuous duty cycles. Their primary commercial purpose is overcoming static head losses in high-rise water distribution, fire suppression networks, and large-scale HVAC circulation loops. Centrifugal designs dominate volume due to lower first-cost and simpler maintenance profiles, while positive displacement variants capture margin pools in precision irrigation and high-viscosity fluid handling. Submersible installations are gaining specification share in flood-prone municipalities seeking reduced noise signatures and space-constrained vault designs.
EPA lead-free standards under the Safe Drinking Water Act and EU Ecodesign regulations on water pump efficiency classes shape product certification requirements and market access thresholds for manufacturers serving North American and European project specifications. China's GB energy efficiency grades and India's BIS performance standards create parallel compliance tracks that favor localized production or joint venture assembly. Stakeholders must monitor how building electrification mandates and evolving net-zero codes recalibrate pump duty specifications before committing to platform refresh cycles.
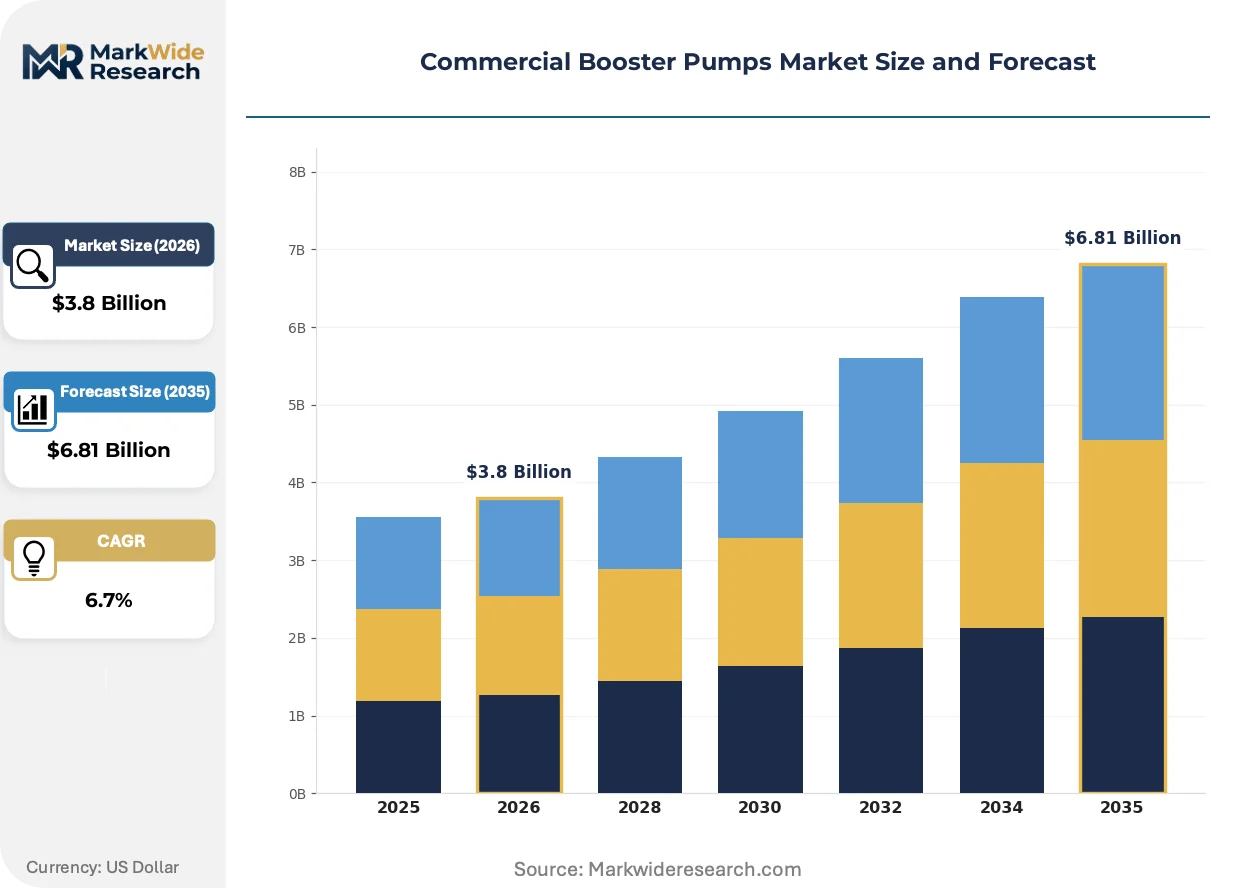
Market Dynamics
Variable-speed drive technology is compressing replacement cycles across commercial building portfolios as energy benchmarking mandates force premature obsolescence of fixed-speed installations. Procurement committees now weight lifecycle operating cost above first-cost, rewiring competitive dynamics toward service-anchored suppliers.
Growth Catalysts
- India's municipal infrastructure push:Central government allocations for urban water distribution are accelerating tender releases for multi-stage booster systems in high-rise residential clusters.
- EU Ecodesign efficiency tiers:Minimum efficiency performance standards are phasing out lower-grade pump classes and concentrating demand on premium variable-speed configurations.
- Submersible vault architectures:Flood-prone municipalities in Southeast Asia are specifying noise-reduced below-grade installations to reclaim street-level real estate.
Market Restraints
- Copper and rare-earth magnet cost volatility:Permanent magnet motor cores face input price swings that compress margin predictability for mid-tier manufacturers.
- Foundry capacity concentration:Cast iron volute housing production clusters in specific industrial zones, creating geographic supply vulnerability during energy rationing periods.
- Legacy mechanical seal limitations:Conventional seal designs fail prematurely in high-solids municipal water, restricting specification share in emerging-market infrastructure.
Strategic Opportunities
- Indonesia's high-rise construction corridor:Jakarta and Surabaya building permits are outpacing installed pump capacity, creating specification white space for packaged booster skids.
- IoT-enabled predictive maintenance:Sensor-integrated pump management platforms are converging with building automation systems to capture recurring service revenue.
- China's dual carbon retrofit mandates:MEE efficiency deadlines are forcing HVAC circuit upgrades in existing commercial stock, not just new construction.
Industry Challenges
- Variable-frequency drive commissioning expertise:Shortage of technicians trained in VFD parameter optimization for multi-pump staging logic delays project handover.
- Cross-border certification reciprocity gaps:UL-listed and CE-marked products require redundant testing for India's BIS compliance, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Booster Pumps Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal, Positive Displacement, Submersible, Vertical Application: Water Supply, Fire Fighting, Irrigation, HVAC End User: Commercial Buildings, Industrial Facilities, Agricultural Sector, Municipalities Installation Type: Onshore, Offshore, Indoor, Outdoor |
| Companies Covered | Grundfos, Xylem Inc., KSB AG, Flowserve Corporation, Sulzer Ltd., WILO SE, Pentair Plc., Danfoss, Franklin Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Booster Pumps Market Emerging Trajectories
Digital twin integration and material science advances are redefining performance benchmarks across commercial booster pump specifications. Equipment buyers now demand predictive capability alongside hydraulic efficiency.
Permanent magnet synchronous motor technology is hybridizing with conventional induction architectures in mid-horsepower commercial segments. Facility managers in Class-A office towers are specifying magnet-assisted designs for duty cycles above 4,000 annual hours. This convergence is compressing the efficiency gap between premium and standard product tiers.
EPA lead-free compliance under the Safe Drinking Water Act is mandating low-lead bronze and stainless steel wetted surfaces for potable water booster systems. Manufacturers serving North American specifications have retooled casting lines and sourcing agreements. The compliance burden falls heaviest on economy-tier suppliers lacking vertical control over metallurgy.
Direct-to-contractor digital platforms are disintermediating traditional two-step distribution in commercial construction procurement. Mechanical contractors in India's tier-1 cities are sourcing booster skids through B2B marketplaces that bypass regional wholesaler markups. Channel compression is most pronounced in standardized sub-10-horsepower segments where specification engineering is minimal.
Commercial Booster Pumps Market Segmentation
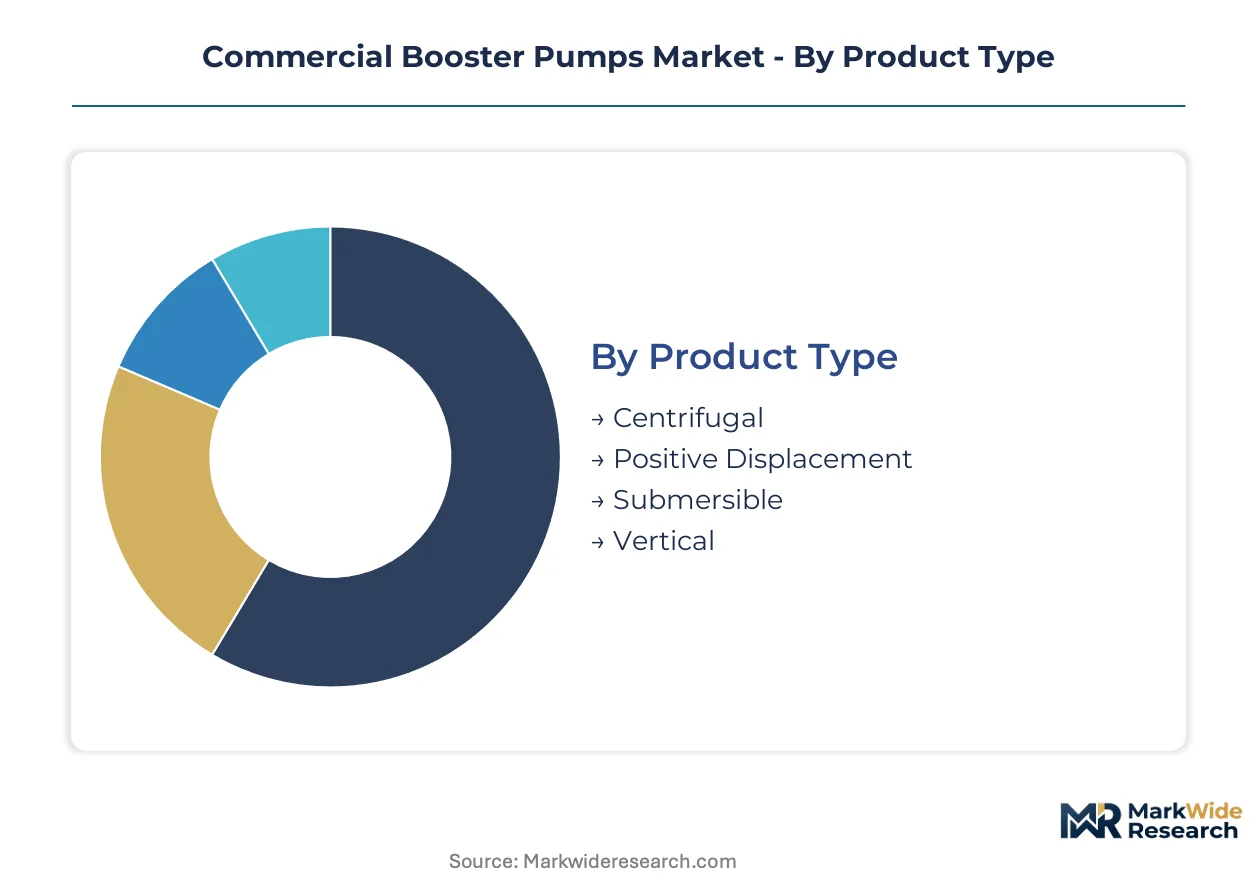
Commercial booster pump procurement cycles vary dramatically across product architectures and installation contexts. Segment-specific replacement timelines and specification complexity determine vendor pricing power and service attachment rates.
Product Type:
Centrifugal designs turn over fastest in standardized building services, while engineered vertical configurations persist for decades in municipal infrastructure.
- Centrifugal:Single-stage or multi-stage impeller architectures dominate commercial building specifications due to lower first-cost and simpler maintenance protocols. Demand concentrates in India's high-rise residential clusters where municipal pressure inadequacies force private booster installations. Fixed-speed units face accelerated replacement under EU Ecodesign tier mandates.
- Positive Displacement:Reciprocating or rotary mechanisms handle high-viscosity fluids and precision flow requirements in industrial process loops. Specification share clusters in agricultural irrigation districts requiring exact discharge rates across variable terrain grades. Higher capital intensity extends replacement cycles versus centrifugal alternatives.
- Submersible:Below-grade motor-pump configurations reduce noise signatures and reclaim street-level space in flood-prone Southeast Asian municipalities.
- Vertical:Deep-well turbine architectures serve high-pressure municipal distribution networks with minimal footprint requirements.
Centrifugal pumps anchor the volume base while submersible configurations gain share at the steepest rate.
Application:
Specification engineering intensity and regulatory compliance burden separate premium application tiers from commodity procurement.
- Water Supply:Potable pressure boosting in multi-zone commercial buildings demands lead-free bronze or stainless steel wetted surfaces under EPA Safe Drinking Water Act mandates. India's urban infrastructure push accelerates tender releases for variable-speed multi-stage systems in residential towers. BIS certification requirements add testing redundancy for imported equipment.
- Fire Fighting:UL-listed and FM-approved configurations must maintain specified flow rates under emergency conditions across suppression network zones. Procurement committees weight lifecycle reliability above first-cost in Class-A office specifications. Commissioning requires certified technician oversight for multi-pump staging logic.
- Irrigation:Agricultural and landscape applications favor lower-specification centrifugal units with minimal electronic complexity.
- HVAC:Circulation loops in China's commercial building stock face MEE efficiency retrofit deadlines under dual carbon goals.
Water supply applications anchor the volume base while HVAC retrofits expand most quickly.
End User:
Customer sophistication and total cost of ownership visibility determine specification tier and service contract attachment.
- Commercial Buildings:Class-A office towers and mixed-use developments specify magnet-assisted permanent magnet synchronous motors for duty cycles exceeding 4,000 annual hours. Procurement through direct-to-contractor digital platforms bypasses traditional wholesaler markups in India's tier-1 cities. Energy benchmarking mandates force premature obsolescence of fixed-speed installations.
- Industrial Facilities:Process-critical applications demand engineered configurations with predictive maintenance integration and extended warranty terms.
- Agricultural Sector:Price-sensitive procurement favors standardized sub-10-horsepower segments with minimal specification engineering.
- Municipalities:Public tender processes prioritize lifecycle operating cost analysis and local content requirements under India's urban infrastructure programs.
Commercial buildings anchor the volume base while industrial facilities command the steepest pricing premiums.
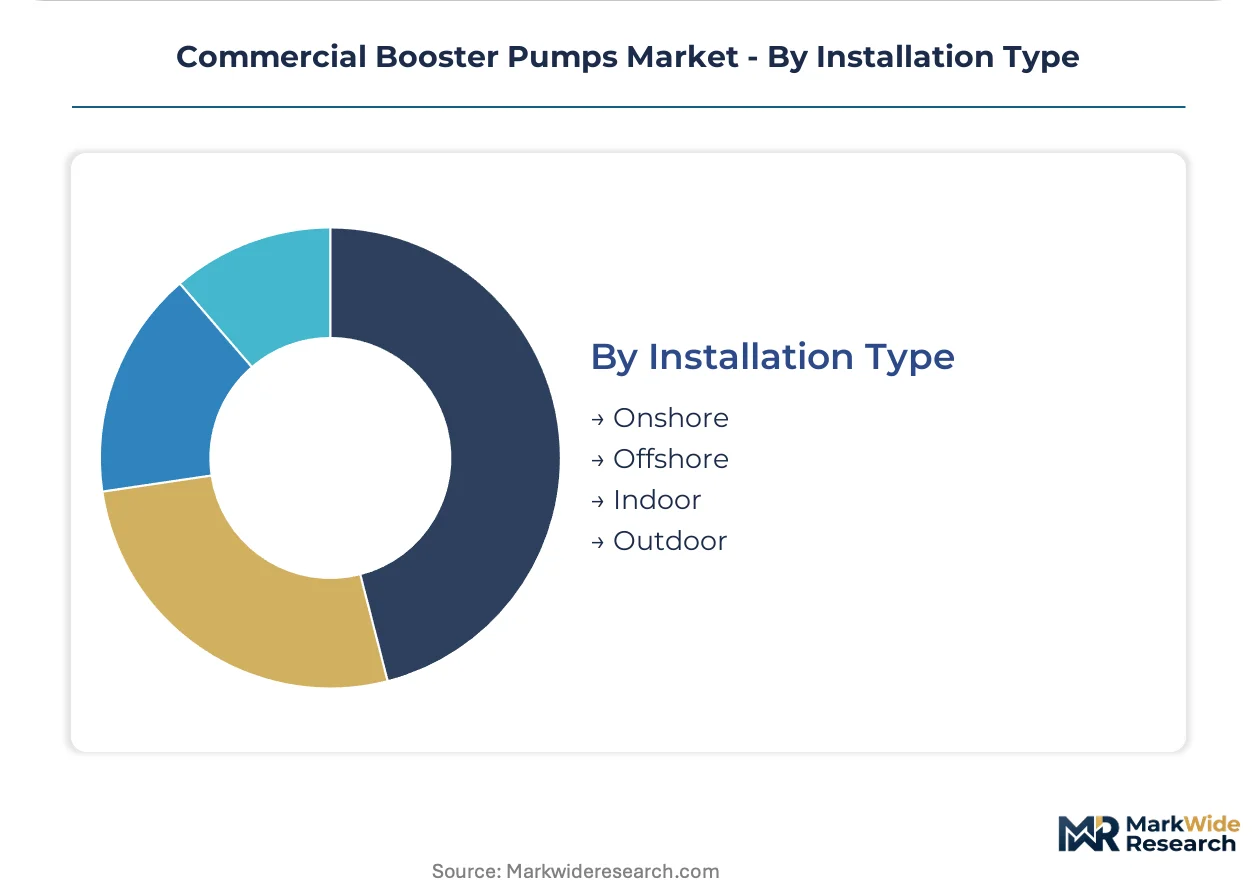
Installation Type:
Physical deployment constraints dictate housing materials, motor protection ratings, and maintenance accessibility requirements.
- Indoor:Climate-controlled mechanical rooms allow standard IP ratings and simplified seal configurations in commercial building basements. Jakarta and Surabaya high-rise construction outpaces installed pump capacity, creating specification white space for packaged booster skids. Noise regulations in European urban centers favor variable-speed drive modulation over fixed-speed throttling.
- Outdoor:Weather-exposed installations require enhanced enclosure ratings and freeze protection in temperate climates.
- Onshore:Standardized civil works and grid connectivity support conventional motor-drive configurations.
- Offshore:Corrosion-resistant metallurgy and specialized sealing systems serve marine and coastal industrial applications.
Indoor installations anchor the volume base while outdoor specifications climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE's dual carbon mandates in China anchor the regulatory framework reshaping procurement patterns across commercial building HVAC circuits and municipal water networks worldwide.
China
Commercial building retrofit deadlines under MEE's efficiency tiers are forcing premature replacement of fixed-speed booster installations in Shanghai and Beijing office towers. GB energy efficiency grades create compliance thresholds that favor localized assembly partnerships over direct import. Yangtze River Delta manufacturing clusters supply magnet-assisted motor cores to domestic pump assemblers.
India
Central government urban infrastructure allocations are accelerating tender releases for multi-stage variable-speed systems in Mumbai and Bangalore high-rise residential corridors. BIS performance standards require redundant testing protocols that extend product launch timelines for imported equipment. Gujarat foundry clusters cast lead-free bronze volute housings for potable water specifications.
Germany
EU Ecodesign minimum efficiency performance standards are phasing out lower-grade pump classes and concentrating demand on premium variable-speed configurations. REACH compliance obligations shape metallurgy sourcing for wetted surfaces in potable applications. Bavaria's industrial automation corridor supplies VFD commissioning expertise for multi-pump staging logic.
United States
EPA Safe Drinking Water Act lead-free mandates are mandating low-lead bronze and stainless steel wetted surfaces for commercial building potable booster specifications. Energy benchmarking mandates in California and New York force premature obsolescence of fixed-speed installations. Texas and Florida municipal utilities specify UL-listed configurations for fire suppression network reliability.
Indonesia
Jakarta and Surabaya high-rise construction permits are outpacing installed pump capacity, creating specification white space for packaged booster skids with integrated VFD controls. Flood-prone municipalities specify submersible vault architectures to reclaim street-level real estate. Local content requirements in public tenders favor joint venture assembly over direct import.
Commercial Booster Pumps Market Vendor Landscape
Full-line system integrators and specialized component suppliers split the market into distinct competitive orbits. The vendor base concentrates around three strategic archetypes: premium specification anchors with dense service networks, IoT-enabled platform operators capturing recurring revenue, and regional fabricators competing on first-cost in standardized segments. Consolidation pressure is accelerating through strategic partnerships between motor manufacturers and controls specialists, alongside geographic expansion via local assembly joint ventures.
Among European-based full-line suppliers, Grundfos and KSB AG occupy anchor positions in premium municipal and commercial building specifications. Xylem Inc. represents the IoT-enabled platform archetype, with its sensor-integrated management systems exemplifying the shift toward recurring service revenue models. These three companies illustrate how competitive positioning increasingly depends on service network density and digital integration depth rather than hardware first-cost alone.
| Leading Market Players |
|---|
| Grundfos |
| Xylem Inc. |
| KSB AG |
| Flowserve Corporation |
| Sulzer Ltd. |
| WILO SE |
| Pentair Plc. |
| Danfoss |
| Franklin Electric |
| Others |
Supply Flow & Price Mechanics
Rare-earth magnet export licensing under China's Ministry of Commerce determines both the premium commanded by permanent-magnet synchronous motor configurations and the geographic distribution of foundry capacity for cast iron volute housings. Copper price volatility and foundry energy rationing in Gujarat and Shandong provinces feed directly into tiered pricing spreads across standard induction and magnet-assisted product lines.
Pricing Analysis
Configured-to-order pricing for engineered vertical turbine systems commands spreads of 40-60% above catalog centrifugal skids due to application-specific hydraulic modeling and extended warranty terms. Three-tier pricing structure across premium, standard, and economy levels stratifies by motor efficiency grade and IoT platform integration depth. Cost compression in economy-tier sub-10-horsepower segments is intensifying because direct-to-contractor digital platforms bypass traditional wholesaler markups. Municipal procurement committees show lowest price sensitivity due to lifecycle operating cost mandates, while agricultural distributors remain most responsive to first-cost positioning.
Supply Chain Analysis
Export-control restrictions on high-performance rare-earth magnet alloys limit permanent-magnet motor core flows from Chinese processing facilities to European and North American pump assemblers. Foundry capacity clusters in China, India, and Germany cast gray iron and ductile iron volute housings, while copper winding wire draws from Chilean and Zambian concentrate. Single-source vulnerability concentrates in neodymium magnet supply chains. Distribution runs through a fragmenting mix of traditional two-step wholesalers, direct-to-contractor platforms, and regional system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial booster pumps market sits in early-cycle recovery as municipal infrastructure stimulus programs across India and Southeast Asia reactivate deferred replacement timelines. Government tender releases for variable-speed multi-stage systems signal the upturn phase.
For Market Incumbents: Pre-empt margin erosion in standardized centrifugal segments by anchoring specification positions through dense service network coverage in Northern European and North American premium building projects. Deepen backward integration into permanent-magnet motor core production to offset rare-earth price volatility exposure. Capture recurring revenue through predictive maintenance platform subscriptions that extend beyond hardware warranty periods. For New Entrants and Emerging Players: Pursue specification white space in Indonesia's Jakarta and Surabaya high-rise construction corridors where installed pump capacity lags building permit issuance. Target submersible vault architectures for flood-prone Southeast Asian municipalities seeking noise-reduced below-grade installations. Enter through joint venture assembly partnerships that satisfy local content requirements in public tenders. For Investors and Strategic Acquirers: EU Ecodesign efficiency tier deadlines reshaping the acquisition landscape favor targets with certified variable-speed drive integration capabilities and established VFD commissioning expertise. Position for five-to-ten year holding periods as building electrification mandates and net-zero codes recalibrate pump duty specifications across commercial building retrofits. Monitor MEE enforcement intensity in China's Yangtze River Delta as the signal for retrofit cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Integration | Sensor-integrated pump management converges with building automation to capture recurring service revenue streams. |
| Permanent Magnet Motor Adoption | Magnet-assisted synchronous designs compress efficiency gaps between premium and standard product tiers. |
| Joint Venture Assembly | Localized production partnerships satisfy India's BIS and China's GB compliance requirements for market access. |
| Predictive Maintenance Development | Digital twin integration redefines performance benchmarks and extends vendor customer lifecycle value. |
| Direct-to-Contractor Channel Buildout | B2B marketplace presence bypasses wholesaler markups in India's tier-1 city procurement. |
Methodological Framework
A standing panel of municipal procurement officers, commercial building facility managers, pump OEM product engineers, and aftermarket service directors provided ongoing calibration against field conditions. Primary interviews with these stakeholders combined with secondary validation from customs trade databases, EPA Safe Drinking Water Act compliance filings, EU Ecodesign directive implementation reports, and BIS certification registries. Bottom-up unit shipment modeling and top-down construction spend allocation triangulated market sizing across the analysis window.
Scenario-bracketing around regulatory enforcement intensity and commodity price trajectories bounded the projection horizon. Segmentation modeling captured product architecture, application context, end-user sophistication, and installation type dimensions. CAGRs derived from regression against historical replacement cycle data and forward infrastructure spend commitments. Input assumptions incorporated MEE dual carbon retrofit deadlines, EU minimum efficiency performance standard phase-out schedules, and India central government urban water allocation trajectories.
Sensitivities concentrate around rare-earth magnet export licensing enforcement, foundry energy rationing severity, and VFD technician training pipeline expansion. Forecasts reflect documented assumptions on regulatory timeline adherence and construction permit issuance rates. Material shifts in China's dual carbon policy implementation or India's municipal tender release cadence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Subsea Pumping System Market
Pumps and Control Devices
Global Smart Pumps Market
Pumps and Control Devices
Subsea Pumps Market
Pumps and Control Devices
Industrial Pump Control Panels Market
Pumps and Control Devices
Vertical Turbine Pumps Market
Pumps and Control Devices
Lubrication Pump Systems Market
Pumps and Control Devices
Global Submersible Pumps Market
Pumps and Control Devices
Cone Penetrometer Market
Pumps and Control Devices
US Industrial Pump Market
Pumps and Control Devices
Pressure Washer Pump Oil Market
Pumps and Control Devices
Drum Pump Market
Pumps and Control Devices
Electrostatic Coalescers Market
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
Global Solar Water Pump Systems Market
Pumps and Control Devices
Europe, Middle-East and Africa Diaphragm Pump Market
Pumps and Control Devices
Hydraulic Pumps Market