
 Condensate Pump Market | 2026-2036
Condensate Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Condensate Pump Market Intelligence
HVAC application demand is broadening as commercial building retrofits accelerate and mini-split installations multiply in multi-family housing. Armstrong International Inc. leverages its steam-utility heritage to anchor industrial-grade condensate recovery systems. Little Giant competes in residential basement and dehumidifier segments through compact electric designs. Sauermann Group specializes in silent-running mini-pump technology for ceiling-void installations where space constraints dominate specification.
A condensate pump is a centrifugal or positive-displacement device engineered to collect and evacuate liquid condensate from air-handling units, boilers, and refrigeration systems, typically operating against heads of 15-50 feet with flow rates under 50 GPM. Electric pumps dominate unit volume across residential and light-commercial installations due to plug-and-play wiring and low maintenance. HVAC applications command the largest revenue pool as chiller plants and rooftop units require continuous condensate removal to prevent coil icing and microbial growth. Food & Beverage end users represent a concentrated margin segment because sanitary-grade stainless construction and FDA-compliant materials command specification premiums.
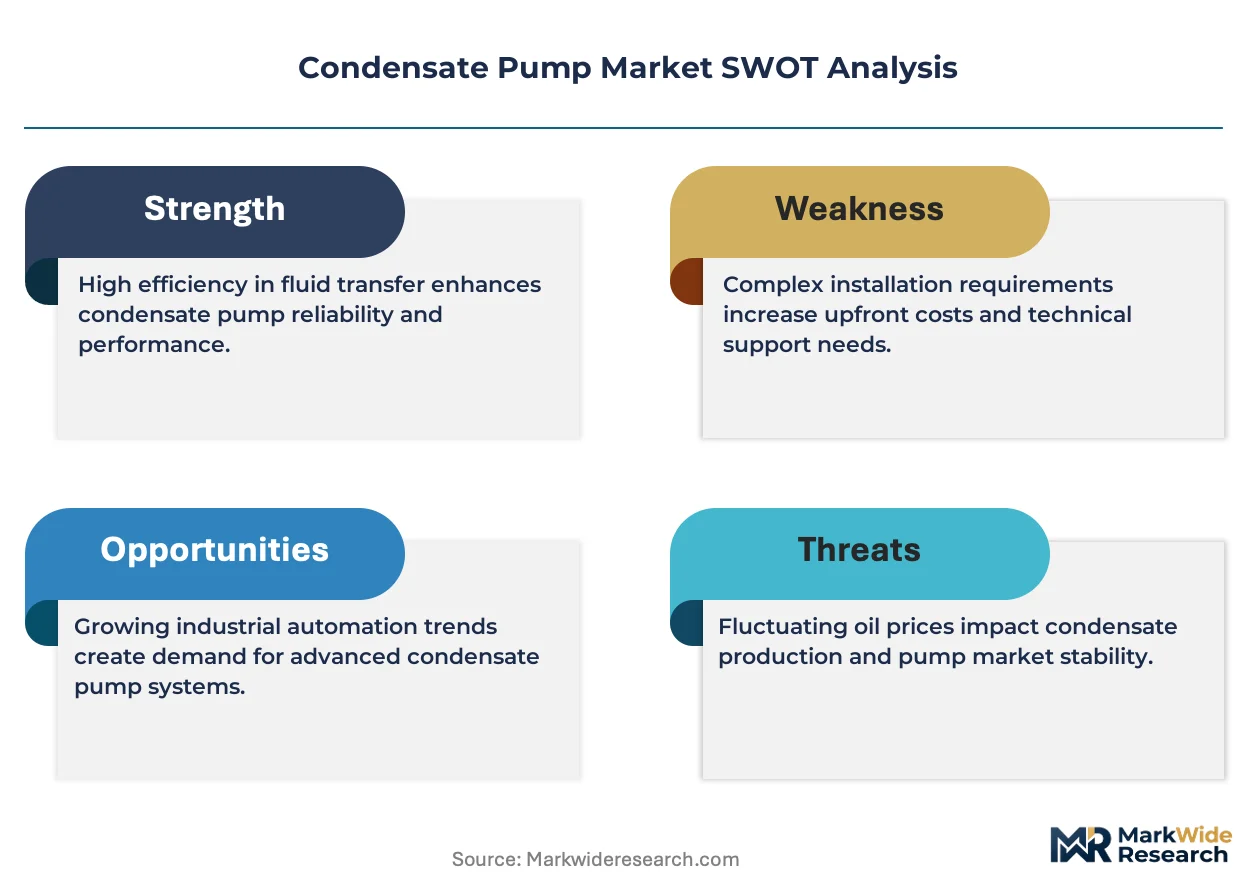
The US Department of Energy enforces minimum efficiency standards for clean-water pumps under 10 CFR 431, directly affecting electric condensate pump motor selections and hydraulic design. The EU Ecodesign Directive and CE marking requirements under the Machinery Directive shape market access for products sold into European commercial HVAC channels. China's GB standards and NMPA-equivalent quality certifications add compliance layers for imports serving its expanding data-center cooling market. Stakeholders must monitor regulatory divergence between efficiency mandates and material restrictions as they calibrate regional product portfolios and certification investments.
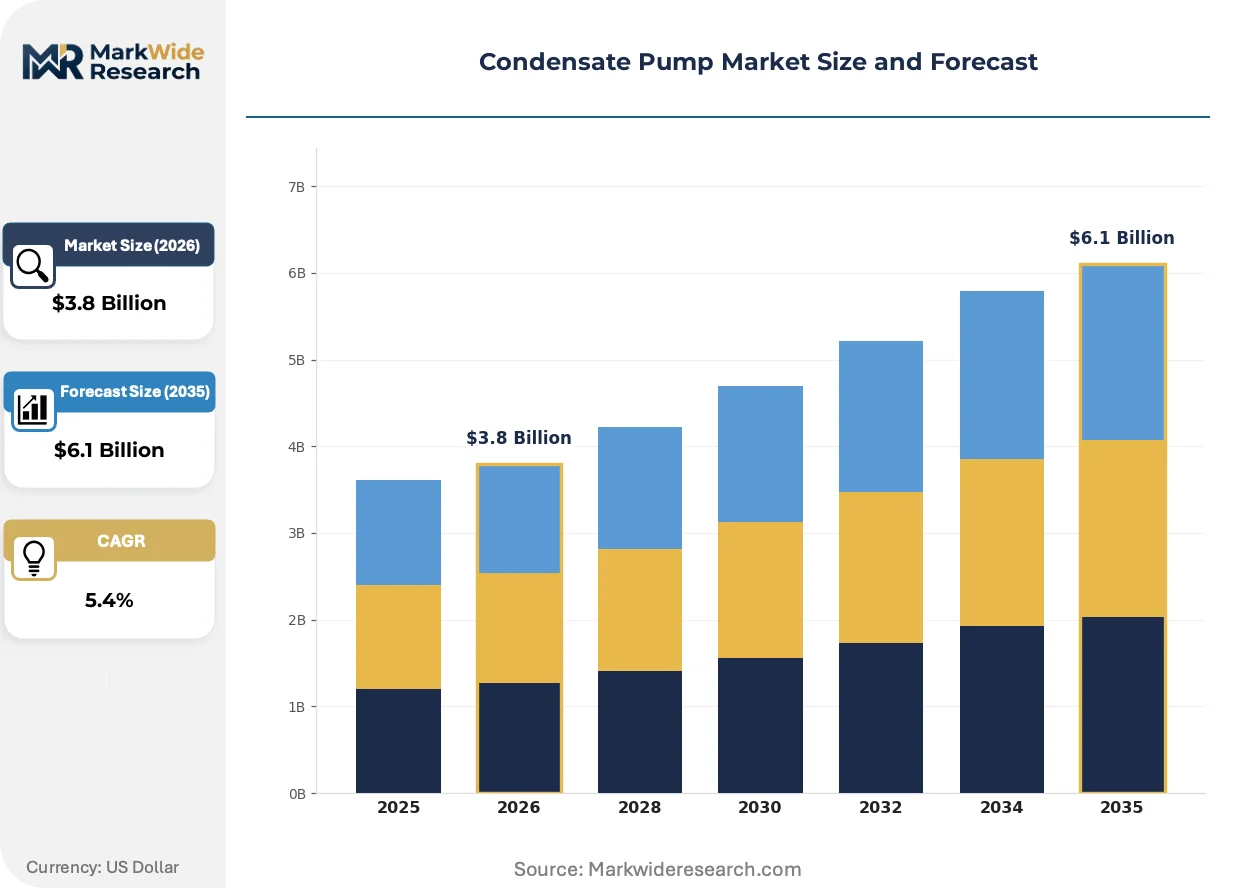
Market Dynamics
Energy-efficiency mandates across North America and Europe are compressing product lifecycles and forcing motor redesigns in condensate pump manufacturing. The US Department of Energy's pump efficiency standards under 10 CFR 431 and the EU Ecodesign Directive are eliminating lower-tier products from commercial channels.
Growth Catalysts
- Commercial building retrofits:Aging HVAC infrastructure in the US Northeast and Germany requires condensate pump replacements to meet modern efficiency codes.
- 10 CFR 431 enforcement:The US Department of Energy's minimum efficiency standards are accelerating electric motor upgrades across residential and light-commercial installations.
- Mini-split proliferation:Multi-family housing developers in Japan and South Korea specify compact condensate pumps for ceiling-void applications where drainage gravity is unavailable.
Market Restraints
- Copper and rare-earth price volatility:Electric motor windings and permanent magnets face input cost swings that compress manufacturer margins.
- Supply concentration in East Asian motor production:Dependence on Chinese and Taiwanese motor suppliers creates vulnerability to trade policy shifts and logistics disruption.
- Gravity drainage substitution:New construction with improved architectural drainage design eliminates pump need in ground-floor and basement applications.
Strategic Opportunities
- Data-center cooling expansion:Hyperscale facilities in India's NCR and Hyderabad require high-reliability condensate removal for precision air-handling units.
- EU F-Gas Regulation phase-down:Refrigerant transition timelines are extending equipment replacement cycles, creating aftermarket pump retrofit demand.
- IoT-enabled predictive maintenance:Sensor-integrated pumps communicating via BACnet and Modbus protocols are opening premium service-contract revenue streams.
Industry Challenges
- Multijurisdictional certification timelines:UL, CE marking, and China's GB standards require parallel testing tracks that delay product launches by 8-14 months.
- Legacy BAS integration complexity:Building automation systems from the 1990s lack digital communication protocols, forcing custom interface development for smart pump retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Condensate Pump Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Pneumatic, Hydraulic, Manual Application: Residential, Commercial, Industrial, HVAC End User: Manufacturing, Oil & Gas, Power Generation, Food & Beverage Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Armstrong International Inc., Little Giant, Liberty Pumps, Sauermann Group, Aspen Pumps Limited, Grundfos Pumps Corporation, Hartell, Pentair, ebm-papst, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Condensate Pump Market Strategic Shifts & Innovations
Silent-running mini-pump architectures and intelligent motor controls are displacing conventional centrifugal designs in space-constrained installations. These advances are compressing the performance gap between residential and commercial-grade equipment.
Magnetic-drive sealless pump technology is expanding into food processing and pharmaceutical cleanrooms where leakage contamination risks are unacceptable. Breweries in Belgium and dairy processors in Wisconsin specify these pumps for CIP-compatible condensate recovery. The elimination of mechanical seals reduces maintenance intervals from quarterly to annual, compressing total cost of ownership calculations against conventional designs.
The EU F-Gas Regulation and its refrigerant phase-down schedule are forcing chiller OEMs to redesign evaporator and condenser configurations. These equipment changes alter condensate generation rates and chemistry, requiring pump manufacturers to recalibrate flow curves and material compatibility. German and Italian HVAC contractors now specify pumps with broader pH tolerance ranges to accommodate transitional refrigerant blends.
Facility managers in US commercial real estate are unbundling after-sales service from equipment procurement, signing direct maintenance contracts with pump specialists rather than relying on original HVAC installers. This disintermediation shifts margin capture toward service networks with diagnostic capabilities and regional parts inventory. The pattern is most visible in Class A office buildings in Chicago and Atlanta where multi-vendor equipment fleets complicate single-source maintenance agreements.
Condensate Pump Market Segmentation
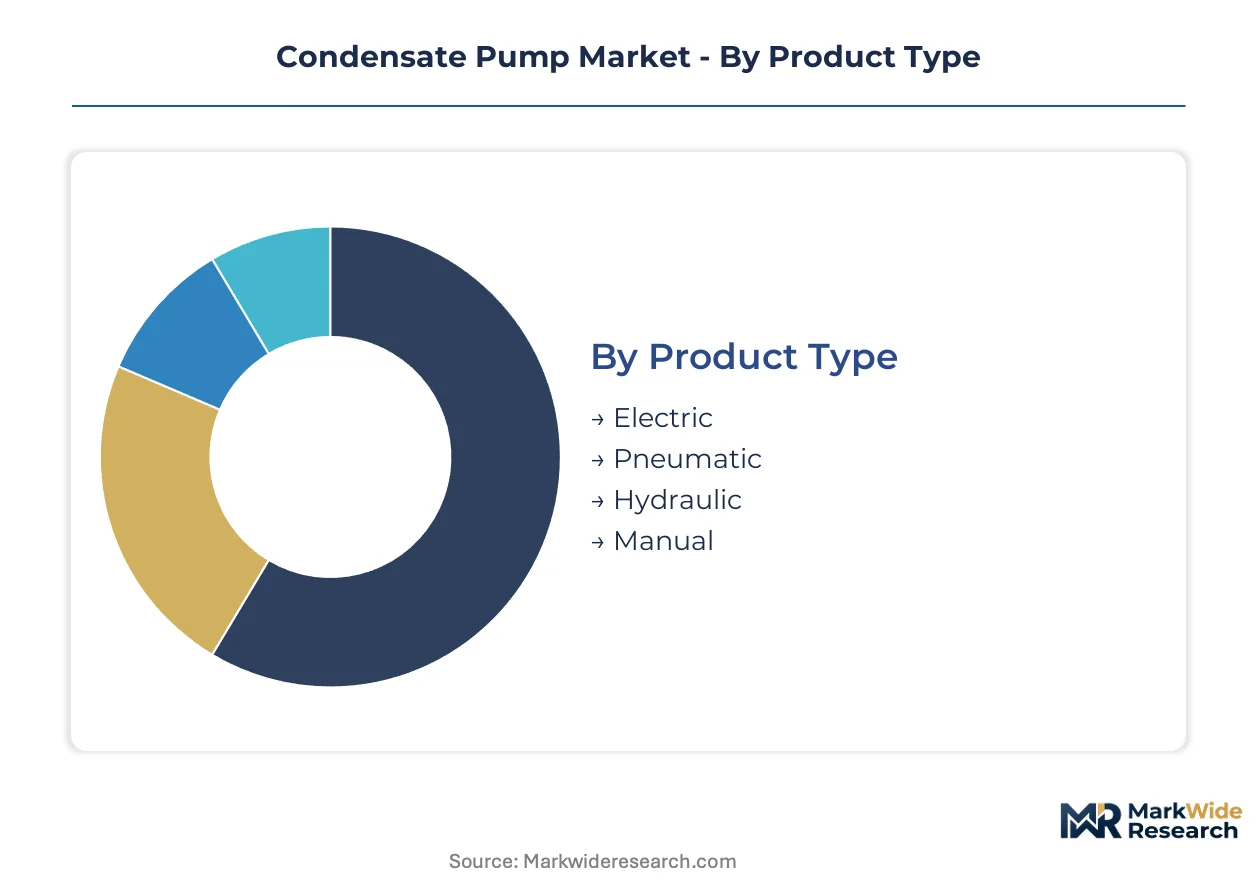
Condensate pump procurement patterns diverge sharply across product architectures and installation environments. Specification requirements for motor efficiency, material compatibility, and control integration vary by application intensity, creating distinct competitive arenas within each segment boundary.
Product Type:
Supply concentration in electric motor manufacturing tilts competitive dynamics toward manufacturers with captive winding capabilities or long-term magnet supply agreements.
- Electric:Centrifugal and positive-displacement designs utilizing AC induction or brushless DC motors dominate unit shipments across residential and light-commercial channels. DOE 10 CFR 431 efficiency mandates are compressing motor selections to premium-efficiency tiers in US commercial procurement.
- Pneumatic:Compressed-air-driven diaphragm and piston configurations serve explosion-risk environments in petrochemical and solvent-processing facilities where electrical ignition hazards prohibit standard motor pumps. Demand concentrates along the US Gulf Coast and Rotterdam-Antwerp refining corridor.
- Hydraulic:Fluid-power actuation for high-pressure condensate recovery in steam-intensive industrial processes.
- Manual:Hand-operated displacement pumps for backup drainage and maintenance bypass in legacy building infrastructure.
Electric configurations absorb the bulk of installed capacity; pneumatic designs are expanding most quickly in hazardous-location specification.
Application:
Cost-tier differentiation separates specification-grade commercial equipment from mass-market residential units, with industrial applications commanding material and testing premiums.
- Residential:Compact electric units with 15-20 foot discharge heads serve basement dehumidifiers, mini-split condensate lines, and high-efficiency furnace drainage. Multi-family developers in Japan and South Korea specify ultra-quiet ceiling-void designs where gravity drainage is architecturally impossible.
- Commercial:Stainless-steel or corrosion-resistant thermoplastic housings with integrated float switches and alarm outputs protect chiller plants and rooftop units in Class A office buildings. Facility managers in Chicago and Atlanta are unbundling service contracts from equipment procurement, favoring pumps with BACnet diagnostic compatibility.
- Industrial:Heavy-duty cast-iron or alloy construction for continuous-duty steam condensate recovery and process cooling loops.
- HVAC:Application-specific designs optimized for air-handling unit integration and variable refrigerant flow systems.
Commercial applications command the steepest pricing tiers; residential volume is climbing fastest in multi-family construction corridors.
End User:
Margin structure varies by material certification requirements, with sanitary-grade construction capturing specification premiums in regulated processing environments.
- Food & Beverage:316L stainless steel and FDA-compliant elastomers are mandatory for condensate recovery in dairy processing, brewing, and prepared-food manufacturing. CIP-compatible magnetic-drive sealless designs reduce maintenance intervals from quarterly to annual at Wisconsin dairy processors and Belgian breweries.
- Power Generation:High-reliability turbine condensate recovery systems with redundant pump configurations and continuous monitoring. Steam plant operators specify pumps with NACE-compliant materials for corrosive condensate chemistry.
- Manufacturing:General industrial process cooling and compressed air system condensate removal across discrete and process manufacturing.
- Oil & Gas:Explosion-proof and sour-service rated equipment for refinery and upstream processing condensate handling.
Food & Beverage installations absorb the bulk of premium-material capacity; power generation replacement cycles are extending fastest as plant lifecycles stretch.
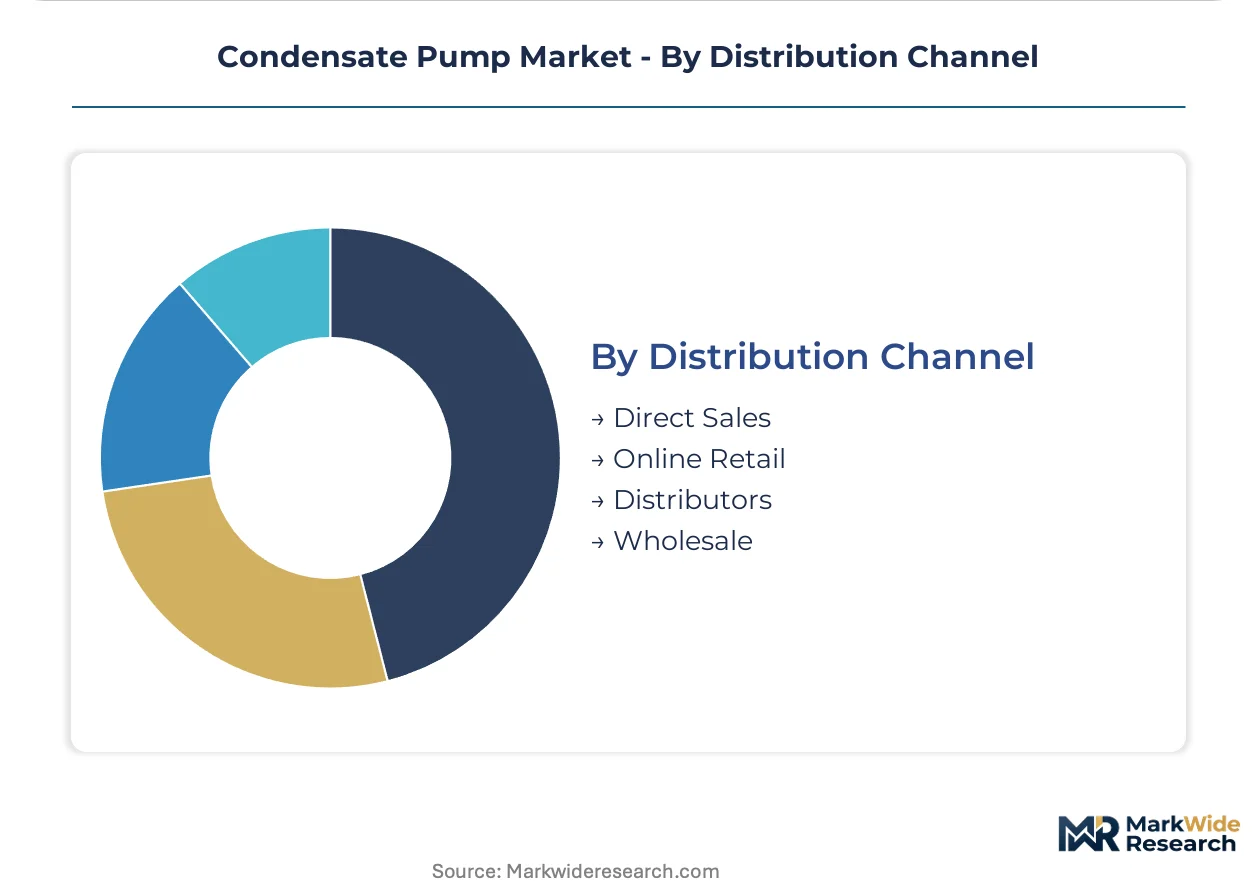
Distribution Channel:
Customer-type stratification separates specification-driven direct procurement from price-sensitive aftermarket replacement through wholesale channels.
- Distributors:HVAC and plumbing specialists with regional inventory and same-day availability dominate commercial retrofit and emergency replacement demand. German and Italian contractors rely on distributor technical support for EU F-Gas Regulation transition compatibility verification.
- Direct Sales:OEM channel partnerships with chiller and air-handling unit manufacturers for original equipment specification. Armstrong International and Sauermann Group cultivate direct relationships with multinational facility management firms for standardized portfolio deployment.
- Online Retail:E-commerce penetration concentrates in residential replacement and small-contractor procurement.
- Wholesale:Volume purchasing for new construction and multi-unit development projects.
Distributor networks handle the bulk of transaction volume; direct sales channels are gaining share fastest in multinational account consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Condensate pump manufacturing concentrates in East Asian motor production clusters, while consumption tilts toward North American and European commercial retrofit markets. Germany and the United States absorb the bulk of specification-grade demand as efficiency mandates compress product lifecycles. India's data-center corridor and Japan's multi-family construction belt are emerging as volume growth poles.
United States
Commercial building retrofits in the Northeast and Southeast manufacturing belt drive specification demand. DOE 10 CFR 431 enforcement accelerates electric motor upgrades across residential and light-commercial channels. Chicago and Atlanta facility managers unbundle service contracts from equipment procurement, favoring pumps with BACnet diagnostic compatibility.
Germany
Industrial corridor demand centers on steam-utility heritage applications and chiller plant replacements. EU Ecodesign Directive and F-Gas Regulation reshape product specifications and extend equipment replacement cycles. HVAC contractors in Bavaria and North Rhine-Westphalia specify pumps with broader pH tolerance ranges for transitional refrigerant blends.
China
Data-center cooling expansion in the Yangtze River Delta and Pearl River Delta generates high-reliability condensate removal demand. GB standards and NMPA-equivalent quality certifications add compliance layers for imports serving precision air-handling units. Ningbo and Shenzhen motor suppliers dominate global winding and magnet supply.
Japan
Multi-family housing developers in Tokyo and Osaka specify ultra-quiet ceiling-void designs where gravity drainage is architecturally impossible. METI efficiency guidelines and JIS standards shape product development for mini-split proliferation. Kansai region contractors prioritize silent-running architectures for dense urban installations.
India
Hyperscale data-center facilities in Delhi-NCR and Hyderabad require continuous condensate removal for precision cooling systems. BIS certification and CEA electrical safety mandates govern commercial HVAC equipment import. Maharashtra and Karnataka industrial zones are expanding process cooling infrastructure with condensate recovery specifications.
Condensate Pump Market Key Industry Players
Top-tier vendors anchor specification-grade commercial and industrial channels, while mid-tier specialists compete on residential volume and price-sensitive retrofit demand. The vendor base organizes around three strategic archetypes: steam-utility heritage industrialists, compact electric residential specialists, and silent-running mini-pump innovators. Dominant competitive moves include geographic expansion through distributor network consolidation and technology licensing for IoT-enabled predictive maintenance capabilities.
Within the steam-utility heritage tier, Armstrong International Inc. occupies a position exemplifying industrial-grade condensate recovery system anchoring. Sauermann Group represents the silent-running mini-pump specialization for space-constrained ceiling-void installations. Little Giant sits within the compact electric segment, competing on residential basement and dehumidifier applications through plug-and-play design archetypes.
| Leading Market Players |
|---|
| Armstrong International Inc. |
| Little Giant |
| Liberty Pumps |
| Sauermann Group |
| Aspen Pumps Limited |
| Grundfos Pumps Corporation |
| Hartell |
| Pentair |
| ebm-papst |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up distributors across the US Midwest and Germany's industrial belt have compressed procurement cycles and sharpened price discipline, forcing manufacturers to absorb copper and rare-earth volatility while defending specification-grade premiums.
Pricing Analysis
Margin tightening in residential electric pumps reflects DOE 10 CFR 431 compliance costs and East Asian motor import tariffs. Three-tier pricing structure across premium, standard, and economy levels separates UL-certified commercial units from mass-market basement replacements. Price differentiation hinges on BACnet diagnostic integration and stainless-steel construction grade. Residential contractors exhibit highest price sensitivity; data-center operators prioritize reliability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and Taiwanese rare-earth magnet suppliers feeding Ningbo motor winding clusters. Copper cathode draws from Chilean and Indonesian smelters; cast-iron housings source from Indian and German foundries. Tariff exposure on permanent-magnet imports threatens margin stability for brushless DC motor configurations. Distribution runs through HVAC wholesaler networks with regional same-day inventory in Chicago, Atlanta, and Germany's Ruhr corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers consolidation leverage as efficiency mandates eliminate sub-tier motor suppliers unable to fund multi-jurisdictional certification tracks.
For Market Incumbents: Anchor specification-grade positioning through captive magnet supply agreements or backward integration into motor winding. Defend against Asian cost-competitive entrants by embedding IoT diagnostic modules that lock facility managers into service contracts. Prioritize CE marking and UL dual-track certification to compress rival launch timelines. For New Entrants and Emerging Players: Capture white-space in India's data-center cooling corridor where hyperscale operators prioritize local service presence over legacy brand recognition. Target pneumatic pump demand along the US Gulf Coast refinery belt where explosion-proof specifications limit incumbent scale advantages. Lead with magnetic-drive sealless designs for Wisconsin dairy and Belgian brewing CIP applications. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier electric specialists with stranded GB-standard inventory in China's Yangtze Delta manufacturing belt. Long-term viability hinges on IoT-enabled service revenue streams displacing transactional equipment margins. Monitor EU F-Gas Regulation implementation velocity as inflection signal for aftermarket retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Magnet Supply Agreement | Secures rare-earth access from Chinese and Taiwanese refiners against tariff disruption. |
| BACnet Protocol Integration | Enables Chicago and Atlanta facility managers to unbundle service from equipment procurement. |
| Dual Certification Investment | Compresses rival launch timelines across US DOE and EU Ecodesign compliance tracks. |
| Regional Distributor Consolidation | Builds same-day inventory density in Germany's North Rhine-Westphalia corridor. |
| IoT Predictive Maintenance Platform | Opens premium service-contract revenue streams for data-center cooling applications. |
Research Approach
Multi-period observation of DOE enforcement patterns, EU F-Gas transition timelines, and copper price volatility anchored the trend analysis, supplemented by interviews with HVAC contractors in Chicago and Atlanta, facility managers at Class A office portfolios, German industrial steam-utility operators, and procurement leads at Indian hyperscale data centers. Secondary validation drew from DOE 10 CFR 431 docket filings, EU Ecodesign Directive implementing measures, SEC 10-K disclosures from listed pump manufacturers, and customs trade data for rare-earth magnet imports. Bottom-up channel volume estimates triangulated against top-down construction spending and HVAC equipment shipment data.
Segment-weighting across product type, application intensity, and end-user material certification requirements structured the analytical framework over the projection horizon. CAGRs derived from installed base replacement cycles, efficiency mandate compliance deadlines, and refrigerant transition timelines. Industry-specific inputs included mini-split penetration rates in Japanese multi-family construction and data-center cooling capacity buildouts in India's NCR and Hyderabad corridors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare-earth export restrictions, trade policy shifts, and refrigerant chemistry transitions altering condensate pH tolerance specifications. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Middle East and Africa Centrifugal Pumps Market
Pumps and Control Devices
Mixed Flow Pump Market
Pumps and Control Devices
Industrial Vacuum Pumps Market
Pumps and Control Devices
Centrifugal Pump Market
Pumps and Control Devices
Middle East and Africa Positive Displacement Pumps Market
Pumps and Control Devices
Spin-On Hydraulic Filter Market
Pumps and Control Devices
Asia Pacific Submersible Pump Market
Pumps and Control Devices
Europe Centrifugal Pumps Market
Pumps and Control Devices
Circulators Market
Pumps and Control Devices
Fluid Transfer System Market
Pumps and Control Devices
Industrial ASME B73.1 Centrifugal Pumps Market
Pumps and Control Devices
Asia-Pacific Cryogenic Pump Market
Pumps and Control Devices
Heavy Duty Dewatering Pumps Market
Pumps and Control Devices
North America Dispensing Pumps Market
Pumps and Control Devices
Industrial Oil Filter Machine Market
Pumps and Control Devices
Suction Pump Market