
 Global Monochloroacetic Acid Market | 2026-2036
Global Monochloroacetic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Monochloroacetic Acid Market Foresight
Specialty derivative manufacturing is reshaping margin distribution across the monochloroacetic acid value chain. AkzoNobel leverages its chlor-alkali integration to control feedstock costs across European production hubs. CABB Group anchors its position through dedicated MCA capacity serving agrochemical and pharmaceutical contract synthesis. Nouryon competes on technology leadership in chlorination process efficiency, sustaining lower unit economics at scale.
Monochloroacetic acid (ClCH₂COOH) is an organochlorine compound produced via acetic acid chlorination, typically yielding crystalline solid or aqueous solution with active content ranging from 80% to 99% depending on purification grade. The substance serves primarily as an intermediate for carboxymethyl cellulose, thioglycolic acid, and glyphosate precursors, with purity thresholds determining eligibility for pharmaceutical versus industrial end uses. Technical grade material dominates current volume flows, while pharmaceutical production end use industry commands premium pricing due to stringent impurity limits. Cosmetic grade output is expanding fastest among product type categories, driven by surfactant and personal care intermediate demand. Chemical manufacturing end use industry remains the most mature demand pool, with margin compression pushing producers toward captive consumption models.
EPA oversight of chlorinated organic emissions shapes US plant siting and abatement investment requirements, while REACH registration mandates in Europe constrain non-compliant import volumes. China's MEE enforces wastewater discharge limits that filter smaller chlorination operators from the supplier base. Stakeholders must monitor regulatory divergence on chlorinated byproduct thresholds, as compliance cost asymmetries are redirecting trade flows between Atlantic and Pacific supply corridors.
Market Dynamics
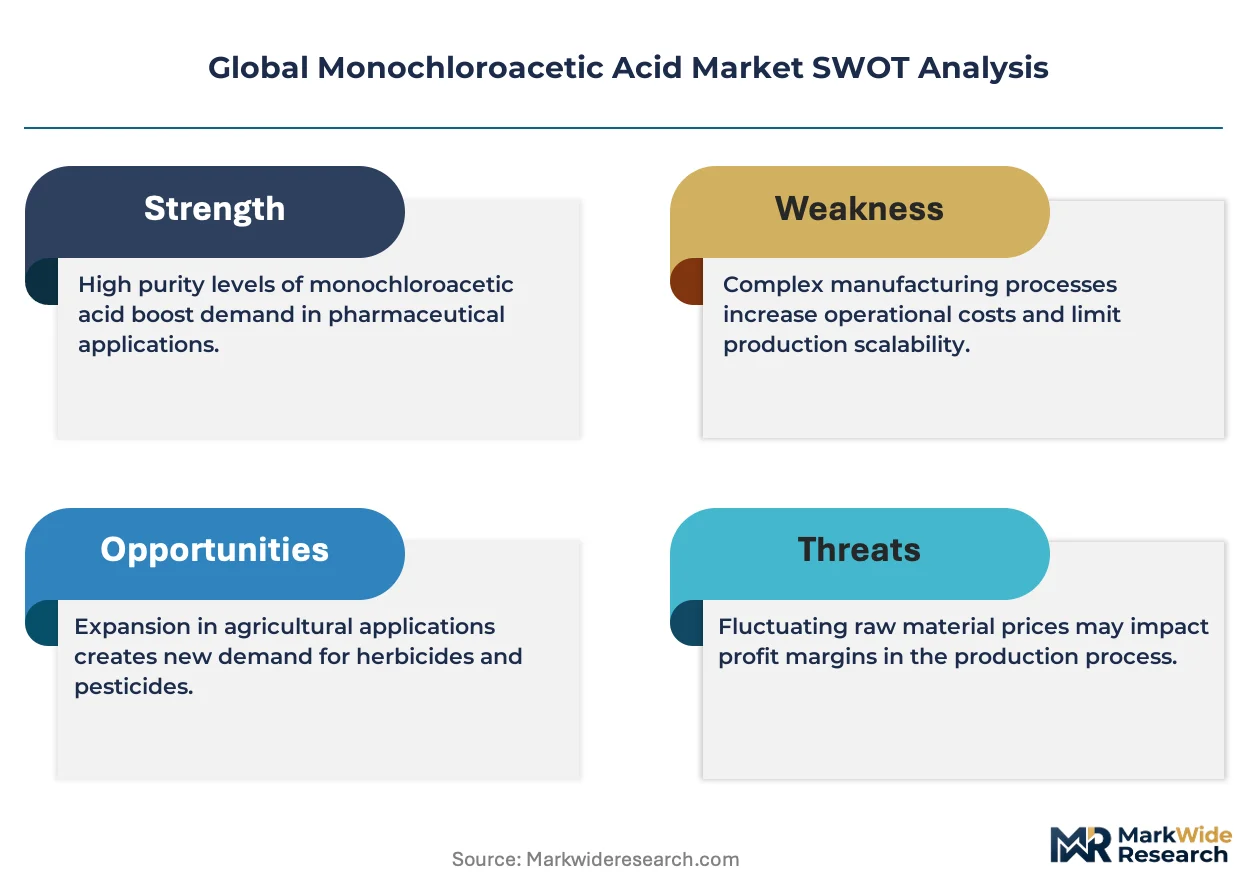
Chlor-alkali integration economics and tightening purity mandates from pharmaceutical regulators are compressing margins for non-integrated producers while rewarding operators with captive acetic acid supply and multi-stage purification trains.
Growth Catalysts
- REACH purity thresholds:European pharmaceutical manufacturers now require sub-50 ppm dichloroacetic acid impurity levels, pulling technical-grade producers toward higher-margin certification tiers.
- Glyphosate precursor demand:Agrochemical formulators in Brazil and Argentina are expanding glyphosate salt production, consuming MCA as the primary chloromethylation feedstock.
- Continuous chlorination technology:Advanced loop reactors with real-time HCl separation are reducing acetic acid losses below 3%, improving yield economics for adopters.
Market Restraints
- Acetic acid price volatility:Feedstock costs fluctuate with methanol-carbonylation plant operating rates, squeezing toll manufacturers without long-term supply contracts.
- Jiangsu-Zhejiang supply concentration:Over 60% of Chinese MCA capacity clusters in two provinces, exposing buyers to regional environmental shutdowns and logistics bottlenecks.
- Chloroacetic acid substitution:Thioglycolic acid producers in cosmetic applications are testing glyoxylic acid routes to bypass chlorinated intermediate handling restrictions.
Strategic Opportunities
- India PLI scheme tailwinds:Active pharmaceutical ingredient manufacturing incentives are attracting MCA purification investments to serve domestic and export markets.
- Biodegradable surfactant intermediates:Carboxymethyl cellulose demand from personal care formulators is creating new volume anchors for cosmetic-grade MCA specifications.
- Carbon border adjustment mechanism:EU CBAM implementation is favoring European producers with verified low-carbon chlorination processes against import competition.
Industry Challenges
- Chlorination process engineering expertise:Experienced operators capable of managing exothermic acetic acid chlorination with precise temperature control remain scarce in emerging production regions.
- Multi-jurisdiction registration timelines:Simultaneous REACH, EPA TSCA, and China MEE new substance notifications extend market entry cycles to 24-36 months for purified grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Monochloroacetic Acid Market |
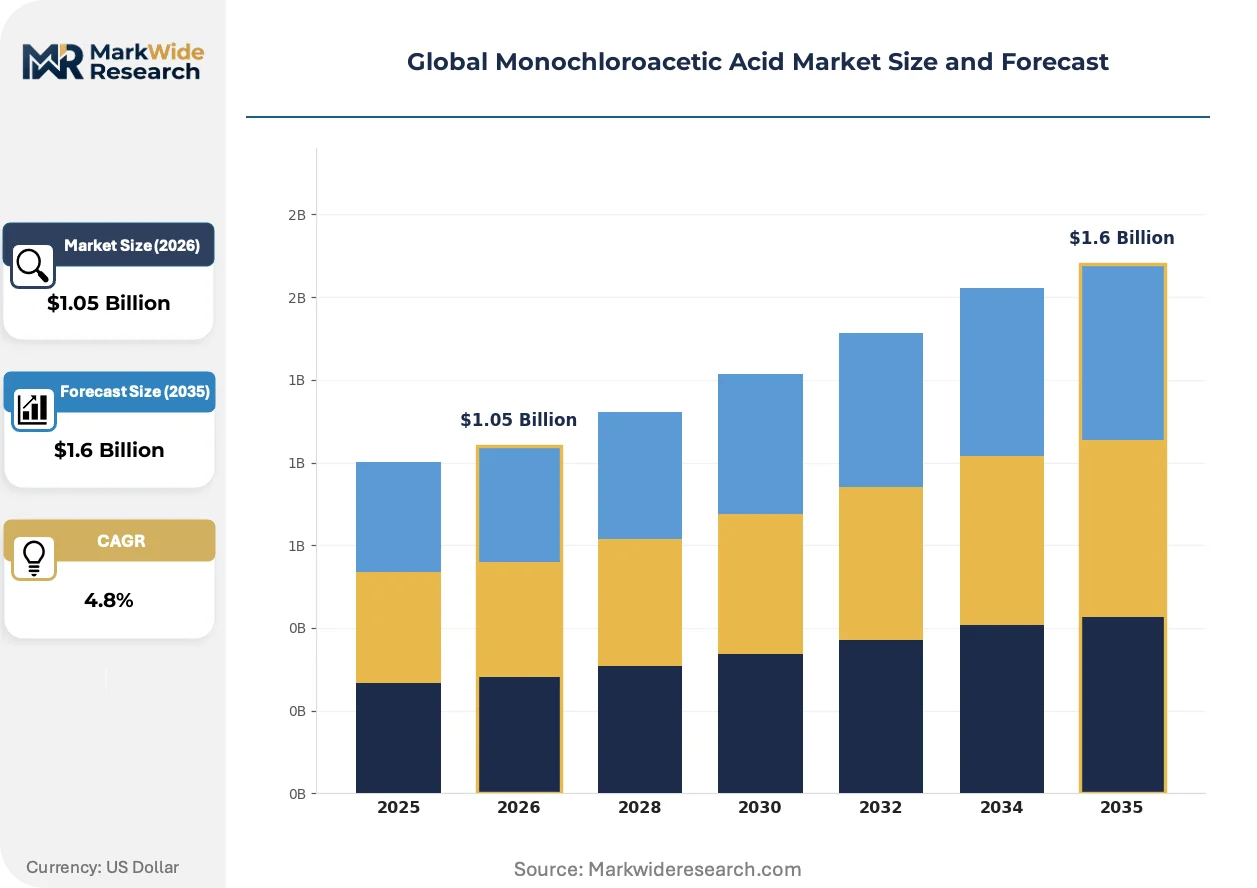
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.6 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Industrial Grade, Cosmetic Grade, Food Grade Application: Herbicides, Textile Processing, Pharmaceuticals, Surfactants, Adhesives End Use Industry: Crop Protection, Chemical Manufacturing, Pharmaceutical Production, Textile Treatment Packaging Type: Drums, Bulk Tankers, Intermediate Bulk Containers, Bags |
| Companies Covered | AkzoNobel, CABB Group, Niacet Corporation, PCC Group, Shandong Minji Chemical, Denak Co. Ltd., Nouryon, Daicel Corporation, Meridian Chem-Bond, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Monochloroacetic Acid Market Shifts & Advancements
Process intensification and regulatory digitization are converging to reshape how chlorination operations demonstrate compliance and optimize yield. These shifts favor capital-rich incumbents while raising barriers for batch-oriented toll manufacturers.
Advanced process control systems with embedded spectroscopic analyzers are digitizing real-time impurity monitoring in continuous chlorination trains. Pharmaceutical contract manufacturers are adopting these systems fastest, driven by FDA process analytical technology guidance. The digitization is compressing batch release timelines from days to hours while reducing off-specification material volumes.
REACH Annex XVII restrictions on chlorinated byproduct discharge are forcing European producers to install thermal oxidizers or catalytic destruction units for vent gas treatment. The regulation is adding 8-12% to capital costs for new capacity. Technical-grade producers serving industrial markets are absorbing these costs through longer depreciation schedules rather than price pass-through.
Consolidated procurement through chemical management service contracts is displacing spot purchasing among large agrochemical formulators. Tier-one distributors with integrated logistics and inventory management capabilities are capturing volume previously fragmented across regional traders. Brazil and Argentina show this pattern most acutely, where multinational crop protection companies have centralized MCA sourcing decisions to São Paulo and Buenos Aires hubs.
Global Monochloroacetic Acid Market Segmentation
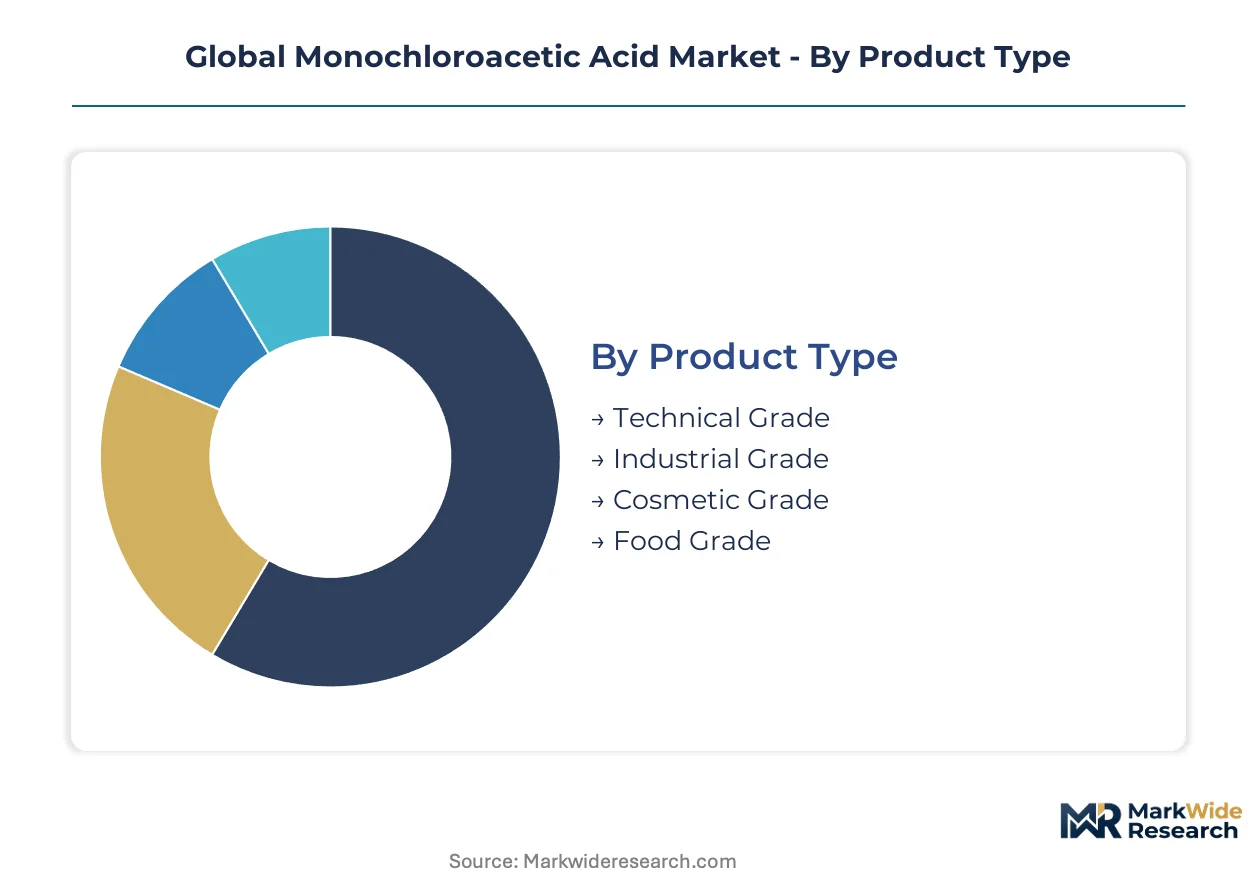
Segmentation in monochloroacetic acid markets tracks how purity thresholds and handling requirements split procurement patterns across pharmaceutical, agrochemical, and industrial buyers. Each grade carries distinct regulatory burdens and service intensity levels that reshape supplier relationships and margin structures.
Product Type:
After-sales service intensity escalates sharply with purity grade, as pharmaceutical and cosmetic buyers demand certificate-of-analysis documentation, batch traceability, and regulatory filing support that technical-grade purchasers rarely require.
- Technical Grade:Material with 80-85% active content and higher dichloroacetic acid residuals serves glyphosate precursor synthesis and industrial carboxymethylation. Demand concentrates in Brazil and Argentina agrochemical corridors where Brazilian formulators absorb volume for glyphosate salt production despite REACH-migrating purity standards pressing specifications upward.
- Cosmetic Grade:Refined to sub-100 ppm impurity thresholds with dedicated heavy metal screening, this specification feeds thioglycolic acid and personal care surfactant synthesis. European and Indian personal care formulators are expanding procurement fastest, drawn by biodegradable surfactant intermediate mandates and CDSCO-aligned import documentation requirements.
- Industrial Grade:Mid-tier purification serving adhesive and textile processing applications with moderate chloride tolerance.
- Food Grade:Highest certification tier with full toxicological dossiers for food additive and pharmaceutical excipient use.
Technical grade holds the largest share; momentum sits with cosmetic grade specifications.
Application:
Cost tier stratification separates commodity herbicide feedstocks from premium pharmaceutical intermediates, with surfactant applications occupying a contested middle ground where purity premiums face formulation cost pressure.
- Herbicides:Glyphosate precursor consumption dominates volume flows, with chloromethylation routes consuming MCA as the primary methylating agent. Brazilian and Argentine crop protection manufacturers anchor demand, though substitution pressure from glyoxylic acid pathways is testing chlorinated intermediate tolerance in EU-destined formulations.
- Pharmaceuticals:Active ingredient synthesis for ibuprofen, diclofenac, and other NSAID precursors demands sub-50 ppm dichloroacetic acid thresholds under FDA process analytical technology guidance. Indian API manufacturers under PLI scheme incentives are expanding purification capacity fastest, drawing cosmetic-grade MCA into pharmaceutical certification tiers.
- Textile Processing:Carboxymethyl cellulose production for fabric finishing and sizing occupies mature demand pools with thinning margins.
- Surfactants:Personal care and industrial detergent intermediates split between cosmetic-grade specification and industrial-grade tolerance.
- Adhesives:Cyanoacrylate and other specialty adhesive synthesis consumes technical-grade material with moderate purity requirements.
Herbicide applications dominate volume; pharmaceuticals command the steepest expansion trajectory.
End Use Industry:
Customer type fragmentation separates multinational formulators with consolidated procurement desks from regional toll manufacturers negotiating spot supply, with contract synthesis relationships reshaping pharmaceutical segment dynamics.
- Crop Protection:Multinational agrochemical companies operating São Paulo and Buenos Aires procurement hubs are centralizing MCA sourcing through chemical management service contracts. Brazilian glyphosate formulators absorb the largest single-country volume, with ANVISA registration requirements filtering non-compliant import sources.
- Pharmaceutical Production:Contract development and manufacturing organizations in India and Europe are qualifying dedicated MCA supply chains under ICH Q7 guidelines, with CDSCO and EMA inspections driving documentation intensity. The segment commands premium pricing through multi-stage purification and real-time spectroscopic release testing.
- Chemical Manufacturing:Captive consumption models dominate as integrated chlor-alkali operators internalize MCA for downstream derivative output, compressing third-party merchant demand.
- Textile Treatment:Regional dyeing and finishing houses in China and India purchase technical-grade material with limited service attachment.
Crop protection absorbs the largest volume; pharmaceutical production is gaining share fastest.
Packaging Type:
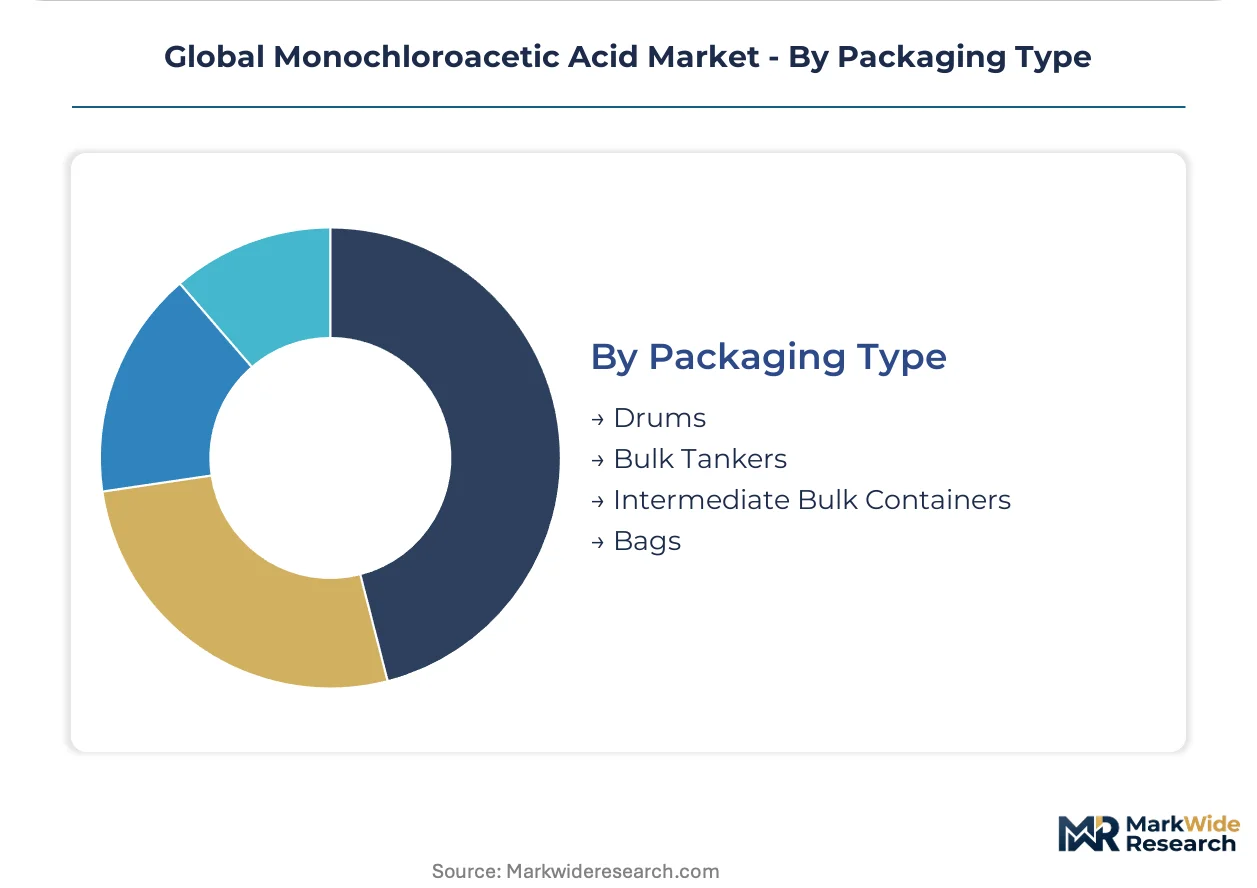
Supply concentration in Jiangsu and Zhejiang provinces shapes logistics economics, with bulk formats favored by integrated derivatives producers and smaller packaging serving dispersed textile and pharmaceutical compounders.
- Bulk Tankers:Dedicated ISO-tank and road-tanker deliveries serve glyphosate precursor manufacturers and large CMC producers with continuous chlorination feed requirements. Brazilian and Indian formulators with direct port access favor this format for cost minimization.
- Intermediate Bulk Containers:1000-liter totes balance handling efficiency with flexibility for mid-scale pharmaceutical and surfactant manufacturers. European CDMOs are standardizing on IBC formats with integrated sampling ports to support process analytical technology compliance.
- Drums:200-liter steel and polyethylene drums serve regional textile processors and small-batch pharmaceutical compounders with limited storage infrastructure.
- Bags:Multi-layer laminated bags contain crystalline solid grades for adhesive and specialty chemical applications with low moisture sensitivity.
Bulk tankers hold the largest share; momentum sits with intermediate bulk containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and India consume MCA primarily for agrochemical and pharmaceutical intermediates, while European demand tilts toward cosmetic-grade specifications under REACH purity mandates. Brazil anchors glyphosate precursor consumption in the Americas, diverging from the pharmaceutical-heavy import profiles of Germany and the United States.
China
Jiangsu and Zhejiang provinces host over sixty percent of national chlor-alkali integrated MCA capacity, feeding glyphosate precursor and carboxymethyl cellulose derivatives. MEE wastewater discharge enforcement has shuttered smaller chlorination operators since 2021, consolidating output among state-affiliated chemical groups. Nantong and Taizhou chemical parks are expanding continuous chlorination trains to serve domestic agrochemical formulators and Indian pharmaceutical API buyers.
India
Maharashtra and Gujarat absorb the fastest-growing pharmaceutical-grade MCA demand as CDSCO-aligned API manufacturers scale under PLI scheme incentives. Dahej and Mundra port corridors are attracting purification investments to bypass European import documentation burdens. Ankleshwar and Tarapur chemical estates are qualifying dedicated MCA supply chains under ICH Q7 guidelines for contract synthesis exports.
Germany
North Rhine-Westphalia chemical clusters anchor European MCA demand for thioglycolic acid and cosmetic surfactant intermediates. ECHA REACH Annex XVII restrictions on chlorinated byproduct discharge have forced thermal oxidizer installations at Leverkusen and Dormagen production hubs. BASF and Bayer legacy sites in Ludwigshafen are transitioning toward pharmaceutical-grade certification tiers to capture premium pricing from EMA-inspected CDMOs.
Brazil
São Paulo state concentrates glyphosate salt formulator demand, with ANVISA registration requirements filtering non-compliant MCA import sources. Port of Santos bulk tanker receipts serve multinational crop protection companies operating centralized procurement desks. Paulínia and Cubatão chemical parks are expanding chloromethylation capacity for soybean belt agrochemical distributors.
United States
Gulf Coast chlor-alkali integration supports MCA output for herbicide and adhesive applications, with EPA TSCA oversight shaping plant siting decisions in Texas and Louisiana. Houston Ship Channel logistics favor bulk tanker deliveries to glyphosate precursor manufacturers. Pasadena and Beaumont production sites are investing in real-time spectroscopic release testing to meet FDA process analytical technology guidance for pharmaceutical contract synthesis.
Global Monochloroacetic Acid Market Competitive Landscape
Capability concentration sits with integrated chlor-alkali operators controlling acetic acid feedstock costs; scale advantage sits with Asian producers leveraging regional chemical manufacturing cluster density. The vendor base splits between European pharmaceutical-grade specialists and Chinese agrochemical-feedstock suppliers. Three archetypes dominate: backward-integrated chemical conglomerates, dedicated chlorination technology licensors, and toll manufacturers serving spot industrial markets. Capacity expansion and multi-stage purification certification represent the dominant competitive moves as purity mandates tighten across jurisdictions.
Among European-based integrated producers, AkzoNobel and Nouryon occupy positions exemplifying chlor-alkali integration economics, while CABB Group anchors the dedicated MCA capacity archetype serving contract synthesis markets. These three names represent the strategic tiering visible in competitive filings: continental European operators with captive feedstock supply, technology-focused chlorination specialists, and regionally concentrated Asian volume producers.
| Leading Market Players |
|---|
| AkzoNobel |
| CABB Group |
| Niacet Corporation |
| PCC Group |
| Shandong Minji Chemical |
| Denak Co. Ltd. |
| Nouryon |
| Daicel Corporation |
| Meridian Chem-Bond |
| Others |
Supply & Pricing Matrix
Single-source dependency on Jiangsu-Zhejiang chlor-alkali corridors determines both the three-tier pricing structure across pharmaceutical, cosmetic, and technical grades and the geographic concentration of bulk tanker logistics. REACH-mandated purity thresholds in Europe and EPA emission controls in the United States widen price spreads between certified and uncertified supply channels.
Pricing Analysis
Contract-based long-term offtake agreements dominate pharmaceutical-grade procurement, while spot purchasing persists for technical-grade agrochemical feedstocks. Price differentiation hinges on certification tier under FDA process analytical technology guidance and volume scale commitments from Brazilian glyphosate formulators. Cost compression in technical-grade segments is intensifying because acetic acid feedstock volatility squeezes non-integrated toll manufacturers. Regional textile processors in China and India exhibit the highest price sensitivity, whereas European CDMOs under ICH Q7 guidelines absorb premium pricing for documented batch traceability.
Supply Chain Analysis
Tariff exposure between China and India is reshaping pharmaceutical-grade procurement patterns as CDSCO-aligned API manufacturers seek domestic purification investments. Supply concentration rests on China, India, and Germany as the dominant production nodes, with feedstock dependencies spanning acetic acid, chlorine, and catalytic chlorination reagents. Single-source vulnerability concentrates in the Nantong-Taizhou chemical park corridor, where environmental enforcement actions can disrupt global glyphosate precursor flows. Distribution runs through chemical management service contracts anchored at São Paulo and Buenos Aires procurement hubs for agrochemical buyers, while European pharmaceutical CDMOs favor direct IBC deliveries with integrated sampling ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where multi-jurisdiction registration timelines create switching costs that protect qualified suppliers from commoditization pressures.
For Market Incumbents: Build certification moats by accelerating REACH Annex XVII compliance investments and securing ICH Q7-aligned supply chain qualifications at Indian API manufacturing clusters. Capacity addition in Dahej and Mundra port corridors captures PLI scheme tailwinds while glyoxylic acid substitution threats in cosmetic applications demand proactive customer lock-in through technical service bundling.
For New Entrants and Emerging Players: Build out purification capabilities serving CDSCO-inspected pharmaceutical contract manufacturers in Ankleshwar and Tarapur chemical estates, where demand for sub-50 ppm dichloroacetic acid grades outstrips qualified supply. Cosmetic-grade specifications for biodegradable surfactant intermediates represent the most penetrable white-space target, with European personal care formulators seeking alternatives to REACH-constrained import sources.
For Investors and Strategic Acquirers: EU CBAM implementation reshapes the acquisition landscape by favoring European producers with verified low-carbon chlorination processes against carbon-intensive import competition. Five-to-ten-year viability centers on integrated chlor-alkali operators with captive acetic acid supply and multi-stage purification trains. The signal to watch is CDSCO expansion of ICH Q7 inspection capacity, which would accelerate pharmaceutical-grade certification timelines and compress returns for late entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetic Acid Feedstock | Captive methanol-carbonylation supply insulates margin structures from commodity volatility. |
| Multi-Stage Purification Certification Investment | REACH Annex XVII compliance unlocks European pharmaceutical CDMO premium pricing tiers. |
| Continuous Chlorination Technology Deployment | Advanced loop reactors with real-time HCl separation reduce acetic acid losses below 3%. |
| Chemical Management Service Contract Expansion | Integrated logistics capabilities capture volume from fragmented regional trader networks. |
| India PLI Scheme Alignment | API manufacturing incentives attract MCA purification investments to Dahej and Mundra corridors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, ECHA REACH registration filings, CDSCO import documentation records, and SEC 10-K disclosures from chlor-alkali operators. Plant managers at Jiangsu and Zhejiang production facilities, procurement leads at Brazilian glyphosate formulators, distribution channel partners in European chemical parks, and technical R&D directors at pharmaceutical CDMOs provided operational validation. Bottom-up capacity utilization estimates triangulate against top-down consumption models derived from downstream derivative output analysis.
Forecast inputs span grade tier stratification, end-use industry demand pools, packaging format preferences, and regional production hub economics across the analysis window. CAGRs emerge from segment-level volume trajectories weighted by purity-premium realization rates and regulatory compliance cost pass-through elasticity. Chlor-alkali integration economics and continuous chlorination technology adoption curves inform pharmaceutical-grade supply expansion assumptions.
Sensitivities concentrate around MEE enforcement intensity in Chinese chemical parks, EU CBAM carbon intensity verification protocols, and glyoxylic acid substitution rates in thioglycolic acid synthesis. Forecasts reflect documented assumptions regarding regulatory timeline adherence and feedstock cost pass-through mechanics. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Europe Fluorosilicic Acid Market
Chemicals
Carbon Tetrabromide Market
Chemicals
Gas Sweetening Chemicals Market
Chemicals
Global Aldehyde Market
Chemicals
Saudi Arabia Construction Chemicals Market
Chemicals
Cetostearyl Alcohol Market
Chemicals
5 Dinitroaniline Market
Chemicals
Calcium Methoxide Market
Chemicals
Chlorosilane Market
Chemicals
Scouring Agents Market
Chemicals
Caustic Soda Market
Chemicals
Schneider's Insect Medium Market
Chemicals
Asia-Pacific Methanol Market
Chemicals
Fluorochemicals Market
Chemicals
Iscotrizinol Market
Chemicals
Hydrogen Chloride Market