
 Ovulation Testing Kits Market | 2026-2036
Ovulation Testing Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Ovulation Testing Kits Market Analytics
Buyer concentration among fertility clinics is expanding as these end users consolidate purchasing power and demand professional-grade accuracy. SPD Swiss Precision Diagnostics leverages its European manufacturing base to sustain supply reliability across regulated markets. Church & Dwight Co., Inc. anchors mass-market distribution through pharmacy and retail channels in North America. Wondfo Biotech competes on manufacturing scale, offering cost-efficient strip production that serves both branded and private-label customers.
Ovulation testing kits are in vitro diagnostic devices that detect luteinizing hormone surges in urine or saliva, typically achieving sensitivity thresholds of 20-40 mIU/mL to predict fertile windows. These products serve both consumer fertility awareness and clinical reproductive health monitoring applications. Digital kits occupy the premium tier, where higher margins reflect integrated algorithmic cycle tracking and Bluetooth connectivity. Urine test strips dominate volume across budget and mid-range pricing tiers, while fertility clinics drive specialized demand for professional-grade LH testers with documented precision protocols.
FDA clearance under 21 CFR Part 820 quality system regulations and CE marking under the EU In Vitro Diagnostic Medical Devices Regulation shape product development timelines and market access pathways for manufacturers. The country's national pharmaceutical regulator in India, CDSCO, imposes additional import and registration requirements that filter which brands reach direct consumers. Stakeholders must monitor evolving harmonization between ISO 13485 quality management standards and national registration frameworks to anticipate compliance costs and competitive positioning shifts.
Market Dynamics
Fertility clinics are consolidating procurement power while direct-to-consumer channels fragment, creating dual demand poles that reshape manufacturer strategy and distribution investment priorities.
Growth Catalysts
- Assisted reproductive technology expansion:Fertility clinics in the United States are scaling professional-grade LH testing capacity to match rising IVF and IUI procedure volumes.
- 21 CFR Part 820 compliance pathways:FDA quality system regulations for in vitro diagnostic devices create trusted market entry frameworks that accelerate commercialization timelines for validated manufacturers.
- Salivary ferning microscopy:Non-urine detection methods are gaining traction among cycle-tracking apps seeking hardware integration partnerships.
Market Restraints
- Monoclonal antibody cost volatility:LH test strip production depends on antibody reagent supply concentrated among a limited set of biologics suppliers.
- EU MDR transition friction:The In Vitro Diagnostic Medical Devices Regulation imposes extended conformity assessment timelines that delay product launches.
- Basal body temperature apps:Zero-cost fertility awareness substitutes capture price-sensitive consumers outside clinical channels.
Strategic Opportunities
- India CDSCO registration pathways:Formalized import frameworks for IVD devices enable branded entry into a direct-to-consumer market currently dominated by unregulated imports.
- Bluetooth-enabled cycle synchronization:Wearable fertility trackers and connected test readers are converging into integrated reproductive health platforms.
- Pharmacy telehealth integration:Retail chains are embedding ovulation testing into virtual fertility consultation workflows.
Industry Challenges
- ISO 13485 auditor capacity constraints:Quality management certification backlogs extend product development timelines for mid-tier manufacturers.
- LH surge detection algorithm validation:Digital kit developers face reproducibility challenges across diverse urine concentration and hydration states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ovulation Testing Kits Market |
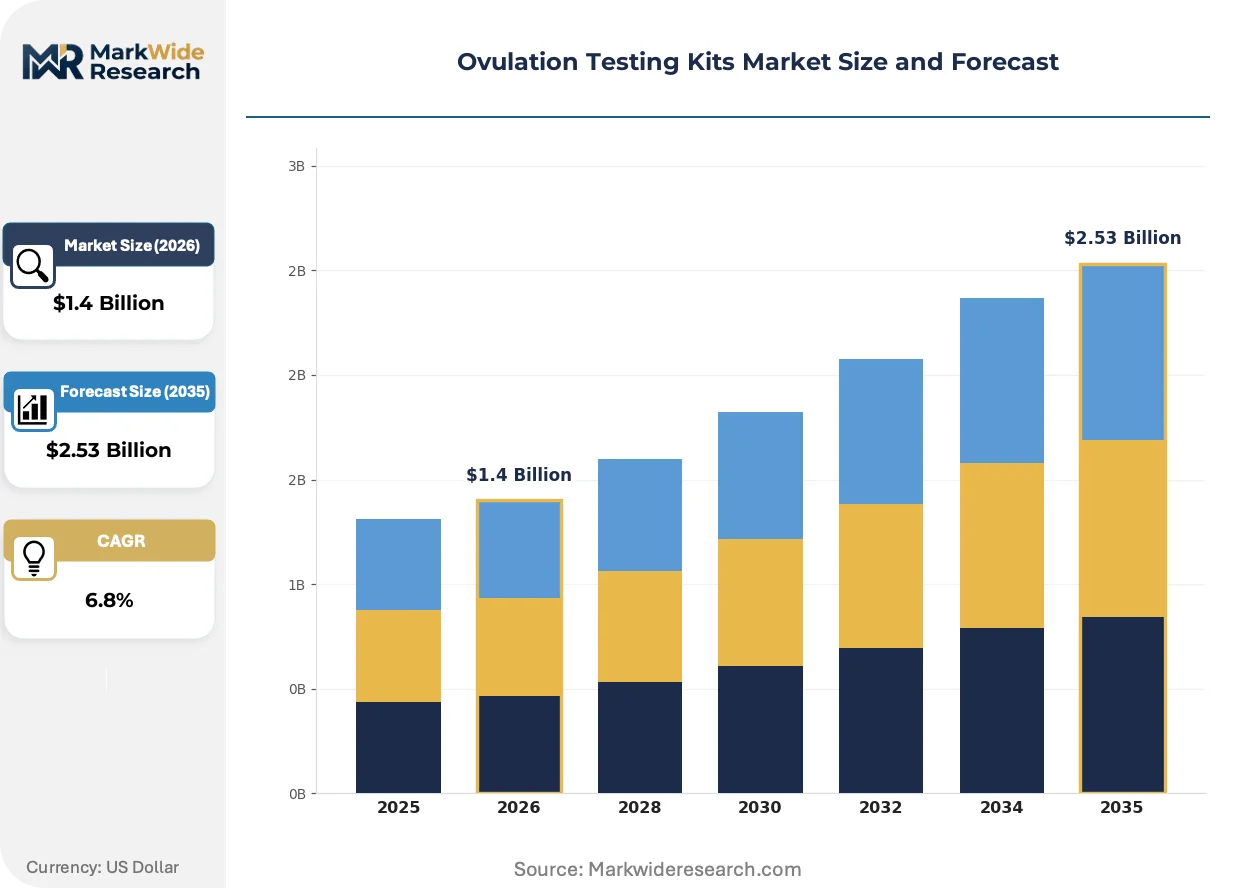
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Kits, Luteinizing Hormone Testers, Urine Test Strips, Saliva Test Kits Distribution Channel: Online Retailers, Pharmacies, Supermarkets, Health Stores End User: Individuals, Couples, Healthcare Professionals, Fertility Clinics Pricing Tier: Budget, Mid-Range, Premium, Professional |
| Companies Covered | SPD Swiss Precision Diagnostics, Church & Dwight Co., Inc., Prestige Brands Holdings, Fairhaven Health, Wondfo Biotech, Piramal Healthcare, Proov, HiLin Life Products, Inc., Geratherm Medical AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ovulation Testing Kits Market Evolving Landscape
Algorithmic cycle prediction and connected hardware are transforming ovulation testing from discrete diagnostic events into continuous fertility monitoring systems that reshape user engagement and clinical data flows.
Multiplex hormone detection technology is expanding into ovulation testing platforms. These systems simultaneously quantify LH, estrone-3-glucuronide, and progesterone metabolites to refine fertile window predictions. Fertility clinics in Germany and the United States are piloting these instruments for personalized IVF stimulation protocols. The technology is expanding into premium consumer segments by enabling single-test comprehensive cycle profiling that compresses multiple diagnostic steps into one device interaction.
CE marking under EU MDR Annex VIII classification rules is tightening clinical evidence requirements for self-testing IVD devices. Manufacturers must now submit performance evaluation reports with expanded metrological traceability documentation. Strip-based products face extended notified body review timelines. Companies are responding by pre-submission engagement with BSI Group and TÜV SÜD to align technical documentation with evolving interpretation guidance.
Subscription-based replenishment models are displacing single-unit pharmacy purchases for digital ovulation test users. Direct-to-consumer platforms bundle hardware with recurring strip shipments and app-based cycle coaching. This shift concentrates customer lifetime value among brands with integrated logistics and software capabilities. The United Kingdom and United States show the highest penetration of these models, where fertility awareness programming through employer benefits drives sustained engagement.
Ovulation Testing Kits Market Segmentation
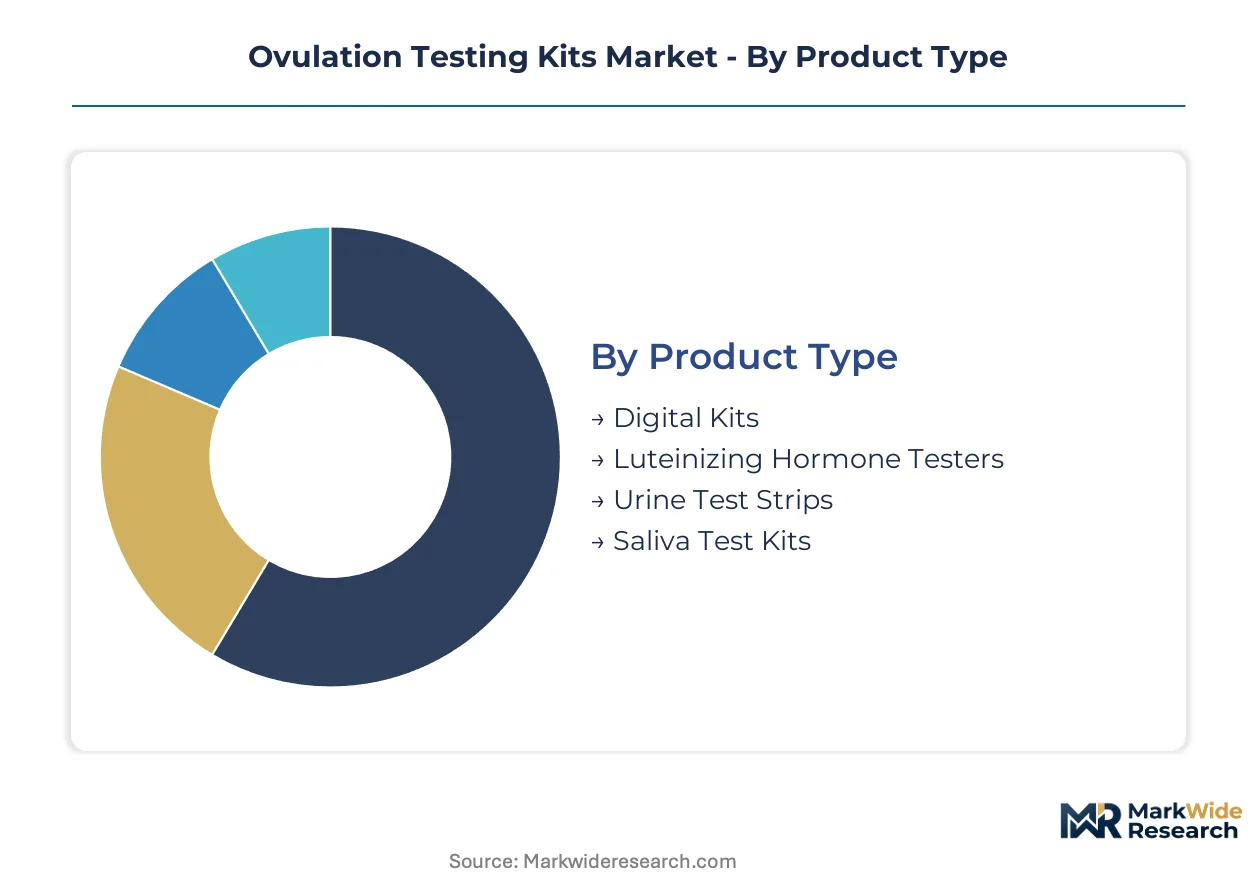
Product differentiation in ovulation testing kits spans precision thresholds, connectivity features, and clinical validation tiers. Manufacturers must align technical specifications with distinct procurement channels and end-user sophistication levels to capture value across fragmented demand.
Product Type:
Detection methodology and algorithmic sophistication define competitive positioning across hardware formats.
- Digital Kits:Integrated optical readers process urine samples through algorithmic analysis, transmitting results via Bluetooth to cycle-tracking applications. Demand concentrates among subscription-based direct-to-consumer platforms in the United States and United Kingdom, where fertility awareness benefits drive sustained engagement.
- Luteinizing Hormone Testers:Handheld electronic devices quantify LH concentration through electrochemical or optical methods, achieving documented precision protocols required by fertility clinics. These units command professional-grade pricing and anchor procurement decisions at assisted reproductive technology centers scaling IVF and IUI capacity.
- Urine Test Strips:Lateral flow immunoassay strips detect LH surges through antibody-antigen binding, manufactured at scale for branded and private-label distribution.
- Saliva Test Kits:Microscopy-based ferning pattern detection offers non-invasive cycle monitoring, attracting hardware integration partnerships from fertility tracking applications.
Mature deployment sits with urine test strips. Newer deployment is concentrated in digital kits.
Distribution Channel:
Channel selection determines margin structure and customer acquisition economics across consumer and clinical pathways.
- Online Retailers:Direct-to-consumer platforms enable subscription replenishment models that bundle hardware with recurring consumable shipments. These channels capture highest customer lifetime value where integrated logistics and software capabilities exist.
- Pharmacies:Brick-and-mortar retail chains in North America embed ovulation testing into virtual fertility consultation workflows, bridging diagnostic purchase with telehealth guidance.
- Supermarkets:Mass-market placement drives impulse purchases among price-sensitive consumers seeking immediate accessibility without clinical consultation.
- Health Stores:Specialty wellness retailers target fertility-conscious demographics with curated product selections and educational support.
Volume leadership sits with pharmacies. Subscription revenue expansion concentrates in online retailers.
End User:
User sophistication and clinical integration requirements segment demand across self-directed and professionally supervised applications.
- Individuals:Single users tracking personal fertility cycles through consumer-grade devices, representing high-volume baseline demand across all distribution channels.
- Couples:Partners coordinating conception timing through shared cycle data and dual-input tracking features, driving demand for connected platform compatibility.
- Healthcare Professionals:General practitioners and obstetricians incorporating ovulation testing into preliminary fertility assessments before specialist referral.
- Fertility Clinics:Specialized reproductive health centers requiring professional-grade LH testers with ISO 13485 quality documentation and FDA 21 CFR Part 820 compliance for assisted reproductive technology protocols.
Procurement consolidation sits with fertility clinics. Volume expansion concentrates in individuals.
Pricing Tier:
Cost stratification reflects certification grade, manufacturing scale, and performance validation depth.
- Premium:Digital kits with Bluetooth connectivity and algorithmic cycle prediction command highest margins, targeting subscription-model consumers in employer-sponsored fertility benefit programs.
- Professional:Clinical-grade instruments with documented precision protocols and regulatory compliance certifications serve fertility clinic procurement at price points reflecting quality system investments.
- Mid-Range:Electronic LH testers without connectivity features balance accuracy and accessibility for pharmacy retail channels.
- Budget:Strip-based products manufactured at scale compete on unit economics for private-label and emerging market distribution.
Margin concentration sits with premium tiers. Volume concentration sits with budget tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for ovulation testing kits concentrates in the United States, where fertility awareness programming and direct-to-consumer health channels sustain the highest per-capita procurement rates worldwide.
United States
Employer-sponsored fertility benefits and pharmacy telehealth integration drive sustained uptake of digital ovulation kits with subscription replenishment models. FDA 21 CFR Part 820 quality system regulations create trusted pathways for IVD device commercialization. Boston and San Francisco anchor reproductive health technology clusters where fertility tracking apps partner with hardware manufacturers for Bluetooth-enabled cycle synchronization.
Germany
Fertility clinics in Bavaria and Baden-Württemberg pilot multiplex hormone detection systems for personalized IVF stimulation protocols. CE marking under EU MDR Annex VIII classification rules tightens clinical evidence requirements for self-testing IVD devices. The Rhine-Main metropolitan region concentrates notified body pre-submission engagement with BSI Group and TÜV SÜD for technical documentation alignment.
United Kingdom
Subscription-based direct-to-consumer platforms show the highest penetration of bundled hardware and recurring consumable shipments among European markets. MHRA post-Brexit regulatory frameworks maintain alignment with EU MDR standards while enabling independent market authorization pathways. London anchors integrated reproductive health platform development where wearable fertility trackers converge with connected test readers.
India
Unregulated import channels currently dominate consumer access, though formalized CDSCO registration pathways for IVD devices are enabling branded entry into direct-to-consumer markets. The country's national pharmaceutical regulator imposes import and registration requirements that filter market participants. Mumbai and Delhi-NCR concentrate distribution infrastructure for both clinical-grade LH testers and cost-efficient strip production serving private-label customers.
China
Manufacturing scale advantages position domestic producers to serve both branded and private-label demand across Asia-Pacific distribution networks. NMPA medical device registration requirements shape product development timelines for in vitro diagnostic devices targeting clinical channels. The Yangtze River Delta concentrates lateral flow immunoassay strip production at volume tiers competing across budget and mid-range pricing segments.
Ovulation Testing Kits Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue algorithmic cycle prediction and connected hardware integration. The market structures around three tiers: multinational diagnostics groups with European manufacturing bases, North American mass-market distributors anchoring pharmacy and retail channels, and Asian-scale manufacturers competing on strip production economics. Three strategic archetypes dominate: regulatory compliance specialists, subscription platform operators, and cost-optimized contract manufacturers. Competitive moves concentrate on notified body pre-submission engagement for EU MDR transition and Bluetooth-enabled fertility tracker partnerships.
Among European-based precision diagnostics specialists, SPD Swiss Precision Diagnostics exemplifies supply reliability strategies across regulated markets. Church & Dwight Co., Inc. anchors mass-market distribution archetypes through pharmacy and retail channel dominance in North America. Wondfo Biotech occupies the scale-driven manufacturing tier, serving both branded and private-label demand through cost-efficient production volumes. These three company structures illustrate the geographic and strategic segmentation defining competitive positioning.
| Leading Market Players |
|---|
| SPD Swiss Precision Diagnostics |
| Church & Dwight Co., Inc. |
| Prestige Brands Holdings |
| Fairhaven Health |
| Wondfo Biotech |
| Piramal Healthcare |
| Proov |
| HiLin Life Products, Inc. |
| Geratherm Medical AG |
| Others |
Value Network & Pricing Analysis
Specialized monoclonal antibody production expertise concentrated in Switzerland and Germany feeds directly into pricing-tier spreads across the ovulation testing kits market, where labor-cost differentials between European precision manufacturing and Asian-scale strip production sustain a three-to-one margin gap between professional-grade and budget-tier products.
Pricing Analysis
Volume concentrates in budget-tier urine test strips while margins pool in premium digital kits with Bluetooth connectivity and algorithmic cycle prediction. Price differentiation rests on FDA 21 CFR Part 820 certification grade and manufacturing scale, with professional-grade LH testers commanding premiums for ISO 13485 documentation. Cost compression in the strip segment is intensifying because Wondfo Biotech and Chinese manufacturers are expanding lateral flow immunoassay capacity. Individual consumers tracking fertility cycles show highest price sensitivity, while fertility clinics purchasing for IVF protocols demonstrate lowest sensitivity to unit cost.
Supply Chain Analysis
Workforce availability for precision diagnostics manufacturing concentrates in Switzerland, Germany, and the Yangtze River Delta, where technical talent pools for electrochemical sensor production and optical reader assembly remain shallower than standard electronics manufacturing. Raw material dependencies center on monoclonal antibody reagents, nitrocellulose membranes, and Bluetooth module chipsets sourced from biologics suppliers and semiconductor foundries. Single-source vulnerability in antibody reagent supply creates concentrated risk for strip-based product lines. Distribution runs through pharmacy retail chains in North America, direct-to-consumer subscription platforms in the United Kingdom and United States, and fertility clinic procurement networks across Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ovulation testing kits market is becoming a vertical-integration race as manufacturers pursue captive control over monoclonal antibody reagent supply to defend margin structures against biologics cost volatility.
For Market Incumbents: Deploy notified body pre-submission engagement as the primary lever to compress EU MDR conformity assessment timelines and accelerate product launches ahead of competitors facing extended review backlogs. Incumbents should anchor backward integration into antibody reagent production to reduce dependence on concentrated biologics suppliers, while simultaneously reinforcing channel control through exclusive pharmacy telehealth partnerships that embed testing hardware into virtual fertility consultation workflows. For New Entrants and Emerging Players: Fertility tracking application developers represent the most penetrable channel partner type for hardware integration partnerships, particularly those seeking Bluetooth-enabled cycle synchronization features. New entrants should target India's formalizing CDSCO registration pathways as the whitespace geography, where branded entry remains underdeveloped against unregulated import channels. A direct-to-consumer subscription model bundling hardware with recurring strip shipments offers the clearest go-to-market angle for capturing customer lifetime value. For Investors and Strategic Acquirers: Re-rating potential sits with algorithmic cycle prediction specialists given convergence between wearable fertility trackers and connected test readers into integrated reproductive health platforms. Long-term viability over a five-to-ten year window favors acquisition targets with demonstrated FDA 510(k) clearance pathways and established notified body relationships for EU MDR compliance. The signal to watch as an inflection indicator is employer-sponsored fertility benefit program expansion, which drives sustained subscription-model penetration and concentrates procurement decisions among benefits administrators.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Annex VIII compliance accelerates market access across German and UK fertility clinic procurement networks. |
| Bluetooth Hardware Integration | Partnerships with fertility tracking apps in Boston and San Francisco clusters enable cycle synchronization platform convergence. |
| Antibody Reagent Backward Integration | Captive biologics supply reduces cost volatility exposure for LH test strip production at scale. |
| Pharmacy Telehealth Partnership | Retail chain embedding of ovulation testing into virtual consultation workflows bridges diagnostic purchase with clinical guidance. |
| CDSCO Registration Investment | Formalized import frameworks enable branded entry into India's direct-to-consumer market currently dominated by unregulated channels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with fertility clinic procurement managers, IVD regulatory affairs leads, biomedical engineers at assisted reproductive technology centers, and pharmacy category buyers. FDA 510(k) databases, EU MDR notified body guidance documents, CDSCO import registration records, and hospital GPO contract databases provided validation layers. Bottom-up modeling of strip production volumes and top-down triangulation against fertility procedure statistics ensured cross-verification.
Granularity-level modeling operated at the product-type, distribution-channel, and end-user intersection, with separate projections for digital kits, LH testers, urine strips, and saliva kits across online, pharmacy, supermarket, and health store channels. CAGRs were derived from trend extrapolation of IVF procedure volumes, fertility awareness benefit penetration, and regulatory transition timelines. Inputs included monoclonal antibody supply constraints, EU MDR implementation friction, and Bluetooth-enabled hardware adoption curves.
Several conditions sit outside the modeled scope, including unforeseen regulatory harmonization shifts, abrupt monoclonal antibody supply disruptions, and fertility tracking app platform consolidation. Forecasts reflect assumptions about sustained employer benefit expansion and stable notified body capacity. A small set of named triggers warrants ongoing watch: EU MDR auditor backlog resolution, India CDSCO enforcement intensity, and salivary ferning microscopy validation for clinical use.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Germany Testing, Inspection and Certification Market
Testing Services
United States Hospital Acquired Disease Testing Market
Testing Services
Dengue Testing Market
Testing Services
Point of Care Testing Market
Testing Services
Global Legionella Testing Market
Testing Services
Vaginal Panel Testing Market
Testing Services
Global Coagulation Testing Market
Testing Services
Mono Rapid Testing Market
Testing Services
Warfarin Sensitivity Testing Market
Testing Services
Global Newborn Screening Market
Testing Services
Global Endotoxin and Pyrogen Testing Market
Testing Services
Asia-Pacific Antimicrobial Susceptibility Testing Market
Testing Services
Thrombophilia Testing Market
Testing Services
Platelet Function Test Market
Testing Services
Europe IVD Regulatory Affairs Outsourcing Market
Testing Services
Pyrogen Testing Market