
 Dengue Testing Market | 2026-2036
Dengue Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Dengue Testing Market Intelligence
Modular assay bundling is shifting how procurement teams evaluate dengue testing portfolios, with buyers favoring combined NS1-IgM-IgG panels over standalone kits. Abbott Laboratories leverages its immunoassay manufacturing scale to anchor hospital laboratory contracts across Latin America. Thermo Fisher Scientific Inc. competes through PCR-based platform specialization that extends into multiplex tropical disease workflows. DiaSorin S.p.A. differentiates via chemiluminescence technology leadership in high-throughput serology segments.
Dengue testing encompasses diagnostic methodologies that detect viral RNA, NS1 antigen, or host antibodies (IgM/IgG) in human blood matrices, with seroconversion timelines and viral load thresholds determining optimal test selection during febrile phases. The primary purpose is to differentiate dengue from chikungunya, Zika, and other flavivirus infections with overlapping clinical presentations. Molecular tests capture the fastest-growing segment as reference laboratories adopt quantitative RT-PCR for viremia monitoring and serotyping, while rapid diagnostic tests dominate volume through community health programs and emergency department triage. ELISA platforms retain margin concentration in blood bank screening and research institute seroprevalence studies where batch processing efficiency offsets longer turnaround times.
WHO prequalification and the EU In Vitro Diagnostic Regulation (IVDR) are reshaping product standards, with CE-marked devices requiring enhanced clinical evidence for NS1 sensitivity claims. FDA clearance pathways for multiplex tropical disease panels influence R&D prioritization among US-focused manufacturers. Brazil's ANVISA and India's CDSCO enforce import licensing and local testing requirements that condition market access for international kit suppliers. Stakeholders must monitor evolving serotype circulation patterns and regulatory harmonization initiatives to align assay development with shifting epidemiological and compliance demands.
Market Dynamics
WHO prequalification tightening for NS1 antigen and IgM/IgG serology kits is compressing manufacturer margins while accelerating consolidation among IVD suppliers serving tropical hospital networks.
Growth Catalysts
- ANVISA import licensing:Brazil's enforcement of local testing requirements for international kit suppliers is conditioning market access and favoring manufacturers with established Brazilian distribution infrastructure.
- Point-of-care expansion:Hospitals across tropical zones are deploying rapid diagnostic tests in emergency department triage workflows, displacing centralized laboratory routing for febrile patient screening.
- Multiplex tropical disease panels:Reference laboratories are adopting quantitative RT-PCR platforms that capture dengue alongside chikungunya and Zika in single workflows.
Market Restraints
- CE-IVDR clinical evidence requirements:Enhanced sensitivity documentation for NS1 antigen claims is extending product registration timelines and inflating regulatory compliance costs for European market entry.
- Serotype circulation volatility:Unpredictable shifts between DENV-1 through DENV-4 dominance across Southeast Asian outbreak zones complicates assay validation and inventory planning for kit manufacturers.
- Laboratory capacity strain:Seasonal outbreak peaks in India and Indonesia overwhelm existing molecular testing infrastructure, creating diagnostic backlogs that degrade public health response velocity.
Strategic Opportunities
- CDSCO streamlined pathways:India's central drug regulator is piloting accelerated review tracks for WHO-prequalified dengue diagnostics, opening faster market access for compliant manufacturers.
- Community health worker deployment:Rapid diagnostic test distribution through village-level health programs in the Philippines and Vietnam represents underpenetrated volume channels outside hospital networks.
- Chemiluminescence platform convergence:Automated high-throughput serology systems are integrating dengue IgM/IgG detection into broader tropical disease screening menus at regional reference laboratories.
Industry Challenges
- Cross-reactivity validation:Differentiating dengue from Zika and yellow fever antibodies demands extensive flavivirus panel testing that extends R&D timelines and inflates clinical study costs.
- Cold chain integrity:RT-PCR reagent stability requirements complicate distribution to remote Indonesian archipelago clinics and Brazilian Amazon health posts lacking reliable refrigeration infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dengue Testing Market |
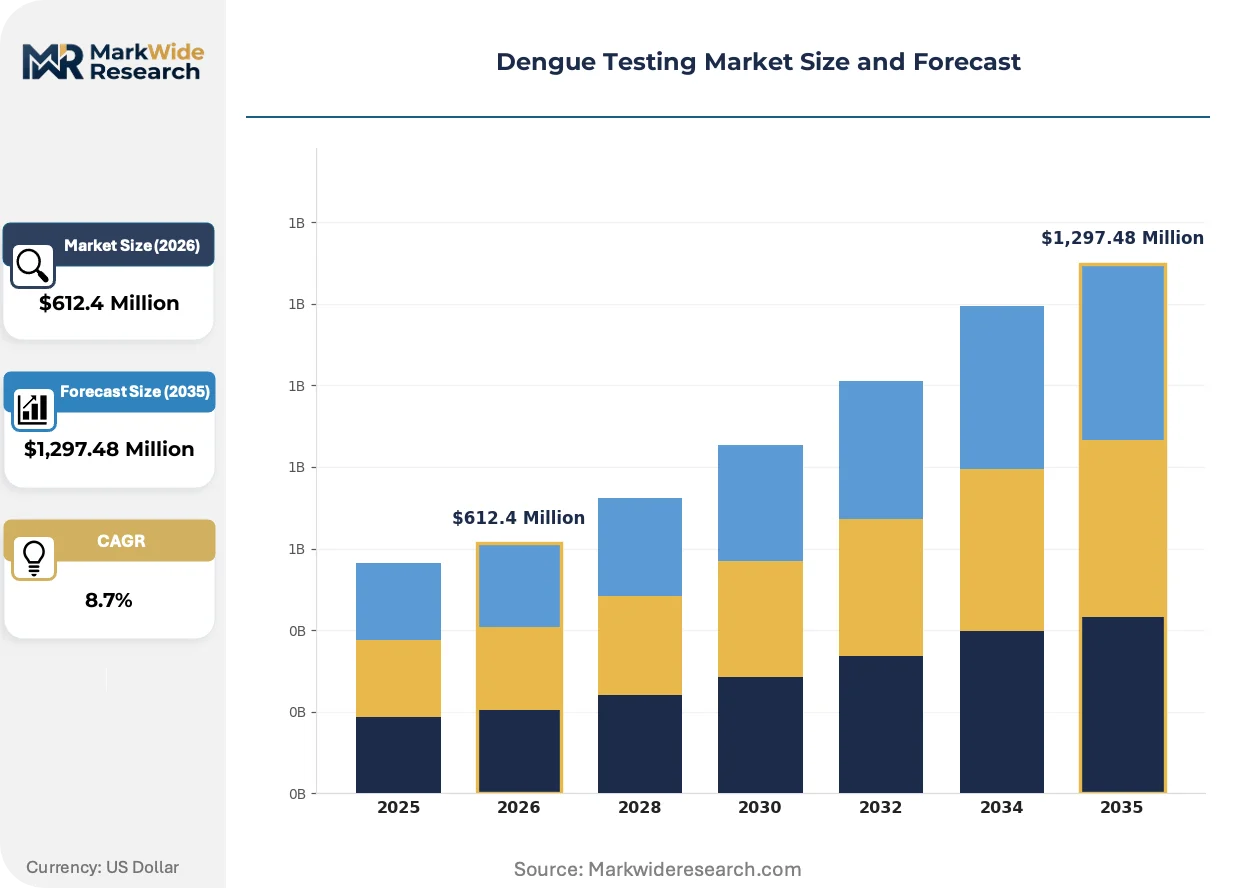
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,297.48 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Serology Tests, Molecular Tests, Antigen Detection, Immunochromatographic Assays, ELISA Sample Type: Blood, Serum, Plasma, Whole Blood, Urine End User: Diagnostic Laboratories, Research Institutes, Blood Banks, Clinical Laboratories, Hospitals Technological Platform: Rapid Diagnostic Tests, PCR-based, Immunoassays, Microfluidics, Biosensors |
| Companies Covered | Thermo Fisher Scientific Inc., Abbott Laboratories, F. Hoffmann-La Roche Ltd, InBios International, Inc., NovaTec Immundiagnostica GmbH, Abnova Corporation, PerkinElmer Inc., CERTEST BIOTEC, DiaSorin S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dengue Testing Market Strategic Shifts & Innovations
Molecular and immunoassay platforms are converging around automated, multiplexed workflows that compress turnaround times while expanding the diagnostic window across febrile phases.
Loop-mediated isothermal amplification (LAMP) is integrating point-of-care molecular detection into battery-operated devices that function without thermal cyclers. District hospitals in Thailand and Malaysia are piloting these platforms for same-day serotyping. The technology is integrating viremia monitoring capabilities previously restricted to centralized reference laboratories into peripheral health facility workflows.
The EU In Vitro Diagnostic Regulation (IVDR) is mandating enhanced performance documentation for Class C infectious disease assays. Manufacturers must now submit extended clinical sensitivity studies for NS1 antigen claims across multiple serotypes. High-throughput serology segments face the steepest compliance burden as legacy ELISA products require substantial dossier rebuilding for CE mark renewal.
Blood bank screening programs are unbundling dengue seroprevalence surveillance from routine transfusion safety testing. National blood services in Brazil and Colombia are contracting dedicated serology batch processing to specialized reference institutes rather than hospital laboratories. This operational pivot concentrates volume with high-throughput chemiluminescence operators while marginalizing smaller ELISA platform holders.
Dengue Testing Market Segmentation
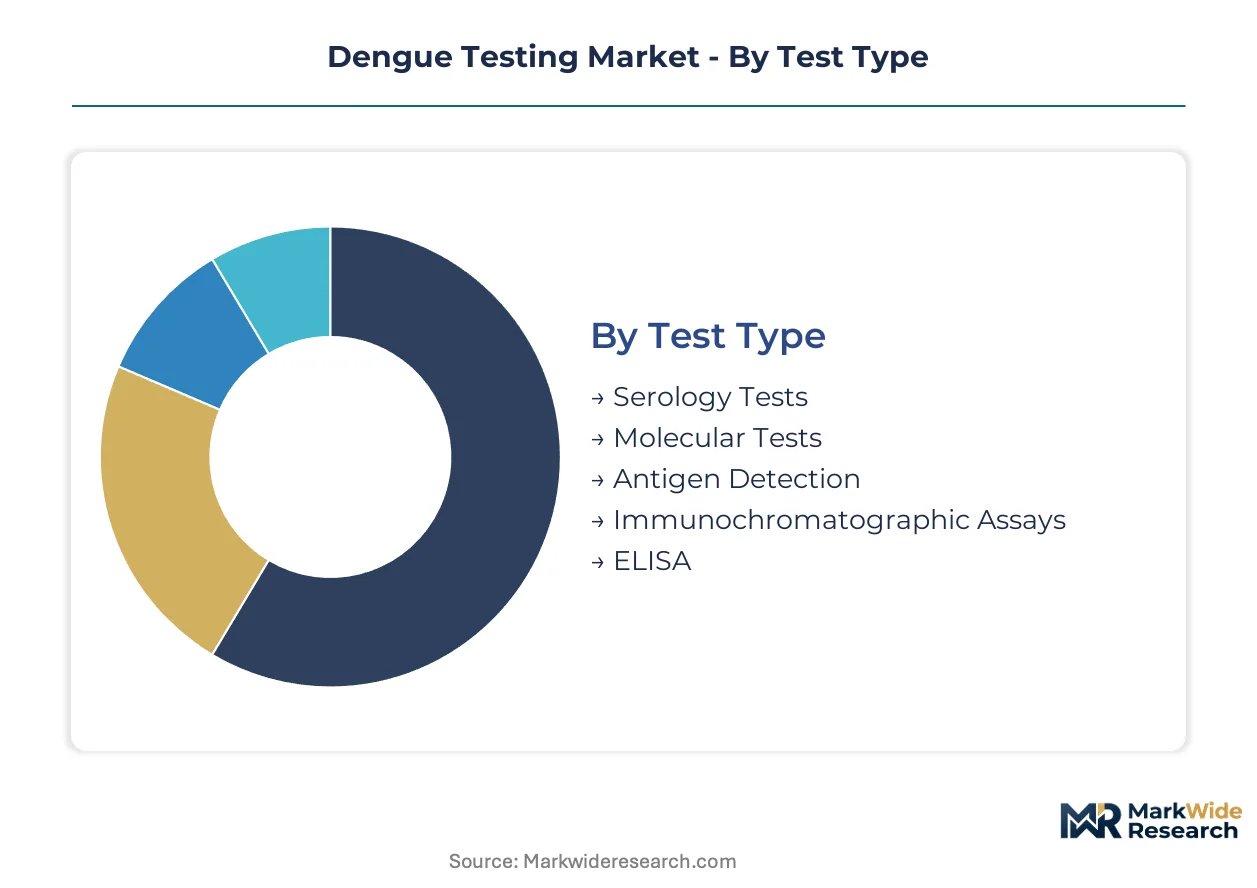
Dengue testing portfolios fragment across technical methodologies, biological matrices, and care settings. Procurement teams evaluate these dimensions simultaneously when configuring laboratory workflows or point-of-care deployments.
Test Type:
Volume concentrates in rapid antigen and antibody screening, while premium revenue accrues to molecular platforms with serotyping capabilities.
- Serology Tests:IgM/IgG antibody detection platforms dominate blood bank screening and seroprevalence surveillance. Brazilian national blood services and Indian reference laboratories batch-process these assays for transfusion safety protocols.
- Molecular Tests:Quantitative RT-PCR captures viral RNA with serotype discrimination for clinical research and viremia monitoring. Thai district hospitals and Malaysian reference centers deploy these for outbreak investigation where differentiation between DENV-1 through DENV-4 alters patient management.
- Antigen Detection:NS1 protein assays enable early acute-phase diagnosis before antibody seroconversion.
- Immunochromatographic Assays:Lateral flow devices power community health worker programs across Philippine villages and Vietnamese rural clinics.
- ELISA:Enzyme-linked platforms retain institutional contracts for high-throughput batch processing in research settings.
Mature deployment sits with Serology Tests. Newer deployment is concentrated in Molecular Tests.
Sample Type:
Processing economics and cold chain requirements shape which biological matrices dominate specific care tiers.
- Blood:Venous whole blood serves centralized laboratory workflows with centrifugation capacity.
- Serum:Separated serum specimens yield optimal antibody titers for quantitative serology in Colombian and Indonesian reference institutes.
- Plasma:Anticoagulated plasma supports molecular extraction protocols with reduced hemolysis interference.
- Whole Blood:Fingerstick capillary samples enable rapid diagnostic test deployment at Brazilian Amazon health posts lacking phlebotomy infrastructure.
- Urine:Non-invasive collection is gaining validation for NS1 antigen detection in pediatric and geriatric populations where venipuncture compliance is problematic.
Centralized infrastructure favors Serum. Decentralized expansion targets Whole Blood.
End User:
Customer type determines purchasing authority, with hospitals controlling emergency department budgets and ministries managing public health screening contracts.
- Diagnostic Laboratories:Private laboratory networks in São Paulo and Mumbai process high volumes for outpatient febrile screening with turnaround-time guarantees.
- Research Institutes:Academic centers in Bangkok and Singapore drive assay validation studies for WHO prequalification submissions.
- Blood Banks:National transfusion services mandate dengue serology for donor screening in Brazil and Colombia.
- Clinical Laboratories:Hospital-affiliated labs balance STAT testing for inpatients with batch efficiency for outpatient panels.
- Hospitals:Emergency departments across tropical Southeast Asia deploy rapid tests for triage decisions during seasonal outbreak surges.
Contract concentration sits with Diagnostic Laboratories. Volume expansion is concentrated in Hospitals.
Technological Platform:
Platform selection locks laboratories into reagent supply relationships and dictates capital equipment refresh cycles.
- Rapid Diagnostic Tests:Immunochromatographic strips and cassettes dominate Philippine village health worker programs and Vietnamese commune clinics.
- PCR-based:Thermal cycler and real-time detection systems anchor reference laboratory serotyping capacity in Thailand and Malaysia.
- Immunoassays:Chemiluminescence analyzers automate IgM/IgG quantification for high-throughput operators in Brazilian metropolitan hospitals.
- Microfluidics:Lab-on-chip architectures miniaturize sample preparation for near-patient molecular testing.
- Biosensors:Electrochemical and optical transducers enable label-free NS1 detection with smartphone readout integration.
Installed base sits with Immunoassays. Steepest expansion trajectory is concentrated in Rapid Diagnostic Tests.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Manaus Free Trade Zone concentrates reagent import and distribution infrastructure for Amazon basin health posts. Special economic zones across Southeast Asia accelerate kit manufacturing localization.
Brazil
Emergency department triage programs and national blood bank screening drive procurement volume. ANVISA enforces local testing requirements and import licensing that conditions market access for international suppliers. São Paulo metropolitan hospitals anchor high-throughput chemiluminescence serology processing for transfusion safety protocols.
India
Seasonal outbreak peaks strain laboratory capacity in Mumbai and Delhi diagnostic networks. CDSCO pilots accelerated review tracks for WHO-prequalified dengue diagnostics, opening faster regulatory pathways. Karnataka and Maharashtra host reference institutes conducting batch seroprevalence surveillance for blood safety.
Thailand
District hospitals pilot loop-mediated isothermal amplification platforms for same-day serotyping during outbreak investigations. The Ministry of Public Health coordinates national surveillance integrating point-of-care rapid testing into village health volunteer programs. Bangkok academic medical centers validate assays for regional WHO prequalification submissions.
Indonesia
Archipelago distribution challenges push procurement toward cold-chain-independent rapid diagnostic tests. The national pharmaceutical regulator enforces import licensing for molecular reagents with stability requirements complicating remote clinic supply. Java-based reference laboratories concentrate quantitative RT-PCR capacity for outbreak investigation.
Vietnam
Commune clinic networks expand immunochromatographic test deployment for febrile patient triage. Provincial health departments integrate dengue surveillance into broader arbovirus monitoring systems. Ho Chi Minh City diagnostic laboratories anchor PCR-based serotyping capacity for southern outbreak zones.
Dengue Testing Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the dengue testing landscape. The vendor base organizes into three tiers: multinational IVD conglomerates with tropical disease portfolios, regional diagnostics specialists with WHO prequalification track records, and emerging platform innovators commercializing novel detection chemistries. Consolidation pressures favor scaled manufacturers capable of absorbing IVDR compliance costs. Strategic moves concentrate on multiplex panel development and point-of-care miniaturization.
Within the multinational conglomerate tier, Thermo Fisher Scientific Inc. and Abbott Laboratories occupy anchor positions exemplifying divergent platform strategies. Thermo Fisher represents PCR-based specialization extending into multiplex tropical disease workflows. Abbott exemplifies immunoassay manufacturing scale leveraged for hospital laboratory contract capture. DiaSorin S.p.A. sits within the high-throughput serology specialist archetype, with chemiluminescence automation positioning for blood bank and reference laboratory consolidation trends.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| InBios International, Inc. |
| NovaTec Immundiagnostica GmbH |
| Abnova Corporation |
| PerkinElmer Inc. |
| CERTEST BIOTEC |
| DiaSorin S.p.A. |
| Others |
Cost & Logistics Intelligence
Brazilian national blood services and Indian state hospital procurement consortiums concentrate purchasing volume, anchoring contract-based long-term offtake pricing with volume-scaled discounts for NS1 antigen and serology panel suppliers. This buyer concentration forces manufacturers to absorb cold-chain logistics premiums into landed pricing or cede share to regional distributors with established tropical zone infrastructure.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to emergency stock replenishment during outbreak surges in Indonesian archipelago clinics and Brazilian Amazon health posts. Three-tier pricing structure across premium, standard, and economy levels segments by WHO prequalification status and serotype cross-reactivity validation depth. Pricing pressure stems from IVDR compliance cost pass-through requirements squeezing mid-tier ELISA manufacturers without chemiluminescence automation scale. Community health worker programs in Philippine villages exhibit highest price sensitivity, while reference laboratories in Bangkok and Singapore prioritize serotyping accuracy over unit economics.
Supply Chain Analysis
Freight costs for temperature-controlled molecular reagent shipments to remote Indonesian islands and Brazilian Amazon regions can exceed product value, driving procurement toward ambient-stable rapid diagnostic tests. Manufacturing concentrates in the United States, Germany, and South Korea for PCR thermal cyclers and chemiluminescence analyzers, while lateral flow device assembly clusters in China and Malaysia. Raw material dependencies include nitrocellulose membranes, fluorescent nanoparticles, and recombinant NS1 proteins. Single-source vulnerability sits with specialized serotype-specific monoclonal antibody suppliers. Distribution runs through ANVISA-licensed Brazilian distributors and CDSCO-registered Indian import agents with cold-chain verification capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from IVDR compliance cost inflation and WHO prequalification tightening will force sub-scale ELISA specialists and rapid test assemblers without automated manufacturing into distressed exits or acquisition targets.
For Market Incumbents: Cement hospital laboratory contract renewal rates by embedding multiplex tropical disease panels into existing immunoassay platform service agreements. Defend margin position through backward integration into recombinant antigen production, reducing dependency on external NS1 protein suppliers facing serotype drift validation delays. Prioritize chemiluminescence automation R&D to capture blood bank screening consolidation in São Paulo and Mumbai metropolitan networks. For New Entrants and Emerging Players: Village health worker networks in Vietnam and Philippine commune clinics represent the most penetrable channel, with immunochromatographic test volumes expanding faster than hospital procurement. Target WHO prequalification fast-track alignment with CDSCO's accelerated review pilot for first-mover advantage in Indian state tender programs. Partner with regional distributors holding ANVISA import licenses rather than building direct Brazilian regulatory infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale rapid diagnostic test manufacturers with established Southeast Asian distribution and pending IVDR technical documentation completion in India and Brazil. Long-term viability hinges on molecular platform convergence capability across LAMP and RT-PCR architectures. Monitor CDSCO WHO-prequalification pilot expansion signals as inflection indicator for Indian market access velocity improvement.| Strategic Initiative | Industry Significance |
|---|---|
| Multiplex Tropical Disease Panel Development | Captures serology-to-molecular workflow consolidation in Thai and Malaysian reference laboratories. |
| IVDR Technical Documentation Completion | Preserves CE mark access for NS1 antigen claims across European hospital networks. |
| WHO Prequalification Fast-Track Alignment | Unlocks CDSCO accelerated review and Indian state procurement eligibility. |
| Cold-Chain-Independent Reagent Formulation | Enables Indonesian archipelago and Brazilian Amazon distribution without refrigeration infrastructure. |
| Community Health Worker Channel Partnership | Secures volume placement in Philippine village programs and Vietnamese rural clinics. |
Research Approach
Document review covered WHO prequalification assessment reports, ANVISA import licensing databases, and CDSCO regulatory circulars, complemented by interviews with hospital laboratory directors, IVD procurement managers at Brazilian blood services, biomedical engineers at Thai district hospitals, and regulatory affairs leads at multinational diagnostics manufacturers. Secondary validation drew from EU IVDR guidance documents, ISO 13485 audit records, and tropical disease surveillance bulletins. Bottom-up test volume modeling and top-down market sizing triangulated across manufacturer shipment data and national health ministry procurement disclosures.
Historical serology-to-molecular test mix shifts were cross-referenced against expert panel input from Bangkok academic medical centers and São Paulo reference institutes. Segmentation dimensions modeled include test type, sample matrix, end-user facility tier, and technological platform across the analysis window. CAGRs were derived from epidemiological outbreak pattern projections and laboratory automation adoption curves. Forecast inputs incorporated serotype circulation volatility assumptions and regulatory harmonization timeline uncertainty between WHO, IVDR, and national prequalification pathways.
Several conditions sit outside the modeled scope, including novel flavivirus emergence with cross-reactivity profiles disrupting existing assay validation, and abrupt regulatory reciprocity withdrawals between Brazil and Mercosur partners. Forecasts reflect documented assumptions about cold-chain infrastructure expansion rates and WHO prequalification throughput capacity. Stakeholders should weight assumptions against their own operating context and monitor CDSCO pilot program expansion signals for Indian market access timing revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Asia-Pacific Viral Clearance Market
Testing Services
Home Blood Testing Devices Market
Testing Services
Mycological Testing Market
Testing Services
Global Terminal Sterilization Services Market
Testing Services
Medical Device Testing Services Market
Testing Services
Asia-Pacific Antimicrobial Susceptibility Testing Market
Testing Services
Adiponectin Testing Market
Testing Services
CRO Mass Spectroscopy Services Market
Testing Services
Rapid Antigen Testing Market
Testing Services
Nucleic Acid Testing Market
Testing Services
Phenytoin Testing Market
Testing Services
Pyrogen Testing Market
Testing Services
Pharmaceutical Analytical Testing Market
Testing Services
Hemostasis Testing Systems Market
Testing Services
Lipase Testing Reagents Market
Testing Services
Prothrombin Time Testing Market