
 Vaginal Panel Testing Market | 2026-2036
Vaginal Panel Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Vaginal Panel Testing Market Analytics
Software-defined assay menus on integrated molecular platforms is decoupling test content from hardware refresh cycles, reshaping capital deployment for clinical laboratories. Becton, Dickinson and Company leverages its BD MAX platform to sustain installed-base loyalty through programmable assay cartridges. Cepheid anchors point-of-care penetration with GeneXpert's expandable test library. bioMérieux competes through FilmArray's syndromic panel architecture, which differentiates via rapid turnaround in emergency department workflows.
Vaginal panel testing comprises multiplex molecular and immunoassay diagnostics designed to detect bacterial vaginosis, vulvovaginal candidiasis, and trichomoniasis from vaginal swab or urine specimens, typically reporting results within 30-90 minutes depending on platform chemistry. The primary commercial purpose centers on replacing sequential single-target testing with simultaneous pathogen identification, improving therapeutic precision while reducing empirical antibiotic prescribing. Nucleic acid tests occupy the premium tier where margin pools concentrate, driven by superior sensitivity for polymicrobial infections. Point-of-care tests represent the fastest-expanding segment as CLIA-waived molecular devices penetrate physician office laboratories and urgent care settings.
The US FDA regulates these devices through the in vitro diagnostic pathway, with CLIA categorization determining site-of-use eligibility and directly shaping addressable market scope for each manufacturer. The Centers for Medicare and Medicaid Services reimbursement frameworks under the Clinical Laboratory Fee Schedule influence test economics and adoption velocity across hospital and independent laboratory settings. Stakeholders must monitor evolving antimicrobial stewardship mandates from the Centers for Disease Control and Prevention, as these programs increasingly define panel content requirements and testing protocols within health systems.
Market Dynamics
The US FDA's CLIA-waived pathway for molecular diagnostics is compressing the point-of-care deployment timeline, forcing hospital laboratories to reconfigure capital allocation between centralized and distributed testing nodes.
Growth Catalysts
- Antimicrobial stewardship mandates:The Centers for Disease Control and Prevention protocols within US integrated delivery networks are mandating rapid pathogen identification to curb empirical antibiotic prescribing.
- Multiplex platform expansion:Hospital laboratories are consolidating single-target workflows into syndromic panels to reduce turnaround time and consumable inventory complexity.
- Point-of-care penetration:Physician office laboratories and urgent care settings across the United States are adopting CLIA-waived molecular devices to capture specimen volume previously routed to centralized labs.
Market Restraints
- Reimbursement compression:The Centers for Medicare and Medicaid Services Clinical Laboratory Fee Schedule revisions are constraining test economics for independent laboratories.
- Platform lock-in effects:Capital-intensive installed bases of integrated molecular systems create switching friction for mid-sized hospital networks.
- Specimen stability limitations:Transport temperature requirements for nucleic acid preservation restrict testing access in rural collection sites without cold chain infrastructure.
Strategic Opportunities
- Software-defined assay menus:Programmable cartridge architectures allow manufacturers to refresh test content without hardware replacement cycles.
- At-home collection models:Self-collected vaginal swab protocols paired with mail-back molecular processing are expanding addressable reach beyond clinical settings.
- Resistance marker integration:Panels incorporating antibiotic susceptibility reporting align with stewardship program requirements in academic medical centers.
Industry Challenges
- Molecular diagnostics technician scarcity:CLIA-waived device operation still requires trained personnel for quality control and result interpretation in point-of-care settings.
- Laboratory information system integration:Syndromic panel data formats often require custom middleware development to interface with electronic health record platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaginal Panel Testing Market |
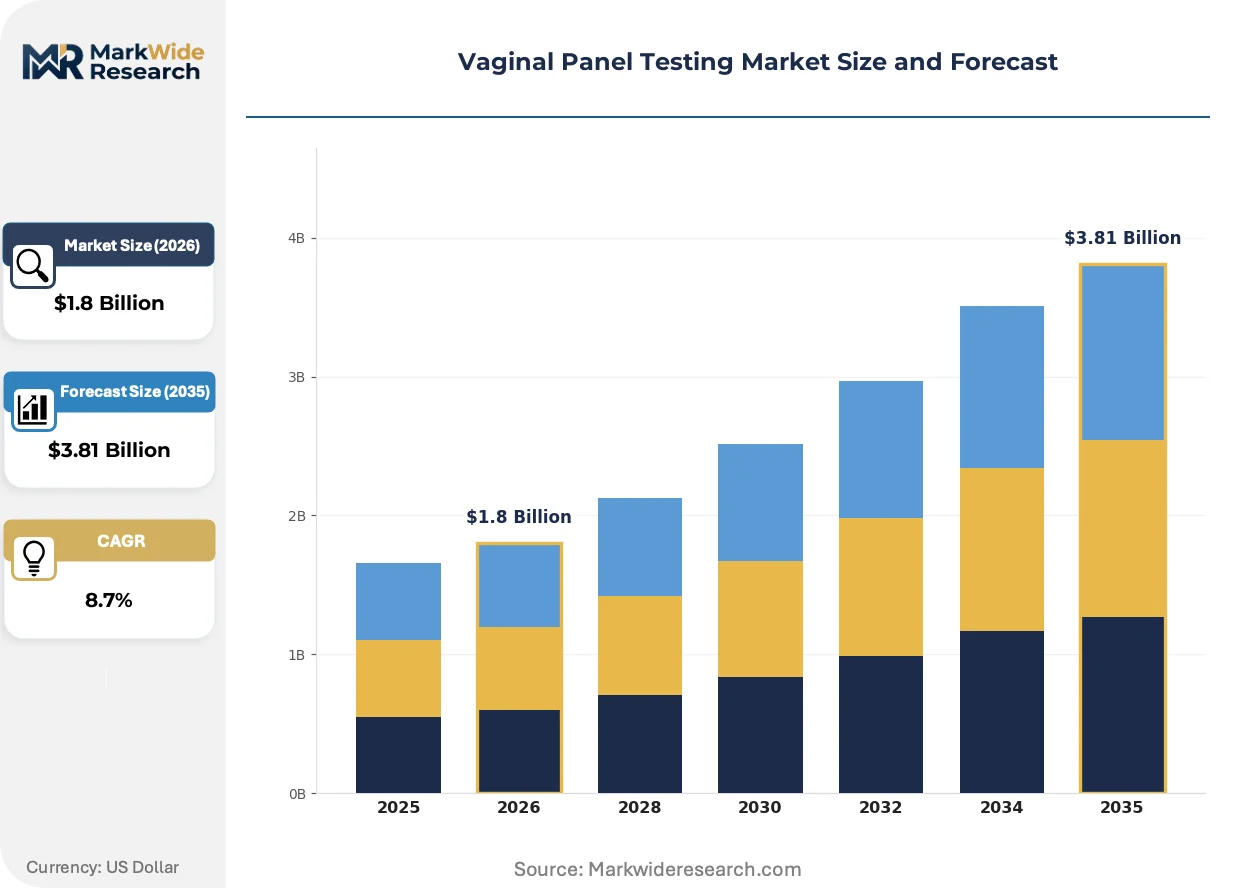
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nucleic Acid Test, Immunoassay, Culture Test, Point-of-Care Test End User: Hospitals, Laboratories, Home Care, Diagnostic Centers Distribution Channel: Online, Pharmacies, Direct Sales, Retail Sample Type: Urine, Swab, Blood, Tissue |
| Companies Covered | Becton, Dickinson and Company, Cepheid, Abbott Laboratories, bioMérieux, Seegene, F. Hoffmann-La Roche, QIAGEN, Thermo Fisher Scientific, Hologic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaginal Panel Testing Market Evolving Landscape
Three forces are restructuring competitive positioning in vaginal panel testing: the convergence of sample-to-answer automation with cloud-connected result reporting, regulatory pathways that accelerate point-of-care molecular authorization, and procurement models that bundle diagnostics with antimicrobial stewardship consulting.
Sample-to-answer cartridge systems are unifying nucleic acid extraction, amplification, and detection within single-use consumables. Hospital laboratories with limited molecular biology staffing are adopting these closed systems to reduce contamination risk and technical training burden. This unification is compressing the competitive advantage previously held by high-complexity reference laboratories.
The US FDA's breakthrough device designation pathway for infectious disease diagnostics is compressing premarket review timelines for novel multiplex targets. Manufacturers pursuing expanded organism claims face streamlined evidentiary requirements when panels address unmet diagnostic needs. Point-of-care molecular platforms targeting sexually transmitted infection co-detection are benefiting most from this regulatory acceleration.
Integrated delivery networks are consolidating laboratory procurement under centralized contracting offices that negotiate multi-year exclusive agreements. Group purchasing organizations are displacing individual hospital negotiations and demanding performance guarantees on turnaround time and test menu breadth. This consolidation is most visible in the southeastern United States, where regional health systems are rationalizing redundant point-of-care deployments across acquired physician practices.
Vaginal Panel Testing Market Segmentation
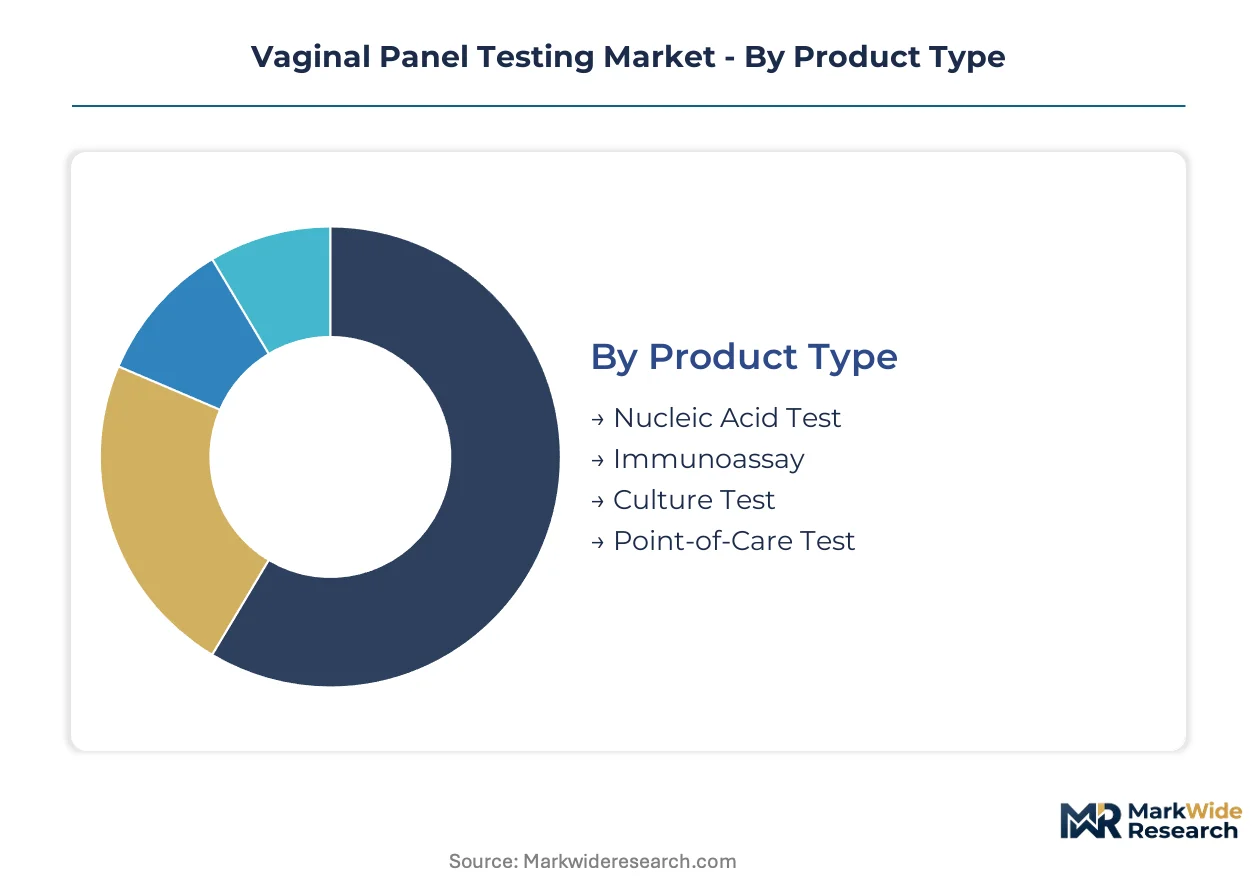
Segmentation in vaginal panel testing reveals distinct procurement patterns across clinical settings, with technology choice and site-of-care requirements driving divergent margin structures and regulatory pathways for manufacturers.
Product Type:
Technology selection separates high-complexity reference laboratories from point-of-care deployers, with capital intensity and staff training requirements creating distinct buyer tiers.
- Nucleic Acid Test:Polymerase chain reaction and isothermal amplification methods detect bacterial vaginosis, candidiasis, and trichomoniasis with superior sensitivity for polymicrobial infections. Academic medical centers and hospital core laboratories concentrate demand here, prioritizing definitive pathogen identification to satisfy antimicrobial stewardship protocols. Nucleic acid tests command premium pricing and concentrate manufacturer margin pools.
- Point-of-Care Test:CLIA-waived molecular and immunoassay devices deliver results within 30 minutes from physician office laboratories and urgent care settings. Physician practices across the United States adopt these systems to retain specimen volume previously referred to centralized laboratories, with the FDA's streamlined authorization pathway compressing deployment timelines.
- Immunoassay:Enzyme-linked immunosorbent assays and lateral flow formats target single-pathogen detection with lower per-test cost. Independent clinical laboratories utilize immunoassays for screening workflows where rapid turnaround outweighs multiplex capability.
- Culture Test:Traditional microbiological cultivation remains relevant for antibiotic susceptibility profiling in complicated or recurrent infections. Reference laboratories maintain culture capacity for stewardship programs requiring resistance phenotyping.
Nucleic acid tests lead volumes today; point-of-care tests are gaining share fastest.
End User:
Site-of-care economics and specimen routing patterns fragment the customer base across integrated delivery networks and independent operators.
- Hospitals:Inpatient and emergency department workflows demand syndromic panels with rapid turnaround to guide empirical therapy decisions. Antimicrobial stewardship mandates from the CDC shape testing protocols and panel content requirements within US health systems.
- Laboratories:Hospital-affiliated and independent reference laboratories consolidate high-complexity molecular testing, leveraging batch processing and technical specialist staffing to achieve cost efficiency. The Clinical Laboratory Fee Schedule constrains reimbursement economics for independent operators.
- Diagnostic Centers:Outpatient facilities and women's health clinics perform screening panels for asymptomatic patients, with volume concentrated in metropolitan areas with established obstetrics-gynecology practice networks.
- Home Care:Self-collected specimen protocols paired with mail-back molecular processing expand access beyond traditional clinical settings, though cold chain requirements limit rural penetration.
Hospitals anchor current revenue; home care represents the steepest expansion trajectory.
Distribution Channel:
Procurement centralization through group purchasing organizations is displacing direct manufacturer relationships in hospital networks.
- Direct Sales:Manufacturers deploy specialized diagnostic sales forces to negotiate multi-year exclusive agreements with integrated delivery networks. Southeastern US health systems increasingly consolidate laboratory procurement under centralized contracting offices.
- Pharmacies:Retail pharmacy chains with in-store clinical services represent an emerging channel for point-of-care test distribution, particularly for urgent care and walk-in screening applications.
- Online:E-commerce platforms serve independent physician practices and smaller diagnostic centers with consumable replenishment, though capital equipment sales remain relationship-intensive.
- Retail:Limited distribution through medical supply retailers targets home collection kit sales where regulatory frameworks permit direct-to-consumer access.
Direct sales dominate contract value; online channels are climbing the fastest.
Sample Type:
Specimen stability requirements and patient collection preferences shape platform design and testing access geography.
- Swab:Vaginal and endocervical swabs remain the standard specimen for multiplex panel testing, with self-collection protocols reducing clinical visit burden. Transport temperature requirements for nucleic acid preservation restrict testing access in rural collection sites lacking cold chain infrastructure.
- Urine:First-catch urine specimens enable non-invasive collection and align with sexually transmitted infection co-detection workflows in emergency departments. Urine-based testing expands screening compliance among patient populations averse to pelvic examination.
- Blood:Serum and plasma samples support serological confirmation in recurrent or persistent infection cases, with limited application in primary diagnostic panels.
- Tissue:Biopsy specimens serve specialized applications in refractory vulvovaginal conditions requiring histopathological correlation.
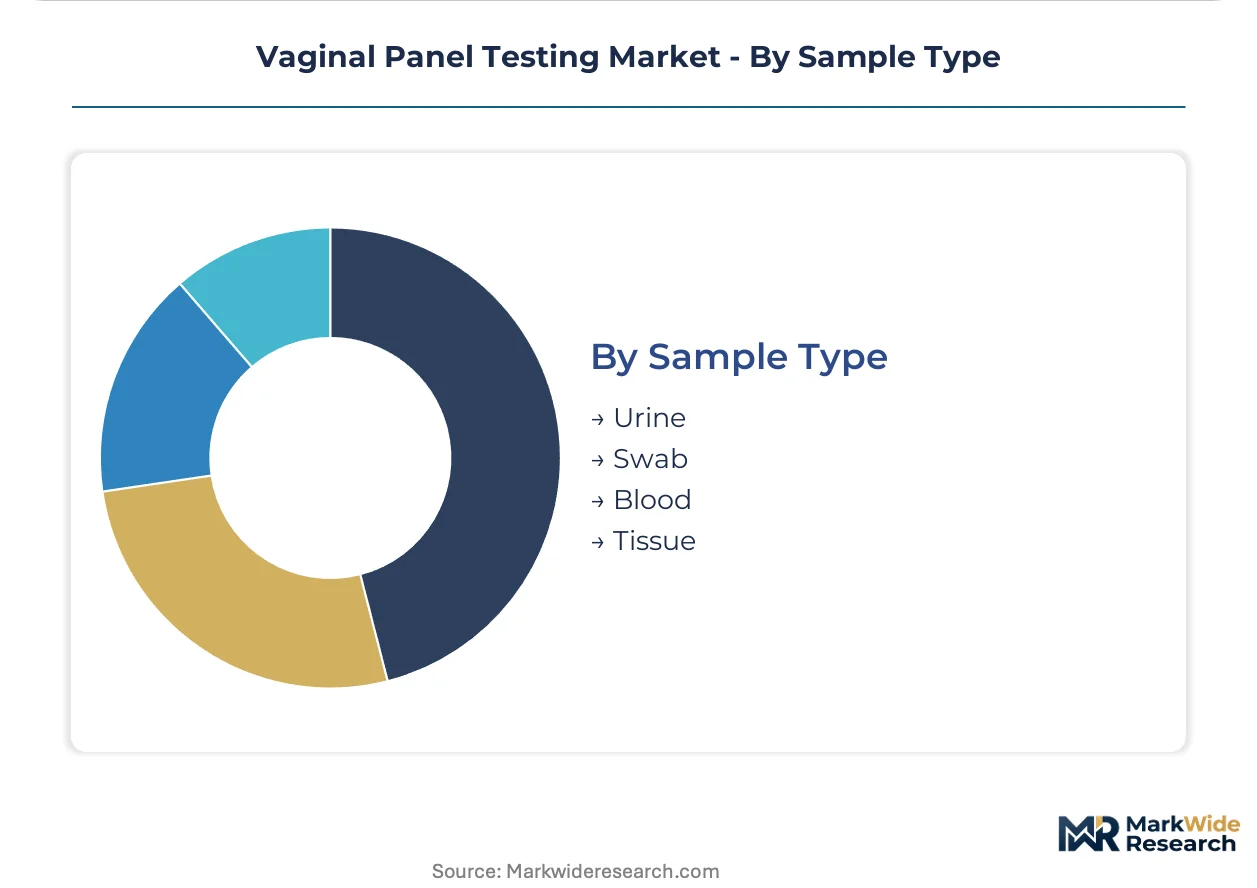
Swab-based testing leads procedure volumes; urine specimens are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems deploy syndromic panels at twice the density of German hospital networks, reflecting divergent reimbursement incentives and stewardship program maturity. Canada and United Kingdom laboratories accelerate adoption through centralized procurement frameworks. Japan's reference laboratories maintain conservative conversion timelines from culture-based workflows.
United States
Integrated delivery networks in Texas and Florida consolidate laboratory procurement under centralized contracting offices, mandating rapid pathogen identification to curb empirical antibiotic prescribing. The FDA's CLIA-waived pathway for molecular diagnostics compresses point-of-care deployment timelines across physician office laboratories. The Southeast region rationalizes redundant point-of-care deployments across acquired physician practices.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia prioritize definitive pathogen identification through nucleic acid amplification methods for polymicrobial infections. The national pharmaceutical regulator maintains stringent post-market surveillance requirements for infectious disease diagnostics. Berlin-Brandenburg hospital networks consolidate high-complexity molecular testing under regional laboratory cooperatives.
United Kingdom
National Health Service trusts in London and the Midlands adopt syndromic panels to reduce turnaround time and consumable inventory complexity. The Medicines and Healthcare products Regulatory Agency streamlines conformity assessment pathways for novel multiplex targets. The Southeast region concentrates demand for emergency department rapid diagnostics.
Japan
Reference laboratories in Kanto and Kansai regions maintain conservative conversion timelines from traditional microbiological cultivation. The national pharmaceutical regulator requires extensive clinical evidence for expanded organism claims on multiplex panels. Tokyo metropolitan hospital networks prioritize batch processing efficiency over point-of-care deployment.
Canada
Provincial health authorities in Ontario and Quebec accelerate adoption through centralized procurement frameworks for antimicrobial stewardship programs. Health Canada regulates devices through the medical device pathway with site-of-use eligibility determining addressable market scope. The Greater Toronto Area concentrates demand for mail-back molecular processing models.
Vaginal Panel Testing Market Competitive Landscape
Top-tier vendors anchor the premium nucleic acid test segment, while mid-tier specialists compete on programmable cartridge architectures and point-of-care deployability. The vendor base stratifies across three archetypes: integrated diagnostics conglomerates with installed-base loyalty programs, molecular platform specialists with expandable test libraries, and regional manufacturers with cost-optimized immunoassay portfolios. Competitive intensity concentrates on software-defined assay menus and multi-year exclusive agreements with integrated delivery networks.
Within the integrated diagnostics tier, Becton, Dickinson and Company and Abbott Laboratories occupy positions defined by capital-intensive installed bases and programmable cartridge architectures. Cepheid exemplifies the point-of-care penetration archetype through CLIA-waived molecular platforms. These three entities represent distinct strategic postures: hardware-anchored ecosystem control, rapid deployment flexibility, and urgent care channel capture.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Cepheid |
| Abbott Laboratories |
| bioMérieux |
| Seegene |
| F. Hoffmann-La Roche |
| QIAGEN |
| Thermo Fisher Scientific |
| Hologic |
| Others |
Value Network & Pricing Analysis
Antimicrobial stewardship mandates from the CDC gate both qualified supply and premium-tier pricing access for vaginal panel testing manufacturers, as health systems restrict procurement to vendors demonstrating rapid pathogen identification capabilities that satisfy empirical prescribing reduction protocols.
Pricing Analysis
Capacity additions in the United States are reshaping price floors for CLIA-waived molecular devices as Cepheid and Abbott Laboratories expand point-of-care manufacturing footprints. Three-tier pricing structure across premium, standard, and economy levels separates nucleic acid test systems from immunoassay platforms and culture-based workflows, with price differentiation driven by FDA clearance tier and antimicrobial stewardship certification depth. Cost compression in the immunoassay segment is intensifying because independent clinical laboratories face Clinical Laboratory Fee Schedule reimbursement constraints. Hospital core laboratories demonstrate lowest price sensitivity due to stewardship program mandates, while urgent care settings exhibit highest sensitivity to per-test consumable costs.
Supply Chain Analysis
Refurbished cartridge return programs and instrument redeployment flows from integrated delivery network consolidations are creating secondary supply channels for molecular platform manufacturers. Manufacturing concentrates in the United States, Germany, and Japan, with reagent production drawing from specialized polymerase suppliers in Singapore and optical component vendors in Taiwan. Supply chain risk centers on single-source vulnerability for isothermal amplification enzymes subject to cold chain preservation requirements. Distribution runs through group purchasing organizations that consolidate multi-year exclusive agreements across southeastern US health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in vaginal panel testing rests on software-defined assay architectures that extend hardware depreciation cycles while enabling premium pricing for resistance marker panels.
For Market Incumbents: Deepen installed-base loyalty through programmable cartridge architectures that decouple test content refreshes from capital replacement cycles. Consolidate point-of-care deployments across acquired physician practices to eliminate redundant instrument placements. Defend against emerging molecular platform specialists by anchoring antimicrobial stewardship consulting services to exclusive GPO contracts. For New Entrants and Emerging Players: The price-point gap between premium nucleic acid systems and economy immunoassay platforms offers entry space for mid-tier syndromic panel specialists. Target urgent care settings in metropolitan Texas and Florida corridors where CLIA-waived authorization accelerates deployment timelines. Pursue mail-back molecular processing partnerships with women's health clinic networks to bypass capital-intensive instrument sales cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among regional immunoassay manufacturers lacking molecular platform capabilities but holding established distribution in independent laboratory channels. Long-term viability favors vendors with software-expandable test menus aligned to CDC stewardship protocol evolution. Monitor FDA breakthrough device designation grants for infectious disease multiplex targets as inflection signals for point-of-care authorization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waived Molecular Authorization | FDA streamlined pathways compress deployment timelines across physician office laboratories. |
| Software-Defined Assay Menu Expansion | Programmable cartridges extend hardware lifecycles while refreshing test content for stewardship compliance. |
| Antimicrobial Stewardship Consulting Bundle | Integrated delivery networks prioritize vendors pairing diagnostics with empirical prescribing reduction protocols. |
| Mail-Back Molecular Processing Model | Self-collected specimen protocols expand addressable reach beyond traditional clinical site infrastructure. |
| Resistance Marker Panel Integration | Academic medical centers demand antibiotic susceptibility reporting to satisfy CDC stewardship mandates. |
Research Methodology
Coverage spans the United States, Germany, United Kingdom, Japan, and Canada, with primary inputs from each market's hospital procurement committees, GPO contracts managers, biomedical engineers, and regulatory affairs specialists. Secondary validation drew from FDA 510(k) filings, CMS Clinical Laboratory Fee Schedule publications, CDC antimicrobial stewardship protocol documents, and hospital procurement database extracts. Bottom-up instrument placement and consumable volume estimates triangulated against top-down health system expenditure aggregates.
Rate-of-change decomposition separated volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include technology tier, site-of-care category, specimen type, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to CLIA-waived authorization timelines and antimicrobial stewardship program penetration rates. Forecast inputs incorporated GPO contract renewal cycles and FDA breakthrough device designation velocity.
Caveats apply where reimbursement schedule revisions or supply chain disruptions for amplification reagents could materially shift the outlook. Practitioners should monitor CDC stewardship protocol updates and FDA point-of-care authorization timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Asia-Pacific Newborn Screening Market
Testing Services
At-Home Celiac Testing Market
Testing Services
Drug Screening Laboratory Service Market
Testing Services
Global Cannabis Testing Market
Testing Services
Nipah Virus (Niv) Infection Testing Market
Testing Services
Infusion Toxicology Services Market
Testing Services
CRO Mass Spectroscopy Services Market
Testing Services
US Bowie Dick Test Pack Market
Testing Services
Global Legionella Testing Market
Testing Services
Europe Medical Device Testing Market
Testing Services
Retrovirus Testing Market
Testing Services
US Cannabis Testing Market
Testing Services
Global Direct-To-Consumer (DTC)Testing Market
Testing Services
Toxicology Drug Screening Market
Testing Services
Comprehensive Metabolic Panel (CMP) Testing Market
Testing Services
Global Roadside Drug Testing Devices Market