
 UWB Anchor Market | 2026-2036
UWB Anchor Market Size, Share, and Industry Trends Forecast 2026-2036
UWB Anchor Market Analytics
The gap between proprietary UWB protocols and IEEE 802.15.4z standardization is narrowing, forcing vendors to redesign hardware architectures for interoperability. Qorvo leverages its RF front-end expertise to supply high-volume UWB chipsets to anchor manufacturers. Pozyx anchors its European presence through open-source positioning software stacks that reduce customer integration costs. SKYLAB M&C Technology dominates cost-sensitive Asian deployments with compact module designs.
A UWB anchor is a fixed or mobile radio node that transmits ultra-wideband pulses across 3.1–10.6 GHz, enabling centimeter-level distance measurement through time-of-flight calculations between tagged objects and reference points. The device serves industrial and commercial environments where GPS signals fail, providing real-time location coordinates for assets, personnel, or autonomous vehicles. Fixed anchors currently lead installations in manufacturing and logistics facilities, while mobile anchor configurations represent the fastest-growing segment as warehouse operators seek flexible zone reconfiguration without infrastructure overhaul. RTLS technology commands the largest technology share, though Time Difference of Arrival architectures gain traction in multi-story healthcare complexes where vertical positioning accuracy determines system value.
The FCC enforces strict power spectral density limits under Part 15 subpart F, compelling anchor designers to implement burst-gating and spectral shaping circuits that add bill-of-materials cost. ETSI's EN 302 567 standard governs European UWB deployments, with CE marking requirements that delay market entry for non-compliant hardware. Stakeholders must monitor evolving frequency allocation debates in Japan and South Korea, where METI and the Korea Communications Commission respectively weigh expanded UWB spectrum access against incumbent radar services.
Market Dynamics
The convergence of IEEE 802.15.4z standardization with proprietary UWB protocols is compressing hardware development cycles and forcing anchor vendors to redesign architectures for interoperability, reshaping competitive positioning across industrial asset-tracking deployments.
Growth Catalysts
- FCC Part 15 subpart F:Unlicensed transmission rules in the United States enable rapid anchor deployment without spectrum licensing delays, accelerating factory-floor RTLS adoption.
- Automotive OEMs in Germany:Precision engineering firms drive demand for centimeter-level localization systems in Stuttgart and Munich manufacturing clusters.
- Time-of-flight calculation advances:Improved pulse-shaping algorithms reduce multipath interference in steel-heavy industrial environments.
Market Restraints
- Spectral shaping circuit costs:Burst-gating hardware required for FCC power density compliance adds bill-of-materials pressure on cost-sensitive Asian manufacturers.
- ETSI EN 302 567 delays:CE marking requirements for European deployments extend hardware certification timelines by six to nine months.
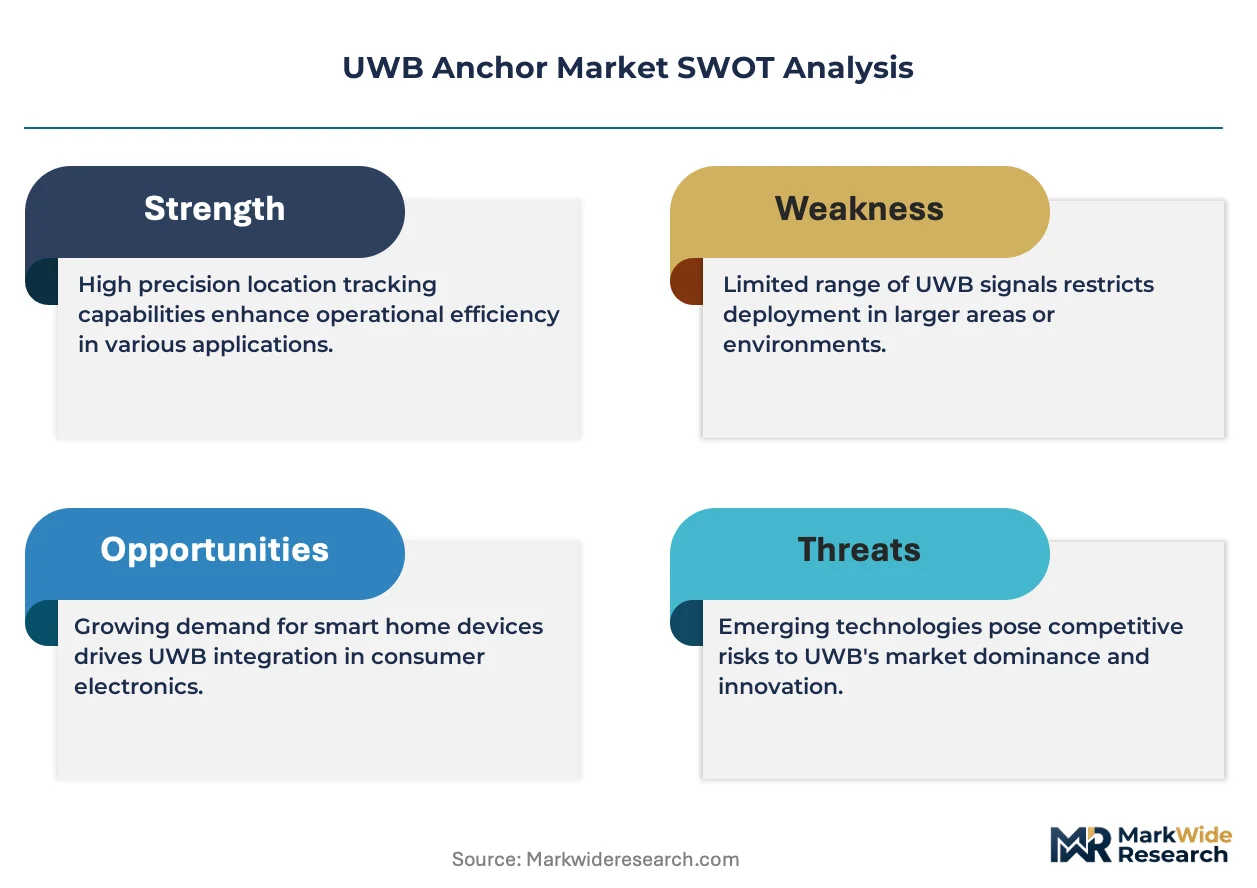
- Bluetooth AoA substitution:Angle-of-arrival alternatives at lower price points capture indoor positioning contracts in retail and hospitality verticals.
Strategic Opportunities
- METI spectrum expansion debates:Japan's Ministry of Economy, Trade and Industry weighs broader UWB allocation against incumbent radar services, potentially unlocking new bandwidth for anchor deployments.
- Mobile anchor configurations:Warehouse operators seek flexible zone reconfiguration without infrastructure overhaul, creating demand for battery-powered, repositionable units.
- Healthcare vertical penetration:Time Difference of Arrival architectures address vertical positioning accuracy requirements in multi-story hospital complexes.
Industry Challenges
- RF front-end engineering scarcity:Specialized talent for 3.1–10.6 GHz antenna design concentrates in Shenzhen and San Diego, creating recruitment bottlenecks for European anchor startups.
- Legacy system integration friction:Manufacturing facilities with decade-old Wi-Fi infrastructure face protocol incompatibility when layering UWB anchors atop existing networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UWB Anchor Market |
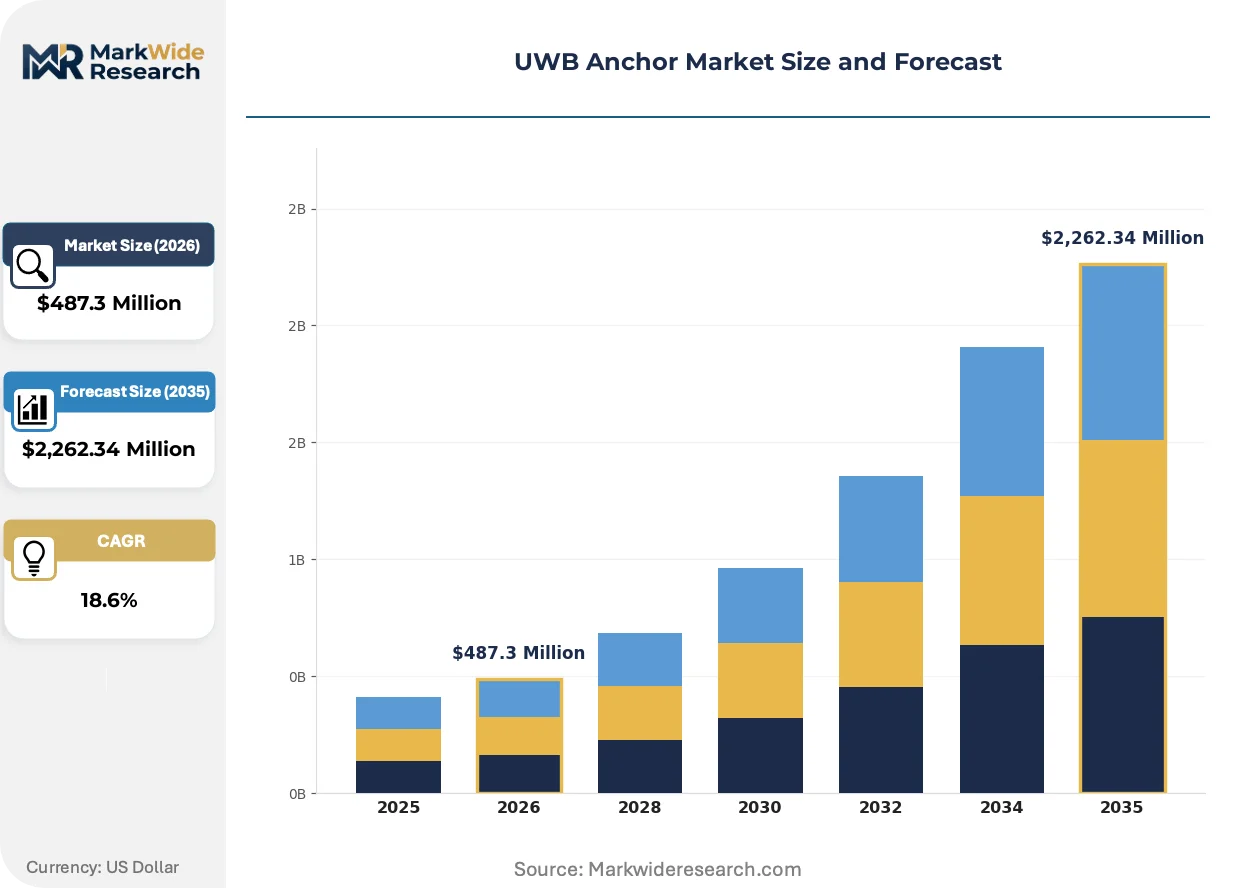
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,262.34 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Anchor, Mobile Anchor, Dynamic Anchor, Ultra-Wideband Module Application: Indoor Positioning, Asset Tracking, Navigation, Smart Homes Technology: RTLS, Time Difference of Arrival, Angle of Arrival, Frequency Hopping End User: Healthcare, Retail, Manufacturing, Logistics |
| Companies Covered | Sewio, Pozyx, Qorvo, Zebra Technologies, NXP Semiconductors, SKYLAB M&C Technology, Gruppo Filippetti, Kinexon, Minew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UWB Anchor Market Evolving Landscape
Hardware miniaturization and software-defined positioning stacks are compressing the traditional boundary between fixed infrastructure and mobile anchor categories, enabling new deployment paradigms across logistics and healthcare environments.
Multi-protocol silicon is collapsing the cost barrier between single-purpose UWB chipsets and flexible radio platforms. Semiconductor vendors integrate 802.15.4z with Bluetooth Low Energy and NFC on unified die architectures. Automotive tier-1 suppliers adopt these converged designs for digital key and asset-tracking programs, collapsing the historical separation between consumer and industrial anchor hardware supply chains.
ETSI's ongoing revision of EN 302 567 is tightening out-of-band emission limits for European UWB devices. Anchor manufacturers must redesign front-end filters and power amplifiers to meet draft specifications anticipated for formal adoption. German industrial automation firms, particularly those supplying BMW and Mercedes-Benz assembly lines, are pre-certifying hardware to avoid production line disruptions.
Buyer procurement patterns are fragmenting as large warehouse operators bypass systems integrators to source anchors directly from module vendors. Amazon and DHL facilities in Leipzig and Rotterdam now specify open-source positioning software stacks as mandatory procurement criteria. This disintermediation compresses margin pools for traditional RTLS installation contractors while rewarding hardware vendors with software competency.
UWB Anchor Market Segmentation
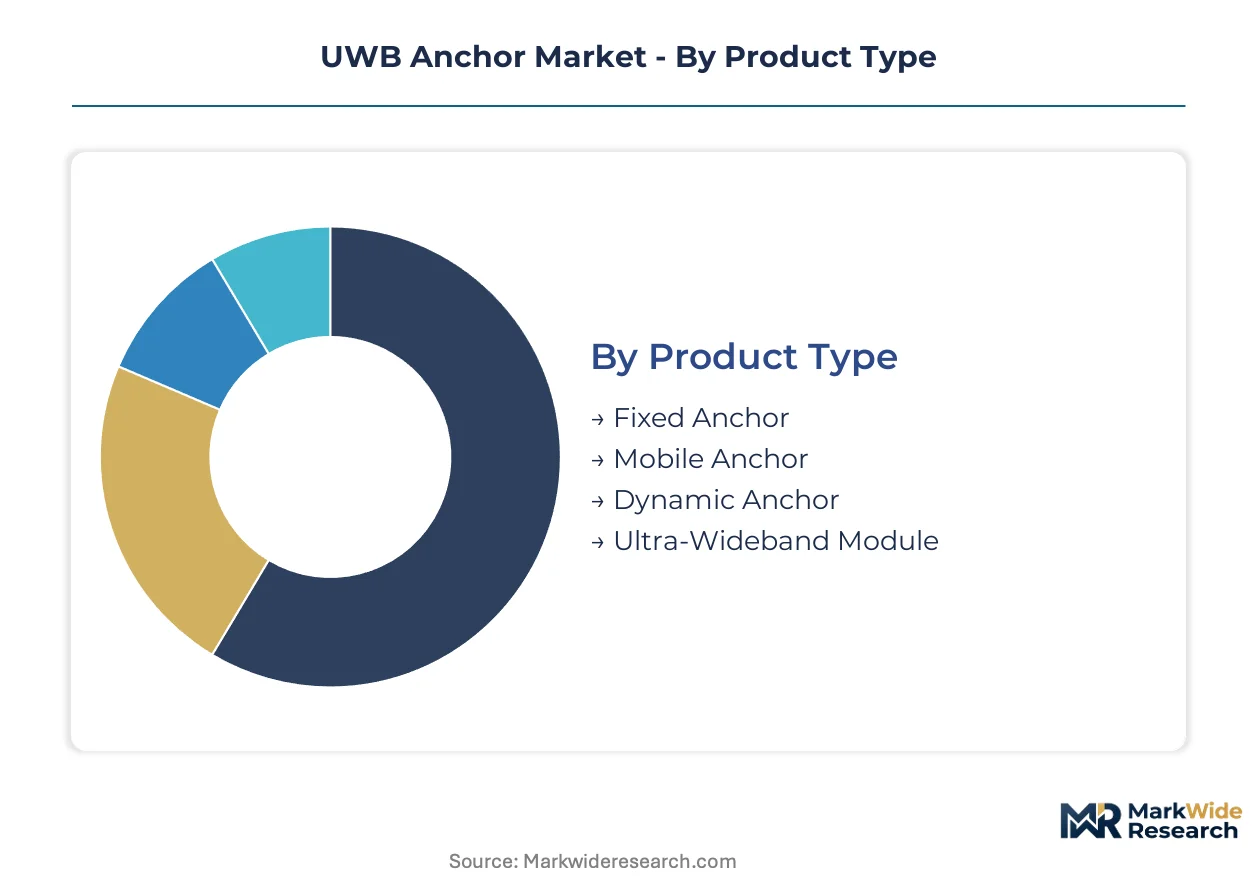
UWB anchor segmentation reveals distinct hardware-service bundles that reshape vendor business models. After-sales calibration and firmware maintenance intensity varies sharply across product configurations, driving margin structures and customer lifetime value calculations.
Product Type:
After-sales service intensity peaks with mobile and dynamic configurations, where battery replacement schedules, repositioning recalibration, and roaming handoff optimization create recurring revenue streams that fixed infrastructure cannot match.
- Fixed Anchor:Wall-mounted or ceiling-mounted units with permanent power and network connections deliver baseline RTLS coverage. German automotive OEMs in Stuttgart manufacturing clusters specify these for assembly line asset tracking where infrastructure stability outweighs flexibility requirements. Fixed Anchor holds the largest share; momentum sits with Mobile Anchor.
- Mobile Anchor:Battery-powered, repositionable units with wireless backhaul enable rapid zone reconfiguration without construction delays. Warehouse operators at Rotterdam and Leipzig logistics hubs deploy these for seasonal layout changes, trading calibration frequency for operational agility.
- Dynamic Anchor:Self-positioning units that autonomously map their coordinates relative to fixed reference points reduce installation labor. Underground mining operations in Western Australia adopt these where GPS denial and infrastructure mobility converge.
- Ultra-Wideband Module:Chipset-level components for OEM integration into third-party hardware. Robotics manufacturers in Shenzhen embed these for autonomous vehicle navigation stacks.
Fixed Anchor holds the largest share; momentum sits with Mobile Anchor.
Application:
Application segmentation tracks customer willingness to pay for precision tiers, with navigation and asset-tracking deployments commanding hardware premiums that smart home installations cannot support.
- Indoor Positioning:Centimeter-level coordinate determination for personnel and equipment in GPS-denied environments. Multi-story hospital complexes in Texas and Bavaria deploy these for vertical accuracy where elevator transitions determine system value.
- Asset Tracking:Real-time location monitoring for high-value inventory and tooling. Fulfillment centers in Poland and Ohio prioritize these for pick-path optimization and theft reduction.
- Navigation:Autonomous vehicle guidance and pedestrian wayfinding in complex structures. Airport terminals in Singapore and Dubai integrate these for passenger routing and baggage tractor automation.
- Smart Homes:Consumer-grade presence detection and device automation. South Korean apartment developers bundle these for lighting and climate control, though price sensitivity constrains hardware specifications.
Asset Tracking commands the greatest installed base; Navigation is climbing the fastest.
Technology:
Technology choice determines antenna count, processing requirements, and ultimately bill-of-materials cost, with multi-path mitigation capabilities separating industrial from consumer-grade deployments.
- RTLS:Comprehensive real-time location system architectures combining multiple measurement techniques. Manufacturing facilities in Michigan and Baden-Württemberg standardize on these for enterprise-wide visibility platforms.
- Time Difference of Arrival:Hyperbolic positioning using synchronized anchor networks for three-dimensional accuracy. Healthcare complexes in Massachusetts and North Rhine-Westphalia specify these for floor-level patient tracking.
- Angle of Arrival:Direction-finding through antenna array phase analysis with lower infrastructure density requirements. Retail environments in France and Japan adopt these for reduced anchor counts in constrained ceiling spaces.
- Frequency Hopping:Rapid channel switching for interference resilience in congested spectrum. Industrial deployments in Shenzhen electronics factories leverage these for coexistence with Wi-Fi 6E networks.
RTLS dominates current procurement; Time Difference of Arrival shows the steepest expansion trajectory.
End User:
End user verticals exhibit divergent procurement patterns, with healthcare and manufacturing demanding certified reliability while retail and logistics prioritize unit economics and rapid scaling.
- Healthcare:Regulated environments requiring FDA-compliant hardware for patient safety and HIPAA-aligned data handling. Hospital networks in California and Hesse mandate these specifications for emergency department workflow optimization.
- Retail:Inventory visibility and customer analytics in brick-and-mortar environments. Fashion chains in Italy and the United Kingdom deploy these for fitting room engagement and loss prevention.
- Manufacturing:Work-in-progress tracking and tool crib management on factory floors. Automotive suppliers in Mexico and Slovakia integrate these with MES systems for just-in-sequence production.
- Logistics:Yard management and cross-dock visibility in high-velocity distribution. Parcel hubs in Tennessee and the Netherlands specify these for trailer positioning and automated gate transactions.
Manufacturing represents the deepest installed base; Healthcare is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers concentrate in Germany's automotive belt, the United States' logistics corridors, and China's electronics manufacturing zones. These three geographies generate anchor demand through distinct procurement patterns: precision engineering specifications, rapid deployment timelines, and cost-optimized volume purchasing respectively.
United States
Amazon fulfillment centers and DHL hubs in Tennessee and Ohio drive demand for mobile anchor configurations that enable seasonal warehouse reconfiguration. FCC Part 15 subpart F governs unlicensed UWB transmission power levels, eliminating spectrum licensing delays that constrain European deployment velocity. Detroit-area automotive suppliers integrate fixed anchors with manufacturing execution systems for just-in-sequence production workflows.
Germany
BMW and Mercedes-Benz assembly lines in Stuttgart and Munich specify centimeter-level localization for tool-crib management and work-in-progress tracking. ETSI's EN 302 567 standard mandates CE marking that extends hardware certification timelines by six to nine months, forcing vendors to pre-certify designs. The Baden-Württemberg precision engineering cluster anchors European demand for industrial-grade RTLS infrastructure.
China
Shenzhen robotics manufacturers embed UWB modules into autonomous vehicle navigation stacks for factory-floor deployment. MIIT governs radio transmission equipment type approval through SRRC certification requirements that align with national spectrum allocation priorities. The Pearl River Delta electronics manufacturing belt concentrates module production and anchor integration capacity.
Japan
Airport terminals in Tokyo and Osaka integrate navigation-grade anchors for passenger routing and baggage tractor automation. METI weighs expanded UWB spectrum allocation against incumbent radar service protection, with regulatory decisions pending that could unlock additional bandwidth. The Kanto manufacturing corridor tests dynamic anchor configurations for flexible zone reconfiguration in high-mix production environments.
Netherlands
Rotterdam port operators and cross-dock facilities specify open-source positioning software stacks as mandatory procurement criteria. CE marking under ETSI EN 302 567 applies, though Dutch regulators prioritize rapid certification for logistics infrastructure investments. The Randstad logistics hub serves as a European testbed for mobile anchor deployments in high-velocity distribution environments.
UWB Anchor Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that compresses margin pools for traditional systems integrators. Semiconductor vendors with RF front-end expertise supply high-volume chipsets to anchor manufacturers, while open-source software providers reduce customer integration costs. Three archetypes dominate: RF component specialists, positioning software platforms, and integrated hardware-systems vendors. Competitive moves concentrate on strategic partnerships with automotive tier-1 suppliers and direct procurement relationships with large warehouse operators that bypass traditional installation contractors.
Among RF-focused semiconductor suppliers, Qorvo exemplifies the component-specialist archetype through its front-end expertise. Pozyx occupies a position within the European software-centric tier, anchoring regional presence through positioning stack offerings. SKYLAB M&C Technology represents the cost-optimized Asian module segment, sitting within the volume-driven fabrication tier that serves price-sensitive deployments.
| Leading Market Players |
|---|
| Sewio |
| Pozyx |
| Qorvo |
| Zebra Technologies |
| NXP Semiconductors |
| SKYLAB M&C Technology |
| Gruppo Filippetti |
| Kinexon |
| Minew |
| Others |
Value Network & Pricing Analysis
RF front-end component concentration in Taiwan and South Korea feeds directly into margin capture by semiconductor vendors supplying anchor manufacturers, while downstream hardware vendors face pressure to absorb spectral compliance costs without passing full burden to logistics buyers.
Pricing Analysis
Cost-plus contracts with RF chipset indexation dominate procurement between anchor manufacturers and semiconductor suppliers. Pricing stratifies across industrial-grade, commercial-grade, and module-only tiers, with CE marking and FCC Part 15 certification levels driving differentiation. Cost compression in commercial-grade hardware is intensifying because Shenzhen module vendors are flooding Asian markets with uncalibrated units. Logistics operators in European port facilities show least price sensitivity due to operational savings from mobile anchor flexibility, while South Korean smart home developers remain most sensitive to per-unit costs.
Supply Chain Analysis
Supplier-financing facilities extended by Taiwanese foundries allow anchor module vendors to manage 90-day payment cycles without liquidity strain. Manufacturing concentrates in China, Taiwan, and Germany, with the Pearl River Delta housing final assembly and Stuttgart-Baden-Württemberg anchoring precision filter production. The supply chain draws from specialized 3.1–10.6 GHz antenna substrates, burst-gating ASICs, and synchronized clock sources. Single-source vulnerability around Qorvo's RF front-end designs creates concentration risk for tier-2 anchor vendors. Distribution runs through direct procurement relationships with Amazon, DHL, and BMW-scale end users that bypass traditional systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UWB anchor market sits in early-cycle expansion as IEEE 802.15.4z standardization unlocks interoperability-driven replacement demand across installed proprietary infrastructure.
For Market Incumbents: Insulate hardware margin pools by deepening captive production of spectral-shaping circuits in Germany and Taiwan, reducing exposure to single-source RF front-end pricing. Pre-certify next-generation designs under draft ETSI EN 302 567 revisions before formal adoption to lock out smaller competitors facing six-to-nine month CE marking delays. Bluetooth AoA substitution in retail verticals threatens pricing power in consumer-adjacent segments. For New Entrants and Emerging Players: Pursue white-space opportunities in mobile anchor configurations for warehouse operators seeking seasonal reconfiguration without construction overhead. Healthcare verticals in multi-story hospital complexes show lowest competitive density for Time Difference of Arrival architectures. A software-first go-to-market bundling open-source positioning stacks with hardware modules reduces customer integration friction and accelerates procurement cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European positioning software platforms that have scaled recurring calibration revenue but lack RF hardware capabilities. The five-to-ten year viability thesis rests on UWB penetration expanding from industrial asset tracking into automotive digital key and consumer device ecosystems. Monitor METI spectrum allocation decisions as the signal for Japanese market acceleration and corresponding valuation multiple expansion for Asia-exposed vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Silicon Integration | Unified die architectures combining UWB with Bluetooth Low Energy collapse cost barriers for automotive tier-1 suppliers. |
| Open-Source Positioning Stack Adoption | Amazon and DHL procurement mandates disintermediate traditional RTLS installation contractors. |
| Pre-Certification Under Draft ETSI Standards | BMW and Mercedes-Benz suppliers avoid production line disruptions from regulatory timeline uncertainty. |
| Mobile Anchor Battery Optimization | Rotterdam logistics hubs enable seasonal reconfiguration without infrastructure overhaul costs. |
| Healthcare TDOA Architecture Deployment | Massachusetts hospital networks achieve floor-level patient tracking precision for emergency workflow optimization. |
Research Methodology
Desk research of FCC Part 15 filings, ETSI EN 302 567 draft specifications, and MIIT SRRC certification databases preceded structured interviews with RF front-end engineering directors, warehouse operations technology leads, and hospital biomedical systems managers. Primary fieldwork with anchor manufacturers in Shenzhen, Stuttgart, and San Diego validated secondary data on bill-of-materials cost structures. SEC filings from Qorvo and NXP Semiconductors, alongside customs records of UWB module trade flows, supported bottom-up unit shipment estimates triangulated against top-down RTLS market sizing.
Assumptions around IEEE 802.15.4z adoption velocity and METI spectrum allocation timelines were held fixed across baseline scenarios, while mobile anchor penetration rates and healthcare vertical expansion were varied in sensitivity testing. The analytical framework modeled product type, application precision tier, technology architecture, and end-user vertical across the projection horizon. CAGRs were derived from installed base growth and replacement cycle analysis. Forecast inputs included automotive OEM localization specifications and logistics operator warehouse automation capex disclosures.
Sensitivities concentrate around regulatory timeline shifts, Bluetooth AoA substitution acceleration, and RF front-end supply concentration. Forecasts reflect documented assumptions on standardization convergence and spectrum allocation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Asia-Pacific Inertial Systems Market
Communication Navigation & Surveillance
Navigation Satellite System Technology Market
Communication Navigation & Surveillance
Inertial Navigation System Market
Communication Navigation & Surveillance
Global Military Communications Market
Communication Navigation & Surveillance
Airborne Laser Obstacle Avoidance Monitoring Systems Market
Communication Navigation & Surveillance
Missile Guidance Radar Market
Communication Navigation & Surveillance
Spain Satellite Communications Market
Communication Navigation & Surveillance
Military Antenna Market
Communication Navigation & Surveillance
Surface Radars Market
Communication Navigation & Surveillance
Global Navigation Satellite System (GNSS) Market
Communication Navigation & Surveillance
Land-Based Situational Awareness Systems Market
Communication Navigation & Surveillance
Advanced Surface Movement Guidance and Control System (A-SMGCS) Market
Communication Navigation & Surveillance
Tactical Data Link Market
Communication Navigation & Surveillance
Radar Transmitter Market
Communication Navigation & Surveillance
UK Autonomous Navigation Market
Communication Navigation & Surveillance
Coherent Radar Market