
 Elder Care Products Market | 2026-2036
Elder Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Elder Care Products Market Analysis
Asset-light leasing models for mobility aids and home monitoring equipment is narrowing the competitive field to firms with balance-sheet capacity for fleet financing. Permobil AB leverages Scandinavian manufacturing scale to sustain premium positioning in powered wheelchairs. Koninklijke Philips N.V. anchors its presence through hospital-to-home care transitions in North American and European markets. Sunrise Medical Inc. specializes in configurable seating systems that differentiate its offerings across European reimbursement environments.
Elder care products encompass assistive and therapeutic goods engineered for geriatric physiological parameters, including bariatric load ratings, antimicrobial surface compositions, and battery systems delivering eight-plus hours of continuous operation for powered mobility devices. Their primary commercial purpose centers on sustaining independent living, reducing caregiver burden, and preventing acute clinical episodes among aging populations. Mobility Aids command the largest revenue pool due to durable medical equipment reimbursement structures, while Smart Home Solutions represent the fastest-expanding segment as sensor miniaturization and edge computing enable predictive fall detection. Nutritional Supplements occupy mature growth trajectories in developed markets but extend volume opportunities in emerging economies where protein-energy malnutrition remains prevalent among institutionalized elderly.
FDA Class II device clearances and the EU Medical Device Regulation impose clinical evidence requirements that shape product development budgets and market entry timelines for hearing implants and remote monitoring systems. Japan's METI collaborates with PMDA to streamline approval for AI-enabled fall detection, accelerating domestic adoption while creating reference standards for export markets. Stakeholders must monitor reimbursement code expansions for telehealth-integrated devices as payors recalibrate cost-offset models between institutional and residential care settings.
Market Dynamics
Home care agencies are consolidating procurement around connected monitoring systems, compressing vendor selection criteria toward platforms that integrate FDA-cleared sensors with real-time caregiver dashboards. This procurement concentration is reshaping competitive positioning toward firms with balance-sheet capacity for fleet financing and regulatory compliance infrastructure.
Growth Catalysts
- Japan's METI-PMDA Collaboration:Streamlined approval pathways for AI-enabled fall detection devices accelerate domestic adoption and establish reference standards for export markets.
- Hospital-to-Home Care Transitions:North American and European reimbursement shifts favor remote patient monitoring systems that reduce readmission penalties.
- Sensor Miniaturization:Edge computing advances enable predictive analytics on battery-powered devices without cloud dependency, expanding deployment in rural residential settings.
Market Restraints
- EU Medical Device Regulation Clinical Evidence Requirements:Hearing implants and remote monitoring systems face extended development budgets and market entry timelines.
- Lithium-Ion Battery Supply Concentration:Powered mobility device manufacturers face input cost volatility tied to cathode material processing in East Asian supply chains.
- Class II Device Clearance Compression:FDA 510(k) pathway scrutiny for predicate device equivalence creates regulatory friction for incremental product iterations.
Strategic Opportunities
- Asset-Light Leasing Models:Mobility aid fleet financing creates white space for balance-sheet-capable firms to capture recurring revenue streams.
- Telehealth-Integrated Device Reimbursement Expansions:US payor cost-offset model recalibration between institutional and residential care settings favors connected therapeutic goods.
- Protein-Energy Malnutrition Addressability:Nutritional supplement volume opportunities extend in emerging economies where institutionalized elderly populations remain underserved.
Industry Challenges
- Antimicrobial Surface Certification Complexity:ISO 22196 testing protocols and EPA registration requirements for medical device coatings extend product qualification timelines.
- Interoperability with Legacy Electronic Health Records:HL7 FHIR integration demands specialized health informatics talent scarce among mid-tier device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elder Care Products Market |
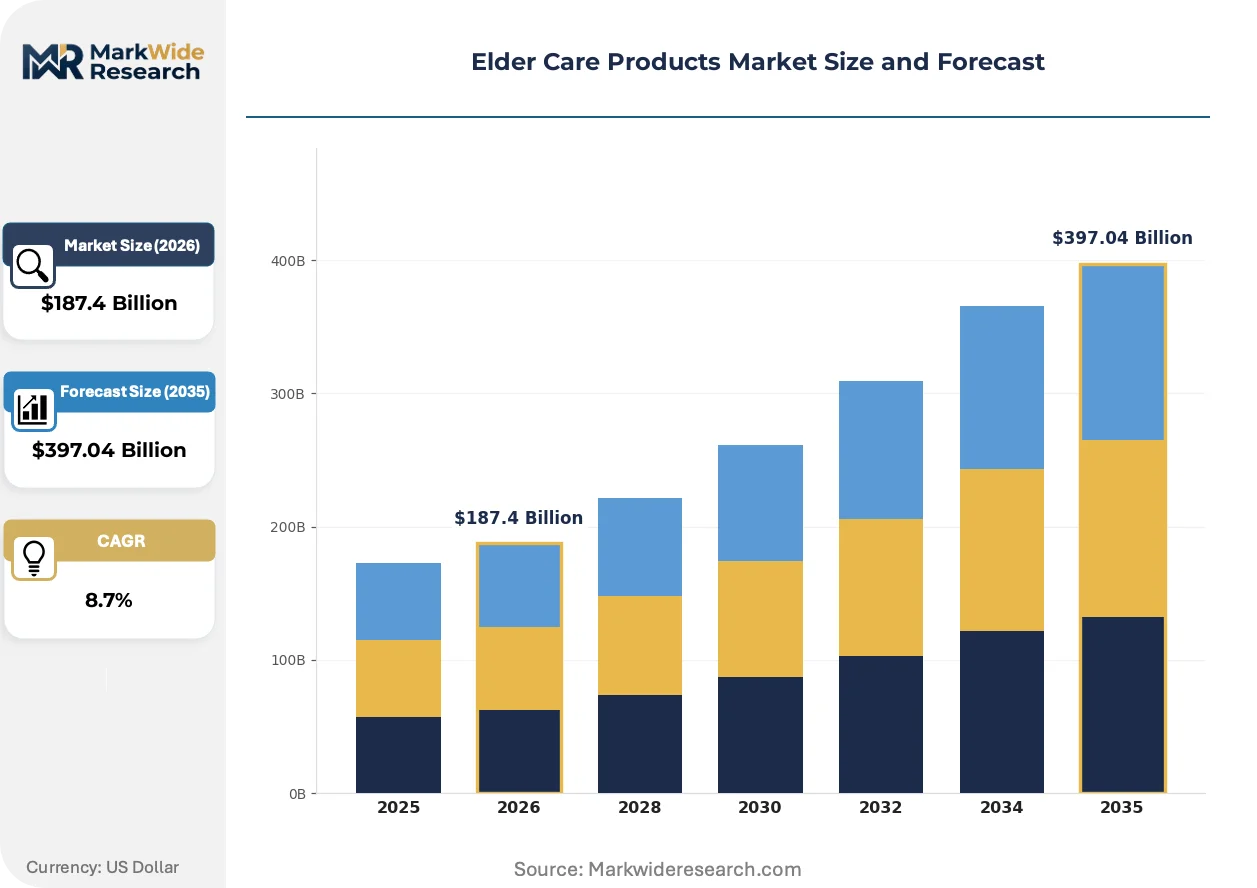
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobility Aids, Incontinence Products, Home Monitors, Nutritional Supplements End User: Residential Care Facilities, Home Care Agencies, Hospitals, Individual Consumers Technology: Assistive Devices, Smart Home Solutions, Telehealth Systems, Medication Management Software Application: Daily Living Assistance, Health Monitoring, Rehabilitation Services, Safety Solutions |
| Companies Covered | Invacare Corporation, Permobil AB, Koninklijke Philips N.V., Cochlear Limited, Pride Mobility Products Corporation, Stryker Corporation, Sunrise Medical Inc., GN Store Nord A/S, Sonova Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elder Care Products Market Emerging Trajectories
Edge computing architectures are migrating predictive analytics capabilities onto battery-constrained devices, eliminating latency dependencies that previously tethered fall detection systems to residential broadband infrastructure.
Sensor fusion algorithms are migrating from cloud-based processing to on-device inference engines, enabling sub-100-millisecond response times for emergency alerts. Home care agencies in Japan and Germany are piloting these systems for nighttime monitoring where connectivity gaps previously created liability exposure. The technology is migrating from premium institutional installations toward standard equipment configurations in consumer-facing residential products.
Japan's PMDA has established a dedicated review pathway for AI-enabled medical devices, compressing approval timelines for software-as-a-medical-device products that demonstrate post-market performance monitoring capabilities. Domestic manufacturers are leveraging this regulatory clarity to secure early-mover positioning in fall detection and medication adherence monitoring. European competitors are adapting submission dossiers to mirror Japan's evidentiary standards for export market access.
Caregiver procurement committees are consolidating vendor relationships around platforms offering integrated device fleets with unified service contracts, displacing the historical model of point-solution purchasing. Home care agencies in the Netherlands and Scandinavian markets are negotiating multi-year equipment leases that bundle maintenance, software updates, and regulatory recertification. This concentration is visible most acutely in powered wheelchair and pressure-relief mattress categories where total cost-of-ownership calculations now dominate selection criteria.
Elder Care Products Market Segmentation
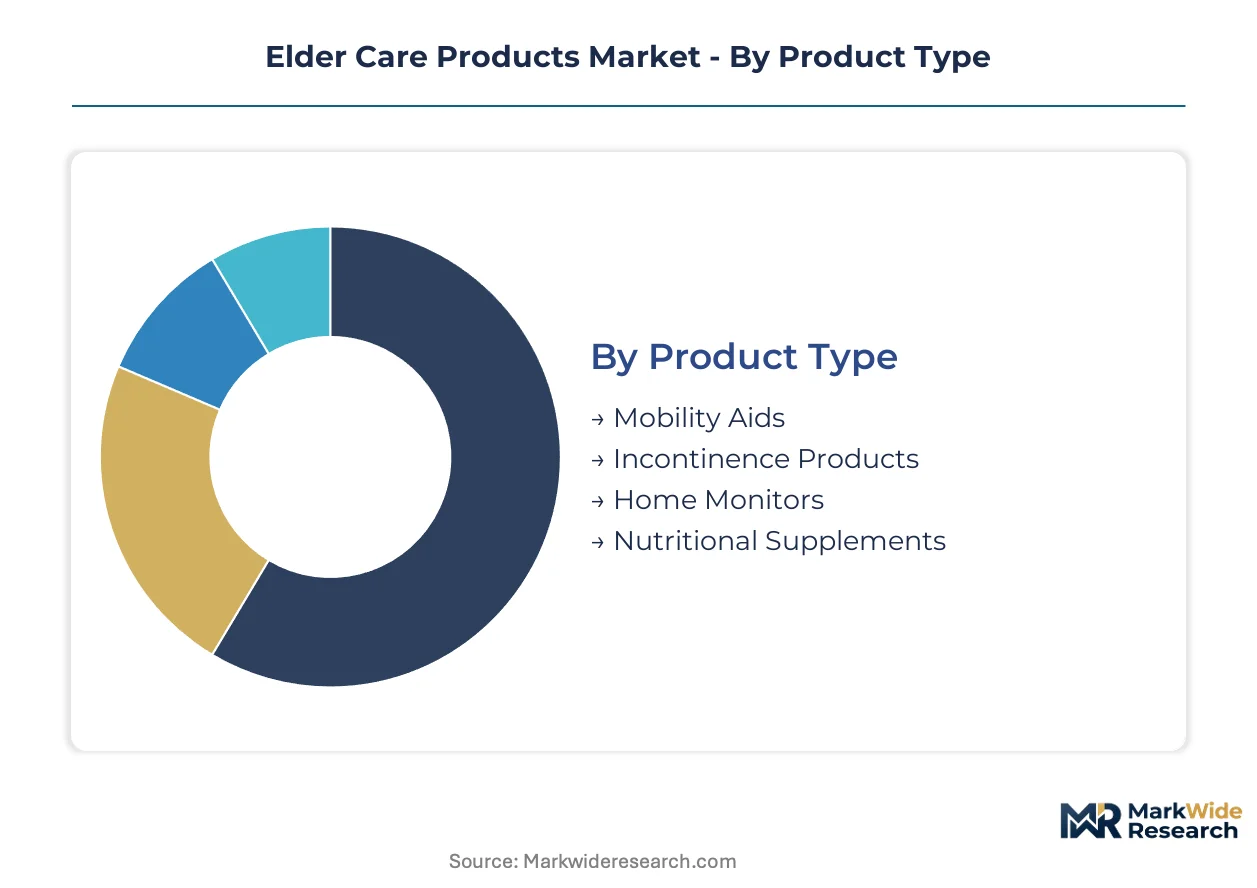
Segmentation in elder care products reveals stark disparities in replacement cycles and capital intensity. Mobility aids and home monitors operate on multi-year depreciation schedules, while consumable categories turn over monthly. Procurement committees weight these rhythms differently when negotiating vendor contracts.
Product Type:
Mobility Aids stretch capital budgets across five-to-seven-year depreciation horizons, whereas Incontinence Products rotate through inventory in thirty-day cycles. This divergence in asset velocity shapes supplier financing terms and distributor warehousing strategies.
- Mobility Aids:Powered wheelchairs and configurable seating systems incorporate bariatric load ratings and eight-hour battery systems engineered for geriatric physiological parameters. Japanese hospitals and German residential care facilities concentrate procurement around Scandinavian-manufactured platforms that bundle maintenance contracts with regulatory recertification. FDA Class II clearance pathways compress development timelines for incremental product iterations.
- Home Monitors:Sensor fusion architectures migrate predictive analytics onto battery-constrained devices, eliminating cloud dependency for fall detection in rural Japanese residential settings. METI-PMDA streamlined approval pathways accelerate domestic adoption while establishing reference standards for export markets. Edge computing advances enable sub-100-millisecond emergency alert response times.
- Incontinence Products:Absorbent hygiene items with antimicrobial surface compositions rotate through institutional procurement on monthly replenishment cycles tied to infection control protocols.
- Nutritional Supplements:Protein-energy formulations address malnutrition prevalence among institutionalized elderly in emerging economies where reimbursement infrastructure remains underdeveloped.
Mobility Aids dominate installed base value. Home Monitors are where expansion concentrates.
End User:
Cost tier stratification separates capital-intensive institutional purchasers from price-sensitive individual consumers. Home Care Agencies occupy the middle tier, consolidating procurement around connected platforms with unified service contracts.
- Home Care Agencies:Fleet financing capacity and regulatory compliance infrastructure determine competitive positioning as procurement committees consolidate vendor relationships around integrated device platforms. Dutch and Scandinavian markets negotiate multi-year equipment leases bundling maintenance, software updates, and EU MDR recertification. Real-time caregiver dashboards with FDA-cleared sensors compress vendor selection criteria.
- Residential Care Facilities:Pressure-relief mattresses and nighttime monitoring systems concentrate demand in Japan and Germany where liability exposure from connectivity gaps drives sensor fusion adoption. Total cost-of-ownership calculations dominate selection criteria across powered wheelchair categories.
- Hospitals:North American reimbursement shifts favor remote patient monitoring systems that reduce readmission penalties during acute-to-residential care transitions.
- Individual Consumers:Out-of-pocket expenditure limits concentrate demand in basic assistive devices outside reimbursement umbrella coverage.
Residential Care Facilities anchor equipment revenue. Home Care Agencies are climbing the fastest as procurement consolidation accelerates.
Technology:
Application maturity separates legacy assistive hardware from software-enabled platforms requiring specialized health informatics talent for EHR integration.
- Smart Home Solutions:Predictive fall detection systems leverage sensor miniaturization and edge computing to expand deployment in broadband-constrained rural residential settings. Japan's PMDA dedicated review pathway compresses approval timelines for software-as-a-medical-device products with post-market performance monitoring capabilities. European competitors adapt submission dossiers to mirror Japanese evidentiary standards.
- Telehealth Systems:HL7 FHIR integration demands scarce health informatics expertise among mid-tier device manufacturers, creating capability gaps in interoperability with legacy electronic health records. US payor cost-offset model recalibration between institutional and residential care settings favors connected therapeutic goods.
- Assistive Devices:Mechanical mobility platforms and daily living tools operate within established durable medical equipment reimbursement codes without connectivity requirements.
- Medication Management Software:AI-enabled adherence monitoring secures early-mover positioning through regulatory clarity in Japanese export markets.
Assistive Devices dominate shipment volume. Smart Home Solutions are gaining share fastest as edge computing eliminates latency dependencies.
Application:
Customer workflow integration separates acute intervention categories from preventive maintenance segments with recurring revenue potential.
- Daily Living Assistance:Configurable seating systems and adaptive utensils address functional decline progression across European reimbursement environments with varying documentation requirements. Sunrise Medical specializes in modular platforms that differentiate offerings through rapid customization turnaround.
- Health Monitoring:Remote patient monitoring systems capture hospital-to-home care transitions in North American markets where readmission penalties drive institutional procurement concentration. Philips anchors presence through integrated device fleets spanning acute and residential settings.
- Rehabilitation Services:Therapeutic equipment procurement ties to episodic care reimbursement with irregular replacement cycles.
- Safety Solutions:Fall detection and emergency response systems concentrate in Japanese residential installations where METI promotes age-tech integration.
Daily Living Assistance dominates installed base. Health Monitoring is where expansion concentrates as reimbursement shifts accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI age-tech subsidies and Germany's hospital-to-home reimbursement shifts are accelerating procurement of connected elder care systems. These policy frameworks are compressing vendor selection criteria toward integrated platforms with regulatory compliance infrastructure.
Japan
Domestic demand concentrates in AI-enabled fall detection and medication adherence monitoring. PMDA's dedicated review pathway for software-as-a-medical-device products compresses approval timelines for domestic manufacturers. Tokyo and Osaka industrial clusters anchor production of sensor fusion systems for export markets.
Germany
Residential care facilities drive procurement of pressure-relief mattresses and nighttime monitoring systems. EU Medical Device Regulation clinical evidence requirements shape development budgets for hearing implants and remote monitoring systems. The Baden-Württemberg region hosts manufacturing scale for configurable seating platforms.
United States
Hospital-to-home care transitions concentrate demand for remote patient monitoring systems that reduce readmission penalties. FDA Class II device clearance pathways compress development timelines for incremental product iterations. Greater Boston and Pacific Northwest clusters specialize in health informatics talent for EHR integration.
Netherlands
Home care agencies negotiate multi-year equipment leases bundling maintenance and regulatory recertification. Reimbursement code expansions for telehealth-integrated devices recalibrate cost-offset models between institutional and residential settings. The Randstad region anchors fleet financing capacity for mobility aid leasing models.
Sweden
Scandinavian manufacturing scale sustains premium positioning in powered wheelchairs with bariatric load ratings and extended battery systems. METI-PMDA regulatory alignment creates export opportunities for AI-enabled devices into Japanese markets. Stockholm-based clusters specialize in antimicrobial surface compositions for medical device coatings.
Elder Care Products Market Vendor Landscape
On the supply side, the industry is tiered between balance-sheet-capable fleet financiers, specialized seating configurators, and integrated health technology platforms. Scandinavian and Dutch manufacturers anchor premium mobility segments through manufacturing scale and multi-year service contracts. Three archetypes dominate: asset-light leasers with financing infrastructure, sensor-integrated platform providers, and configurable seating specialists. Competitive moves concentrate on procurement consolidation through unified service contracts and regulatory recertification bundling.
Among the named participants, Permobil AB and Sunrise Medical Inc. exemplify the manufacturing-scale archetype with Scandinavian and European positioning respectively, while Koninklijke Philips N.V. occupies the integrated health technology tier spanning hospital-to-home transitions. These three entities represent distinct competitive vectors: manufacturing depth, configurability specialization, and platform integration.
| Leading Market Players |
|---|
| Invacare Corporation |
| Permobil AB |
| Koninklijke Philips N.V. |
| Cochlear Limited |
| Pride Mobility Products Corporation |
| Stryker Corporation |
| Sunrise Medical Inc. |
| GN Store Nord A/S |
| Sonova Holding AG |
| Others |
Supply Flow & Price Mechanics
Lithium-ion cathode material processing concentration in East Asian supply chains determines both pricing tier spreads and supply chain shape for powered mobility devices, compressing margins on battery-dependent products while amplifying cost advantages for manufacturers with captive cell supply.
Pricing Analysis
Certification level creates the primary spread across FDA Class II, EU MDR CE-marked, and uncertified consumer tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with FDA-grade devices commanding substantial premiums over ISO 22196-tested alternatives. Price differentiation hinges on antimicrobial surface validation and battery system endurance ratings. Cost compression in economy tiers intensifies because home care agencies consolidate procurement around bundled service contracts. Individual consumers exhibit highest price sensitivity, while Dutch and Scandinavian institutional purchasers prioritize total cost-of-ownership over unit pricing.
Supply Chain Analysis
Scandinavian contract manufacturers and German precision engineering firms hold dominant capacity for configurable seating systems and powered wheelchair platforms. Manufacturing concentrates in Sweden, Germany, and the Netherlands for premium mobility equipment, while sensor assembly feeds from Japanese and South Korean electronics clusters. Raw material dependencies span lithium carbonate for battery systems, medical-grade aluminum alloys for frame construction, and antimicrobial coating compounds. Single-source vulnerability runs through East Asian cathode material suppliers. Distribution runs through specialized durable medical equipment distributors with GPO contracts and direct hospital system relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized health informatics talent scarcity constrains mid-tier device manufacturers attempting HL7 FHIR integration, creating acquisition premiums for firms with proven EHR interoperability capabilities.
For Market Incumbents: Build regulatory compliance infrastructure as a moat against emerging sensor-integrated platform providers. Expand fleet financing capacity to capture Dutch and Scandinavian multi-year equipment lease contracts before competitors secure procurement consolidation. Deepen backward integration into battery system assembly to offset cathode material cost volatility from East Asian supply chains. For New Entrants and Emerging Players: Build out protein-energy nutritional supplement distribution networks in emerging economies where institutionalized elderly populations remain underserved by reimbursement infrastructure. Target Japanese residential care facilities with AI-enabled fall detection devices leveraging PMDA's streamlined software-as-a-medical-device pathway. Pursue white-label manufacturing partnerships with Scandinavian OEMs to bypass capital-intensive fleet financing requirements. For Investors and Strategic Acquirers: FDA 510(k) pathway scrutiny for predicate device equivalence reshapes the acquisition landscape toward targets with cleared device portfolios and established predicate relationships. Five-to-ten-year viability favors firms with balance-sheet capacity for asset-light leasing models and regulatory recertification bundling. Monitor EU MDR clinical evidence requirement enforcement as inflection signal for hearing implant and remote monitoring system development budget escalations.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Bundling | Compresses vendor selection criteria toward integrated platform providers with compliance infrastructure. |
| Software-as-a-Medical-Device Development | Captures PMDA streamlined approval pathway for AI-enabled fall detection in Japanese export markets. |
| Hospital System Partnership | Secures acute-to-residential care transition revenue through remote patient monitoring system integration. |
| Reimbursement Strategy Investment | Aligns telehealth-integrated device portfolios with US payor cost-offset model recalibration. |
| Antimicrobial Surface Certification | Extends product qualification timelines but creates differentiation against uncertified competitors. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with hospital purchasing committees, home care agency procurement directors, biomedical engineers, and GPO contracts managers; and secondary validation through FDA 510(k) filings, EU MDR submission databases, CMS Medicare reimbursement code updates, and hospital procurement system records. Bottom-up triangulation across equipment shipment data and top-down reconciliation against durable medical equipment expenditure reports anchored volume estimates.
Forecast inputs span mobility aid depreciation cycles, home monitor sensor replacement rates, and nutritional supplement consumption patterns across institutional and residential settings. Segmentation dimensions modeled include product type, end-user category, technology maturity tier, and application workflow integration. CAGRs were derived from regression analysis of historical procurement data and policy-driven reimbursement shifts. Edge computing adoption curves and METI-PMDA regulatory alignment timelines informed technology segment projections across the analysis window.
Stress conditions across lithium supply chain disruptions, FDA clearance timeline extensions, and EU MDR clinical evidence cost escalations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement code expansions and fleet financing availability. Quarterly review of PMDA approval velocity and home care agency procurement consolidation indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Global Home Health Care Services Market
Home Healthcare
Homecare Oxygen Concentrators Market
Home Healthcare
Global Health Caregiving Market
Home Healthcare
Elderly Care Apps Market
Home Healthcare
Europe Home Care Market
Home Healthcare
Global Elderly Care Market
Home Healthcare
Elder Care Subscription Market
Home Healthcare
US Home Healthcare Market
Home Healthcare
Global Home Infusion Therapy Market
Home Healthcare
Global Home Healthcare Software Market
Home Healthcare
Virtual Companion Care Market
Home Healthcare
Portable Toilet for Elderly Market
Home Healthcare
Home Care Service Market
Home Healthcare
US Home Healthcare Services Market
Home Healthcare
Smart Mattress Market
Home Healthcare
Global Home Health Hub Market