

Outbound Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Outbound Logistics Market Insights
Truck driver shortages across North America and Europe are unwinding traditional capacity models and forcing network redesigns. DHL Supply Chain leverages its dedicated delivery infrastructure to lock in pharmaceutical and automotive contracts. FedEx sustains premium positioning through express delivery density in intra-continental corridors. United Parcel Service anchors its outbound logistics footprint with integrated warehousing and final-mile technology investments.
Outbound logistics encompasses the planning, execution, and control of product flows from manufacturing or distribution points to end customers, typically requiring coordination across multimodal transport with delivery windows measured in hours for express segments and days for standard freight. Its primary purpose is to fulfill customer orders while minimizing total landed cost and inventory exposure across the supply chain. Maritime and air freight modes capture the highest value per shipment in intercontinental lanes, while truck transport dominates volume in regional distribution. Third-party logistics providers are absorbing freight brokerage functions as shippers seek consolidated accountability, and transportation management systems are becoming the default control layer for manufacturers managing complex supplier networks.
The EPA in the United States enforces emissions standards that compel fleet operators to accelerate alternative-fuel vehicle adoption, while the EU Green Deal and F-Gas Regulation in Europe mandate progressive carbon intensity reductions for commercial transport. These frameworks shape demand by restricting market access for non-compliant carriers and redirecting procurement toward certified low-emission logistics partners. Stakeholders must monitor regulatory phase-in timelines and assess whether captive fleet investment or outsourced green logistics partnerships offer superior compliance economics.
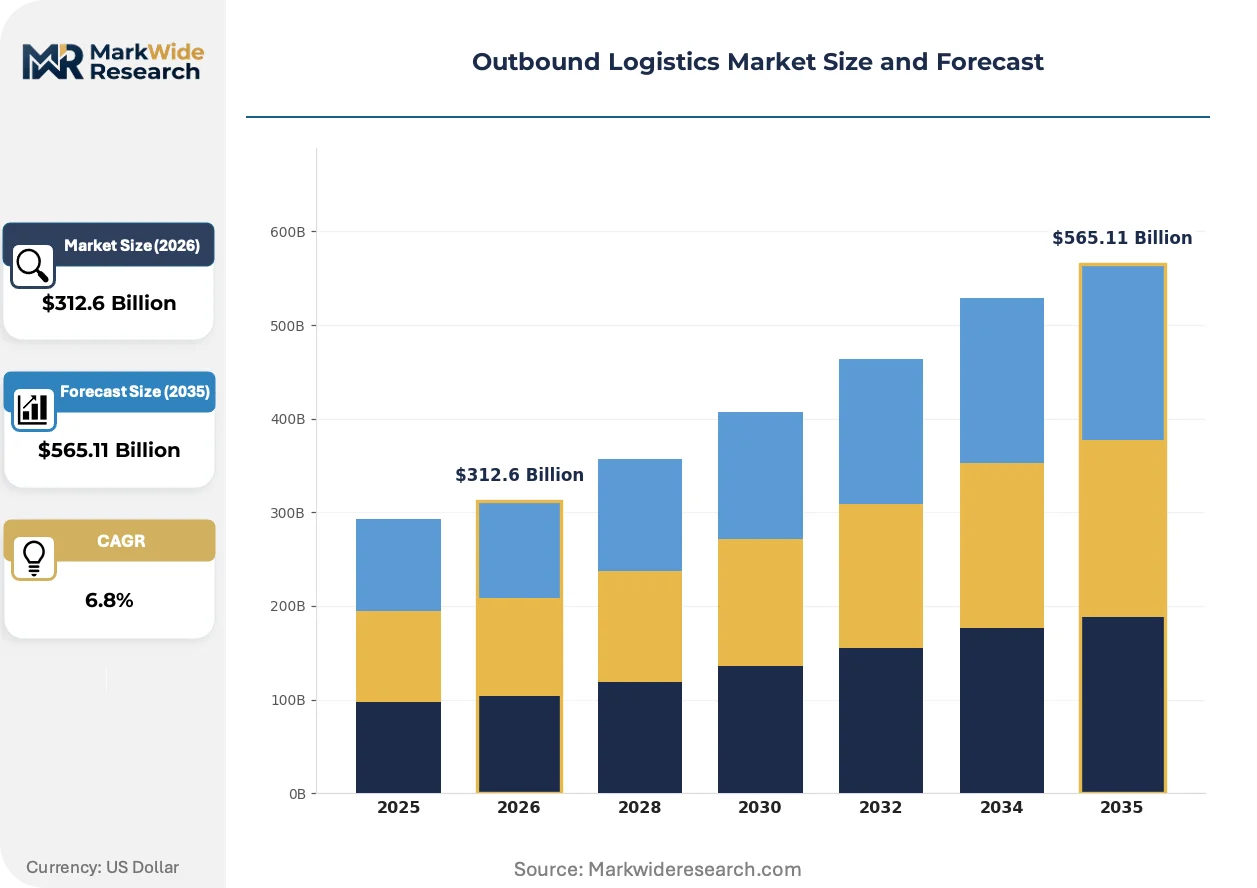
Market Dynamics
EU Green Deal emissions standards are forcing fleet operators across Europe to retire diesel assets prematurely and restructure contract economics around alternative-fuel vehicle procurement.
Growth Catalysts
- E-commerce fulfillment velocity:Same-day and next-day delivery promises from retail platforms are pulling investment into dedicated last-mile networks and micro-fulfillment infrastructure.
- EU Green Deal phase-in:Progressive carbon intensity mandates for commercial transport are redirecting shipper procurement toward certified low-emission logistics partners with compliant fleets.
- Pharmaceutical cold chain expansion:Temperature-sensitive biologics distribution is demanding validated packaging, real-time monitoring, and redundant lane configurations across intercontinental corridors.
Market Restraints
- Truck driver shortage:Demographic contraction in licensed commercial drivers across Germany, France, and the United States is compressing available capacity and inflating spot market rates.
- Alternative-fuel vehicle cost premium:Electric and hydrogen-powered commercial trucks carry 40-60% higher capital costs than diesel equivalents, straining fleet replacement cycles.
- Charging infrastructure gaps:Inconsistent high-power charging networks along major freight corridors limit operational range for battery-electric long-haul configurations.
Strategic Opportunities
- India manufacturing corridor development:Dedicated freight corridors and industrial cluster formation around Gujarat and Tamil Nadu are creating demand for integrated third-party logistics services.
- Carbon border adjustment mechanisms:EU CBAM implementation is incentivizing exporters to secure low-emission logistics certification for scope 3 emissions reporting.
- Autonomous yard operations:Convergence of computer vision and vehicle telematics is enabling unmanned trailer repositioning and gate automation at distribution centers.
Industry Challenges
- Telematics integration complexity:Legacy transportation management systems require expensive API reconfiguration to ingest real-time vehicle data streams from heterogeneous fleet compositions.
- Driver retention and training:Commercial driver academies face enrollment shortfalls while existing workforces require reskilling on electric vehicle operation and battery management protocols.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outbound Logistics Market Trends and Innovations
Digital freight platforms and predictive routing algorithms are compressing planning cycles from days to hours, while sustainability certification is becoming a contract qualification threshold rather than a value-added option.
Dynamic freight matching platforms using machine learning-based capacity prediction are supplanting traditional freight brokerage relationships in spot market procurement. Mid-sized manufacturers with volatile shipping volumes are adopting these platforms fastest, drawn by reduced tender lead times and transparent pricing. The structural consequence is margin compression for conventional broker networks that lack algorithmic pricing capabilities.
The EPA's phased emissions standards for heavy-duty vehicles are compelling fleet operators to accelerate zero-emission truck procurement ahead of total cost parity timelines. Operators serving California ports face the most compressed compliance deadlines under the state's Advanced Clean Trucks regulation. This pressure is fragmenting fleet homogeneity as carriers blend diesel, battery-electric, and hydrogen assets to maintain service coverage.
Shippers are unbundling transportation procurement from warehousing contracts, reversing the integrated 3PL model that dominated the past decade. Automotive and industrial manufacturers in Germany are leading this shift, separating lane-specific rate negotiations from fixed-site logistics agreements. The separation enables more granular carbon accounting and supplier performance scorecarding at the shipment level.
Outbound Logistics Market Segmentation
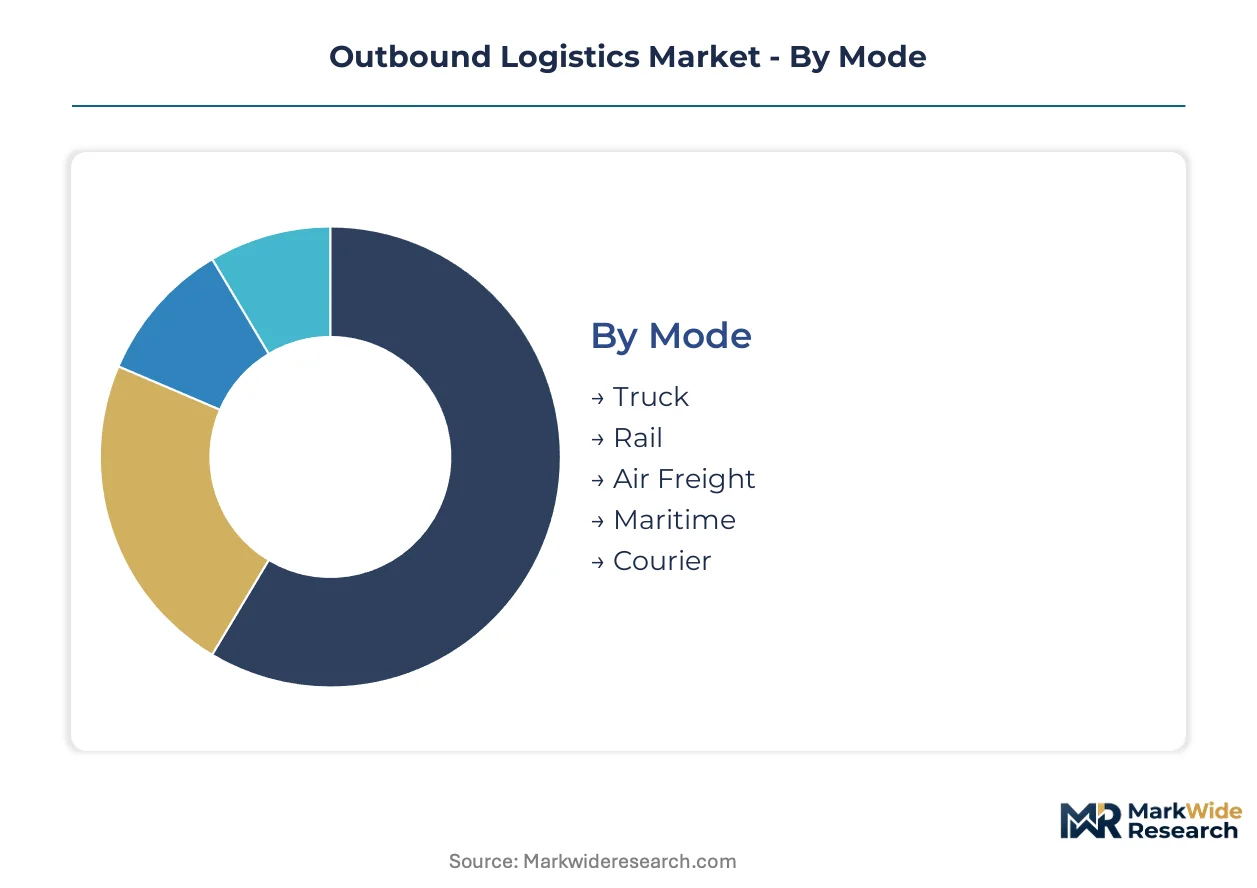
Outbound logistics segmentation reveals where capital is concentrating and which service configurations face displacement from alternative fulfillment models. Mode and service type choices determine carbon exposure, contract tenure, and margin structure for logistics providers across end-use verticals.
Mode:
Rail and coastal shipping exert the strongest substitution pressure on long-haul trucking as fuel costs and emissions regulations tighten.
- Truck:Dominates regional distribution with door-to-door flexibility and rapid terminal turnaround times. German automotive clusters and US Midwest manufacturing corridors depend on dedicated trucking networks for just-in-sequence assembly line feeds.
- Air Freight:Commands premium per-kilogram pricing for time-critical pharmaceutical and electronics shipments. Temperature-controlled biologics distribution from Swissmedic-certified Swiss facilities to US FDA-regulated cold chains drives specialized freighter capacity deployment.
- Rail:Intermodal block trains between Chinese manufacturing hubs and European distribution terminals offer cost-efficient alternatives to maritime-air combinations for mid-urgency cargo.
- Maritime:Containerized ocean freight carries the highest absolute tonnage in intercontinental lanes, with port congestion at Los Angeles-Long Beach and Rotterdam creating schedule reliability challenges.
- Courier:Parcel networks optimized for sub-30-kilogram shipments integrate first-mile pickup with last-mile residential delivery, capturing e-commerce return flows as a revenue stream.
Truck transport anchors the volume base while air freight gains share at the steepest rate on pharmaceutical and high-value electronics corridors.
Service Type:
Margin structures diverge sharply between asset-heavy dedicated operations and asset-light brokerage intermediation.
- Third-Party Logistics:Integrated 3PL contracts bundle transportation, warehousing, and value-added services under single accountability. DHL Supply Chain and similar operators leverage dedicated delivery infrastructure to lock in automotive and pharmaceutical clients requiring validated lane configurations.
- Express Delivery:Time-definite services with delivery windows measured in hours command 3-5x standard freight rates. Intra-European express corridors from Cologne-Bonn and Paris-Charles de Gaulle hubs sustain FedEx premium positioning through network density.
- Dedicated Delivery:Captive fleet and driver assignments for single-shipper accounts eliminate co-loading complexity but require minimum volume commitments to justify asset utilization.
- Freight Brokerage:Digital platforms using machine learning-based capacity prediction are compressing margins for traditional broker networks lacking algorithmic pricing capabilities.
- Warehousing:Distribution center operations are unbundling from transportation contracts in Germany, enabling granular carbon accounting at the shipment level.
Third-party logistics providers capture the broadest contract base while express delivery climbs fastest on e-commerce velocity requirements.
Customer Type:
Procurement sophistication varies dramatically between industrial manufacturers with captive logistics teams and fragmented retail networks.
- E-commerce Platforms:Same-day and next-day delivery promises pull investment into micro-fulfillment infrastructure and dedicated last-mile networks with real-time inventory positioning.
- Manufacturers:Automotive and industrial producers in Germany's Baden-Württemberg and Bavaria clusters require integrated inbound-outbound coordination for just-in-sequence production feeds.
- Retailers:Omnichannel fulfillment demands merge store replenishment with direct-to-consumer parcel flows, complicating inventory allocation across network nodes.
- Distributors:Wholesale intermediaries consolidate fragmented supplier outputs into full-truckload shipments for downstream retail and foodservice accounts.
- Wholesalers:Bulk commodity handlers prioritize cost per ton over transit speed, favoring rail and maritime modes with extended planning horizons.
Manufacturers anchor contract value through integrated supply chain requirements while e-commerce platforms expand most quickly on consumer delivery promise escalation.
Technology:
Control layer investments determine which operators can ingest heterogeneous data streams from blended diesel, battery-electric, and hydrogen fleets.
- Transportation Management System:TMS platforms serve as the default control layer for manufacturers managing complex supplier networks, requiring expensive API reconfiguration to ingest real-time vehicle data from legacy fleet compositions.
- Fleet Telematics:Real-time vehicle location, fuel consumption, and driver behavior monitoring enable dynamic route adjustment and predictive maintenance scheduling across dispersed asset bases.
- Route Optimization Software:Machine learning algorithms compress planning cycles from days to hours, matching volatile demand patterns against available capacity with transparent pricing.
- Warehouse Management System:WMS integration with yard management enables automated gate scheduling and trailer repositioning at high-throughput distribution centers.
- Autonomous Vehicles:Computer vision and vehicle telematics convergence is enabling unmanned yard operations and gate automation, though regulatory frameworks from NHTSA and national European transport authorities limit highway deployment.
Transportation management systems anchor technology spending while fleet telematics gains share fastest on emissions compliance and driver shortage mitigation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German automotive clusters demand synchronized inbound-outbound coordination, while US e-commerce platforms prioritize velocity over cost. Indian manufacturing corridors favor rail-truck intermodal combinations.
United States
EPA emissions standards for heavy-duty vehicles compel fleet operators toward zero-emission truck procurement ahead of cost parity. The Advanced Clean Trucks regulation in California imposes the most compressed compliance deadlines. Los Angeles-Long Beach port complexes drive dedicated drayage network investment to address chronic congestion.
Germany
EU Green Deal mandates progressively tighten carbon intensity requirements for commercial transport fleets. KBA vehicle certification processes shape alternative-fuel adoption timelines for domestic carriers. Baden-Württemberg and Bavaria automotive clusters require just-in-sequence logistics integration that unbundles warehousing from transportation contracts.
China
Dual carbon goals and MIIT new energy vehicle policies accelerate electric commercial truck deployment along coastal manufacturing belts. NMPA pharmaceutical distribution regulations drive cold chain infrastructure standardization. Yangtze River Delta and Pearl River Delta manufacturing hubs concentrate demand for multimodal export logistics.
India
Dedicated freight corridors and PLI scheme manufacturing incentives generate integrated third-party logistics demand around Gujarat and Tamil Nadu industrial clusters. DGFT export procedures shape documentation and customs brokerage service requirements. Maharashtra's Mumbai-Pune belt anchors pharmaceutical cold chain distribution to regulated markets.
Japan
METI logistics efficiency targets and aging workforce demographics accelerate automation investment in yard operations and warehouse gate management. PMDA pharmaceutical distribution standards mandate validated temperature control for biologics exports. Kanto and Kansai manufacturing belts sustain premium express delivery density for electronics and precision components.
Outbound Logistics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the current market structure. Consolidated 3PL operators with captive warehousing and fleet assets command multi-year contracts from automotive and pharmaceutical manufacturers. Regional express specialists and digital freight platforms occupy distinct competitive positions. Capacity expansion through alternative-fuel fleet procurement and strategic partnerships for last-mile density represent the dominant competitive moves.
Among integrated logistics providers, DHL Supply Chain, FedEx, and United Parcel Service exemplify the asset-heavy archetype that dominates contract logistics and express delivery. These operators anchor their market positions through dedicated infrastructure investments and technology control layers that manage heterogeneous fleet compositions.
| Leading Market Players |
|---|
| DHL Supply Chain |
| FedEx |
| United Parcel Service |
| DSV |
| Kuehne + Nagel |
| DB Schenker |
| CEVA Logistics |
| Expeditors International of Washington |
| Nippon Express Holdings |
| Others |
Pricing and Supply Chain Analysis
Long-term dedicated delivery contracts with minimum volume commitments lock in supply access for automotive and pharmaceutical shippers while providing carriers with predictable revenue streams that offset alternative-fuel fleet procurement premiums. These arrangements concentrate pricing power with integrated 3PL operators holding captive warehousing and fleet assets across German industrial clusters.
Pricing Analysis
Contract-based long-term offtake agreements dominate automotive and pharmaceutical verticals, with price differentiation driven by EU Green Deal certification tier and dedicated fleet asset allocation. Express delivery corridors command substantial premiums over standard freight rates based on network density and time-definite guarantees. Pricing pressure stems from digital freight platforms compressing spot market margins through algorithmic capacity matching. Small and mid-sized manufacturers exhibit highest price sensitivity, while pharmaceutical cold chain operators prioritize validated lane certification over rate minimization.
Supply Chain Analysis
Port congestion at Los Angeles-Long Beach and Rotterdam elevates inbound logistics costs for containerized ocean freight feeding North American and European distribution networks. Supply concentration centers on China for manufacturing exports, Germany for automotive components, and India for pharmaceutical distribution infrastructure. Raw material dependencies include container vessel capacity, chassis availability, and battery-electric truck components. Single-source vulnerability runs through concentrated container shipping alliances. Distribution runs through hub-and-spoke parcel networks integrated with micro-fulfillment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large e-commerce platforms and automotive OEMs with captive logistics teams, fragmenting procurement leverage for mid-sized shippers without dedicated supply chain functions.
For Market Incumbents: Shield contract renewals by accelerating EU Green Deal fleet certification ahead of regulatory phase-in deadlines. Deepen backward integration into alternative-fuel vehicle procurement through strategic partnerships with charging infrastructure providers. Lock in pharmaceutical and automotive accounts with validated cold chain and just-in-sequence capabilities that digital freight platforms cannot replicate. For New Entrants and Emerging Players: EU Green Deal certification fast-track services offer entry points for regional specialists targeting mid-sized German manufacturers unbundling warehousing from transportation contracts. White-space exists in autonomous yard operations and last-mile micro-fulfillment infrastructure serving secondary European cities. Pursue asset-light brokerage models with machine learning-based capacity prediction to capture volatile spot market volumes. For Investors and Strategic Acquirers: Regional express specialists with dense intra-European network coverage represent attractive acquisition targets as FedEx and United Parcel Service consolidate premium positioning. Long-term viability hinges on alternative-fuel fleet transition economics and regulatory compliance timelines. Monitor EU carbon border adjustment mechanism implementation as inflection indicator for low-emission logistics certification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative-Fuel Fleet Procurement | EU Green Deal mandates force premature diesel retirement and reshape contract economics. |
| Micro-Fulfillment Infrastructure Deployment | Same-day delivery promises from Amazon and Zalando pull capital into urban last-mile nodes. |
| Digital Freight Platform Integration | Machine learning capacity prediction compresses spot market margins for traditional brokers. |
| Pharmaceutical Cold Chain Certification | Swissmedic and FDA validation requirements drive specialized freighter capacity deployment. |
| Autonomous Yard Operations | Computer vision convergence enables unmanned trailer repositioning at high-throughput distribution centers. |
Research Methodology
Cross-validation between primary interviews with logistics procurement directors, fleet operations managers, and pharmaceutical supply chain leads and secondary validation through customs trade data, EPA emissions filings, and EU transport authority statistics anchors the qualitative findings. Bottom-up triangulation against carrier fleet composition disclosures and top-down reconciliation with industrial production indices ensures coverage consistency. Stakeholder input captured contract structure evolution, regulatory compliance timelines, and technology adoption patterns across multimodal transport configurations.
Sensitivity analysis around EU Green Deal phase-in schedules and alternative-fuel vehicle cost trajectories shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include transport mode, service type configuration, customer procurement sophistication, and technology control layer adoption. CAGRs derive from trend extrapolation against historical fleet investment cycles and regulatory milestone impacts. Forecast inputs incorporate truck driver demographic projections and charging infrastructure deployment timelines along major freight corridors.
Decision-makers should treat outputs as directional under assumptions of progressive emissions regulation enforcement and sustained e-commerce fulfillment velocity escalation; material deviation would warrant model refresh. Specific risks include accelerated EU carbon border adjustment mechanism implementation, breakthrough battery-electric range extension, or autonomous vehicle regulatory approval ahead of baseline assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.