
 Australia Freight and Logistics Market | 2026-2036
Australia Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Freight and Logistics Market Outlook
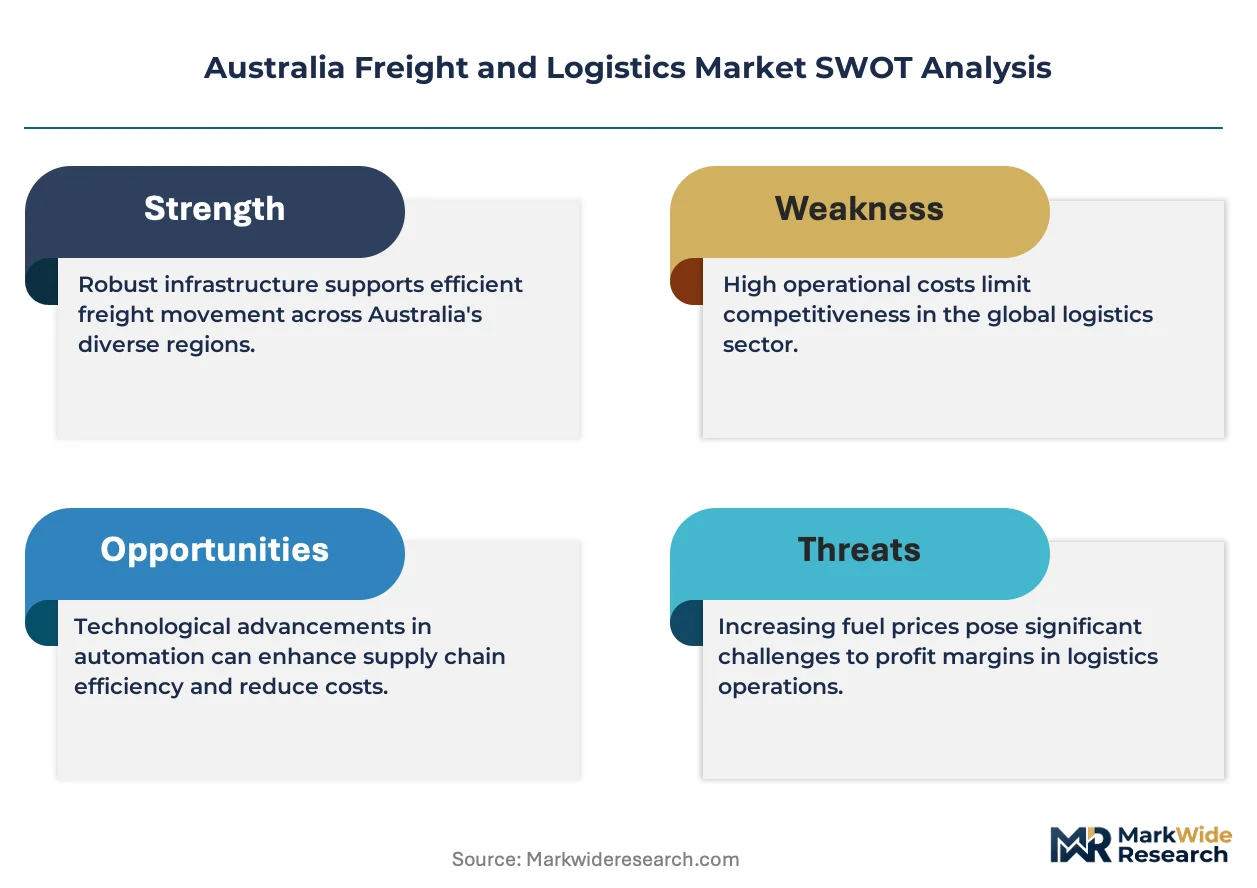
Last-mile delivery margin pools is fragmenting across express, same-day, and scheduled service tiers as e-commerce volume splits between premium speed and cost-optimized options. Toll Group anchors its position through extensive intermodal terminal ownership along the eastern seaboard. Qube dominates bulk and automotive port logistics with specialized stevedoring assets in Port Botany and Port of Melbourne. Linfox sustains competitive differentiation through cold chain infrastructure serving pharmaceutical and perishable grocery clients.
Australia freight and logistics encompasses the physical movement of goods via road, rail, air, and sea modes, supported by warehousing, customs brokerage, and supply chain technology platforms operating across distances exceeding 4,000 kilometers between major population centers. The sector functions as the circulatory infrastructure for Australian trade, connecting import gateways to domestic consumption and export production zones. Road freight absorbs the dominant share of domestic tonnage moved, though rail freight is gaining structural traction on bulk commodity and intermodal corridors where track access reform improves transit economics. E-commerce clients represent the fastest-growing demand pool, with automated scheduling and AI routing technologies becoming baseline requirements for contract retention rather than differentiation.
The National Heavy Vehicle Regulator enforces mass, dimension, and fatigue limits under the Heavy Vehicle National Law, directly constraining fleet productivity and shaping investment in larger high-productivity vehicles. Infrastructure Australia coordinates priority corridor assessments that determine which freight routes receive federal funding for capacity expansion. Stakeholders must weigh exposure to regulatory compliance costs against automation-led productivity gains when evaluating asset deployment across state border networks.
Market Dynamics
The Heavy Vehicle National Law administered by the National Heavy Vehicle Regulator is compressing fleet productivity and forcing capital redeployment toward higher-productivity vehicle configurations across Australia's interstate corridors.
Growth Catalysts
- E-commerce fulfillment infrastructure:Australian retailers are intensifying same-day delivery requirements, pulling investment into automated warehousing and urban micro-fulfillment nodes.
- Track access reform:Rail freight economics are improving on bulk commodity corridors, enabling mode shift from road for containerized agricultural and mineral exports.
- Heavy Vehicle National Law:Compliance obligations are standardizing across state borders, reducing regulatory fragmentation for fleet operators running Sydney-Melbourne-Brisbane routes.
Market Restraints
- Fuel cost volatility:Diesel price exposure constrains margin predictability for long-haul operators dependent on road transport across Australia's vast distances.
- Driver shortage concentration:Heavy vehicle license attainment timelines create recruitment bottlenecks in Queensland and Western Australia mining corridors.
- Intermodal terminal scarcity:Limited rail-head capacity in Adelaide and Perth restricts network optionality for freight forwarders seeking mode flexibility.
Strategic Opportunities
- Perishable cold chain expansion:Pharmaceutical and premium grocery segments offer margin accretive specialization beyond commodity freight.
- Port Botany automation:Stevedoring technology upgrades are creating throughput capacity for automotive and containerized agricultural exporters.
- AI routing convergence:Machine learning platforms combined with telematics are enabling dynamic fleet dispatch that compresses empty running kilometers.
Industry Challenges
- Telematics integration complexity:Legacy fleet management systems resist seamless data exchange with newer IoT sensor networks, delaying real-time visibility deployment.
- Fatigue management certification:Electronic work diary compliance timelines strain smaller operators lacking dedicated compliance personnel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Freight and Logistics Market |
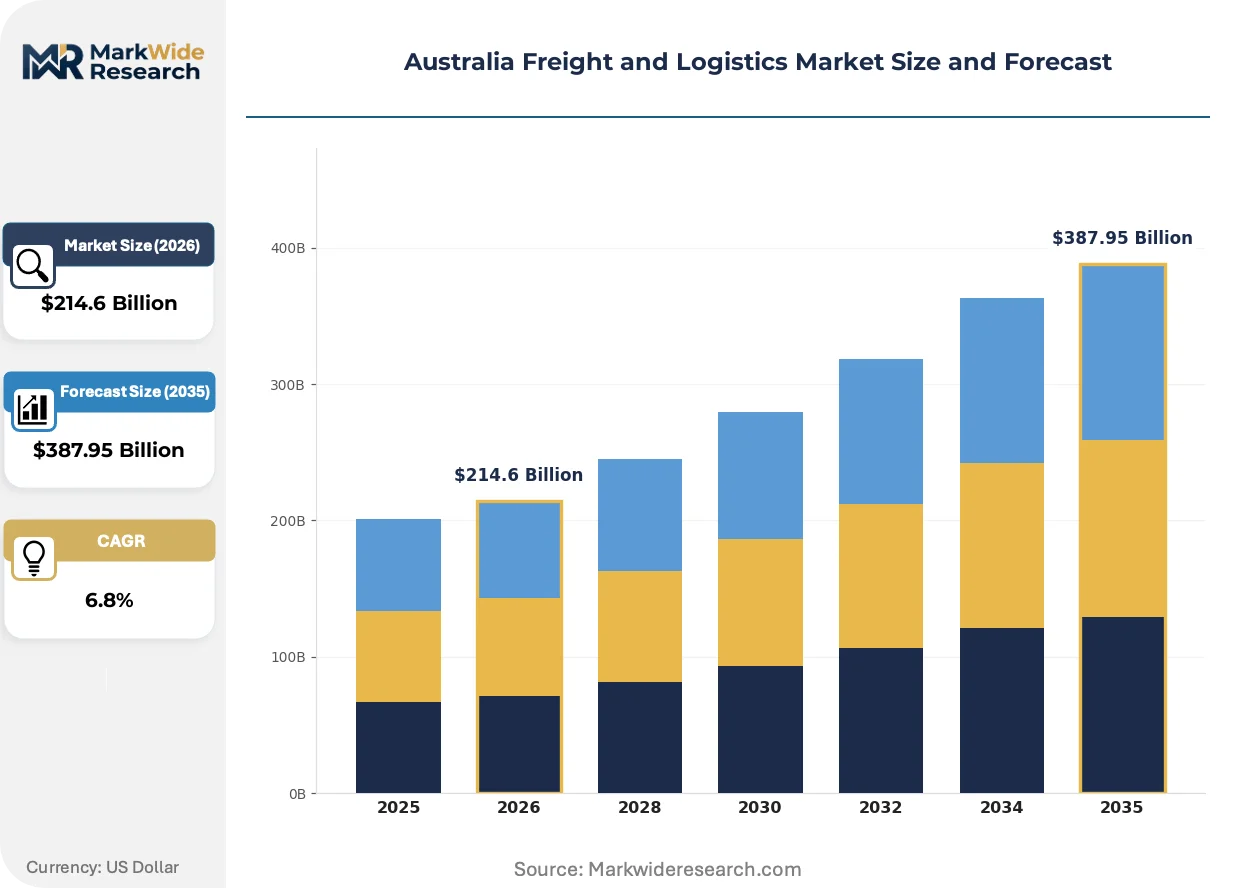
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $387.95 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Road Freight, Rail Freight, Air Freight, Sea Freight Client Type: SMEs, Large Enterprises, Government, E-Commerce Delivery Mode: Standard, Express, Same-Day, Scheduled Technology: GPS Tracking, Automated Scheduling, AI Routing, Cold Chain Solutions |
| Companies Covered | K&S Group, Couriers & Freight, Linfox, DSH Global Logistics, CEVA Logistics, Toll Group, Qube, Leocata's Transport, Maersk, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Freight and Logistics Market Strategic Shifts
Automation and data-centric operations are compressing traditional service hierarchies while regulatory standardization reshapes competitive requirements across Australia's freight networks.
Autonomous yard management systems are migrating from pilot deployments to operational scale at intermodal terminals. Major retailers and third-party logistics providers are adopting these platforms to compress container dwell times. The technology is migrating from proof-of-concept demonstrations to contract-retention requirements for terminal handling contracts along the eastern seaboard.
The Heavy Vehicle National Law continues tightening mass and dimension enforcement through the National Heavy Vehicle Regulator. Fleet operators face escalating compliance costs and productivity constraints that favor investment in high-productivity vehicle combinations. Interstate operators are responding by consolidating into larger fleet configurations capable of absorbing regulatory overhead.
Consolidated procurement platforms are displacing fragmented spot-market engagement for e-commerce fulfillment contracts. Retailers are bundling warehousing, line-haul, and last-mile services under single-source agreements with tier-one providers. This pattern is most visible in Sydney and Melbourne, where automated sortation hubs anchor multi-year service contracts.
Australia Freight and Logistics Market Segmentation
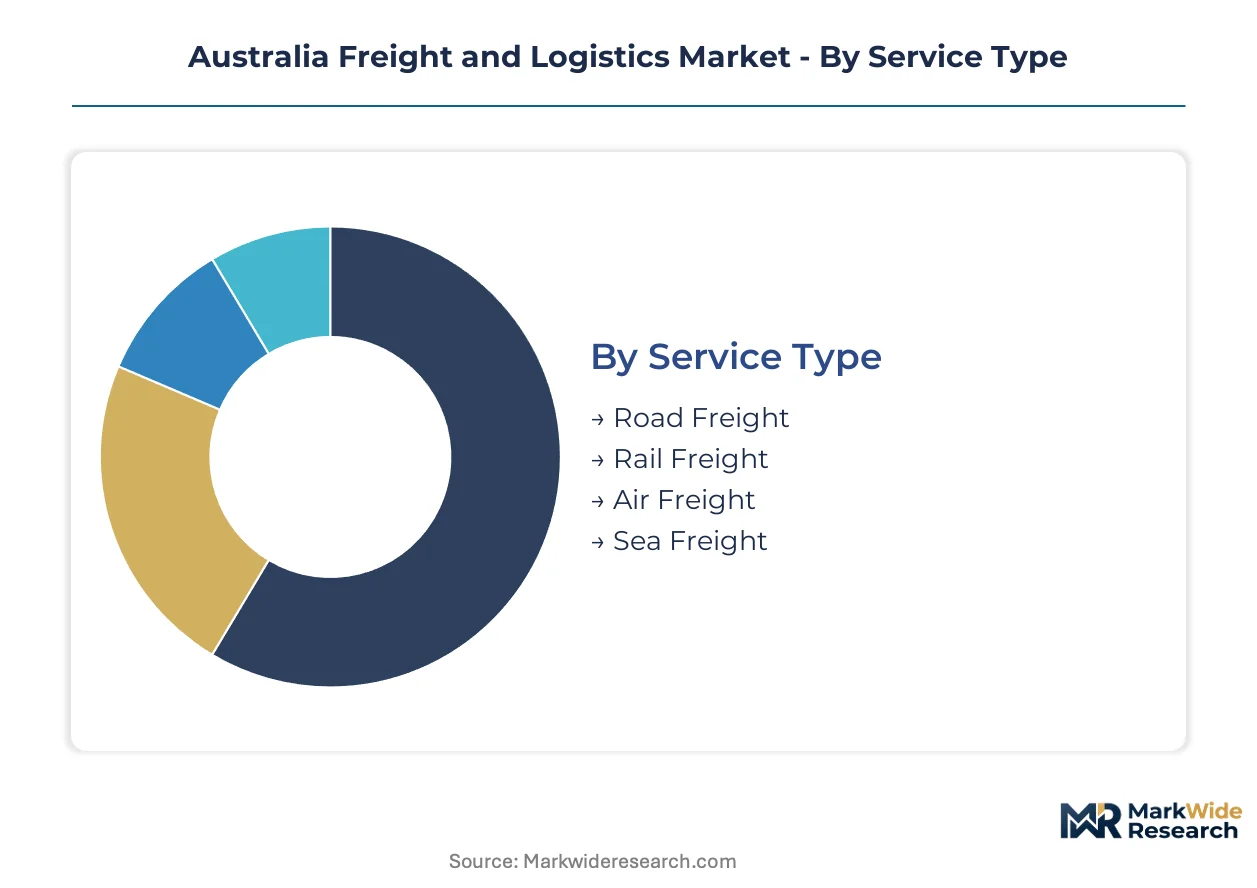
Segmentation in Australian freight and logistics reveals distinct operational economics across service modes, with cycle-time velocity determining capital intensity and margin structure. Each dimension exposes different competitive barriers and technology requirements.
Service Type:
Road freight turns inventory fastest with door-to-door flexibility, while sea freight operates on the longest capital cycles with vessel and port asset lock-in.
- Road Freight:Dominates domestic tonnage through flexible routing across Australia's 4,000-kilometer east-west span. Fleet operators concentrate investment in high-productivity vehicle combinations to absorb National Heavy Vehicle Regulator compliance costs on interstate corridors.
- Rail Freight:Gaining structural traction on bulk commodity and containerized corridors where track access reform improves transit economics. Mining exporters in Queensland and Western Australia drive volume concentration.
- Air Freight:Premium velocity segment serving pharmaceutical and perishable shippers requiring temperature-controlled transit. Limited domestic belly-hold capacity constrains network expansion.
- Sea Freight:Anchors international trade flows through Port Botany and Port of Melbourne with specialized stevedoring assets. Container dwell time compression remains the primary operational metric.
Road freight anchors the volume base while rail freight gains share at the steepest rate.
Client Type:
Cost tiers separate commodity shippers seeking rate minimization from premium clients purchasing supply chain reliability and compliance documentation.
- E-Commerce:Fastest-growing demand pool with automated scheduling and AI routing technologies becoming baseline contract requirements. Retailers bundle warehousing, line-haul, and last-mile services under single-source agreements.
- Large Enterprises:Demand integrated supply chain platforms with dedicated account management and multi-modal optimization. Mining and agricultural exporters dominate volume concentration.
- SMEs:Fragmented spot-market engagement with price-sensitive procurement patterns. Smaller operators struggle with electronic work diary compliance timelines under fatigue management regulations.
- Government:Structured tender processes for defense, healthcare, and infrastructure logistics with stringent security and traceability requirements.
Large enterprises anchor the volume base while e-commerce climbs the fastest.
Delivery Mode:
Speed premiums create four distinct service tiers with diverging fleet and labor configurations.
- Same-Day:Urban micro-fulfillment networks with automated sortation hubs in Sydney and Melbourne. Capital deployment concentrates in automated warehousing clusters along the eastern seaboard.
- Express:Time-definite service with dedicated line-haul lanes and premium pricing. Interstate operators maintain scheduled departures on Sydney-Melbourne-Brisbane corridors.
- Standard:Consolidated shipment economics with flexible transit windows. Road freight absorbs the majority of standard delivery volume.
- Scheduled:Contracted recurring lanes for manufacturing and retail replenishment cycles. Predictable demand patterns enable high asset utilization.
Standard delivery anchors the volume base while same-day service expands most quickly.
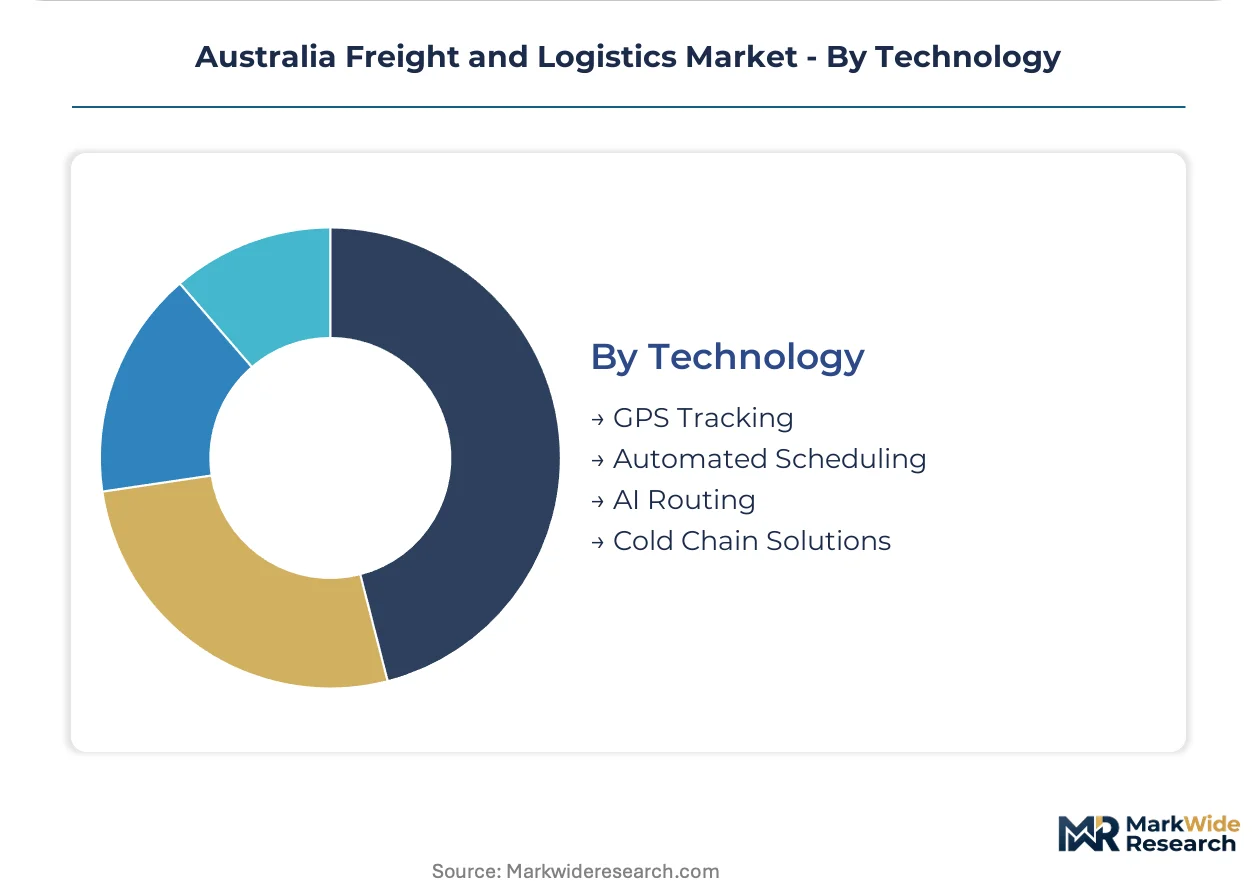
Technology:
Maturity stages separate proven telematics from emerging AI platforms still achieving operational scale.
- AI Routing:Machine learning platforms combined with telematics enable dynamic fleet dispatch that compresses empty running kilometers. Major retailers require this capability for contract retention.
- Cold Chain Solutions:Temperature-controlled infrastructure serving pharmaceutical and premium grocery segments with margin-accretive specialization beyond commodity freight.
- GPS Tracking:Baseline visibility layer with near-universal fleet penetration. Legacy systems resist seamless data exchange with newer IoT sensor networks.
- Automated Scheduling:Yard management systems migrating from pilot to operational scale at intermodal terminals. Container dwell time reduction drives adoption.
GPS tracking anchors the volume base while AI routing gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Australia mining corridors exhibit the lowest price elasticity as bulk commodity exporters prioritize reliability over rate minimization, while SME spot-market shippers in South Australia display acute sensitivity to freight rate fluctuations.
New South Wales
Port Botany container throughput and Sydney metro e-commerce fulfillment anchor demand concentration. The National Heavy Vehicle Regulator enforces fatigue management compliance across the Hume Highway corridor. Automated warehousing clusters in Western Sydney absorb capital deployment for same-day delivery infrastructure serving premium retail clients.
Victoria
Automotive stevedoring and pharmaceutical cold chain requirements drive specialized logistics demand. Infrastructure Australia coordinates federal funding priority assessments for the Melbourne-Brisbane inland rail corridor. Intermodal terminals in Melbourne's west concentrate rail-road transfer capacity for containerized agricultural exports.
Queensland
Mining logistics in the Bowen Basin and last-mile delivery expansion in Greater Brisbane create divergent demand profiles. Heavy vehicle license attainment timelines create driver recruitment bottlenecks in resource corridors. Townsville and Gladstone port upgrades expand bulk export capacity for mineral and agricultural commodities.
Western Australia
Iron ore and lithium export volumes sustain bulk freight demand despite distance penalties from eastern manufacturing centers. The state's transport department administers access permits for high-productivity vehicles on Pilbara mining routes. Perth's limited rail-head capacity restricts intermodal optionality for freight forwarders seeking mode flexibility.
South Australia
Grain export logistics and defense supply chain requirements shape regional demand composition. Interstate operators face productivity constraints from Heavy Vehicle National Law compliance costs on the Adelaide-Melbourne corridor. The Port of Flinders container terminal expansion aims to reduce dwell times for automotive and agricultural exporters.
Australia Freight and Logistics Market Competitive Environment
Capability concentration sits with specialized stevedoring and cold chain operators; scale advantage sits with diversified national networks owning intermodal terminal assets. The market structures around three tiers: integrated multimodal providers with terminal ownership, specialized port logistics operators with stevedoring assets, and regional road freight specialists with corridor-specific density. Competitive moves center on automated yard management deployment and bundled e-commerce fulfillment contracts that consolidate warehousing, line-haul, and last-mile services.
Within the integrated multimodal tier, Toll Group and Linfox exemplify scale-driven operators with eastern seaboard terminal networks and cold chain infrastructure specialization. Qube occupies a position among port-centric specialists with stevedoring assets concentrated at Port Botany and Port of Melbourne. These three anchors represent distinct competitive archetypes: national network scale, vertical terminal integration, and port logistics specialization.
| Leading Market Players |
|---|
| K&S Group |
| Couriers & Freight |
| Linfox |
| DSH Global Logistics |
| CEVA Logistics |
| Toll Group |
| Qube |
| Leocata's Transport |
| Maersk |
| Others |
Value Chain & Pricing Dynamics
Diesel refinery concentration on Singapore's Jurong Island feeds directly into margin compression for Australian road freight operators running the Sydney-Melbourne-Brisbane corridor. Fuel pass-through clauses in long-haul contracts determine which fleet operators retain pricing power versus those absorbing volatility.
Pricing Analysis
After-sales maintenance contracts and extended warranty tiers now generate lifetime value exceeding initial equipment sales for high-productivity vehicle suppliers. Three-tier pricing structure across premium express, standard scheduled, and economy deferred delivery segments dominates contract structures. Cost compression in economy deferred tiers intensifies because SME shippers consolidate spot-market procurement through digital freight platforms. Large mining exporters exhibit lowest price sensitivity while South Australian grain shippers display acute rate responsiveness.
Supply Chain Analysis
Extended payment terms from Chinese chassis manufacturers and Japanese engine suppliers strain working capital for Australian fleet operators. Component sourcing concentrates in China, Japan, and Thailand for driveline systems, telematics hardware, and refrigeration units. Single-source vulnerability in semiconductor-based engine management modules creates delivery uncertainty for high-productivity vehicle builds. Distribution runs through manufacturer-authorized dealer networks with captive parts warehousing in Melbourne and Brisbane.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from cold chain monitoring subscriptions and predictive maintenance platforms expands faster than hardware sales for temperature-controlled fleet operators. Recurring telemetry data fees now anchor customer lifetime value calculations.
For Market Incumbents: Pre-empt autonomous dispatch platform adoption by consolidating mid-tier regional operators before AI routing becomes table stakes. Defensive moves center on securing intermodal terminal access rights in Adelaide and Perth while investing in National Heavy Vehicle Regulator certification capabilities that smaller competitors cannot replicate. Scale absorbs compliance overhead that fragments regional specialist margins. For New Entrants and Emerging Players: Western Australia mining corridors offer geographic underpenetration for specialized bulk logistics operators with high-productivity vehicle expertise. White-space targets include lithium export cold chain and Pilbara remote-site replenishment contracts. Go-to-market positioning should emphasize fatigue-management compliance automation that appeals to resource sector procurement teams. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cold chain specialists holding pharmaceutical certification and eastern seaboard warehouse networks. Five-to-ten year viability hinges on e-commerce fulfillment infrastructure ownership rather than pure transport capacity. Acquisition targets should display bundled service contracts with major retailers. The signal to watch is same-day delivery volume share crossing threshold levels that justify automated micro-fulfillment capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| High-Productivity Vehicle Fleet Conversion | Absorbs National Heavy Vehicle Regulator compliance costs while lifting tonnage-per-driver economics on interstate corridors. |
| Automated Yard Management Deployment | Compresses container dwell times at Port Botany and Port of Melbourne stevedoring contracts. |
| Cold Chain Certification Investment | Captures pharmaceutical and premium grocery segments with margin-accretive temperature-controlled infrastructure. |
| AI Routing Platform Integration | Enables dynamic dispatch that reduces empty running kilometers for contract retention with major retailers. |
| Intermodal Terminal Capacity Expansion | Creates rail-road transfer optionality in Adelaide and Perth where scarcity constrains mode flexibility. |
Study Parameters
Operator-level perspectives from fleet dispatch managers, intermodal terminal operators, cold chain compliance officers, and e-commerce logistics procurement leads anchored the qualitative base. Primary fieldwork combined with secondary validation against Infrastructure Australia corridor assessments, National Heavy Vehicle Regulator compliance bulletins, Australian Bureau of Statistics trade data, and container throughput reports from Port Botany and Port of Melbourne. Bottom-up service segment sizing triangulated against top-down GDP-linked freight intensity models.
Scenario-bracketing around fuel price trajectories and e-commerce penetration rates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service mode, client type, delivery velocity tier, and technology maturity stage. CAGRs derived from trend extrapolation adjusted for regulatory inflection points and infrastructure investment pipelines. Forecast inputs incorporated track access reform timelines and automated warehousing deployment schedules.
Practitioners should monitor Heavy Vehicle National Law amendment schedules and intermodal terminal commissioning dates for early signals of capacity constraint shifts. Forecasts reflect documented assumptions about diesel price bands and retail e-commerce growth curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
China Project Logistics Market
Logistics and Shipping
Dry Van Container Market
Logistics and Shipping
United States Chartered Air Freight Transport Market
Logistics and Shipping
First and Last Mile Delivery Market
Logistics and Shipping
Canada Cold Chain Logistics Market
Logistics and Shipping
Repositioning and Offloading Market
Logistics and Shipping
Logistics Outsourcing Market
Logistics and Shipping
APAC Contract Logistics Market
Logistics and Shipping
Europe Contract Logistics Market
Logistics and Shipping
Malaysia Freight and Logistics Market
Logistics and Shipping
Automotive Logistics Market
Logistics and Shipping
ASEAN Warehousing and Distribution Logistics Market
Logistics and Shipping
Switzerland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Japan Contract Logistics Market
Logistics and Shipping
United Arab Emirates Freight and Logistics Market
Logistics and Shipping
Middle Mile Delivery Market