
 Otic Drugs Market | 2026-2036
Otic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Otic Drugs Market Analysis
The otic drugs market is rebalancing around a widening gap between premium intratympanic formulations and commodity topical antibiotics. Novartis AG leverages its ophthalmic and otic crossover expertise to sustain leadership in steroid-antibiotic combinations. Pfizer anchors the generic antibiotic segment through manufacturing scale, while Otonomy Inc. differentiates via sustained-release gel technology for middle-ear delivery.
Otic drugs comprise pharmaceutical preparations engineered for administration to the external auditory canal, tympanic membrane, or middle ear, typically formulated at pH 4.5-6.5 to match physiological conditions and prevent ototoxicity. These agents serve primarily to treat bacterial and fungal infections, reduce inflammation, dissolve cerumen, or deliver anesthesia during otologic procedures. Otic suspensions lead volume due to their stability with insoluble corticosteroids, while intratympanic delivery modes represent the fastest-expanding margin pool as surgeons adopt office-based injection protocols for Meniere's disease and sudden sensorineural hearing loss. Pain Management therapy area growth reflects broader shifts toward outpatient otologic surgery and same-day discharge protocols.
The FDA governs otic drug approvals under 21 CFR 524 with stringent ototoxicity screening requirements, while the EMA's Committee for Medicinal Products for Human Use applies centralized pediatric investigation plans for pediatric otitis media therapies. Japan's PMDA mandates local tolerance studies for novel otic excipients, creating divergent development timelines across regulatory jurisdictions. Stakeholders must monitor evolving bioequivalence standards for complex otic suspensions, as regulatory science around Q1/Q2 sameness and in vitro release testing is unsettled and will determine generic substitution rates.
Market Dynamics
The otic drugs market is rebalancing around a widening gap between premium intratympanic formulations and commodity topical antibiotics, with sustained-release gel technology compressing dosing frequency expectations and office-based injection protocols displacing hospital-based administration for Meniere's disease therapy.
Growth Catalysts
- FDA Review of Steroid-Antibiotic Combinations:The agency's ongoing evaluation under 21 CFR 524 is streamlining approval pathways for fixed-dose otic suspensions, accelerating formulary placement timelines for ENT outpatient clinics.
- Germany's Ambulatory Surgery Infrastructure:Intratympanic therapy access and ear surgery rates exceeding European averages are concentrating demand for middle-ear delivery systems in German hospital pharmacies.
- Sustained-Release Gel Platforms:Hydrogel excipient advances enabling single-injection corticosteroid depot release are reducing treatment burden for sudden sensorineural hearing loss protocols.
Market Restraints
- Ototoxicity Screening Burden:FDA-mandated preclinical auditory safety studies under 21 CFR 524 extend development timelines by 18-24 months for novel otic excipients, elevating R&D fixed costs.
- API Supply Concentration:Corticosteroid active pharmaceutical ingredient production clusters in Indian and Chinese contract manufacturers, exposing formulators to import tariff volatility and geopolitical supply disruptions.
- Generic Substitution Pressure:Unsettled bioequivalence standards for complex otic suspensions—specifically Q1/Q2 sameness determinations—create regulatory uncertainty that dampens branded investment in formulation innovation.
Strategic Opportunities
- Pediatric Otitis Media Undertreatment:The EMA's centralized pediatric investigation plans create regulatory incentives for age-appropriate drop formulations in European markets where pediatric ENT specialist density remains uneven.
- Office-Based Intratympanic Administration:ENT clinics adopting same-day injection protocols for Meniere's disease represent an expanding margin pool for single-use delivery devices and preservative-free steroid vials.
- Cerumenolytic-Adjuvant Combinations:Convergence of surfactant-based wax dissolution chemistry with antimicrobial prophylaxis addresses the aging demographic's dual burden of conductive hearing loss and recurrent external otitis.
Industry Challenges
- Otologic Pharmacology Expertise Scarcity:Formulation scientists with specialized knowledge of tympanic membrane permeability and round-window pharmacokinetics command premium compensation, constraining mid-tier generic houses.
- Legacy Manufacturing Retrofit Costs:Transitioning aqueous solution lines to aseptic suspension capability for corticosteroid-antibiotic combinations requires seven-figure capital expenditure for isolator technology and dedicated filling suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Otic Drugs Market |
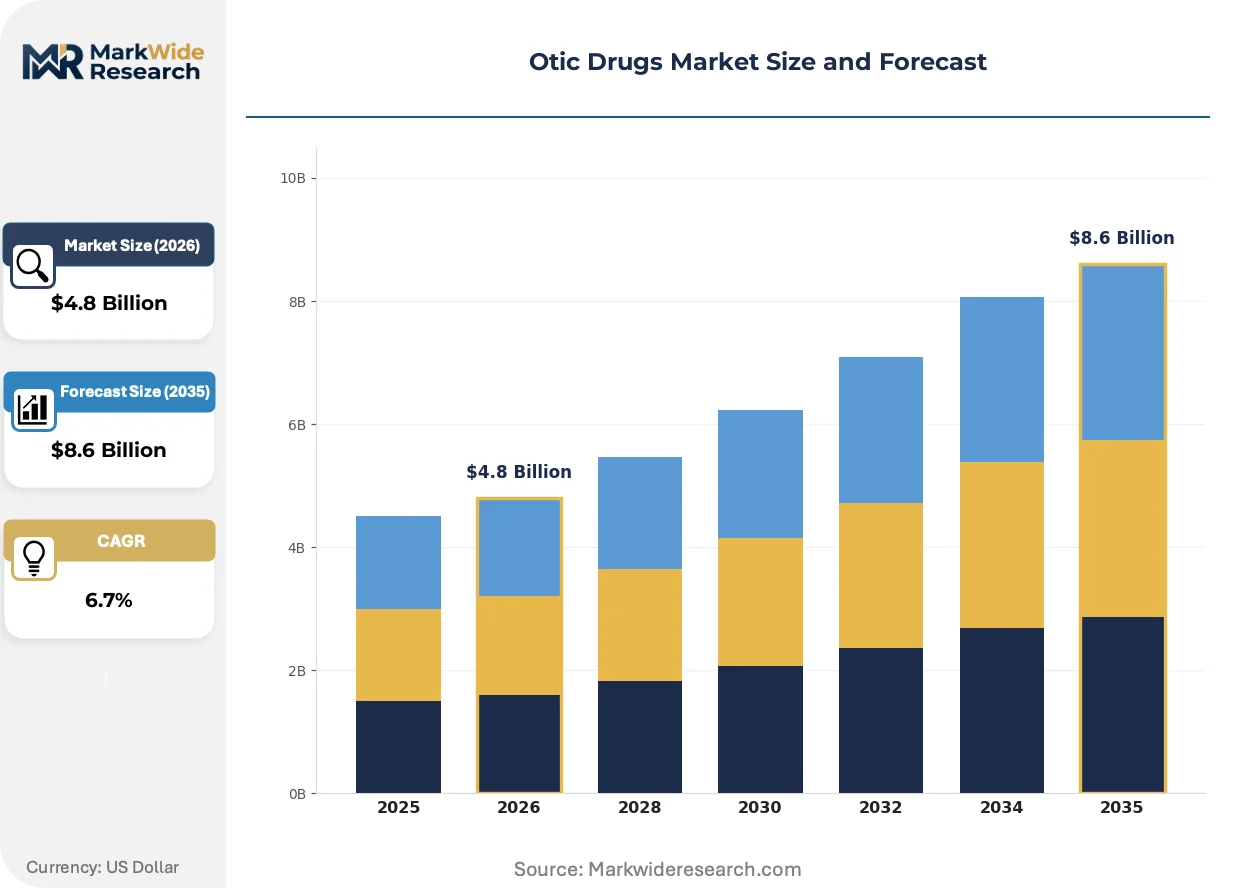
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Otic Solutions, Otic Suspensions, Otic Ointments, Otic Gels Therapy Area: Ear Infections, Allergic Otitis, Cerumen Impaction, Pain Management Delivery Mode: Topical, Intratympanic, Systemic, Surgical End User: Hospitals, Clinics, Home Healthcare, Pharmacies |
| Companies Covered | Novartis AG, Sanofi S.A., GlaxoSmithKline plc, Pfizer, Johnson & Johnson Services Inc., Bayer AG, Teva Pharmaceutical Industries Ltd., AstraZeneca Pharmaceuticals LP, Otonomy Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Otic Drugs Market Emerging Trajectories
Formulation science and regulatory science are diverging in pace, with delivery platform advances outpacing bioequivalence methodology standardization and creating competitive advantage for sponsors with proprietary in vitro release testing protocols.
Intratympanic hydrogel depot systems are modularizing the treatment paradigm for inner-ear disorders. These thermosensitive poloxamer-based platforms enable office-based administration by ENT surgeons without anesthesia support. The technology is modularizing the site of care from ambulatory surgical centers to standard examination rooms, compressing reimbursement codes and expanding addressable patient populations.
Japan's PMDA now mandates local tolerance studies for novel otic excipients under revised pharmaceutical quality guidelines, diverging from FDA and EMA requirements. This regulatory friction forces multinational sponsors to maintain parallel development tracks. Pediatric formulation specialists face the steepest compliance burden, as Japan's aging demographic priorities diverge from Western pediatric otitis media investment patterns.
Hospital pharmacy procurement committees are unbundling antibiotic suspension contracts from bundled surgical supply agreements, creating direct purchasing relationships with generic otic manufacturers. This disintermediation of group purchasing organizations is most visible in German acute care networks, where formulary autonomy and ENT outpatient volume growth concentrate negotiating leverage with regional hospital chains.
Otic Drugs Market Segmentation
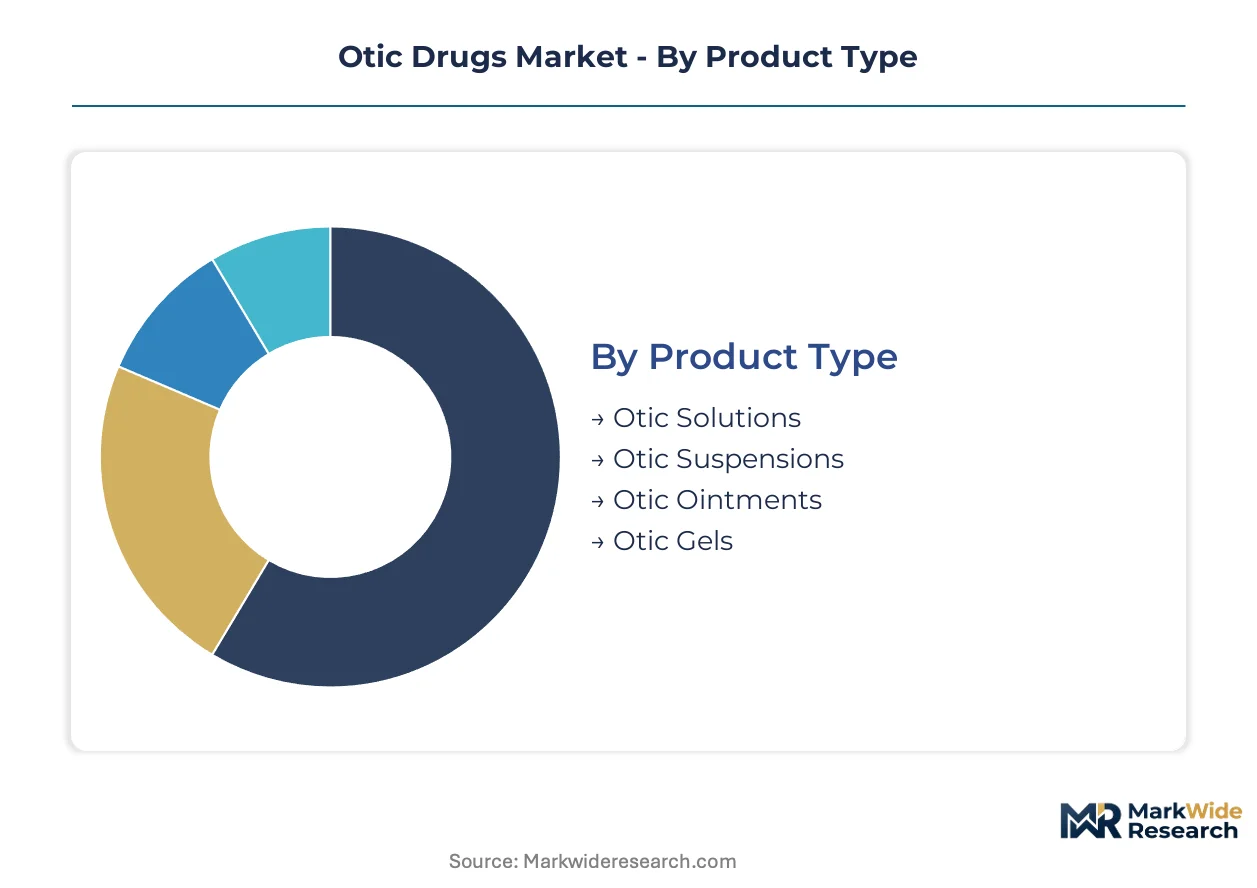
Otic drug segmentation reveals how formulation chemistry, therapy focus, and site-of-care economics allocate value across the supply chain. Each dimension carries distinct regulatory burdens and margin profiles that reshape competitive positioning.
Product Type:
Supply concentration in suspension manufacturing capacity favors established contract manufacturers with isolator technology and dedicated aseptic filling suites.
- Otic Solutions:Aqueous formulations with dissolved active ingredients dominate high-volume antibiotic and anesthetic applications. Demand clusters in US ENT outpatient clinics where same-day dispensing protocols prioritize rapid dissolution kinetics and visual clarity for compliance verification.
- Otic Suspensions:Heterogeneous mixtures stabilizing insoluble corticosteroids in micronized form enable extended shelf life and controlled release. German hospital pharmacies command premium supply allocations as ambulatory ear surgery expansion strains regional manufacturing capacity.
- Otic Ointments:Semisolid petrolatum-based vehicles provide prolonged contact time for external canal conditions.
- Otic Gels:Thermosensitive poloxamer platforms enable sustained-release depot formation for intratympanic delivery.
Otic suspensions absorb the bulk of installed capacity; otic gels are expanding most quickly.
Therapy Area:
Cost tier differentiation separates commodity infection management from premium inner-ear disorder protocols with specialized pharmacokinetic requirements.
- Ear Infections:Bacterial and fungal pathogen targeting spans acute otitis externa through chronic suppurative otitis media. Pediatric volume concentrates demand for preservative-free formulations in European markets where EMA pediatric investigation plans incentivize age-appropriate development.
- Pain Management:Topical anesthetic and anti-inflammatory combinations support outpatient otologic surgery and same-day discharge protocols. US ambulatory surgical centers drive formulation preference toward rapid-onset lidocaine-benzocaine combinations with minimal systemic absorption profiles.
- Allergic Otitis:Mast cell stabilizers and corticosteroid combinations address seasonal and perennial triggers.
- Cerumen Impaction:Surfactant-based dissolution chemistry serves aging populations with conductive hearing loss.
Ear infections absorb the bulk of installed capacity; pain management is climbing the fastest.
Delivery Mode:
Volume concentration in topical administration masks margin migration toward invasive delivery methods requiring specialized training and device ecosystems.
- Topical:External auditory canal instillation remains the default for infection and inflammation management. Manufacturing scale advantages accrue to Indian and Chinese API suppliers feeding generic suspension production for high-volume markets.
- Intratympanic:Direct middle-ear injection via tympanostomy or transtympanic needle bypasses blood-labyrinth barrier limitations. Japanese PMDA local tolerance mandates for novel excipients create compliance friction that favors sponsors with established polymer safety dossiers.
- Systemic:Oral and parenteral antibiotics reserve for complicated infections with regional extension.
- Surgical:Intraoperative irrigation and implantable delivery systems serve refractory cases.
Topical delivery absorbs the bulk of installed capacity; intratympanic delivery is gaining share fastest.
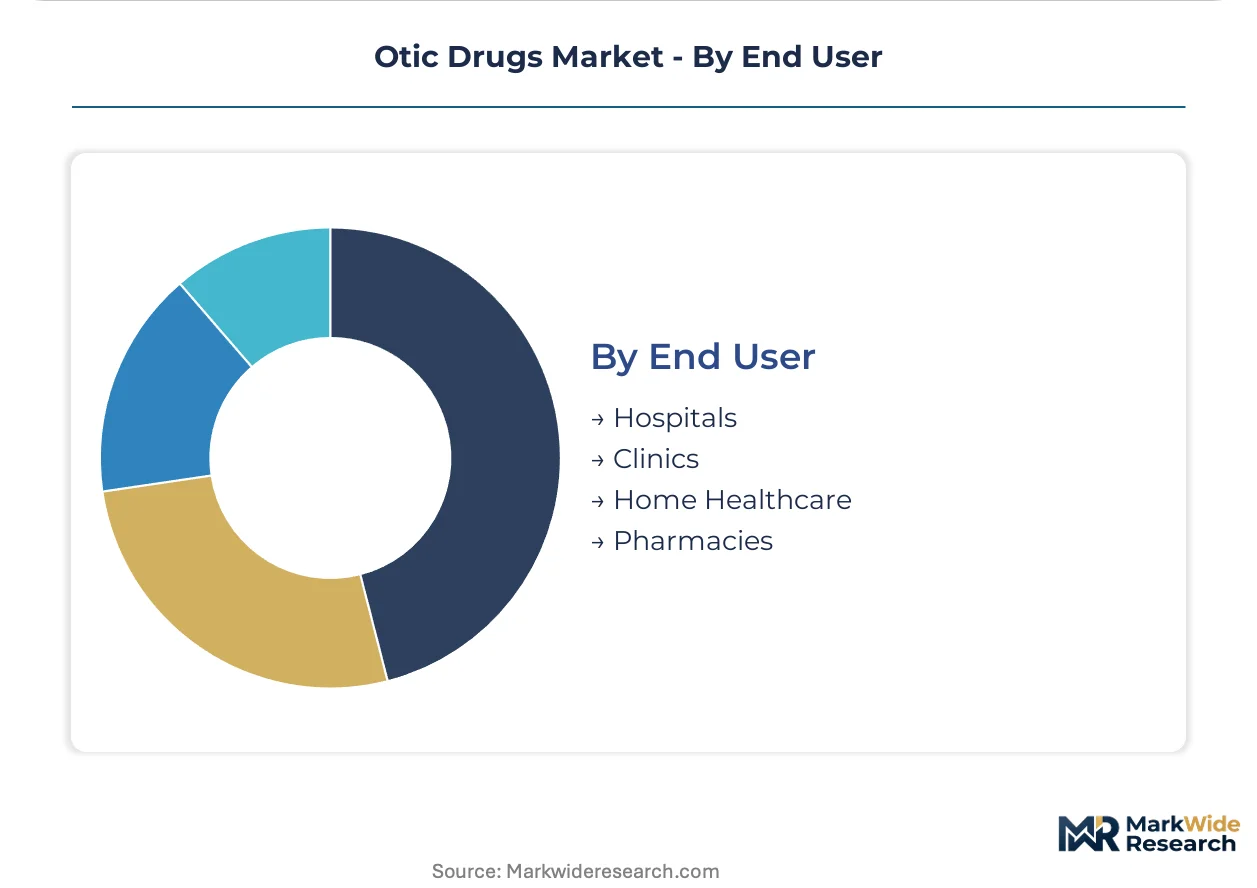
End User:
Customer type stratification reflects reimbursement code compression and procurement committee unbundling of pharmaceutical contracts from surgical supply agreements.
- Hospitals:Acute care networks with integrated ENT departments maintain captive pharmacy capacity for perioperative otic bundles. German regional hospital chains leverage formulary autonomy to negotiate direct manufacturer relationships bypassing group purchasing organizations.
- Clinics:Office-based otolaryngology practices drive intratympanic protocol adoption without anesthesia support. US Medicare reimbursement for in-clinic injection procedures reshapes site-of-care economics toward standalone ENT facilities.
- Home Healthcare:Self-administered drops and irrigation systems serve chronic condition management.
- Pharmacies:Retail and hospital outpatient dispensing capture prescription volume for acute episode resolution.
Hospitals absorb the bulk of installed capacity; clinics are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge pharmaceutical corridor anchors otic drug development activity, with sustained-release formulation expertise clustering around Massachusetts General Hospital's otology research programs and MIT's polymer science laboratories. This concentration shapes regulatory science advancement and clinical trial design across North America.
United States
FDA's 21 CFR 524 ototoxicity screening requirements govern approval timelines for novel otic excipients, extending development cycles for intratympanic gel platforms. Medicare reimbursement codes for office-based injection procedures are compressing site-of-care economics toward standalone ENT clinics. The Philadelphia-Wilmington corridor concentrates contract manufacturing capacity for aseptic otic suspensions.
Germany
Ambulatory ear surgery rates exceeding European averages concentrate demand for middle-ear delivery systems in regional hospital pharmacy networks. The KBA's medical device quality standards intersect with EMA centralized procedures for pediatric otitis media therapies. The Rhine-Ruhr industrial basin hosts specialized isolator technology manufacturers serving suspension formulation lines.
Japan
PMDA's revised pharmaceutical quality guidelines mandate local tolerance studies for novel otic excipients, creating compliance friction that favors sponsors with established polymer safety dossiers. METI's healthcare technology assessment programs prioritize aging-related hearing loss interventions over pediatric indications. The Kansai region's chemical industry supplies hydrogel excipient precursors for thermosensitive depot formulations.
India
Corticosteroid active pharmaceutical ingredient production clusters in Gujarat and Maharashtra contract manufacturing facilities, exposing formulators to import tariff volatility and DGFT export licensing requirements. CDSCO's bioequivalence standards for complex otic suspensions remain unsettled, dampening branded investment in formulation innovation. The Hyderabad-Visakhapatnam corridor specializes in generic antibiotic suspension production.
United Kingdom
EMA pediatric investigation plans create regulatory incentives for age-appropriate drop formulations, though pediatric ENT specialist density remains uneven across NHS trusts. The MHRA's post-Brexit regulatory autonomy permits divergence from EU centralized procedures for novel delivery devices. London's university hospital networks drive intratympanic protocol adoption for sudden sensorineural hearing loss.
Otic Drugs Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and delivery mode specialization, with intratympanic gel technology commanding pricing power over topical antibiotic suspensions. The market structure stratifies into three tiers: multinational pharmaceutical conglomerates with crossover ophthalmic-otic expertise, mid-cap specialists in sustained-release platforms, and regional generic houses competing on manufacturing scale. Strategic moves center on portfolio diversification into pediatric formulations and backward integration into corticosteroid API supply.
Within the sustained-release platform tier, Otonomy Inc. exemplifies technology-driven differentiation through its gel-based middle-ear delivery expertise, while Novartis AG anchors the multinational conglomerate archetype with ophthalmic-otic crossover capabilities. Pfizer occupies the scale-driven position in generic antibiotic manufacturing. These three represent the dominant competitive archetypes: technology specialists leveraging proprietary excipient platforms, diversified pharmacos with therapeutic area synergies, and volume players optimizing contract manufacturing relationships.
| Leading Market Players |
|---|
| Novartis AG |
| Sanofi S.A. |
| GlaxoSmithKline plc |
| Pfizer |
| Johnson & Johnson Services Inc. |
| Bayer AG |
| Teva Pharmaceutical Industries Ltd. |
| AstraZeneca Pharmaceuticals LP |
| Otonomy Inc. |
| Others |
Supply Flow & Price Mechanics
Backward integration into corticosteroid active pharmaceutical ingredient production anchors pricing power for otic suspension manufacturers, as captive supply of micronized hydrocortisone and dexamethasone insulates formulators from Indian and Chinese contract manufacturer tariff volatility. This upstream control separates premium intratympanic gel developers from commodity topical antibiotic houses competing on manufacturing scale alone.
Pricing Analysis
Outcome-based pricing anchored to office-based injection procedure reimbursement codes governs intratympanic steroid depot formulations, with ENT clinic throughput economics determining willingness-to-pay thresholds. Three-tier pricing structure across premium sustained-release gels, standard antibiotic suspensions, and economy generic drops reflects formulation complexity and regulatory dossier depth. Pricing pressure stems from unsettled FDA bioequivalence standards for complex otic suspensions, which dampens branded investment and compresses margins in the generic tier. Hospital pharmacy procurement committees exhibit highest price sensitivity due to formulary unbundling trends, while standalone ENT clinics prioritize clinical efficacy over unit cost.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive otic suspensions and preservative-free steroid vials remain underdeveloped, exposing distributors to cold-chain integrity failures and product spoilage. Active pharmaceutical ingredient production clusters in India, China, and the United States, with corticosteroid manufacturing concentrated in Gujarat and Maharashtra facilities. Hydrogel excipient precursors, aseptic filling equipment, and isolator technology constitute critical input dependencies. Single-source vulnerability in poloxamer-based thermosensitive polymer supply creates exposure to Kansai region chemical industry disruptions. Distribution runs through regional hospital pharmacy networks in Germany and group purchasing organization channels in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Otic drug market consolidation accelerates as FDA ototoxicity screening burdens and seven-figure manufacturing retrofit costs force mid-tier generic houses toward exit or acquisition, concentrating value capture among technology specialists and multinational conglomerates with ophthalmic-otic crossover expertise.
For Market Incumbents: Cement leadership in intratympanic delivery through proprietary in vitro release testing protocols that accelerate regulatory submissions under 21 CFR 524. Acquire isolator-equipped contract manufacturers in the Philadelphia-Wilmington corridor to secure aseptic suspension capacity for corticosteroid-antibiotic combinations. Patent thickets around sustained-release gel platforms defend against emerging entrants with hydrogel depot formulations. For New Entrants and Emerging Players: Launch via direct hospital pharmacy relationships in German regional chains where formulary autonomy and ENT outpatient volume growth concentrate negotiating leverage. Target pediatric otitis media formulations in European markets where EMA centralized pediatric investigation plans create regulatory incentives and specialist density remains uneven. Position surfactant-based cerumenolytic-adjuvant combinations for aging demographic conductive hearing loss protocols. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational pharmacos seeking ophthalmic-otic therapeutic area synergies. Long-term viability favors sponsors with established polymer safety dossiers that satisfy Japan PMDA local tolerance mandates without parallel development track costs. Watch FDA bioequivalence standard finalization for complex otic suspensions as the inflection signal determining generic substitution rates and branded formulation R&D returns.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Steroid-Antibiotic Combinations | 21 CFR 524 ototoxicity screening compliance accelerates formulary placement timelines for ENT outpatient clinics. |
| Manufacturing Scale-Up of Aseptic Suspension Lines | Isolator technology investment in the Philadelphia-Wilmington corridor captures German hospital pharmacy demand concentration. |
| Pipeline Diversification into Pediatric Formulations | EMA centralized pediatric investigation plans create regulatory incentives for age-appropriate drop development. |
| Reimbursement Strategy for Office-Based Injection | Medicare coding for in-clinic intratympanic procedures compresses site-of-care economics toward standalone ENT facilities. |
| Strategic Partnership for Hydrogel Excipient Supply | Kansai region chemical industry alliances secure poloxamer precursor access for thermosensitive depot formulations. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews conducted with ENT drug development executives, regulatory affairs leads, hospital pharmacy procurement managers, and formulary directors. FDA 21 CFR 524 submissions, EMA centralized procedure documents, and PMDA pharmaceutical quality guideline revisions supplied regulatory trajectory intelligence. Bottom-up patient flow modeling and top-down pharmaceutical market sizing were reconciled through iterative triangulation.
Data-stream reconciliation across volume and value outputs employed a segmented analytical framework spanning product type, therapy area, delivery mode, and end user, with regional regulatory clusters modeled separately. CAGRs were derived from procedure volume trends, reimbursement code evolution, and manufacturing capacity expansion patterns. Intratympanic injection protocol adoption curves and sustained-release gel platform penetration assumptions informed inner-ear disorder segment projections across the analysis window.
Regulatory standard finalization delays, API supply disruptions from Indian export licensing changes, and German hospital pharmacy procurement committee unbundling acceleration are the dominant revision risks to modeled outcomes. Forecasts embed assumptions about FDA bioequivalence methodology settlement timelines and EMA pediatric investigation plan enforcement consistency. Practitioners should monitor FDA Q1/Q2 sameness determinations for complex otic suspensions and METI healthcare technology assessment priority shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Anti-Inflammatory Analgesic and Antipyretic Drugs Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
Critical Care Drugs Market
Pharmaceuticals
Cortisone Market
Pharmaceuticals
Cough Cold and Allergy Hay Fever Remedies in Mexico Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
H2-Receptor Antagonists Market
Pharmaceuticals
Aripiprazole Market
Pharmaceuticals
Laxatives Market
Pharmaceuticals
Spain OTC Drugs Market
Pharmaceuticals
Liquid Filled Hard Capsules Market
Pharmaceuticals
North America Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Global Pericarditis Drugs Market
Pharmaceuticals
Zoledronic Acid Market
Pharmaceuticals
Australia Pharmaceuticals Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market