
 Asia-Pacific Diabetes Care Devices Market | 2026-2036
Asia-Pacific Diabetes Care Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Diabetes Care Devices Market Analysis
Leasing arrangements for insulin pump systems is reconfiguring competitive access across Southeast Asian markets, allowing smaller providers to compete without heavy capital outlay. Novo Nordisk leverages its manufacturing scale to anchor supply contracts with hospital networks across India and Australia. Abbott Laboratories differentiates through wearable technology integration that extends its presence from clinical settings into home care environments.
Asia-Pacific diabetes care devices encompass instruments for glucose monitoring, insulin delivery, and lancing, typically incorporating biosensor strips, electrochemical measurement circuits, or precision piston mechanisms for subcutaneous drug administration. These devices serve to maintain glycemic control and prevent complications in diabetic patients across outpatient and residential settings. Blood glucose meters retain the largest installed base among device types, though continuous glucose monitors capture expanding margin pools as sensor accuracy improves and replacement cycles shorten. Smart devices and wearable technology within the technology segment are attracting R&D investment as manufacturers integrate predictive algorithms and real-time data transmission capabilities.
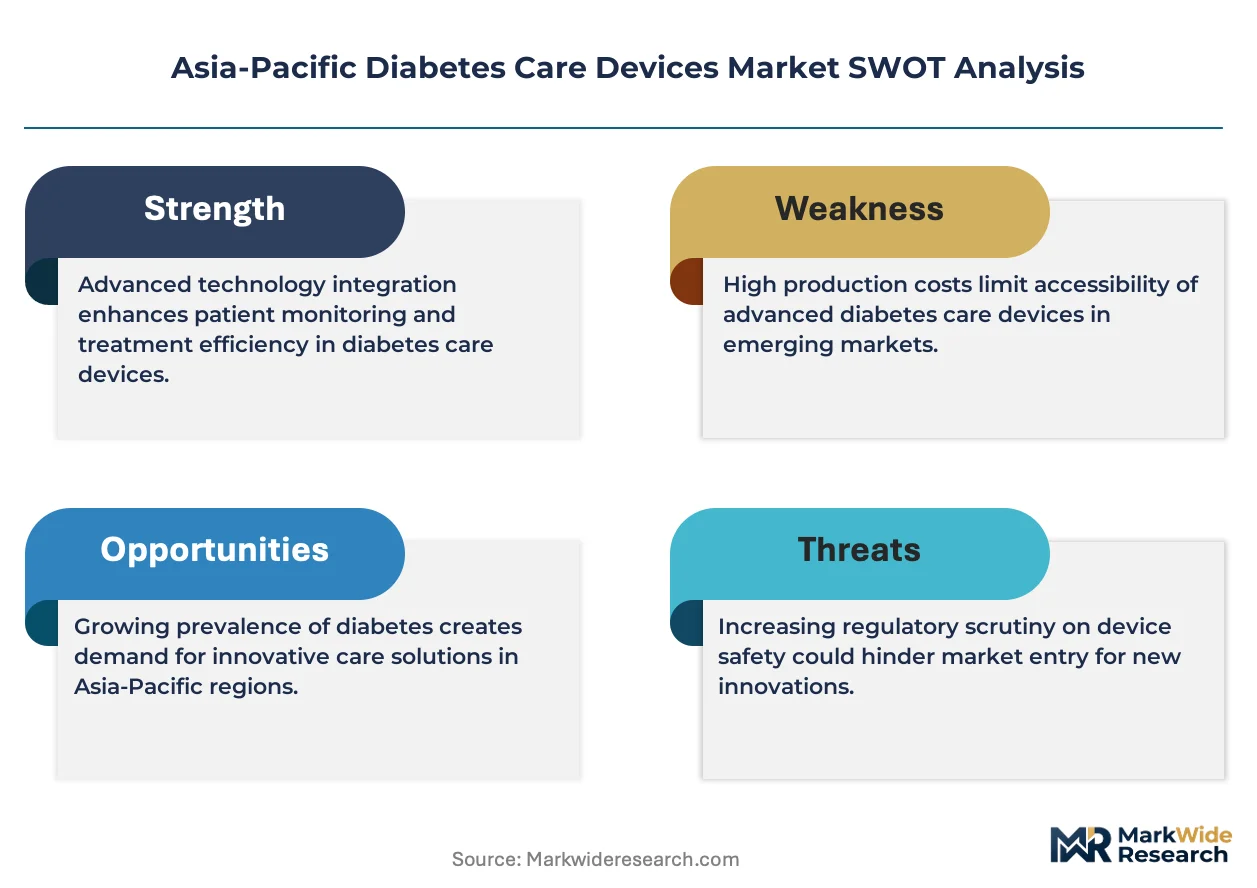
Japan's PMDA maintains stringent premarket approval requirements for glucose monitoring systems, while India's CDSCO aligns with BIS standards to regulate import quality and local production consistency. Australia's TGA enforces post-market surveillance that shapes product lifecycle obligations for device sponsors operating across multiple Asia-Pacific jurisdictions. Stakeholders must monitor reimbursement negotiations in China and South Korea, where national health insurance decisions will determine which device categories achieve scalable patient access.
Market Dynamics
Reimbursement scale-up for continuous glucose monitors across China and Japan is compressing the addressable market for traditional blood glucose meters while redirecting capital toward sensor manufacturing capacity.
Growth Catalysts
- PLI scheme acceleration:India's production-linked incentive scheme for medical devices is expanding domestic insulin pen and biosensor strip manufacturing capacity, reducing import dependence for hospital procurement.
- Home care migration:Post-acute diabetes management is shifting from outpatient clinics to residential settings across Australia and South Korea, expanding the installed base for patient-operated monitoring devices.
- Sensor accuracy gains:Electrochemical measurement improvements are shortening replacement cycles for continuous glucose monitors, pulling forward recurring revenue streams for manufacturers serving Japan's aging patient population.
Market Restraints
- Import quality friction:India's CDSCO alignment with BIS standards creates compliance bottlenecks for foreign manufacturers seeking rapid market entry against local production incentives.
- Capital intensity barriers:Precision piston mechanism production for insulin pumps requires specialized cleanroom infrastructure that concentrates supply among established East Asian contract manufacturers.
- PMDA timeline rigidity:Japan's premarket approval requirements for glucose monitoring systems extend commercialization cycles, delaying technology refresh rates relative to other Asia-Pacific jurisdictions.
Strategic Opportunities
- Southeast Asian leasing penetration:Hospital networks in Indonesia, Vietnam, and Thailand are adopting equipment leasing for insulin pump systems, opening access for capital-constrained providers.
- Wearable convergence:Integration of predictive algorithms with real-time data transmission is creating hybrid device categories that span clinical monitoring and consumer fitness applications.
- Australian post-market leverage:TGA surveillance data requirements are generating proprietary clinical evidence that sponsors can repurpose for reimbursement negotiations in South Korea and Taiwan.
Industry Challenges
- Multijurisdictional compliance staffing:Device sponsors operating across PMDA, CDSCO, TGA, and NMPA frameworks face scarcity of regulatory affairs specialists with simultaneous expertise in all four systems.
- Legacy meter obsolescence management:Blood glucose meter manufacturers must sustain service infrastructure for installed base patients while reallocating R&D toward sensor platforms, straining operational bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Diabetes Care Devices Market |
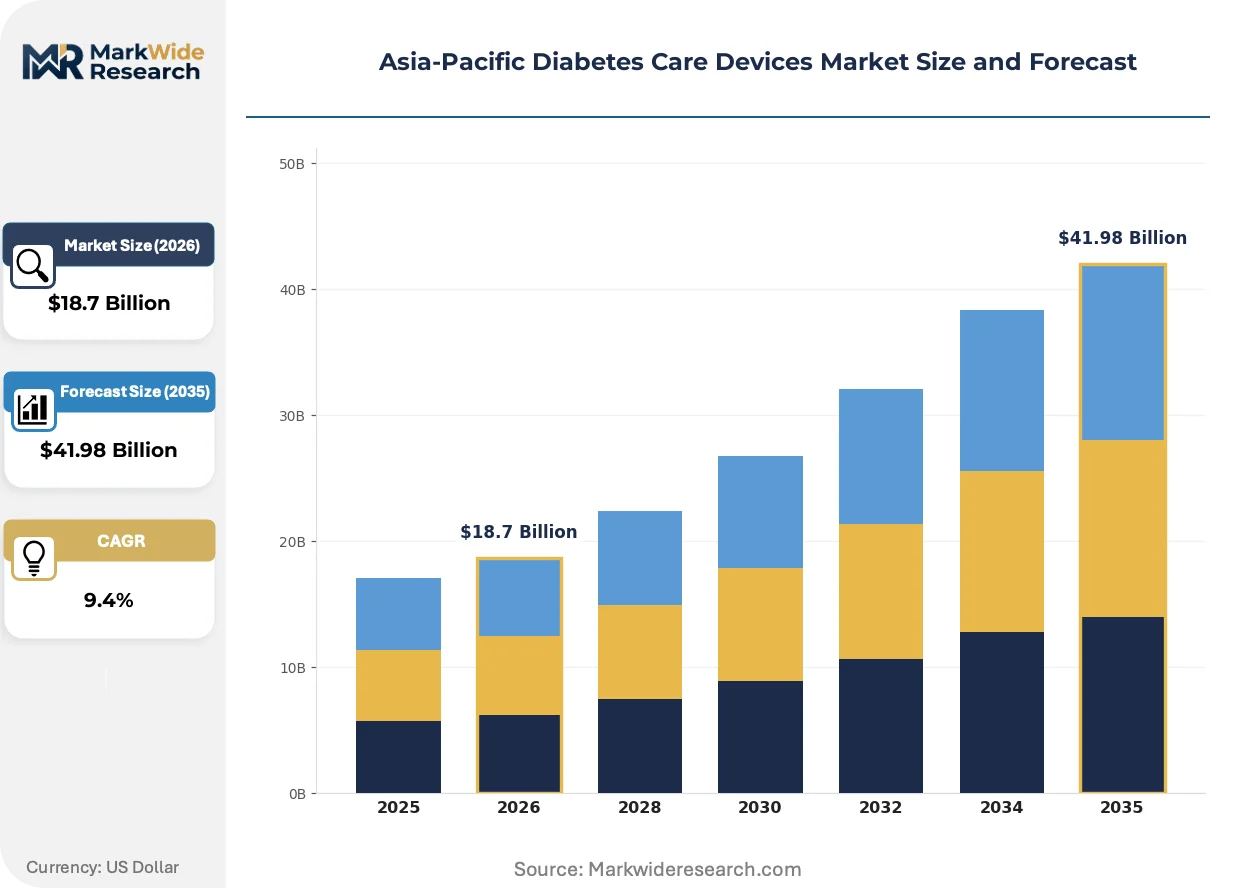
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Blood Glucose Meters, Insulin Pumps, Continuous Glucose Monitors, Lancets End User: Hospitals, Clinics, Home Care, Retail Pharmacies Technology: Smart Devices, Wearable Technology, Mobile Applications, Cloud Platforms Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Novo Nordisk, Eli Lilly and Company, Abbott Laboratories, Becton, Dickinson and Company, ARKRAY, F. Hoffmann-La Roche, Medtronic, Terumo Corporation, Ascensia Diabetes Care, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Diabetes Care Devices Market Emerging Trajectories
Sensor miniaturization and algorithmic prediction are converging to transform diabetes management from episodic measurement toward continuous metabolic awareness, with regulatory frameworks racing to catch up to hardware capabilities.
Non-invasive glucose monitoring through optical spectroscopy and interstitial fluid sensing is collapsing the distinction between medical-grade and consumer wellness devices. Japanese and Australian patients are piloting smartphone-integrated sensors that bypass fingerstick calibration entirely. This convergence is collapsing the premium pricing tier that previously separated hospital-prescribed monitors from direct-to-consumer alternatives.
PMDA's 2023 guidance on software-as-a-medical-device is forcing glucose monitoring manufacturers to submit algorithm updates as formal regulatory amendments rather than over-the-air patches. The industrial consequence is slower feature rollouts for predictive hypoglycemia alerts. Continuous glucose monitor sponsors with established quality management systems are absorbing these costs more readily than new entrants targeting Japan's reimbursement-eligible patient pool.
Hospital procurement committees across India and China are unbundling device acquisition from consumables contracts, separating insulin pump hardware from sensor strip supply agreements. Distributors that previously captured bundled margins are losing pricing control to direct manufacturer negotiations with institutional buyers. This unbundling is most visible in tier-one Chinese cities where provincial health insurance administrators are mandating transparent line-item reimbursement coding.
Asia-Pacific Diabetes Care Devices Market Segmentation
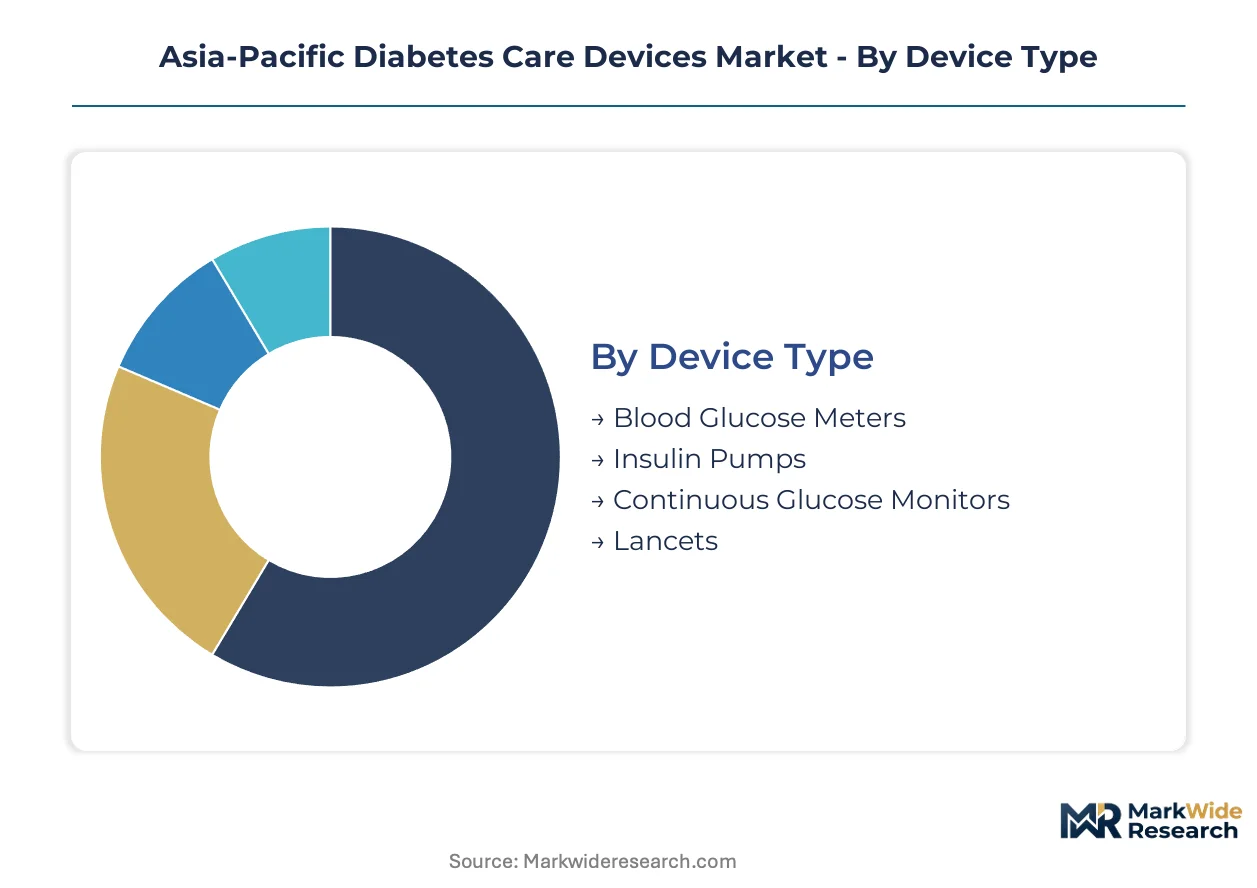
Segmentation in the Asia-Pacific diabetes care devices market reveals divergent replacement cycles and margin structures across hardware categories. Manufacturers allocate R&D and manufacturing capacity based on these velocity differentials.
Device Type:
Replacement cycles range from single-use disposables to capital equipment with decade-long amortization schedules.
- Continuous Glucose Monitors:Electrochemical sensor systems with 7-14 day wear periods generate recurring revenue through disposable transmitter patches. China's provincial health insurance administrators are scaling reimbursement access in tier-one cities, compressing out-of-pocket patient costs.
- Blood Glucose Meters:Handheld electrochemical measurement devices with test strip consumables retain the largest installed base across India and Southeast Asia due to lower acquisition costs. India's CDSCO alignment with BIS standards shapes import quality requirements for foreign manufacturers competing against domestic production.
- Insulin Pumps:Precision piston mechanism devices for subcutaneous drug delivery require specialized cleanroom manufacturing concentrated among East Asian contract manufacturers.
- Lancets:Single-use lancing devices with controlled penetration depth specifications turn over fastest as consumable disposables.
Blood glucose meters anchor the volume base while continuous glucose monitors gain share at the steepest rate.
End User:
Procurement authority and reimbursement eligibility vary sharply across institutional and retail channels.
- Home Care:Patient-operated monitoring and delivery devices are expanding fastest as post-acute diabetes management shifts from outpatient clinics to residential settings across Australia and South Korea.
- Hospitals:Acute care settings demand hospital-grade precision and calibration protocols, with procurement committees in India and China unbundling device acquisition from consumables contracts.
- Clinics:Outpatient facilities balance capital constraints with clinical accuracy requirements for glucose monitoring.
- Retail Pharmacies:Over-the-counter sales channels serve price-sensitive patients without prescription coverage, particularly in Southeast Asian markets.
Home care captures the steepest expansion trajectory as reimbursement frameworks adapt to outpatient cost pressures.
Technology:
Integration complexity and regulatory classification determine commercialization timelines for connected device platforms.
- Wearable Technology:Skin-adherent biosensors with real-time data transmission are attracting R&D investment as manufacturers integrate predictive algorithms. Japan's PMDA software-as-a-medical-device guidance forces algorithm updates through formal regulatory amendments rather than over-the-air patches.
- Smart Devices:Connected glucose meters with automated logging and dose calculation capabilities bridge clinical and consumer applications.
- Mobile Applications:Smartphone-integrated data visualization and alert systems require compliance with multiple national data protection frameworks.
- Cloud Platforms:Centralized data aggregation for population health management faces cybersecurity certification requirements across Australian TGA and South Korean MFDS jurisdictions.
Wearable technology commands the premium pricing tier while smart devices expand volume through affordability.
Distribution Channel:
Channel control determines margin retention and pricing transparency in institutional versus retail procurement.
- Direct Sales:Manufacturer negotiations with hospital networks and procurement committees capture margin previously absorbed by distribution intermediaries, particularly visible in tier-one Chinese cities with mandated line-item reimbursement coding.
- Distributors:Regional logistics providers with cold-chain capabilities for insulin storage retain relevance in fragmented Southeast Asian markets.
- Online Retail:E-commerce platforms for direct-to-consumer device sales are expanding fastest in markets with mature digital payment infrastructure.
- Offline Retail:Brick-and-mortar pharmacy and medical supply stores serve patients requiring in-person training and technical support.
Direct sales concentrate in institutional procurement while online retail climbs fastest in consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japan's PMDA-regulated premium tier while India extracts value through PLI-scaled domestic manufacturing. China's provincial reimbursement decisions determine which device categories achieve volume scale across the region.
China
Provincial health insurance administrators in tier-one cities are scaling reimbursement access for continuous glucose monitors, compressing out-of-pocket patient costs. NMPA registration requirements shape import timelines for foreign manufacturers against domestic production incentives. Shanghai and Beijing clusters concentrate sensor manufacturing capacity as hospital procurement committees mandate transparent line-item reimbursement coding.
Japan
PMDA premarket approval requirements for glucose monitoring systems extend commercialization cycles, delaying technology refresh rates relative to other jurisdictions. METI industrial policy directs R&D subsidies toward wearable biosensor integration. The Kanto/Tokyo corridor anchors precision manufacturing for electrochemical measurement circuits serving the aging patient population.
India
CDSCO alignment with BIS standards creates compliance bottlenecks for foreign manufacturers seeking rapid market entry. The PLI scheme for medical devices accelerates domestic insulin pen and biosensor strip manufacturing capacity, reducing import dependence. Maharashtra and Gujarat industrial corridors concentrate cleanroom infrastructure for precision piston mechanism production.
Australia
TGA post-market surveillance generates proprietary clinical evidence that sponsors repurpose for reimbursement negotiations in neighboring jurisdictions. Home care migration shifts post-acute diabetes management from outpatient clinics to residential settings. The New South Wales and Victoria corridor expands installed base for patient-operated monitoring devices through mature digital payment infrastructure.
South Korea
MFDS reimbursement negotiations determine which device categories achieve scalable patient access through national health insurance decisions. Sensor accuracy improvements pull forward replacement cycles for continuous glucose monitors. The Seoul Capital Area concentrates R&D investment for predictive algorithm integration with real-time data transmission capabilities.
Asia-Pacific Diabetes Care Devices Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying precision mechanisms and electrochemical sensors to multiple end-device brands. The vendor base organizes around three archetypes: multinational healthcare conglomerates with full-stack glucose management portfolios, regional manufacturing specialists leveraging PLI incentives and contract fabrication scale, and emerging wearable technology firms bridging clinical and consumer applications. Dominant competitive moves include strategic partnerships with hospital procurement networks and backward integration into biosensor strip production to capture recurring consumables revenue.
Among the multinational healthcare conglomerates, Novo Nordisk, Abbott Laboratories, and Medtronic occupy positions spanning insulin delivery, continuous monitoring, and data platform integration. Novo Nordisk exemplifies the pharmaceutical-device hybrid archetype, anchoring supply relationships through manufacturing scale. Abbott Laboratories represents wearable technology convergence, extending presence from clinical settings into home care environments. Medtronic sits within the integrated system tier, combining hardware platforms with algorithmic prediction capabilities.
| Leading Market Players |
|---|
| Novo Nordisk |
| Eli Lilly and Company |
| Abbott Laboratories |
| Becton, Dickinson and Company |
| ARKRAY |
| F. Hoffmann-La Roche |
| Medtronic |
| Terumo Corporation |
| Ascensia Diabetes Care |
| Others |
Supply Flow & Price Mechanics
Shanghai and Beijing manufacturing clusters concentrate electrochemical sensor production capacity, concentrating bargaining power among East Asian contract manufacturers serving downstream device sponsors. Hospital procurement committees across tier-one Chinese cities exploit this concentration through unbundled line-item reimbursement mandates that strip distributor margins and compress hardware acquisition premiums.
Pricing Analysis
Configured-to-order insulin pump systems command substantial premiums over standard catalog configurations due to patient-specific dosing algorithm calibration and dedicated clinical training bundles. Pricing stratifies across premium, standard, and economy tiers based on sensor accuracy certification grade and after-sales service entitlements. Cost compression in economy-tier blood glucose meters intensifies as India's PLI-scaled domestic manufacturing displaces import-dependent distribution. Retail pharmacy channels exhibit acute price sensitivity, while hospital procurement committees with centralized GPO contracts demonstrate lower elasticity due to bundled consumables lock-in.
Supply Chain Analysis
Precision piston mechanisms and electrochemical sensor substrates draw from concentrated feedstock supply anchored in Japan, South Korea, and select Chinese provinces with specialized cleanroom infrastructure. Raw material dependencies center on medical-grade stainless steel alloys, biosensor enzyme reagents, and polymer substrates for adhesive patches. Single-source vulnerability concentrates in precision machining for insulin pump drive systems, where qualified contract manufacturers number fewer than ten across the region. Distribution runs through hybrid direct-manufacturer and regional cold-chain logistics networks, with the latter retaining relevance in fragmented Southeast Asian markets lacking consolidated procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific diabetes care devices market exhibits cyclical recovery characteristics as reimbursement scale-up for continuous glucose monitors across China and Japan pulls replacement demand forward from traditional meter obsolescence cycles.
For Market Incumbents: Harden quality management systems against PMDA software-as-a-medical-device amendment requirements to preserve algorithm update velocity against emerging wearable technology entrants. Anchor hospital network supply contracts through backward integration into biosensor strip production, capturing recurring consumables revenue that offsets hardware margin compression from unbundled procurement mandates. For New Entrants and Emerging Players: Southeast Asian tier-two cities present underpenetrated white-space for patient-operated monitoring devices as home care migration accelerates across Indonesia, Vietnam, and Thailand. Target capital-constrained hospital networks with equipment leasing arrangements for insulin pump systems, bypassing upfront procurement barriers that favor established East Asian manufacturers with balance sheet depth. For Investors and Strategic Acquirers: Long-term, this sits as a chronic-disease platform play because sensor miniaturization and algorithmic prediction are collapsing the distinction between medical-grade and consumer wellness applications, expanding addressable patient populations beyond diagnosed diabetics to pre-diabetic metabolic monitoring. Monitor PMDA reimbursement negotiation outcomes for non-invasive optical spectroscopy devices as the inflection signal indicating regulatory acceptance of calibration-free monitoring platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Abbott Laboratories anchors procurement relationships through integrated wearable technology platforms spanning clinical and home care environments. |
| Reimbursement Strategy | Novo Nordisk leverages manufacturing scale to secure supply contracts with networks as China's provincial administrators expand CGM coverage. |
| Software Companion Development | Medtronic integrates predictive hypoglycemia algorithms that require PMDA amendment submissions, slowing feature rollout relative to less regulated jurisdictions. |
| CE Marking Pathway | European regulatory alignment accelerates parallel entry into Australian TGA and South Korean MFDS frameworks through mutual recognition principles. |
| Backward Integration | Domestic manufacturers exploit India's PLI scheme to capture biosensor strip production from import-dependent distributors. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of hospital procurement databases, GPO contract filings, and national health insurance reimbursement schedules. Primary interviews engaged hospital purchasing committee members, biomedical engineers, regulatory affairs specialists with PMDA/CDSCO/TGA expertise, and GPO contracts managers across tier-one Chinese cities and Indian industrial corridors. Secondary validation drew from NMPA registration filings, CDSCO import quality bulletins, TGA post-market surveillance reports, and MFDS reimbursement decision archives. Bottom-up patient population modeling triangulated against top-down manufacturer revenue aggregation.
Forecast inputs incorporate device replacement cycle velocity, sensor accuracy improvement trajectories, and reimbursement expansion schedules across the projection horizon. Segmentation dimensions span device type, end-user setting, technology integration level, and distribution channel control. CAGRs derive from fitted growth curves calibrated to historical adoption patterns and regulatory milestone timing. Industry-specific inputs include PLI scheme capacity addition timelines and PMDA software-as-a-medical-device guidance compliance cost absorption rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by emerging wearable technology firms with consumer electronics supply chain leverage would shift outcomes beyond modeled parameters. Material shifts in NMPA or PMDA reimbursement eligibility criteria for non-invasive monitoring platforms would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Self-Monitoring Blood Glucose (SMBG) Market
Diabetes Care
Malaysia Insulin Infusion Pump Market
Diabetes Care
France Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market
Diabetes Care
France Diabetes Devices Market
Diabetes Care
Smart Glucose Monitors Market
Diabetes Care
Canada Continuous Glucose Monitoring Market
Diabetes Care
Middle East and Africa Diabetes Care Devices Market
Diabetes Care
Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Gestational Diabetes Market
Diabetes Care
Middle East and Africa Insulin Pens Market
Diabetes Care
Japan Oral Anti-Diabetic Drug Market
Diabetes Care
Diabetes Care Devices and Drugs Market
Diabetes Care
Global Implantable Insulin Pump Market
Diabetes Care
Russia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Smart Insulin Pens Market