
 Australia Blood Glucose Monitoring Market | 2026-2036
Australia Blood Glucose Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Blood Glucose Monitoring Market Insights
The Australian government's National Diabetes Strategy is pivoting chronic disease management toward patient-centered, technology-enabled care models. Abbott Diabetes Care leverages its FreeStyle portfolio to dominate retail pharmacy channels across metropolitan Australia. Dexcom competes through intensive endocrinologist engagement and private health fund reimbursement pathways. Roche Diabetes Care anchors hospital and pathology laboratory contracts with integrated data management platforms.
Blood glucose monitoring encompasses electrochemical, optical, and enzymatic sensor systems that quantify interstitial or capillary glucose concentrations for therapeutic decision-making. Continuous glucose monitors employing subcutaneous electrochemical sensors now capture the fastest-expanding revenue pool as real-time data integration with insulin delivery systems reduces hypoglycemic events. Self-monitoring devices retain volume leadership among Type 2 diabetes patients in regional and remote communities where specialist access remains limited. Flash glucose monitors occupy a transitional position, appealing to tech-adherent patients seeking intermittent scanning without full continuous alerts.
TGA medical device frameworks govern pre-market approval, post-market surveillance, and software-as-medical-device classifications for connected glucose platforms. The Therapeutic Goods Administration collaborates with the Australian Commission on Safety and Quality in Health Care to mandate cybersecurity and data interoperability standards for remote patient monitoring. Stakeholders must monitor evolving private health insurance rebate schedules and Medicare Benefits Schedule amendments that determine out-of-pocket costs and therefore device switching behavior across patient segments.
Market Dynamics
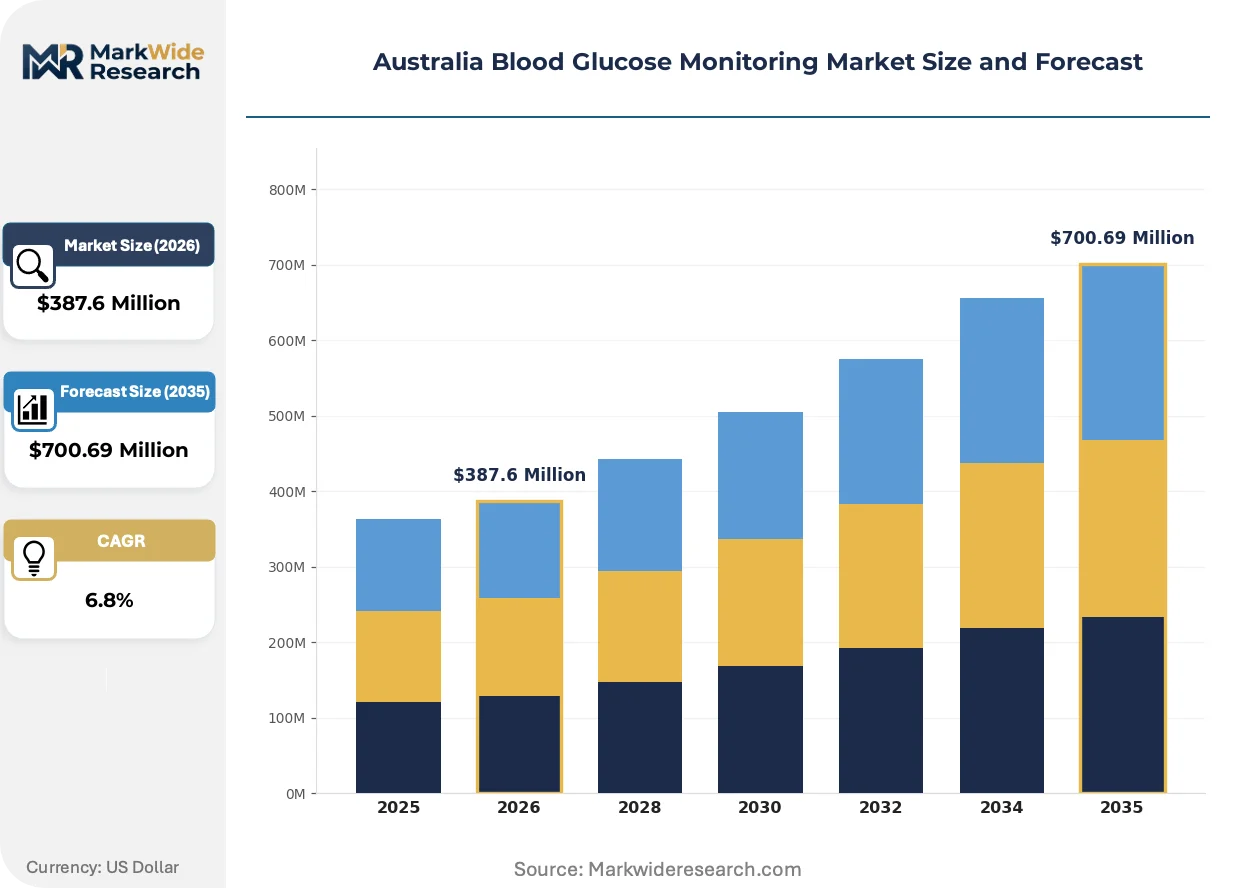
The Australian blood glucose monitoring market is undergoing a structural transformation driven by TGA's accelerated software-as-medical-device pathways, which compress approval timelines for connected glucose platforms and redistribute competitive advantage toward data-integrated systems.
Growth Catalysts
- TGA regulatory streamlining:The Therapeutic Goods Administration's expedited pre-market assessment for continuous glucose monitoring devices reduces time-to-market for next-generation sensors, stimulating manufacturer investment in real-time glucose platforms.
- Aging demographic concentration:Australia's 65-plus population clustering in metropolitan Sydney and Melbourne generates concentrated demand for home-based diabetes management technologies that reduce specialist dependency.
- Private health fund expansion:Reimbursement schedule expansions by major Australian insurers for flash and continuous monitoring systems lower out-of-pocket barriers and accelerate device switching from traditional self-monitoring.
Market Restraints
- Sensor consumable cost structure:Electrochemical sensor replacement cycles impose recurring expenditure burdens that limit adoption among uninsured Type 2 diabetes patients in regional Queensland and Western Australia.
- Specialist service concentration:Endocrinology and credentialled diabetes educator services cluster in New South Wales and Victoria, creating access inequities that suppress device utilization in Tasmania and Northern Territory.
- Interoperability fragmentation:Proprietary data formats across competing continuous glucose monitor ecosystems obstruct seamless integration with third-party insulin delivery systems and electronic health records.
Strategic Opportunities
- Remote and Indigenous health penetration:Under-served Aboriginal and Torres Strait Islander communities in remote Northern Territory and Western Australia present untapped demand for telehealth-integrated glucose monitoring with culturally adapted delivery models.
- Medicare Benefits Schedule alignment:Anticipated amendments to MBS item numbers for remote patient monitoring reimbursement would subsidize continuous glucose monitor prescriptions and expand addressable patient pools.
- Artificial intelligence convergence:Machine learning algorithms layered atop continuous glucose data streams enable predictive hypoglycemia alerts and personalized insulin dosing recommendations, creating differentiated value propositions.
Industry Challenges
- Cybersecurity compliance complexity:TGA and Australian Commission on Safety and Quality in Health Care mandates for connected device security require ongoing software validation expenditure that strains mid-tier manufacturer resources.
- Data governance skill scarcity:Shortages of health informatics specialists capable of navigating TGA software-as-medical-device classifications and privacy law intersections delay product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Blood Glucose Monitoring Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Monitoring Devices, Continuous Glucose Monitors, Flash Glucose Monitors, Implantable Systems Technology: Electrochemical Sensors, Optical Sensors, Enzymatic Sensors, Microfluidic Technology Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes Monitoring End User: Home Care, Clinics, Diagnostic Laboratories, Research Institutes |
| Companies Covered | Abbott Diabetes Care, Dexcom, Medtronic, Roche Diabetes Care, Ascensia Diabetes Care, Everesense, Johnson & Johnson, Senseonics Holdings, Bionime Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Blood Glucose Monitoring Market Trends and Innovations
Real-time glucose data integration with automated insulin delivery systems is compressing the boundary between monitoring and therapeutic intervention, while regulatory frameworks and reimbursement structures race to accommodate closed-loop architectures.
Subcutaneous electrochemical sensors with factory-calibrated algorithms are absorbing market share from traditional self-monitoring blood glucose systems among Type 1 diabetes patients and insulin-requiring Type 2 cohorts. Endocrinology practices in Melbourne and Sydney are prescribing these devices at accelerating rates, compressing the addressable market for fingerstick-based meters and test strip consumables.
TGA's software-as-medical-device classification guidance for glucose prediction algorithms imposes clinical validation requirements that favor established manufacturers with robust quality management systems. The regulation mandates cybersecurity documentation and post-market surveillance protocols that extend development timelines but elevate safety standards for Australian patients. Smaller sensor developers are responding by pursuing partnership pathways rather than independent regulatory submissions.
Patient data ownership preferences are shifting control toward consumer-directed health information exchange, disrupting traditional pathology laboratory reporting relationships. Younger diabetes patients in urban Australian centers increasingly demand direct smartphone access to raw glucose data streams, displacing clinician-mediated interpretation models. This behavioral pivot is most visible in Victoria's private endocrinology clinics, where patient-driven device selection now precedes specialist recommendation.
Australia Blood Glucose Monitoring Market Segmentation
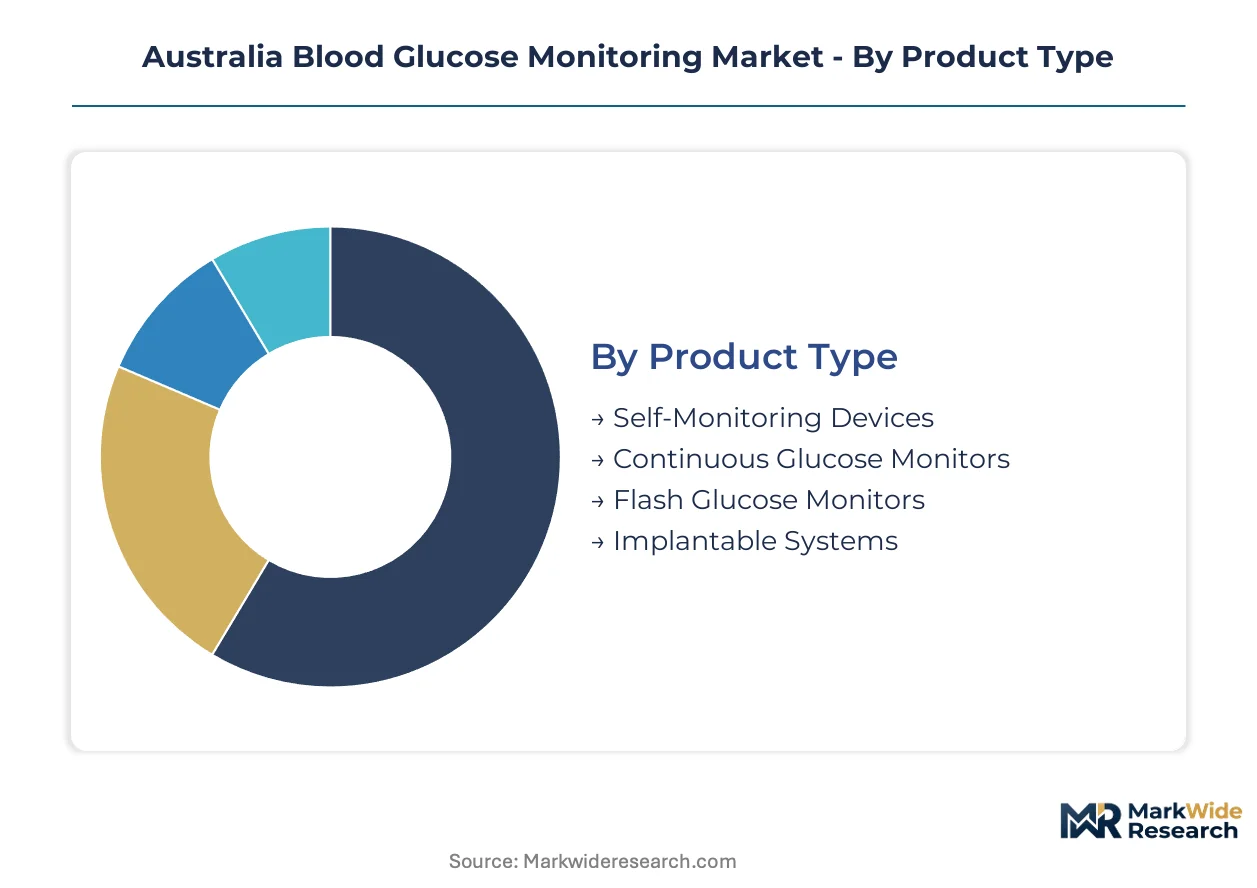
Segmentation in Australia's blood glucose monitoring market reveals how patient physiology, care setting, and reimbursement access fragment purchasing behavior. TGA pathways and private health fund schedules create divergent commercial trajectories across each dimension.
Product Type:
Cost tier determines whether patients bear full out-of-pocket expense or secure partial reimbursement through private health funds.
- Self-Monitoring Devices:Fingerstick-based electrochemical meters with disposable test strips remain the lowest-cost entry point. Demand concentrates in regional Queensland and Western Australia where specialist access is limited and patients self-fund consumables.
- Continuous Glucose Monitors:Subcutaneous electrochemical sensors transmit real-time glucose data to receivers or smartphones. Melbourne and Sydney endocrinology practices prescribe these devices at accelerating rates, compressing the addressable market for traditional meters.
- Flash Glucose Monitors:Factory-calibrated sensors enable intermittent scanning without continuous alerts. These devices occupy a mid-tier reimbursement position that appeals to tech-adherent Type 2 patients seeking data visibility without alarm fatigue.
- Implantable Systems:Long-duration sensors inserted subcutaneously for months-long monitoring cycles. These systems target insulin-requiring patients with needle aversion or skin sensitivity to adhesive-based external sensors.
Self-Monitoring Devices lead volumes today; Continuous Glucose Monitors are gaining share fastest.
Technology:
Application context determines whether accuracy specifications or convenience features dominate procurement decisions.
- Electrochemical Sensors:Glucose oxidase or glucose dehydrogenase reactions generate measurable current proportional to blood glucose concentration. These sensors dominate both self-monitoring and continuous monitoring platforms due to established manufacturing scale and TGA validation pathways.
- Optical Sensors:Near-infrared spectroscopy or Raman scattering techniques measure glucose through skin without blood extraction. Research institutes in Victoria pilot these systems for non-invasive monitoring, though accuracy limitations constrain clinical adoption.
- Enzymatic Sensors:Biological catalysts immobilized on electrodes accelerate glucose-specific reactions. These sensors appear in legacy hospital-based point-of-care devices with established pathology laboratory integration.
- Microfluidic Technology:Miniaturized fluid channels enable sample processing with microliter blood volumes. Home Care settings in New South Wales adopt these systems for pediatric and geriatric patients with low blood volume tolerance.
Electrochemical Sensors anchor current installed base; Microfluidic Technology is climbing the fastest as patient convenience priorities intensify.
Application:
Patient physiology and disease progression stage create distinct monitoring intensity requirements and reimbursement eligibility.
- Type 1 Diabetes:Absolute insulin deficiency mandates intensive glucose monitoring for dosing decisions. Continuous glucose monitor adoption concentrates among this cohort due to private health fund coverage and endocrinologist advocacy in metropolitan Sydney.
- Type 2 Diabetes:Insulin resistance with progressive beta-cell failure generates the largest patient volume but variable monitoring adherence. Self-monitoring dominates in regional areas; continuous systems penetrate insulin-requiring subsets with private insurance.
- Gestational Diabetes:Glucose intolerance during pregnancy requires short-duration intensive monitoring. Diagnostic Laboratories in Victoria process bulk glucose tolerance tests while Home Care devices support between-visit self-management.
- Prediabetes Monitoring:Elevated glucose below diabetes threshold prompts lifestyle intervention tracking. Pharmacies in Queensland retail entry-level meters to this preventive health segment with limited specialist involvement.
Type 2 Diabetes generates highest absolute volumes; Type 1 Diabetes shows steepest expansion trajectory as closed-loop insulin delivery integrates with continuous monitoring.
End User:
Procurement authority and reimbursement pathway determine whether devices are patient-purchased, clinic-provisioned, or institution-contracted.
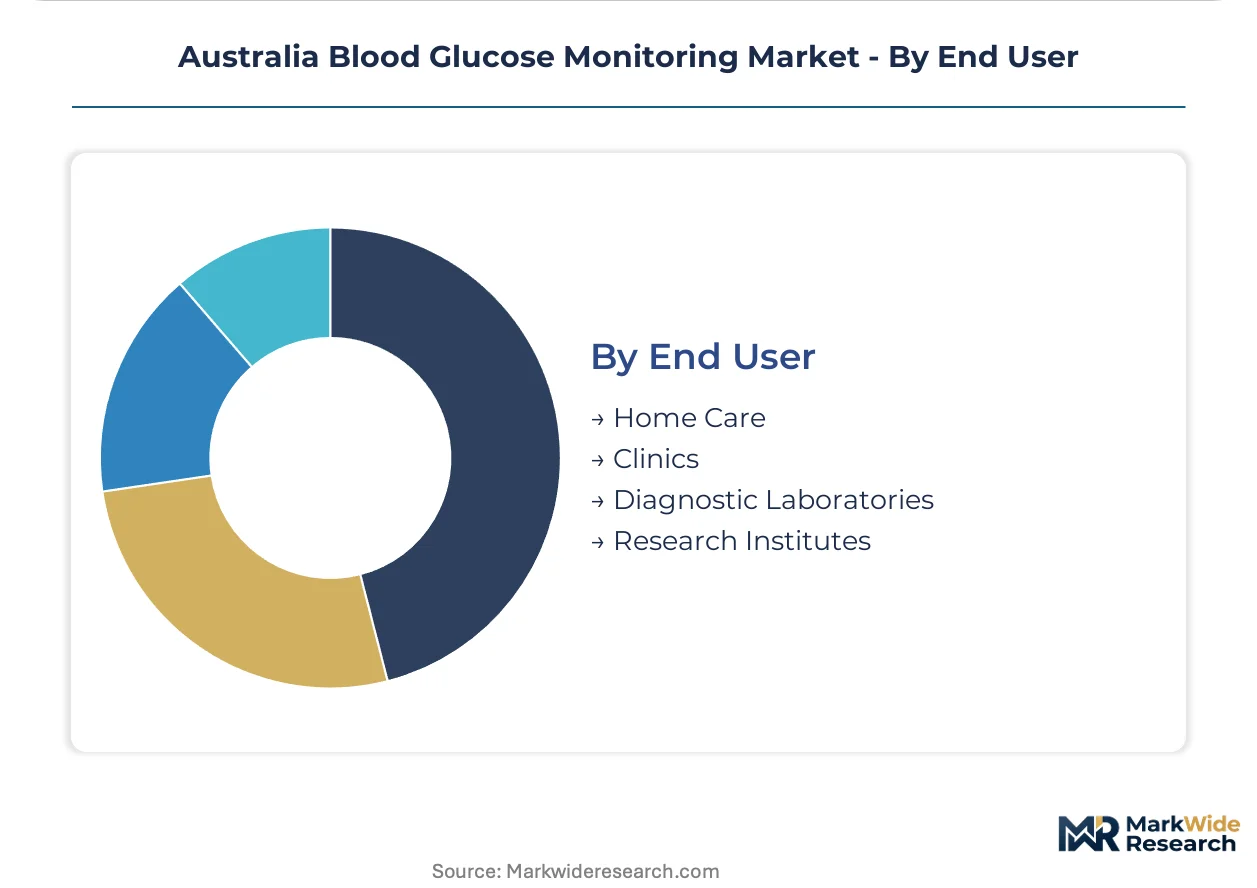
- Home Care:Patients or caregivers acquire devices through retail pharmacy, online direct-to-consumer, or private health fund subsidy. New South Wales and Victoria concentrate this demand due to higher disposable income and specialist prescription rates.
- Clinics:Endocrinology and credentialled diabetes educator practices procure point-of-care devices for in-consultation assessment. These settings influence patient device selection through prescription authority and reimbursement form assistance.
- Diagnostic Laboratories:Pathology networks operate centralized glucose testing with high-throughput analyzers. Hospital contracts in Melbourne and Sydney anchor this segment with integrated data management platform requirements.
- Research Institutes:Universities and medical research organizations pilot novel sensor technologies. These users prioritize data granularity and interoperability over cost minimization, creating premium demand for research-grade continuous monitors.
Home Care dominates device shipments; Clinics are expanding most quickly as specialist prescribing authority drives continuous monitor uptake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diabetes management technologies in Australia trace their clinical integration to the 1980s expansion of pathology laboratory networks and the subsequent decentralization of glucose testing into community pharmacy channels. The current market geography reflects this evolution, with metropolitan concentration of specialist services and persistent access gaps in remote territories.
New South Wales
Sydney's endocrinology corridor generates concentrated demand for continuous glucose monitors as private health fund coverage expands. TGA's streamlined software-as-medical-device pathways accelerate product registration for manufacturers targeting this high-prescribing cluster. The Northern Rivers and Central Coast regions exhibit slower adoption due to limited credentialled diabetes educator availability.
Victoria
Melbourne's private endocrinology practices prescribe flash and continuous monitoring systems at rates exceeding national averages. The state's Diabetes Australia branch administers subsidized device access programs for low-income patients. Regional Victoria, particularly the Gippsland and Grampians areas, relies predominantly on self-monitoring due to specialist service scarcity.
Queensland
Brisbane anchors device distribution through major pharmacy chains and private hospital networks. The state's rural and remote health districts, including Cape York and the Torres Strait, present persistent access challenges for sensor-based technologies. Queensland Health's telehealth expansion programs aim to bridge this gap through remote patient monitoring reimbursement pilots.
Western Australia
Perth's metropolitan diabetes services concentrate continuous glucose monitor prescribing among insulin-requiring patients with private insurance. The Pilbara and Kimberley regions exhibit the nation's lowest device penetration rates due to supply chain distances and limited specialist outreach. Aboriginal Community Controlled Health Services in these areas pilot culturally adapted glucose management programs.
Australia Blood Glucose Monitoring Market Competitive Landscape
Premium-margin players sit above commodity-margin players across reimbursement access and data integration capabilities, creating a tiered competitive structure. The vendor base clusters around three strategic archetypes: multinational medical device conglomerates with established TGA relationships, specialized diabetes technology firms with endocrinologist-focused commercial models, and emerging sensor developers pursuing partnership pathways rather than independent regulatory submissions. Dominant competitive moves include vertical integration into data analytics platforms and strategic alliances with private health funds to secure preferred reimbursement status.
Within the multinational conglomerate tier, Abbott Diabetes Care and Roche Diabetes Care exemplify divergent channel strategies, with the former dominating retail pharmacy distribution and the latter anchoring hospital and pathology laboratory contracts. Dexcom occupies a specialized position representing the pure-play continuous glucose monitor archetype, competing through intensive specialist engagement and private health fund reimbursement pathway development. These three companies collectively illustrate how scale, specialization, and channel focus segment competitive positioning in the Australian market.
| Leading Market Players |
|---|
| Abbott Diabetes Care |
| Dexcom |
| Medtronic |
| Roche Diabetes Care |
| Ascensia Diabetes Care |
| Everesense |
| Johnson & Johnson |
| Senseonics Holdings |
| Bionime Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive sensor manufacturing by Abbott Diabetes Care and Dexcom anchors both supply security and premium pricing power in the Australian continuous glucose monitor segment. These vertically integrated producers control electrochemical sensor fabrication and algorithm development, enabling sustained margin capture against test strip commoditization while TGA compliance costs deter price competition from smaller entrants.
Pricing Analysis
Subscription-based sensor replacement models dominate revenue architecture across continuous and flash glucose monitoring tiers. Price differentiation rests on real-time data integration depth and private health fund rebate eligibility rather than hardware specifications alone. Cost compression in the self-monitoring tier intensifies as pharmacy chains consolidate test strip procurement and generic alternatives displace branded consumables. Uninsured Type 2 diabetes patients in regional Western Australia exhibit highest price sensitivity, while privately insured Type 1 cohorts in Sydney demonstrate lowest elasticity due to rebate coverage.
Supply Chain Analysis
Electrochemical sensor membrane chemistry rests on Japanese and German specialty polymer producers for glucose-selective coatings and biocompatible adhesives. Subcutaneous needle assemblies draw from precision metalworking clusters in Switzerland and the United States, while semiconductor components for wireless transmission feed from Taiwanese foundries. Single-source vulnerability concentrates in the enzyme immobilization substrate layer, where proprietary formulations limit supplier switching. Distribution runs through hospital pharmacy consignment, retail pharmacy chains, and direct-to-consumer channels with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia blood glucose monitoring market compounds steadily as aging demographics and TGA regulatory streamlining sustain device upgrade cycles across successive patient cohorts.
For Market Incumbents: To counter interoperability fragmentation eroding ecosystem lock-in, deepen vertical control over data analytics platforms and pursue exclusive private health fund preferred-provider agreements. Secure TGA software-as-medical-device pre-certifications for algorithm updates to compress competitor time-to-market advantages. For New Entrants and Emerging Players: Enter via remote Indigenous health service contracts in Northern Territory and Western Australia, where incumbent specialist networks remain thin and culturally adapted delivery models create defensible positioning. Target Aboriginal Community Controlled Health Services with telehealth-integrated glucose monitoring bundled with diabetes educator outreach. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier sensor developers because TGA compliance burdens and private health fund rebate pathway complexity favor scaled players with existing regulatory infrastructure and payer relationships. Watch Medicare Benefits Schedule remote patient monitoring amendments as the inflection signal for continuous glucose monitor subsidy expansion.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Software-as-Medical-Device Pre-Certification | Accelerates algorithm update deployment while elevating cybersecurity compliance barriers for rivals. |
| Private Health Fund Preferred Provider Agreement | Locks in rebate pathway exclusivity and reduces patient out-of-pocket switching incentives. |
| Remote Indigenous Health Service Partnership | Opens underpenetrated Northern Territory and Western Australia markets with culturally adapted delivery. |
| Data Analytics Platform Integration | Captures recurring software revenue and strengthens ecosystem stickiness against interoperability mandates. |
| Medicare Benefits Schedule Alignment Strategy | Positions for anticipated remote patient monitoring reimbursement expansion and subsidized prescription growth. |
Research Methodology
Bottom-up end-user modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with endocrinologists, credentialled diabetes educators, hospital biomedical engineers, private health fund reimbursement managers, and pharmacy procurement directors combined with secondary validation from TGA device registration databases, Medicare Benefits Schedule amendment records, Diabetes Australia program reports, and private health insurance rebate schedule filings. Triangulation across these sources calibrated patient-level adoption assumptions against supply-side shipment data.
Historical trendline analysis of continuous glucose monitor prescribing rates in Melbourne and Sydney specialist practices informed the projection framework across the analysis window. Segmentation dimensions modeled include product type tier, patient diabetes classification, reimbursement eligibility status, and metropolitan versus regional geography. CAGRs derived from fitted adoption curves incorporating TGA approval velocity, private health fund coverage expansion timing, and endocrinologist density gradients. Forecast inputs incorporated sensor replacement cycle frequencies and algorithm update deployment patterns.
Inputs from TGA registration databases and private health fund rebate schedules were available through the study window; gaps in real-time patient out-of-pocket expenditure data introduce uncertainty bands around price elasticity assumptions. Forecasts reflect documented assumptions regarding MBS amendment timing and telehealth reimbursement pilot scalability. Regulatory delay risk, sensor supply disruption, and cybersecurity incident frequency warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Asia Pacific Diabetes Pen Market
Diabetes Care
Saudi Arabia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Type 2 Diabetes Market
Diabetes Care
Italy Oral Anti-Diabetic Drug Market
Diabetes Care
Self-Monitoring Blood Glucose Strips Market
Diabetes Care
Global Smart Insulin Pens Market
Diabetes Care
Japan Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Digital Diabetes Management Market
Diabetes Care
Germany Insulin Infusion Pump Market
Diabetes Care
South Korea Insulin Infusion Pump Market
Diabetes Care
Middle East and Africa Continuous Glucose Monitoring Market
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
Continuous Glucose Monitoring in Philippines Market
Diabetes Care
Type 2 Diabetes Drugs and Devices Market
Diabetes Care
Oman Insulin Drugs and Delivery Devices Market
Diabetes Care
Latin America Diabetes Care Devices Market