
 Global Orphan Drugs Market | 2026-2036
Global Orphan Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Orphan Drugs Market Outlook
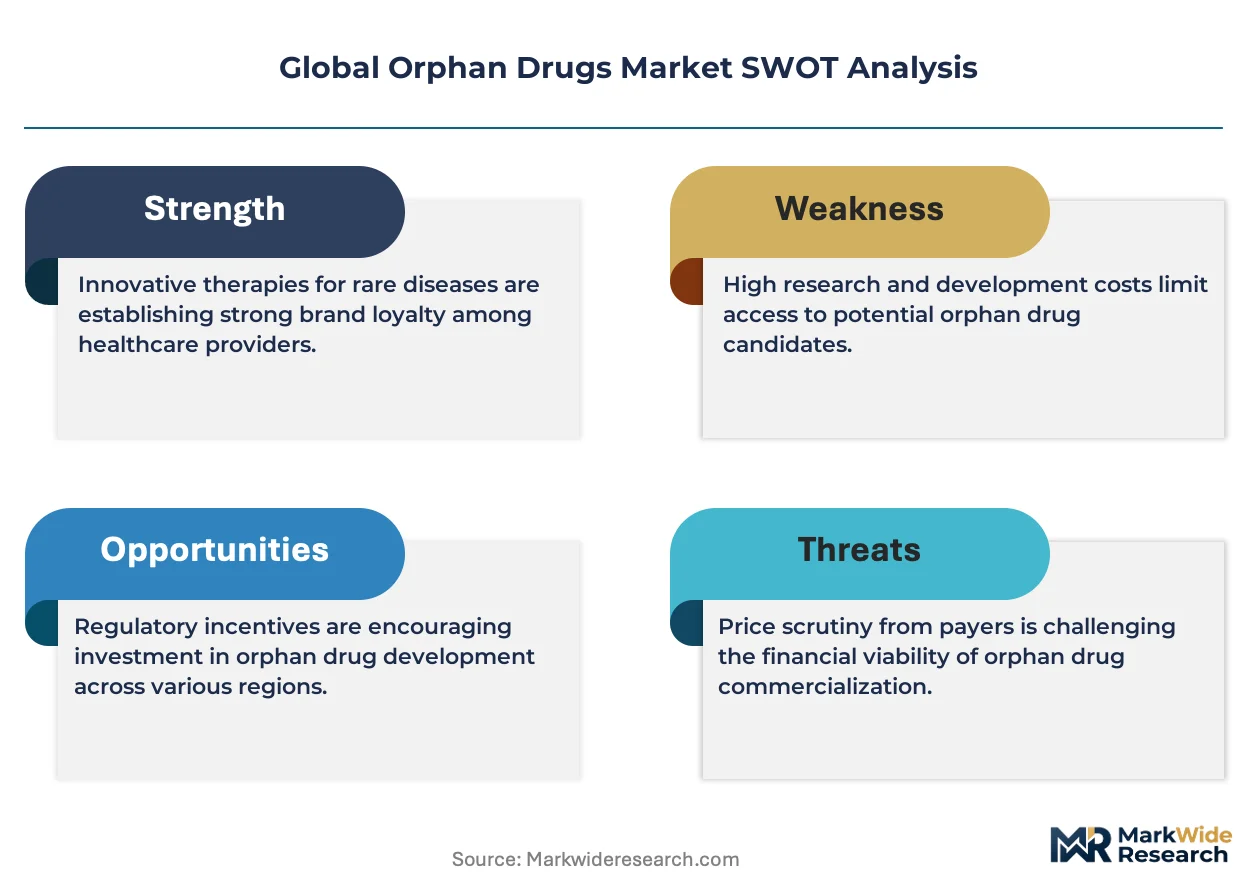
Outcome-based pricing and risk-sharing agreements is repositioning how orphan drug value gets captured across the treatment lifecycle. F. Hoffmann-La Roche Ltd. leverages its diagnostic-drug pairing capabilities to anchor companion testing with therapy delivery. Novartis AG sustains leadership through gene therapy manufacturing scale and specialized distribution networks. Bristol-Myers Squibb Company differentiates via its immuno-oncology portfolio depth in rare tumor indications.
Orphan drugs are pharmaceutical agents developed to treat rare diseases affecting fewer than 200,000 patients in the United States or comparable prevalence thresholds elsewhere, typically requiring biologic manufacturing platforms, cold-chain logistics, and batch sizes measured in kilograms rather than metric tons. Their primary purpose is to address unmet medical needs in patient populations too small to justify conventional drug development economics. Monoclonal antibodies occupy the largest revenue pool among product types due to established manufacturing infrastructure and broad rare disease applicability. Gene therapies represent the fastest-expanding segment, with structural margins concentrated in one-time curative regimens that challenge traditional reimbursement models. Neurological disorders within the therapy area dimension command premium pricing power driven by progressive disease trajectories and limited therapeutic alternatives.
The FDA Orphan Drug Act grants seven-year market exclusivity and tax credits for clinical trials, while EMA orphan designation provides protocol assistance and reduced regulatory fees across European member states. The EU AI Act and MDR frameworks are tightening evidentiary requirements for novel modalities including cell and gene therapies. China's NMPA has accelerated rare disease drug review pathways under its priority review voucher system. Stakeholders must monitor how converging regulatory timelines across FDA, EMA, and NMPA reshape first-mover advantages and parallel submission strategies.
Market Dynamics
Gene therapy manufacturing scale and companion diagnostic pairing are compressing development timelines while fragmenting value capture across the treatment lifecycle.
Growth Catalysts
- FDA Orphan Drug Act:Seven-year market exclusivity and clinical trial tax credits reduce development risk for rare disease indications. The framework incentivizes biologics platforms.
- Specialty clinic networks:Dispensing infrastructure for cold-chain biologics is expanding across tertiary care centers. These facilities anchor patient access and adherence monitoring.
- EMA protocol assistance:Reduced regulatory fees and scientific advice streamline European orphan designations. Parallel FDA-EMA submissions accelerate market entry timelines.
Market Restraints
- Batch manufacturing constraints:Kilogram-scale biologics production limits economies of scale. Viral vector capacity for gene therapies concentrates at single-source contract manufacturers.
- Reimbursement fragmentation:Payer heterogeneity across national health systems creates pricing arbitrage risks. Germany's AMNOG early benefit assessment imposes cost-effectiveness ceilings.
- Patient identification bottlenecks:Ultra-rare prevalence requires diagnostic infrastructure that lags therapeutic availability. Genetic testing penetration varies sharply by healthcare system maturity.
Strategic Opportunities
- China's priority review voucher system:NMPA accelerated pathways for rare disease drugs reduce regulatory lag versus standard biologics approvals. Domestic partnership requirements favor local licensing structures.
- One-time curative regimens:Gene therapies displace chronic administration models. Annuity-style payment structures and outcomes-based contracts address budget impact concerns.
- Neurological disorder expansion:Progressive disease trajectories with limited alternatives command premium positioning. Spinal muscular atrophy and amyotrophic lateral sclerosis represent adjacent indication white space.
Industry Challenges
- Viral vector manufacturing talent scarcity:Cell culture and purification expertise for AAV and lentiviral platforms concentrates at a handful of academic centers and contract development organizations.
- Cold-chain logistics integrity:Temperature excursion risks during distribution to dispersed patient populations require redundant monitoring systems. Last-mile delivery in emerging markets lacks validated infrastructure.
- Companion diagnostic co-development:Parallel FDA Center for Devices and Radiological Health and Center for Drug Evaluation and Review timelines create synchronization risks. Biomarker validation delays can stall therapeutic approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Orphan Drugs Market |
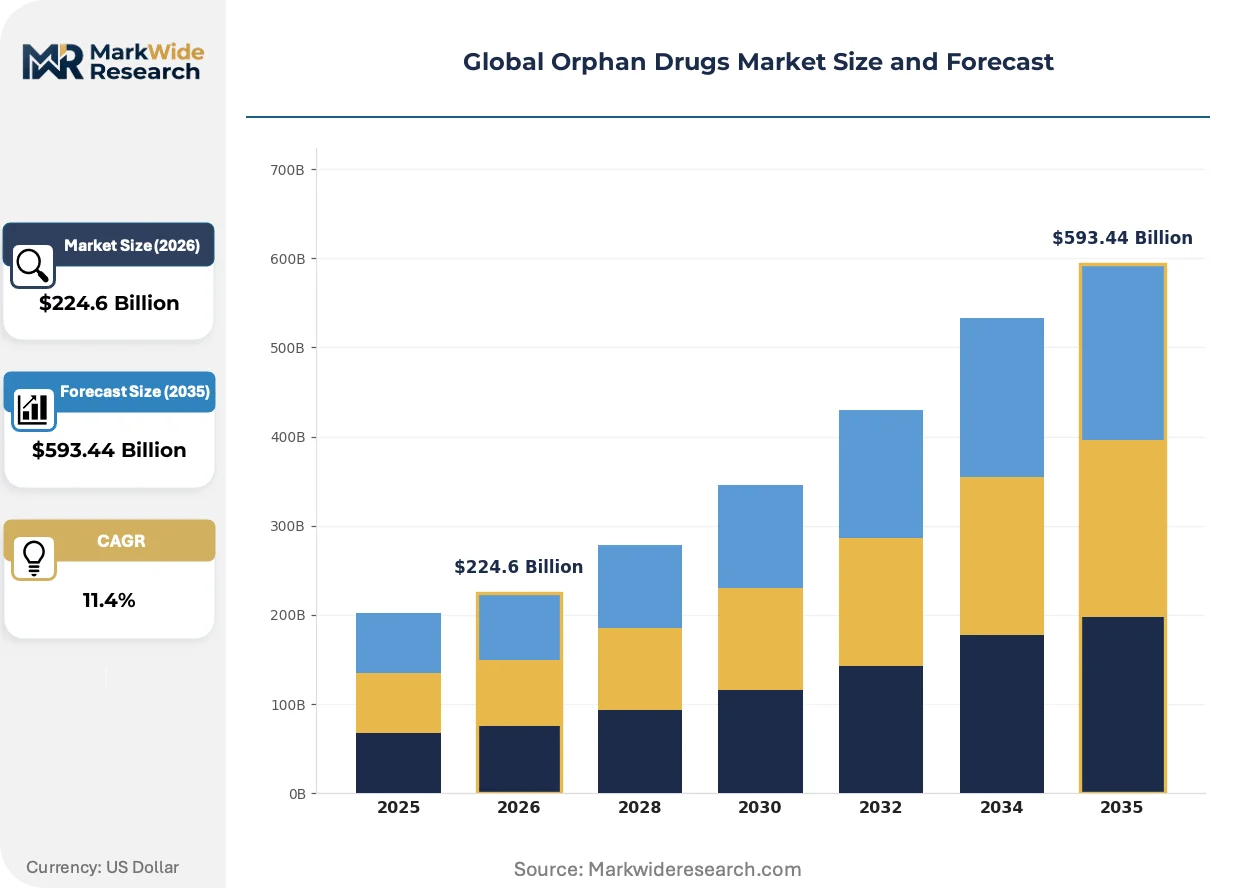
| Market Size in 2026 | $224.6 Billion |
| Market Size in 2035 | $593.44 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Enzyme Replacement Therapies, Gene Therapies, Protein Therapies Therapy Area: Neurological Disorders, Hematological Disorders, Rare Cancers, Endocrine Disorders End User: Hospitals, Specialty Clinics, Research Institutions, Home Care Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral |
| Companies Covered | F. Hoffmann-La Roche Ltd., Bristol-Myers Squibb Company, Novartis AG, Johnson & Johnson Services Inc., Biogen Inc., Pfizer Inc., AstraZeneca, Amgen Inc., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Orphan Drugs Market Strategic Shifts
Platform standardization and regulatory convergence are compressing the gap between scientific breakthrough and commercial accessibility for rare disease modalities.
CRISPR-based gene editing is expanding into inherited hematologic disorders as the core therapeutic mechanism. Academic medical centers and specialty pharmacy networks are adopting these platforms faster than traditional hospital systems can absorb them. Manufacturing scale-up for allogeneic cell therapies is expanding into modular facility designs that reduce capital intensity.
The EU AI Act and MDR frameworks are tightening evidentiary requirements for algorithm-driven diagnostic tools used in patient selection. Cell and gene therapy sponsors must now submit computational validation packages alongside clinical data. European notified bodies are extending review timelines for novel modalities, compressing first-mover advantages for parallel FDA-EMA filers.
Patient advocacy organizations are consolidating procurement influence through specialized pharmacy benefit managers. Rare disease foundations in the United States now direct formulary placement discussions through dedicated reimbursement navigators. This channel shift is most visible in oncology and immunology indications where foundation-sponsored access programs bridge coverage gaps.
Global Orphan Drugs Market Segmentation
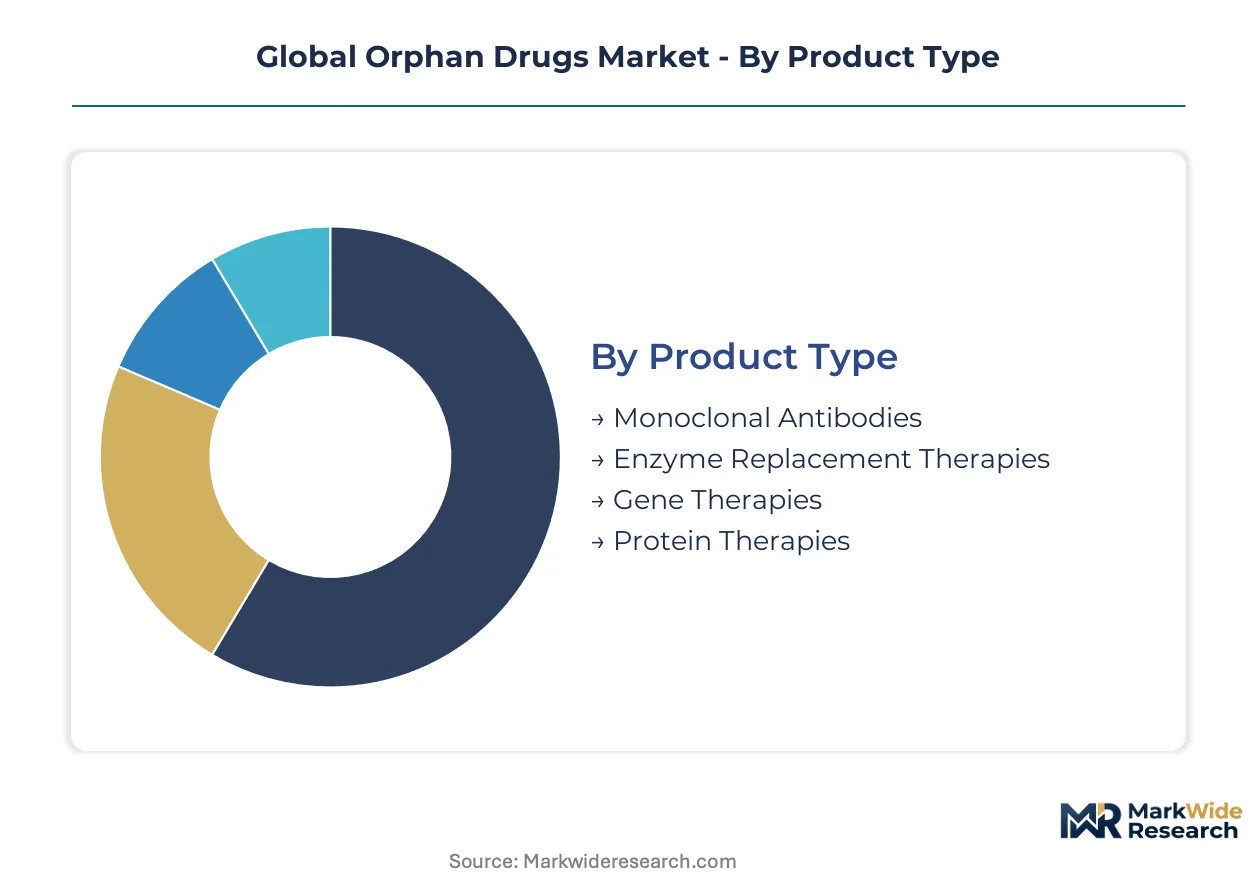
Orphan drug segmentation reveals how manufacturing complexity, regulatory pathways, and patient access infrastructure fragment commercial opportunities across distinct product and delivery categories. Each dimension carries unique certification burdens and reimbursement mechanics that reshape competitive positioning.
Product Type:
FDA Center for Biologics Evaluation and Review oversight intensifies with molecular sophistication, with gene therapies requiring IND-enabling GLP toxicology studies that monoclonal antibodies bypass through established platform master files.
- Monoclonal Antibodies:Established mammalian cell culture platforms yield consistent glycosylation profiles. Demand concentrates in United States specialty oncology clinics where companion diagnostic pairing streamlines prior authorization.
- Gene Therapies:Viral vector manufacturing requires FDA Chemistry, Manufacturing, and Controls documentation for each serotype modification. Germany's university hospital networks anchor European patient access through centralized treatment centers.
- Enzyme Replacement Therapies:Recombinant protein production leverages CHO cell lines with decades of regulatory precedent.
- Protein Therapies:Fusion proteins and cytokine analogs occupy mid-tier manufacturing complexity between antibodies and gene modalities.
Monoclonal antibodies sit at the top of the volume ranking, with gene therapies climbing the fastest.
Therapy Area:
EMA scientific advice timelines vary by disease prevalence, with ultra-rare neurological indications receiving accelerated protocol assistance that hematological disorders with larger patient pools cannot access.
- Neurological Disorders:Blood-brain barrier penetration requirements drive intrathecal delivery specialization. Japan's PMDA has established dedicated review teams for amyotrophic lateral sclerosis and spinal muscular atrophy candidates.
- Rare Cancers:Tumor-agnostic biomarker approvals expand addressable populations beyond histology-defined subsets. United States community oncology practices increasingly refer patients to academic centers for molecularly targeted trials.
- Hematological Disorders:Bone marrow transplant conditioning regimens create combination therapy opportunities.
- Endocrine Disorders:Hormone replacement analogs face biosimilar competition pressure in mature markets.
Neurological disorders command the steepest pricing premiums, with rare cancers gaining share fastest through biomarker expansion.
End User:
Reimbursement mechanics diverge sharply by care setting, with United States hospital outpatient prospective payment systems creating site-of-service arbitrage that European DRG-based systems suppress.
- Specialty Clinics:Cold-chain handling infrastructure and REMS program administration concentrate in tertiary care-affiliated dispensaries. France's ANSM mandates specialized pharmacy certification for gene therapy distribution.
- Hospitals:Inpatient gene therapy administration requires bone marrow transplant unit adjacency for adverse event management. China's NMPA restricts CAR-T dispensing to Grade 3A hospitals with ICU backup.
- Research Institutions:Academic medical centers anchor expanded access programs and compassionate use pathways.
- Home Care:Subcutaneous formulations enable self-administration for stable chronic indications.
Specialty clinics dominate current dispensing volume, with home care infrastructure expanding most quickly for subcutaneous biologics.
Delivery Mode:
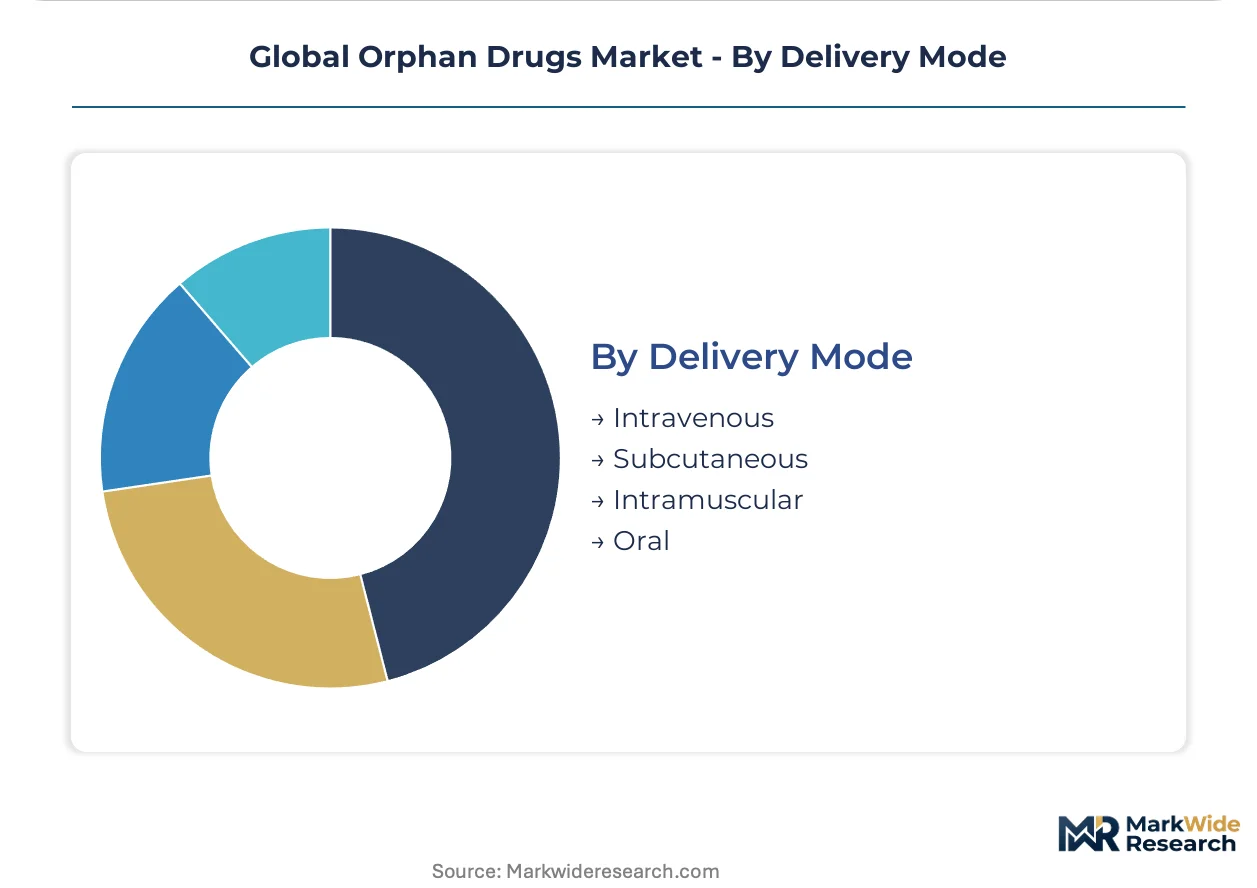
Route selection determines cold-chain intensity and patient compliance economics, with intravenous formulations requiring infusion center capacity that subcutaneous alternatives circumvent.
- Intravenous:Infusion duration and monitoring requirements anchor revenue to hospital outpatient departments. Germany's AMNOG assessment specifically evaluates infusion center productivity impact in cost-effectiveness calculations.
- Subcutaneous:Prefilled syringe and autoinjector formats reduce healthcare professional time burden. United States specialty pharmacy distribution networks prioritize these formulations for patient adherence programs.
- Intramuscular:Depot formulations extend dosing intervals for chronic enzyme replacement.
- Oral:Small molecule orphan indications leverage conventional pharmacy distribution with limited cold-chain burden.
Intravenous administration retains the highest procedure volume, with subcutaneous delivery gaining share fastest through patient convenience differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States captures the steepest pricing premiums for neurological orphan indications, while Germany enforces the tightest cost-effectiveness ceilings through early benefit assessments. Japan accelerates review timelines for ultra-rare diseases through dedicated PMDA teams.
United States
Specialty oncology clinics and academic medical centers anchor patient access infrastructure. The FDA Orphan Drug Act grants seven-year market exclusivity and clinical trial tax credits. The Greater Boston biotech corridor concentrates gene therapy manufacturing and viral vector production capacity.
Germany
University hospital networks centralize gene therapy administration and bone marrow transplant adjacency requirements. The AMNOG early benefit assessment imposes cost-effectiveness ceilings on orphan drug pricing. The Munich and Heidelberg clusters anchor European clinical trial enrollment and centralized treatment center certification.
Japan
PMDA dedicated review teams compress timelines for amyotrophic lateral sclerosis and spinal muscular atrophy candidates. The Sakigake designation system provides priority review vouchers for rare disease innovations. The Kanto region around Tokyo concentrates specialty pharmacy distribution and patient advocacy organization headquarters.
China
NMPA priority review vouchers accelerate rare disease drug approvals versus standard biologics pathways. Grade 3A hospital requirements with ICU backup restrict CAR-T and gene therapy dispensing to major urban centers. The Yangtze River Delta and Beijing-Tianjin-Hebei clusters concentrate domestic partnership licensing and manufacturing joint ventures.
Switzerland
Swissmedic alignment with EMA scientific advice streamlines parallel European submission strategies. The Basel pharmaceutical corridor anchors diagnostic-drug pairing capabilities and companion test co-development. Geneva-based patient advocacy organizations influence procurement negotiations across European national health systems.
Global Orphan Drugs Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated pharmaceutical conglomerates commanding gene therapy platforms and mid-cap biotech firms anchoring monoclonal antibody niches. Market structure tilts toward consolidation at the top tier where manufacturing scale and regulatory expertise concentrate, while fragmentation persists in enzyme replacement and protein therapy categories. Three archetypes dominate: diagnostic-therapy paired integrators, gene therapy manufacturing specialists, and immuno-oncology portfolio builders. Competitive moves center on companion diagnostic co-development partnerships and viral vector manufacturing capacity expansion through single-source contract arrangements.
Within the diagnostic-therapy integration tier, F. Hoffmann-La Roche Ltd. exemplifies the pairing of companion testing with therapeutic delivery. Novartis AG occupies a position at the gene therapy manufacturing scale end of the spectrum. Bristol-Myers Squibb Company sits within the immuno-oncology depth archetype for rare tumor indications. These three Swiss and US-based entities anchor distinct strategic positioning vectors without overlapping core capabilities.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Bristol-Myers Squibb Company |
| Novartis AG |
| Johnson & Johnson Services Inc. |
| Biogen Inc. |
| Pfizer Inc. |
| AstraZeneca |
| Amgen Inc. |
| Sanofi |
| Others |
Value Chain & Pricing Dynamics
Curative gene therapy premiums versus chronic biologic maintenance tiers split the orphan drug landscape into divergent value capture models, with one-time administration regimens commanding multimillion-dollar price points that amortize across years while enzyme replacement therapies face compressed margins under indication-stacking pressures. This bifurcation concentrates manufacturing investment in viral vector capacity for the premium tier while pushing standard-tier production toward modular, multi-product facilities that sacrifice specialization for flexibility.
Pricing Analysis
Capacity additions in Switzerland and the United States are reshaping price floors for viral vector manufacturing as contract development organizations expand GMP suites. Three-tier pricing structure across premium curative, standard maintenance, and economy biosimilar levels stratifies by molecular complexity and exclusivity duration. Pricing pressure stems from Germany's AMNOG early benefit assessments imposing cost-effectiveness ceilings on neurological indications. Hospital outpatient departments demonstrate highest price sensitivity due to site-of-service arbitrage, while specialty clinics absorb premiums through foundation-sponsored access programs.
Supply Chain Analysis
Cold-chain freight costs for gene therapies run through validated container systems that consume 15-20% of product cost structure across transoceanic lanes. Viral vector manufacturing concentrates in the United States, Switzerland, and Germany, with plasmid DNA sourcing anchored in academic center spinouts. Supply chain risk centers on single-source AAV serotype production that lacks redundant qualification pathways. Distribution runs through specialty pharmacy networks with REMS certification rather than conventional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The orphan drug market rewards geographic arbitrage between the United States' premium pricing tolerance and China's accelerated regulatory pathways, with NMPA priority review vouchers compressing development timelines against FDA exclusivity premiums. Manufacturers must calibrate partnership structures to capture both value pools without triggering parallel trade or reference pricing contagion.
For Market Incumbents: Extend viral vector manufacturing footprints into modular facility designs that reduce capital intensity per indication. Secure companion diagnostic co-development partnerships ahead of FDA Center for Devices and Radiological Health timeline synchronization risks. Anchor capacity in the Greater Boston corridor where talent concentration supports AAV platform expertise against emerging contract manufacturer competition. For New Entrants and Emerging Players: Launch via China's domestic partnership licensing structures that satisfy NMPA local production requirements for priority review voucher eligibility. Target ultra-rare neurological disorders in Japan where PMDA dedicated review teams compress approval timelines for amyotrophic lateral sclerosis candidates. Pursue academic medical center alliances that anchor expanded access programs and compassionate use pathways ahead of formal reimbursement negotiations. For Investors and Strategic Acquirers: Consolidation pressure builds where viral vector manufacturing talent scarcity concentrates at single-source academic centers and contract development organizations. Long-term viability favors platforms with diagnostic-therapy integration capabilities and gene therapy manufacturing scale rather than monoclonal antibody niche players facing biosimilar erosion. Watch for inflection in foundation-sponsored procurement influence through specialized pharmacy benefit managers that redirect formulary placement discussions.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA Center for Devices and Radiological Health alignment with therapeutic timelines reduces approval synchronization risks. |
| Viral Vector Manufacturing Scale-Up | Modular GMP facility expansion in Switzerland and the United States addresses AAV and lentiviral capacity constraints. |
| China Domestic Partnership Licensing | NMPA local production requirements unlock priority review voucher pathways for rare disease indications. |
| Specialty Pharmacy Network Certification | REMS program administration and cold-chain integrity anchor patient access for gene therapy distribution. |
| Neurological Disorder Pipeline Expansion | PMDA dedicated review teams for spinal muscular atrophy compress Japanese approval timelines against standard pathways. |
Study Parameters
Direct dialogue with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers grounded qualitative assessment of manufacturing constraints and reimbursement mechanics. Secondary validation drew from FDA orphan drug designations, EMA scientific advice protocols, ClinicalTrials.gov enrollment data, and CMS Medicare Part B reimbursement schedules. Bottom-up patient population sizing and top-down market value triangulation cross-checked segment assumptions across therapy areas and geographic clusters.
Output metrics across the projection horizon reflect segmented modeling by product type, therapy area, and administration route dimensions with regional regulatory clusters overlaying geographic splits. CAGRs derived from historical approval velocity, pricing trajectory analysis, and manufacturing capacity expansion timelines. Forecast inputs incorporated gene therapy manufacturing batch success rates and companion diagnostic co-development synchronization risks specific to rare disease modalities.
Several conditions sit outside the modeled scope, including pipeline attrition beyond Phase II, regulatory pathway reversals, and geopolitical trade restrictions on biologics raw materials. Forecasts reflect assumptions on reimbursement persistence and manufacturing yield improvements that industry stakeholders validated. A model refresh is warranted upon material change in FDA-EMA-NMPA regulatory convergence timelines or viral vector manufacturing capacity expansion velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Interstitial Cystitis Drugs Market
Pharmaceuticals
Middle East and Africa Anti-Fungal Agents Market
Pharmaceuticals
Amylin Analogs Market
Pharmaceuticals
Global Transdermal Drug Delivery Systems Market
Pharmaceuticals
Europe Heparin Market
Pharmaceuticals
US Compounding Pharmacies Market
Pharmaceuticals
India Over-The-Counter Drugs (OTC) Market
Pharmaceuticals
Global Manidipine Hydrochloride Market
Pharmaceuticals
Azathioprine API Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
RNA-Targeted Small Molecules Market
Pharmaceuticals
Alopecia Drugs Market
Pharmaceuticals
Flavors Into Over-The-Counter (OTC) Pharmaceuticals Market
Pharmaceuticals
Oral Anti-Diabetic Drugs Market
Pharmaceuticals
Lithuania Pharmaceutical Market
Pharmaceuticals
Global Preventive Vaccines Market