
 Metominostrobin Market | 2026-2036
Metominostrobin Market Size, Share, and Industry Trends Forecast 2026-2036
Metominostrobin Market Analytics
Aftermarket technical support and crop advisory services is tilting margin pools away from pure product sales toward bundled agronomic solutions. Syngenta leverages its digital farming platform to extend service revenue per hectare treated. BASF anchors its position through backward integration into active ingredient synthesis. Summit Agro International specializes in niche rice-market formulations across Japanese prefectures.
Metominostrobin is a strobilurin fungicide with a methoxyiminoacetamide core structure, formulated as emulsifiable concentrates or water-dispersible granules for foliar application against rice blast and sheath blight. The fungicide segment dominates value contribution due to premium pricing for blast control in Japonica rice systems. Agricultural applications lead volume throughput, though turf management channels sustain higher per-unit margins through specialized distributor networks. Online retail is accelerating fastest among distribution channels as cooperatives consolidate procurement through digital platforms.
Japan's Ministry of Agriculture, Forestry and Fisheries enforces residue limits that filter non-compliant suppliers from premium rice segments. China's Ministry of Ecology and Environment implements emission standards that raise manufacturing compliance costs for domestic producers. The EU F-Gas Regulation and REACH framework restrict import pathways for non-European formulators. Stakeholders must monitor evolving maximum residue limits in target export markets before committing to capacity expansion decisions.
Market Dynamics
Rice blast resistance management protocols are forcing strobilurin fungicide rotations across East Asian monoculture systems, compressing product lifecycles and demanding continuous formulation innovation from active ingredient suppliers.
Growth Catalysts
- Japan's Positive List System:Agricultural chemical residue monitoring creates premium pricing tiers for compliant metominostrobin formulations, filtering substandard competitors from Japonica rice segments.
- Jiangsu Province Rice Monoculture:Concentrated planting patterns in China's eastern coastal belt generate predictable seasonal demand cycles for blast control applications.
- Sheath Blight Pressure:Escalating fungal disease incidence in high-yielding Indica varieties sustains prophylactic fungicide adoption rates across tropical rice belts.
Market Restraints
- Active Ingredient Supply Concentration:Captive production of methoxyiminoacetamide intermediates by Japanese and Chinese chemical conglomerates limits third-party formulator access.
- EU F-Gas Regulation:Import pathway restrictions for non-European formulators block market participation regardless of technical efficacy demonstrations.
- Cross-Resistance Development:Regional overreliance on single-site strobilurin modes of action accelerates pathogen adaptation, shortening effective product lifespans.
Strategic Opportunities
- Vietnam Mekong Delta Expansion:Underpenetrated commercial rice sectors in southern Vietnamese provinces present volume growth potential for water-dispersible granule formulations.
- Digital Cooperative Procurement:Platform-based purchasing consolidation among Chinese agricultural cooperatives creates direct manufacturer-to-farm channel bypass opportunities.
- Turf Management Diversification:Specialized distributor networks for golf course and sports field maintenance sustain higher per-unit margins than commodity rice applications.
Industry Challenges
- Residue Analytical Capacity:Laboratory testing bottlenecks for maximum residue limit compliance delay product registration timelines in target export markets.
- Formulation Patent Thickets:Complex intellectual property layering around strobilurin adjuvant systems restricts generic manufacturer market entry strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metominostrobin Market |
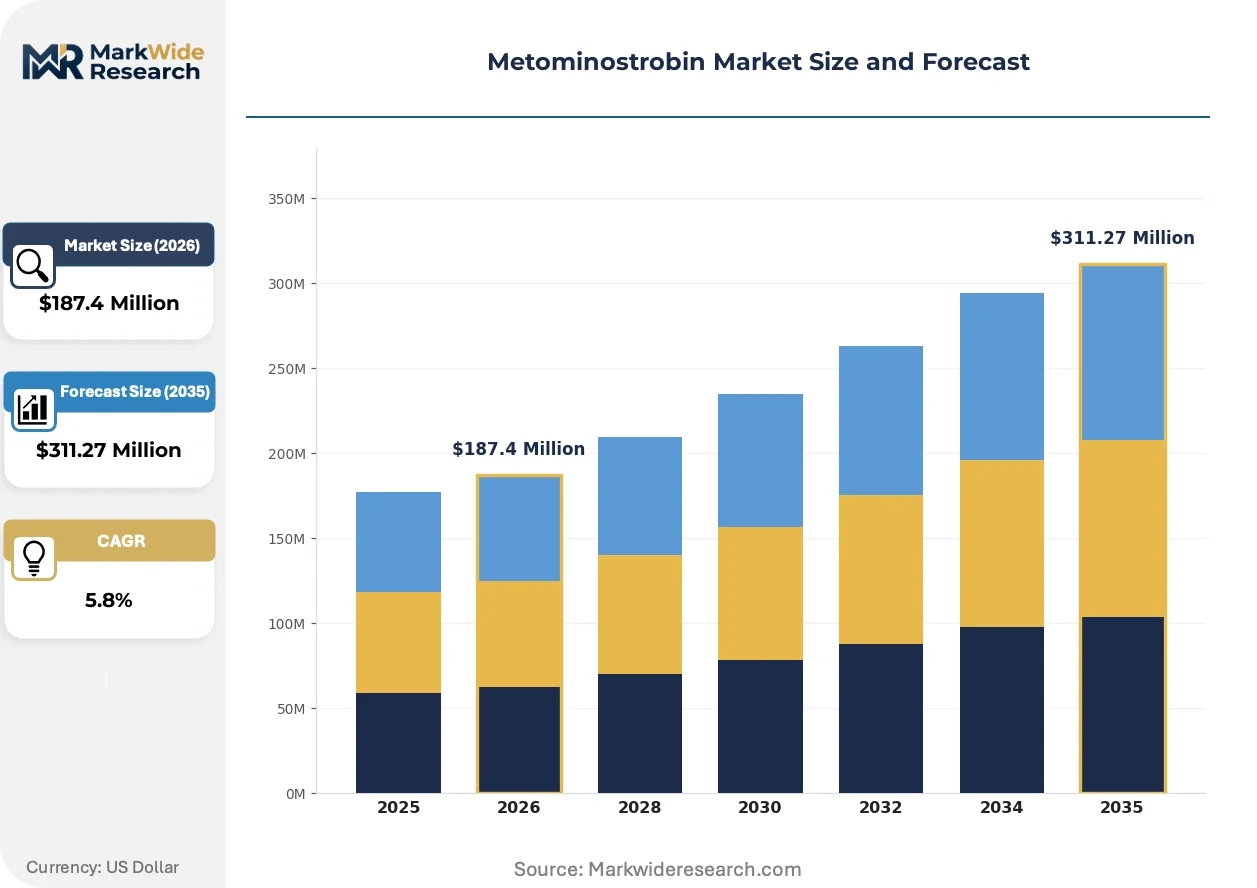
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fungicide, Herbicide, Insecticide, Growth Regulator Application: Agricultural, Horticultural, Turf Management, Forestry Distribution Channel: Online Retail, Agrochemical Suppliers, Distributors, Wholesale End User: Farmers, Agronomists, Landscapers, Agricultural Cooperatives |
| Companies Covered | Syngenta, Bayer CropScience, Sumitomo Corporation, Summit Agro International, BASF, FMC Corporation, ADAMA Agricultural Solutions, UPL, Nufarm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metominostrobin Market Evolving Landscape
Formulation chemistry and application precision technologies are converging to reshape fungicide value capture, moving competitive advantage from molecule ownership toward integrated disease management systems.
Drone-based variable-rate application systems are digitizing foliar fungicide deployment across Chinese rice cooperatives. Jiangsu and Zhejiang farming collectives now coordinate aerial spraying through centralized digital platforms. This shift is digitizing historical distributor relationships and compressing margin pools toward equipment-as-a-service providers.
China's Ministry of Ecology and Environment emission standards are tightening manufacturing compliance thresholds for domestic active ingredient producers. Facility upgrade mandates are diverting capital toward pollution control infrastructure. Domestic formulators with backward-integrated synthesis capabilities absorb these costs more efficiently than import-dependent competitors.
Rice miller procurement consolidation is altering fungicide specification authority. Large-scale milling operations in Japan now dictate active ingredient selection to contracted growers, displacing traditional agrochemical retailer influence. This concentration is most visible in Hokkaido and Niigata prefectures where integrated supply chains dominate quality rice production.
Metominostrobin Market Segmentation
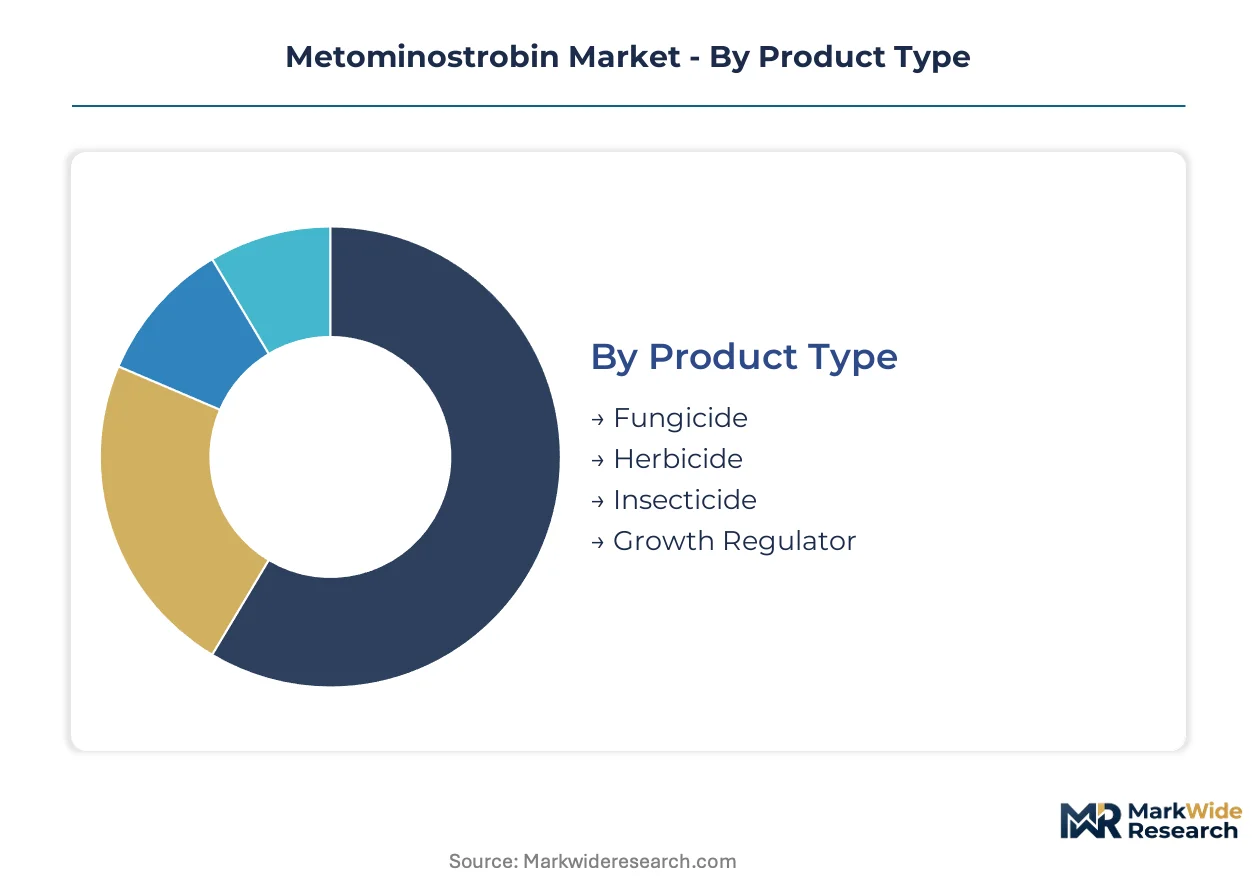
Segmentation in the metominostrobin market reveals how formulation chemistry, application setting, and procurement channel intersect to determine pricing power and customer loyalty. Distinct buyer behaviors across rice monoculture systems versus turf maintenance operations create divergent margin structures for active ingredient suppliers.
Product Type:
Mature chemistries dominate commercial volumes while novel modes of action carve out defensive positions against resistance development.
- Fungicide:Strobilurin formulations with methoxyiminoacetamide core structures target rice blast and sheath blight through foliar application. Demand concentrates in China's Jiangsu and Zhejiang provinces where Japonica rice monoculture sustains seasonal treatment cycles.
- Herbicide:Metominostrobin-adjuvant combinations suppress grassy weeds in paddy systems without phytotoxicity to cultivated varieties. Japanese prefectures with strict residue protocols drive premium-tier procurement for compliant formulations.
- Insecticide:Limited cross-functional applications address secondary pest pressure in integrated pest management protocols.
- Growth Regulator:Niche positioning for plant health enhancement in high-value horticultural export crops.
Fungicide retains volume leadership; growth regulator holds the steepest expansion curve.
Application:
Cost tier separation between commodity rice production and specialized turf maintenance creates divergent service models for formulators.
- Agricultural:Rice blast control in East Asian monoculture systems generates predictable seasonal demand through emulsifiable concentrate and water-dispersible granule formulations. China's eastern coastal belt anchors throughput volume.
- Turf Management:Golf course and sports field maintenance channels sustain higher per-unit margins through specialized distributor networks with technical advisory bundling.
- Horticultural:Protected cultivation systems in greenhouse clusters demand precision application compatibility.
- Forestry:Plantation timber protection against needle cast diseases in temperate conifer regions.
Agricultural commands absolute volume; turf management delivers margin density.
Distribution Channel:
Customer type fragmentation between individual growers and consolidated cooperatives is reconfiguring route-to-market economics.
- Online Retail:Platform-based purchasing consolidation among Chinese agricultural cooperatives accelerates fastest, digitizing historical distributor relationships and compressing margin pools toward equipment-as-a-service providers.
- Agrochemical Suppliers:Technical support bundling maintains relevance in Japan's positive list compliance environment.
- Distributors:Regional inventory positioning for just-in-time delivery during narrow application windows.
- Wholesale:Volume aggregation for large-scale farming operations with centralized procurement authority.
Agrochemical suppliers retain relationship depth; online retail gains share fastest.
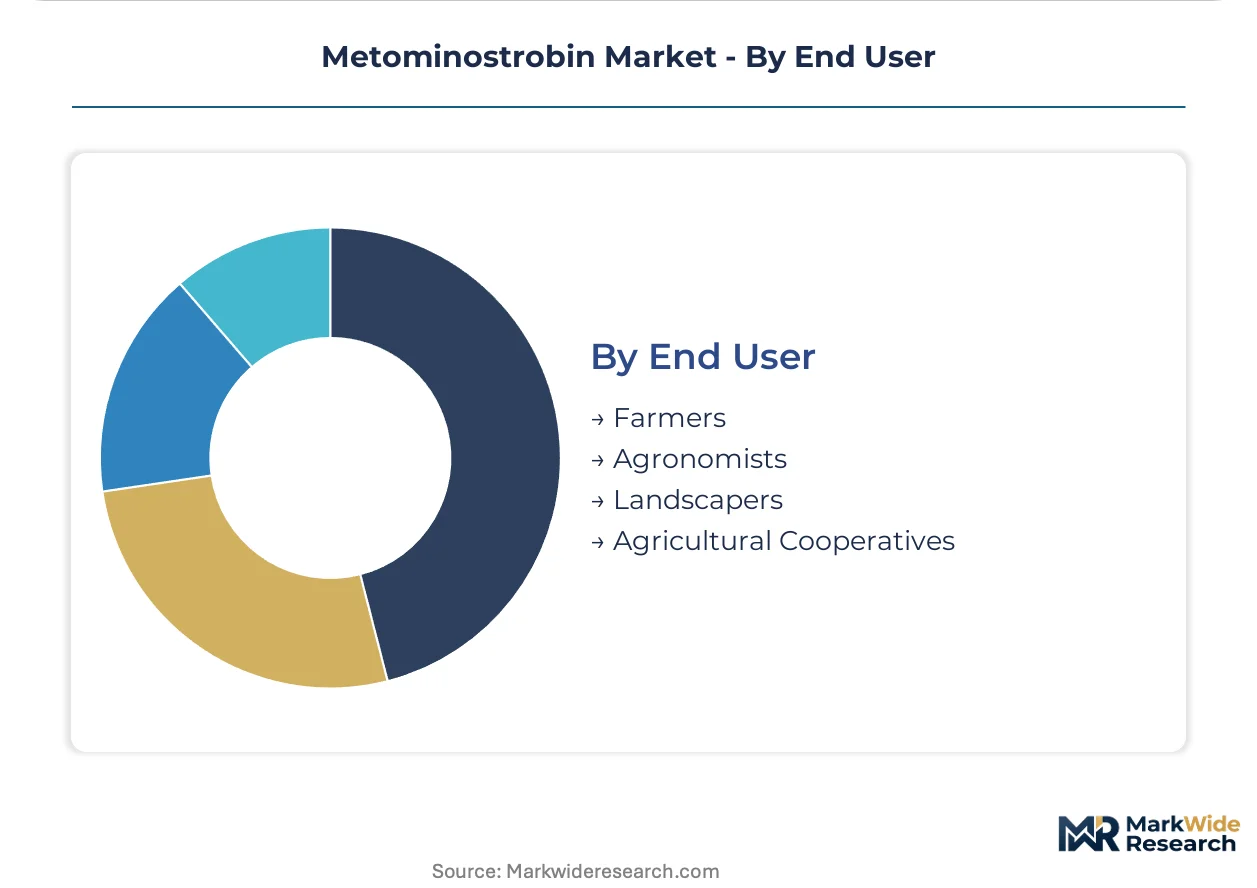
End User:
Supply concentration among rice miller procurement desks is displacing traditional retailer influence over active ingredient specification.
- Farmers:Individual growers in Vietnam's Mekong Delta present underpenetrated volume potential for water-dispersible granule formulations with simplified handling protocols.
- Agricultural Cooperatives:Centralized digital platforms in Jiangsu and Zhejiang farming collectives now coordinate aerial spraying procurement, bypassing legacy distributor tiers.
- Agronomists:Technical advisory services tilting margin pools toward bundled disease management solutions.
- Landscapers:Municipal and commercial turf maintenance contracts with specification authority for aesthetic quality thresholds.
Farmers represent absolute user volume; agricultural cooperatives climb the fastest on platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's Jiangsu and Zhejiang provinces demonstrate acute price sensitivity due to cooperative procurement consolidation, while Japanese prefectures exhibit inelastic demand for compliant formulations under residue monitoring protocols. This elasticity divergence shapes divergent go-to-market economics across East Asian rice belts.
China
Jiangsu and Zhejiang farming collectives drive concentrated seasonal demand for blast control applications in Japonica rice monoculture systems. The Ministry of Ecology and Environment enforces emission standards that raise manufacturing compliance costs for domestic active ingredient producers. Yangtze River Delta chemical clusters absorb these facility upgrade mandates more efficiently than import-dependent formulators.
Japan
Prefectures with strict residue protocols sustain premium-tier procurement for compliant metominostrobin formulations in quality rice segments. METI and the Ministry of Agriculture, Forestry and Fisheries administer the positive list system that filters non-compliant suppliers from premium markets. Hokkaido and Niigata prefectures concentrate integrated supply chains where rice miller procurement desks now dictate active ingredient selection.
Vietnam
Mekong Delta commercial rice sectors present underpenetrated volume potential for simplified handling protocols in water-dispersible granule formulations. The country's national agricultural regulator monitors residue limits for export-oriented production systems. Southern Vietnamese provinces maintain fragmented distributor networks that resist platform-based procurement consolidation seen in China.
South Korea
Protected cultivation systems in greenhouse clusters demand precision application compatibility for integrated pest management protocols. The Ministry of Food and Drug Safety enforces agricultural chemical residue standards aligned with export market requirements. Seoul Capital Area formulators coordinate technical advisory bundling that sustains margin density against commodity pricing pressure.
Thailand
Central Plains rice belts generate predictable seasonal demand cycles for sheath blight control in high-yielding Indica varieties. The country's agricultural chemical regulator implements registration timelines that delay market entry for non-integrated suppliers. Bangkok-based distributor networks maintain inventory positioning for just-in-time delivery during narrow application windows.
Metominostrobin Market Competitive Landscape
Capability concentration sits with backward-integrated Japanese and Chinese chemical conglomerates holding captive production of methoxyiminoacetamide intermediates; scale advantage sits with multinational formulators with broad distribution infrastructure. The market structures around three tiers: integrated active ingredient suppliers, regional formulation specialists, and platform-dependent generic manufacturers. Two dominant competitive moves define current positioning: digital farming platform development for service revenue extension, and cooperative procurement channel bypass through direct manufacturer-to-farm relationships.
Within the integrated supplier tier, Syngenta and BASF exemplify archetypes of platform-enabled service bundling and backward-integrated synthesis capabilities respectively. Summit Agro International occupies a position as regional formulation specialist across Japanese prefectures.
| Leading Market Players |
|---|
| Syngenta |
| Bayer CropScience |
| Sumitomo Corporation |
| Summit Agro International |
| BASF |
| FMC Corporation |
| ADAMA Agricultural Solutions |
| UPL |
| Nufarm |
| Others |
Value Network & Pricing Analysis
Overcapacity in China's Yangtze River Delta methoxyiminoacetamide intermediate plants is compressing supplier pricing power while simultaneously forcing facility consolidation decisions among domestic producers. This utilization squeeze feeds directly into formulation cost structures across East Asian rice markets, with backward-integrated conglomerates absorbing margin compression more efficiently than import-dependent competitors.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between Japanese rice millers and compliant formulators, insulating premium-tier suppliers from spot-market volatility. Price differentiation hinges on residue compliance certification under Japan's positive list system and volume scale through cooperative procurement platforms. Cost compression in standard-grade formulations is intensifying because Jiangsu and Zhejiang farming collectives consolidate purchasing authority. Agricultural cooperatives demonstrate acute price sensitivity; Japanese prefecture-level millers exhibit inelastic demand for certified products.
Supply Chain Analysis
Upstream feedstock production of methoxyiminoacetamide intermediates concentrates in China and Japan, with captive synthesis capabilities held by Sumitomo Corporation and domestic Chinese chemical conglomerates. Active ingredient production draws from aniline derivatives and specialized solvent systems, with formulation packaging resting on regional polymer supply chains. Single-source vulnerability characterizes the intermediate tier, where third-party formulators lack alternative supplier pathways. Distribution runs through rice miller procurement desks in Japan and digital cooperative platforms in China, displacing traditional agrochemical retailer tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metominostrobin market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive positioning. Japan's positive list compliance requirements generate switching costs that protect incumbent formulators from generic substitution.
For Market Incumbents: Entrench position through deepening backward integration into methoxyiminoacetamide synthesis and securing long-term offtake contracts with Hokkaido and Niigata rice millers. Cross-resistance development in regional pathogen populations threatens product lifecycles; invest in combination formulation R&D with novel mode-of-action partners. Channel control through digital farming platforms extends service revenue per hectare treated.
For New Entrants and Emerging Players: Build out water-dispersible granule formulation capabilities targeting Vietnam's Mekong Delta, where distributor fragmentation resists platform consolidation and simplified handling protocols address farmer preference. Vietnam's underpenetrated commercial rice sectors present the most accessible volume opportunity. Direct technical advisory relationships with provincial agricultural extension services offer a viable go-to-market angle bypassing entrenched distributor networks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across emission-compliant active ingredient synthesis, favoring scaled producers with pollution control infrastructure already deployed. Long-term viability over the coming decade rests on regulatory compliance depth rather than molecule differentiation alone. Acquisition targets should demonstrate captive intermediate supply and positive list registration portfolios. Watch for China's Ministry of Ecology and Environment enforcement intensity as the inflection signal for domestic producer margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive methoxyiminoacetamide synthesis insulates margin structures from intermediate supply bottlenecks. |
| Digital Platform Development | Syngenta's farming platform extends service revenue per hectare beyond commodity product margins. |
| Formulation Patent Investment | Adjuvant system IP thickets restrict generic manufacturer market entry in strobilurin segments. |
| Geographic Expansion | Vietnam's Mekong Delta offers volume growth potential for simplified water-dispersible granule protocols. |
| Regulatory Compliance Certification | Japan's positive list registration filters competitors from premium Japonica rice market segments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, agrochemical registration filings, and rice production statistics from East Asian agricultural ministries. Primary interviews engaged plant managers at Yangtze River Delta synthesis facilities, procurement leads at Japanese rice milling cooperatives, and technical R&D directors at multinational formulators. Secondary validation drew from China Ministry of Ecology and Environment emission disclosures, Japan MAFF residue monitoring reports, and Vietnam agricultural extension service records. Bottom-up volume modeling triangulated against top-down market sizing across formulation chemistry tiers.
Forecast inputs incorporate active ingredient production capacity utilization, cooperative procurement platform adoption curves, and resistance management protocol evolution across East Asian rice monoculture systems. Segmentation dimensions span formulation type, application setting, distribution channel, and regional regulatory cluster. CAGRs derive from trend extrapolation adjusted for patent expiry timelines and registration pathway friction. Industry-specific inputs include drone-based application penetration rates and rice miller procurement consolidation trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed chemical conglomerates would shift pricing outcomes beyond modeled ranges. Cross-checking against China customs export data for methoxyiminoacetamide intermediates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Colloidal Gold Suspension Market
Specialty Chemicals
Magnesium Gluconate Market
Specialty Chemicals
Myrcene Market
Specialty Chemicals
Solanesol Market
Specialty Chemicals
Betanin Market
Specialty Chemicals
Polyether Modified Silicone Market
Specialty Chemicals
Explosives and Pyrotechnics Market
Specialty Chemicals
North America Mexoryl SX (Ecamsule) Market
Specialty Chemicals
Middle East and Africa Amino Acids Market
Specialty Chemicals
Anhydroxylitol Market
Specialty Chemicals
Special Boiling Point Solvents Market
Specialty Chemicals
Dehazer Market
Specialty Chemicals
1 - 4 - Cyclohexanedimethanol Dibenzoate Market
Specialty Chemicals
Halogen-Free Flame Retardants Market
Specialty Chemicals
Calcium D-Pantothenate Market
Specialty Chemicals
Dimethyl Silicone Market