
 AEA Salicylic Acid Market | 2026-2036
AEA Salicylic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
AEA Salicylic Acid Market Outlook
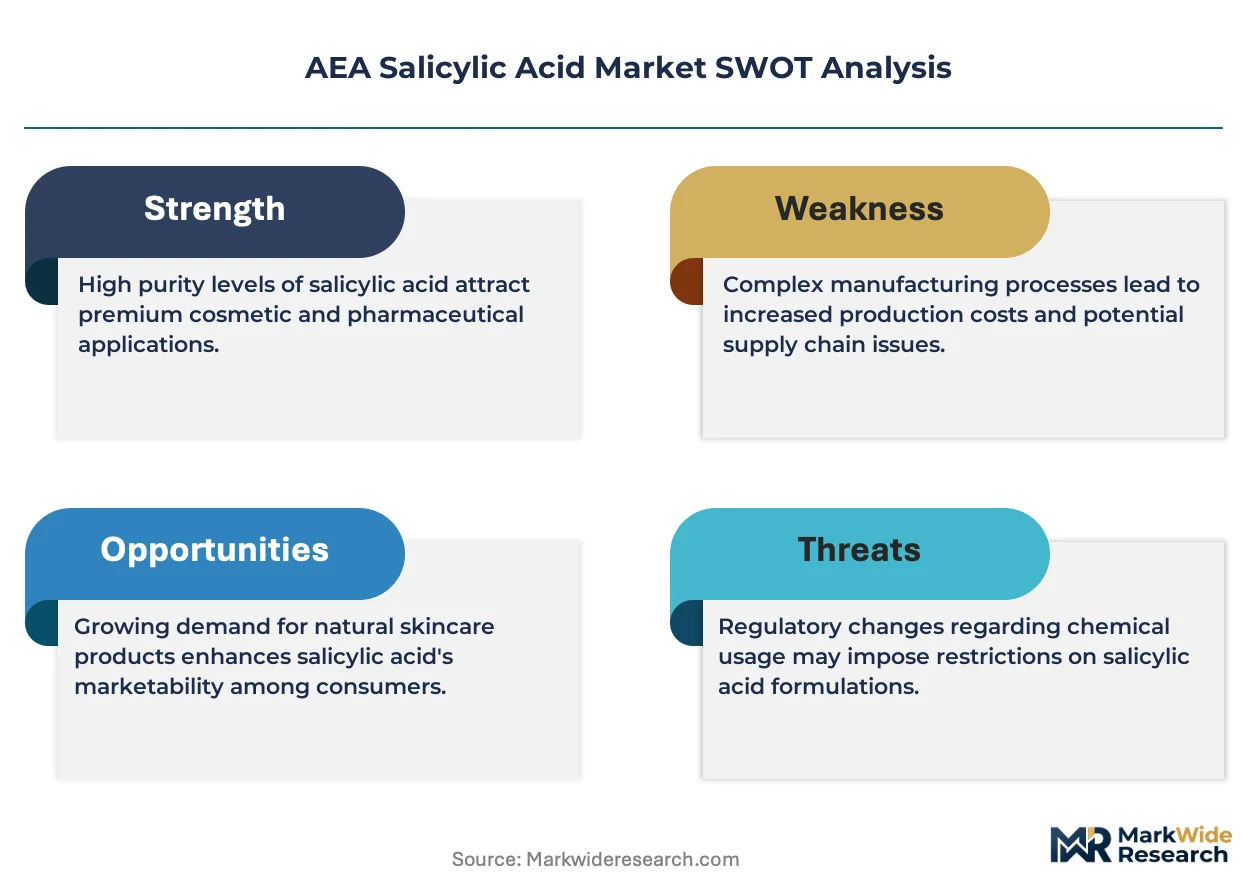
A capital-intensity divergence between integrated manufacturers and specialist distributors is bifurcating competitive dynamics in the AEA Salicylic Acid Market. Novacyl leverages backward integration into phenol-based feedstock production to control input costs across European supply chains. Merck KGaA sustains pharmaceutical-grade certification regimes that anchor its position in dermatology and API segments. Wego Chemical Group competes through specialized logistics infrastructure serving North American personal care compounders.
Acetyl ethyl ester of salicylic acid, commonly referenced as AEA salicylic acid, functions as a modified salicylate derivative with enhanced lipophilicity and reduced gastric irritation compared to native salicylic acid, typically synthesized through esterification of salicylic acid with acetic anhydride followed by ethylation; its primary commercial purpose centers on topical dermatological formulations, anti-inflammatory drug intermediates, and cosmetic exfoliant applications. The powder segment dominates bulk pharmaceutical procurement due to stability in long-term storage and compatibility with tableting equipment, while solution formats are capturing expanding share in cosmetic formulation houses seeking ready-to-process inputs. Dermatology applications lead value generation given prescription-grade margin pools, though agriculture represents an emerging outlet for plant-defense elicitor formulations.
REACH registration requirements in Europe, EPA toxic substance control provisions in the United States, and FDA monograph standards for over-the-counter acne therapies collectively elevate compliance costs and filter market access for non-specialized suppliers. The EU Green Deal chemical sustainability framework is pushing manufacturers toward bio-based feedstock alternatives and reduced solvent intensity in esterification processes. Stakeholders must monitor regulatory divergence between pharmaceutical and cosmetic grade specifications to avoid formulation recertification delays.
Market Dynamics
REACH registration requirements and EPA toxic substance control provisions are compressing supplier margins while elevating purity benchmarks, forcing non-specialized manufacturers to exit or consolidate as certification costs concentrate procurement among integrated chemical distributors.
Growth Catalysts
- Dermatology prescription volumes:Acne therapeutics and keratolytic preparations are expanding procurement from compounding pharmacies and clinic networks, particularly in markets with aging populations seeking non-antibiotic topical solutions.
- EU Green Deal chemical sustainability framework:The push toward bio-based feedstock alternatives is creating first-mover advantages for manufacturers investing in enzymatic esterification processes and solvent recovery systems.
- Plant-defense elicitor formulations:Agricultural biotechnology firms are piloting AEA salicylic acid derivatives for induced systemic resistance in high-value crop protection, opening volume outlets beyond pharmaceutical and cosmetic segments.
Market Restraints
- Phenol feedstock volatility:Crude oil-linked benzene-toluene-xylene chain fluctuations transmit directly to salicylic acid production economics, compressing margin predictability for non-integrated formulators.
- German chemical distributor concentration:Specialized distributors in the Rhine-Ruhr corridor control access to European personal care contract manufacturers, creating bottleneck risk for new market entrants lacking established relationships.
- Glycolic acid substitution in cosmetic exfoliants:Alpha-hydroxy acid alternatives with comparable keratolytic efficacy and lower regulatory burden are displacing AEA salicylic acid in over-the-counter cosmetic formulations.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO-aligned API producers are seeking qualified salicylic acid suppliers for export-oriented dermatology product lines, creating white space for REACH-registered exporters.
- Continuous flow reactor technology:Microreactor-based esterification processes are converging with real-time analytical control to reduce batch-to-batch variation and accelerate pharmaceutical-grade certification timelines.
- Direct-to-compounder e-commerce channels:Specialized chemical marketplaces are emerging as alternative procurement routes for mid-volume cosmetic formulators seeking reduced minimum order quantities and faster fulfillment.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA monograph compliance and EMA good manufacturing practice audits require 18-24 month qualification periods, straining working capital for capacity expansion projects.
- Analytical chemist talent scarcity:Specialized expertise in impurity profiling and stability-indicating method development is concentrating at established contract research organizations, inflating recruitment costs for in-house quality functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AEA Salicylic Acid Market |
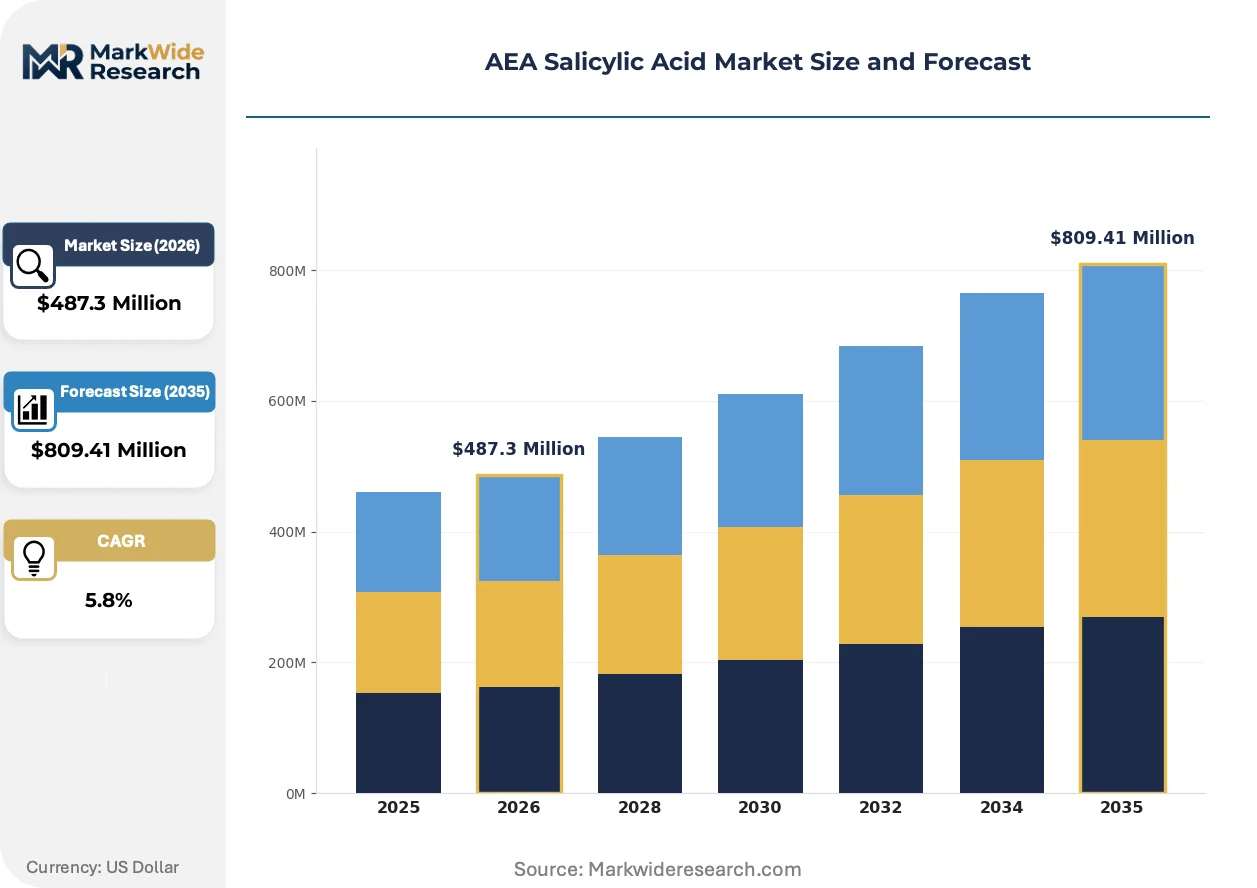
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Solution, Granules, Emulsion Application: Pharmaceuticals, Cosmetics, Agriculture, Dermatology End User: Manufacturers, Retailers, Distributors, Healthcare Providers Packaging Type: Bulk, Sachets, Bottles, Jars |
| Companies Covered | Novacyl, Wego Chemical Group, Alfa Aesar, Reagents, Merck KGaA, Avonchem Limited, Midas Pharma GmbH, Larachem Inc, J.M. Loveridge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AEA Salicylic Acid Market Strategic Shifts
Enzymatic biocatalysis and continuous processing technologies are decomposing traditional batch manufacturing economics while regulatory sustainability mandates reconfigure feedstock sourcing strategies across the value chain.
Immobilized lipase biocatalysts for regioselective esterification are decomposing energy-intensive thermal processing requirements in AEA salicylic acid synthesis. Pharmaceutical contract manufacturers in Switzerland and Germany are adopting these systems at pilot scale, with commercial deployment accelerating as enzyme stability improvements reduce catalyst replacement frequency. The technology is decomposing capital barriers for mid-scale producers seeking pharmaceutical-grade certification without multi-reactor infrastructure investments.
REACH authorization requirements for phenol derivatives are tightening substance volume thresholds and downstream user notification obligations. Chemical distributors serving European personal care formulators are consolidating supplier panels to reduce compliance administration burden, favoring integrated manufacturers with dedicated regulatory affairs functions. The policy shift most affects mid-volume cosmetic compounders in France and Italy, which are migrating procurement toward pre-registered supply chains to avoid formulation recertification delays.
Specification-driven procurement is compressing traditional spot-market purchasing cycles as dermatology clinics and pharmaceutical formulators demand certificate-of-analysis consistency across multi-year supply agreements. Specialized distributors are responding with vendor-managed inventory programs that transfer storage and quality assurance costs upstream. This behavioral shift is most visible in North American personal care compounding, where just-in-time delivery requirements from contract manufacturers are eliminating buffer stock tolerance.
AEA Salicylic Acid Market Segmentation
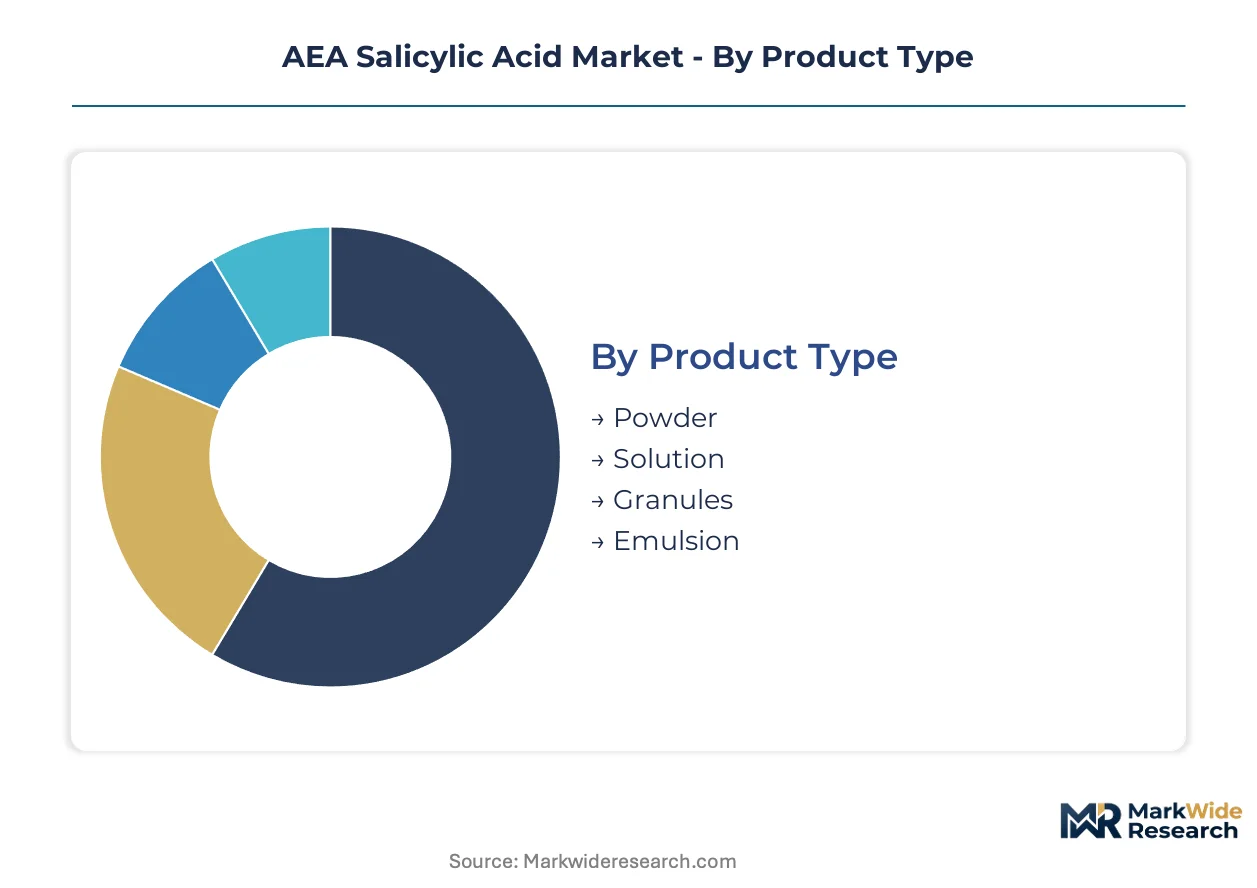
AEA salicylic acid procurement patterns diverge sharply across formulation requirements and regulatory pathways. Pharmaceutical-grade certification timelines and cosmetic-grade stability specifications create distinct commercial segments with non-overlapping supplier qualifications.
Product Type:
REACH and FDA monograph standards enforce divergent purity thresholds across physical formats, concentrating procurement among specialized manufacturers with dedicated quality systems.
- Powder:Crystalline solid with enhanced shelf stability and precise dosing compatibility for tableting operations. German pharmaceutical compounders and North American dermatology clinics prioritize powder formats for prescription acne therapies and keratolytic preparations, though hygroscopicity management requires climate-controlled storage infrastructure.
- Solution:Pre-dissolved aqueous or alcoholic preparation eliminating in-house solubilization steps. Cosmetic formulators in France and Italy are shifting procurement toward solution formats to reduce batch processing time and minimize occupational exposure during manufacturing, with ready-to-process inputs gaining share in mid-volume personal care operations.
- Granules:Free-flowing agglomerated particles designed for controlled-release pharmaceutical applications.
- Emulsion:Oil-in-water or water-in-oil dispersion systems targeting topical delivery with modified skin penetration kinetics.
Established volume favors powder; emerging adoption favors solution.
Application:
Margin structures and certification burdens vary dramatically across end-use sectors, with prescription-grade dermatology commanding premium pricing over agricultural outlets.
- Pharmaceuticals:Active pharmaceutical ingredient and intermediate applications governed by FDA monograph and EMA good manufacturing practice requirements. Swiss and German contract manufacturers anchor demand for multi-tonne annual volumes with certificate-of-analysis consistency spanning 24-month qualification cycles.
- Dermatology:Direct clinical deployment in prescription acne therapeutics and psoriasis management protocols. Compounding pharmacies in the United States and clinic networks in Germany are expanding procurement of prescription-grade material as antibiotic stewardship programs elevate non-antimicrobial topical alternatives.
- Cosmetics:Over-the-counter exfoliant and anti-aging formulations subject to cosmetic regulation rather than pharmaceutical oversight.
- Agriculture:Plant-defense elicitor applications in high-value crop protection with emerging volume potential.
Revenue concentration sits with dermatology; volume expansion is climbing the fastest in agriculture.
End User:
Procurement scale and technical specification depth separate institutional buyers from intermediaries with limited quality assurance capabilities.
- Manufacturers:Integrated pharmaceutical and cosmetic formulators with in-house analytical laboratories and direct supplier auditing programs. These buyers command lowest unit pricing through multi-year supply agreements and vendor-managed inventory arrangements.
- Healthcare Providers:Dermatology clinics and hospital pharmacies with prescription compounding licenses seeking certificate-of-analysis documentation for every lot received.
- Distributors:Specialized chemical handlers serving as regulatory compliance intermediaries for smaller formulators lacking REACH registration capabilities.
- Retailers:Direct-to-consumer channels with limited technical specification requirements and highest per-unit procurement costs.
Contract security favors manufacturers; service intensity favors distributors.
Packaging Type:
Logistics economics and contamination risk profiles dictate format selection across supply chain tiers.
- Bulk:Industrial-scale drum or tote configurations minimizing per-kilogram packaging cost for high-volume pharmaceutical manufacturers. Rhine-Ruhr chemical distributors specialize in bulk handling infrastructure serving German personal care contract manufacturers with just-in-time delivery requirements.
- Bottles:Laboratory and small-batch compounding formats with tamper-evident closures and graduated dispensing features.
- Sachets:Single-use pouches for sample distribution and travel-size cosmetic applications.
- Jars:Wide-mouth containers facilitating scoop access for semi-solid emulsion products.
Unit economics favor bulk; flexibility favors bottles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal Germany as the dominant surplus producer while the United States and India remain net importers of pharmaceutical-grade material. Rhine-Ruhr chemical distributors channel European supply toward personal care contract manufacturers, creating structural dependencies that shape procurement patterns across three continents.
Germany
Dermatology clinics in Bavaria and North Rhine-Westphalia anchor continental demand for prescription-grade powder formulations. REACH registration requirements enforced by ECHA tighten substance volume thresholds for phenol derivatives, elevating compliance burdens for downstream cosmetic compounders. The Rhine-Ruhr corridor hosts specialized chemical distributors serving just-in-time delivery contracts for personal care manufacturers in Frankfurt and Düsseldorf.
United States
Compounding pharmacies and clinic networks across Texas and California are expanding procurement of non-antibiotic topical therapies. EPA toxic substance control provisions intersect with FDA monograph standards for over-the-counter acne products, compressing supplier margins while filtering market access. The Greater Boston pharmaceutical cluster anchors API demand from Swiss and German contract manufacturers seeking multi-year supply agreements.
India
CDSCO-aligned API producers in Maharashtra and Gujarat are seeking qualified salicylic acid suppliers for export-oriented dermatology product lines. The country's national pharmaceutical regulator is aligning inspection protocols with EMA good manufacturing practice standards, accelerating qualification timelines for European market access. Hyderabad and Mumbai manufacturing hubs are piloting continuous flow reactor technology to reduce batch-to-batch variation in esterification processes.
Switzerland
Swissmedic governs pharmaceutical-grade certification for contract manufacturers serving global dermatology brands headquartered in Basel and Zurich. The EU Green Deal chemical sustainability framework is pushing manufacturers toward enzymatic biocatalysis and solvent recovery systems. Basel's pharmaceutical corridor anchors pilot-scale adoption of immobilized lipase catalysts for regioselective esterification.
China
Domestic cosmetic formulators in the Yangtze River Delta are shifting procurement toward solution formats to reduce in-house processing steps. NMPA alignment with international pharmaceutical standards is elevating purity benchmarks for export-oriented manufacturers. Shanghai and Zhejiang chemical parks are consolidating specialty ester production to serve Southeast Asian personal care markets.
AEA Salicylic Acid Market Competitive Environment
Concentration sits with integrated European chemical groups and specialized North American distributors. Three to five integrated manufacturers control upstream phenol feedstock access, while mid-scale distributors compete through regulatory compliance intermediation. Strategic archetypes include backward-integrated phenol producers, pharmaceutical-grade certification specialists, and logistics-focused regional distributors. Competitive moves center on multi-year supply agreement lock-ins and vendor-managed inventory programs that transfer storage costs upstream.
Among European-integrated manufacturers, Novacyl and Merck KGaA exemplify divergent positioning strategies. Novacyl represents the backward-integrated archetype with captive phenol supply chains, while Merck KGaA anchors the pharmaceutical-grade certification tier. Wego Chemical Group occupies a position within the North American distribution layer, serving personal care compounders through specialized logistics infrastructure. These three entities collectively illustrate how capital intensity and regulatory capability separate market tiers.
| Leading Market Players |
|---|
| Novacyl |
| Wego Chemical Group |
| Alfa Aesar |
| Reagents |
| Merck KGaA |
| Avonchem Limited |
| Midas Pharma GmbH |
| Larachem Inc |
| J.M. Loveridge Limited |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at phenol-based esterification plants in the Rhine-Ruhr corridor shapes both supply concentration and price floors for AEA salicylic acid across European and North American markets. Integrated manufacturers with captive feedstock production command pricing power over specialist distributors, while REACH compliance costs and EPA certification burdens establish minimum viable scale thresholds that filter smaller compounders from premium-grade procurement.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that dominates pharmaceutical-grade procurement. Pricing stratifies across pharmaceutical, cosmetic, and agricultural certification tiers, with FDA monograph compliance and EMA good manufacturing practice standards commanding substantial premiums over cosmetic-grade material. Cost compression in cosmetic-grade powder formats is intensifying because glycolic acid substitution erodes volume commitments from personal care formulators. Mid-volume cosmetic compounders exhibit highest price sensitivity, while Swiss and German contract manufacturers with multi-year dermatology supply agreements demonstrate lowest sensitivity due to formulation recertification barriers.
Supply Chain Analysis
Just-in-time delivery preferences among North American personal care contract manufacturers are eliminating buffer stock tolerance and compressing order-to-fulfillment windows. Supply concentrates in Germany, Switzerland, and India, with phenol feedstock, acetic anhydride, and ethanolamine representing critical input dependencies. Single-source vulnerability around German chemical distributors in the Rhine-Ruhr corridor creates bottleneck risk for new market entrants lacking established relationships. Distribution runs through specialized chemical handlers serving as regulatory compliance intermediaries for smaller formulators lacking REACH registration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AEA salicylic acid demand tracks dermatology prescription cyclicality, with acne therapeutic volumes recovering as antibiotic stewardship programs elevate non-antimicrobial topical alternatives across aging populations.
For Market Incumbents: Secure multi-year supply agreement lock-ins with Swiss and German contract manufacturers before continuous flow reactor technology decomposes batch manufacturing economics for mid-scale competitors. Defend margin position by deepening backward integration into phenol feedstock production and accelerating enzymatic biocatalysis pilot programs to meet EU Green Deal sustainability mandates.
For New Entrants and Emerging Players: Anchor in Indian pharmaceutical manufacturing expansion, where CDSCO-aligned API producers seek qualified salicylic acid suppliers for export-oriented dermatology product lines. Target mid-volume cosmetic formulators in France and Italy migrating procurement toward pre-registered supply chains to avoid REACH formulation recertification delays. Pursue direct-to-compounder e-commerce channels as an alternative procurement route with reduced minimum order quantities.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated manufacturers with pharmaceutical-grade certification capabilities and captive phenol supply chains over pure-play distributors. Long-term viability hinges on enzymatic esterification adoption and solvent recovery system deployment across the analysis window. Watch for inflection when continuous flow reactor technology achieves commercial scale and compresses batch-to-batch variation below current pharmaceutical-grade thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive phenol production insulates Novacyl from crude oil-linked BTX chain volatility. |
| Pharmaceutical-Grade Certification | EMA good manufacturing practice audits anchor Merck KGaA's position in dermatology API segments. |
| Enzymatic Biocatalysis Adoption | Immobilized lipase systems reduce energy intensity for Swiss contract manufacturers. |
| Direct-to-Compounder E-Commerce | Specialized chemical marketplaces bypass German distributor concentration for mid-volume buyers. |
| Continuous Flow Reactor Deployment | Microreactor-based esterification accelerates pharmaceutical-grade certification timelines for Indian producers. |
Study Parameters
Desk research of customs trade data, REACH registration databases, and FDA monograph filings preceded structured interviews with pharmaceutical procurement managers, cosmetic formulator technical directors, chemical distribution channel partners, and regulatory affairs specialists at EMA-notified bodies. Primary fieldwork with plant managers at esterification facilities and quality assurance leads at contract manufacturers was validated against secondary sources including SEC 10-K filings, Cefic chemical industry reports, and CDSCO API inspection records. Bottom-up volume estimates from end-use segmentations were triangulated against top-down trade flow analyses.
Variance decomposition across product type, application, and end-user segments structured the analytical framework over the projection horizon. Modeled dimensions included pharmaceutical versus cosmetic grade tiers, powder versus solution formats, and regional production hub classifications. CAGRs were derived from segment-level volume trajectories weighted by purity-adjusted pricing differentials. Forecast inputs incorporated phenol feedstock cost curves, REACH authorization timelines for phenol derivatives, and enzymatic biocatalysis adoption rates at pilot-scale facilities.
Material uncertainties — phenol feedstock volatility, regulatory divergence between pharmaceutical and cosmetic specifications, and glycolic acid substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions regarding EMA inspection protocol stability and EPA toxic substance control provision enforcement intensity. Revision becomes warranted when enzymatic esterification cost parity with thermal processing crosses commercial viability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Protein Purification Resin Market
Specialty Chemicals
Halogen-Free Flame Retardants Market
Specialty Chemicals
Disodium Adenosine Triphosphate Market
Specialty Chemicals
Phenylbenzimidazole Sulfonic Acid Market
Specialty Chemicals
PEG and PPG Esters Market
Specialty Chemicals
Global Water Based Acrylates Copolymer Rheology Modifiers Market
Specialty Chemicals
Bio-Based Aromatics Market
Specialty Chemicals
Calcium D-Pantothenate Market
Specialty Chemicals
Silanes and Silicones Market
Specialty Chemicals
United States Aerosol Cans Market
Specialty Chemicals
US Antimicrobial Plastics Market
Specialty Chemicals
Prils Market
Specialty Chemicals
Global Photoacid Generators Market
Specialty Chemicals
1 - 4 - Cyclohexanedimethanol Dibenzoate Market
Specialty Chemicals
Palm Methyl Ester Derivatives Market
Specialty Chemicals
Preparative Chromatography Market