
 Diindolylmethane Market | 2026-2036
Diindolylmethane Market Size, Share, and Industry Trends Forecast 2026-2036
Diindolylmethane Market Outlook
Dietary supplement demand is rebalancing toward hormone health and detoxification positioning as consumers shift from general wellness to targeted condition management. NOW Foods leverages its broad retail distribution to sustain volume leadership across mass-market channels. BioResponse Nutrients anchors its position through patented absorption-enhanced formulations that differentiate from commodity-grade competitors. Source Naturals specializes in practitioner-focused SKUs that command premium placement in integrative medicine clinics.
Diindolylmethane is a bioactive compound formed from the acid-catalyzed condensation of indole-3-carbinol, typically standardized to 100-400 mg doses in commercial preparations, and functions primarily as a modulator of estrogen metabolism pathways in dietary supplement and pharmaceutical applications. The capsule segment dominates current revenue due to convenience-driven consumer preference and precise dosing compliance, while liquid extracts represent the fastest-growing format as bioavailability innovations attract functional food developers. Pharmaceutical-grade tablets occupy the highest margin tier, constrained by stringent purity thresholds and extended qualification cycles for drug-master-file submissions.
The FDA's NDI notification requirements and cGMP enforcement for dietary supplements create compliance barriers that favor established manufacturers with dedicated regulatory affairs infrastructure. EFSA's health claims framework in Europe restricts direct hormone-related marketing, pushing brands toward structure-function positioning with substantiated safety dossiers. Stakeholders must monitor evolving pharmacovigilance expectations for botanical-derived actives and assess whether preemptive investment in clinical trial endpoints will secure defensible positioning as competitive differentiation tightens.
Market Dynamics
Pharmaceutical-grade purity thresholds and FDA New Dietary Ingredient notification requirements are compressing supplier margins while forcing consolidation among contract manufacturers serving the nutraceutical and clinical trial supply chains.
Growth Catalysts
- Estrogen metabolism research:Clinical validation of DIM's role in hormone modulation is expanding practitioner adoption in integrative medicine clinics across Germany and the United States.
- EFSA substantiation pathways:European manufacturers are investing in safety dossiers to secure structure-function claims under evolving botanical active guidelines.
- Cruciferous vegetable extraction:Improved acid-catalyzed condensation yields from broccoli and cabbage feedstocks are lowering raw material costs for standardized 100-400 mg formulations.
Market Restraints
- Indole-3-carbinol price volatility:Agricultural supply fluctuations for Brassica crops create input cost instability for DIM producers dependent on consistent feedstock quality.
- cGMP compliance infrastructure:Small and mid-sized manufacturers face capital barriers to meeting FDA enforcement standards for dietary supplement manufacturing.
- Synthetic estrogen modulator competition:Pharmaceutical alternatives with faster onset profiles threaten DIM's positioning in hormone therapy adjuvant applications.
Strategic Opportunities
- Functional food integration:Liquid extract bioavailability innovations are attracting beverage developers seeking hormone-support positioning in premium wellness products.
- Pharmacy network expansion:European pharmacy chains in France and Switzerland are creating dedicated natural health sections that elevate DIM from specialty to mainstream placement.
- Dual carbon goals alignment:China's green manufacturing incentives favor domestic producers investing in enzymatic conversion processes that reduce solvent waste.
Industry Challenges
- Analytical chemist scarcity:Qualified personnel for HPLC validation of DIM-isomer ratios and heavy metal screening are concentrated among legacy botanical extract houses.
- Drug-master-file qualification timelines:Pharmaceutical-grade tablet submissions require 18-24 month stability studies that tie up working capital and delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diindolylmethane Market |
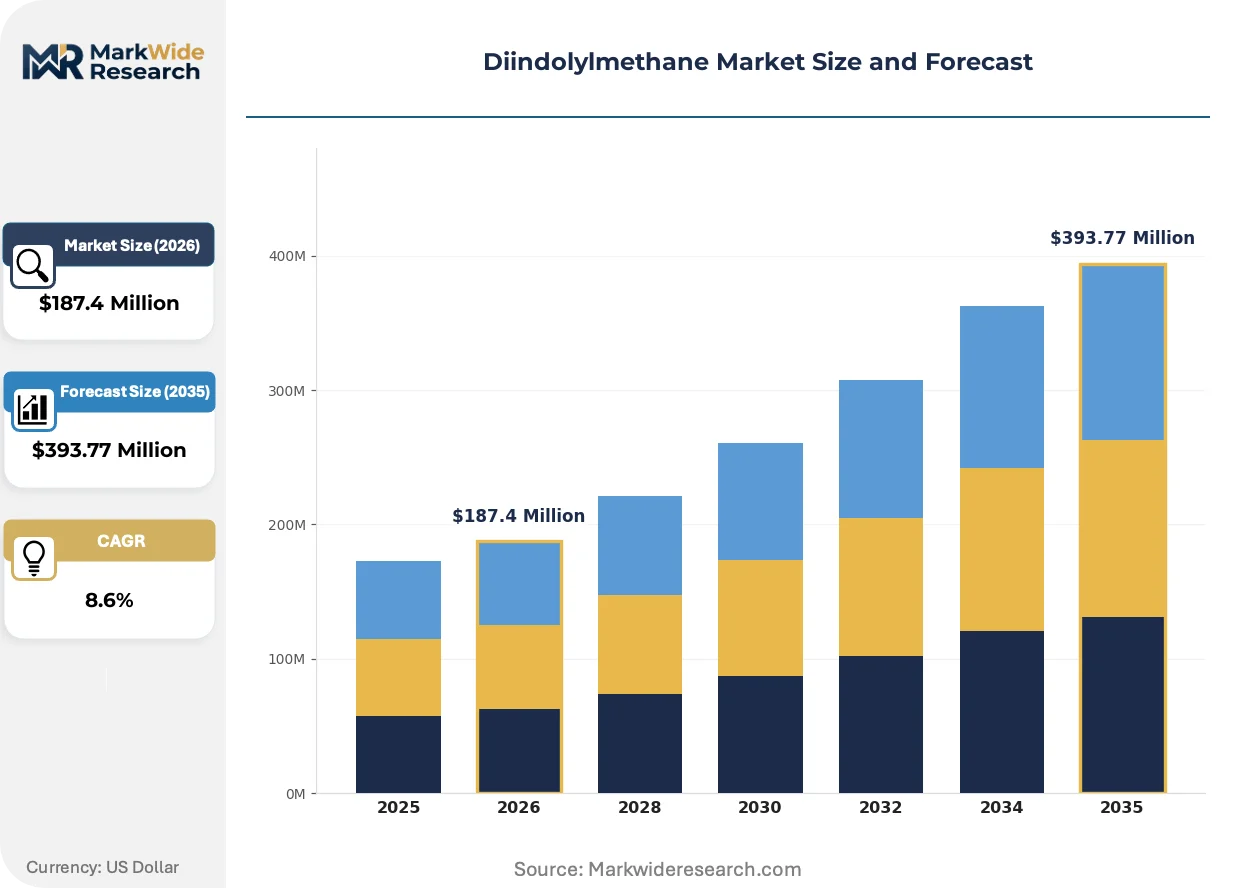
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Tablets, Liquid Extracts Application: Dietary Supplements, Functional Foods, Pharmaceuticals, Cosmetics End User: Individuals, Healthcare Professionals, Nutraceutical Companies, Research Institutions Distribution Channel: Online Retail, Health Stores, Pharmacies, Direct Sales |
| Companies Covered | NOW Foods, Source Naturals, Nature's Way, Pure Bulk, Solaray, BioResponse Nutrients, Nutri Advanced, Genestra Brands, Nutricost, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diindolylmethane Market Strategic Shifts
Formulation science and regulatory positioning are converging to redefine how DIM reaches end-users, with absorption enhancement and delivery format innovation separating premium offerings from commodity-grade competition.
Liposomal encapsulation technology is integrating phospholipid-based delivery systems that protect DIM from gastric degradation and improve lymphatic absorption. Functional food developers in Japan and South Korea are adopting these systems at accelerated pace for fortified beverage applications. This convergence is compressing the performance gap between capsule and liquid formats while enabling new product categories.
REACH registration requirements for novel botanical derivatives are forcing European suppliers to consolidate substance identity documentation and toxicology data packages. Industrial consequence includes withdrawal of non-compliant raw material sources from the supply chain. Pharmaceutical-grade tablet manufacturers targeting EMA drug-master-file status are most affected, responding through dedicated regulatory affairs hires and third-party dossier compilation services.
Direct-to-consumer subscription models are displacing traditional retail replenishment cycles for hormone-support supplements. Mass-market e-commerce platforms and specialized telehealth services are capturing patient acquisition from brick-and-mortar channels. This behavioral shift is most visible in United States metropolitan markets where integrative medicine practitioners increasingly recommend specific SKUs through patient portals rather than in-clinic dispensing.
Diindolylmethane Market Segmentation
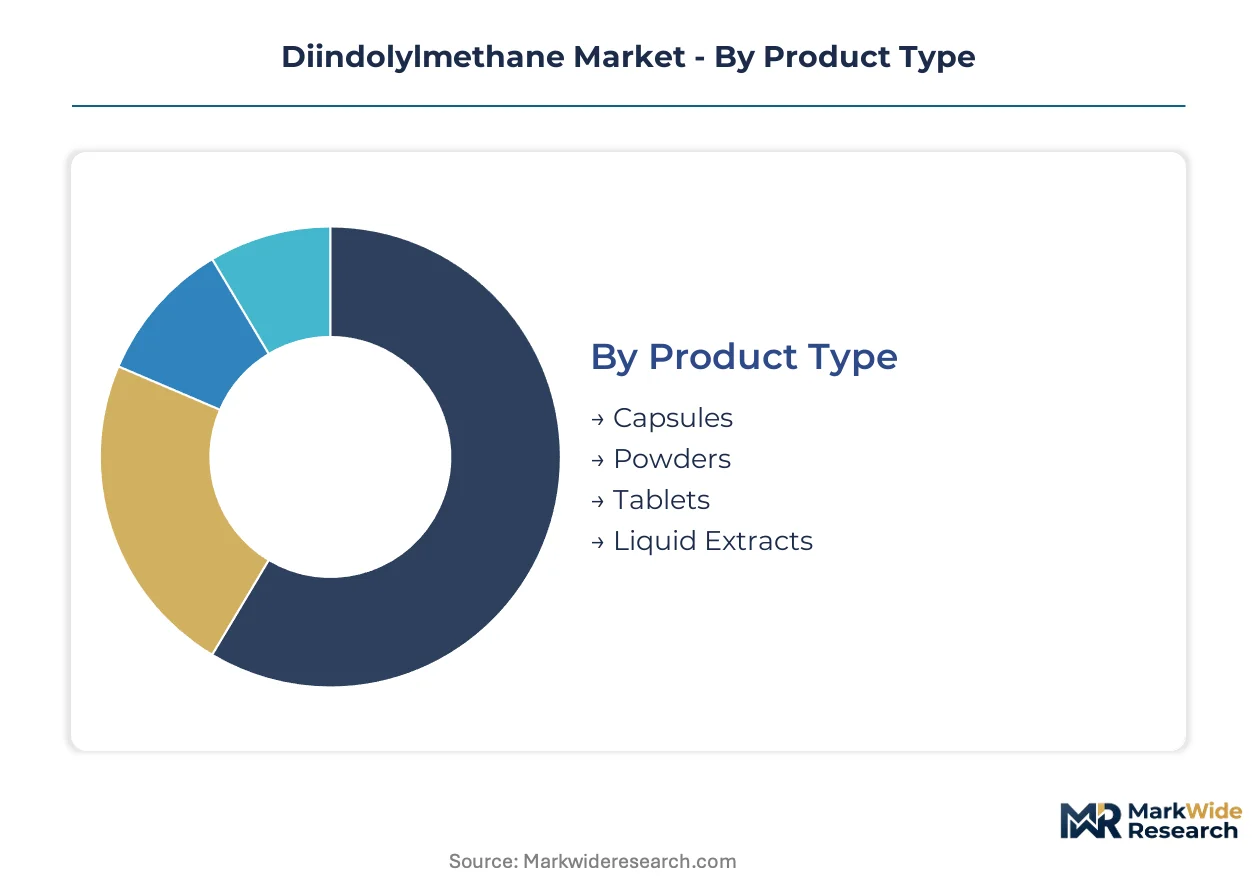
Diindolylmethane market segmentation reveals how capital allocation, regulatory pathways, and consumer access models fragment commercial opportunity across distinct value tiers. Each dimension carries specific margin structures and qualification barriers that determine competitive positioning.
Product Type:
Capital intensity varies sharply across formats, with pharmaceutical-grade manufacturing requiring dedicated cleanroom infrastructure and analytical validation suites that commodity-grade producers cannot readily replicate.
- Capsules:Standardized gelatin or vegetable cellulose shells containing 100-400 mg DIM powder dominate current procurement volumes due to dosing precision and shelf stability. Convenience-driven consumers in United States direct-to-consumer channels favor this format for hormone-support regimens, though gelatin sourcing faces scrutiny from vegan-positioned competitors.
- Liquid Extracts:Liposomal and micellar delivery systems command premium positioning through enhanced lymphatic absorption and functional food compatibility. Beverage developers in Japan and South Korea are integrating these formats for hormone-support positioning in premium wellness products, with bioavailability innovations compressing the performance gap against traditional capsules.
- Powders:Bulk active ingredient for contract manufacturers and compounding pharmacies, requiring minimal downstream processing but demanding rigorous homogeneity testing for potency consistency.
- Tablets:Pharmaceutical-grade compressed forms with the highest purity thresholds and extended FDA drug-master-file qualification cycles, constraining supplier participation to established manufacturers with dedicated regulatory affairs infrastructure.
Capsules absorb the bulk of installed capacity; liquid extracts are expanding most quickly.
Application:
Regulatory jurisdiction determines market access complexity, with pharmaceutical pathways demanding clinical substantiation that nutraceutical channels circumvent through structure-function positioning.
- Dietary Supplements:Hormone-balancing and detoxification claims drive procurement from nutraceutical companies expanding dedicated DIM product lines. NOW Foods and similar mass-market distributors sustain volume leadership through broad retail penetration, though FDA NDI notification requirements compress margins for new entrants lacking established compliance infrastructure.
- Pharmaceuticals:Estrogen metabolism modulation in adjuvant hormone therapy applications requires EMA or FDA drug-master-file status, with 18-24 month stability studies tying up working capital. German and United States integrative medicine clinics represent the primary demand concentration for prescription-grade formulations.
- Functional Foods:Fortified beverages and nutrition bars incorporating liposomal DIM extracts target convenience-oriented consumers seeking hormone support without pill burden.
- Cosmetics:Topical applications leveraging DIM's anti-androgenic properties for skin health positioning remain niche, constrained by dermal penetration challenges and limited clinical validation.
Dietary supplements capture the dominant revenue share; pharmaceuticals offer the steepest expansion trajectory for qualified suppliers.
End User:
Procurement sophistication separates institutional buyers with technical specification requirements from individual consumers driven by brand recognition and practitioner recommendation.
- Individuals:Direct-to-consumer acquisition through e-commerce platforms and subscription services, with telehealth portals displacing traditional retail replenishment cycles in United States metropolitan markets.
- Nutraceutical Companies:Formulation houses sourcing standardized actives for private-label and branded supplement lines, prioritizing batch consistency and documentation packages for retailer compliance.
- Healthcare Professionals:Integrative medicine practitioners in Germany and the United States recommending specific SKUs through patient portals, commanding premium placement for practitioner-exclusive product lines.
- Research Institutions:Clinical trial supply procurement with stringent chain-of-custody requirements and isomer-ratio specifications for estrogen metabolism studies.
Nutraceutical companies absorb the bulk of production volume; healthcare professionals are expanding most quickly as practitioner adoption accelerates.
Distribution Channel:
Channel selection directly determines margin realization, with direct sales capturing full value capture while third-party retail surrenders percentage points for access and credibility.
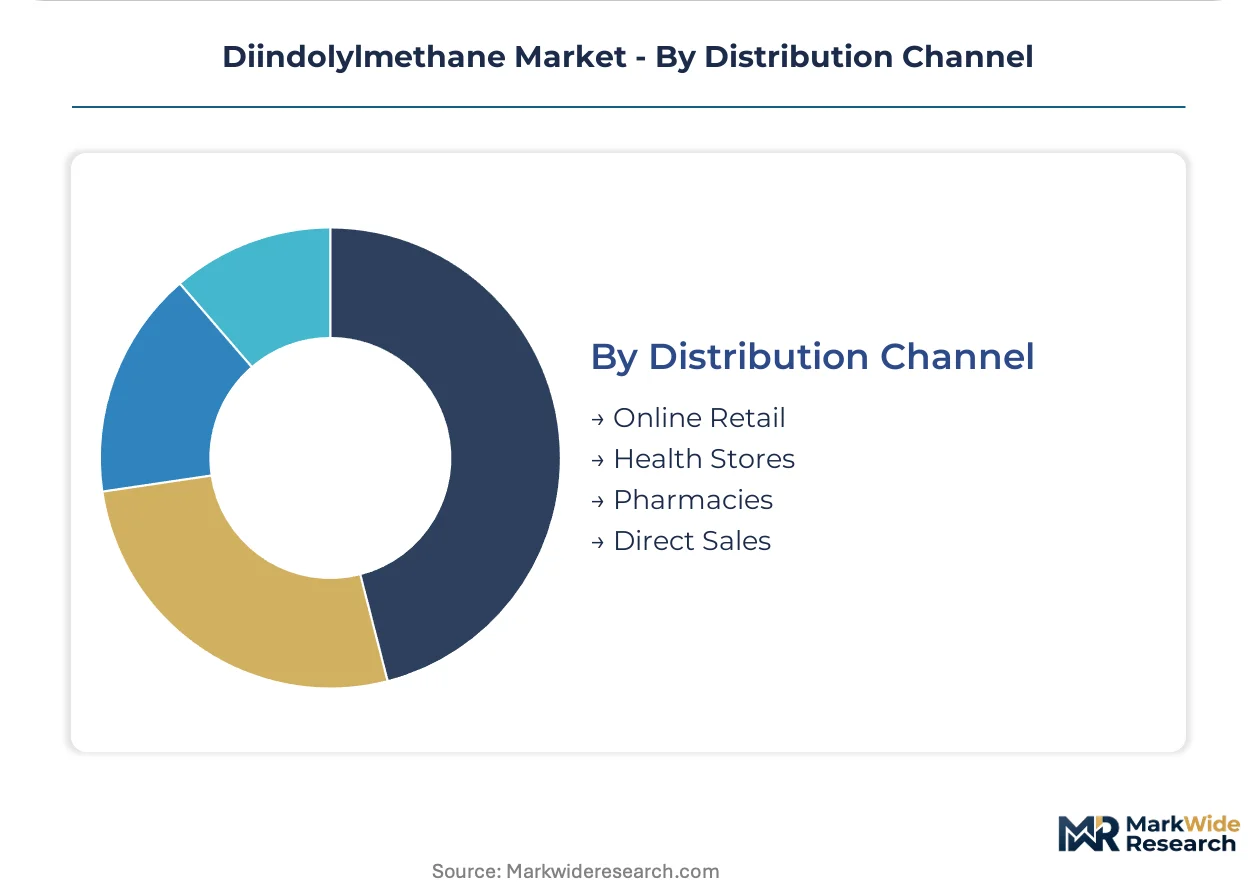
- Online Retail:Mass-market e-commerce platforms and specialized telehealth services capturing patient acquisition from brick-and-mortar channels, with subscription models locking in recurring revenue.
- Pharmacies:European chains in France and Switzerland creating dedicated natural health sections that elevate DIM from specialty to mainstream placement, requiring pharmacist training investment.
- Health Stores:Independent and chain retailers serving supplement enthusiasts with educated staff capable of explaining estrogen metabolism positioning.
- Direct Sales:Manufacturer-controlled channels bypassing retail markup, constrained by customer acquisition costs and fulfillment infrastructure requirements.
Online retail absorbs the bulk of transaction volume; pharmacies are gaining share fastest through professional credibility transfer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's green manufacturing incentives within the Yangtze River Delta special economic zone are concentrating DIM production capacity among enzymatic conversion specialists seeking dual carbon goal compliance.
United States
Direct-to-consumer subscription models are displacing brick-and-mortar replenishment cycles in metropolitan markets. FDA New Dietary Ingredient notification requirements compress margins for entrants lacking established compliance infrastructure. NOW Foods and BioResponse Nutrients anchor volume leadership across mass-market and practitioner channels respectively.
Germany
Integrative medicine clinics in Munich and Hamburg are expanding practitioner adoption of hormone-balancing formulations. EFSA's structure-function claims framework restricts direct hormone marketing, pushing brands toward substantiated safety dossiers. Bavaria-based extraction houses concentrate analytical chemistry talent for HPLC validation.
Switzerland
Pharmacy chains in Zurich and Geneva are creating dedicated natural health sections that elevate DIM from specialty to mainstream placement. Swissmedic's pharmaceutical-grade oversight attracts drug-master-file submissions for estrogen metabolism adjuvant applications. Basel-region regulatory affairs specialists serve cross-border EMA qualification.
Japan
Functional beverage developers in Tokyo and Osaka are integrating liposomal DIM extracts for hormone-support positioning. METI's health food labeling standards shape substantiation requirements for bioavailability claims. Kansai-region formulation houses pioneer micellar delivery systems for fortified drink applications.
South Korea
Premium wellness product manufacturers in Seoul are adopting absorption-enhanced formats at accelerated pace. MFDS health functional food regulations govern structure-function claim eligibility for botanical actives. Gyeonggi-do contract manufacturers serve Japanese and domestic brand outsourcing demand.
Diindolylmethane Market Competitive Environment
Top-tier vendors anchor premium practitioner and pharmaceutical-grade tiers, while commodity-grade producers compete on volume and retail penetration. The supplier base stratifies across patented absorption technologies, mass-market distribution scale, and clinical trial supply qualification. Three archetypes dominate: formulation innovators with delivery-system patents, broad-line distributors with retail shelf presence, and niche specialists serving integrative medicine channels. Competitive moves concentrate on liposomal technology licensing and pharmacy network expansion partnerships.
Among U.S.-based nutraceutical houses, NOW Foods exemplifies mass-market scale archetypes with broad retail distribution, while BioResponse Nutrients occupies the patented formulation tier through absorption-enhanced positioning. Source Naturals represents the practitioner-channel specialist archetype commanding premium placement in integrative medicine clinics.
| Leading Market Players |
|---|
| NOW Foods |
| Source Naturals |
| Nature's Way |
| Pure Bulk |
| Solaray |
| BioResponse Nutrients |
| Nutri Advanced |
| Genestra Brands |
| Nutricost |
| Others |
Value Chain & Pricing Dynamics
Indole-3-carbinol spot market volatility cascades through DIM supply chains into tiered pricing structures, with Brassica crop yield fluctuations compressing margins for non-integrated manufacturers while enzymatic conversion specialists in China's Yangtze River Delta capture cost advantages through green manufacturing incentives.
Pricing Analysis
Lead-time premiums reward pharmaceutical-grade tablet manufacturers completing 18-24 month drug-master-file stability studies, while spot inventory discounts attract commodity-grade capsule producers serving mass-market nutraceutical channels. Three-tier pricing structure across premium, standard, and economy levels separates patented liposomal formulations from conventional powders and bulk actives. Pricing pressure stems from FDA cGMP enforcement raising compliance infrastructure costs for smaller contract manufacturers. Direct-to-consumer subscription buyers demonstrate lowest price sensitivity, while bulk procurement teams at nutraceutical houses negotiate aggressively on volume.
Supply Chain Analysis
Reverse-logistics flows remain minimal given DIM's stability profile and single-use consumption patterns in dietary supplement applications. Concentration centers on China for enzymatic conversion feedstocks, India for acid-catalyzed condensation intermediates, and Germany for analytical validation and pharmaceutical-grade finishing. Raw material dependencies include Brassica crop harvests from Hebei Province, phospholipid delivery system components from South Korean suppliers, and HPLC-grade solvents from BASF's Ludwigshafen complex. Single-source vulnerability concentrates in qualified analytical chemist talent pools anchored at legacy botanical extract houses. Distribution runs through direct-to-consumer e-commerce platforms and European pharmacy networks with dedicated natural health sections.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where FDA New Dietary Ingredient notification requirements and extended drug-master-file qualification timelines force capital-constrained competitors toward exit or acquisition.
For Market Incumbents: Cement market position through backward integration into Brassica cultivation partnerships in Hebei Province and enzymatic conversion capacity additions in Yangtze River Delta special economic zones. Patent licensing of liposomal delivery systems to functional food developers in Japan and South Korea defends against synthetic estrogen modulator substitution threats. Regulatory affairs infrastructure investment isolates commodity-grade competitors lacking dedicated FDA compliance teams. For New Entrants and Emerging Players: Telehealth portal partnerships offer the most penetrable route for practitioner-channel access, bypassing entrenched retail shelf presence held by mass-market distributors. White-space targets include liquid extract formulations for premium wellness beverage developers and subscription-model direct sales in United States metropolitan markets. Go-to-market positioning should emphasize structure-function substantiation dossiers aligned with EFSA botanical active guidelines for European pharmacy network entry. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap enzymatic conversion specialists with dual carbon goal compliance in China and established EMA regulatory affairs capabilities in Germany. Long-term viability over the next decade hinges on clinical trial endpoint investment securing defensible positioning as hormone therapy adjuvant applications mature. Monitor FDA pharmacovigilance guidance evolution for botanical-derived actives as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Conversion Capacity Expansion | Green manufacturing incentives in China's Yangtze River Delta reward solvent-waste reduction with preferential licensing. |
| Liposomal Delivery System Licensing | Functional food developers in Japan and South Korea license phospholipid-based technology for beverage fortification applications. |
| Drug-Master-File Qualification Investment | EMA and FDA submissions for pharmaceutical-grade tablets secure premium positioning in integrative medicine clinics. |
| Direct-to-Consumer Subscription Launch | Telehealth portals in United States metropolitan markets displace brick-and-mortar replenishment cycles with recurring revenue capture. |
| European Pharmacy Network Partnership | Swiss and French chains create dedicated natural health sections requiring pharmacist training investment for mainstream placement. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with formulation scientists at nutraceutical houses, regulatory affairs leads at pharmaceutical-grade manufacturers, procurement managers at European pharmacy chains, and analytical chemists at extraction specialists. FDA New Dietary Ingredient notifications, EMA drug-master-file submissions, ClinicalTrials.gov entries, and import-export databases provided validation anchors. Bottom-up volume builds across product formats and applications triangulated against top-down market sizing from trade association revenue aggregates.
Granularity-level modeling captured product type segmentation at the delivery-format level, application splits between dietary supplement and pharmaceutical pathways, and distribution channel dynamics across direct-to-consumer and pharmacy networks. CAGRs derived from regression analysis of historical procurement volumes against Brassica crop yield indices and practitioner adoption curves in Germany and the United States. Forecast inputs included enzymatic conversion yield improvements and evolving EFSA structure-function claim substantiation requirements.
The model holds under stable Brassica agricultural supply and sustained FDA cGMP enforcement intensity; deviation in indole-3-carbinol price spikes or accelerated synthetic estrogen modulator clinical advancement would shift volume trajectories. Practitioners should monitor FDA pharmacovigilance guidance for botanical-derived actives and EMA botanical active guideline revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
CMIT/MIT Market
Specialty Chemicals
Global Metal Chelates Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market
Specialty Chemicals
Epoxidized Soybean Oil Market
Specialty Chemicals
Sizing and Thickening Market
Specialty Chemicals
UV Filters Market
Specialty Chemicals
Specialty Chemicals Market
Specialty Chemicals
Food Grade Paraffin Market
Specialty Chemicals
Global Salicylic Acid Market
Specialty Chemicals
Tubatoxin Market
Specialty Chemicals
Cellulose Ether Market
Specialty Chemicals
4-Benzoylbutyric Acid Market
Specialty Chemicals
Palm Methyl Ester Derivatives Market
Specialty Chemicals
Monoaluminum Phosphate Market
Specialty Chemicals
Octofluoropropane Market