
 Global Silanes Market | 2026-2036
Global Silanes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Silanes Market Foresight
Electronics manufacturing is restructuring the Global Silanes Market as advanced packaging and flexible display substrates absorb higher volumes of amino and epoxy silanes. Momentive Performance Materials leverages its silicone-hybrid technology leadership to anchor supply relationships with semiconductor foundries. Wacker Chemie AG sustains broad geographic coverage through integrated silicon-metal feedstock positions in Germany and the United States. Shin-Etsu Chemical Co., Ltd. dominates ultra-high-purity grades for electronics, competing on specification tightness rather than volume scale.
Silanes are silicon-hydrogen or silicon-organic compounds containing at least one silicon-carbon or silicon-halogen bond, typically synthesized via direct process or hydrosilylation reactions at temperatures between 200°C and 300°C, functioning primarily as coupling agents, cross-linkers, and surface modifiers across polymer and inorganic material interfaces. Amino silanes and epoxy silanes occupy the fastest-expanding margin pools as electronics and coatings applications demand higher adhesion performance and moisture resistance. Methacryloxy silanes lead in mature rubber reinforcement and dental applications where formulation standards have stabilized and price competition intensifies. Vinyl silanes retain structural importance in cable and pipe cross-linking, though growth rates trail electronics-oriented segments.
REACH registration requirements in Europe and China's GB standards under SAMR oversight are elevating purity documentation and toxicity testing burdens, reshaping product development priorities and market access costs for non-compliant suppliers. The EPA in the United States monitors volatile organic compound emissions from silane-based coating formulations, pressuring waterborne and low-VOC alternatives. Stakeholders must monitor regulatory divergence between European hazard classification expansions and Asian performance-based standards when allocating R&D and certification budgets.
Market Dynamics
Semiconductor packaging miniaturization and display substrate evolution are compressing specification tolerances for amino and epoxy silanes, forcing producers to prioritize ultra-high-purity synthesis over volume scale.
Growth Catalysts
- REACH registration expansions:ECHA's tightening hazard classifications for organosilicon compounds are accelerating substitution toward compliant silane grades in European coatings and adhesives.
- Flexible OLED substrate manufacturing:South Korean and Chinese display fabs are absorbing specialized silane coupling agents for barrier layer adhesion in foldable screen production.
- Hydrosilylation catalyst advances:Platinum and rhodium complex improvements are reducing synthesis temperatures below 200°C, trimming energy costs for producers.
Market Restraints
- Metallurgical-grade silicon price volatility:Feedstock costs fluctuate with Chinese polysilicon capacity expansions and power rationing in Yunnan and Xinjiang provinces.
- Chlorosilane supply concentration:Four integrated producers control roughly three-quarters of intermediate supply, creating bottleneck risk for non-integrated formulators.
- Fluorosilane substitution in electronics:Perfluorinated compounds retain performance advantages in extreme moisture resistance applications, capping silane penetration in aerospace-grade conformal coatings.
Strategic Opportunities
- India's PLI scheme for electronics:Smartphone and component manufacturing incentives are building captive silane demand in Noida and Sriperumbudur industrial corridors.
- Waterborne coating transitions:EPA VOC enforcement is opening formulation slots for low-emission silane cross-linkers in US architectural coatings.
- Bio-based silane precursors:Agricultural waste silicon extraction and biohydrogen feedstocks are enabling carbon-intensity certifications for European automotive suppliers.
Industry Challenges
- Ultra-high-purity contamination control:Semiconductor-grade specifications below 10 ppb metal content require cleanroom synthesis environments and specialized analytical capabilities.
- Multi-jurisdictional certification timelines:Parallel REACH, GB standard, and EPA registrations extend product launch cycles by 18-36 months for new molecular architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Silanes Market |
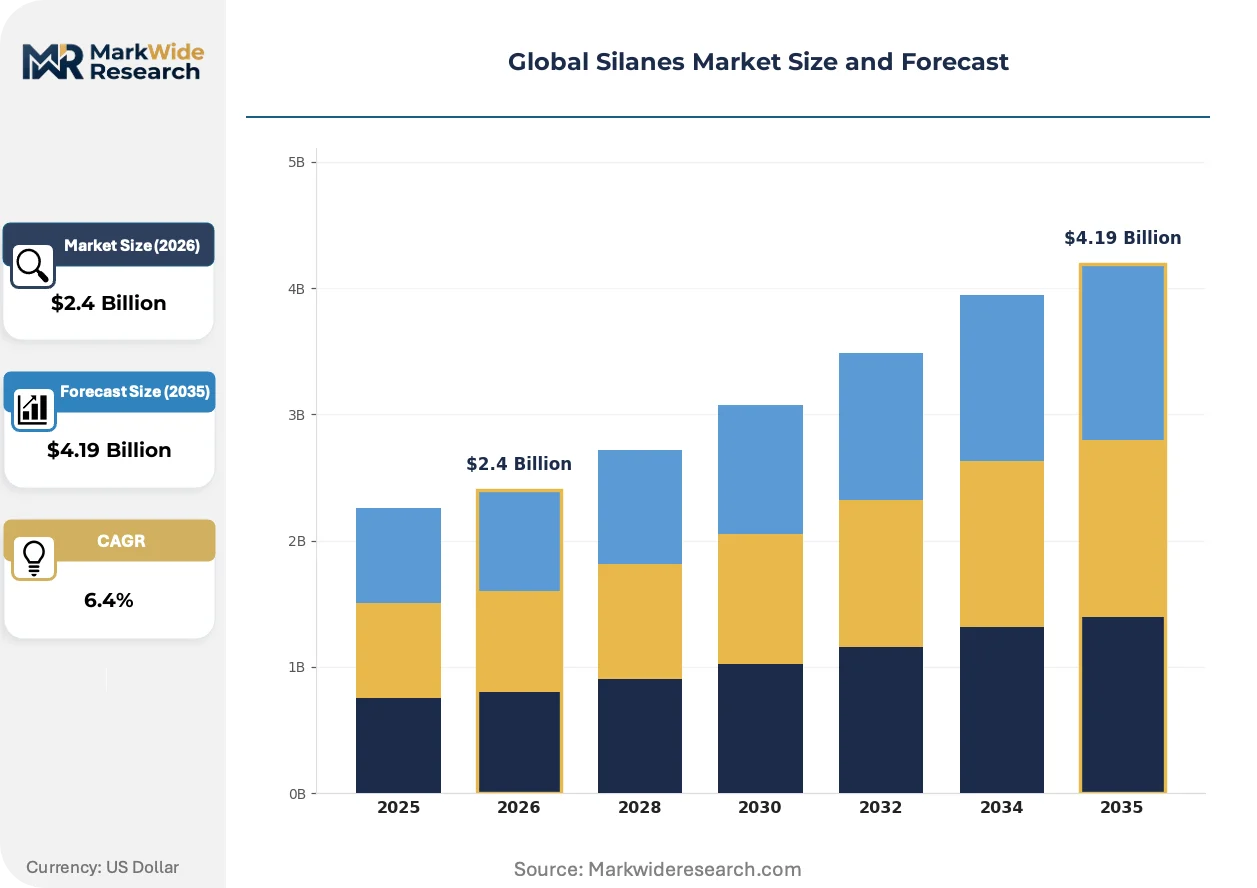
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.19 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl Silanes, Amino Silanes, Epoxy Silanes, Mercapto Silanes, Methacryloxy Silanes Application: Adhesives & Sealants, Coatings & Paints, Rubber Reinforcement, Surface Treatment, Pharmaceuticals End User Industry: Construction, Electronics Manufacturing, Agriculture Inputs, Personal Care, Aerospace Engineering Distribution Channel: Direct Sales, Distributors, Online Marketplaces, Industrial Supply Stores, Third-Party Logistics |
| Companies Covered | Momentive Performance Materials Inc., KCC Corporation, Evonik Industries AG, Elkem ASA, OCI Company Ltd, Wacker Chemie AG, Shin-Etsu Chemical Co., Ltd., Gelest, Inc., Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Silanes Market Shifts & Advancements
Process intensification and regulatory chemistry are compressing traditional synthesis routes while electronics-grade purity requirements fragment the technical baseline across end-use verticals.
Continuous flow hydrosilylation reactors are overtaking batch vessel production for standard-grade silanes. German and US specialty chemical producers are retrofitting pilot plants with microchannel designs that cut residence times from hours to minutes. This shift is compressing capital requirements for mid-scale entrants while locking incumbents into legacy asset write-down decisions.
China's GB standards under SAMR oversight are mandating full substance toxicity dossiers for silanes imported above 1 ton annually. Domestic producers gain six-to-twelve-month compliance advantages over foreign suppliers. Electronics and automotive OEMs in the Yangtze River Delta are now requiring GB certification as a procurement precondition.
Specification-driven buying is fragmenting traditional distributor relationships in East Asian electronics clusters. Samsung and BOE procurement teams are engaging silane producers directly for lot-level purity documentation, bypassing regional chemical distributors. This disintermediation concentrates in South Korea's Giheung and China's Suzhou manufacturing corridors where foundry-scale volume justifies dedicated supply agreements.
Global Silanes Market Segmentation
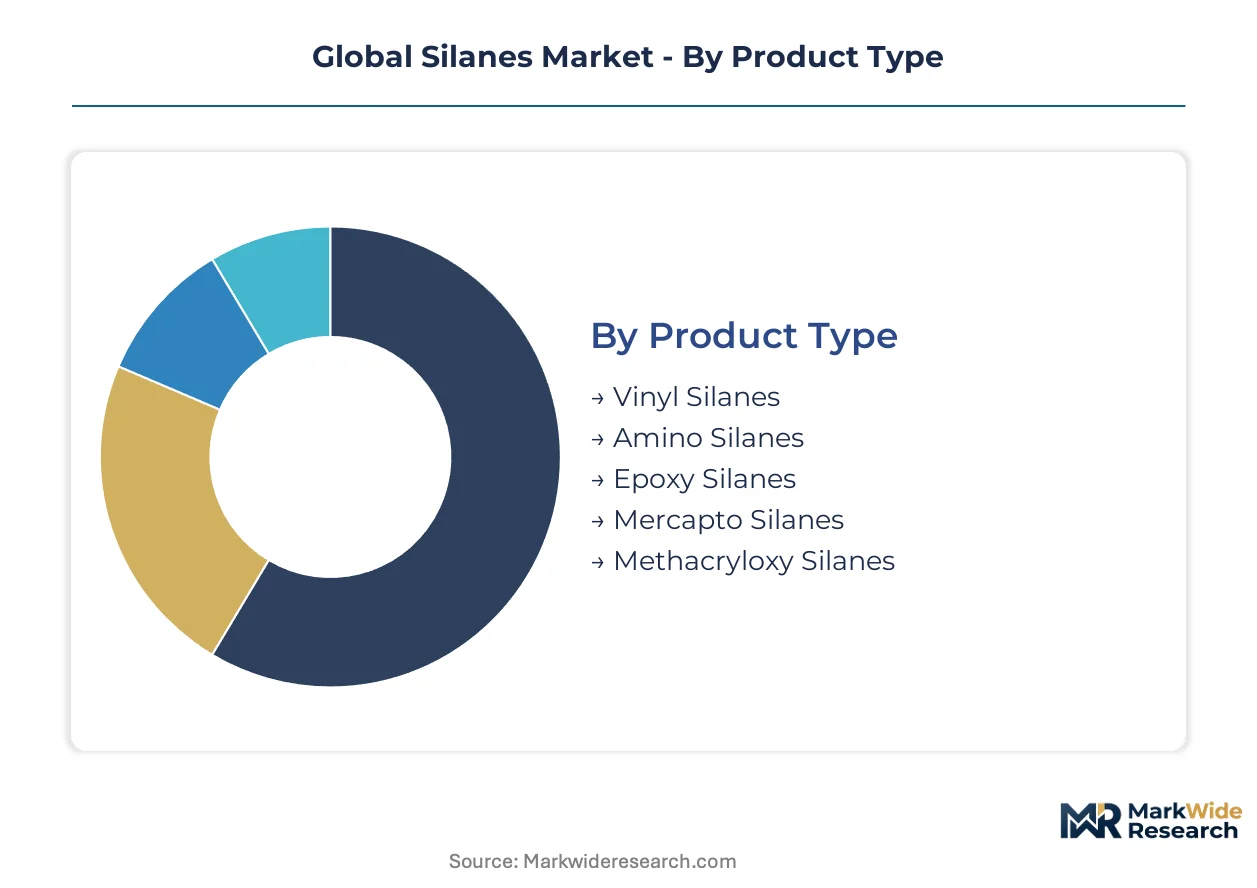
Silane producers face divergent technical specifications across electronics, construction, and automotive end-uses. Segmentation reveals where formulation complexity commands premium positioning versus where commoditization erodes margin.
Product Type:
Supply concentration in chlorosilane intermediates shapes competitive dynamics across molecular architectures, with integrated producers capturing margin in specialized grades while non-integrated players compete on standard volumes.
- Amino Silanes:Contain reactive amine functionality enabling covalent bonding with inorganic substrates and organic polymers. Semiconductor packaging lines in South Korea and China's Yangtze River Delta absorb ultra-high-purity grades for die-attach adhesives, with SAMR GB standards tightening metal contamination thresholds below 10 ppb. Epoxy silanes represent the fastest-growing trajectory as flexible OLED barrier layers multiply substrate adhesion points per display.
- Epoxy Silanes:Feature oxirane rings delivering superior moisture resistance and thermal stability in cross-linked networks. Chinese display fabs in Suzhou and Giheung corridors specify lot-level purity documentation, disintermediating traditional distributors for direct producer relationships.
- Vinyl Silanes:Enable peroxide-initiated cross-linking in polyethylene cable and pipe applications. Mature formulation standards in German and US infrastructure markets intensify price competition.
- Mercapto Silanes:Sulfur-functional chemistry dominates tire industry silica-silane coupling for rolling resistance reduction. Michelin and Bridgestone procurement specifications drive sulfur loading optimization.
- Methacryloxy Silanes:Acrylic functionality serves dental composite and optical coating applications where ISO 10993 biocompatibility certification creates entry barriers.
Today's leader: Amino Silanes. Tomorrow's challenger: Epoxy Silanes.
Application:
Cost tier differentiation separates specification-intensive electronics applications from volume-driven construction segments, with certification burden determining viable competitor sets.
- Adhesives & Sealants:Structural bonding in automotive lightweighting and semiconductor packaging demands low-alpha emission grades for memory device reliability. Henkel and 3M formulation partnerships specify silane lot traceability.
- Coatings & Paints:EPA VOC enforcement and REACH hazard classification expansions accelerate waterborne silane cross-linker adoption in US architectural and European industrial coatings.
- Rubber Reinforcement:Green tire silica-silane systems represent established volume demand, with sustainability certifications from agricultural waste silicon extraction gaining traction among European OEMs.
- Surface Treatment:Metal pretreatment and glass fiber sizing applications concentrate in Chinese automotive and wind energy manufacturing clusters.
- Pharmaceuticals:Drug delivery and medical device surface modification require ISO 13485 quality systems and FDA master file submissions, limiting supplier pools.
Electronics applications command 40-60% formulation cost premiums over construction grades. Construction volumes absorb standard-specification output from non-integrated producers.
End User Industry:
Customer type fragmentation separates specification buyers with captive technical teams from price-sensitive procurement functions in mature verticals.
- Electronics Manufacturing:Advanced packaging and flexible display substrates compress metal contamination tolerances and drive direct producer engagement. Samsung and BOE procurement teams bypass distributors for lot-level documentation.
- Construction:Sealant and waterproofing applications in German and US infrastructure markets operate on three-tier pricing structures across premium certified, standard performance, and economy grades.
- Aerospace Engineering:Conformal coatings and composite adhesion applications balance silane performance against fluorosilane substitution in extreme moisture resistance specifications.
- Agriculture Inputs:Silane-treated fertilizers and crop protection formulations expand in Indian PLI-supported manufacturing corridors.
- Personal Care:Cosmetic-grade amino silanes for hair conditioning and skin feel modification require REACH cosmetic regulation compliance and ECHA safety dossiers.
Electronics procurement is shifting toward direct technical partnerships. Construction remains distributor-dependent with price transparency.
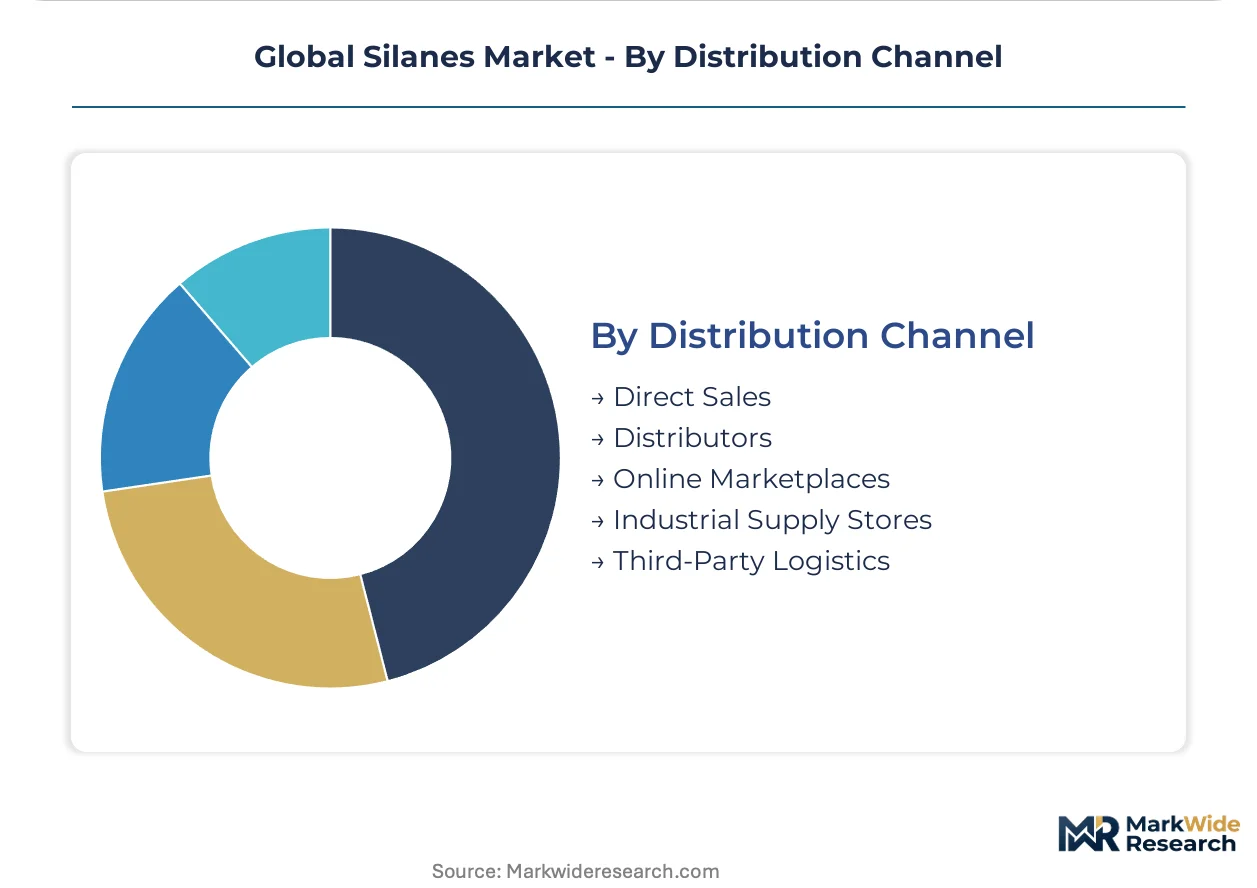
Distribution Channel:
Geography of demand concentration determines channel economics, with clustered manufacturing justifying dedicated supply agreements while fragmented markets sustain distributor networks.
- Direct Sales:Foundry-scale electronics manufacturers in South Korea's Giheung and China's Suzhou corridors negotiate dedicated supply agreements with purity documentation requirements.
- Distributors:Regional chemical distributors retain relevance in fragmented European coatings and US construction markets where formulation technical service adds value.
- Third-Party Logistics:Temperature-controlled silane transport and hazardous materials certification create specialized 3PL relationships for cross-border Asia-Europe supply.
- Industrial Supply Stores:Standard-grade vinyl and mercapto silanes for maintenance and repair operations in North American manufacturing belts.
- Online Marketplaces:Emerging channel for laboratory-scale quantities and sampling programs in academic and startup R&D procurement.
Channel selection correlates with specification intensity: direct for electronics, distributor for construction, hybrid for automotive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta manufacturing clusters absorb the highest silane procurement volumes globally as semiconductor packaging and display substrate production concentrates in East Asia. Regulatory divergence between REACH hazard classifications and China's GB standards under SAMR oversight fragments compliance pathways. Foundry-scale buyers in South Korea's Giheung corridor and China's Suzhou industrial zone now mandate direct producer relationships with lot-level purity documentation.
China
Flexible OLED substrate manufacturing in Suzhou and Hefei display fabs drives specialized amino and epoxy silane absorption. SAMR's GB standards mandate full substance toxicity dossiers for imports above one ton annually, granting domestic producers six-to-twelve-month compliance advantages. Yangtze River Delta electronics and automotive OEMs now require GB certification as a procurement precondition, bypassing traditional distributors for direct technical partnerships.
South Korea
Advanced semiconductor packaging lines in Giheung and Pyeongtaek absorb ultra-high-purity silane grades for die-attach adhesives and barrier layer applications. The Ministry of Trade, Industry and Energy supports domestic materials self-sufficiency through targeted R&D subsidies. Samsung Display procurement teams negotiate dedicated supply agreements with direct purity documentation requirements, disintermediating regional chemical distributors entirely.
Germany
Automotive lightweighting and industrial coatings sustain methacryloxy and vinyl silane demand from Bavarian and North Rhine-Westphalian manufacturing belts. ECHA's REACH registration expansions for organosilicon compounds accelerate substitution toward compliant grades in coatings and adhesives. Wacker Chemie's integrated silicon-metal feedstock positions in Burghausen and Charleston anchor supply security for European formulators facing chlorosilane concentration risk.
United States
Waterborne coating transitions in architectural and industrial applications open formulation slots for low-emission silane cross-linkers. EPA enforcement of volatile organic compound emissions from silane-based coatings pressures solventborne alternative displacement. Momentive Performance Materials leverages silicone-hybrid technology leadership from Ohio and New York facilities to anchor supply relationships with domestic semiconductor foundries.
India
Smartphone and component manufacturing incentives under the PLI scheme build captive silane demand in Noida and Sriperumbudur industrial corridors. The Bureau of Indian Standards develops domestic purity benchmarks for electronics-grade imports as local assembly scales. Tamil Nadu and Uttar Pradesh electronics manufacturing clusters attract silane distributor networks expanding from Singapore and Dubai logistics hubs.
Global Silanes Market Competitive Landscape
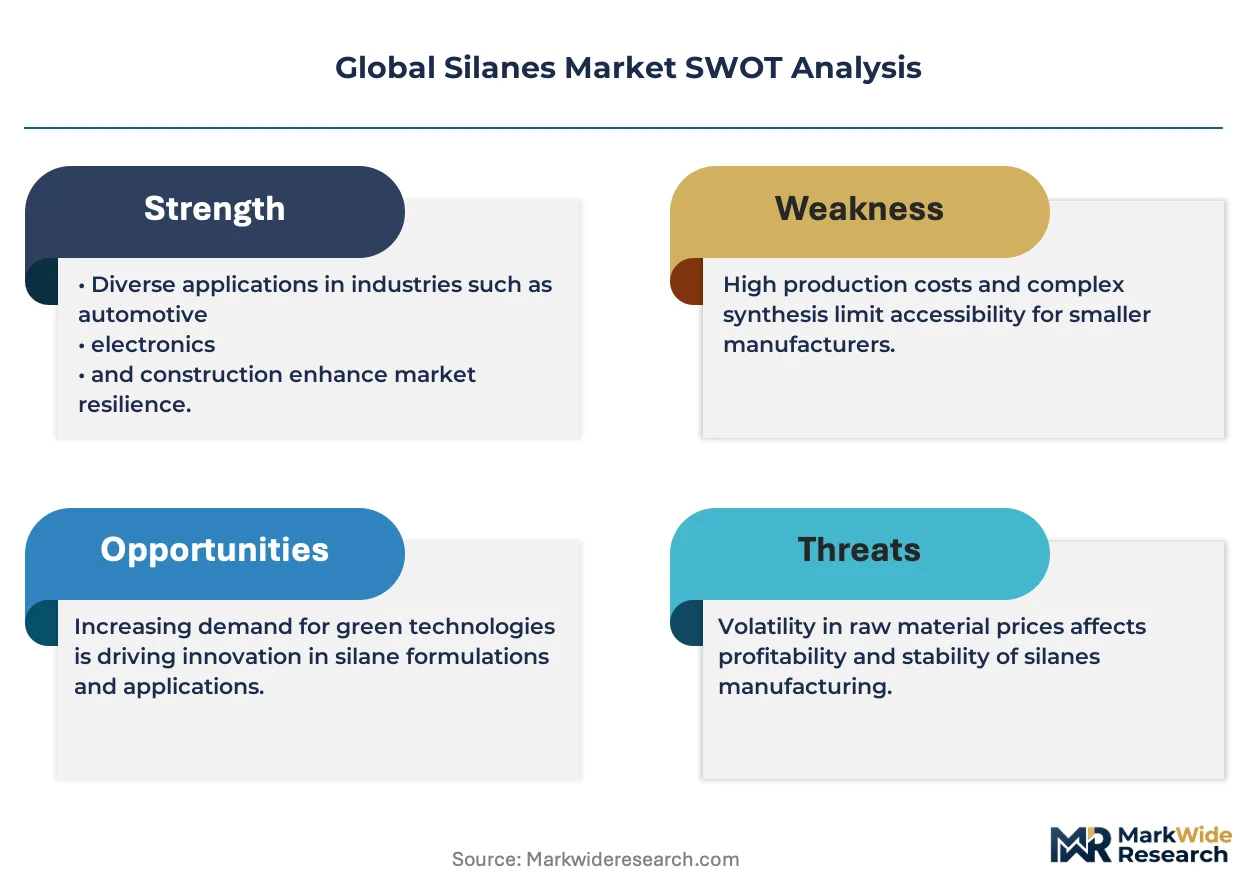
Capacity expansion dominates the current landscape as integrated producers retrofit chlorosilane assets for electronics-grade output. Four manufacturers control roughly three-quarters of intermediate supply, creating tiered access for non-integrated formulators. Two strategic archetypes have emerged: silicon-metal integrated players capturing margin in specialized grades, and regional formulators competing on standard volumes with distributor-dependent reach. M&A activity concentrates on hydrosilylation catalyst technology and regional distribution networks.
Among German and Japanese specialty chemical producers, Wacker Chemie AG, Shin-Etsu Chemical Co., Ltd., and Momentive Performance Materials Inc. exemplify divergent competitive positions. Wacker Chemie occupies the integrated archetype with captive silicon-metal feedstock control. Shin-Etsu represents the ultra-high-purity specialization vector competing on specification tightness rather than volume scale. Momentive anchors the silicone-hybrid technology tier serving semiconductor foundry direct procurement relationships. Each exemplifies how geographic feedstock positioning and purity certification capabilities determine viable customer segments.
| Leading Market Players |
|---|
| Momentive Performance Materials Inc. |
| KCC Corporation |
| Evonik Industries AG |
| Elkem ASA |
| OCI Company Ltd |
| Wacker Chemie AG |
| Shin-Etsu Chemical Co., Ltd. |
| Gelest, Inc. |
| Dow Inc. |
| Others |
Supply & Pricing Matrix
Metallurgical-grade silicon price indices in Yunnan and Xinjiang provinces cascade through chlorosilane intermediate costs into three distinct pricing tiers for downstream silane grades. Electronics manufacturers absorb premium positioning for ultra-high-purity specifications while construction buyers negotiate on standard-grade volumes.
Pricing Analysis
Input-cost pass-through from silicon-metal feedstock volatility shapes contract structures across the value chain. Pricing stratifies across semiconductor-grade, industrial-grade, and commodity-grade tiers with purity certification and lot-level documentation as primary price differentiation drivers. Cost compression in vinyl and mercapto silanes intensifies as Chinese polysilicon capacity expansions soften metallurgical-grade silicon benchmarks. Construction procurement functions exhibit highest price sensitivity while semiconductor foundries prioritize specification adherence over unit cost.
Supply Chain Analysis
Specialized chemical engineering talent availability in Burghausen, Charleston, and Zhangjiagang manufacturing corridors constrains capacity expansion timelines for electronics-grade output. Supply concentrates in Germany, China, and the United States with chlorosilane intermediates, platinum-group catalysts, and high-purity hydrogen as critical input dependencies. Single-source vulnerability pervades hydrosilylation catalyst supply with four integrated producers controlling intermediate flows. Distribution runs through direct technical partnerships for electronics clusters and regional chemical distributors for fragmented coatings markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play with China's GB standard compliance timelines creating six-to-twelve-month cost advantages for domestic producers over import-dependent competitors.
For Market Incumbents: Extend certification coverage across REACH, GB standards, and EPA registrations to lock out regional formulators lacking parallel compliance infrastructure. Fluorosilane substitution threats in aerospace-grade conformal coatings demand R&D investment in moisture-resistance performance parity. Backward integration into silicon-metal feedstock secures margin capture as chlorosilane concentration risk intensifies.
For New Entrants and Emerging Players: Online marketplaces for laboratory-scale quantities and sampling programs offer low-friction entry into academic and startup R&D procurement channels. India's PLI-supported electronics manufacturing corridors present the most penetrable geography with nascent distributor networks and evolving purity benchmarks. Direct technical partnerships with emerging display fabs bypass entrenched incumbent-distributor relationships.
For Investors and Strategic Acquirers: Asymmetric upside sits with hydrosilylation catalyst technology specialists and regional distribution networks in undersupplied manufacturing corridors. Long-term viability hinges on regulatory certification capabilities spanning multi-jurisdictional requirements rather than volume scale alone. Watch for SAMR GB standard enforcement acceleration as inflection indicator for domestic producer margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon-Metal Feedstock | Wacker Chemie's Burghausen and Charleston positions anchor supply security for European formulators. |
| Ultra-High-Purity Synthesis Capacity Expansion | Shin-Etsu's cleanroom synthesis environments capture semiconductor-grade specification premiums. |
| Multi-Jurisdictional Certification Investment | Parallel REACH, GB standard, and EPA registrations extend product launch cycles but lock out competitors. |
| Direct Technical Partnership Programs | Samsung and BOE procurement teams negotiate dedicated supply agreements with lot-level purity documentation. |
| Hydrosilylation Catalyst Technology Acquisition | Platinum and rhodium complex improvements reduce synthesis temperatures below 200°C, trimming energy costs. |
Research Methodology
Multiple input streams — technical R&D directors at specialty chemical producers, procurement leads at semiconductor foundries, distribution channel partners, and regulatory affairs specialists — were reconciled against customs and trade data, SEC filings, and ECHA registration databases. Primary interviews with plant managers in German and Chinese manufacturing belts informed capacity utilization and purity specification trends. Bottom-up segment sizing triangulated against top-down industry value chain analysis.
Historical capacity expansion patterns cross-referenced against panel input from downstream formulation partnerships shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-use industry, grade purity specification, and regional production hub. CAGRs derived from supply-demand balance trajectories incorporating hydrosilylation catalyst efficiency gains and electronics manufacturing absorption rates.
The model assumes a particular technology adoption path for continuous flow reactor deployment; alternative pathways for batch vessel retention would alter the outlook for mid-scale entrant economics. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and feedstock price normalization. Material deviation in SAMR GB standard acceleration or metallurgical-grade silicon supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Crystal Hard Wax Market
Specialty Chemicals
Carbocernaite Market
Specialty Chemicals
Perfluoropolyether (PFPE) Market
Specialty Chemicals
Precipitated Barium Sulfate Market
Specialty Chemicals
Copper (I) Hexafluoroacetylacetonate 1, 5- Cyclooctadiene Market
Specialty Chemicals
Plastic Stabilizer Market
Specialty Chemicals
4-ADPA Market
Specialty Chemicals
Cloud Emulsions Market
Specialty Chemicals
North America Aerosol Cans Market
Specialty Chemicals
Specialty Chemicals Market
Specialty Chemicals
Metal Biocide Market
Specialty Chemicals
Superoxide Dismutase Market
Specialty Chemicals
Germany Starch Derivatives Market
Specialty Chemicals
Fluoroethylene Carbonate (FEC) Market
Specialty Chemicals
Metominostrobin Market
Specialty Chemicals
Acesulfame Potassium Market