
 Wheat Fiber Market | 2026-2036
Wheat Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Wheat Fiber Market Outlook
Food processing expertise in dietary fiber extraction and modification is redrawing competitive boundaries in wheat fiber supply. Cargill Incorporated leverages its grain origination infrastructure to secure consistent wheat straw and bran feedstock across North American growing regions. Roquette Freres SA anchors its position through specialized wet-milling capabilities that isolate high-purity soluble fractions for pharmaceutical-grade applications. Tate & Lyle PLC competes by extending its ingredient formulation services beyond commodity supply, helping bakery and beverage clients rebalance fiber content without compromising sensory profiles.
Wheat fiber comprises the lignocellulosic and hemicellulosic fractions extracted from wheat bran, straw, or endosperm cell walls, typically containing 60-85% total dietary fiber with variable ratios of soluble to insoluble components depending on extraction method and wheat cultivar. Manufacturers employ mechanical milling, enzymatic treatment, or chemical fractionation to achieve particle sizes and hydration capacities suited to specific food matrix requirements, with insoluble fiber providing bulking and moisture retention in baked goods while soluble fractions contribute viscosity and fermentability in beverages and nutritional products. The insoluble fiber segment dominates volume due to its entrenched use in bread and pasta applications, though functional fiber isolates command premium positioning as brands reformulate for protein-fiber dual claims. Soluble fiber from wheat sources is gaining traction in dietary supplements as gut microbiome science advances, yet gluten-free fiber remains a niche constrained by cross-contamination control costs and smaller addressable populations.
The FDA's 2016 revised Nutrition Facts regulations, which established specific criteria for isolated or synthetic fibers to qualify as dietary fiber on labels, continue to shape R&D investment priorities by requiring clinical evidence of physiological benefit for novel fiber ingredients. In Europe, EFSA health claim assessments and the EU Green Deal's Farm to Fork sustainability targets are pushing processors toward valorization of wheat processing sidestreams rather than virgin grain diversion. Stakeholders must monitor evolving fiber qualification thresholds across jurisdictions while calibrating capital deployment between commodity-scale insoluble production and higher-margin functional isolate capacity.
Market Dynamics
The FDA's updated dietary fiber definition under Nutrition Facts labeling rules is compressing ingredient qualification pathways and forcing manufacturers to rebuild clinical evidence portfolios for novel wheat fiber isolates.
Growth Catalysts
- Clean-label bakery reformulation:European and North American bread manufacturers are accelerating wheat fiber incorporation as a texturizer that replaces synthetic additives while maintaining dough handling properties.
- EU Green Deal sidestream valorization:The Farm to Fork strategy incentivizes processors to extract dietary fiber from wheat bran and straw residues rather than diverting virgin grain, improving circularity metrics.
- Gut microbiome science advancement:Soluble wheat fiber fractions are gaining dietary supplement applications as clinical research validates fermentability benefits, expanding addressable categories beyond traditional food uses.
Market Restraints
- Gluten cross-contamination control costs:Producing certified gluten-free wheat fiber requires dedicated processing lines and testing protocols that constrain economies of scale for niche addressable populations.
- Clinical evidence requirements:The FDA's 2016 fiber qualification criteria mandate physiological benefit studies for novel isolates, extending R&D timelines and capital recovery periods.
- Oat and pea fiber substitution:Alternative plant fibers with established health claims and simpler supply chains compete for clean-label positioning in bakery and beverage applications.
Strategic Opportunities
- Pharmaceutical-grade soluble isolates:Wet-milling specialization to produce high-purity fractions for nutraceutical capsules and medical foods commands premium positioning above commodity insoluble grades.
- Protein-fiber dual claim products:Sports nutrition and meal replacement brands seek combined macronutrient fortification, creating formulation partnerships that bundle wheat fiber with protein concentrates.
- Downstream beverage viscosity solutions:Soluble wheat fiber's fermentability and mouthfeel properties suit ready-to-drink nutritional beverages, an application segment with faster growth than mature bakery channels.
Industry Challenges
- Multi-jurisdictional fiber qualification complexity:EFSA health claim assessments diverge from FDA physiological benefit standards, forcing parallel clinical study designs and label adaptation costs for international product lines.
- Enzymatic extraction scale-up engineering:Transitioning from mechanical milling to enzymatic or chemical fractionation requires bioprocess expertise and fermentation infrastructure uncommon in traditional grain processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheat Fiber Market |
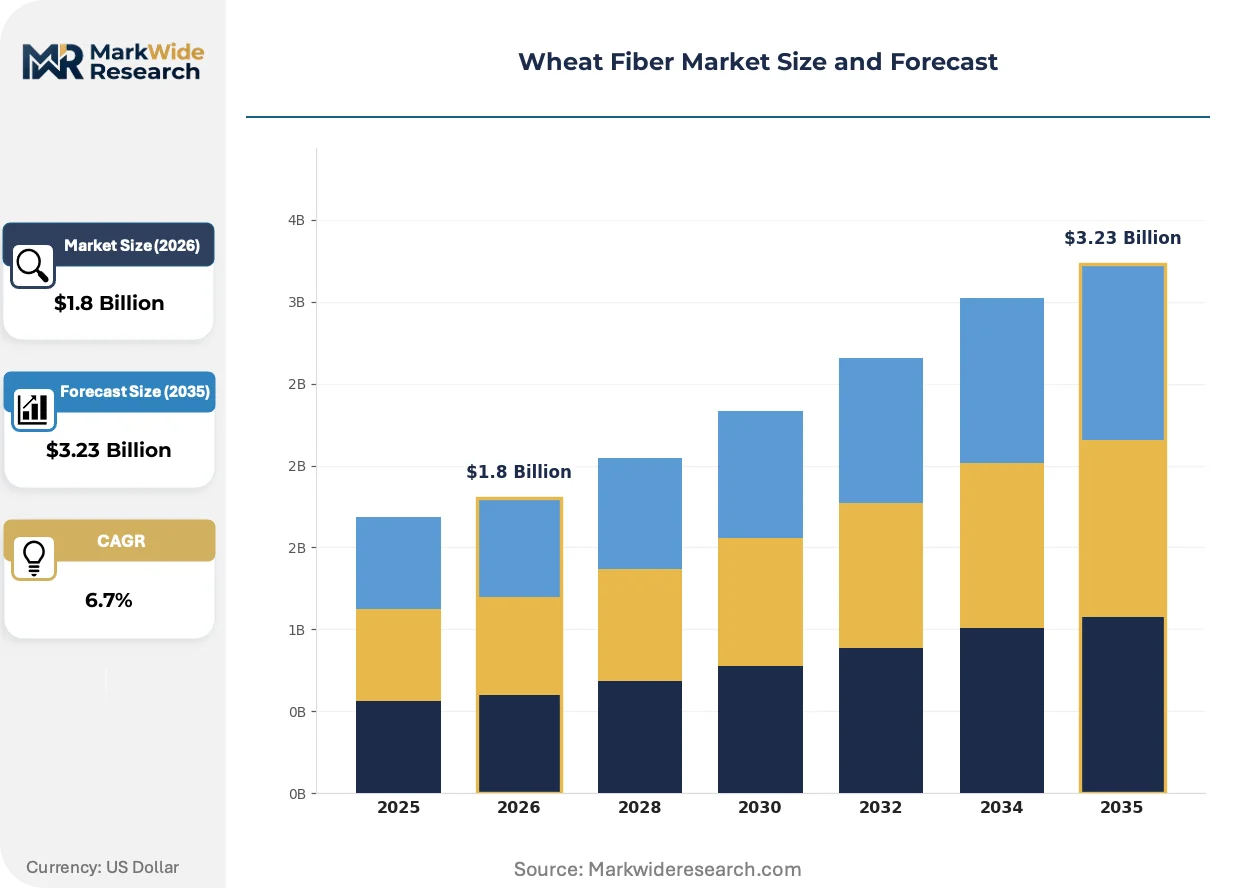
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soluble Fiber, Insoluble Fiber, Gluten-Free Fiber, Functional Fiber End Use Industry: Beverages, Bakery Products, Snacks, Dietary Supplements Application: Nutritional Products, Food Processing, Animal Feed, Pharmaceuticals Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Wholesalers |
| Companies Covered | Cargill Incorporated, DuPont De Nemours and Company, Archer Daniels Midland Company, Ingredion Incorporated, Tate & Lyle PLC, Roquette Freres SA, Suedzucker AG, SunOpta Inc, Rettenmaier & Sohne GmbH + Co KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheat Fiber Market Strategic Shifts
Enzymatic fiber modification and precision milling technologies are redefining what wheat fiber can deliver across food matrices, while regulatory divergence between major markets fragments standardization efforts.
Enzymatic treatment of wheat bran is decomposing lignocellulosic structures into targeted molecular weight fractions with tailored hydration and viscosity profiles. Pharmaceutical and nutraceutical manufacturers are adopting these isolates for encapsulation and controlled-release applications. This capability is decomposing the traditional commodity-insoluble versus premium-soluble segmentation by enabling grade-specific production from shared feedstock.
EFSA's evolving health claim assessment framework is tightening evidentiary standards for wheat fiber physiological benefits in European markets. Manufacturers must now commission human intervention studies demonstrating specific gut health outcomes to maintain label claims. Bakery and supplement segments targeting EU distribution are responding by consolidating R&D budgets toward clinical trial programs rather than formulation innovation alone.
Direct procurement relationships between food manufacturers and regional wheat processors are shortening fiber supply chains that historically ran through ingredient distributors. Large bakery groups in Germany and the United States are establishing volume commitments with specific millers to secure consistent bran specifications. This disintermediation is most visible in private-label bread and pasta manufacturing, where cost transparency and traceability requirements override distributor convenience.
Wheat Fiber Market Segmentation
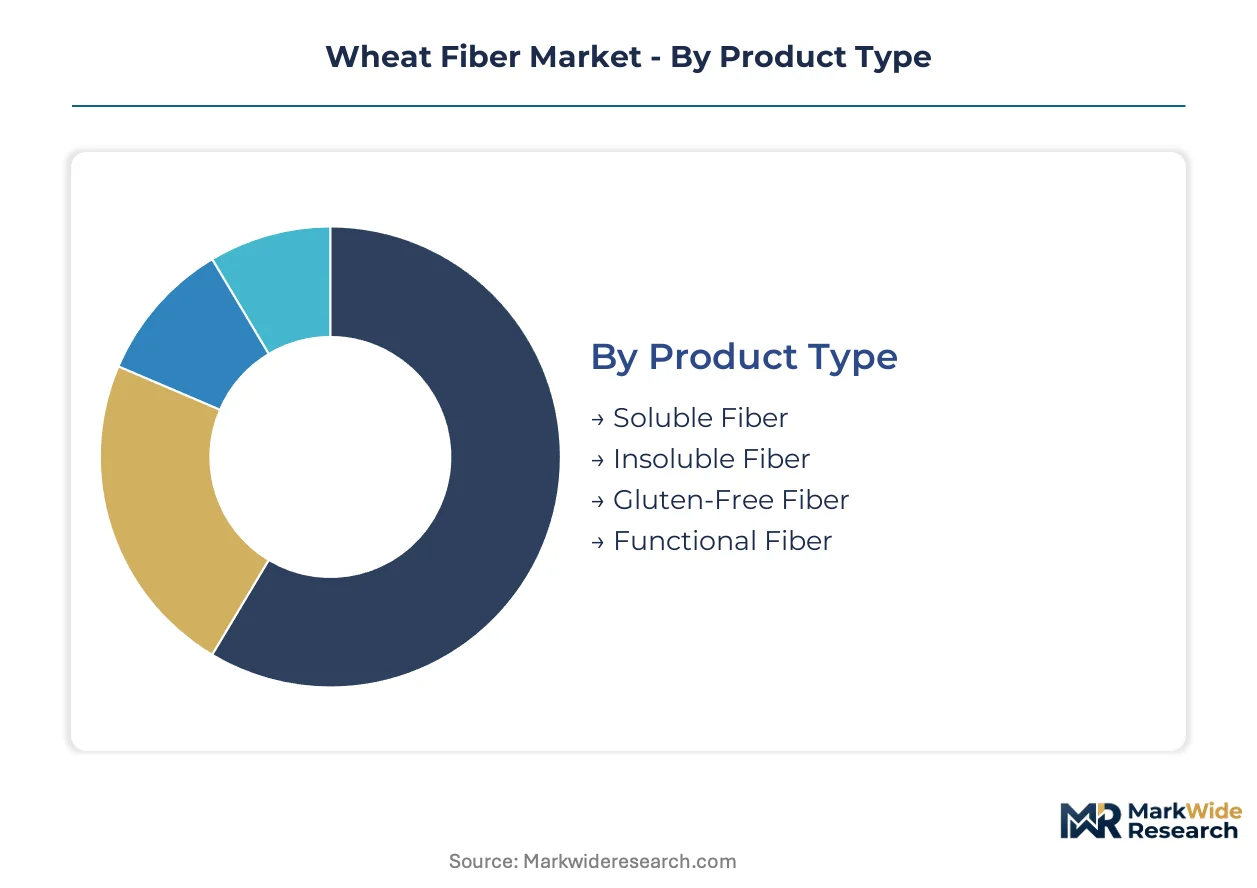
Wheat fiber segmentation reveals divergent commercial logics across product grades and end-use channels. Soluble isolates command pharmaceutical premiums while commodity insoluble grades compete on volume scale in mature bakery applications.
Product Type:
Insoluble fiber dominates domestic production in Germany and the United States, while soluble fractions and functional isolates flow disproportionately to export markets serving nutraceutical formulators.
- Soluble Fiber:High-purity fractions extracted through enzymatic or wet-milling processes, typically containing beta-glucans and arabinoxylans with demonstrated fermentability. Demand concentrates in dietary supplement capsules and medical foods manufactured in Switzerland and Japan, where EFSA and PMDA evidentiary standards reward clinical validation with premium positioning.
- Insoluble Fiber:Lignocellulosic and hemicellulosic fractions from mechanical bran milling, providing bulk density and moisture retention in dough systems. German and Italian bread manufacturers anchor volume demand, though substitution pressure from oat fiber in clean-label reformulations constrains margin expansion in mature European markets.
- Gluten-Free Fiber:Requires dedicated processing lines and batch testing to certify sub-20ppm gluten thresholds. Niche positioning serves celiac populations in Australia and Canada, where TGA and Health Canada labeling rules enforce strict cross-contamination protocols that fragment production scale.
- Functional Fiber:Modified fractions with tailored hydration capacities and particle size distributions for specific matrix requirements. Sports nutrition brands in the United States and meal replacement manufacturers in the United Kingdom drive specification development for protein-fiber dual claim products.
Insoluble fiber holds the largest share; momentum sits with functional fiber isolates.
End Use Industry:
Cost tier stratification separates commodity bakery applications from premium beverage and supplement channels, with snack manufacturers occupying an intermediate specification band.
- Bakery Products:Bread, pasta, and pastry manufacturers represent the foundational demand base, incorporating wheat fiber for dough handling improvement and clean-label texturization. German milling groups and North American industrial bakeries specify standard-grade insoluble fractions where cost transparency outweighs functional precision.
- Dietary Supplements:Capsule and powder formulators seek soluble fractions with validated fermentability for gut microbiome positioning. Swiss and Japanese nutraceutical manufacturers commission custom isolates that meet pharmaceutical-grade purity thresholds, paying substantial premiums over food-grade specifications.
- Beverages:Ready-to-drink nutritional products and fiber-fortified juices employ soluble wheat fiber for viscosity and mouthfeel control. Formulation partnerships between ingredient suppliers and beverage brands in the United States and United Kingdom are accelerating specification development for this application.
- Snacks:Extruded and baked snack manufacturers use fiber for structural integrity and satiety claims in bars and crisps. This segment occupies a mid-tier pricing position between commodity bakery and premium supplement applications.
Bakery products generate the highest volume; dietary supplements deliver the steepest expansion trajectory.
Application:
Volume concentration in food processing contrasts with margin concentration in pharmaceutical applications, where regulatory qualification creates defendable pricing power.
- Food Processing:Industrial bakeries and pasta manufacturers in Germany, Italy, and the United States constitute the core demand pool for standard-grade insoluble fiber. FDA and EFSA fiber qualification rules shape formulation decisions, with manufacturers preferring established ingredients with cleared label claims over novel isolates requiring fresh clinical evidence.
- Pharmaceuticals:Encapsulation substrates and controlled-release matrices employ high-purity soluble fractions. Swiss and Japanese pharmaceutical manufacturers source through direct procurement relationships that bypass traditional ingredient distributors, securing batch consistency for regulatory filings.
- Nutritional Products:Meal replacements, sports nutrition, and clinical nutrition products combine fiber fortification with protein and micronutrient positioning. Formulation services bundled with ingredient supply are displacing commodity transactions in this application.
- Animal Feed:Wheat bran and lower-grade fiber fractions serve ruminant and monogastric feed formulations, particularly in integrated grain processing operations where sidestream valorization improves circularity metrics under EU Green Deal frameworks.
Food processing commands absolute volume; pharmaceuticals capture the highest value per kilogram.
Distribution Channel:
Customer type and order scale determine channel selection, with large manufacturers disintermediating distributors while small formulators rely on specialized retail access.
- Wholesalers:Bulk ingredient distributors serve mid-scale food manufacturers and regional bakery groups across Germany, France, and the United States. This channel retains relevance where formulation expertise requirements are modest and specification standardization permits inventory pooling.
- Health Food Stores:Specialized retailers supply small-scale supplement manufacturers and artisanal food producers seeking organic or non-GMO certified fiber grades. Premium positioning and technical consultation services differentiate this channel from commodity wholesale.
- Supermarkets:Limited retail-packaged fiber sales for home baking and DIY supplement preparation, primarily in German and UK markets where consumer familiarity with fiber fortification exceeds other geographies.
- Online Retail:E-commerce platforms serve niche formulators and research institutions requiring small-batch specialty grades with rapid specification lookup and comparative technical documentation.
Wholesalers maintain the broadest reach; direct procurement is displacing intermediary relationships fastest among large accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA's fiber qualification framework anchors European demand concentration, while FDA labeling rules reshape North American formulation priorities. Regulatory divergence between these jurisdictions fragments standardization efforts across the forecast window.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia drive insoluble fiber consumption for clean-label bread reformulation. The EU Green Deal's Farm to Fork strategy accelerates wheat sidestream valorization mandates. Rettenmaier & Sohne GmbH + Co KG anchors supply from its Rosenberg headquarters, securing volume commitments with milling groups across southern Germany.
United States
Ready-to-drink beverage manufacturers and sports nutrition brands in California and Illinois expand soluble fiber procurement for viscosity control. FDA's 2016 Nutrition Facts fiber definition requires clinical evidence portfolios for novel isolates. Cargill Incorporated leverages its grain origination infrastructure across Midwest growing regions to secure consistent wheat straw and bran feedstock.
Switzerland
Pharmaceutical-grade soluble fiber demand concentrates in Basel and Zurich for encapsulation applications. Swissmedic and EFSA alignment on health claim evidentiary standards supports premium positioning. Nutraceutical manufacturers commission custom isolates meeting pharmaceutical purity thresholds, paying substantial premiums over food-grade specifications.
Japan
Dietary supplement formulators in Tokyo and Osaka seek fermentable wheat fractions for gut microbiome positioning. PMDA evidentiary standards reward clinical validation with premium market access. Direct procurement relationships between supplement manufacturers and regional processors shorten historically distributor-dependent supply chains.
United Kingdom
Meal replacement and bakery manufacturers in Greater London and the Midlands rebalance fiber content for protein-fiber dual claims. Post-Brexit regulatory divergence from EFSA frameworks complicates label claim continuity. Tate & Lyle PLC extends formulation services from its London base, bundling technical consultation with ingredient supply.
Wheat Fiber Market Competitive Environment
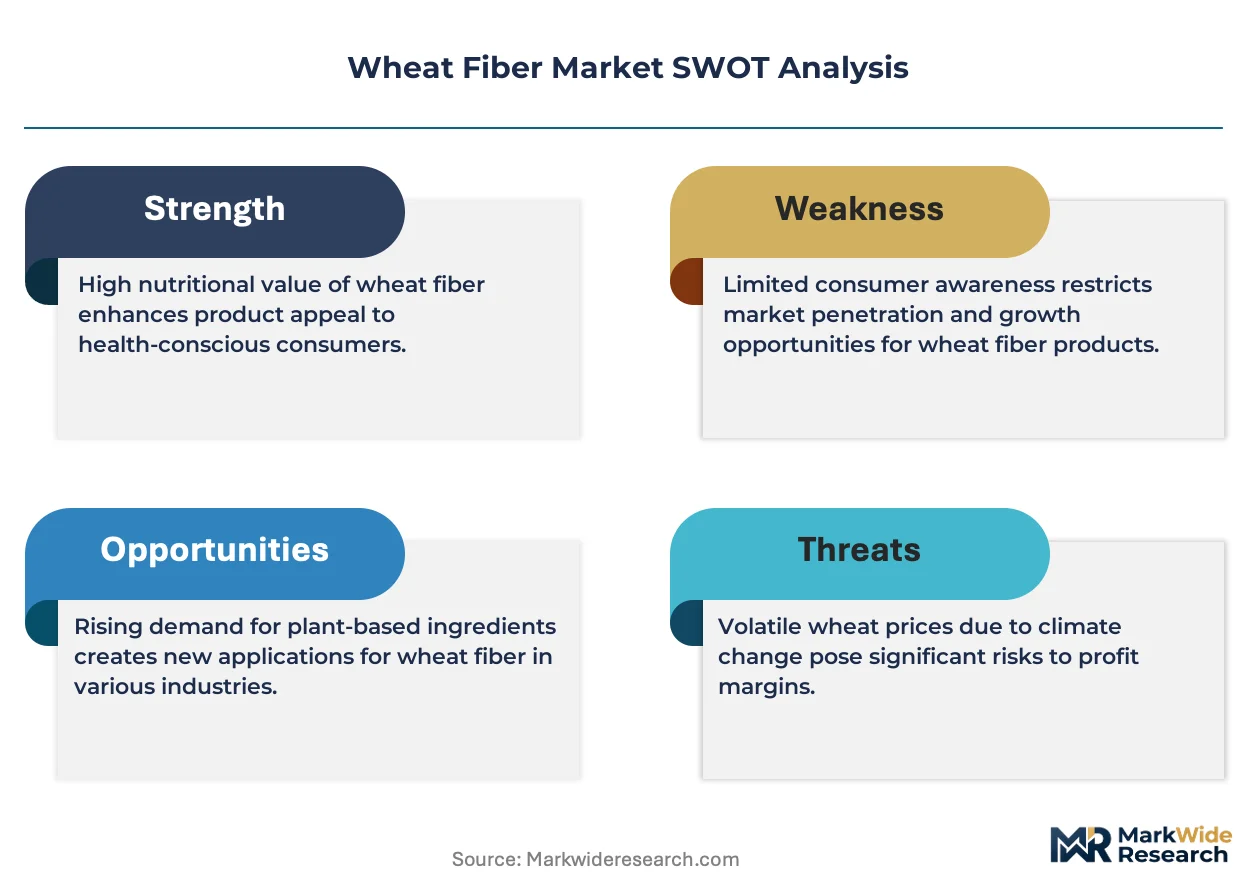
A small set of integrated leaders sits above a broader specialist tier, with grain traders and wet-milling specialists occupying distinct competitive positions. The upper tier commands origination infrastructure and pharmaceutical-grade purification capabilities. Three archetypes define the field: integrated grain processors with captive feedstock access, specialized wet-milling operators with enzymatic fractionation expertise, and formulation-service bundlers extending beyond commodity supply. Capacity expansion in soluble isolate production and backward integration into wheat processing sidestreams represent the dominant competitive moves.
Within the integrated processor tier, Cargill Incorporated and Archer Daniels Midland Company exemplify origination-scale positioning, while Roquette Freres SA represents wet-milling specialization for high-purity fractions. Tate & Lyle PLC occupies the formulation-service vector, bundling technical consultation with ingredient supply to displace commodity transactions.
| Leading Market Players |
|---|
| Cargill Incorporated |
| DuPont De Nemours and Company |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Roquette Freres SA |
| Suedzucker AG |
| SunOpta Inc |
| Rettenmaier & Sohne GmbH + Co KG |
| Others |
Value Chain & Pricing Dynamics
Mill-scale economies in German wheat processing anchor price floors across European fiber markets, concentrating supply among integrated origination networks while compressing margins for mechanical-milling commodity grades. Capacity utilization rates at bran-processing facilities in Bavaria and North Rhine-Westphalia directly determine spot pricing volatility for standard insoluble fractions.
Pricing Analysis
German pharmaceutical-grade soluble fiber commands substantial premiums over North American food-grade specifications, with Swiss and Japanese buyers paying differential rates for EFSA- and PMDA-validated isolates. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical encapsulation substrates from bakery-grade insoluble fractions and animal feed sidestreams. Cost compression in commodity insoluble grades is intensifying because oat fiber substitution in clean-label bakery reformulations constrains margin expansion. Industrial bread manufacturers in Germany and Italy exhibit highest price sensitivity, while Swiss nutraceutical formulators demonstrate lowest elasticity due to regulatory qualification requirements.
Supply Chain Analysis
Inventory cycles at wheat milling operations typically extend 6-8 weeks for bran feedstock, creating lead-time sensitivity for pharmaceutical-grade soluble fiber orders requiring batch-specific purity certification. Supply concentrates in Germany, the United States, and France, with Rettenmaier & Sohne and Cargill anchoring origination infrastructure across these geographies. Wheat straw and bran feedstock draws from Midwest growing regions and southern German wheat belts, with enzymatic extraction reagents sourced from specialized bioprocess chemical suppliers. Single-source vulnerability persists for pharmaceutical-grade wet-milling capacity, where Roquette Freres SA and limited European specialists control high-purity fraction supply. Distribution runs through bulk ingredient wholesalers serving mid-scale manufacturers, though direct procurement relationships are displacing intermediary channels among large bakery and beverage accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wheat fiber market presents a defensive-moat structure anchored in regulatory entrenchment, where FDA fiber qualification requirements and EFSA health claim evidentiary standards create multi-year barriers to novel isolate commercialization.
For Market Incumbents: Compound origination-scale advantages by securing long-term volume commitments with German and Midwest wheat milling groups, locking in bran feedstock access that emerging enzymatic fractionation specialists cannot replicate without capital-intensive backward integration. Prioritize certification investment for pharmaceutical-grade soluble isolates, as PMDA and Swissmedic alignment on gut microbiome health claims creates premium pricing power that commodity insoluble producers cannot access.
For New Entrants and Emerging Players: Anchor in beverage viscosity solutions for ready-to-drink nutritional products, where formulation partnerships with California and Illinois manufacturers offer faster penetration than entrenched bakery channels dominated by established suppliers. Target gluten-free fiber certification for Australian and Canadian celiac populations, where TGA and Health Canada labeling enforcement creates niche premium positioning despite constrained scale. Pursue direct procurement relationships with sports nutrition brands seeking protein-fiber dual claim bundles, bypassing distributor relationships where incumbents hold channel control.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among wet-milling specialists with pharmaceutical-grade purification capabilities, where multi-year nutraceutical supply contracts and regulatory filing dependencies generate predictable cash flows across the analysis window. Prioritize acquisition targets with demonstrated EFSA health claim validation or FDA fiber qualification clearance, as these regulatory assets require 3-5 year investment timelines that financial buyers cannot easily replicate. Watch for inflection when oat fiber substitution rates in European clean-label bakery reformulations cross thresholds that force wheat fiber margin compression and consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wheat Milling | Cargill's grain origination infrastructure secures captive bran feedstock across Midwest growing regions. |
| Pharmaceutical-Grade Wet-Milling Expansion | Roquette Freres SA's enzymatic fractionation capabilities command premium pricing from Swiss encapsulation manufacturers. |
| EFSA Health Claim Clinical Investment | Rettenmaier & Sohne's Rosenberg R&D programs validate gut microbiome outcomes for European supplement positioning. |
| Direct Procurement Relationship Development | Tate & Lyle's London-based formulation services displace distributor channels for UK meal replacement brands. |
| Gluten-Free Processing Line Certification | Dedicated Australian facilities meeting TGA sub-20ppm thresholds access premium celiac-population segments. |
Study Parameters
The analysis maps soluble fiber isolates, insoluble fiber grades, gluten-free certified fractions, and functional modified fibers, each validated through plant managers at wheat processing facilities, procurement leads at industrial bakeries, regulatory affairs specialists at nutraceutical manufacturers, and technical R&D directors at ingredient formulators. Primary interview findings were cross-referenced with secondary sources including FDA Nutrition Facts labeling guidance documents, EFSA health claim assessment registers, EU Farm to Fork strategy implementation reports, and customs trade data for wheat bran and fiber concentrate flows. Bottom-up volume estimates from facility-level capacity assessments were reconciled with top-down demand projections derived from end-use industry consumption patterns.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation models incorporating product type, end-use industry, application channel, and geographic regulatory cluster dimensions. CAGRs were derived from fitted growth curves calibrated to historical capacity expansion rates and demand elasticity estimates for bakery, beverage, and supplement applications. Forecast inputs included wheat cultivar fiber content variation, enzymatic extraction yield improvements, and evolving fiber qualification thresholds across FDA, EFSA, and PMDA jurisdictions.
Decision-makers should treat outputs as directional under assumptions of stable regulatory frameworks and continued clean-label reformulation momentum; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding wheat supply chain continuity and clinical validation timelines for novel isolates. Revision becomes warranted when oat fiber substitution rates in European bakery applications or FDA fiber definition enforcement intensity crosses thresholds that alter competitive dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Wheat Bran Market
Grains
Asia Pacific Maize Market
Grains
Grain Bins Market
Grains
Oat Flour Market
Grains
South American Maize Market
Grains
North America Pulses Market
Grains
00 Flour Market
Grains
Gluten Feed Market
Grains
Barley Market
Grains
Basmati Rice Market
Grains
Grain Storage Silos Market
Grains
Sorghum Market
Grains
Africa Wheat Flour Market
Grains
Uganda Grains Market
Grains
Chickpeas Market
Grains
Global Grain Analysis Market