
 United Kingdom Casein and Caseinates Market | 2026-2036
United Kingdom Casein and Caseinates Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Casein and Caseinates Market Analytics
Modular ingredient bundling is pivoting how food processors purchase caseinates, shifting from single-specification bulk orders to blended protein systems that combine sodium caseinate with emulsifier packages. Arla Foods amba anchors its UK position through backward integration into cooperative milk supply. Royal FrieslandCampina N.V. leverages its Dutch processing network to compete on sodium caseinate consistency. Fonterra Co-operative Group Limited differentiates through specialized technical service for pharmaceutical-grade material.
Casein and caseinates comprise milk-derived proteins separated through acid or rennet precipitation, with caseinates produced by neutralizing acid casein using sodium, calcium, or potassium hydroxide to improve water solubility and emulsification capacity; these functional proteins serve primarily as binding agents, emulsifiers, and nutritional fortifiers across food and pharmaceutical applications. Powder form dominates current UK volume due to extended shelf stability and lower transport costs, though liquid caseinate concentrates are gaining traction in ready-to-drink nutritional formulations. Sodium caseinate leads product type demand through its superior foaming and emulsification properties in processed meat and coffee whitener applications, while calcium caseinate captures expanding nutraceutical interest for slow-release amino acid profiles.
The Food Standards Agency enforces compositional standards for dairy-derived ingredients under retained EU food law, while the Medicines and Healthcare products Regulatory Agency governs pharmaceutical-grade caseinate specifications for excipient use. British Standards Institution certification for food contact materials shapes packaging requirements and supplier qualification protocols. Stakeholders must monitor evolving divergence between UK and EU food safety regulations as the basis for ingredient approval timelines and cross-border trade documentation requirements.
Market Dynamics
Modular ingredient bundling is restructuring how UK food processors purchase caseinates, shifting procurement from single-specification bulk orders toward integrated protein-emulsifier systems that reduce formulation complexity and supplier management overhead.
Growth Catalysts
- Retained EU Food Law Alignment:The Food Standards Agency maintains compositional standards for dairy-derived ingredients, providing regulatory continuity that sustains cross-border ingredient trade confidence.
- Nutraceutical Protein Fortification:Sports nutrition and medical food manufacturers are expanding caseinate procurement for slow-release amino acid delivery systems.
- Midlands Processing Corridor Concentration:England's central food manufacturing belt generates clustered demand that reduces logistics costs and enables just-in-time delivery models.
Market Restraints
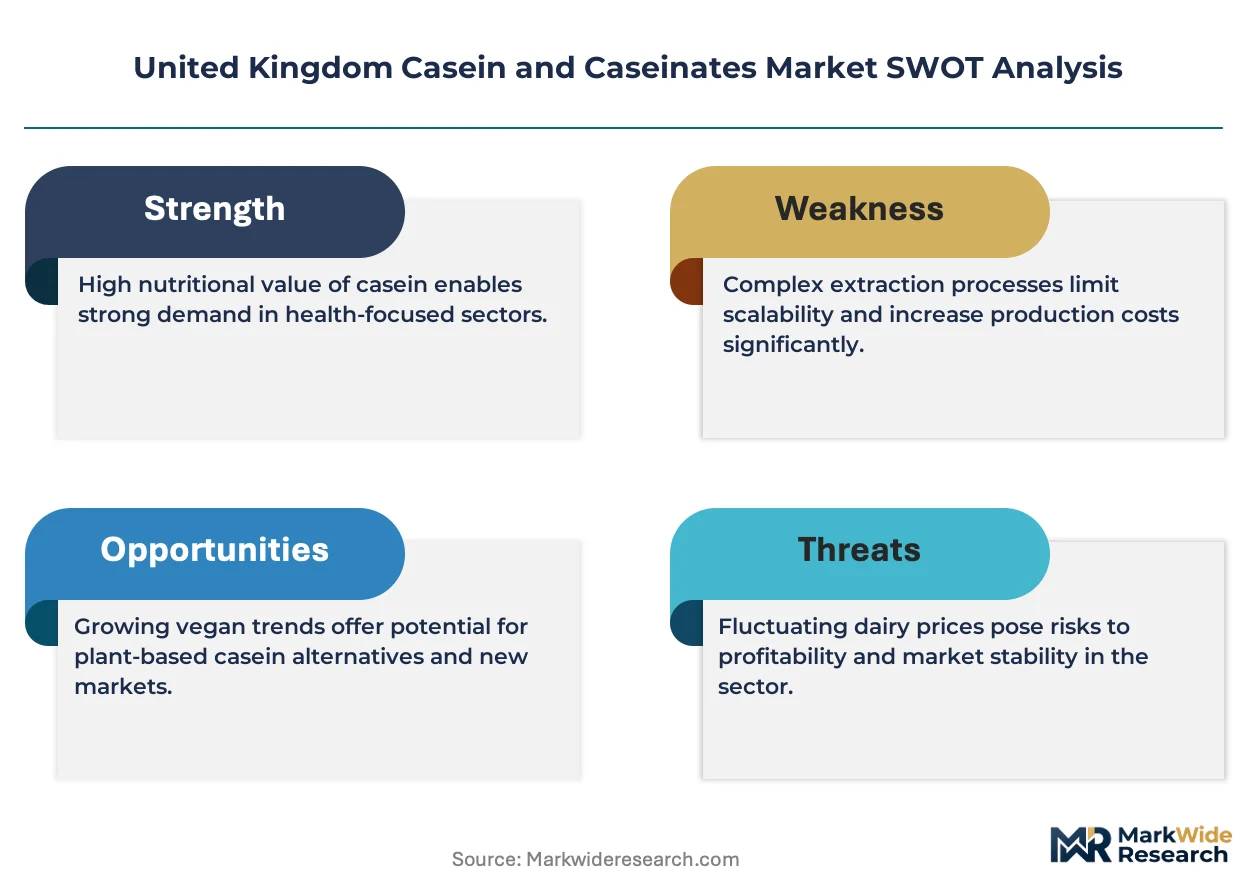
- Milk Supply Volatility:UK dairy farm gate prices fluctuate with feed cost inflation and weather patterns, compressing casein processor margins during input spikes.
- Supplier Concentration Risk:Three cooperative dairy processors control the majority of domestic caseinate production capacity, creating bottleneck vulnerability.
- Plant Protein Substitution:Pea and fava bean protein isolates are capturing share in meat analogue applications where emulsification requirements are less stringent.
Strategic Opportunities
- Pharmaceutical-Grade Excipient Expansion:The Medicines and Healthcare products Regulatory Agency's updated excipient guidelines create pathways for caseinate suppliers to enter parenteral nutrition formulations.
- Ready-to-Drink Liquid Concentrates:Beverage manufacturers are piloting liquid caseinate systems that eliminate powder reconstitution steps in high-volume production lines.
- British Standards Institution Certification Premium:Food contact material certification is enabling suppliers to command price premiums in premium packaged goods channels.
Industry Challenges
- Technical Service Talent Scarcity:Formulation chemists with dual expertise in dairy protein functionality and pharmaceutical excipient standards are in short supply across the UK supplier base.
- Legacy Equipment Retrofit Costs:Powder processing lines require capital-intensive upgrades to handle liquid concentrate viscosity profiles and extended shelf-life packaging.
- Diverging UK-EU Documentation Requirements:Post-Brexit regulatory divergence is forcing exporters to maintain parallel compliance systems for ingredient approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Casein and Caseinates Market |
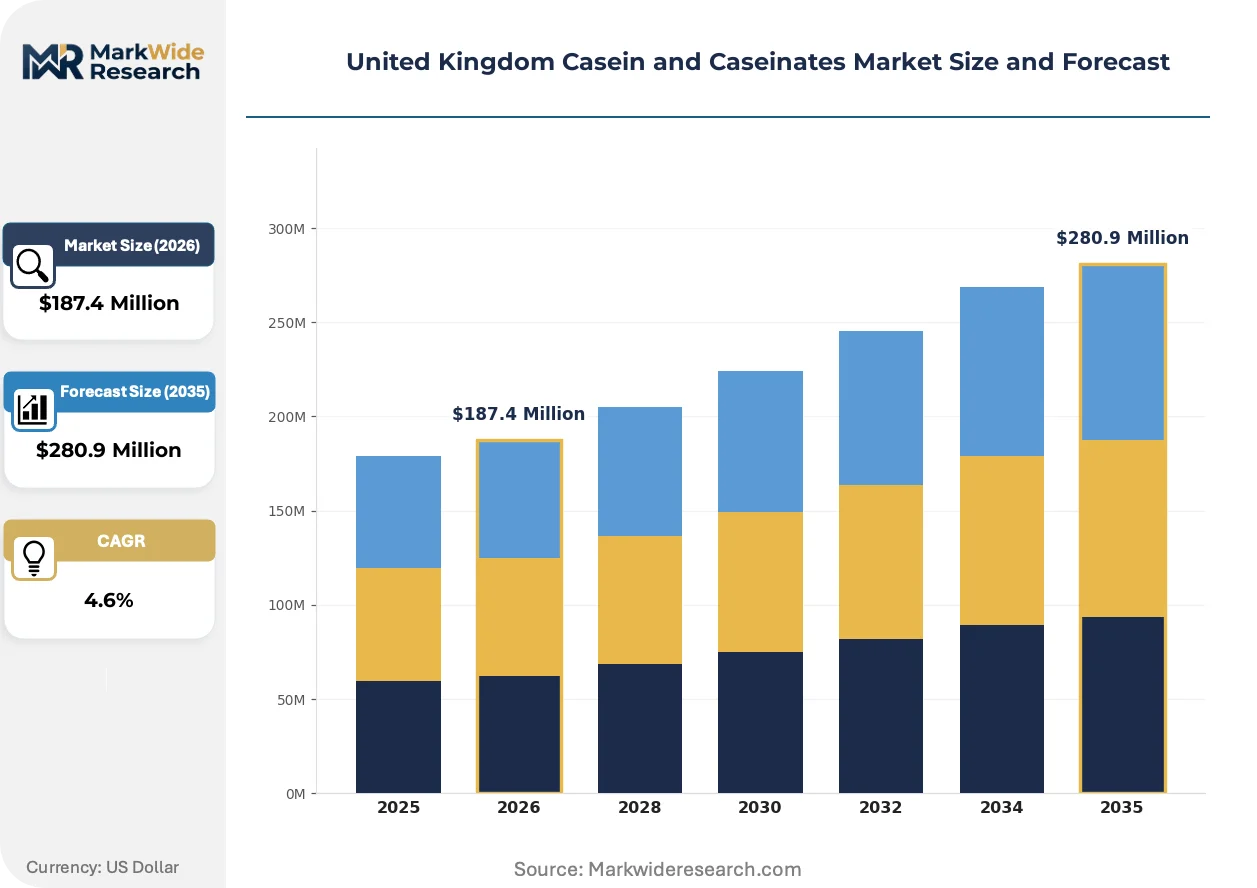
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casein, Calcium Caseinate, Sodium Caseinate, Potassium Caseinate End Use Industry: Dairy, Food Processing, Pharmaceuticals, Nutraceuticals Form: Powder, Granule, Liquid, Coated Packaging Type: Bags, Drums, Totes, Bulk |
| Companies Covered | Arla Foods amba, Royal FrieslandCampina N.V., Fonterra Co-operative Group Limited, MEGGLE GmbH & Co.KG, Agrial Group, Lactoprot Deutschland GmbH, LAITA, Erie Foods International, Inc., Prinova Group LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Casein and Caseinates Market Evolving Landscape
Digital process control systems and protein fractionation advances are compressing production cycles while regulatory divergence between the UK and EU is forcing compliance architecture redesign across the supplier base.
Membrane filtration technology is automating casein micelle separation with precision that acid precipitation cannot match. Pharmaceutical-grade material producers are adopting these systems fastest, driven by excipient consistency requirements. This automation is compressing batch-to-batch variation to sub-2% protein content deviation, enabling suppliers to reduce quality hold times and accelerate customer qualification cycles.
The Food Standards Agency's updated dairy labeling requirements are tightening ingredient traceability standards for all supply chain tiers. Processors must now maintain farm-level documentation for casein source batches used in retail-facing products. Nutraceutical contract manufacturers face the steepest compliance burden, as they lack the backward integration that major cooperatives use to satisfy audit demands.
Ingredient bundling contracts are consolidating supplier relationships as food processors seek single-source accountability for protein-emulsifier-stabilizer combinations. Ready-meal manufacturers are leading this shift, replacing three separate procurement streams with integrated formulation packages. Scotland's prepared foods sector shows the fastest adoption, driven by processor consolidation and centralized technical purchasing functions.
United Kingdom Casein and Caseinates Market Segmentation
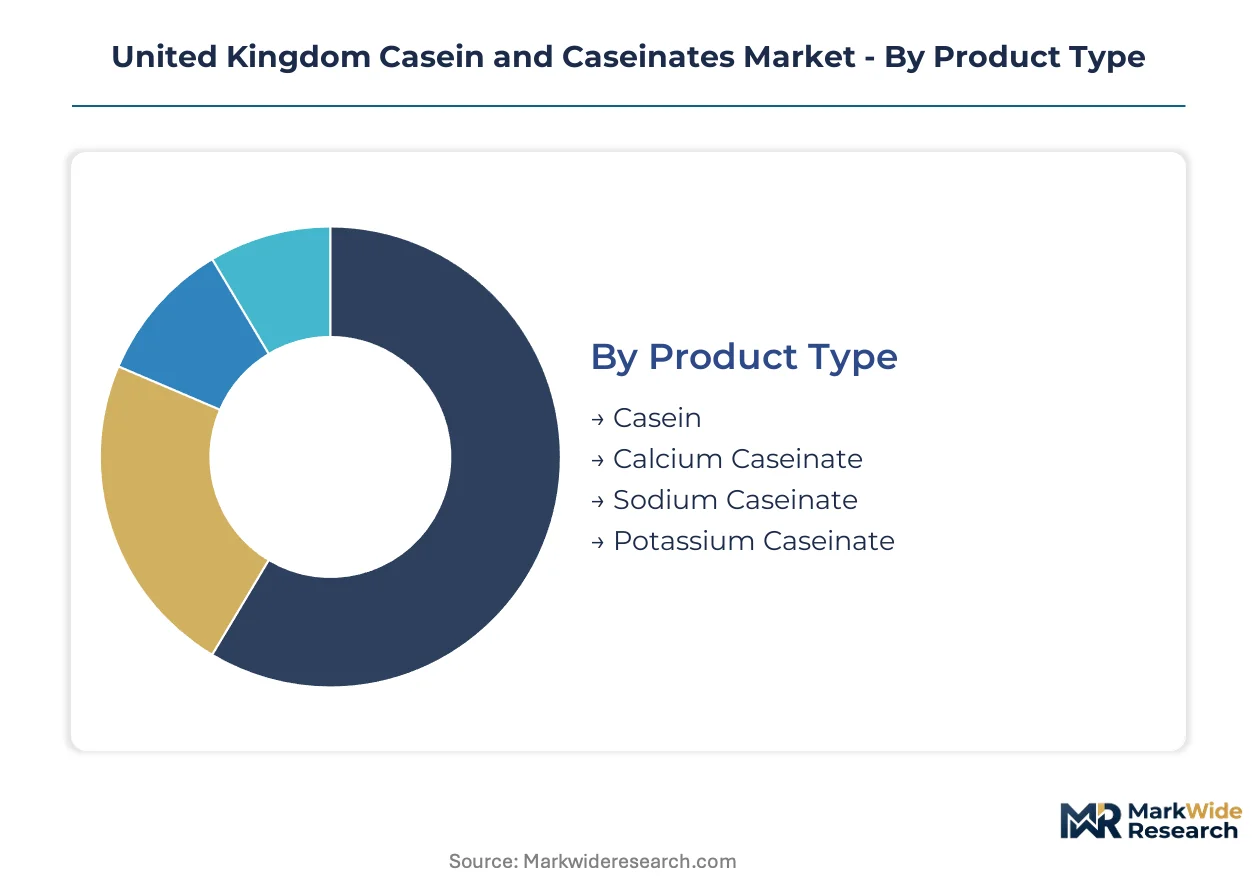
Casein and caseinate procurement patterns in the United Kingdom diverge sharply across application requirements, with pharmaceutical-grade specifications commanding fundamentally different supply chain configurations than commodity food-grade material. Understanding these segment boundaries enables suppliers to align technical service resources and certification investments with margin concentration.
Product Type:
Supply concentration in UK caseinate production tilts toward sodium and calcium variants, reflecting the Midlands food processing corridor's emulsification and nutritional fortification requirements.
- Sodium Caseinate:Produced through neutralization of acid casein with sodium hydroxide, this variant delivers superior foaming capacity and water-binding performance. Coffee whitener and processed meat manufacturers in England's central belt source this grade most intensively, drawn by its established emulsification reliability in high-speed production lines.
- Calcium Caseinate:Slow-release amino acid delivery characteristics distinguish this segment, produced via calcium hydroxide neutralization. Sports nutrition and medical food formulators are expanding procurement of this grade, prioritizing its sustained nitrogen release profile for overnight recovery applications.
- Casein:The acid or rennet-precipitated base protein retains limited water solubility, restricting its application to cheese manufacturing and industrial adhesive formulations where emulsification is secondary.
- Potassium Caseinate:Mineral-fortified positioning drives modest demand from specialized clinical nutrition products targeting electrolyte-balanced formulations.
Today's leader: Sodium Caseinate. Tomorrow's challenger: Calcium Caseinate.
End Use Industry:
Application-driven cost tiering separates commodity food-grade procurement from pharmaceutical-grade excipient qualification, with the latter requiring Medicines and Healthcare products Regulatory Agency compliance architecture.
- Food Processing:Ready-meal manufacturers and meat processors constitute the volume anchor, deploying caseinates for moisture retention and texture stabilization in reformed products. Scotland's prepared foods sector shows fastest adoption of bundled protein-emulsifier systems, consolidating supplier relationships around single-source accountability.
- Pharmaceuticals:Parenteral nutrition and tablet excipient applications demand batch-level traceability and sub-2% protein deviation consistency. Membrane filtration adoption concentrates in this segment, driven by excipient qualification requirements under retained EU pharmaceutical standards.
- Nutraceuticals:Protein fortification in sports nutrition and medical foods is expanding caseinate procurement, though contract manufacturers face steepest traceability burdens without cooperative backward integration.
- Dairy:Cheese manufacturing and dairy-based beverage applications utilize acid casein for curd formation and protein standardization, representing mature demand with limited growth trajectory.
Food Processing commands current volume. Pharmaceuticals offers the steepest expansion trajectory.
Form:
Customer type segmentation separates powder-loyal legacy processors from liquid-curious beverage innovators, with equipment retrofit costs determining migration pace.
- Powder:Extended shelf stability and lower transport costs sustain dominance across traditional food manufacturing, with established reconstitution protocols in Midlands processing facilities.
- Liquid:Ready-to-drink nutritional formulations are piloting liquid caseinate concentrates to eliminate powder reconstitution steps, though high-volume production line adaptation remains capital-intensive.
- Granule:Intermediate flow characteristics serve specialty applications requiring controlled dissolution rates in instant beverage matrices.
- Coated:Encapsulation technologies protect protein functionality in aggressive processing environments, capturing niche pharmaceutical and fortified food applications.
Powder retains installed base dominance. Liquid is gaining share fastest among beverage innovators.
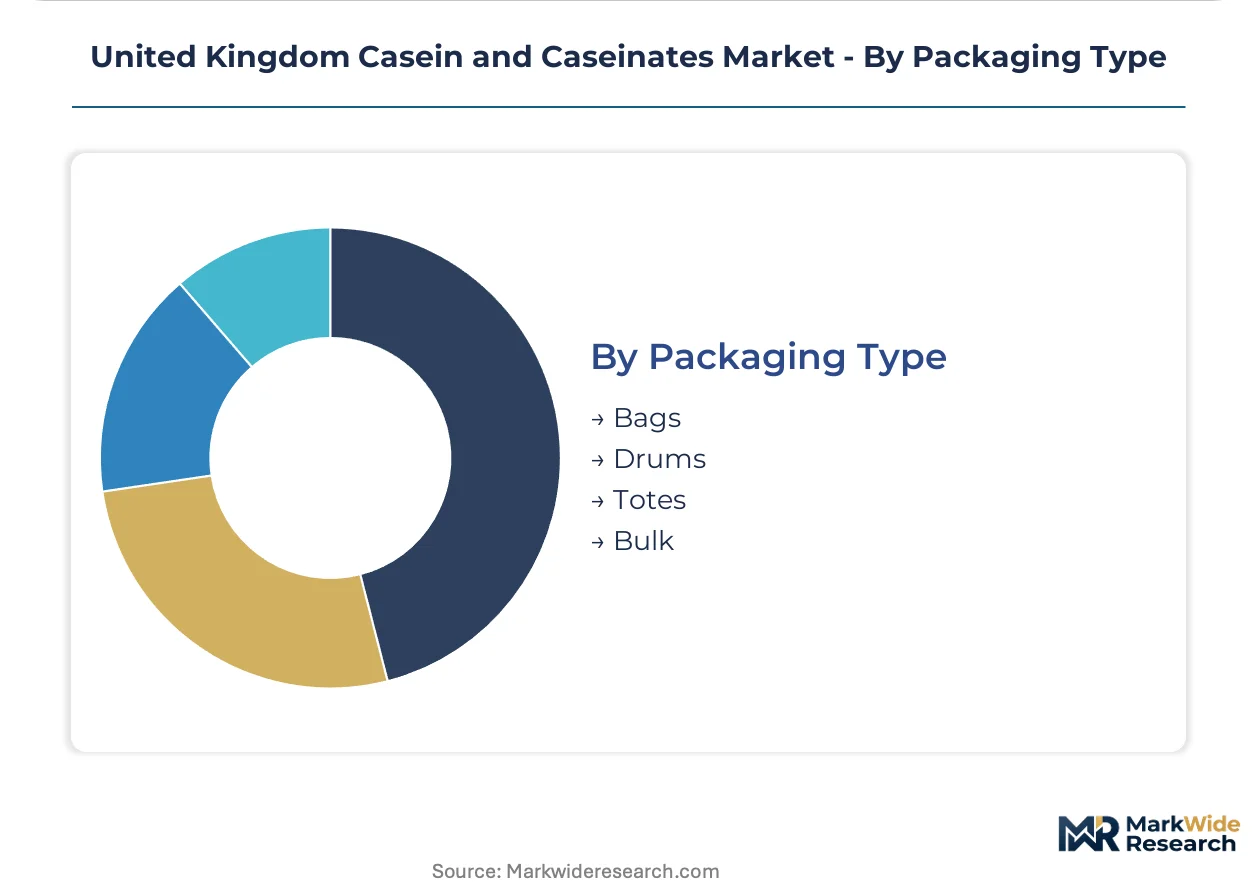
Packaging Type:
Volume scale and handling automation requirements differentiate procurement patterns across the Midlands processing corridor's centralized technical purchasing functions.
- Bulk:Tanker and silo delivery systems serve the largest food processors, minimizing handling costs and enabling continuous production integration.
- Totes:Intermediate bulk containers balance flexibility with efficiency for mid-scale nutraceutical contract manufacturers lacking dedicated powder handling infrastructure.
- Drums:Steel and fiber drums dominate pharmaceutical-grade material distribution, supporting batch segregation and cleanroom transfer protocols.
- Bags:Multi-wall paper and polyethylene bags retain position in artisanal and specialty food applications with lower throughput requirements.
Bulk leads industrial procurement. Totes are climbing fastest among mid-scale nutraceutical operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom casein and caseinates industry traces its commercial scale to the cooperative dairy movements of the early twentieth century, when centralized milk collection enabled acid casein precipitation at industrial volume. Today's regional configuration reflects this heritage, with production and demand clustering around historic dairy processing centers that have evolved into specialized protein ingredient hubs.
Midlands
England's central food manufacturing belt generates the densest caseinate procurement activity, driven by ready-meal manufacturers and meat processors seeking emulsification reliability. The Food Standards Agency enforces retained EU compositional standards across this corridor, sustaining cross-border trade confidence for dairy-derived ingredients. Leicester and Nottingham anchor the region's technical purchasing functions, where processors pilot bundled protein-emulsifier systems.
Scotland
Prepared foods manufacturers in Scotland's central belt are consolidating supplier relationships around single-source accountability for protein-stabilizer combinations. The country's national food safety regulator maintains alignment with UK-wide dairy labeling requirements while adapting to devolved agricultural policy frameworks. Glasgow and Edinburgh food processing zones show fastest adoption of modular ingredient bundling contracts among UK regions.
North England
Yorkshire's dairy processing heritage supports specialized casein production for cheese manufacturing and industrial adhesive applications. Regional agricultural support programs under the Department for Environment, Food and Rural Affairs shape milk supply stability for local processors. Leeds and Bradford retain legacy acid casein facilities serving mature demand segments with limited growth trajectory.
Wales
Dairy cooperative infrastructure in rural Wales supplies raw material to caseinate processors serving nutraceutical and pharmaceutical-grade markets. The Welsh Government's food and drink strategy emphasizes premium ingredient traceability standards that align with Medicines and Healthcare products Regulatory Agency excipient guidelines. Carmarthenshire and Pembrokeshire dairy clusters feed specialized slow-release protein formulations for sports nutrition applications.
United Kingdom Casein and Caseinates Market Competitive Landscape
The competitive structure tilts toward cooperative dairy processors with captive milk supply and multinational ingredient specialists with technical service depth. Three strategic archetypes dominate: vertically integrated cooperatives controlling upstream raw material, European processors leveraging cross-border production networks, and specialized excipient suppliers focusing on pharmaceutical-grade consistency. Capacity rationalization and membrane filtration technology licensing represent the primary competitive moves reshaping supplier positioning.
Within the cooperative processor tier, Arla Foods amba and Royal FrieslandCampina N.V. occupy positions defined by backward integration into member milk supply. Fonterra Co-operative Group Limited represents the technical service archetype, anchoring pharmaceutical-grade material differentiation through specialized customer support. Among European specialists, MEGGLE GmbH & Co.KG and Lactoprot Deutschland GmbH exemplify the cross-border production model, sourcing regional milk supply while serving UK formulation requirements.
| Leading Market Players |
|---|
| Arla Foods amba |
| Royal FrieslandCampina N.V. |
| Fonterra Co-operative Group Limited |
| MEGGLE GmbH & Co.KG |
| Agrial Group |
| Lactoprot Deutschland GmbH |
| LAITA |
| Erie Foods International, Inc. |
| Prinova Group LLC |
| Others |
Value Network & Pricing Analysis
Formulation chemist scarcity in England's Midlands widens spreads between pharmaceutical-grade premiums and commodity food-grade pricing, as labor-cost differentials compound certification overhead for excipient-qualified material.
Pricing Analysis
Three-tier pricing structure across pharmaceutical, food-grade, and industrial levels separates UK caseinate procurement by certification burden and traceability depth. Pharmaceutical-grade material commands substantial premiums due to Medicines and Healthcare products Regulatory Agency excipient compliance and batch-level documentation. Cost compression in food-grade tiers is intensifying because milk supply volatility and feed cost inflation compress processor margins. Contract nutraceutical manufacturers show highest price sensitivity due to fragmented volumes and lack of cooperative backward integration, while parenteral nutrition formulators remain least sensitive given patient-safety imperatives.
Supply Chain Analysis
Single-source vulnerability sits with Dutch and New Zealand processing networks that supply sodium caseinate consistency to UK coffee whitener manufacturers. Raw material flows draw from cooperative dairy herds across Denmark, the Netherlands, and New Zealand, with protein fractionation equipment sourced from German and Italian specialists. Tariff exposure on post-Brexit dairy trade is forcing parallel compliance documentation for cross-border shipments. Distribution runs through Midlands tanker networks for bulk industrial users and specialized drum logistics for pharmaceutical-grade material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom casein and caseinates market functions as a geographic-arbitrage play, with pharmaceutical-grade certification costs substantially lower than equivalent US FDA compliance burdens while maintaining EU-aligned quality standards.
For Market Incumbents: Deepen membrane filtration technology licensing to defend against plant protein substitution in meat analogue applications. Arla Foods amba and Royal FrieslandCampina N.V. should expand technical service teams for pharmaceutical-grade qualification, as Fonterra Co-operative Group Limited's specialized support model captures excipient market share. Cooperative processors must invest in farm-level traceability systems before the Food Standards Agency tightens dairy labeling requirements further.
For New Entrants and Emerging Players: Enter via liquid caseinate concentrate production for ready-to-drink beverage innovators, where equipment retrofit costs deter legacy powder processors. Scotland's prepared foods sector offers the most penetrable geography, with centralized technical purchasing functions seeking single-source protein-emulsifier accountability. Partner with Midlands contract manufacturers lacking in-house formulation expertise to bypass direct cooperative competition.
For Investors and Strategic Acquirers: Nutraceutical contract manufacturers are the most active acquirer in this space, seeking backward integration to escape traceability compliance burdens. Long-term viability hinges on membrane filtration automation and pharmaceutical-grade certification depth. Watch for divergence between UK and EU food safety regulations as the critical inflection signal, as parallel compliance systems would substantially raise exporter operating costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Technology Licensing | Arla Foods amba and FrieslandCampina deploy automated micelle separation to compress batch-to-batch protein deviation below 2%. |
| Pharmaceutical-Grade Excipient Certification | Medicines and Healthcare products Regulatory Agency compliance opens parenteral nutrition formulation access with premium pricing power. |
| Liquid Concentrate Production Capacity | Beverage manufacturers pilot ready-to-drink systems that eliminate powder reconstitution steps in high-volume lines. |
| Farm-Level Traceability System Investment | Food Standards Agency dairy labeling requirements force processor documentation back to milk source batches. |
| Technical Service Team Expansion | Fonterra Co-operative Group Limited's specialized customer support model differentiates pharmaceutical-grade material consistency. |
Research Methodology
Coverage spans England's Midlands processing corridor, Scotland's central belt prepared foods sector, North England's Yorkshire dairy heritage, and Wales's cooperative infrastructure, with primary inputs from each region. The analysis combines structured interviews with formulation chemists, procurement leads at ready-meal manufacturers, technical directors at nutraceutical contract manufacturers, and regulatory affairs specialists at cooperative processors. Secondary validation draws from Food Standards Agency enforcement data, Medicines and Healthcare products Regulatory Agency excipient guidelines, British Standards Institution certification records, and retained EU food law documentation. Bottom-up volume modeling and top-down value triangulation cross-validate segment outputs.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models product type segmentation by sodium, calcium, and potassium variants; end-use industry splits across food processing, pharmaceuticals, nutraceuticals, and dairy applications; form differentiation between powder and liquid concentrates; and packaging tiering from bulk tanker to pharmaceutical drums. CAGRs derive from installed base erosion analysis, replacement cycle timing, and penetration rate assumptions for liquid concentrate adoption. Forecast inputs incorporate milk supply volatility patterns, feed cost inflation pass-through, and membrane filtration adoption curves.
Inputs from cooperative processor disclosures and regulatory filing databases were available through the study window; gaps in real-time farm-gate pricing and contract manufacturer margin structures introduce uncertainty bands around volume projections. Forecasts reflect assumptions on UK-EU regulatory divergence pace, plant protein substitution elasticity, and pharmaceutical-grade qualification timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Low Fat Cheese Market
Dairy Products
Milk Protein Concentrate Market
Dairy Products
Mascarpone Cheese Market
Dairy Products
Skimmed Milk Market
Dairy Products
North America Whole Milk Powder Market
Dairy Products
United States Casein Market
Dairy Products
Hydrolyzed Casein Market
Dairy Products
GCC Camel Dairy Market
Dairy Products
Condensed Milk Market
Dairy Products
Plain Yogurt Market
Dairy Products
A2 Milk Market
Dairy Products
Europe Chocolate Milk Market
Dairy Products
Dairy Blends Market
Dairy Products
Global Butter Market
Dairy Products
Global Dairy Market
Dairy Products
Table Butter Market