
 Asia-Pacific Milk Protein Market | 2026-2036
Asia-Pacific Milk Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Milk Protein Market Outlook
Modular protein blends with whey-casein ratios is rebalancing buyer choice across sports nutrition and infant formula segments. Fonterra Co-operative Group Limited anchors its position through backward integration into New Zealand dairy farming. Glanbia PLC differentiates via specialized whey protein isolate production for performance nutrition. Kerry Group PLC extends its reach through flavor-protein co-development services for Asia-Pacific food manufacturers.
Asia-Pacific milk protein encompasses whey protein, casein protein, milk protein concentrate, and milk protein isolate extracted through membrane filtration, ion exchange, or microfiltration processes, yielding protein concentrations from 35% to 90% by dry weight for functional food fortification. Casein protein dominates margin pools in cheese manufacturing applications where slow-digesting properties command formulation premiums. Whey protein leads volume growth in sports nutrition and dietary supplements driven by gym culture expansion across Southeast Asian metros. Milk protein concentrate occupies a mature position in bakery and dairy products where cost-efficient protein standardization sustains steady demand.
China's SAMR enforces GB standards on dairy protein labeling and import safety testing, while India's FSSAI mandates compositional thresholds for protein claims in packaged foods, collectively elevating compliance costs for cross-border suppliers. Japan's PMDA and METI coordinate on novel food ingredient approvals affecting whey protein hydrolysate introductions. Stakeholders must track evolving protein-content verification protocols and certification harmonization across national regulators to secure uninterrupted market access.
Market Dynamics
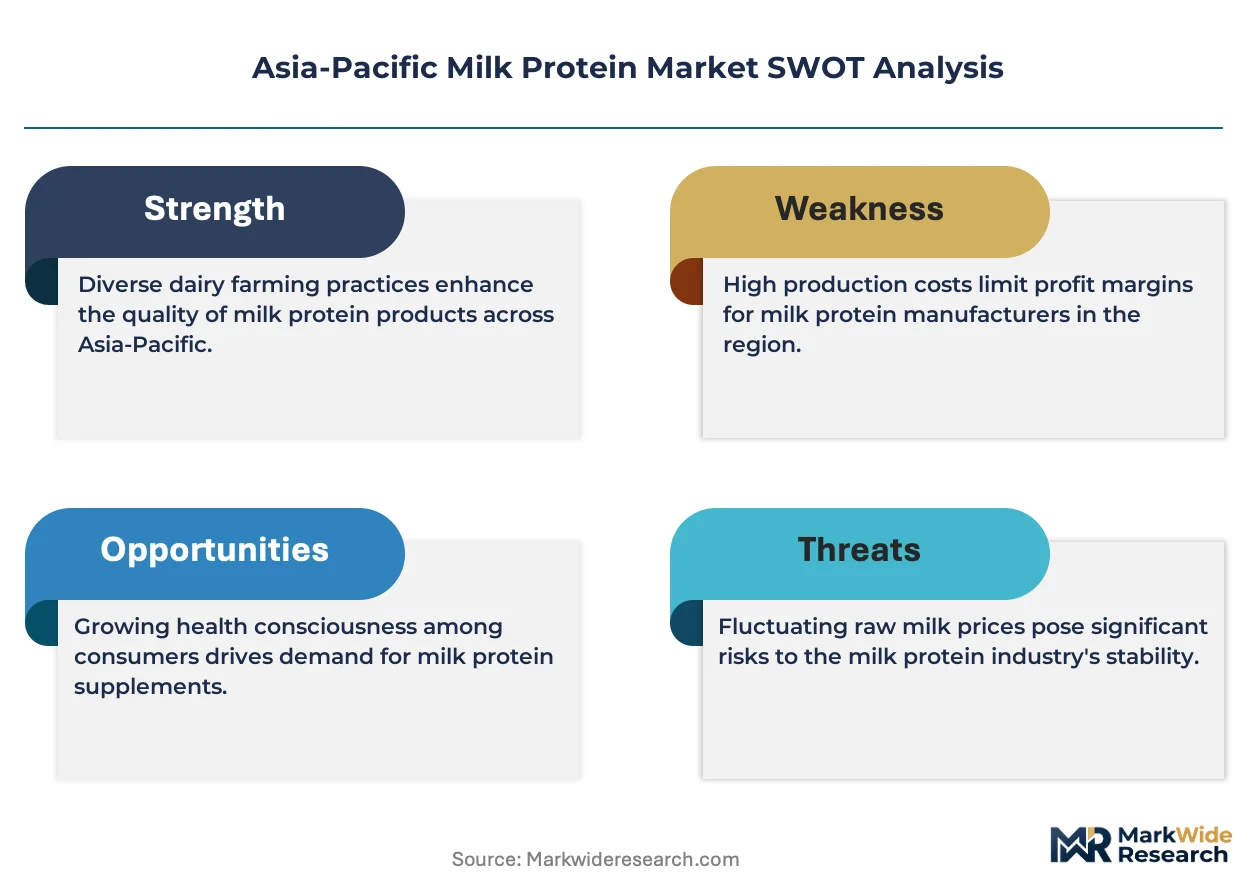
China's GB standards tightening on dairy protein purity is forcing reformulation investments across imported whey and casein supply chains, compressing margins for non-compliant suppliers while accelerating domestic membrane filtration capacity buildouts.
Growth Catalysts
- Sports Nutrition Expansion:Gym culture proliferation across Jakarta, Bangkok, and Ho Chi Minh City drives whey protein isolate demand in ready-to-drink formats and powder sachets.
- FSSAI Protein Threshold Mandates:India's packaged food labeling rules now require minimum protein content disclosures, pushing bakery and dairy manufacturers toward standardized milk protein concentrates.
- Membrane Filtration Scale-Up:New Zealand and Australian processors are deploying ceramic microfiltration systems that yield 90%+ protein isolates with superior functional properties for infant formula fortification.
Market Restraints
- Feed Cost Volatility:New Zealand dairy farm input costs fluctuate with global grain and palm kernel expeller prices, transmitting margin pressure downstream to protein concentrate pricing.
- Import Concentration Risk:China's SAMR safety testing protocols create single-point bottlenecks at designated port laboratories, extending clearance timelines for whey protein shipments.
- Plant Protein Substitution:Pea and fava protein isolates from domestic Chinese and Indian extraction facilities compete on cost in mass-market sports nutrition applications.
Strategic Opportunities
- Vietnam Functional Food White Space:Urban middle-class expansion in Hanoi and Da Nang outpaces local protein fortification supply, creating first-mover openings for whey-casein blend suppliers.
- Clean Label Positioning:Japan's METI guidelines on processed food transparency reward minimal-ingredient protein claims, favoring single-source milk protein isolates over compound blends.
- Direct-to-Consumer Channels:Southeast Asian e-commerce platforms now host dedicated sports nutrition verticals, bypassing traditional pharmacy and gym retail gatekeepers for isolate and hydrolysate sales.
Industry Challenges
- Cross-Border Certification Timelines:Japan's PMDA novel food ingredient approvals for whey protein hydrolysates extend 18-24 months, delaying product launches versus domestic Japanese dairy processors.
- Legacy Dairy Integration:Southeast Asian food manufacturers operate aged spray-drying and blending equipment that requires retrofitting to handle high-concentration protein isolates without denaturation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Milk Protein Market |
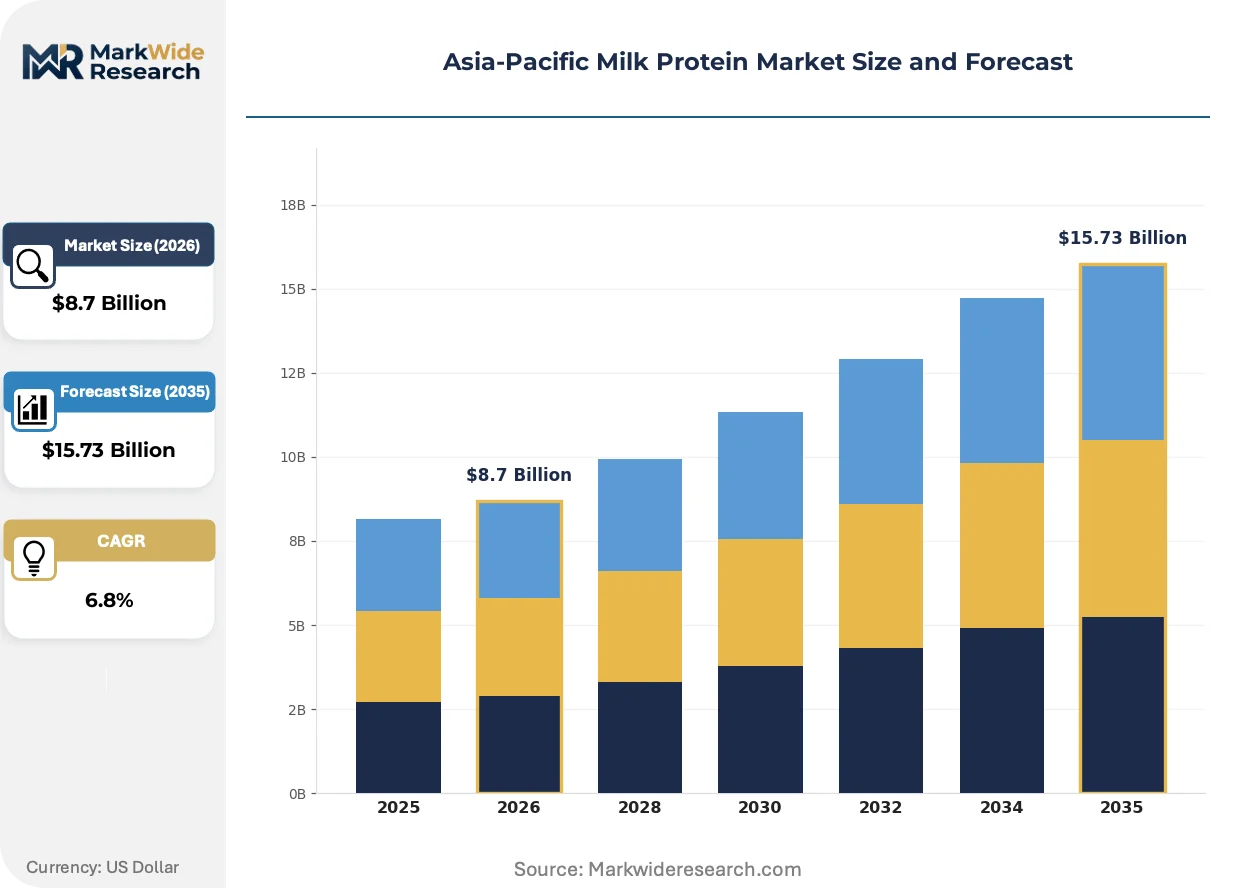
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Milk Protein Concentrate, Milk Protein Isolate Application: Dairy Products, Nutritional Supplements, Infant Formula, Bakery Products End User: Food & Beverage Industry, Healthcare, Sports Nutrition, Dietary Supplements Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Glanbia PLC, Lactalis Ingredients, Fonterra Co-operative Group Limited, Carbery Group Ltd., Saputo Inc., Arla Foods amba, Kerry Group PLC, Nestlé S.A., Koninklijke FrieslandCampina N.V., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Milk Protein Market Strategic Shifts
Membrane technology advances and regulatory transparency mandates are compressing traditional supply chain tiers while enabling precision protein customization for specific end-use functional requirements across Asia-Pacific food manufacturing.
Ultrafiltration-diafiltration cascades with ceramic membranes are unifying protein fractionation and concentration steps previously handled by separate ion exchange columns. Australian and New Zealand dairy processors now deploy these integrated systems to produce native whey protein with preserved bioactivity for infant nutrition. The technology is unifying quality tiers that previously separated commodity concentrates from premium isolates, enabling mid-tier suppliers to access performance nutrition contracts.
China's SAMR enforcement of GB 28050 nutritional labeling standards now mandates third-party verification of protein content claims on imported dairy ingredients. The regulation forces foreign suppliers to pre-certify batches through designated Chinese laboratories before shipment, adding documentation overhead but reducing post-entry rejection risk. Japanese and South Korean ingredient exporters have adapted fastest, leveraging existing bilateral mutual recognition agreements to streamline compliance.
Functional food manufacturers in India and Southeast Asia now specify protein content by application performance rather than dry-weight percentage alone, shifting procurement criteria toward solubility, emulsification capacity, and heat stability metrics. This specification evolution displaces commodity trading of undifferentiated concentrates in favor of co-development partnerships with processors capable of custom fractionation. The pattern is most visible in Mumbai and Bangalore, where bakery and beverage formulators now embed supplier technical service teams in pilot plant trials.
Asia-Pacific Milk Protein Market Segmentation
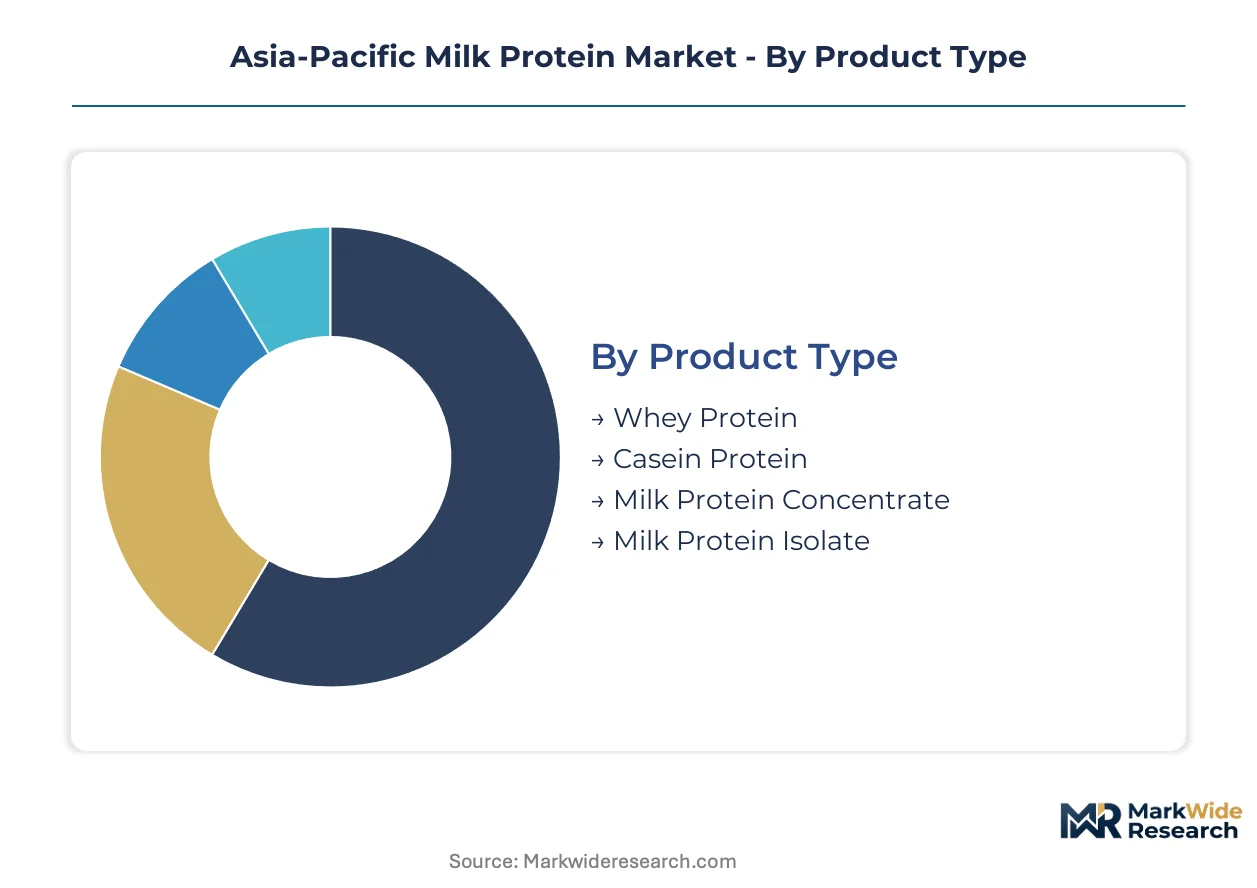
Protein fractionation technologies enable precise customization across Asia-Pacific food manufacturing, with membrane filtration advances allowing processors to tailor functional properties for specific end-use requirements rather than selling undifferentiated commodity grades.
Product Type:
Customization spans from standardized concentrates to precision isolates, with protein concentration levels and functional profiles determining application fit across infant nutrition, sports performance, and clinical dietetics.
- Whey Protein:Rapid-absorption protein fractions (concentrates at 35-80% protein, isolates at 90%+) extracted via ultrafiltration and ion exchange. Demand concentrates in Vietnam and Indonesia where gym culture expansion drives ready-to-drink and powder sachet consumption, though plant protein cost competition constrains mass-market penetration.
- Casein Protein:Slow-digesting micellar structures prized for sustained amino acid release in overnight recovery formulations and medical nutrition. New Zealand processors dominate supply through captive dairy farming operations, with Japanese and South Korean buyers commanding premium pricing for cheese manufacturing and specialized clinical applications.
- Milk Protein Concentrate:Cost-efficient 40-85% protein blends standardizing dairy solids in processed foods and UHT beverages. India's FSSAI protein disclosure mandates are accelerating adoption in packaged bakery and dairy categories.
- Milk Protein Isolate:90%+ protein purity achieved through microfiltration-diafiltration cascades, delivering superior solubility and heat stability for infant formula fortification. Australian ceramic membrane deployments are expanding commercial availability beyond traditional premium tiers.
Most installed capacity flows through Whey Protein. Expansion is steepest in Milk Protein Isolate.
Application:
Cost tiers separate commodity protein standardization from premium functional fortification, with regulatory thresholds and performance specifications determining procurement patterns across food manufacturing segments.
- Dairy Products:Protein standardization in yogurt, cheese, and UHT milk using concentrates for solids-not-fat adjustment. China's GB dairy standards enforcement is tightening compositional requirements for imported ingredients.
- Nutritional Supplements:High-purity isolates and hydrolysates targeting clinical nutrition, weight management, and geriatric protein supplementation. Japan's PMDA novel food approvals create 18-24 month entry barriers for foreign hydrolysate suppliers.
- Infant Formula:Whey-dominant protein ratios mimicking human milk composition, requiring 90%+ isolate purity with preserved bioactivity. New Zealand and Australian processors leverage integrated membrane systems to meet Chinese SAMR import safety protocols.
- Bakery Products:Emulsification and water-binding functional proteins improving texture and shelf-life in bread and pastry applications. Mumbai and Bangalore formulators now embed supplier technical teams in pilot plant trials for performance-based procurement.
Volume concentrates in Dairy Products. Margin expansion is strongest in Infant Formula.
End User:
Customer sophistication varies from commodity bulk buyers to co-development partners demanding application-specific functional validation and embedded technical service capabilities.
- Food & Beverage Industry:Large-scale manufacturers standardizing protein content across dairy, bakery, and beverage portfolios. Procurement is shifting from spot trading to long-term supply agreements with processors capable of custom fractionation.
- Healthcare:Clinical nutrition formulators requiring documented bioavailability and allergen control for tube feeding and recovery protocols. Japan's METI processed food transparency guidelines favor single-source isolates over compound blends.
- Sports Nutrition:Performance-focused brands in Jakarta, Bangkok, and Ho Chi Minh City driving isolate and hydrolysate demand through e-commerce verticals bypassing traditional retail gatekeepers.
- Dietary Supplements:Capsule and tablet manufacturers sourcing spray-dried concentrates for multivitamin and mineral complexes, competing directly with plant protein alternatives on cost in price-sensitive segments.
Transaction volume flows through Food & Beverage Industry. Technical service intensity is highest in Healthcare.
Distribution Channel:
Channel selection reflects buyer urgency, order scale, and technical support requirements, with digital platforms disrupting traditional pharmacy and gym retail dominance in sports nutrition.
- Online Retail:Dedicated sports nutrition verticals on Southeast Asian e-commerce platforms enabling direct isolate and hydrolysate sales to consumers, with subscription models capturing recurring revenue.
- Supermarkets:Mass-market whey concentrates and fortified dairy products reaching urban middle-class consumers through modern trade expansion in Hanoi and Da Nang.
- Specialty Stores:Pharmacy and fitness retail channels providing technical consultation for clinical nutrition and performance protein selection, though losing share to digital alternatives.
- Wholesale:Bulk concentrate and standard-grade whey shipments to food manufacturers and institutional buyers, with China's SAMR designated port laboratory testing creating clearance bottlenecks.
Volume concentrates in Wholesale. Channel expansion is steepest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand's dairy cooperative model established the foundational supply architecture for Asia-Pacific milk protein, with integrated farming-to-processing operations later replicated across Australian and Chinese membrane filtration facilities.
China
Urban consumers in Shanghai and Beijing drive whey protein isolate demand for sports nutrition and infant formula fortification. SAMR enforces GB 28050 nutritional labeling standards requiring third-party verification of protein content claims on imported dairy ingredients. Qingdao and Tianjin host designated port laboratories where clearance timelines for whey shipments create single-point bottlenecks.
Japan
Clinical nutrition formulators in Tokyo and Osaka command premium pricing for micellar casein in medical recovery protocols. METI guidelines on processed food transparency reward minimal-ingredient protein claims, while PMDA novel food approvals for whey protein hydrolysates extend 18-24 months. The Kanto region concentrates demand for single-source isolates over compound blends.
India
FSSAI protein threshold mandates for packaged food labeling accelerate milk protein concentrate adoption in Mumbai and Bangalore bakery operations. Urban middle-class expansion in Delhi-NCR and Hyderabad outpaces local protein fortification supply. Western Maharashtra and Gujarat dairy processors retrofit aged spray-drying equipment to handle high-concentration isolates.
Vietnam
Hanoi and Da Nang urban consumers drive functional food white space opportunities for whey-casein blend suppliers. E-commerce platforms host dedicated sports nutrition verticals bypassing traditional pharmacy retail gatekeepers. Southern Ho Chi Minh City anchors gym culture proliferation demanding ready-to-drink protein formats.
Australia
Ceramic microfiltration deployments in Victorian and New South Wales processing facilities yield 90%+ protein isolates with preserved bioactivity for infant nutrition. Export-oriented suppliers leverage bilateral mutual recognition agreements to streamline Chinese SAMR compliance. Sydney and Melbourne technical service teams embed with Asia-Pacific food manufacturers for co-development partnerships.
Asia-Pacific Milk Protein Market Competitive Environment
Premium-margin players sit above commodity-margin players across protein purity tiers, with 90%+ isolate specialists commanding formulation premiums while 35-50% concentrate suppliers compete on volume. The vendor base organizes around backward-integrated dairy cooperatives, specialized fractionation technology owners, and flavor-protein co-development service providers. Three archetypes dominate: captive farming-to-processing operators, membrane technology specialists, and application technical service integrators. Capacity expansion and strategic partnerships represent the dominant competitive moves, with ceramic filtration system deployment and e-commerce channel development as secondary vectors.
Within the backward-integrated cooperative tier, Fonterra Co-operative Group Limited and Glanbia PLC exemplify contrasting geographic anchoring strategies, with the former representing New Zealand farming-to-processing integration and the latter occupying Irish-European specialized whey protein isolate production. Kerry Group PLC sits within the technical service archetype, offering flavor-protein co-development capabilities that extend reach across Asia-Pacific food manufacturing. These three entities collectively span the value chain from upstream dairy farming through downstream formulation partnership, illustrating the tiered competitive structure without exhaustively mapping all participants.
| Leading Market Players |
|---|
| Glanbia PLC |
| Lactalis Ingredients |
| Fonterra Co-operative Group Limited |
| Carbery Group Ltd. |
| Saputo Inc. |
| Arla Foods amba |
| Kerry Group PLC |
| Nestlé S.A. |
| Koninklijke FrieslandCampina N.V. |
| Others |
Value Chain & Pricing Dynamics
Global dairy commodity indices, particularly Fonterra's Global Dairy Trade auction results, cascade through Asia-Pacific milk protein supply chains into distinct pricing tiers that separate membrane filtration specialists from commodity concentrate traders. New Zealand farmgate milk prices transmit directly into whey isolate premiums, while Chinese SAMR certification costs create additional margin layers for import-dependent buyers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ceramic membrane isolates from ultrafiltration concentrates and commodity-grade blends. Price differentiation rests on protein purity certification and bioactivity preservation metrics, with 90%+ isolates commanding formulation premiums in infant nutrition. Pricing pressure stems from plant protein substitution in mass-market sports nutrition, compressing whey concentrate margins. Food and beverage manufacturers exhibit highest price sensitivity through spot-market procurement, while clinical nutrition formulators accept premium positioning for documented bioavailability.
Supply Chain Analysis
Certification gating through China's SAMR designated port laboratories and Japan's PMDA novel food approvals constrains supplier participation and fragments downstream availability. Supply concentrates in New Zealand, Australia, and Ireland through backward-integrated dairy cooperatives and specialized fractionation facilities. Raw material flows depend on pasture-based milk production seasons and ceramic membrane filtration capacity deployment. Single-source vulnerability runs through China's Qingdao and Tianjin port laboratory bottlenecks for import clearance. Distribution runs through wholesale bulk shipments to food manufacturers, with e-commerce verticals gaining share in sports nutrition isolates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific milk protein offers margin expansion through ceramic membrane technology scale-up and premium isolate tier growth, with cost-down drivers from unified ultrafiltration-diafiltration cascades displacing legacy ion exchange systems.
For Market Incumbents: Extend technical service embedding into Mumbai and Bangalore pilot plant trials to lock in co-development partnerships before membrane technology commoditization accelerates. Defend against Australian ceramic membrane entrants by securing long-term supply agreements with Vietnamese and Indonesian sports nutrition brands. Prioritize FSSAI pre-certification investments to capture India's protein disclosure mandate acceleration. For New Entrants and Emerging Players: Ceramic microfiltration system deployment offers entry into Vietnam's functional food white space where local protein fortification supply lags urban middle-class expansion. Target Hanoi and Da Nang through direct-to-consumer e-commerce verticals bypassing pharmacy retail gatekeepers. Pursue METI-aligned clean label positioning in Japan's Kanto region where minimal-ingredient claims reward single-source isolates. For Investors and Strategic Acquirers: Asymmetric upside sits with membrane technology specialists possessing bilateral mutual recognition agreements for Chinese SAMR compliance streamlining. Five-to-ten year viability favors processors integrating farming through fractionation with preserved bioactivity capabilities. Watch for PMDA approval timeline compression as signal of competitive access normalization in Japanese clinical nutrition.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Membrane Capacity Expansion | Australian and New Zealand processors deploy unified systems yielding 90%+ isolates for infant formula. |
| Backward Integration into Dairy Farming | New Zealand cooperatives secure captive milk supply through pasture-based production control. |
| Flavor-Protein Co-Development Partnerships | Technical service providers embed teams with Asia-Pacific food manufacturers for application-specific trials. |
| E-Commerce Vertical Development | Southeast Asian platforms host dedicated sports nutrition channels bypassing traditional retail gatekeepers. |
| Regulatory Pre-Certification Investment | Foreign suppliers pre-verify batches through designated Chinese laboratories to reduce post-entry rejection risk. |
Study Parameters
Bottom-up application modeling reconciled against top-down dairy processing capacity tracking forms the analytical core of this study. Primary interviews with membrane filtration technology directors, F&B procurement leads at Mumbai and Bangalore formulators, sports nutrition brand managers in Jakarta and Ho Chi Minh City, and regulatory affairs specialists navigating SAMR and PMDA protocols combined with secondary validation from Fonterra Global Dairy Trade auction data, Chinese customs import records, FSSAI packaged food labeling filings, and Japanese METI processed food transparency guidelines.
Historical trendline analysis of protein fractionation technology deployment and dairy ingredient trade flows established baseline growth patterns across the projection horizon. Segmentation modeling captured product type tiers, application performance requirements, end-user technical service intensity, and distribution channel evolution. CAGRs derived from installed capacity expansion timelines and regulatory approval velocity. Forecast inputs included ceramic membrane adoption curves and plant protein substitution elasticities in mass-market sports nutrition.
The model holds under stable New Zealand farmgate milk pricing and sustained Chinese import demand; deviation in feed cost volatility or SAMR enforcement intensity would shift the outlook materially. Forecasts reflect documented assumptions regarding membrane technology diffusion and bilateral mutual recognition agreement expansion. Deviation in PMDA novel food approval timelines or FSSAI threshold mandate implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Organic Dairy Market
Dairy Products
Skimmed Milk Market
Dairy Products
North America Whole Milk Powder Market
Dairy Products
Lactose Free Butter Market
Dairy Products
Yogurt Drink Market
Dairy Products
Lactose and Derivative Market
Dairy Products
Natural Cheese Market
Dairy Products
Disposable Curd Cups Market
Dairy Products
United States Casein Market
Dairy Products
GCC Camel Dairy Market
Dairy Products
Reconstituted Milk Market
Dairy Products
Global Yogurt Market
Dairy Products
United Kingdom Whey Protein Market
Dairy Products
Cheese Concentrate Market
Dairy Products
North America Fluid Milk Market
Dairy Products
Ghee Market