
 Condensed Milk Market | 2026-2036
Condensed Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Condensed Milk Market Analysis
The gap between artisan-grade condensed milk and mass-market commodity supply is expanding as ingredient provenance and fat-content specifications diverge sharply. Nestlé S.A. leverages its century-long dairy sourcing networks to sustain premium positioning across Latin American retail channels. Hochwald Foods GmbH anchors European private-label supply through backward integration into German dairy cooperative systems. Arla Foods Amba competes on organic-certified condensed milk lines that command shelf-space premiums in Scandinavian supermarkets.
Condensed milk is heat-treated cow's milk with approximately sixty percent water removed, yielding a viscous liquid with minimum eight percent milk fat and twenty-eight percent total milk solids; manufacturers apply vacuum evaporation followed by sugar infusion for sweetened variants to inhibit microbial growth and extend ambient shelf stability. Food manufacturers remain the dominant end-user segment, absorbing bulk volumes for confectionery and processed dessert applications where sweetened condensed milk provides standardized viscosity and caramelization control. Specialty stores represent the fastest-growing distribution channel as consumers in urban clusters seek imported or small-batch condensed milk formats for home baking.
FDA standards govern milk solids and fat-content labeling in the United States, while EFSA and EU hygiene directives regulate dairy processing conditions and additive permissions across European member states. BIS certification requirements in India mandate specific microbiological thresholds for imported condensed milk products, creating compliance barriers for new entrants. Stakeholders must monitor evolving sugar-tax legislation and clean-label reformulation pressures that threaten traditional sweetened condensed milk formulations.
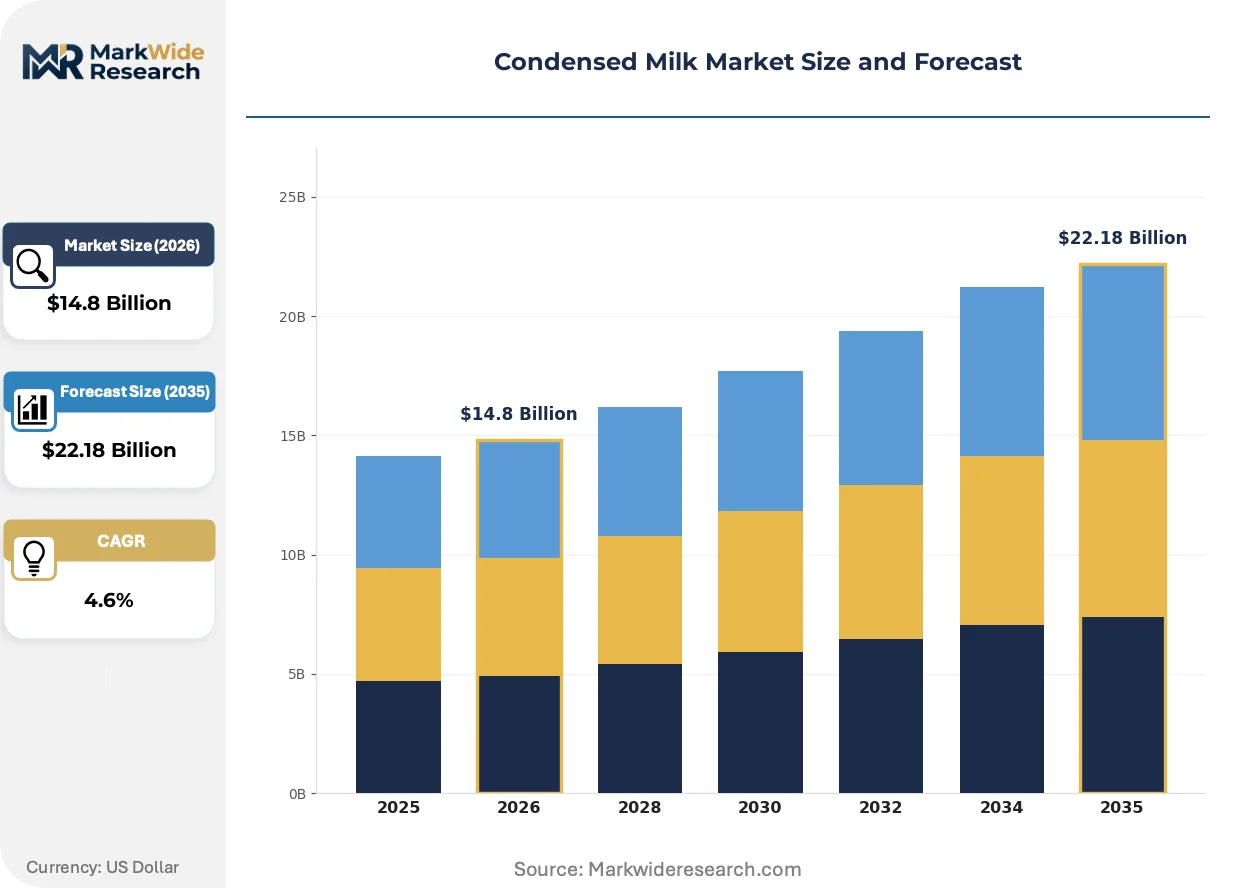
Market Dynamics
The EU F-Gas Regulation is forcing dairy processors to abandon conventional refrigeration-dependent evaporation methods, compressing margins for manufacturers reliant on energy-intensive vacuum concentration systems while accelerating capital redeployment toward alternative thermal processing technologies.
Growth Catalysts
- Sweetened condensed milk:Bakery chains across Southeast Asia are scaling procurement for premium pastry lines, pulling volumes from commodity-grade suppliers toward fat-standardized ingredient formats.
- Vietnam dairy infrastructure:Domestic processing capacity expansion by state-linked cooperatives is reducing import dependency and creating localized supply hubs for regional confectionery manufacturers.
- FDA milk solids standards:Standardized labeling requirements in the United States are enabling cross-border formulation consistency, reducing technical barriers for exporters targeting North American food manufacturers.
Market Restraints
- Raw milk input volatility:Fluctuating farmgate prices in Germany and New Zealand are compressing processor margins, particularly for private-label suppliers without long-term cooperative contracts.
- Cooling technology concentration:Dependence on fluorinated gas refrigeration systems creates compliance exposure under EU F-Gas phase-down schedules, stranding capital in legacy equipment.
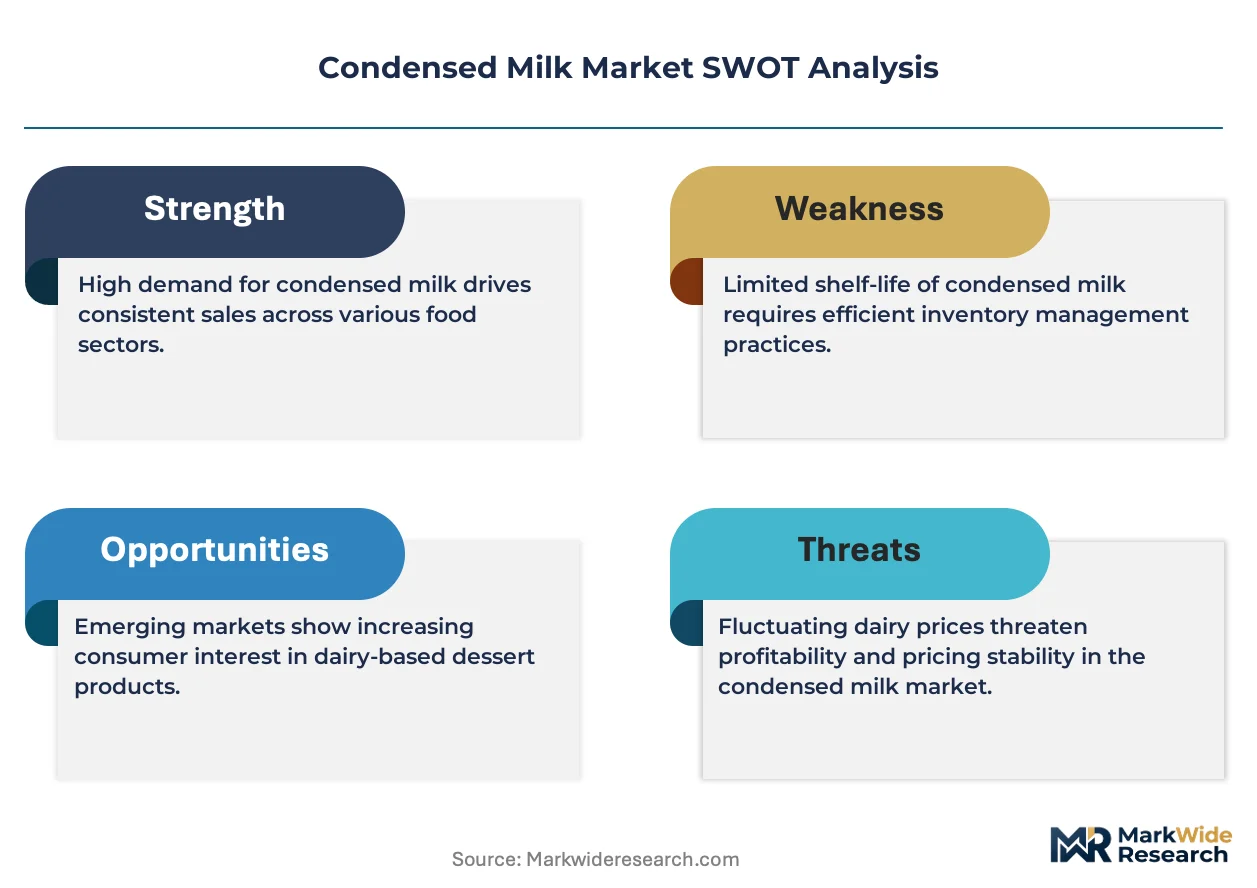
- Plant-based substitution:Oat and coconut cream concentrates are displacing traditional condensed milk in vegan confectionery applications, eroding volume in European specialty channels.
Strategic Opportunities
- Specialty store channel:Urban consumer clusters in São Paulo and Mexico City are driving demand for imported small-batch formats, creating premium positioning opportunities outside mass retail.
- Organic certification tailwind:EFSA-aligned organic dairy processing protocols are enabling shelf-space premiums in Scandinavian supermarkets, rewarding early certifiers with category captain status.
- Clean-label reformulation:Sugar-reduced and additive-free variants align with evolving national sugar-tax frameworks in the United Kingdom and South Africa, opening reformulation-first mover advantages.
Industry Challenges
- Microbiological certification timelines:BIS compliance requirements in India mandate extended testing protocols for imported products, delaying market entry by six to twelve months for new exporters.
- Legacy system integration:Retrofitting vacuum evaporation lines for reduced-energy thermal processing requires substantial capital expenditure and skilled technician availability that remains scarce in emerging dairy regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Condensed Milk Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweetened Condensed Milk, Unsweetened Condensed Milk, Evaporated Milk, Dairy Alternatives Distribution Channel: Supermarkets, Online Retail, Hypermarkets, Specialty Stores End User: Food Manufacturers, Restaurants, Bakeries, Households Packaging Type: Cans, Bottles, Tetra Packs, Pouches |
| Companies Covered | Eagle Family Foods Group, Vinamilk, Nestlé S.A., Santini Foods, Inc., Hochwald Foods GmbH, FrieslandCampina N.V., Arla Foods Amba, Morinaga Milk Industry Co., Ltd., Fonterra Co-operative Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Condensed Milk Market Emerging Trajectories
Membrane filtration and alternative thermal concentration technologies are displacing conventional evaporation methods, while regulatory pressure on refrigeration gases and shifting procurement patterns among industrial buyers are restructuring competitive positioning across ingredient-grade and retail-format supply tiers.
Membrane filtration systems utilizing reverse osmosis and nanofiltration are decentralizing production economics by enabling smaller-scale, lower-energy concentration at regional dairy hubs. Food manufacturers in Brazil and Indonesia are adopting these systems to reduce transport costs from centralized processing facilities. The technology is decentralizing supply chain geography, compressing the historical advantage of large-scale evaporator operators concentrated in Northern Europe.
The EU F-Gas Regulation mandates phased reduction in hydrofluorocarbon use across industrial cooling equipment, directly impacting vacuum evaporation operations. Dairy processors in the Netherlands and Denmark are retrofitting plants with absorption chilling or mechanical vapor recompression to maintain throughput. Sweetened condensed milk production lines with high refrigeration dependency face the steepest compliance costs and longest payback periods on capital replacement.
Industrial buyers are consolidating procurement through direct contracting with cooperative dairy processors, bypassing traditional ingredient distributors. Confectionery manufacturers in Vietnam and Thailand are negotiating fat-content and viscosity specifications directly with Vinamilk and regional suppliers. This pattern concentrates purchasing power among large-scale food manufacturers while fragmenting service requirements for smaller bakery and dessert processors.
Condensed Milk Market Segmentation
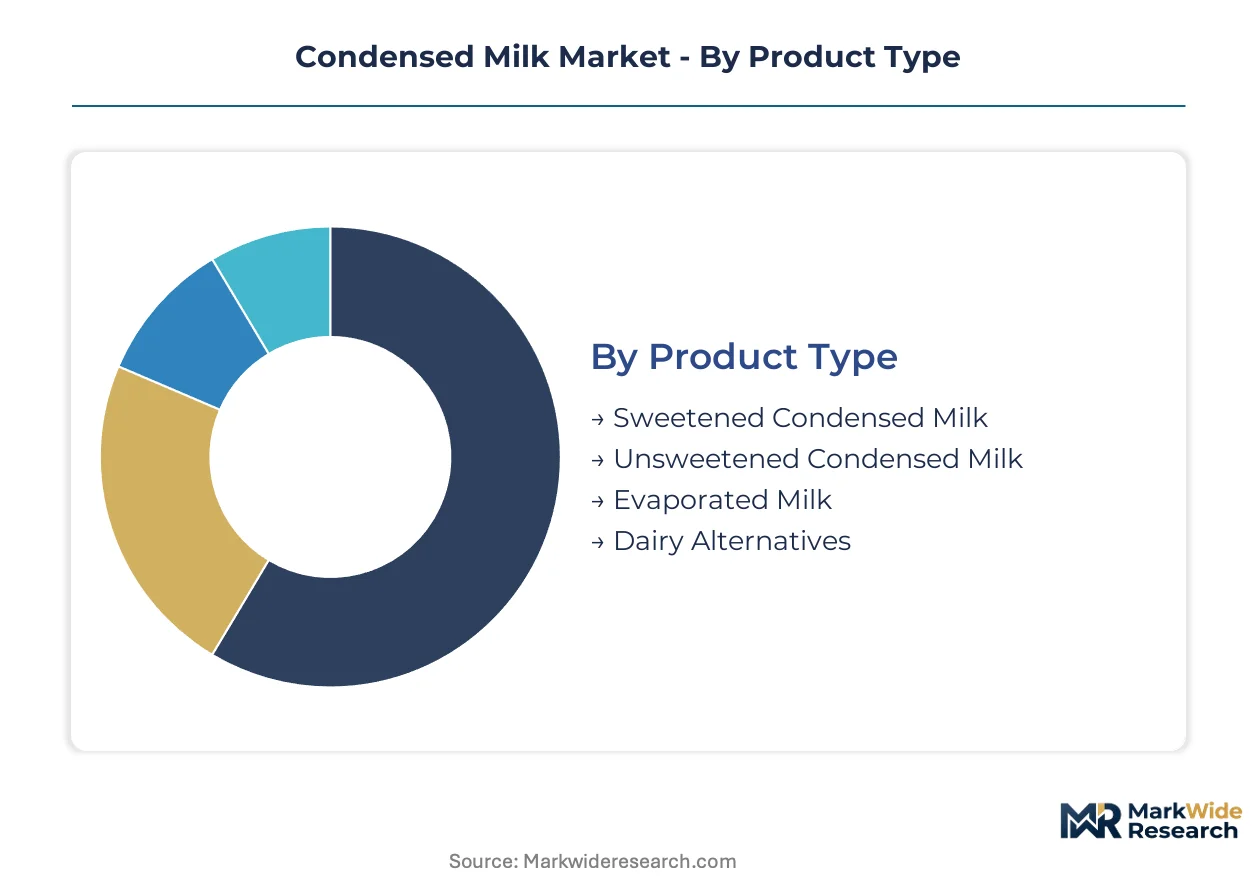
Condensed milk segmentation reveals how formulation standards, channel economics, and end-use specifications create divergent margin structures across supply tiers. Manufacturers configure production lines around viscosity requirements and shelf-stability demands that vary sharply by buyer category.
Product Type:
Product selection tracks directly to thermal processing intensity and sugar-infusion protocols, with equipment upgrade cycles driving format transitions as energy regulations tighten.
- Sweetened Condensed Milk:Heat-treated milk with approximately forty-five percent added sucrose creates osmotic pressure that inhibits microbial proliferation without refrigeration. Bakery chains across Vietnam and Thailand are pulling volumes toward fat-standardized formats for caramelization control in premium pastry applications.
- Unsweetened Condensed Milk:Vacuum-evaporated milk retaining natural lactose requires sterile packaging and rapid chill-chain distribution. Industrial procurement concentrates in German and Dutch dairy cooperatives supplying ingredient distributors to confectionery manufacturers.
- Evaporated Milk:Sterilized concentrated milk with minimum 7.5% milk fat serves reconstitution applications in institutional foodservice.
- Dairy Alternatives:Oat and coconut cream concentrates displace traditional formulations in vegan-certified confectionery channels across Scandinavian markets.
Sweetened condensed milk sits at the top of the volume ranking, with dairy alternatives climbing the fastest as plant-based certification expands in European retail.
Distribution Channel:
Channel economics separate bulk ingredient flows from premium-format retail, with margin capture shifting toward direct manufacturer relationships in industrial segments.
- Supermarkets:Mass retail shelf space prioritizes standardized viscosity and extended ambient stability for household baking applications. Private-label suppliers compete through cooperative sourcing contracts in German and French retail networks.
- Online Retail:E-commerce penetration enables direct-to-baker procurement of imported small-batch formats bypassing traditional distributor markups. Urban consumer clusters in São Paulo and Mexico City drive premium positioning for specialty condensed milk variants.
- Hypermarkets:Volume-oriented formats emphasize economy-tier pricing for institutional buyers and foodservice distributors.
- Specialty Stores:Curated imported selections command shelf-space premiums through provenance certification and artisan-grade fat-content specifications.
Supermarkets retain the highest absolute volume throughput, though specialty stores are gaining share fastest as urban baking culture intensifies.
End User:
End-use concentration determines formulation precision requirements, with industrial buyers consolidating procurement through direct cooperative contracts.
- Food Manufacturers:Confectionery and processed dessert producers absorb bulk volumes where standardized viscosity enables caramelization control at scale. Vinamilk and regional Vietnamese suppliers are negotiating direct fat-content specifications with chocolate manufacturers.
- Restaurants:Foodservice operators prioritize ambient-stable formats with rapid reconstitution properties for dessert sauce applications.
- Bakeries:Artisan and chain bakery procurement is fragmenting between commodity-grade distributors and direct-import specialty channels.
- Households:Retail-format demand concentrates in sweetened variants for home baking and beverage applications.
Food manufacturers dominate procurement volume, while bakeries are expanding most quickly as Southeast Asian pastry chains scale premium ingredient sourcing.
Packaging Type:
Packaging selection balances shelf-stability engineering against logistics economics, with format transitions accelerating as retail channel requirements diverge.
- Cans:Metal packaging provides hermetic sealing and light protection for multi-year ambient shelf life in tropical distribution conditions. Southeast Asian retail channels maintain heavy reliance on tinplate formats for household sweetened condensed milk.
- Tetra Packs:Aseptic carton systems enable lighter-weight distribution and rectangular pallet efficiency for foodservice bulk supply. Brazilian and Indonesian manufacturers are adopting these formats to reduce transport costs from regional dairy hubs.
- Bottles:Glass and plastic formats serve reconstitution-ready evaporated milk applications in institutional channels.
- Pouches:Flexible packaging reduces material cost for single-serve and sample formats in emerging market penetration strategies.
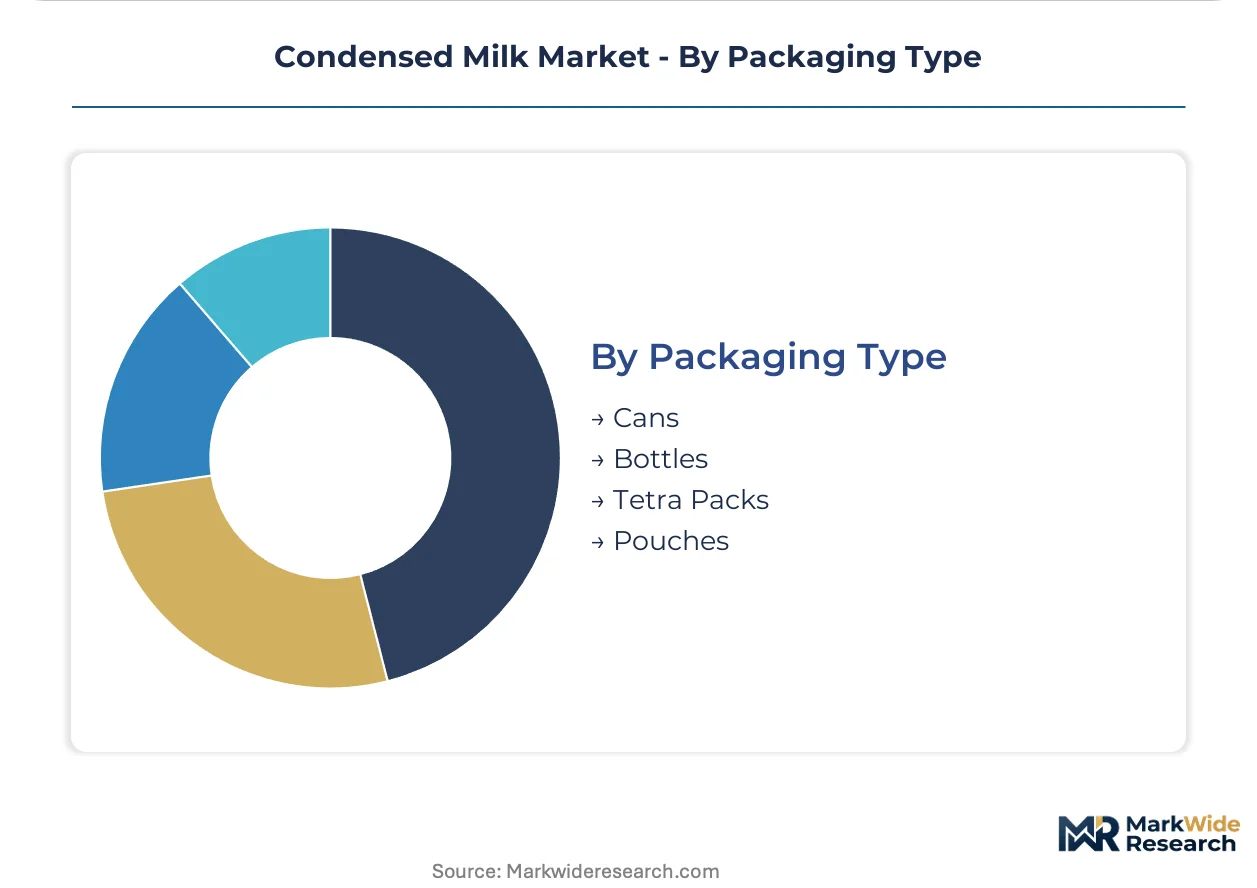
Cans maintain volume leadership across tropical markets, with Tetra Packs posting the steepest expansion trajectory as membrane filtration enables decentralized regional production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy processing expertise concentrates in Northern European cooperative systems and Southeast Asian state-linked enterprises, with regulatory divergence on cooling technologies and sugar-content standards fragmenting cross-border formulation consistency.
Germany
Private-label procurement from Hochwald Foods GmbH and cooperative dairy networks supplies European confectionery manufacturers with fat-standardized unsweetened formats. The EU F-Gas Regulation mandates phased hydrofluorocarbon reduction, forcing retrofitting of vacuum evaporation plants in Lower Saxony. The Münsterland dairy cluster anchors backward integration into milk powder and condensed milk processing for industrial ingredient distributors.
United States
FDA milk solids labeling standards enable cross-border formulation consistency for exporters targeting North American food manufacturers. The agency's dairy product standards of identity govern minimum fat content and additive permissions for sweetened and evaporated milk categories. Wisconsin and California dairy cooperatives concentrate evaporated milk production for institutional foodservice reconstitution applications.
Vietnam
Vinamilk's domestic processing capacity expansion reduces import dependency and creates localized supply hubs for regional chocolate and confectionery manufacturers. The Ministry of Agriculture and Rural Development oversees dairy development schemes that incentivize cold-chain infrastructure investment. The Mekong Delta and Red River Delta clusters concentrate state-linked cooperative milk collection and condensed milk processing for bakery chain procurement.
Brazil
Membrane filtration adoption at regional dairy hubs enables decentralized production economics for food manufacturers seeking transport cost reduction. ANVISA dairy product regulations govern microbiological thresholds and additive permissions for imported condensed milk formats. São Paulo's urban consumer clusters drive specialty store demand for imported small-batch condensed milk variants for home baking applications.
India
BIS certification requirements mandate extended testing protocols for imported condensed milk products, creating compliance barriers for new market entrants. The Food Safety and Standards Authority of India oversees dairy processing hygiene directives and additive permissions. The Anand dairy cooperative cluster in Gujarat and the Karnataka milk federation concentrate domestic sweetened condensed milk production for confectionery and dessert processing applications.
Condensed Milk Market Vendor Landscape
Top-tier vendors anchor premium positioning through century-long dairy sourcing networks and organic certification premiums, while mid-tier private-label suppliers compete on cooperative backward integration and regional scale. The vendor base stratifies across multinational ingredient distributors, national dairy cooperatives, and specialized organic processors. Three archetypes dominate: heritage-brand multinationals leveraging global sourcing infrastructure, cooperative-integrated European suppliers controlling private-label supply, and state-linked Asian processors capturing domestic capacity expansion. Competitive moves concentrate on direct contracting with food manufacturers and retrofitting production lines for reduced-energy thermal processing.
Within the heritage-brand tier, Nestlé S.A. exemplifies sustained premium positioning across Latin American retail channels through established dairy sourcing networks. Arla Foods Amba represents the organic-certified archetype commanding shelf-space premiums in Scandinavian supermarkets. Hochwald Foods GmbH anchors European private-label supply through cooperative integration. Vinamilk occupies a position as the state-linked Asian processor capturing domestic infrastructure expansion in Vietnam.
| Leading Market Players |
|---|
| Eagle Family Foods Group |
| Vinamilk |
| Nestlé S.A. |
| Santini Foods, Inc. |
| Hochwald Foods GmbH |
| FrieslandCampina N.V. |
| Arla Foods Amba |
| Morinaga Milk Industry Co., Ltd. |
| Fonterra Co-operative Group Ltd. |
| Others |
Supply Flow & Price Mechanics
Backward integration into dairy cooperative systems anchors supply security and pricing power for European processors, compressing margins for non-integrated competitors exposed to raw milk spot volatility. This structural divide between captive sourcing and open-market procurement generates tiered margin outcomes across the sweetened condensed milk value chain.
Pricing Analysis
The bundled service split separates ingredient-grade bulk supply with technical specification support from unbundled commodity transactions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with organic-certified lines commanding shelf-space premiums in Scandinavian retail. Cost compression in economy tiers is intensifying because of raw milk input volatility in Germany and New Zealand. Food manufacturers exhibit lowest price sensitivity due to formulation lock-in, while household retail buyers show highest elasticity to branded premium positioning.
Supply Chain Analysis
Return flows and byproduct valorization remain underdeveloped in condensed milk processing, though whey stream recovery offers emerging circularity potential. Raw milk sourcing concentrates in Germany, Vietnam, and New Zealand, with processors drawing from cooperative collection networks and state-linked dairy clusters. Production hinges on vacuum evaporation equipment with fluorinated gas cooling systems facing EU F-Gas phase-down exposure. Distribution runs through direct manufacturer contracts with food manufacturers and ingredient distributors serving confectionery channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation operates as a regulatory compounder, accelerating capital redeployment toward alternative thermal processing and reshaping competitive economics for refrigeration-dependent producers.
For Market Incumbents: To counter stranded asset risk in legacy vacuum evaporation infrastructure, retrofit production lines with mechanical vapor recompression or absorption chilling systems in Netherlands and Denmark plants. Secure long-term cooperative milk supply contracts to anchor input cost predictability against farmgate volatility. For New Entrants and Emerging Players: BIS certification requirements in India opens a window for domestic processors to capture import-replacement demand while foreign entrants navigate six-to-twelve month compliance timelines. Target specialty store channels in São Paulo and Mexico City with imported small-batch formats, leveraging direct-to-baker e-commerce procurement to bypass traditional distributor markups. For Investors and Strategic Acquirers: Roll-up economics work for regional membrane filtration technology providers because decentralized production is displacing centralized evaporator economics in Brazil and Indonesia. Monitor EU F-Gas implementation pace as inflection indicator for stranded asset risk concentration among legacy equipment operators.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | Sugar-reduced variants align with United Kingdom and South Africa sugar-tax frameworks, opening first-mover positioning. |
| Backward Integration | Cooperative dairy network control secures raw milk supply stability against farmgate price volatility in Germany. |
| Membrane Filtration Adoption | Regional hub deployment reduces transport costs from centralized facilities for Brazilian and Indonesian manufacturers. |
| Organic Certification Investment | EFSA-aligned protocols enable category captain status and shelf-space premiums in Scandinavian supermarket channels. |
| Direct Manufacturer Contracting | Vinamilk and regional suppliers negotiate fat-content specifications directly with Vietnam and Thailand confectionery producers. |
Methodological Framework
Coverage spans Southeast Asia, Northern Europe, Latin America, and South Asia, with primary inputs from each region combined with secondary validation. Dairy processing executives, cooperative procurement managers, confectionery manufacturer R&D directors, and specialty store buyers provided operational perspectives. Secondary sources include FDA standards documentation, EU F-Gas Regulation filings, BIS certification protocols, ANVISA dairy regulations, and trade flow data from customs authorities. Bottom-up volume modeling and top-down value triangulation cross-validated segment outputs.
Granularity extends to product type, distribution channel, end user, and packaging format dimensions, with additional modeling of regional regulatory cluster effects. CAGRs derive from historical trajectory analysis and forward projection of input cost and demand drivers across the analysis window. Forecast inputs incorporate EU F-Gas compliance cost assumptions, Vinamilk capacity expansion schedules, and membrane filtration adoption curves in decentralized production hubs.
Revisions become necessary when EU F-Gas phase-down accelerates, raw milk price volatility exceeds historical bands, or plant-based substitution rates in European specialty channels outpace baseline assumptions. Practitioners should monitor cooling technology retrofit completion rates, cooperative contract renewal patterns, and sugar-tax legislative momentum for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Canada Casein and Caseinate Market
Dairy Products
Cholesterol Reduced Butter Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
Green Tea Butter Market
Dairy Products
Cheddar Cheese Market
Dairy Products
Global Fortified Dairy Products Market
Dairy Products
Lactose Free Dairy Products Market
Dairy Products
Ghee Market
Dairy Products
US Yogurt and Probiotic Drink Market
Dairy Products
Fat-Rich Dairy Products Market
Dairy Products
Drinkable Yogurt Market
Dairy Products
North America Dairy Market
Dairy Products
Global Reduced Fat Butter Market
Dairy Products
Milk Fat Fractions Market
Dairy Products
Milk Retentate Market
Dairy Products
United States Camel Dairy Market