
 Canada Organic Food Market | 2026-2036
Canada Organic Food Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Organic Food Market Insights
Canada is narrowing its reliance on imported organic grains through Prairie province capacity expansion in Saskatchewan and Manitoba. Yorkshire Valley Farms leverages vertical integration across its Ontario poultry and feed operations. One Degree Organics anchors its identity in transparent sourcing, tracing every ingredient to a specific farm. Prana specializes in value-added processing, converting raw organic inputs into packaged snacks for national retail distribution.
Canada organic food encompasses agricultural products and processed goods cultivated without synthetic pesticides, genetically modified organisms, or petroleum-based fertilizers, certified under standards mandating minimum organic matter thresholds and buffer zones between conventional and organic acreage. The category serves consumer health preferences, environmental stewardship commitments, and premium positioning strategies across retail and food service channels. Fruits and vegetables occupy the largest product type share due to established consumer familiarity and year-round import supplementation. Online stores represent the fastest-expanding distribution channel, though supermarkets retain margin dominance through private-label organic lines. Households drive volume, while restaurants and cafes generate higher per-unit premiums through menu certification claims.
Health Canada administers the Canada Organic Regime, enforcing the Safe Food for Canadians Regulations that mandate third-party certification for organic claims. The Canadian Food Inspection Agency conducts border inspections and domestic audits, while provincial agricultural ministries supplement with land-use and water-quality standards. Stakeholders must monitor evolving equivalency agreements with trading partners and anticipate tighter traceability requirements that could reshape supplier qualification protocols.
Market Dynamics
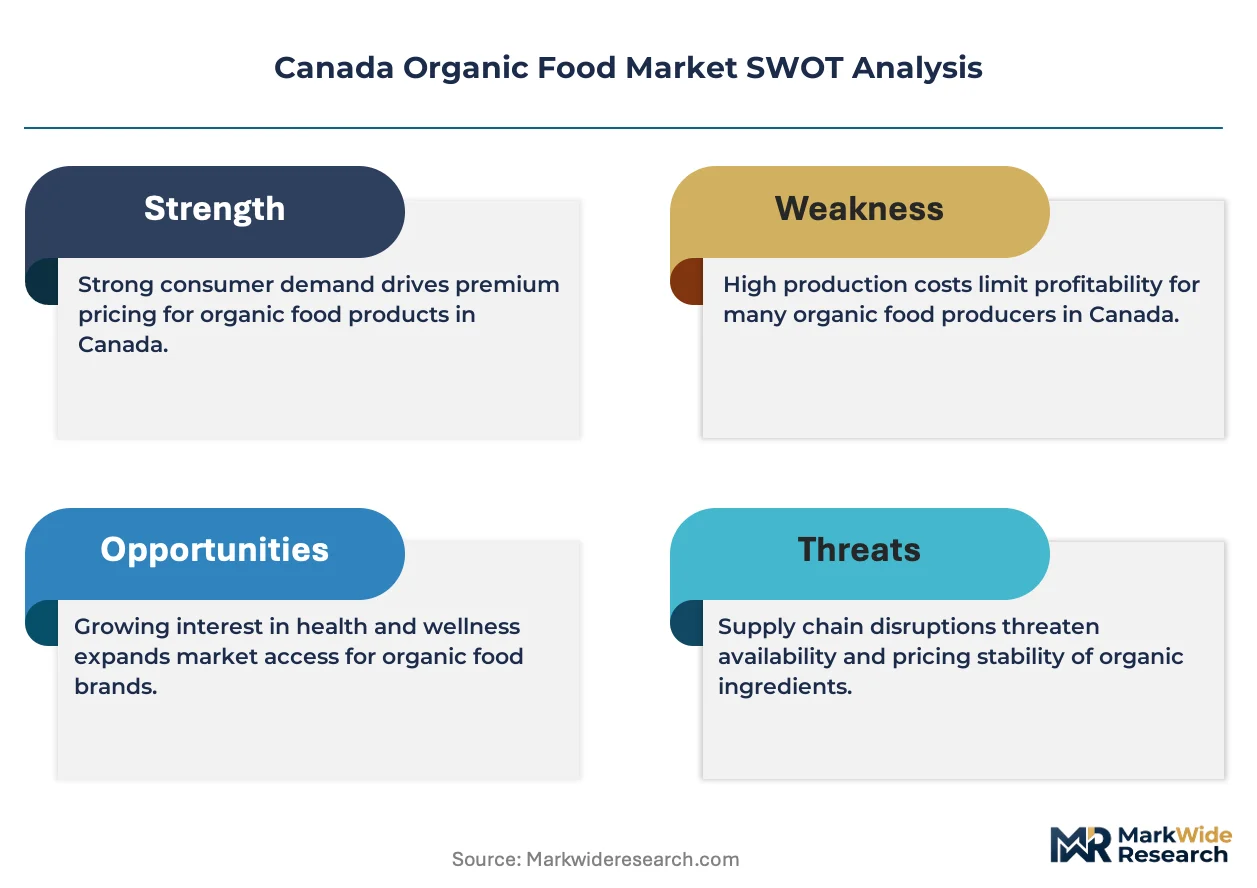
Health Canada's tightened Canada Organic Regime compliance thresholds are forcing Prairie province feed grain producers to rebuild buffer zones and certification documentation, compressing domestic supply timelines while accelerating import substitution strategies.
Growth Catalysts
- Canada Organic Regime equivalency expansion:Health Canada's bilateral agreements with the USDA National Organic Program and EU organic frameworks unlock cross-border retail placement for certified Canadian exporters.
- Direct-to-consumer farm networks:Ontario and British Columbia producers are building subscription-based CSA models that bypass conventional wholesale markups.
- Prairie province feed grain capacity:Saskatchewan and Manitoba organic acreage expansion reduces poultry and livestock producer dependence on imported organic soy and corn.
Market Restraints
- Organic input cost volatility:Certified organic seed and approved fertilizer prices fluctuate with conventional commodity spreads, squeezing margin predictability for transitioning farms.
- Third-party auditor concentration:CFIA-accredited certification bodies cluster in Ontario and Quebec, creating geographic access barriers for Atlantic and northern producers.
- Three-year transition lock-in:Mandatory soil management periods before harvest certification delay revenue generation for conventional-to-organic conversions.
Strategic Opportunities
- Atlantic province retail underpenetration:New Brunswick and Nova Scotia supermarket organic private-label shelf space remains below national averages, offering first-mover positioning for regional processors.
- Regenerative agriculture certification layering:Producers stacking Climate Action Reserve or Verra carbon credits atop organic certification access premium pricing from institutional food service buyers.
- Blockchain-IoT traceability convergence:Farm-management platforms integrating satellite imagery with immutable ledger records are collapsing verification costs for export documentation.
Industry Challenges
- Organic agronomist scarcity:Specialized soil biology and pest management expertise concentrates in Ontario and British Columbia, limiting technical support for Prairie and Atlantic transition farms.
- Legacy equipment incompatibility:Conventional grain handling and processing infrastructure requires capital-intensive retrofitting to prevent commingling and maintain organic integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Organic Food Market |
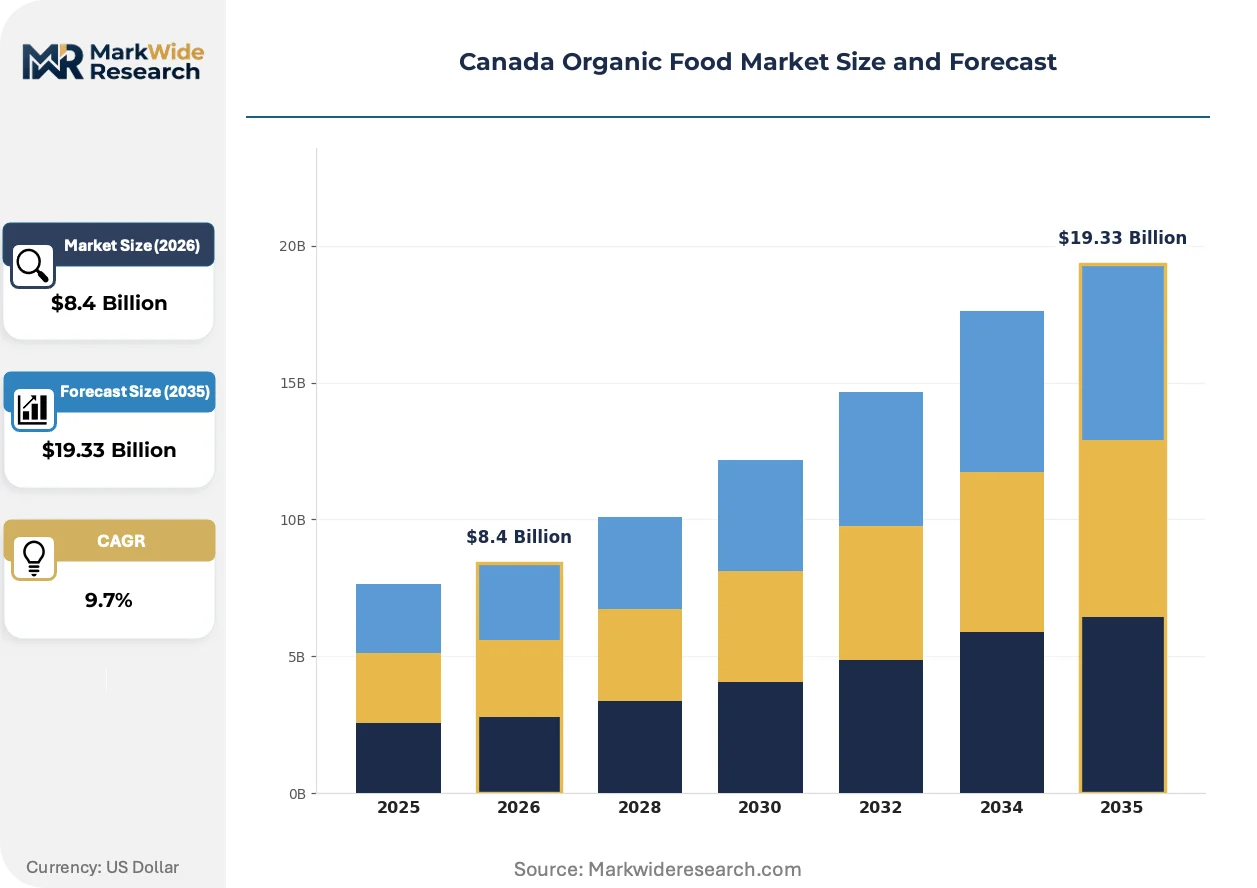
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
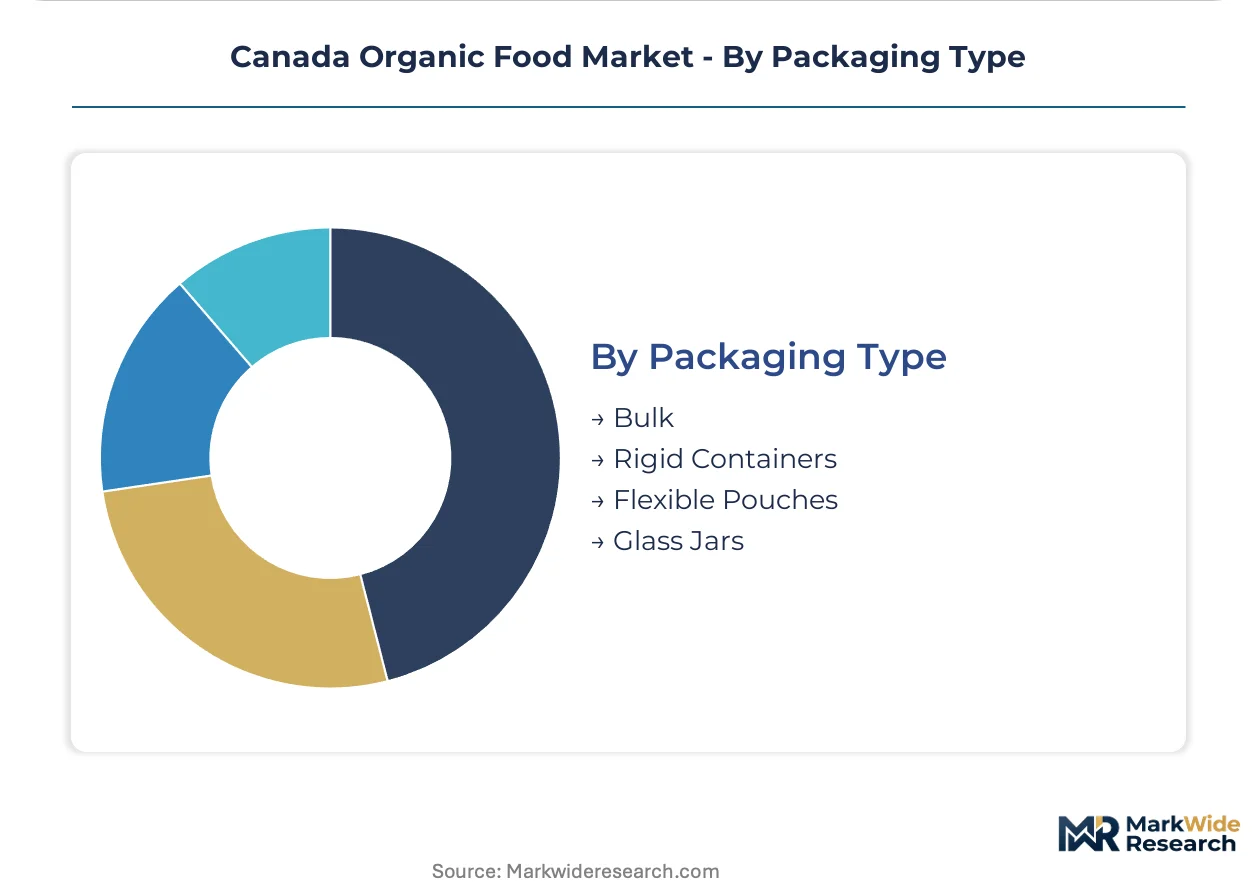
| Segmentation | Product Type: Fruits, Vegetables, Grains, Dairy Distribution Channel: Supermarkets, Online Stores, Farmers' Markets, Health Food Stores Customer Type: Households, Restaurants, Cafes, Food Service Providers Packaging Type: Bulk, Rigid Containers, Flexible Pouches, Glass Jars |
| Companies Covered | Yorkshire Valley Farms, Enviro Mushroom Farm, One Degree Organics, Ayoub’s Dried Fruits & Nuts, imPRESS Foods, Prana, Rossdown Farms & Natural Foods, THEOBROMA Chocolat, Nature’s Emporium, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Organic Food Market Trends and Innovations
Digital traceability infrastructure and regenerative certification layering are compressing verification costs while expanding premium positioning beyond baseline organic claims. These shifts reshape competitive differentiation across production and retail tiers.
Blockchain-enabled supply chain documentation is collapsing audit and certification renewal expenses for export-oriented grain handlers. Saskatchewan organic wheat and pulse exporters are adopting distributed ledger platforms to automate CFIA-equivalency documentation for EU and US buyers. This compression enables mid-scale cooperatives to compete with vertically integrated national brands on cross-border compliance speed.
Health Canada's Safe Food for Canadians Regulations are tightening organic claim substantiation requirements at retail and food service points of sale. The Canadian Food Inspection Agency has expanded domestic audit frequency for processed organic products, particularly in snack and beverage categories with complex multi-ingredient supply chains. British Columbia and Ontario retailers are responding by demanding batch-level traceability from supplier contracts.
Subscription-based procurement is displacing spot-market purchasing among urban households in Toronto and Vancouver. Direct farm-to-door delivery platforms bypass conventional supermarket markup structures while capturing consumer willingness to prepay for seasonal harvest commitments. This channel shift concentrates demand forecasting risk with producers but secures working capital earlier in production cycles.
Canada Organic Food Market Segmentation

Canada's organic food segmentation reveals how certification requirements, cold-chain logistics, and retail channel economics reshape competitive positioning across product tiers. Each dimension carries distinct margin profiles and regulatory exposure under Health Canada's enforcement framework.
Product Type:
Mature segments dominate shelf space while emerging categories reshape procurement patterns among institutional buyers.
- Fruits:Year-round import dependency from California, Mexico, and Chile sustains consistent availability despite domestic seasonality constraints. Ontario and British Columbia retail chains prioritize certified organic berries and tree fruits for private-label programs, though perishability compresses margin recovery on unsold inventory.
- Vegetables:Leafy greens and root vegetables anchor CSA subscription models across the Golden Horseshoe and Lower Mainland, where direct-to-consumer pricing captures 40-60% premiums over wholesale. Quebec's organic greenhouse sector extends domestic production windows for tomatoes and peppers.
- Grains:Prairie organic wheat and pulse production supplies domestic processors and EU export markets under equivalency protocols.
- Dairy:Supply-managed organic milk pools in Ontario and Quebec face processing capacity bottlenecks during spring flush periods.
Fruits and vegetables handle the majority of throughput; grains are gaining share fastest through Prairie export expansion.
Distribution Channel:
Channel selection determines margin capture speed and working capital requirements for producers at different scales.
- Supermarkets:Loblaws, Sobeys, and Metro private-label organic lines extract volume commitments from suppliers in exchange for national shelf placement. Category managers enforce batch-level traceability documentation exceeding baseline CFIA requirements.
- Online Stores:Instacart-partnered retailers and direct farm platforms collapse geographic access barriers for Atlantic and northern households. Fulfillment infrastructure investments by Spud.ca and similar regional operators compress delivery windows to 24-48 hours for perishables.
- Farmers' Markets:Seasonal concentration in Toronto, Vancouver, and Montreal cores sustains price premiums through face-to-face provenance storytelling.
- Health Food Stores:Independent retailers in university towns and affluent suburbs stock specialty organic imports and supplements absent from mass-market assortments.
Supermarkets handle the majority of throughput; online stores are expanding most quickly on share.
Customer Type:
Volume concentration diverges from margin intensity across household and institutional purchasing patterns.
- Households:Weekly grocery basket purchases drive baseline demand stability, with Toronto and Vancouver households showing highest per-capita organic expenditure. Subscription prepayment models shift demand forecasting risk to producers while securing working capital.
- Restaurants:Menu certification claims command 15-25% plate-price premiums in fine-dining segments, though ingredient traceability documentation burdens smaller operators.
- Cafes:Coffee shop chains and independent roasters prioritize certified organic dairy alternatives and baked goods for brand differentiation.
- Food Service Providers:Institutional buyers in healthcare and education sectors layer regenerative agriculture requirements atop organic certification for carbon accounting compliance.
Households handle the majority of throughput; food service providers are climbing the fastest on share through institutional procurement mandates.
Packaging Type:
Packaging selection reflects tension between shelf-life extension, regulatory labeling requirements, and plastic reduction commitments.
- Bulk:Loose produce and gravity-bin grains eliminate packaging cost while requiring retailer investment in sanitary dispensing infrastructure. Vancouver and Toronto co-ops lead adoption.
- Rigid Containers:Recycled PET and molded fiber trays protect delicate produce through distribution, though PFAS concerns in compostable alternatives trigger Health Canada scrutiny.
- Flexible Pouches:Stand-up bags for snacks and grains minimize shipping cube and shelf footprint.
- Glass Jars:Premium positioning for sauces, condiments, and preserves supports circular return programs in urban cores.
Rigid containers handle the majority of throughput; bulk is expanding most quickly on share through zero-waste retail formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Organic feed grain production concentrates in Saskatchewan and Manitoba, where Prairie province acreage expansion reduces import dependence for domestic livestock operations. Ontario and British Columbia anchor consumer demand through urban retail density and direct-to-consumer farm networks. Health Canada's Canada Organic Regime enforces uniform certification standards while provincial agricultural ministries layer land-use and water-quality requirements.
Ontario
Toronto households drive the highest per-capita organic expenditure in Canada, with subscription-based CSA models capturing 40-60% premiums over wholesale channels. Health Canada's Safe Food for Canadians Regulations mandate third-party certification for all organic claims sold through provincial retail chains. The Golden Horseshoe corridor hosts Yorkshire Valley Farms' vertically integrated poultry and feed operations, demonstrating scale advantages in supply-managed protein categories.
British Columbia
Vancouver's zero-waste retail formats accelerate bulk produce adoption, with co-operative grocery chains investing in sanitary dispensing infrastructure for loose grains and vegetables. The Canadian Food Inspection Agency has expanded audit frequency for processed organic products distributed through Lower Mainland retail networks. Direct farm-to-door delivery platforms in Metro Vancouver collapse conventional supermarket markups while securing producer working capital through seasonal prepayment commitments.
Quebec
Organic greenhouse production around Montreal extends domestic availability windows for tomatoes and peppers, reducing import dependency during winter months. Supply-managed organic milk pools face spring flush processing bottlenecks that compress producer margins during peak production periods. Quebec's provincial agricultural ministry supplements federal Canada Organic Regime standards with additional water-quality monitoring requirements for St. Lawrence watershed operations.
Prairie Provinces
Saskatchewan and Manitoba organic wheat and pulse exporters leverage blockchain-enabled documentation to automate CFIA-equivalency paperwork for EU and US buyers. The three-year transition lock-in for conventional-to-organic conversion delays revenue generation for Prairie grain operations, accelerating reliance on specialized organic seed suppliers. Organic agronomist scarcity limits technical support availability for soil biology and pest management across the region's expanding transition farms.
Atlantic Canada
New Brunswick and Nova Scotia supermarket organic private-label shelf space remains below national averages, creating first-mover positioning opportunities for regional processors. CFIA-accredited certification bodies cluster in Ontario and Quebec, generating geographic access barriers that elevate compliance costs for Atlantic producers. Halifax and Moncton retail chains are beginning to demand batch-level traceability documentation exceeding baseline federal requirements for multi-ingredient organic products.
Canada Organic Food Market Competitive Landscape
Vertically integrated protein processors and transparent sourcing specialists split the market between scale efficiency and premium positioning. The competitive structure favors operators controlling upstream feed inputs or downstream retail channels. Three archetypes dominate: Prairie grain cooperatives leveraging equivalency documentation for export markets, Ontario-Quebec livestock integrators capturing supply-managed category margins, and British Columbia-based direct-to-consumer platforms collapsing wholesale markups. Capacity expansion in Prairie organic acreage and M&A activity among regional snack processors represent the dominant competitive moves.
Among Ontario-based livestock integrators, Yorkshire Valley Farms exemplifies vertical control across poultry and feed operations. Transparent sourcing specialists include One Degree Organics, which anchors its market position in farm-level traceability. Value-added processors such as Prana occupy positions in packaged snack categories, converting raw organic inputs into national retail distribution. These three operators represent distinct strategic poles: captive supply chains, ingredient provenance documentation, and processing margin capture.
| Leading Market Players |
|---|
| Yorkshire Valley Farms |
| Enviro Mushroom Farm |
| One Degree Organics |
| Ayoub's Dried Fruits & Nuts |
| imPRESS Foods |
| Prana |
| Rossdown Farms & Natural Foods |
| THEOBROMA Chocolat |
| Nature's Emporium |
| Others |
Pricing and Supply Chain Analysis
The Port of Vancouver container corridor anchors cost dynamics for organic produce imports from California and Mexico, with freight rate volatility compressing margin recovery for Ontario retailers while amplifying price differentiation between direct-from-farm subscription tiers and conventional supermarket channels.
Pricing Analysis
The Canada Organic Regime dictates the pricing tier structure across certified, transitional, and uncertified segments. Three-tier pricing structure across premium certified, standard transitional, and economy conventional levels separates Saskatchewan grain cooperatives from Ontario-Quebec livestock integrators. Cost compression in premium tiers is intensifying because Health Canada's tightened buffer zone requirements elevate compliance documentation expenses. Household subscribers in Toronto and Vancouver show least price sensitivity, while Atlantic Canada supermarket shoppers exhibit highest elasticity.
Supply Chain Analysis
Yorkshire Valley Farms and Prana hold captive processing capacity across Ontario poultry and snack manufacturing nodes. Domestic supply concentrates in Saskatchewan and Manitoba for grains, Ontario and Quebec for dairy and poultry, British Columbia for produce. Certified organic seed and approved fertilizer inputs rest on Prairie province production and US import channels. Single-source vulnerability runs through CFIA-accredited certification bodies clustered in Ontario and Quebec. Distribution runs through Loblaws and Sobeys private-label networks, with Spud.ca and farm-direct platforms gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada organic food is approaching a platform-economics inflection where blockchain-IoT traceability infrastructure enables subscription-based farm networks to bypass incumbent wholesale markups, collapsing verification costs while expanding direct-to-consumer interoperability.
For Market Incumbents: Pre-empt Atlantic province retail underpenetration by acquiring regional processors before national competitors establish private-label shelf space. Secure backward integration into Prairie organic feed grain through long-term offtake agreements with Saskatchewan cooperatives, insulating poultry operations from import substitution volatility.
For New Entrants and Emerging Players: Pursue New Brunswick and Nova Scotia supermarket organic private-label gaps where shelf space sits below national averages. Target regenerative agriculture certification layering for institutional food service buyers in healthcare and education sectors. Launch with batch-level traceability documentation exceeding baseline CFIA requirements as the go-to-market wedge.
For Investors and Strategic Acquirers: Prairie grain cooperatives with blockchain-enabled equivalency documentation represent the most defensible acquisition archetype for EU and US export exposure. Long-term viability hinges on equivalency agreement durability and carbon credit stacking economics. Watch Health Canada traceability requirement tightening as the signal for supplier qualification protocol disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-IoT Traceability Integration | Saskatchewan wheat exporters automate CFIA-equivalency documentation for EU buyers through distributed ledger platforms. |
| Regenerative Certification Layering | Producers stack Climate Action Reserve credits atop organic claims for premium pricing from institutional food service. |
| Direct-to-Consumer Platform Launch | Ontario and British Columbia farm networks bypass supermarket markups through subscription-based CSA models. |
| Prairie Feed Grain Capacity Expansion | Manitoba and Saskatchewan acreage growth reduces poultry producer dependence on imported organic soy and corn. |
| Atlantic Province Processor Acquisition | First-movers secure regional private-label shelf space before national retailers consolidate distribution. |
Research Methodology
The analysis maps organic grains, produce, dairy, and processed foods segments, each validated through primary interviews with CFIA compliance officers, organic certification body auditors, supermarket category managers, and Prairie grain cooperative executives. Secondary sources include Health Canada regulatory filings, Canadian Food Inspection Agency audit protocols, Statistics Canada agricultural census data, and provincial agricultural ministry land-use records. Bottom-up acreage and production estimates triangulate against top-down retail scanner data.
Assumptions held fixed include Health Canada equivalency agreement durability with USDA and EU frameworks, while organic input cost volatility and Atlantic province retail penetration rates were modeled as scenario variables. Segmentation dimensions span product type, distribution channel, customer type, and packaging format across the projection horizon. CAGRs derive from compound growth modeling of household expenditure patterns and institutional procurement mandates. Forecast inputs incorporate Prairie province organic acreage expansion timelines and CFIA audit frequency expansion.
Macroeconomic conditions sit as an overlay; deviation in freight rate indices and organic commodity spreads would shift the trajectory. Forecasts reflect assumptions about certification body capacity expansion and equivalency negotiation outcomes. Quarterly review of Health Canada regulatory amendments and Atlantic province retail private-label rollout is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Organic Cocoa Market
Organic Food and Beverages
Organic Coconut Syrup Market
Organic Food and Beverages
Scandinavia Organic Packaged Food and Beverages Market
Organic Food and Beverages
Organic Rice Syrup Market
Organic Food and Beverages
South Korea Organic Food Market
Organic Food and Beverages
Australia Organic Beverages Market
Organic Food and Beverages
United States Organic Food Market
Organic Food and Beverages
India Organic Food Market
Organic Food and Beverages
Organic Ice Cream Market
Organic Food and Beverages
Asia-Pacific Organic Food Market
Organic Food and Beverages
Organic Yogurt Market
Organic Food and Beverages
Saudi Arabia Organic Food Market
Organic Food and Beverages
UK Organic Food Market
Organic Food and Beverages
UAE Organic Food Market
Organic Food and Beverages
Organic Coconut Sugar Market
Organic Food and Beverages
Italy Organic Food Market