
 Fast Food Market | 2026-2036
Fast Food Market Size, Share, and Industry Trends Forecast 2026-2036
Fast Food Market Intelligence
Digital subscription and loyalty programs is pivoting the fast food value proposition from transactional meals to recurring revenue relationships. McDonald's leverages its app-based rewards ecosystem to capture repeat visits and first-party consumer data. Chick-fil-A sustains exceptional brand loyalty through a membership model that preloads mobile wallets and personalizes offers. Starbucks dominates the beverage subscription segment with frequency-based incentives that lock in morning ritual behavior.
Fast food comprises prepared meals manufactured through standardized cooking protocols, assembled via modular ingredient kits, and distributed through limited-service channels with sub-five-minute order cycles. The category serves commercial purposes of caloric convenience, temporal efficiency, and price-accessible satiation for time-constrained consumers. Burgers and fried chicken anchor mature margin pools in Western markets where protein-centric menus command stable traffic, while delivery services and mobile apps represent the fastest-expanding service model as last-mile logistics and kiosk-based labor reduction reshape unit economics. Quick service restaurants still occupy the volume-dominant format, though third-party aggregators are extracting meaningful commission structures from operator profitability.
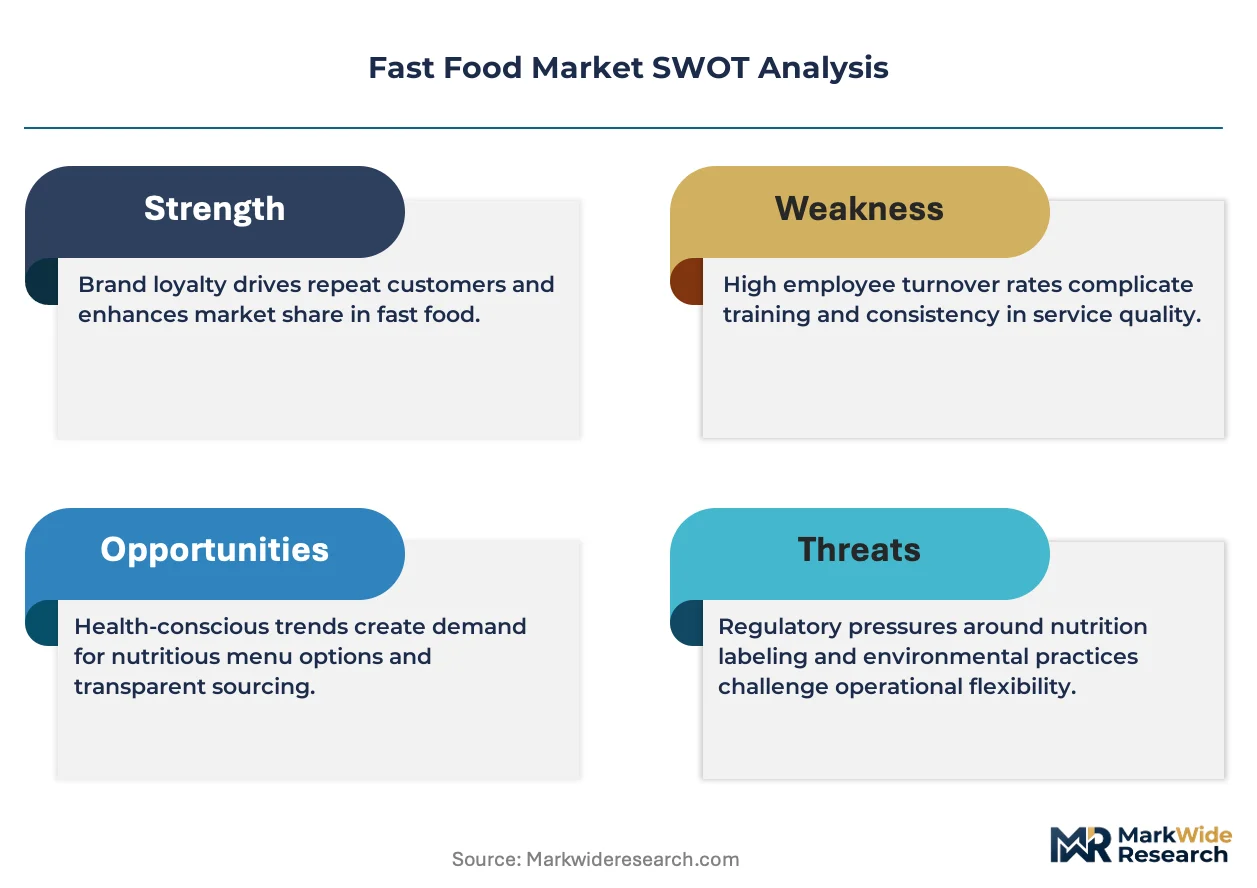
The FDA enforces nutrition disclosure and allergen labeling that compels reformulation of sodium-dense and trans-fat-laden menus, while the USDA monitors meat supply chain integrity affecting procurement standards across burger and fried chicken categories. EFSA and national regulators across Europe impose stricter additive restrictions and packaging waste directives that elevate compliance costs for multinational operators. Stakeholders must monitor how AI-driven dynamic pricing and ghost kitchen proliferation alter real estate requirements and labor deployment decisions across their network architecture.
Market Dynamics
Digital ordering infrastructure and ghost kitchen proliferation are compressing real estate footprints while fragmenting demand capture across multiple virtual brands operating from single physical locations. Labor automation pressures intersect with FDA menu labeling mandates to force simultaneous capital deployment and formulation reformulation.
Growth Catalysts
- Urban Employment Density:Working professionals in metropolitan India and China generate concentrated lunch-hour traffic that rewards high-throughput kitchen designs and mobile pre-ordering systems.
- Digital Loyalty Ecosystems:App-based rewards programs capture first-party consumer data and repeat visit behavior, converting transactional meals into recurring revenue relationships.
- Last-Mile Logistics Maturation:Third-party delivery platforms expand addressable demand beyond traditional trade-area radii, enabling revenue recovery from underutilized kitchen capacity.
Market Restraints
- Commodity Protein Volatility:USDA-monitored beef and poultry supply chains expose operators to feed-cost transmission and climate-driven herd fluctuations.
- Commission Structure Extraction:Third-party aggregators capture 15-30% of order value, compressing unit economics for operators without sufficient scale to negotiate rate relief.
- Trans-Fat Reformulation Costs:FDA enforcement of nutrition disclosure and hydrogenated oil restrictions forces menu redevelopment and supplier requalification.
Strategic Opportunities
- India Tier-II Urban Expansion:Secondary cities with rising disposable incomes and limited organized fast-food penetration offer first-mover positioning for standardized formats.
- AI-Driven Dynamic Pricing:Machine learning models that adjust menu pricing by time-of-day and demand elasticity maximize revenue per available kitchen hour.
- Plant-Based Protein Convergence:Alternative protein technologies and flexitarian consumer preferences create new margin pools beyond traditional animal-protein dependence.
Industry Challenges
- Kitchen Automation Integration:Robotics deployment for frying and assembly requires retraining existing crews and retrofitting legacy equipment footprints.
- Multi-Brand Ghost Kitchen Complexity:Operators managing several virtual concepts from single locations face inventory fragmentation and brand-dilution risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fast Food Market |
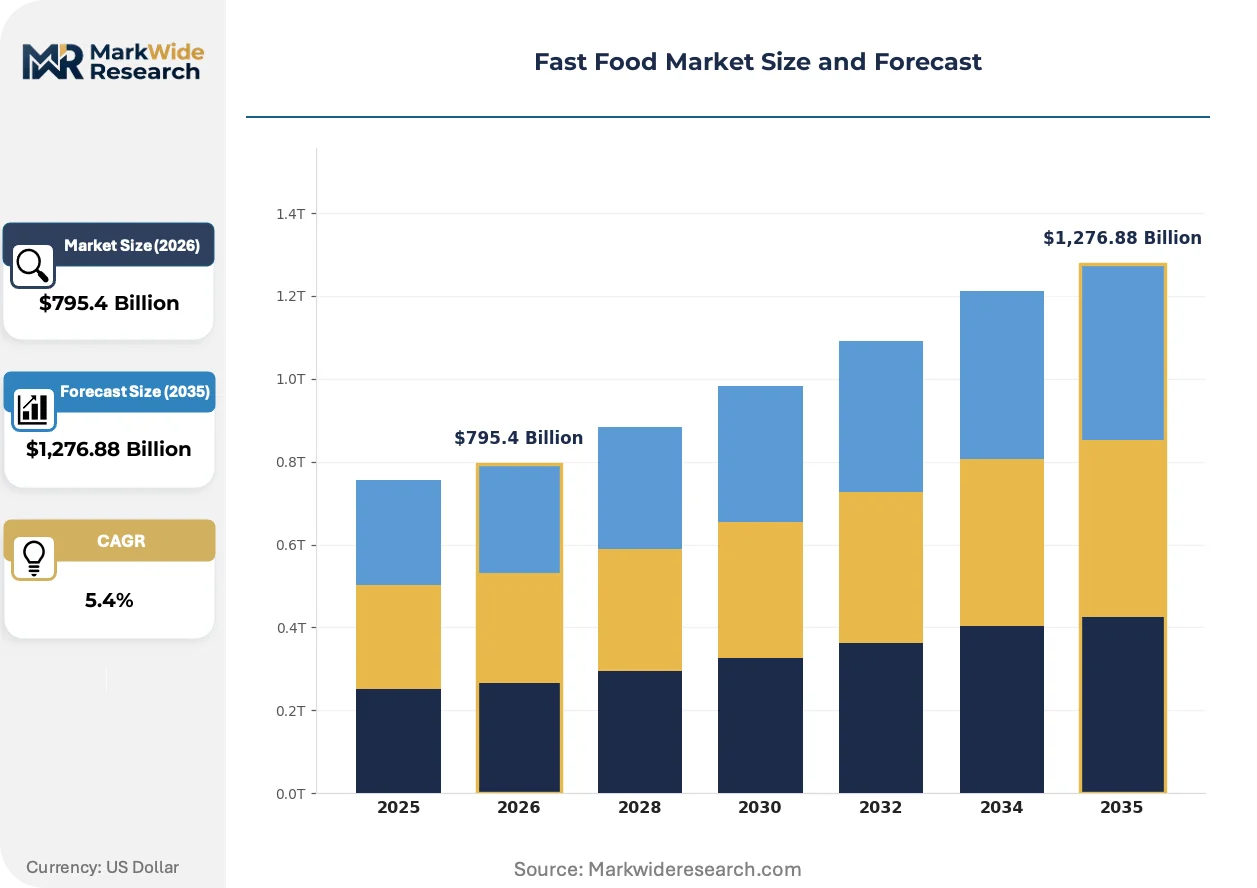
| Market Size in 2026 | $795.4 Billion |
| Market Size in 2035 | $1,276.88 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Burgers, Fried Chicken, Sandwiches, Pizzas, Tex-Mex, Seafood Service Model: Quick Service Restaurants, Food Trucks, Delivery Services, Drive-Thru, Cafeterias, Kiosks Customer Category: Students, Working Professionals, Families, Tourists, Fitness Enthusiasts, Office Workers Distribution Channel: Online Orders, In-Store Purchase, Mobile Apps, Third-Party Aggregators, Corporate Canteens, Vending Machines |
| Companies Covered | KFC, Domino’s, McDonald’s, Wendy’s, Taco Bell, Starbucks, Burger King, Chick-fil-A, Subway, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fast Food Market Strategic Shifts & Innovations
Kitchen automation and predictive demand systems are redrawing capital allocation priorities across the fast-food value chain. Three developments merit particular attention from operators and investors.
Robotic fry stations and automated beverage dispensers are modularizing kitchen labor deployment across dayparts. Chains with high throughput in the United States and China are piloting these systems during peak hours to redeploy human labor toward customer-facing roles. This technology is modularizing the traditional brigade structure, enabling smaller physical footprints without sacrificing output volume.
EFSA additive restrictions and EU packaging waste directives are elevating compliance costs for multinational operators with European exposure. The industrial consequence is accelerated shift toward paper-based packaging and clean-label ingredient declarations. Burger and fried chicken categories are most affected, with reformulation timelines compressing against 2025 implementation deadlines.
Subscription-based consumption models are displacing episodic purchase behavior in morning-daypart and beverage categories. Mobile wallet preloading and frequency-based incentives lock in ritual behavior that third-party delivery cannot easily intercept. This shift is most visible in United States coastal metropolitan areas where app penetration and digital payment adoption concentrate.
Fast Food Market Segmentation
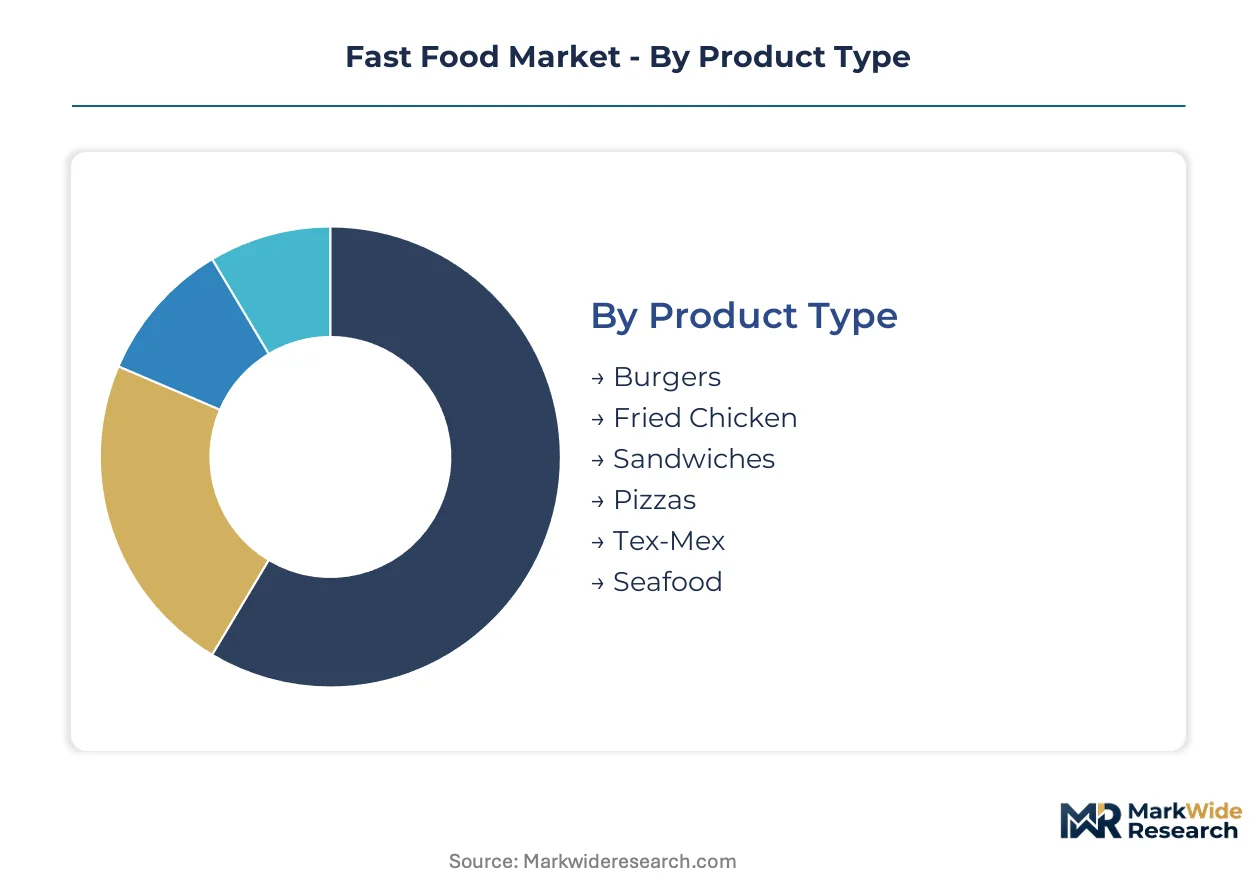
Fast food operators configure production systems and capital deployment around distinct demand profiles. Product specifications, service velocity requirements, and channel economics each impose different margin structures and real estate footprints across the value chain.
Product Type:
Protein format and cooking methodology determine kitchen equipment specifications, supplier qualification requirements, and throughput design parameters.
- Burgers:Ground beef patties cooked on flat-top grills or flame broilers anchor the category's highest-volume production formats. Demand concentrates in the United States where drive-thru infrastructure and breakfast-daypart extensions sustain traffic density; USDA-monitored beef supply chains expose operators to feed-cost volatility and climate-driven herd fluctuations.
- Fried Chicken:Pressure-fried bone-in pieces and boneless tenders require dedicated fryer banks with oil filtration systems and extended cook cycles. Working professionals in metropolitan India and China generate concentrated lunch-hour traffic that rewards high-throughput kitchen designs; FSSAI and SAMR enforcement of trans-fat restrictions forces oil specification changes and supplier requalification.
- Sandwiches:Cold and hot sub formats with modular assembly lines enable customization at speed.
- Pizzas:Oven-based production with extended bake times favors delivery-optimized kitchens over dine-in footprints.
- Tex-Mex:Protein-plus-carbohydrate bowls and wraps with fresh ingredient staging requirements.
- Seafood:Perishable supply chains with shorter holding windows and specialized allergen protocols.
Mature deployment sits with Burgers. Newer deployment is concentrated in Fried Chicken.
Service Model:
Capital intensity and labor deployment patterns vary sharply across physical formats and virtual delivery infrastructure.
- Quick Service Restaurants:Standalone buildings with drive-thru lanes, dining rooms, and high-volume production kitchens represent the dominant format for revenue capture. The United States, China, and India absorb the bulk of outlet expansion as these markets scale digital ordering infrastructure and standardized kitchen protocols.
- Delivery Services:Third-party platform integration and native app ecosystems extend trade-area radii beyond traditional catchment zones. Ghost kitchen proliferation and last-mile logistics maturation enable revenue recovery from underutilized kitchen capacity; commission structures of 15-30% compress unit economics for operators without scale.
- Drive-Thru:Lane-based vehicle throughput systems optimized for sub-five-minute order cycles.
- Food Trucks:Mobile units with constrained equipment sets and event-dependent revenue.
- Cafeterias:Institutional feeding formats with contract-based volume commitments.
- Kiosks:Compact footprints with limited menu scope and high automation potential.
Quick Service Restaurants retain the dominant revenue share. Delivery Services are climbing the fastest as digital ordering infrastructure penetrates secondary markets.
Customer Category:
Daypart concentration and price elasticity profiles shape menu engineering and promotional calendar design.
- Working Professionals:Time-constrained urban employees seeking caloric convenience and temporal efficiency during compressed lunch windows. This segment is expanding most quickly as employment density rises in metropolitan India and China; mobile pre-ordering systems and subscription-based consumption models lock in ritual behavior.
- Families:Multi-person occasions with value-meal bundling requirements and child-oriented menu extensions. Demand concentrates in suburban United States trade areas where drive-thru throughput and play-place amenities sustain visit frequency.
- Students:Price-sensitive cohort with high digital engagement and promotional responsiveness.
- Tourists:Episodic demand with low loyalty attachment and location-dependent capture.
- Fitness Enthusiasts:Protein-forward and calorie-conscious menu seekers with clean-label preferences.
- Office Workers:Corporate cluster demand with group ordering dynamics and catering potential.
Working Professionals command the steepest expansion trajectory. Families anchor the revenue base in mature Western markets.
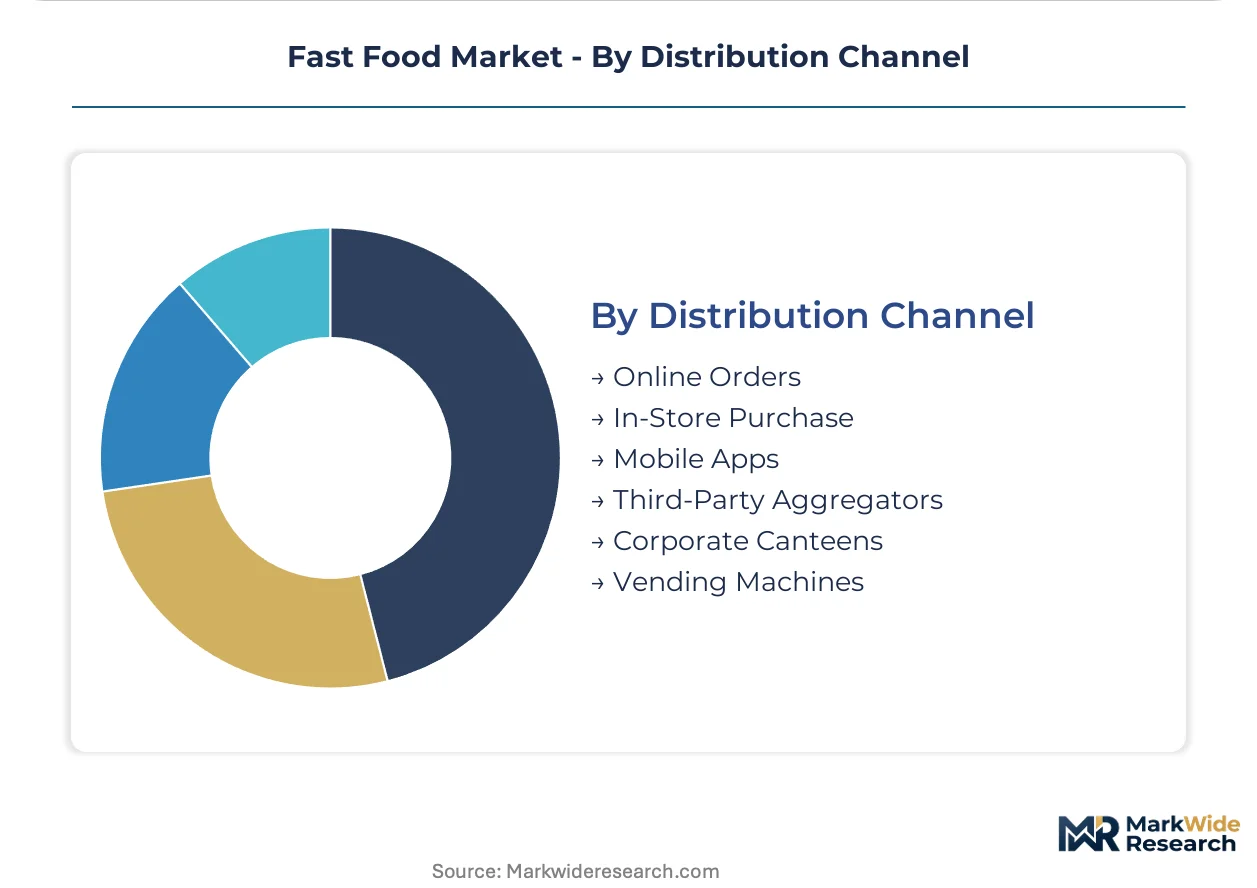
Distribution Channel:
Order origination point determines data capture potential, commission burden, and customer relationship ownership.
- Mobile Apps:Native brand applications with preloaded wallets, frequency-based incentives, and first-party data capture. Starbucks and McDonald's leverage app-based rewards ecosystems to convert transactional meals into recurring revenue relationships; personalized offers and subscription models displace episodic purchase behavior.
- Third-Party Aggregators:Platform-mediated demand with broad consumer reach and high acquisition cost. DoorDash, Uber Eats, and Meituan extract meaningful commission structures from operator profitability while fragmenting brand control over customer experience.
- Online Orders:Web-based origination with lower engagement frequency than mobile-native channels.
- In-Store Purchase:Counter and kiosk-based origination with highest margin retention.
- Corporate Canteens:B2B contract feeding with volume commitments and limited menu flexibility.
- Vending Machines:Automated retail with constrained product scope and minimal labor requirement.
In-Store Purchase retains margin superiority. Mobile Apps are gaining share fastest as digital payment adoption concentrates in United States coastal metropolitan areas.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production gravity concentrates in the United States and China where standardized kitchen protocols and digital ordering infrastructure scale most efficiently, while consumption expansion accelerates fastest in India as urban employment density rises and organized fast-food penetration deepens in secondary cities.
United States
Drive-thru throughput systems and subscription-based mobile wallet programs sustain traffic density across suburban trade areas. FDA menu labeling mandates and trans-fat restrictions compel ongoing reformulation of sodium-dense offerings. The Dallas-Fort Worth metroplex anchors aggressive outlet expansion as operators deploy kiosk-based labor reduction and AI-driven dynamic pricing across high-volume locations.
China
Metropolitan lunch-hour traffic in Shanghai and Beijing rewards high-throughput kitchen designs integrated with native super-app ecosystems. SAMR enforcement of food safety standards and additive restrictions elevates supplier qualification requirements. The Yangtze River Delta cluster concentrates ghost kitchen proliferation as operators fragment demand capture across multiple virtual brands from single physical locations.
India
Working professionals in Bengaluru and Mumbai generate concentrated demand for caloric convenience during compressed lunch windows. FSSAI trans-fat regulations and packaging waste directives force oil specification changes and clean-label ingredient transitions. Tier-II cities including Pune and Hyderabad offer first-mover positioning as disposable incomes rise and digital payment adoption accelerates.
Germany
EFSA additive restrictions and EU packaging waste directives elevate compliance costs for burger and fried chicken categories with European exposure. The country's central logistics position supports multi-country supply chain coordination for multinational operators. Berlin and Hamburg concentrate delivery-optimized kitchen footprints as third-party aggregators expand addressable demand beyond traditional trade-area radii.
Brazil
São Paulo's dense urban corridors sustain high-frequency consumption patterns among time-constrained professionals seeking price-accessible satiation. ANVISA monitoring of meat supply chain integrity affects procurement standards across protein-centric menus. The city's expanding middle-class neighborhoods attract standardized format deployment as operators target recurring revenue relationships through app-based loyalty ecosystems.
Fast Food Market Key Industry Players
Top-tier vendors anchor the premium-traffic tier, while mid-scale operators and regional specialists populate fragmented lower tiers. The vendor base separates into three strategic archetypes: scale-driven chains with dense digital infrastructure, protein-format specialists commanding narrow category dominance, and platform-native virtual brands exploiting ghost kitchen economics. Competitive positioning hardens through M&A consolidation of regional players and backward integration into proprietary delivery logistics.
Within the scale-driven tier, McDonald's and Starbucks exemplify operators converting transactional meals into recurring revenue relationships through app-based rewards ecosystems and preloaded mobile wallets. KFC occupies a position representing protein-format specialists leveraging standardized pressure-frying protocols across high-throughput markets. These anchors demonstrate how first-party data capture and frequency-based incentives lock in ritual consumer behavior that third-party delivery cannot easily intercept.
| Leading Market Players |
|---|
| KFC |
| Domino's |
| McDonald's |
| Wendy's |
| Taco Bell |
| Starbucks |
| Burger King |
| Chick-fil-A |
| Subway |
| Others |
Cost & Logistics Intelligence
USDA-reported beef price volatility cascades through procurement tiers into three distinct pricing levels: premium branded menus absorb commodity swings through subscription lock-in, standard quick-service tiers negotiate quarterly contract adjustments, and economy operators face immediate margin compression from spot-market protein exposure.
Pricing Analysis
Margin tightening in the standard tier reflects third-party aggregator commission extraction and trans-fat reformulation compliance costs. Three-tier pricing structure across premium, standard, and economy levels separates subscription-backed loyalty programs from transaction-dependent foot traffic and value-menu desperation pricing. Price differentiation traces to digital infrastructure depth and geographic delivery cost stratification. Students and price-conscious families exhibit highest sensitivity; subscription-locked professionals show lowest elasticity.
Supply Chain Analysis
Protein supply rests on USDA-monitored domestic beef herds, Brazilian poultry operations, and Indian feed-integrated poultry farms. Key inputs include specialized frying oils, modular packaging substrates, and frozen potato products. Single-source vulnerability concentrates in hydrogenated oil alternatives facing FDA enforcement timelines. Distribution runs through cold-chain logistics networks terminating at quick-service restaurant back-of-house receiving docks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital ordering infrastructure is displacing legacy counter-service economics, with AI-driven kitchen automation and ghost kitchen proliferation compressing traditional real estate and labor models.
For Market Incumbents: Deploy subscription-based mobile wallet ecosystems to capture first-party data and ritual behavior before third-party aggregators fragment customer relationships. Consolidate kitchen automation investments in high-throughput metropolitan locations to offset labor cost pressures from FDA menu labeling mandates. Backward integration into proprietary delivery logistics defends margin position against commission extraction. For New Entrants and Emerging Players: Ghost kitchen infrastructure in India's Tier-II cities offers the most penetrable white-space opportunity as disposable incomes rise and organized fast-food penetration remains shallow. Target working professionals through app-native pre-ordering systems rather than capital-intensive dine-in footprints. Franchise-light licensing models accelerate geographic coverage without balance-sheet strain. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional quick-service chains with underutilized kitchen capacity in secondary US and Chinese metropolitan markets. Five-to-ten-year viability hinges on digital infrastructure migration completion. Watch ghost kitchen operator consolidation rates as the inflection signal for platform economics stabilization.| Strategic Initiative | Industry Significance |
|---|---|
| Kitchen Automation Deployment | Robotic fry stations redeploy labor toward customer-facing roles in high-throughput US and China locations. |
| Subscription Model Launch | Frequency-based mobile wallet incentives lock in morning ritual behavior against aggregator interception. |
| Ghost Kitchen Expansion | Multi-brand virtual concepts from single locations fragment demand capture across metropolitan India and China. |
| Clean-Label Reformulation | FDA and EFSA additive restrictions force oil specification changes ahead of compliance deadlines. |
| Tier-II Market Entry | Secondary Indian cities with rising employment density offer first-mover positioning for standardized formats. |
Research Approach
SEC filings, FDA enforcement actions, and USDA commodity reports formed the secondary backbone, cross-referenced against primary interviews with quick-service restaurant operations directors, supply chain procurement managers, franchise development executives, and third-party delivery platform strategists. Bottom-up outlet expansion tracking and top-down consumer expenditure analysis enabled triangulation across data sources.
Bottom-up modeling aggregated unit economics across service model segments, while top-down validation referenced national food-away-from-home expenditure patterns. Segmentation dimensions included product type, service model, customer category, and distribution channel across the projection horizon. CAGRs derived from historical outlet growth correlations with urban employment density and digital payment adoption curves. Forecast inputs incorporated ghost kitchen proliferation rates and regulatory compliance cost trajectories.
The model holds under stable commodity price regimes and continued digital infrastructure investment; deviation in protein supply shocks or trans-fat enforcement acceleration would shift trajectory. A small set of named triggers warrants ongoing watch: USDA herd liquidation cycles, SAMR additive restriction expansion, and third-party aggregator commission renegotiation outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Gas Fryers Market
Food Service
Bahrain Food Service Market
Food Service
Healthy Takeout Market
Food Service
Oman Food Service Market
Food Service
Self-Heating Hot Pot Market
Food Service
South America Free from Food Market
Food Service
Personal Chef Services Market
Food Service
Haute Cuisine Market
Food Service
Brazil Foodservice Market
Food Service
Kamado Grill Market
Food Service
Saudi Arabia Out of Home (OOH) Delivery Market
Food Service
Aquarium Protein Skimmers Market
Food Service
UK Smokeless Indoor Grills Market
Food Service
Instant Noodle Vending Machine Market
Food Service
United States Smokeless Indoor Grills Market
Food Service
Sandwich Toasters Market