
 Organic Beverages Market | 2026-2036
Organic Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Beverages Market Analysis
Millennial households is reorganizing demand away from conventional soft drink buyers toward wellness-oriented purchasers seeking clean-label formulations. Danone S.A. leverages its dairy-alternative infrastructure to dominate European organic beverage distribution. The Hain Celestial Group, Inc. anchors North American shelf presence through health food store partnerships. PepsiCo, Inc. competes by extending its portfolio into organic tea and juice segments through existing retail channels.
Organic beverages comprise drinks manufactured from ingredients certified under national or regional organic standards, requiring minimum synthetic pesticide residue thresholds and prohibiting genetically modified organisms in formulation. These products serve commercial and retail markets seeking reduced chemical exposure and transparent agricultural sourcing. Organic juices and organic tea currently lead product type revenue due to established consumer familiarity and broader retail placement, while organic soft drinks represent the fastest-growing category as soda alternatives gain traction among younger demographics. Supermarkets control the largest distribution channel volume, though online retailers capture the fastest growth as direct-to-subscription models reduce conventional retail markup.
USDA organic certification in the United States and EU organic regulations enforced by EFSA govern ingredient sourcing, processing methods, and label claims across major markets. These frameworks create compliance barriers that favor established operators with dedicated supply chain auditing capabilities. Stakeholders should monitor evolving pesticide residue thresholds and packaging sustainability mandates, as regulatory tightening will determine which suppliers retain market access without reformulation costs.
Market Dynamics
EU organic certification tightening under EFSA traceability mandates is restructuring supplier qualification requirements across European distribution networks. This regulatory compression favors operators with captive supply chains and dedicated auditing infrastructure.
Growth Catalysts
- EU Green Deal implementation:The EU Green Deal's farm-to-fork strategy mandates pesticide reduction targets that accelerate organic ingredient sourcing commitments from mainstream beverage manufacturers.
- Direct-to-subscription channel expansion:Online retailers in Germany and France are capturing household replenishment demand through recurring delivery models that bypass conventional retail markup structures.
- Clean-label formulation technology:Advanced natural preservation methods eliminate synthetic additive dependencies, enabling shelf-stable organic products without compromising certification integrity.
Market Restraints
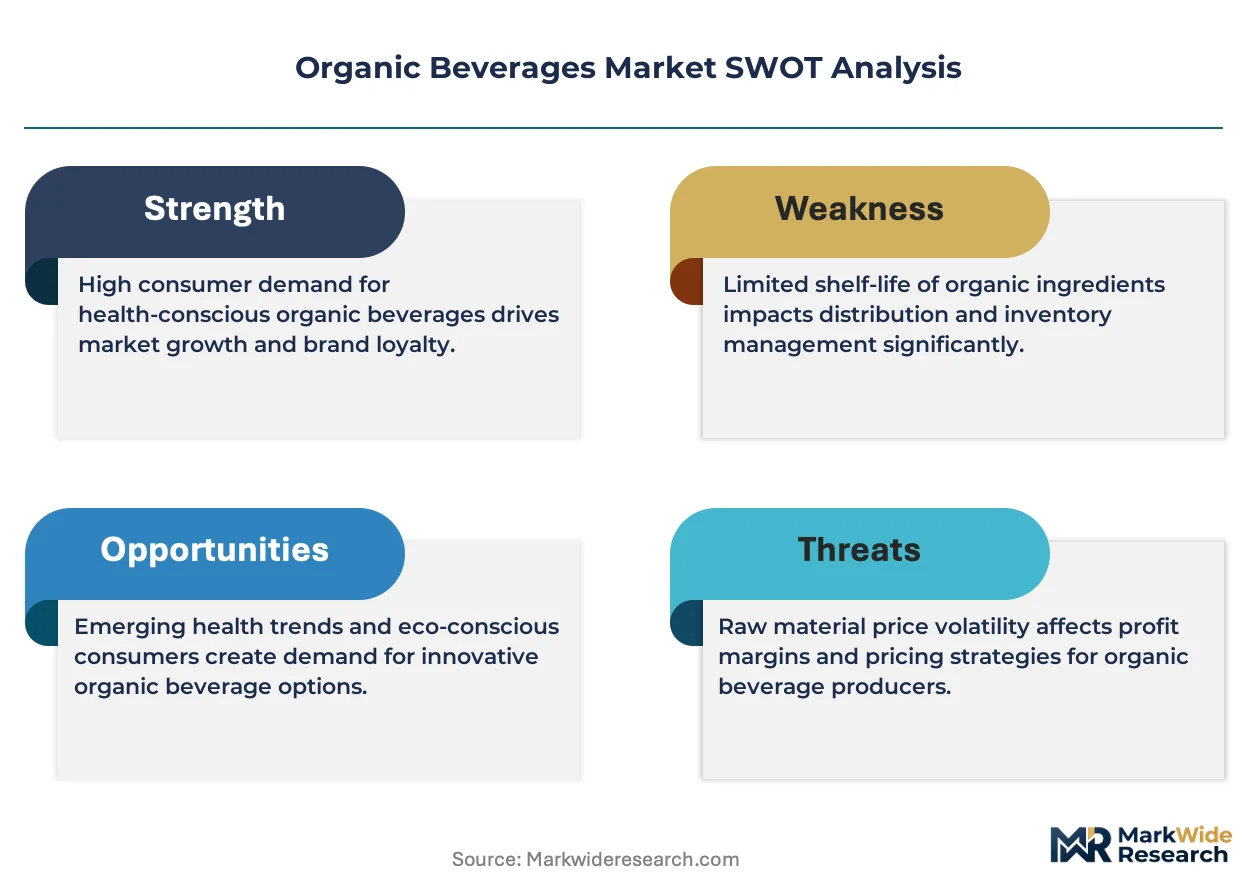
- Organic ingredient supply concentration:Certified organic fruit and botanical sourcing clusters in limited Mediterranean and Latin American growing regions, creating weather-dependent availability constraints.
- EFSA compliance cost escalation:The European Food Safety Authority's evolving residue testing protocols impose laboratory and documentation burdens that disproportionately impact smaller formulation operations.
- Conventional beverage price anchoring:Mass-market soft drink pricing sets consumer reference points that compress organic product margin structures despite input cost differentials.
Strategic Opportunities
- Eastern European market penetration:Poland and Romania exhibit underdeveloped organic retail infrastructure relative to Western European saturation levels, creating first-mover positioning potential.
- Organic soft drink category white space:Younger demographic demand for soda alternatives outpaces current certified product availability, opening formulation innovation territory.
- Packaging sustainability mandates:EU single-use plastic directives are accelerating biodegradable and refillable container adoption that aligns with organic brand positioning.
Industry Challenges
- Multi-jurisdiction certification complexity:USDA Organic and EU organic label equivalency negotiations create dual-compliance burdens for cross-Atlantic product lines.
- Cold chain reconfiguration requirements:Temperature-sensitive organic juice distribution demands infrastructure investment that strains legacy logistics networks.
- Skilled organic agronomist scarcity:Certified organic agricultural expertise remains concentrated in traditional dairy and produce sectors rather than beverage-dedicated supply bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Beverages Market |
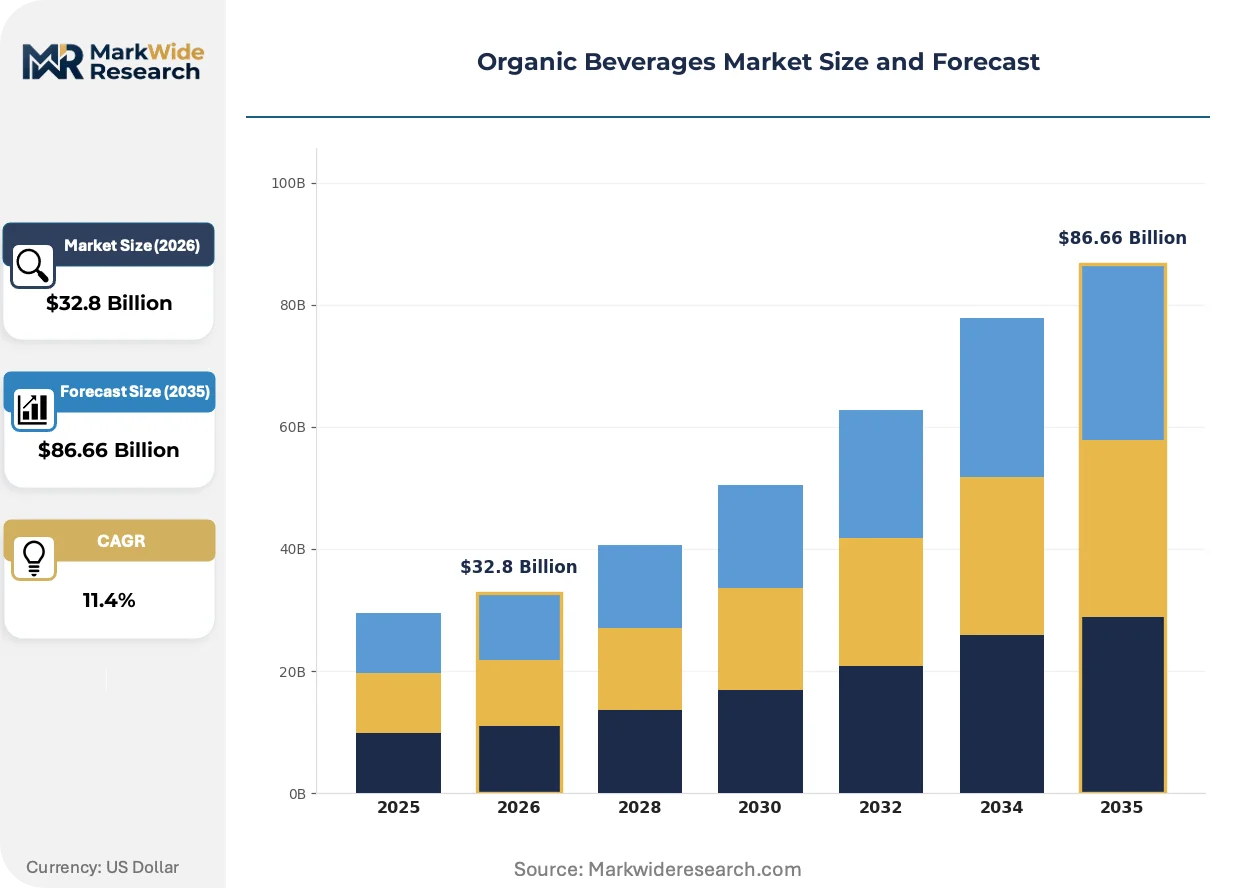
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $86.66 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Juices, Organic Tea, Organic Coffee, Organic Soft Drinks Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Specialty Shops End User: Health-Conscious Consumers, Millennials, Athletes, Families Packaging Type: Bottles, Tetra Packs, Cans, Pouches |
| Companies Covered | Danone S.A., Keurig Dr Pepper Inc., The Coca-Cola Company, Organic Valley, Suja Life LLC, PepsiCo, Inc., The Hain Celestial Group, Inc., Oatly AB, Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Beverages Market Emerging Trajectories
Reformulation priorities are pivoting toward natural preservation systems and transparent supply chain verification as certification standards tighten. Technology deployment and channel restructuring are compressing traditional competitive advantages.
High-pressure processing technology is displacing thermal pasteurization in organic juice manufacturing. Mid-sized organic beverage producers in France and Germany are adopting cold-press HPP systems at accelerating capital deployment rates. This shift is displacing shelf-life extension through chemical preservatives, forcing reformulation teams to rebuild stability profiles around pressure-treated matrices.
EFSA's updated organic labeling enforcement under the EU Green Deal is mandating blockchain-enabled ingredient traceability. The industrial consequence requires upstream technology integration from farm management systems through bottling facilities. Organic tea and juice segments face the steepest compliance curves, with German distributors already deploying batch-level QR verification to preempt regulatory audit exposure.
Subscription-based replenishment models are capturing household purchasing decisions previously routed through supermarket beverage aisles. Direct-to-consumer channels in urban French and German markets are replacing intermittent promotional buying with predictable consumption patterns. This behavioral shift concentrates most visibly among millennial households seeking wellness-oriented beverage portfolios with minimal shopping friction.
Organic Beverages Market Segmentation
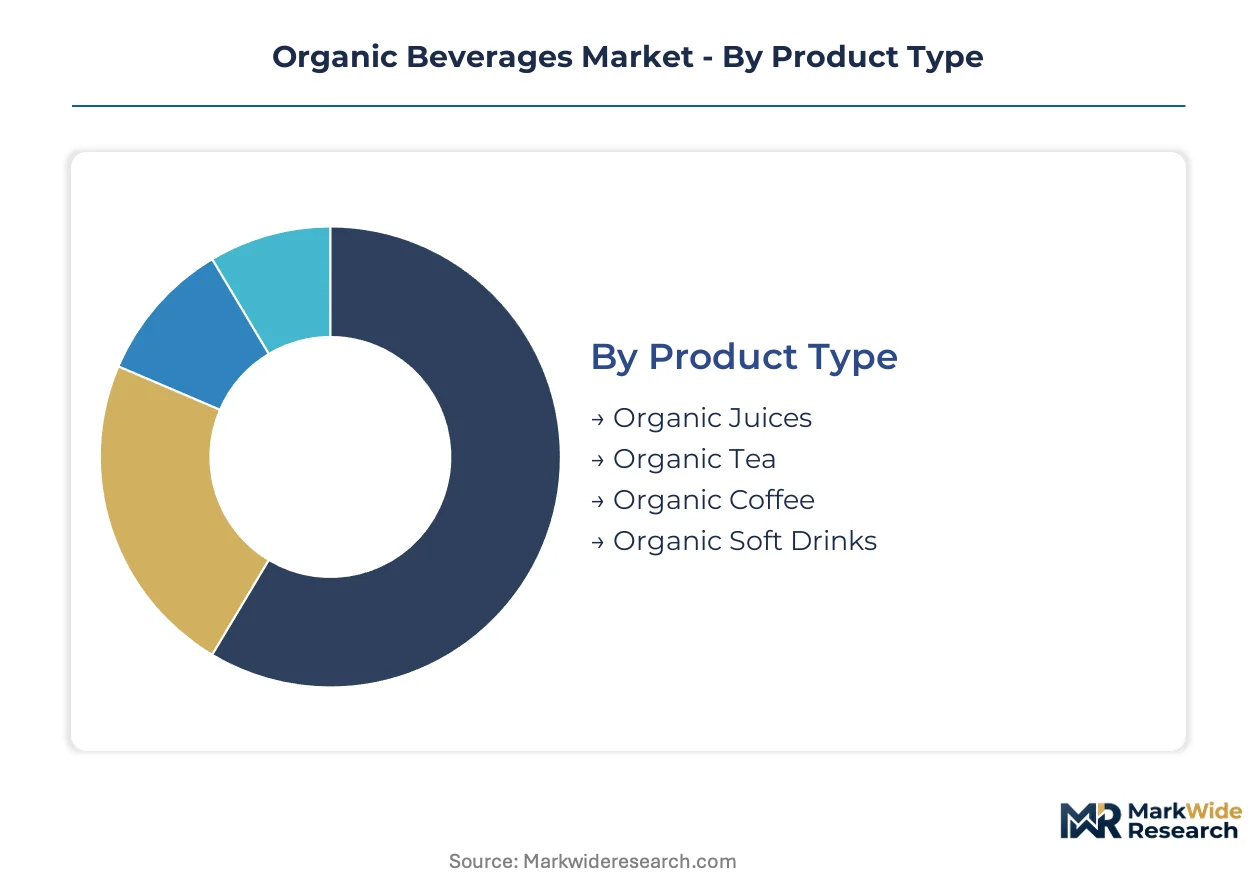
Organic beverage segmentation reveals divergent channel economics and certification requirements across product formats. Distribution infrastructure maturity varies sharply by segment, with refrigerated juice demanding cold-chain investment while shelf-stable tea penetrates conventional retail more easily.
Product Type:
Supermarkets dominate volume for established categories, while online retailers capture emerging formats through subscription mechanics that reduce price sensitivity.
- Organic Juices:Cold-pressed fruit and vegetable blends requiring refrigerated distribution through supermarket and health food channels. German retailers are expanding private-label juice lines as EFSA traceability mandates push suppliers toward captive sourcing relationships.
- Organic Tea:Shelf-stable botanical infusions with longer distribution radius and lower logistics burden. French direct-to-consumer platforms are capturing replenishment demand for premium tea assortments through recurring delivery models.
- Organic Coffee:Roasted bean and ready-to-drink formats concentrated in specialty retail and café channels.
- Organic Soft Drinks:Carbonated and still alternatives to conventional sodas, gaining placement in mainstream supermarkets as younger consumers shift away from synthetic formulations.
By volume, organic juices lead. By growth pace, organic soft drinks are expanding most quickly.
Distribution Channel:
Margin structures concentrate differently across channels, with health food stores commanding premium positioning while supermarkets compete on assortment breadth.
- Supermarkets:Mass-market placement with refrigerated section competition driving promotional intensity. French and German chains are dedicating expanded shelf space to certified organic beverages under EU Green Deal sourcing commitments.
- Online Retailers:Direct-to-subscription models bypassing wholesale markup and capturing household replenishment patterns. Urban millennial demand in Berlin and Paris is accelerating platform investment in personalized wellness assortments.
- Health Food Stores:Curated premium positioning with educated staff driving trial conversion for unfamiliar brands.
- Specialty Shops:Independent retailers focusing on local and artisanal organic producers with limited distribution radius.
Supermarkets move the most units. Online channels show the steepest expansion trajectory.
End User:
Athletes and families exhibit divergent purchase frequencies, with performance-oriented consumption driving premium pricing while household bulk buying emphasizes value tiers.
- Health-Conscious Consumers:Core demographic prioritizing clean-label verification and transparent sourcing across all beverage categories. EFSA certification logos influence purchase decisions in French and German retail environments.
- Millennials:Digital-native cohort shifting purchases toward subscription platforms and wellness-oriented brand portfolios. Urban concentration in Hamburg and Lyon creates cluster effects for direct-to-consumer trial.
- Athletes:Performance-focused segment seeking functional hydration with organic certification.
- Families:Multi-person households purchasing larger formats through supermarket channels with price sensitivity moderated by child-focused health concerns.
Health-conscious consumers anchor volume. Millennials are gaining share fastest.
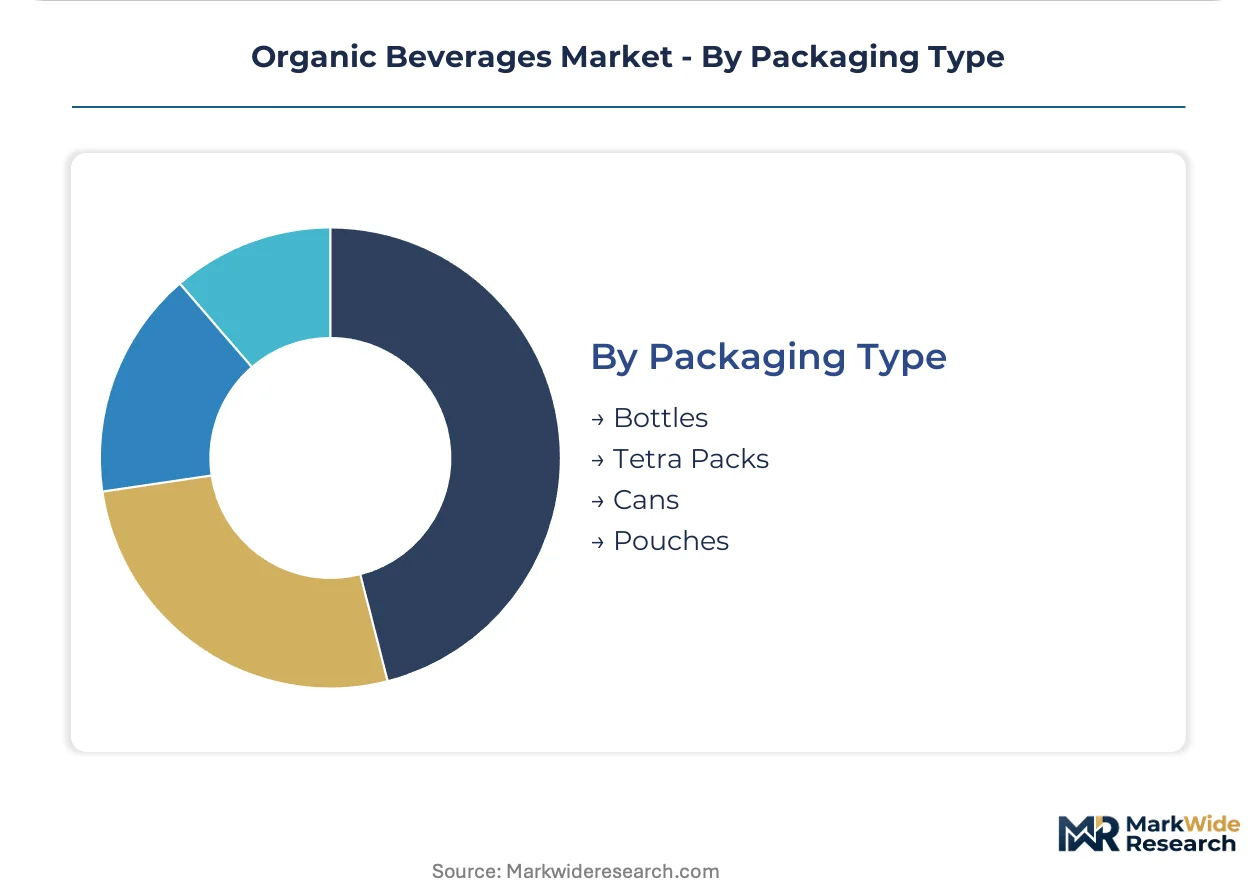
Packaging Type:
EU single-use plastic directives are reconfiguring format economics, with biodegradable alternatives capturing regulatory preference despite higher unit costs.
- Bottles:Glass and recyclable PET formats dominating premium juice and ready-to-drink coffee segments. German deposit-return systems create circular infrastructure advantages for bottle formats.
- Tetra Packs:Aseptic cartons enabling ambient distribution for organic milk alternatives and juices. French retailers are expanding tetra pack placement as shelf-stable assortments reduce cold-chain burden.
- Cans:Aluminum formats gaining traction in organic soft drinks and carbonated teas.
- Pouches:Flexible packaging for single-serve and children's portions with lower shipping weight.
Tetra packs lead by volume. Bottles command the highest growth pace as sustainability credentials intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites Europe's organic beverage import capacity, while Germany's rail-linked distribution hubs extend reach into Central European markets. These logistics assets concentrate regulatory enforcement and retail innovation in adjacent economic zones.
Germany
Millennial households in Hamburg and Berlin drive subscription-platform adoption for organic juice replenishment. EFSA traceability mandates under the EU Green Deal force batch-level QR verification across German distribution networks. Bavarian organic dairy cooperatives are converting processing lines to beverage-dedicated HPP systems.
France
Paris-based direct-to-consumer platforms capture wellness-oriented household purchasing through recurring tea and juice deliveries. ANSM and DGCCRF enforcement of EU organic labeling standards intensifies laboratory documentation requirements for imported botanicals. The Lyon cluster anchors cold-pressed juice manufacturing with Rhône-Alpes fruit sourcing contracts.
United States
USDA Organic certification creates compliance barriers that favor operators with dedicated supply chain auditing capabilities. California's Central Valley concentrates certified organic fruit production for juice processors. Pacific Northwest coffee roasters are extending into ready-to-drink organic formats through Seattle and Portland retail partnerships.
United Kingdom
Health food store chains in London and Manchester curate premium organic beverage assortments with educated staff driving trial conversion. Food Standards Agency alignment with EU organic regulations post-Brexit maintains equivalent residue testing protocols. Scottish oat milk producers leverage domestic grain sourcing for clean-label positioning.
Netherlands
Rotterdam's port infrastructure enables bulk organic ingredient import for European redistribution. The Dutch Food and Consumer Product Safety Authority enforces EU organic certification with accelerated inspection schedules for re-export shipments. Amsterdam-based logistics platforms specialize in temperature-controlled organic beverage warehousing.
Organic Beverages Market Vendor Landscape
Listed leaders compete with private specialists across certification infrastructure and channel access. The market exhibits tiered concentration with multinational beverage conglomerates controlling supermarket shelf space while private organic specialists dominate health food and subscription channels. Three archetypes predominate: dairy-alternative originators leveraging existing organic supply chains, conventional beverage giants extending portfolios through acquisition, and pure-play organic specialists with captive ingredient sourcing. Competitive intensity centers on M&A activity targeting regional organic brands and vertical integration into certified agricultural supply bases.
Within the dairy-alternative tier, Danone S.A. and Oatly AB exemplify operators converting existing organic infrastructure toward beverage-dedicated production. Among conventional beverage conglomerates, PepsiCo, Inc. and The Coca-Cola Company occupy positions scaling organic line extensions through established retail relationships. The Hain Celestial Group, Inc. anchors the pure-play specialist archetype with health food channel concentration.
| Leading Market Players |
|---|
| Danone S.A. |
| Keurig Dr Pepper Inc. |
| The Coca-Cola Company |
| Organic Valley |
| Suja Life LLC |
| PepsiCo, Inc. |
| The Hain Celestial Group, Inc. |
| Oatly AB |
| Nestlé S.A. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between German retailers and Mediterranean fruit cooperatives lock in both organic ingredient supply and price visibility across volatile harvest cycles. These agreements transfer weather-risk exposure to growers while securing volume commitments that stabilize shelf-stock for downstream distribution.
Pricing Analysis
Volume-discount tiering structures separate premium cold-pressed juices from standard tetra-pack formats and economy private-label lines. EFSA certification grade and refrigerated distribution cost create the primary price differentiation drivers. Cost compression in standard-tier products is intensifying because conventional soft drink pricing sets consumer reference points. Families purchasing through supermarket channels exhibit the highest price sensitivity, while health-conscious subscribers to direct-to-consumer platforms show the least.
Supply Chain Analysis
Spain and Italy anchor certified organic citrus and stone fruit production for European juice processors, while Latin American cooperatives supply tropical botanicals for tea formulations. Organic beverage manufacturing draws from concentrated Mediterranean growing regions, temperature-controlled logistics networks, and aseptic packaging facilities. Single-source vulnerability in organic lemon and orange concentrate creates supply chain risk during adverse weather events. Distribution runs through Rotterdam port infrastructure for bulk ingredient import, then rail-linked German hubs for Central European redistribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified organic agronomist capacity trails beverage-dedicated demand across all major supply bases, constraining formulation innovation and traceability compliance simultaneously. This skill scarcity rewards operators who build captive agricultural expertise before competitors secure limited talent pools.
For Market Incumbents: Compound traceability infrastructure advantages by deploying blockchain-enabled batch verification ahead of EFSA enforcement deadlines. Deepen backward integration into Rhône-Alpes and Andalusian fruit sourcing contracts to preempt supply competition from emerging organic soft drink entrants. Channel control through exclusive health food store partnerships remains a defensible lever against supermarket private-label erosion.
For New Entrants and Emerging Players: Subscription-platform personalization for millennial households in underpenetrated Eastern European cities offers the most penetrable white space. Direct-to-consumer tea assortments bypass incumbent shelf-space dominance in Warsaw and Bucharest. A sustainability-first go-to-market angle aligns with EU single-use plastic directives while differentiating against legacy packaging formats.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-subscription specialists with captive sourcing relationships and established urban millennial cohorts. Over the projection horizon, vertically integrated mid-cap operators with HPP processing capabilities and Mediterranean supply contracts represent the optimal acquisition target archetype. Watch for inflection when EFSA residue-testing protocol changes trigger forced reformulation costs that strain smaller competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Press HPP Capacity Expansion | High-pressure processing adoption by French and German mid-tier producers displaces thermal pasteurization and synthetic preservatives. |
| Blockchain Traceability Integration | Farm-to-bottle QR verification systems preempt EFSA audit exposure and satisfy EU Green Deal transparency mandates. |
| Direct-to-Consumer Platform Launch | Subscription models in Berlin and Paris capture recurring replenishment demand while bypassing supermarket promotional cycles. |
| Eastern European Distribution Buildout | First-mover positioning in Poland and Romania exploits underdeveloped organic retail infrastructure relative to Western saturation. |
| Biodegradable Packaging Transition | EU single-use plastic directives accelerate compostable bottle and refillable container adoption that reinforces brand positioning. |
Methodological Framework
Operator-level perspectives from organic beverage brand managers, EFSA compliance officers at German distributors, Mediterranean cooperative agronomists, and French direct-to-consumer platform founders anchored the qualitative base. Primary interview insights combined with secondary validation from EU organic certification registries, customs import data for concentrated juices, Nielsen retail audit figures, and SEC filings from listed beverage conglomerates. Bottom-up volume modeling and top-down value triangulation cross-checked segment estimates across the analysis window.
Sensitivity analysis tested forecast robustness against organic ingredient price volatility and regulatory tightening scenarios. Segmentation dimensions modeled include product format, distribution channel, end-user archetype, and packaging type alongside geographic regulatory cluster variations. CAGRs derived from fitted trend extrapolation adjusted for identified inflection drivers including EU Green Deal implementation pace and subscription-platform penetration rates. Forecast inputs incorporated EFSA enforcement intensity indices and cold-chain infrastructure investment flows.
Material uncertainties — harvest yield variability, equivalency negotiation outcomes between USDA Organic and EU organic frameworks, and consumer willingness-to-pay erosion — sit outside the modeled envelope. Forecasts reflect assumptions about certification integrity maintenance and logistics cost trajectories. Recalibration cycles align with material shifts in EFSA testing protocols and EU packaging directive enforcement schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Organic Fast Food Market
Organic Food and Beverages
South Africa Organic Food Market
Organic Food and Beverages
Global Organic Chocolate Spreads Market
Organic Food and Beverages
Non-GMO Food Market
Organic Food and Beverages
Global Organic Coconut Water Market
Organic Food and Beverages
Brazil Organic Food Market
Organic Food and Beverages
Organic Fruit Powder Market
Organic Food and Beverages
Natural Food and Drinks Market
Organic Food and Beverages
Canada Organic Food Market
Organic Food and Beverages
Organic Goji Berry Market
Organic Food and Beverages
Organic Soda Market
Organic Food and Beverages
Spain Organic Food Market
Organic Food and Beverages
Organic Yeast Market
Organic Food and Beverages
United States Organic Food Market
Organic Food and Beverages
Organic Stevia Market
Organic Food and Beverages
Australia Organic Beverages Market