
 Organic Coating Market | 2026-2036
Organic Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Coating Market Outlook
Modular coating service bundles that combine application equipment with maintenance contracts is recalibrating how industrial buyers evaluate total cost of ownership. PPG Industries leverages its captive distribution network to anchor long-term supply agreements with automotive OEMs. Akzo Nobel competes through specialized marine and protective lines that sustain premium positioning in corrosion-intensive environments. BASF differentiates via backward integration into resin production, controlling raw material quality and supply security for high-performance formulations.
Organic coatings are polymer-based protective films, typically 25–150 microns dry-film thickness, applied to substrates through curing mechanisms that form barrier layers against corrosion, weathering, and chemical exposure; their primary purpose is extending asset life while enabling color and finish customization for commercial and industrial products. Water-based coatings now lead volume in architectural applications where EPA VOC limits and EU solvent-emission directives have compressed solvent-based alternatives into specialty industrial niches. Powder coatings represent the fastest-growing technology segment, driven by near-zero volatile organic compound output and rising electrostatic spraying adoption in automotive and furniture manufacturing. UV-cured systems command concentrated margin pools in packaging and consumer goods where line-speed requirements and energy-cure efficiency offset higher capital investment in mercury or LED lamp systems.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants and the EU REACH framework restrict solvent content and mandate hazard communication, directly shaping reformulation roadmaps and product registration costs for suppliers seeking market access in North America and Europe. China's Ministry of Ecology and Environment enforces GB standards on volatile organic compound emissions from coating operations, creating compliance thresholds that favor domestic water-based and powder coating producers while raising barriers for imported solvent-borne formulations. Stakeholders must monitor divergence between regional chemical restriction schedules and assess whether localized production or technology licensing offers the more defensible path to sustained participation across major demand centers.
Market Dynamics
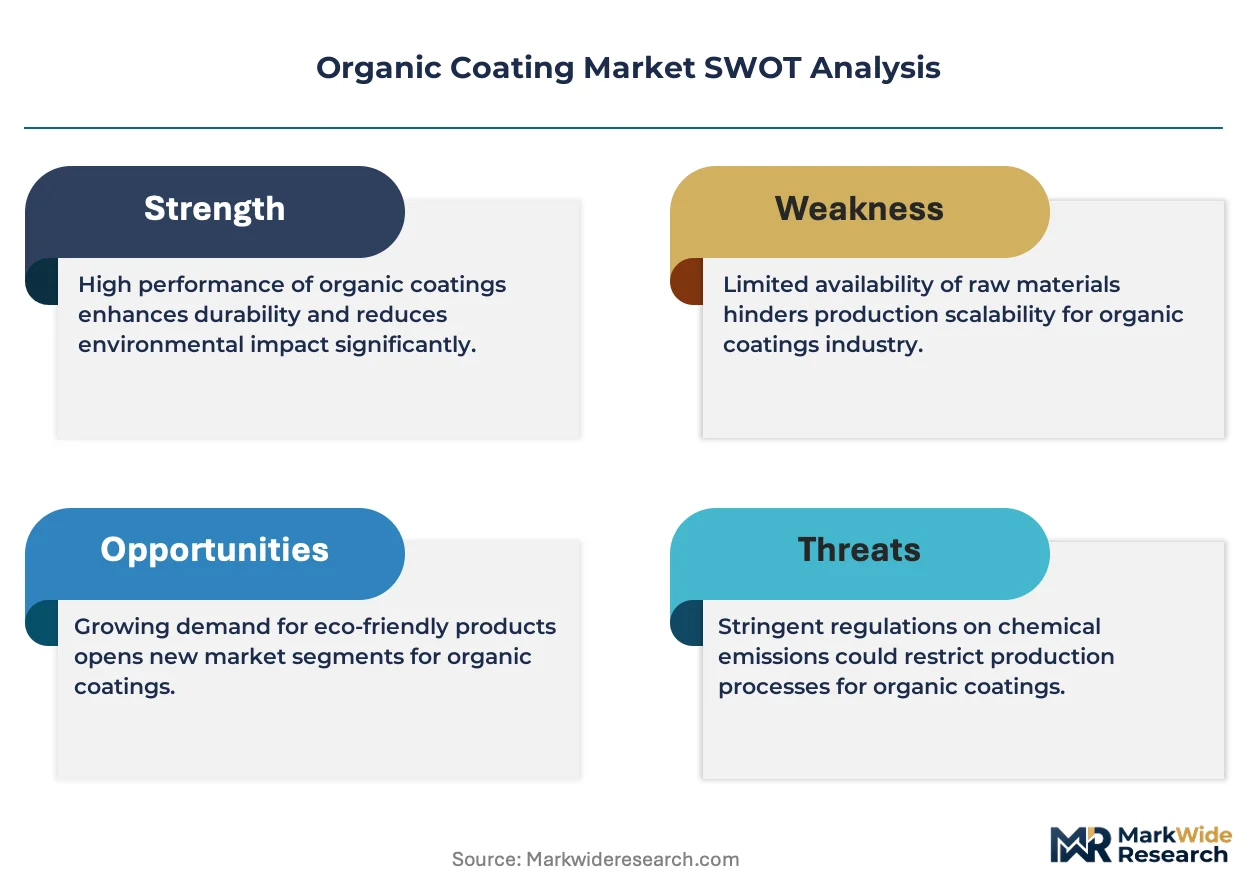
Water-based and powder coating technologies are compressing solvent-borne volumes as automotive OEMs and construction material suppliers face tightening volatile organic compound limits across major manufacturing jurisdictions.
Growth Catalysts
- REACH solvent restrictions:EU manufacturers must reformulate coatings to meet hazard communication and emission thresholds, accelerating water-based system procurement.
- Automotive electrification:Battery enclosure and electric vehicle body panel production requires corrosion-resistant coatings with thermal management properties.
- China GB standards enforcement:Domestic coating operations face volatile organic compound emission ceilings that favor local water-based and powder producers.
Market Restraints
- Petrochemical feedstock volatility:Epoxy and acrylic resin prices fluctuate with crude oil derivatives, compressing formulation margins.
- Application equipment capex:Electrostatic powder lines and UV-cure lamp systems require capital outlays that deter small-batch metal fabricators.
- Solvent-borne niche persistence:Marine and aerospace sectors still demand high-performance solvent systems where water-based alternatives fail durability tests.
Strategic Opportunities
- India construction boom:Infrastructure and residential building expansion creates untapped demand for architectural coatings with antimicrobial and self-cleaning properties.
- UV-cure packaging convergence:Mercury and LED lamp systems combined with high-speed flexographic printing lines enable instant-dry decorative finishes.
- US Inflation Reduction Act:Domestic manufacturing incentives for clean technology production extend to coating operations serving renewable energy component suppliers.
Industry Challenges
- Formulation chemist scarcity:Expertise in hybrid water-borne urethane and fluoropolymer systems concentrates at established suppliers, limiting new entrant R&D velocity.
- Multi-jurisdiction registration timelines:Separate EPA, REACH, and NMPA substance notifications delay product launch windows by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Coating Market |
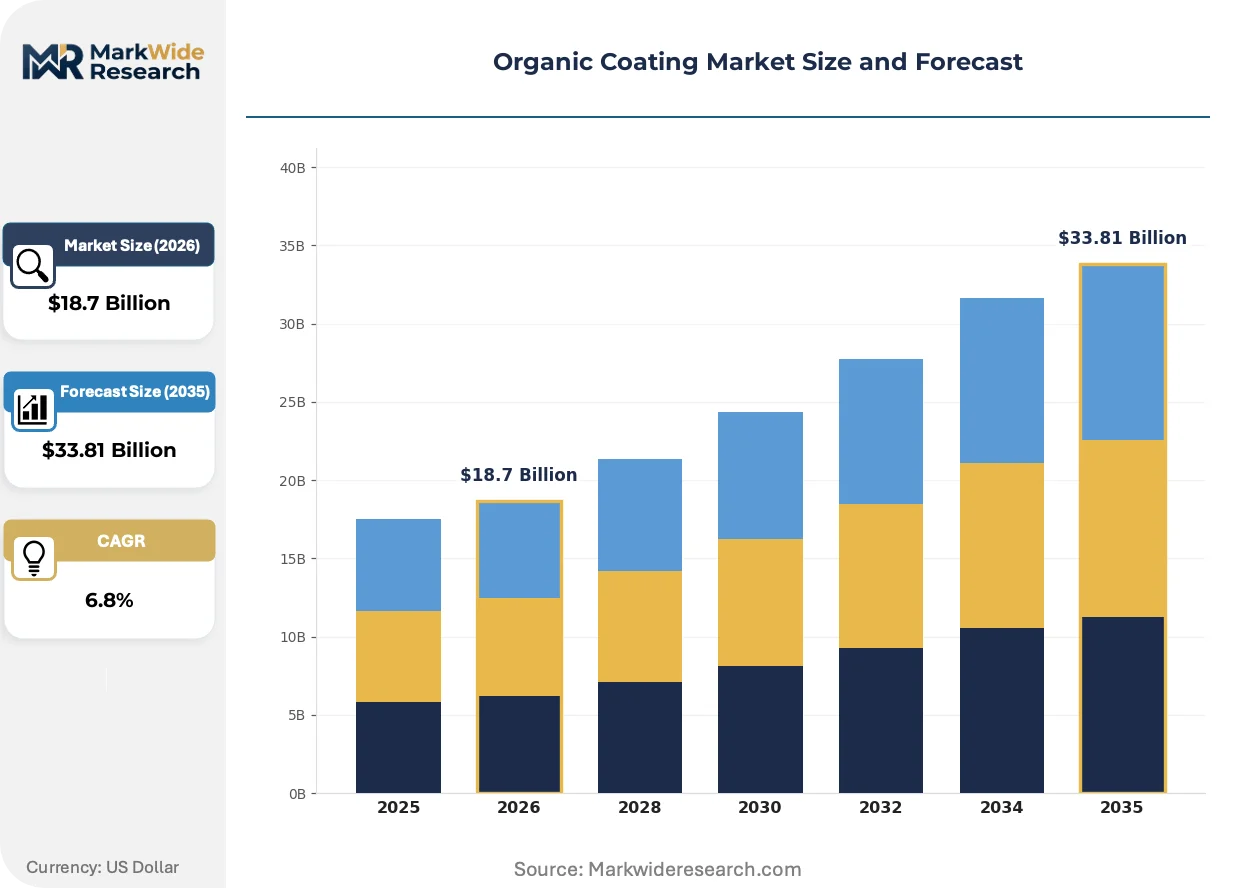
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based Coatings, Solvent-Based Coatings, Powder Coatings, UV-Cured Coatings End User: Automotive, Construction, Aerospace, Consumer Goods Application: Architectural, Industrial, Furniture, Packaging Technology: Electrostatic Spraying, Roller Coating, Spray Coating, Dipping |
| Companies Covered | The Sherwin-Williams Company, PPG Industries, Akzo Nobel, Axalta Coating Systems, Jotun, Hempel, BASF, Asian Paints, RPM International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Coating Market Strategic Shifts
Coating chemistry is pivoting toward energy-cure and near-zero-emission systems as regulatory pressure intersects with automotive and packaging line-speed requirements.
Photoinitiator-advanced UV-cured coatings is electrifying decorative and protective applications through instant polymerization under mercury or LED lamp arrays. Food packaging converters and consumer electronics housing manufacturers are adopting these systems at accelerating rates. The technology is electrifying margin structures by eliminating thermal oven footprints and enabling just-in-time production workflows.
EPA National Emission Standards for Hazardous Air Pollutants enforcement is forcing automotive assembly plants and coil coating operations to document solvent capture efficiency. Facilities in Michigan, Ohio, and Tennessee face inspection schedules that compress allowable coating application windows. Metal building component suppliers are responding with accelerated powder line conversions and infrared-cure auxiliary systems.
Buyers are unbundling coating supply from turnkey application service contracts that bundle equipment, maintenance, and material provisioning. Industrial purchasers in Germany and the United States now evaluate total cost of ownership across 5-7 year horizons rather than per-liter pricing. This pattern is most visible in automotive tier-one supplier networks where procurement teams consolidate vendor relationships to reduce qualification overhead.
Organic Coating Market Segmentation
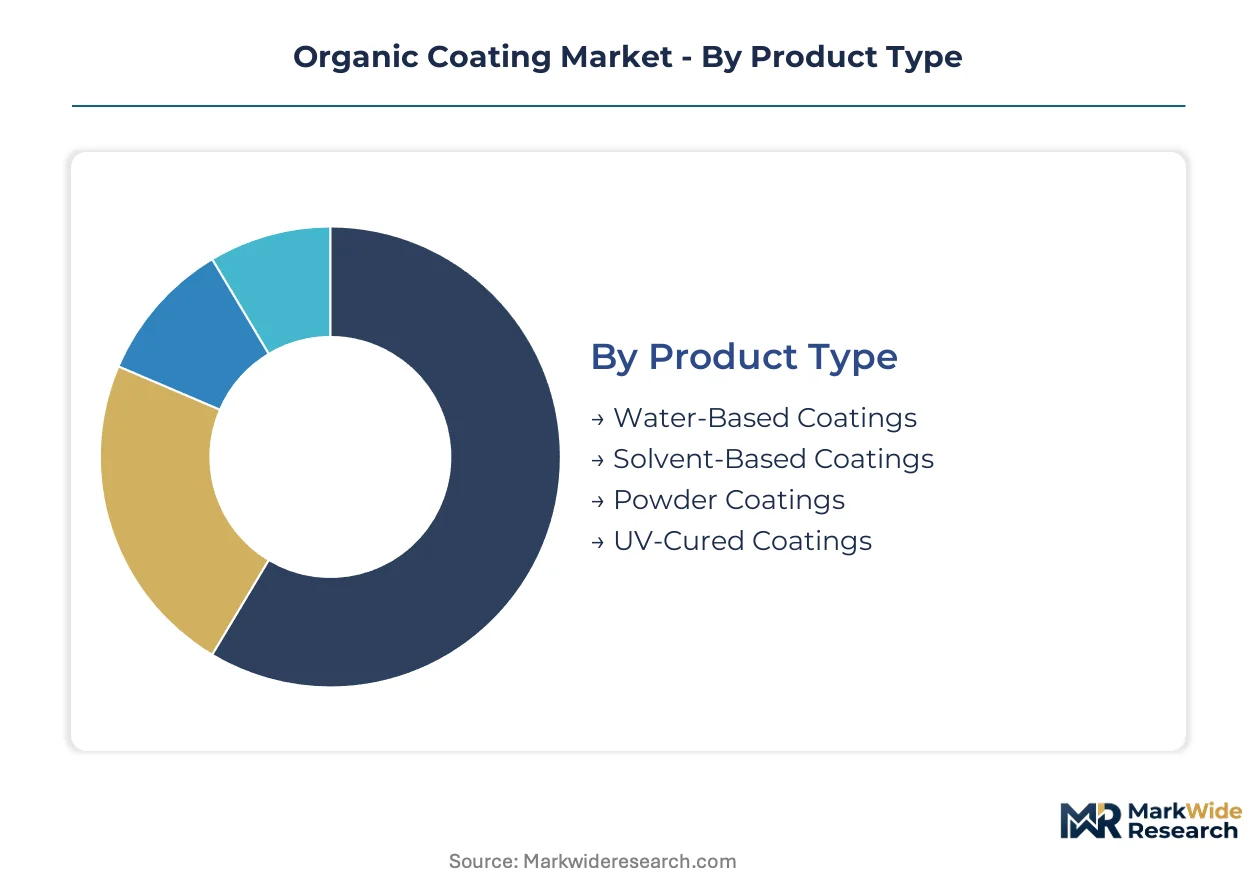
Organic coating suppliers configure formulation portfolios around distinct performance specifications, regulatory thresholds, and application equipment requirements. Each segmentation dimension reveals divergent margin structures and customer loyalty patterns that shape competitive positioning across automotive, construction, and industrial end-uses.
Product Type:
The customization-vs-standardization spectrum spans from commodity architectural emulsions to precision-engineered UV-cured systems with photoinitiator optimization.
- Water-Based Coatings:Acrylic and polyurethane dispersions with 5-15% co-solvent content dominate architectural specifications where EPA VOC limits and EU solvent-emission directives have compressed solvent-borne alternatives. Demand concentrates in residential and commercial construction across Germany and the United States where green building certification requirements favor low-emission formulations.
- Powder Coatings:Thermoset epoxy and polyester formulations applied through electrostatic charging achieve near-zero volatile organic compound output with 40-60 micron film builds. Automotive tier-one suppliers in Michigan and Tennessee are converting metal finishing lines to accommodate battery enclosure and electric vehicle body panel coating requirements.
- Solvent-Based Coatings:High-solids alkyd and fluoropolymer systems retain marine and aerospace applications where water-based alternatives fail salt-spray and flexibility specifications.
- UV-Cured Coatings:Photoinitiator-acrylate oligomer blends polymerize instantly under mercury or LED lamp arrays for food packaging converters and consumer electronics housing manufacturers.
Leading the category by volume: Water-Based Coatings. Growing fastest: Powder Coatings.
End User:
Cost tier stratification separates specification-grade automotive OEM contracts from price-sensitive construction material procurement.
- Automotive:OEM assembly plants and tier-one suppliers demand corrosion-resistant coatings with thermal management properties for battery enclosures and electric vehicle architectures. Procurement teams in Germany, the United States, and China evaluate total cost of ownership across 5-7 year supply agreements rather than per-liter pricing.
- Construction:Residential and commercial building material suppliers drive architectural coating volumes with antimicrobial and self-cleaning functional specifications. Infrastructure expansion in India is creating untapped demand for durable exterior finishes.
- Aerospace:Airframe manufacturers and MRO facilities specify high-performance solvent-borne systems where qualification timelines and durability testing create substantial supplier switching costs.
- Consumer Goods:Electronics housing and appliance manufacturers favor UV-cured decorative finishes with instant-dry properties for high-speed production workflows.
Highest absolute spend: Automotive. Steepest expansion trajectory: Construction.
Application:
Application method determines equipment capital requirements and line-speed economics across batch and continuous processing environments.
- Architectural:Exterior wall and roof coating specifications emphasize weathering resistance and color retention over 15-20 year service lives.
- Industrial:Metal fabrication and machinery finishing requires chemical-resistant barrier films for factory and process equipment.
- Furniture:Wood and metal furniture manufacturers combine decorative appearance with scratch-resistant surface properties.
- Packaging:Food and beverage converters demand instant-cure systems with migration-compliant formulations for direct food contact.
Widest formulation variety: Industrial. Tightest regulatory scrutiny: Packaging.
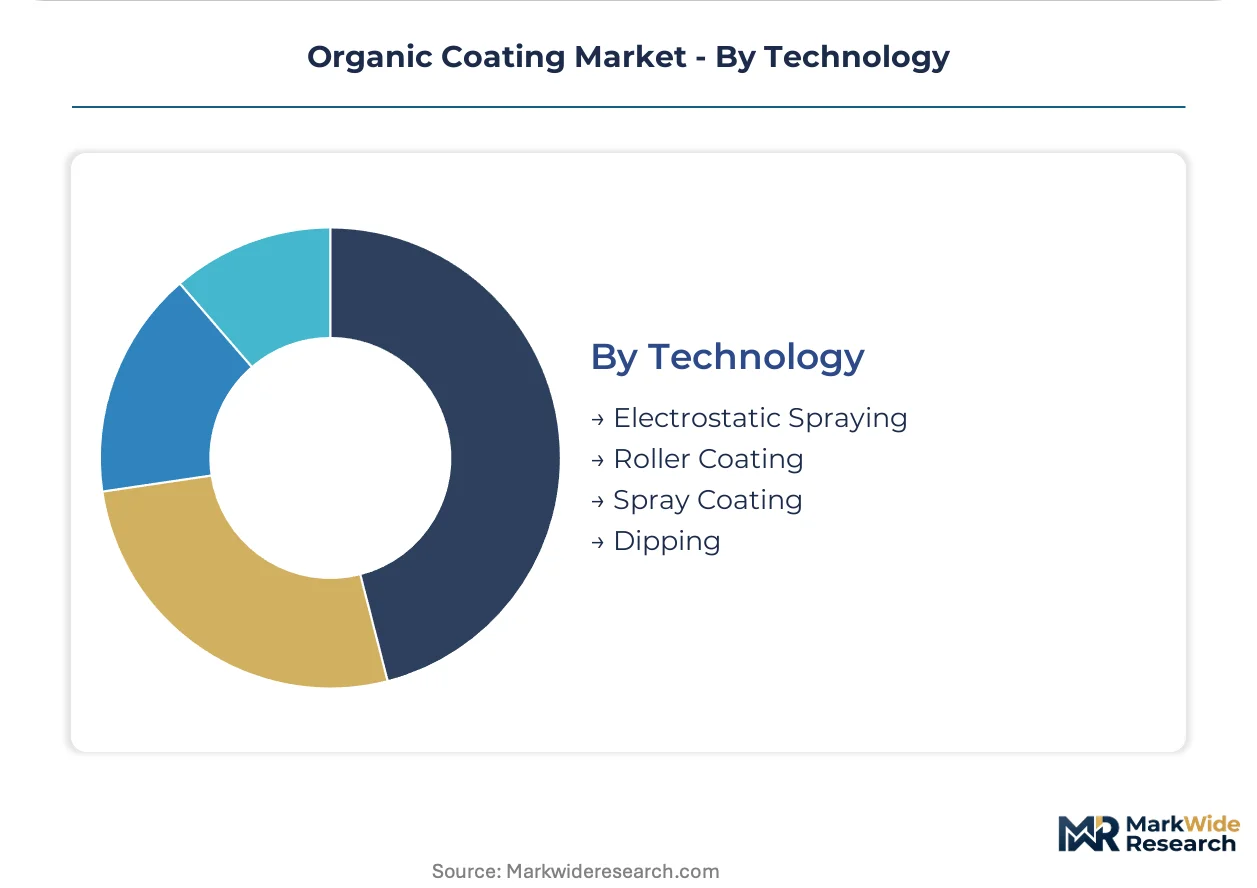
Technology:
Volume scale separates high-throughput continuous coil coating from job-shop batch processing with frequent color changes.
- Electrostatic Spraying:Charged particle deposition achieves 95%+ transfer efficiency for automotive and appliance manufacturing with automated reciprocating equipment.
- Roller Coating:Continuous flat-stock processing serves metal building component suppliers with uniform film thickness across coil coating lines.
- Spray Coating:Manual and robotic air-atomized application accommodates complex geometries and low-volume custom finishing.
- Dipping:Immersion coating provides complete coverage for small parts and fasteners with uniform edge protection.
Dominant in automotive: Electrostatic Spraying. Fastest equipment conversion: Roller Coating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in China, Germany, and the United States where automotive assembly and construction material manufacturing drive consumption. Import-dependent markets in Southeast Asia and Latin America absorb surplus volumes from these manufacturing hubs. Regulatory divergence across EPA, REACH, and GB standards fragments formulation requirements by destination.
United States
Automotive OEMs in Michigan, Ohio, and Tennessee are converting metal finishing lines to powder systems for battery enclosure production. EPA National Emission Standards for Hazardous Air Pollutants enforcement compresses allowable coating application windows at assembly plants. Metal building component suppliers in the Southeast are accelerating infrared-cure auxiliary system adoption.
Germany
Automotive tier-one suppliers evaluate total cost of ownership across 5-7 year supply agreements rather than per-liter pricing. REACH solvent restrictions force reformulation toward water-based systems with hazard communication compliance. Industrial coating operations in North Rhine-Westphalia and Bavaria anchor procurement consolidation trends across European supplier networks.
China
Domestic coating operations face volatile organic compound emission ceilings under Ministry of Ecology and Environment GB standards. Battery and electric vehicle production in the Yangtze River Delta and Pearl River Delta generates specialized corrosion-resistant coating demand. Local water-based and powder coating producers capture share as imported solvent-borne formulations face rising compliance barriers.
India
Infrastructure and residential building expansion in Maharashtra and Gujarat creates demand for architectural coatings with antimicrobial and self-cleaning properties. Bureau of Indian Standards certification requirements shape product registration timelines for foreign suppliers. Construction material suppliers in Delhi-NCR and Bangalore are consolidating vendor relationships to reduce qualification overhead.
Japan
Consumer electronics housing manufacturers in Kanto and Kansai regions favor UV-cured decorative finishes for high-speed production workflows. METI energy efficiency guidelines accelerate mercury-to-LED lamp system conversions in packaging converter operations. Precision coating specialists in Nagoya industrial corridors maintain qualification-driven supplier switching costs.
Organic Coating Market Competitive Environment
The competitive structure tilts toward diversified chemical conglomerates with captive resin production and specialized coating formulators with deep end-use expertise. Tier-one automotive supply agreements favor suppliers with integrated distribution networks and multi-year service bundling capabilities. Three archetypes dominate: backward-integrated resin producers, application-technology specialists, and regional formulation leaders. Consolidation proceeds through strategic partnerships for technology licensing and geographic expansion through distribution acquisition.
Among diversified chemical conglomerates, BASF anchors the backward-integrated archetype through in-house resin production. PPG Industries and Akzo Nobel occupy positions spanning automotive OEM supply and specialized industrial lines. These three represent the scale-driven tier where formulation breadth and regulatory compliance infrastructure create qualification barriers.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| PPG Industries |
| Akzo Nobel |
| Axalta Coating Systems |
| Jotun |
| Hempel |
| BASF |
| Asian Paints |
| RPM International |
| Others |
Value Chain & Pricing Dynamics
Performance-grade certification divergence between automotive OEM specifications and commodity architectural coatings manifests in both pricing premiums and supply chain complexity. Tier-one automotive contracts command value-based pricing anchored to thermal management and corrosion resistance benchmarks, while construction-grade water-based emulsions compete on volume scale with compressed margins. This bifurcation drives supplier consolidation toward captive resin production or specialized formulation expertise.
Pricing Analysis
Cost-down pressure on commodity architectural tiers accelerates because Chinese and Indian domestic producers expand water-based capacity under GB and BIS compliance thresholds. Three-tier pricing structure across premium, standard, and economy levels separates fluoropolymer automotive systems from mid-grade powder coatings and bulk construction emulsions. Price differentiation hinges on certification grade (REACH registration tier) and volume scale, with automotive OEMs least price-sensitive due to qualification switching costs. Margin tightening in solvent-borne marine specialties reflects feedstock volatility and shrinking addressable market.
Supply Chain Analysis
REACH and EPA registration qualification gates fragment supplier eligibility across North American and European demand centers. Resin production concentrates in China, Germany, and the United States, with epoxy and acrylic feedstock supply anchored in petrochemical corridors near Rotterdam, Houston, and Ningbo. Raw material dependencies on crude oil derivatives, titanium dioxide pigments, and photoinitiator chemicals expose formulations to commodity price volatility. Distribution runs through captive automotive OEM networks and independent architectural coating distributors serving regional construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic coating market sits in a technology-transition phase as powder and UV-cured systems displace solvent-borne chemistries across automotive and packaging end-uses. This shift rewards suppliers with energy-cure equipment integration and near-zero-emission formulation portfolios.
For Market Incumbents: Deepen backward integration into specialty resin production to defend margin position against petrochemical feedstock volatility. Incumbent suppliers should consolidate qualification-driven automotive OEM relationships through bundled equipment-service contracts, while accelerating mercury-to-LED lamp system partnerships for packaging converter customers.
For New Entrants and Emerging Players: Small-batch metal fabricators in India and Southeast Asia represent an underserved buyer archetype with limited access to powder line capital. New entrants should target this segment with UV-cure retrofit kits and toll-coating service models, leveraging regulatory lag in GB standards enforcement to establish local formulation presence before compliance barriers harden.
For Investors and Strategic Acquirers: Re-rating potential sits with application-technology specialists given accelerating automotive electrification coating requirements. Investors should monitor battery enclosure production ramp rates as the inflection signal for specialized corrosion-resistant coating demand. Acquisition targets include regional powder coating formulators with automotive tier-two qualification and UV-cure equipment integration capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | BASF's captive epoxy supply secures formulation margin against petrochemical volatility. |
| Long-term Supply Agreement | PPG's automotive OEM contracts anchor volume through electrification transition. |
| Green Manufacturing Transition | Water-based system conversion aligns with EPA NESHAP enforcement timelines. |
| Joint Venture | Regional partnerships in India bypass BIS certification barriers for foreign entrants. |
| Technology Licensing | UV-cure photoinitiator patents enable packaging converter line-speed advantages. |
Study Parameters
Trade databases, SEC 10-K filings, and ECHA registration records formed the secondary backbone, cross-referenced with primary interviews involving coating formulators, automotive tier-one procurement leads, plant managers at resin production facilities, and distribution channel partners. Bottom-up volume estimates from end-use consumption patterns and top-down value reconciliation against customs and trade data ensured triangulation integrity across the analysis window.
Bottom-up modeling aggregated segment-level demand across product type, end-use industry, application method, and regional production hub dimensions. Top-down validation tested aggregate market scale against petrochemical feedstock consumption patterns and coating equipment installation rates. CAGRs derived from regression analysis of historical volume trends and regulatory-driven technology substitution curves, with automotive electrification content-per-vehicle and construction green-building certification adoption as key forecast inputs.
Revisions become necessary when REACH substance restriction schedules accelerate, GB standards enforcement tightens beyond current trajectories, or automotive battery enclosure designs shift to alternative corrosion protection methods. Forecasts reflect documented assumptions about regulatory compliance timelines and technology substitution elasticities. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
2,6-Dichloro Aniline Market
Organic Chemicals
North America Phenol Market
Organic Chemicals
Para-Tert-Octylphenol (POTP) Market
Organic Chemicals
Crotonic Acid Market
Organic Chemicals
Nonylphenol Market
Organic Chemicals
Cyclic Ketones Market
Organic Chemicals
Anthracene Market
Organic Chemicals
Terephthalic Aldehyde Market
Organic Chemicals
DMDM Hydantoin Market
Organic Chemicals
Phenolic Board Market
Organic Chemicals
Acrylonitrile Market
Organic Chemicals
Organic Rheological Modifiers Market
Organic Chemicals
Synthetic and Bio-Based Aniline Market
Organic Chemicals
Global Benzoic Acid Market
Organic Chemicals
Europe Lactic Acid Market
Organic Chemicals
Cycloalkanes Market