
 Cycloalkanes Market | 2026-2036
Cycloalkanes Market Size, Share, and Industry Trends Forecast 2026-2036
Cycloalkanes Market Outlook
Pharmaceutical-grade cycloalkane specifications are unwinding legacy industrial-grade margins as buyers enforce tighter impurity thresholds. ExxonMobil Corporation leverages its integrated Gulf Coast refining complex to supply high-purity cyclohexane streams. SABIC anchors Middle Eastern production with advantaged feedstock costs from Saudi ethane crackers. INEOS Group specializes in European cyclopentane output for blowing-agent applications.
Cycloalkanes are saturated cyclic hydrocarbons with general formula CnH2n, typically produced through catalytic hydrogenation of aromatic precursors or fractional distillation of naphtha streams, serving primarily as non-polar solvents, chemical intermediates, and refrigerant blowing agents. Cyclohexane dominates value generation due to its role as adipic acid and caprolactam precursor for nylon manufacturing, while cyclopentane is displacing older refrigerant formulations under environmental protocols. Chemical feedstock applications command the deepest margin pools, with solvent demand fragmenting across pharmaceutical and electronics cleaning end users.
EPA regulates cycloalkane emissions under Clean Air Act provisions for volatile organic compounds, while EMA and FDA impose residual solvent limits in pharmaceutical applications through ICH Q3C guidance. ECHA REACH registration requirements enforce comprehensive toxicological dossiers for cyclohexane and cyclopentane commercial volumes above one tonne annually. Stakeholders must monitor evolving F-Gas Regulation phase-down schedules and state-level low-GWP refrigerant mandates to anticipate cyclopentane substitution economics.
Market Dynamics
Pharmaceutical manufacturers enforce tighter impurity thresholds on cycloalkane suppliers, compressing legacy industrial-grade margins while rewarding integrated refiners with adipic acid and caprolactam feedstock capabilities.
Growth Catalysts
- EU F-Gas Regulation phase-down:The European mandate accelerates cyclopentane substitution for high-GWP refrigerant blowing agents in appliance manufacturing.
- Nylon 6,6 polymerization demand:Textile and automotive fiber producers expand cyclohexane consumption as adipic acid precursor for engineering plastics.
- China hydrogenation capacity expansion:State-backed petrochemical complexes scale catalytic reforming units for domestic chemical manufacturing feedstock security.
Market Restraints
- Naphtha feedstock volatility:Crude-linked aromatic precursor costs swing cycloalkane production economics without corresponding price pass-through mechanisms.
- REACH registration burden:ECHA toxicological dossier requirements for cyclohexane and cyclopentane volumes above one tonne annually impose compliance overhead on specialty chemical distributors.
- Fluorinated refrigerant incumbent defense:HFO-1234yf and HFO-1336mzz-Z maintain technical performance advantages in ultra-low temperature applications despite higher GWP.
Strategic Opportunities
- India pharmaceutical excipient qualification:CDSCO-aligned ICH Q3C residual solvent compliance opens import substitution for European and US cycloalkane suppliers.
- Electronics cleaning grade specification:Semiconductor wafer processing protocols demand sub-ppm impurity cyclohexane for photoresist stripping applications.
- Carbon border adjustment mechanism:EU CBAM implementation favors low-carbon intensity hydrogenation routes from natural gas-based feedstock regions.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA and EMA ICH Q3C qualification protocols extend 18-24 months for new cycloalkane supply sources.
- Catalytic reforming catalyst replacement cycles:Platinum-rhenium reformer catalyst regeneration requires scheduled downtime that disrupts continuous adipic acid feedstock supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cycloalkanes Market |
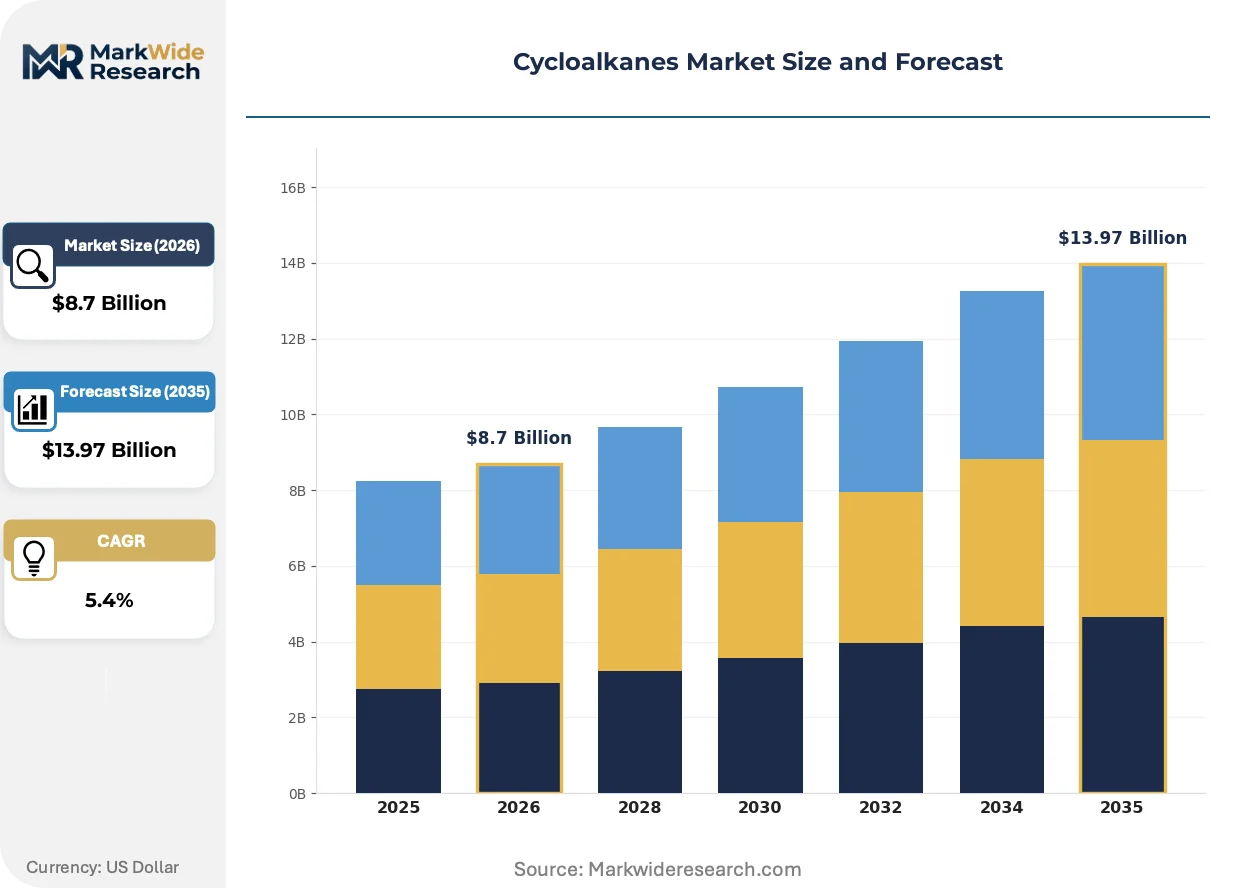
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cyclopentane, Cyclohexane, Cycloheptane, Cyclooctane Application: Solvent, Fuel, Chemical Feedstock, Refrigerant End User: Automotive, Aerospace, Pharmaceuticals, Chemical Manufacturing Technology: Hydrogenation, Isomerization, Distillation, Extraction |
| Companies Covered | SABIC, Royal Dutch Shell, ExxonMobil Corporation, China National Petroleum Corporation, TotalEnergies SE, INEOS Group, Reliance Industries Limited, Mitsubishi Chemical Corporation, Chevron Phillips Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cycloalkanes Market Strategic Shifts
Membrane separation and adsorptive purification technologies are compressing traditional fractional distillation economics while regulatory phase-downs reconfigure refrigerant blowing agent chemistry.
Advanced zeolitic adsorption systems for trace aromatic removal are supplanting multi-stage extractive distillation in high-purity cyclohexane production. Pharmaceutical and electronics-grade buyers adopt these units to meet sub-100 ppm benzene specifications without energy-intensive thermal separation. The shift enables smaller-scale regional producers to compete with integrated Gulf Coast refiners on purity metrics rather than volume scale.
EPA Clean Air Act volatile organic compound enforcement tightens storage and handling requirements for cycloalkane solvents in coatings and adhesive applications. Industrial end-users retrofit vapor recovery systems and floating roof tanks to maintain operating permits. The compliance burden concentrates demand among larger chemical distributors with environmental engineering capabilities.
Specification-driven procurement now dominates pharmaceutical excipient sourcing, with buyers auditing hydrogenation catalyst provenance and naphtha origin rather than accepting standard industrial grades. Contract manufacturers in Ireland and Singapore enforce batch-level impurity certificates. The behavioral shift fragments solvent demand away from commodity traders toward integrated refiners with pharmaceutical-grade certifications.
Cycloalkanes Market Segmentation
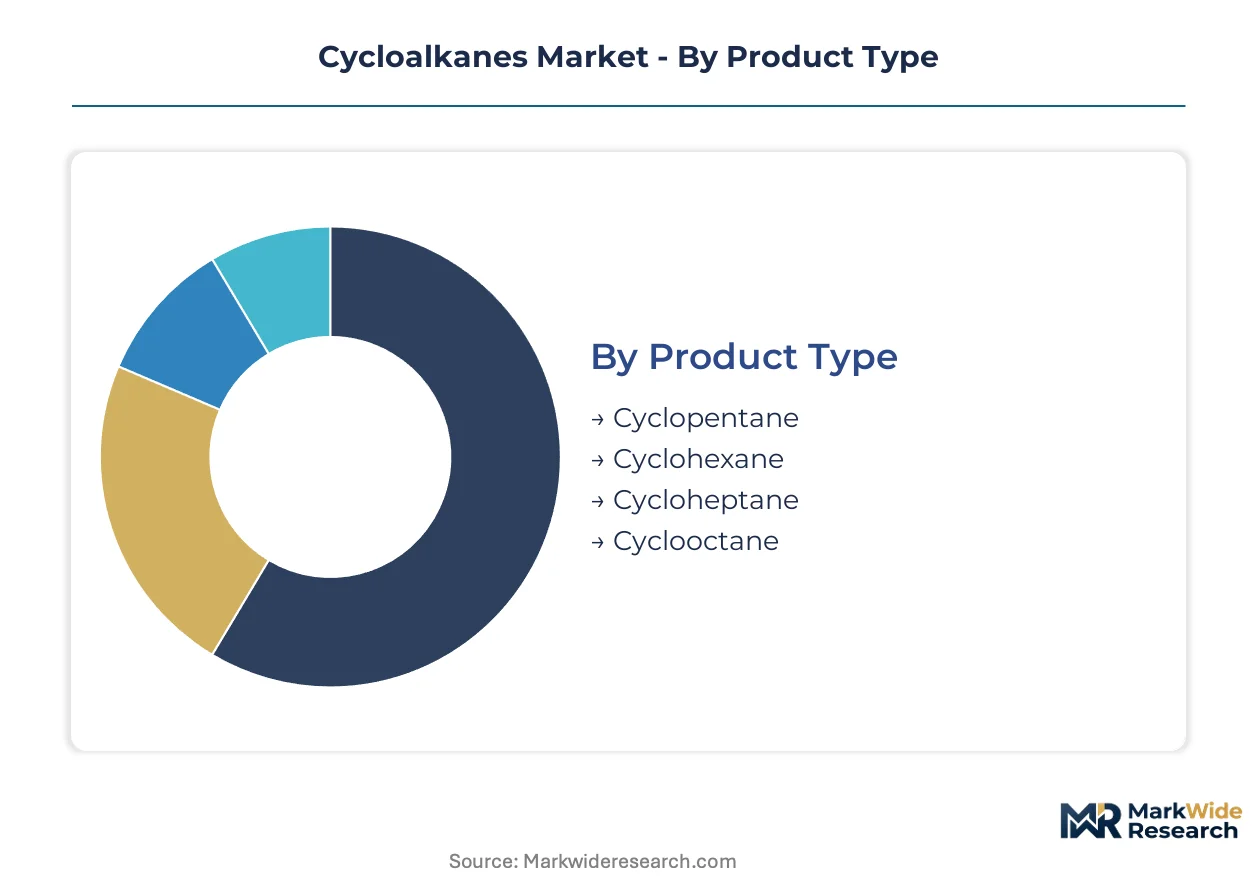
Cycloalkane commercial flows diverge sharply by molecular weight and purity grade, with pharmaceutical and refrigerant channels demanding certified supply chains while fuel and solvent applications tolerate broader specification ranges. Understanding these segment-channel pairings reveals where margin pools concentrate and where commodity trading dynamics dominate.
Product Type:
Channel-mix patterns separate high-volume industrial feedstocks from specialty-grade molecules, with cyclohexane flowing predominantly through integrated refinery-to-nylon producer pipelines while cyclopentane distributes via refrigerant compounders and appliance manufacturers.
- Cyclohexane:Six-membered ring structure serves as the dominant adipic acid and caprolactam precursor for nylon 6,6 polymerization. Chemical manufacturing clusters in Germany, China, and the US Gulf Coast absorb volumes through direct pipeline connections from hydrogenation units, bypassing merchant distribution entirely.
- Cyclopentane:Five-carbon ring formulation functions as the primary blowing agent replacing HCFC-141b in polyurethane insulation foams under EU F-Gas Regulation phase-down mandates. Appliance manufacturers in Poland, Italy, and Turkey source through regional compounders who blend with polyols at specified ratios.
- Cycloheptane:Seven-membered ring finds niche solvent applications in pharmaceutical crystallization and specialty polymer research. Laboratory chemical distributors in Switzerland and Massachusetts handle kilogram-scale shipments with COA documentation.
- Cyclooctane:Eight-carbon cyclic hydrocarbon supplies limited demand from fragrance compounders and high-temperature lubricant formulators. Merchant volumes move through Rotterdam and Singapore trading hubs in drum quantities.
By volume, cyclohexane leads. By growth pace, cyclopentane is expanding most quickly.
Application:
Cost-tier stratification separates specification-driven pharmaceutical and electronics grades from bulk fuel and refrigerant applications, with solvent purity premiums reaching multiples of industrial-grade pricing.
- Solvent:Non-polar extraction media for pharmaceutical active ingredient purification and electronics photoresist stripping. ICH Q3C residual solvent limits enforced by FDA and EMA drive sub-ppm benzene specifications, channeling demand toward integrated refiners with adsorptive purification capabilities.
- Chemical Feedstock:Adipic acid, caprolactam, and specialty polymer precursors dominate tonnage flows. Nylon producers in Shanghai, Ludwigshafen, and Houston secure volumes through long-term offtake contracts indexed to naphtha differentials.
- Refrigerant:Blowing agent applications in appliance insulation foams and secondary refrigerant blends. EU F-Gas Regulation quotas restrict high-GWP alternatives, accelerating cyclopentane uptake in domestic refrigeration manufacturing.
- Fuel:Minor blending component for high-octane gasoline formulations and racing fuel specialties. Independent refiners in Texas and Alberta purchase spot cargoes when octane economics justify cycloalkane premiums over reformate.
Chemical feedstock commands the deepest volume. Refrigerant applications show the steepest expansion trajectory.
End User:
Customer-type concentration clusters cycloalkane procurement around three distinct buying behaviors: integrated chemical producers with captive supply, specification-enforcing pharmaceutical contract manufacturers, and cost-sensitive fuel blenders.
- Chemical Manufacturing:Nylon, adipic acid, and caprolactam producers constitute the foundational demand base. BASF, Invista, and Ascend Performance Materials operate dedicated hydrogenation units or secure pipeline deliveries from adjacent refineries.
- Pharmaceuticals:API manufacturers and contract development organizations enforce batch-level impurity certificates. Facilities in Ireland, Singapore, and Puerto Rico audit supplier catalyst provenance and naphtha origin as part of qualification protocols.
- Automotive:Engineering plastics for under-hood components and fuel system applications. Tier-1 suppliers in Michigan, Bavaria, and Aichi Prefecture specify cyclohexane-derived nylon grades for heat resistance requirements.
- Aerospace:Limited specialty lubricant and sealant applications requiring thermal stability. Defense contractors and commercial aviation MRO facilities in Toulouse, Seattle, and Toulouse source through approved chemical distributors.
Chemical manufacturing anchors volume absorption. Pharmaceuticals generate the highest purity premiums.
Technology:
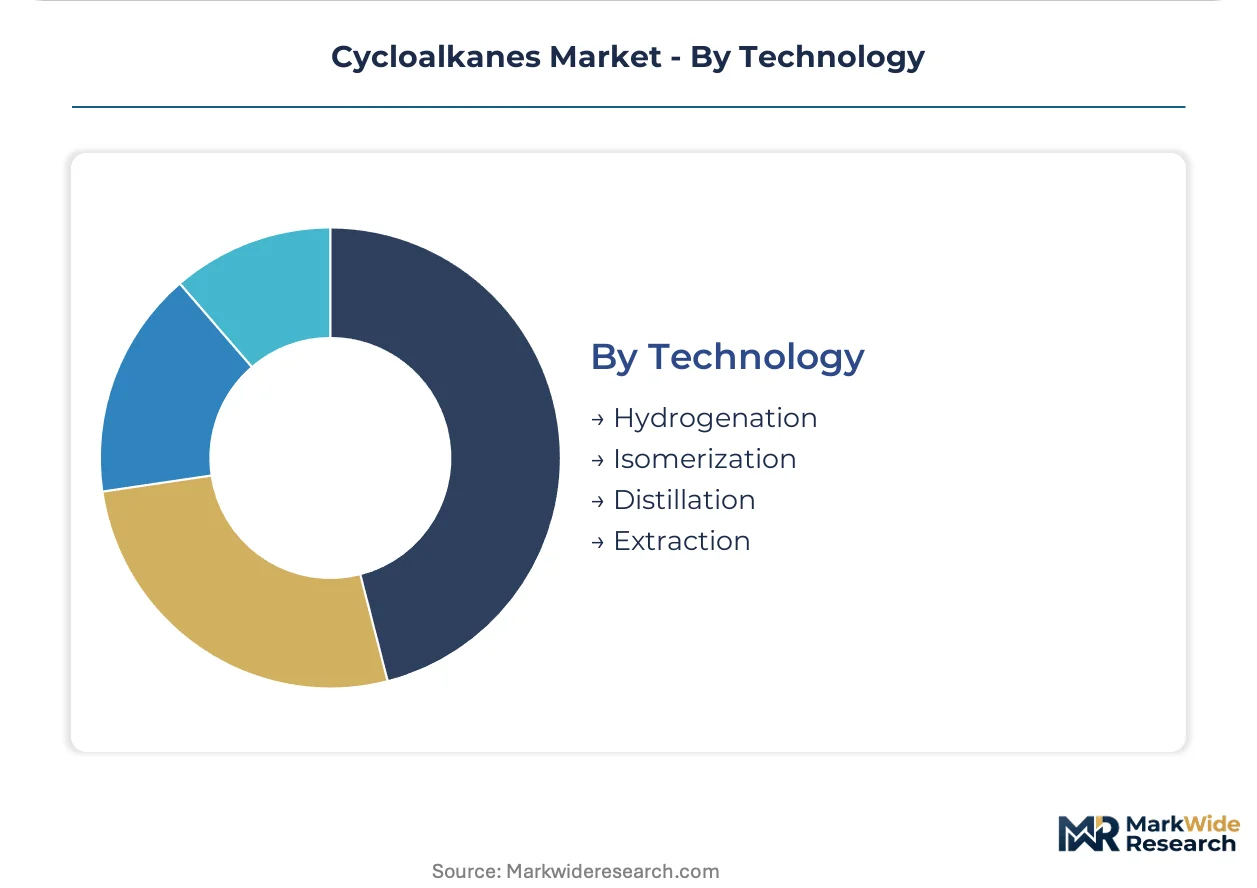
Supply concentration patterns favor producers with integrated hydrogenation and isomerization capabilities, while standalone distillation operators compete on regional logistics rather than process technology.
- Hydrogenation:Catalytic conversion of benzene to cyclohexane using platinum or nickel catalysts at elevated pressure. ExxonMobil's Baytown complex and Sinopec's Zhenhai refinery operate world-scale units with pharmaceutical-grade certification.
- Isomerization:Rearrangement of linear alkanes to cyclic structures over acidic zeolite catalysts. Saudi Aramco's Jubail facilities leverage advantaged ethane feedstock costs for cyclopentane production.
- Distillation:Fractional separation of naphtha cuts containing cycloalkane fractions. European independent refiners in Rotterdam and Antwerp maintain merchant market presence through this lower-capital approach.
- Extraction:Selective removal of cycloalkanes from reformate streams using polar solvents. UOP and Axens license technologies deployed in South Korean and Indian refinery expansions.
Hydrogenation dominates value generation. Isomerization is gaining share in Middle Eastern capacity additions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated refiners with hydrogenation capabilities cluster near naphtha supply hubs and nylon manufacturing corridors. Capacity expansion concentrates in regions with advantaged feedstock costs and tightening environmental compliance frameworks.
China
State-backed petrochemical complexes in Zhenhai and Ningbo scale catalytic reforming units for domestic adipic acid feedstock security. The Ministry of Ecology and Environment enforces dual carbon goals that favor natural gas-based hydrogenation routes over coal-derived alternatives. Sinopec's integrated refining-petrochemical hubs in the Yangtze River Delta supply pharmaceutical-grade cyclohexane to contract manufacturers in Shanghai and Suzhou.
United States
Gulf Coast refiners leverage pipeline connectivity to nylon producers in Texas and Louisiana for continuous chemical feedstock delivery. EPA Clean Air Act provisions regulate volatile organic compound emissions from cycloalkane storage and handling facilities. ExxonMobil's Baytown complex anchors North American pharmaceutical-grade supply with adsorptive purification certification.
Germany
BASF's Ludwigshafen operations consume cyclohexane volumes through dedicated pipeline connections from adjacent hydrogenation units. ECHA REACH registration requirements enforce comprehensive toxicological dossiers for cyclohexane and cyclopentane commercial volumes above one tonne annually. The Rhine-Ruhr chemical corridor maintains Europe's densest concentration of adipic acid and caprolactam manufacturing.
Saudi Arabia
SABIC anchors Middle Eastern production with advantaged ethane feedstock costs from Saudi crackers for cyclopentane output. The Saudi Food and Drug Authority aligns pharmaceutical excipient standards with ICH Q3C residual solvent guidance. Jubail industrial city hosts expanding isomerization capacity serving refrigerant compounders in Turkey and Egypt.
India
Reliance Industries operates hydrogenation units at its Jamnagar refining complex for domestic nylon precursor supply. CDSCO-aligned ICH Q3C residual solvent compliance opens import substitution opportunities for European and US cycloalkane suppliers. Pharmaceutical contract manufacturers in Hyderabad and Ahmedabad audit supplier catalyst provenance as part of qualification protocols.
Cycloalkanes Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the cycloalkanes value chain. Integrated oil majors with Gulf Coast and Middle Eastern refining assets dominate volume production through captive hydrogenation capacity. Specialty chemical distributors compete on pharmaceutical-grade certification and regional logistics rather than scale. Competitive moves concentrate on backward integration into naphtha sourcing and forward partnerships with nylon and refrigerant compounders.
Among integrated oil majors, ExxonMobil Corporation and SABIC exemplify the scale-driven archetype with world-scale hydrogenation complexes and pipeline-delivered supply relationships. INEOS Group occupies a position within the European specialty tier, focusing on cyclopentane output for blowing-agent applications under F-Gas Regulation compliance. These three anchors represent divergent geographic and strategic positioning across feedstock-advantaged, regulation-responsive, and specification-driven market segments.
| Leading Market Players |
|---|
| SABIC |
| Royal Dutch Shell |
| ExxonMobil Corporation |
| China National Petroleum Corporation |
| TotalEnergies SE |
| INEOS Group |
| Reliance Industries Limited |
| Mitsubishi Chemical Corporation |
| Chevron Phillips Chemical Company |
| Others |
Value Chain & Pricing Dynamics
Cyclopentane substitution for high-GWP refrigerant blowing agents simultaneously redraws supply geography toward Middle Eastern ethane crackers and compresses pricing economics for legacy naphtha-derived producers. EU F-Gas Regulation phase-down mandates accelerate this displacement, channeling procurement toward regions with advantaged feedstock costs while eroding margins for European independent refiners without isomerization capabilities.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across pharmaceutical, refrigerant, and industrial solvent grades. Three-tier pricing structure across premium, standard, and economy levels separates ICH Q3C-certified pharmaceutical supply from appliance-grade blowing agents and commodity fuel blending stocks. Cost compression in industrial-grade cyclohexane is intensifying because REACH registration burdens and naphtha volatility squeeze merchant distributors without integrated hydrogenation. Pharmaceutical contract manufacturers exhibit the lowest price sensitivity due to qualification lock-in, while fuel blenders demonstrate acute responsiveness to octane spread fluctuations.
Supply Chain Analysis
Saudi Arabia and the United States anchor cycloalkane production through world-scale hydrogenation and isomerization complexes. Sinopec's Zhenhai refinery and ExxonMobil's Baytown facility draw from naphtha reforming and catalytic hydrogenation routes respectively, with feedstock sourcing tethered to regional crude differentials and natural gas economics. Single-source vulnerability concentrates in platinum-rhenium catalyst supply from South African and Russian refiners, exposing reformer operations to geopolitical disruption. Distribution runs through pipeline-connected chemical manufacturing clusters for nylon feedstock, while refrigerant compounders source via regional tanker and drum logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cycloalkanes market operates as a regulatory-moat business where REACH registration dossiers and pharmaceutical-grade certifications create switching costs that entrench incumbent positions. Network effects concentrate in pipeline-connected refining-petrochemical corridors, locking in adipic acid and caprolactam offtake relationships.
For Market Incumbents: Consolidate hydrogenation capacity around Gulf Coast and Middle Eastern feedstock-advantaged hubs to defend margin position against naphtha volatility. Deepen pharmaceutical-grade certification portfolios to exploit ICH Q3C qualification timelines that delay competitor entry by 18-24 months. Prioritize backward integration into catalyst regeneration capabilities to mitigate platinum-rhenium supply concentration risk.
For New Entrants and Emerging Players: Differentiate on carbon-intensity credentials to capture EU CBAM-compliant supply contracts as border adjustments favor natural gas-based hydrogenation routes. Target electronics cleaning grade specifications in South Korea and Taiwan where semiconductor wafer processing protocols demand sub-ppm impurity cyclohexane absent from incumbent merchant portfolios. Pursue toll manufacturing partnerships with regional refiners lacking pharmaceutical certification infrastructure.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European specialty distributors carrying REACH registration overhead but lacking integrated hydrogenation. Long-term viability hinges on feedstock cost position and regulatory compliance infrastructure rather than volume scale. Monitor F-Gas Regulation quota auction prices as the inflection indicator for cyclopentane substitution economics and Middle Eastern capacity utilization rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphtha Sourcing | Secures feedstock cost stability for hydrogenation units at ExxonMobil and Sinopec complexes. |
| Pharmaceutical-Grade Certification Investment | Enables ICH Q3C-compliant supply to contract manufacturers in Ireland and Singapore. |
| Isomerization Capacity Expansion | Captures cyclopentane demand from EU F-Gas Regulation-driven refrigerant reformulation. |
| Long-term Supply Agreement with Nylon Producers | Locks in adipic acid and caprolactam offtake through pipeline-connected delivery. |
| Adsorptive Purification Technology Deployment | Meets sub-100 ppm benzene specifications for electronics and pharmaceutical end users. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with hydrogenation unit managers, pharmaceutical procurement leads, refrigerant compounder technical directors, and ECHA regulatory affairs specialists; and secondary validation through customs trade databases, SEC 10-K petrochemical segment disclosures, ECHA registration dossiers, and Cefic industry statistics. Bottom-up capacity modeling triangulated against top-down naphtha consumption forecasts to reconcile volume estimates.
Across the analysis window, projections integrated grade-tier segmentation by purity specification, end-use industry concentration across nylon and appliance manufacturing, and regional production hub clustering. CAGRs derived from elasticity-adjusted demand curves incorporating EU F-Gas Regulation phase-down schedules and China hydrogenation capacity buildout timelines. Industry-specific inputs included platinum-rhenium catalyst replacement cycles and ICH Q3C residual solvent limit revisions.
Decision-makers should treat outputs as directional under stable naphtha-crude differentials and unchanged REACH registration thresholds; material deviation in feedstock economics or regulatory stringency would warrant model refresh. Specific risks include accelerated HFO refrigerant incumbent defense, coal-to-chemicals policy reversals in China, and pharmaceutical audit standard harmonization beyond current ICH frameworks. Recalibration cycles align with material shifts in F-Gas Regulation quota allocations and dual carbon goal enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
2-Methylbutanoic Acid Market
Organic Chemicals
Dioctyl Phthalate Market
Organic Chemicals
Ethylamine Market
Organic Chemicals
4-Tert-Butylcyclohexanone Market
Organic Chemicals
Gamma-Butyrolactone (GBL) Market
Organic Chemicals
Dimethylformamide (DMF) Market
Organic Chemicals
1,3-Dioxolane Market
Organic Chemicals
Anisole Derivatives Market
Organic Chemicals
Azelaic Acid Market
Organic Chemicals
Triethylene Glycol Market
Organic Chemicals
Alanine Market
Organic Chemicals
Organic Matting Agent Market
Organic Chemicals
Methacrylic Acid Market
Organic Chemicals
US Humate Market
Organic Chemicals
Global Benzoic Acid Market
Organic Chemicals
2,5-Dimethyl-2,4-Hexadiene Market