
 Para-Tert-Octylphenol (POTP) Market | 2026-2036
Para-Tert-Octylphenol (POTP) Market Size, Share, and Industry Trends Forecast 2026-2036
Para-Tert-Octylphenol (POTP) Market Analytics
REACH compliance in Europe is shifting demand toward lower-impurity POTP grades across adhesive and coatings supply chains. SI Group, Inc. leverages its phenolic resin technology leadership to sustain formulation partnerships with tier-one automotive suppliers. Maruzen Petrochemical Co., Ltd. anchors Asia-Pacific supply through integrated petrochemical feedstock access. Sasol Limited competes on Fischer-Tropsch-derived feedstock differentiation in stabilizer applications.
Para-tert-octylphenol is an alkylphenol produced via acid-catalyzed alkylation of phenol with diisobutylene, yielding a branched C8 alkyl chain at the para position with typical purity grades exceeding 99%. The compound serves primarily as a chemical intermediate for phenolic resins, surfactant synthesis, and polymer stabilizers where hindered phenol architecture delivers antioxidant performance. Phenolic resin applications dominate volume flows due to entrenched demand from plywood bonding and friction material formulations. Surfactant derivatives represent the fastest-expanding category as industrial cleaning compounders reformulate for emulsion stability. Additives segment margin pools concentrate in rubber antioxidant grades where specification stringency limits supplier qualification.
EPA oversight of alkylphenol ethoxylate fate in aquatic systems shapes North American product registration requirements for downstream surfactant applications. ECHA maintains strict dossier obligations under REACH for POTP importers and manufacturers operating within EU member states. China's MEE enforces emission controls on alkylation facilities that constrain capacity additions in Shandong and Jiangsu provinces. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with divergent hazard classification thresholds.
Market Dynamics
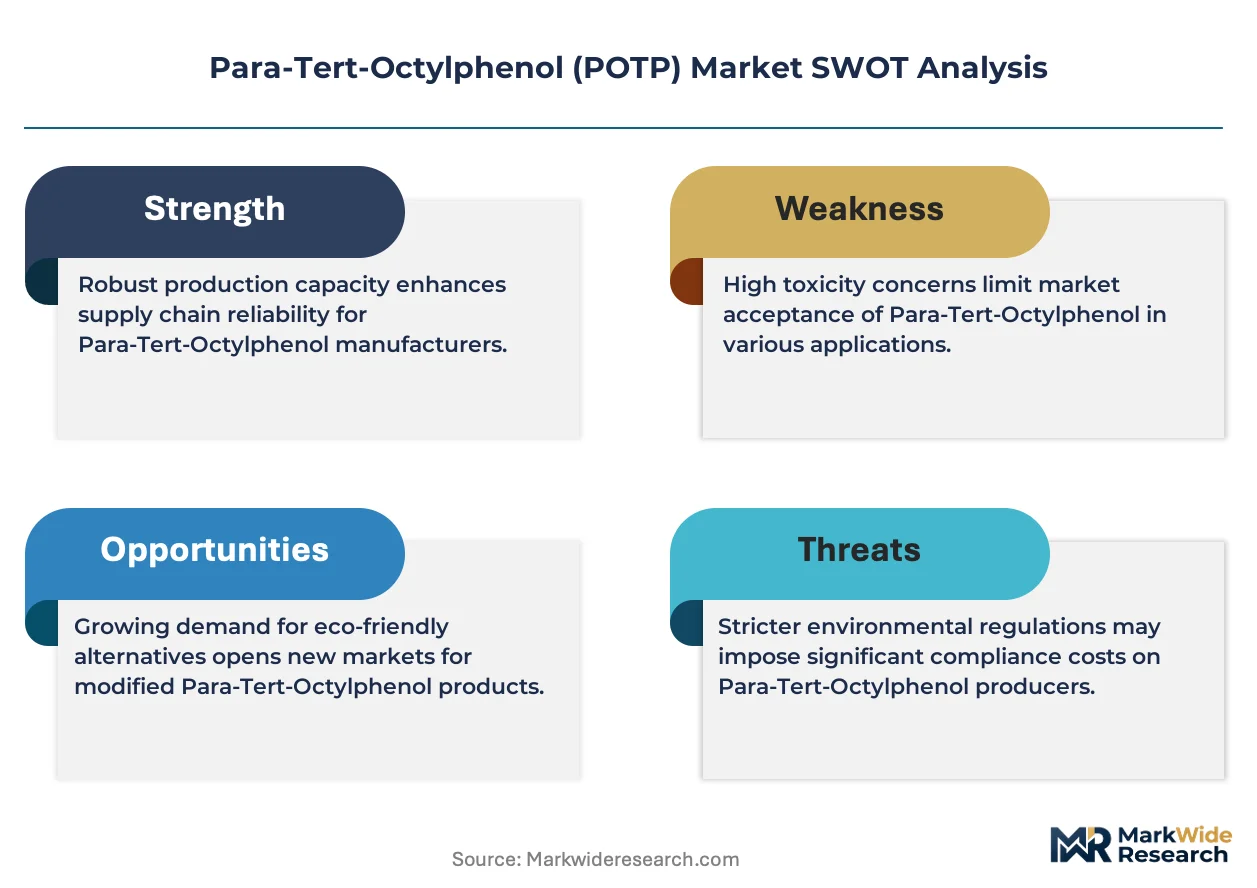
REACH compliance in Europe is compressing supplier qualification timelines and forcing reformulation across phenolic resin value chains, tightening impurity specifications faster than incumbents can adapt capacity.
Growth Catalysts
- Phenolic resin demand:Plywood bonding and friction material manufacturers in China are expanding specialty chemical output, pulling C8 alkylphenol volumes through integrated petrochemical complexes.
- REACH specifications:Lower-impurity grade requirements across EU adhesive supply chains are differentiating qualified suppliers from commodity traders, creating margin pools for compliant producers.
- Surfactant reformulation:Industrial cleaning compounders are adopting POTP-derived emulsion stabilizers for aqueous system performance, displacing legacy ethoxylate architectures.
Market Restraints
- Diisobutylene feedstock volatility:Acid-catalyzed alkylation economics hinge on C4 olefin availability from steam cracker operations, exposing margins to petrochemical cycle swings.
- Shandong-Jiangsu capacity constraints:China's MEE emission controls on alkylation facilities limit greenfield additions despite domestic resin producer demand concentration.
- Alkylphenol ethoxylate substitution:EPA aquatic fate oversight is accelerating downstream migration to nonylphenol-free surfactant chemistries in North American industrial cleaning applications.
Strategic Opportunities
- India specialty chemical expansion:Domestic phenolic resin producers under PLI scheme incentives are qualifying new intermediate suppliers for plywood and automotive friction formulations.
- Rubber antioxidant grade premiumization:Specification stringency in tire manufacturing is compressing qualified supplier lists, concentrating margin pools among certified producers.
- Dual carbon alignment:China's carbon intensity targets are favoring integrated producers with captive hydrogen and steam balances over merchant alkylation operators.
Industry Challenges
- REACH dossier maintenance:ECHA substance evaluation obligations require continuous toxicological data generation, stretching regulatory affairs bandwidth for smaller importers.
- Alkylation catalyst regeneration:Sulfonic acid resin bed replacement cycles demand specialized handling infrastructure, raising operational complexity for non-integrated processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Para-Tert-Octylphenol (POTP) Market |
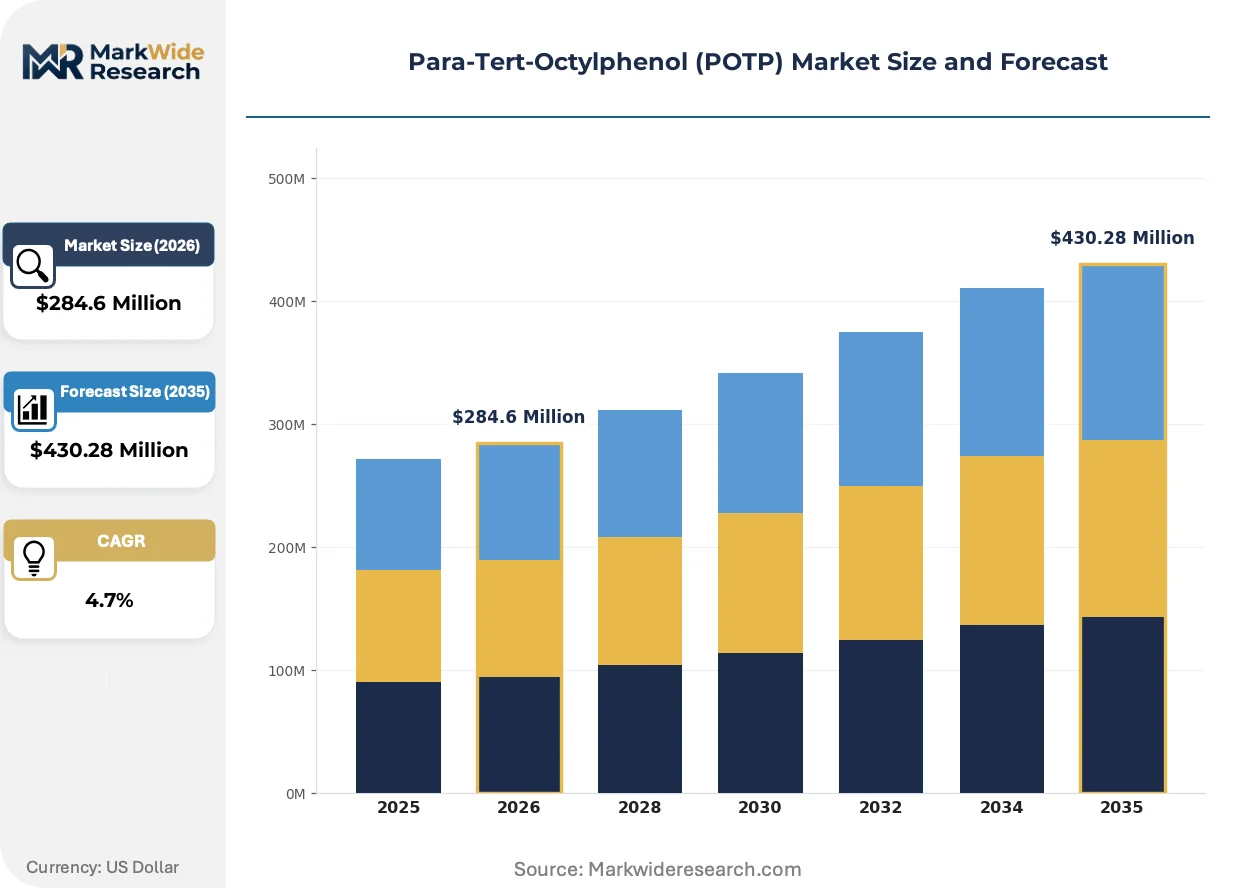
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $430.28 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phenolic Resin, Surfactants, Stabilizers, Additives Application: Coatings, Adhesives, Plastics, Rubber End User: Automotive, Construction, Consumer Goods, Electronics Distribution Channel: Direct Sales, Online Stores, Distributors, Retail |
| Companies Covered | SI Group, Inc., Maruzen Petrochemical Co., Ltd., Zibo Xujia Chemical Industry Co., Ltd., Dover Chemical Corporation, Sasol Limited, DIC Corporation, ICC Industries Inc., Prasol Chemicals Limited, Red Avenue New Materials Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Para-Tert-Octylphenol (POTP) Market Evolving Landscape
Formulation science is pivoting toward hindered phenol architectures that deliver antioxidant performance without downstream ethoxylate regulatory exposure, compressing traditional surfactant synthesis pathways.
Continuous alkylation reactor technology is integrating phenol conversion efficiencies above batch operations, enabling real-time impurity control that REACH-qualifying grades demand. Automotive friction material compounders in Germany and Japan are adopting this platform to secure supply chain continuity. The technology is integrating process analytical chemistry that reduces off-specification volumes and accelerates customer qualification timelines.
ECHA's SVHC candidate list expansion for endocrine-disrupting properties is forcing downstream surfactant registrants to submit extended safety dossiers or reformulate. Industrial cleaning manufacturers serving EU institutional buyers are migrating to POTP-derived alternatives ahead of authorization deadlines. North American formulators are tracking this regulatory trajectory to anticipate EPA parallel action on aquatic toxicity endpoints.
Buyer consolidation among tier-one automotive suppliers is compressing supplier approval cycles from 18 months to 9 months, favoring producers with integrated resin technology partnerships. Coatings manufacturers in China's Yangtze River Delta are consolidating procurement through platform chemical distributors, disintermediating traditional trader networks. This concentration is most visible in Shandong province, where domestic phenolic resin leaders are qualifying single-source POTP relationships to secure volume commitments.
Para-Tert-Octylphenol (POTP) Market Segmentation
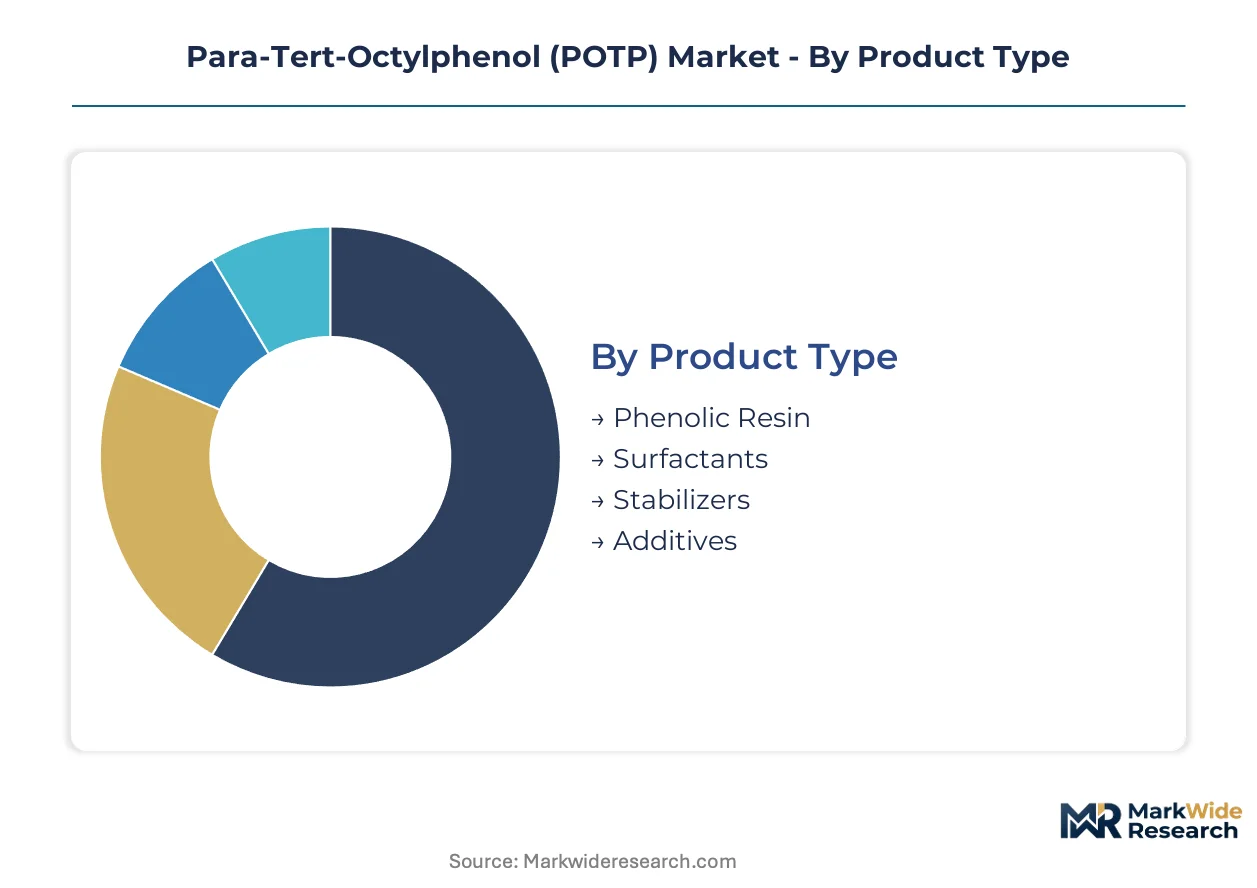
POTP demand fragments across distinct technical specifications and supply chain configurations. Each segment category reflects divergent purity requirements, regulatory exposure, and customer procurement patterns that reshape supplier competitive positioning.
Product Type:
Customization intensity spans from commodity phenolic intermediates to specification-locked antioxidant grades, with purity thresholds and certification burdens determining margin architecture.
- Phenolic Resin:Technical-grade POTP with typical purity exceeding 99% serves as the primary alkylation intermediate for formaldehyde condensation. Plywood bonding manufacturers in China pull volumes through integrated petrochemical complexes, though REACH impurity specifications are compressing qualified supplier lists in European adhesive supply chains.
- Surfactants:Ethoxylated derivatives deliver emulsion stability in aqueous industrial cleaning systems. Reformulation momentum is accelerating as EPA aquatic fate oversight and ECHA SVHC candidate list expansion displace legacy nonylphenol architectures in North American and EU institutional buyer segments.
- Stabilizers:Hindered phenol configurations provide antioxidant protection in polymer processing. Fischer-Tropsch-derived feedstock differentiation creates specification tiers in rubber and plastics applications.
- Additives:Rubber antioxidant grades face qualification stringency that limits supplier certification. Tire manufacturing concentration is compressing approved vendor lists to certified producers with continuous alkylation reactor technology.
Leading the category by volume: Phenolic Resin. Growing fastest: Surfactants.
Application:
End-use performance requirements range from architectural durability specifications to friction material thermal stability, with regulatory geography determining formulation chemistry selection.
- Coatings:High-performance formulations demand lower-impurity POTP grades for UV stability and adhesion. Automotive OEM specifications in Germany and Japan are integrating continuous process analytical chemistry to accelerate qualification timelines.
- Adhesives:Plywood and engineered wood bonding consumes technical-grade volumes. REACH compliance is forcing reformulation across EU supply chains toward reduced residual phenol content.
- Plastics:Polymer stabilization applications require hindered phenol architecture without downstream ethoxylate regulatory exposure. Processing aid compounders are migrating toward POTP-derived alternatives ahead of authorization deadlines.
- Rubber:Friction material formulations for automotive brake systems anchor specialty grade demand. Tier-one supplier consolidation is compressing approval cycles from 18 months to 9 months.
Dominant by volume: Adhesives. Climbing the fastest: Coatings.
End User:
Procurement sophistication varies from platform chemical distributor consolidation to direct mill relationships, with qualification burden and volume scale inversely correlated across customer tiers.
- Automotive:Tier-one friction material and coating suppliers enforce specification stringency that favors integrated resin technology partnerships. Single-source POTP relationships are consolidating in China's Yangtze River Delta procurement platforms.
- Construction:Plywood and engineered wood manufacturers drive phenolic resin intermediate consumption. Domestic resin producers under India's PLI scheme incentives are qualifying new intermediate suppliers for volume commitments.
- Consumer Goods:Cleaning compound and personal care formulators face downstream ethoxylate substitution pressure. ECHA endocrine-disrupting property evaluations are accelerating migration to alternative surfactant chemistries.
- Electronics:Encapsulant and coating applications demand ultra-low ionic impurity specifications. Semiconductor packaging material qualification cycles extend supplier approval timelines.
Largest volume concentration: Construction. Steepest expansion trajectory: Automotive.
Distribution Channel:
Channel economics reflect shipment scale, technical service requirements, and geographic proximity to alkylation capacity clusters, with disintermediation pressure strongest in concentrated demand regions.
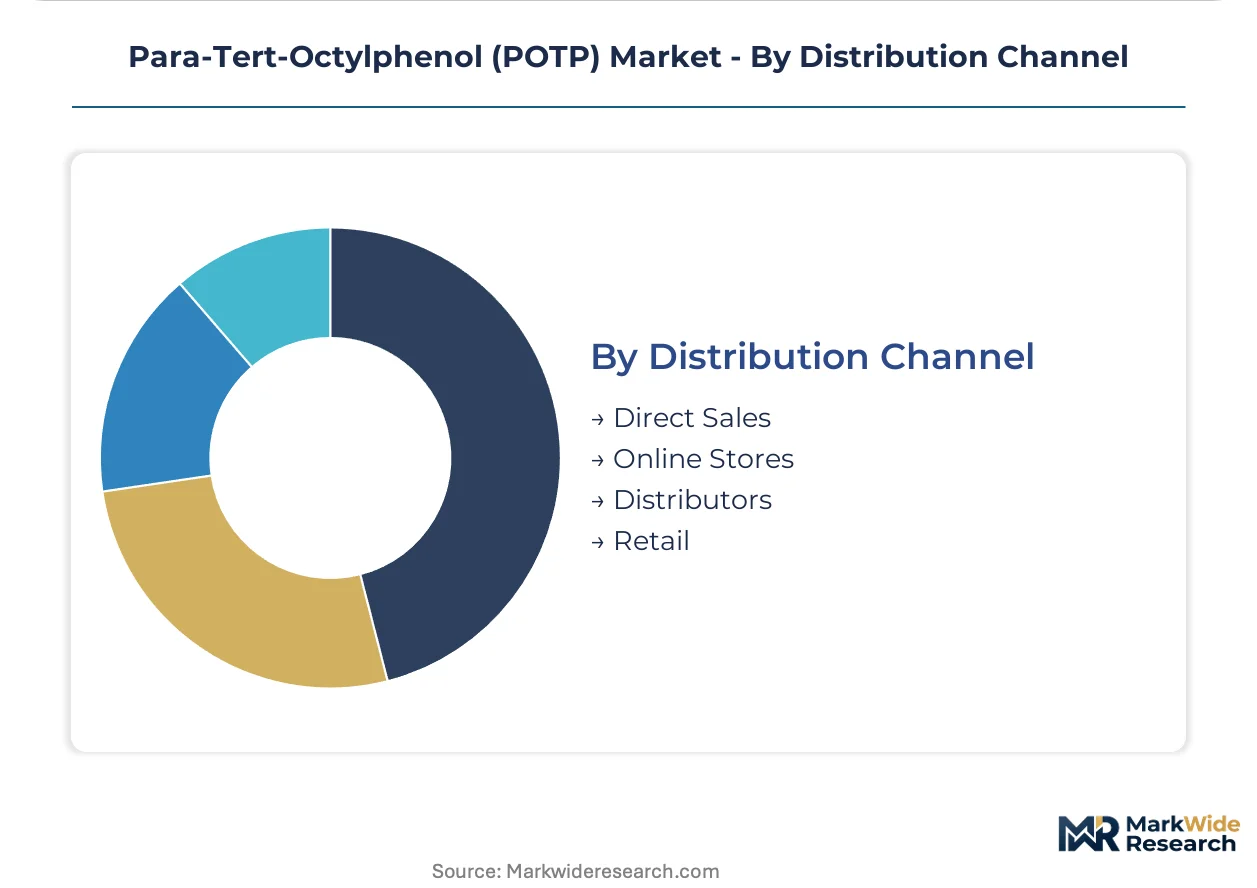
- Direct Sales:Integrated phenolic resin producers and large-volume automotive compounders negotiate mill-direct contracts. China's domestic resin leaders are consolidating procurement through captive supply arrangements in Shandong province.
- Distributors:Platform chemical distributors in Asia-Pacific are disintermediating traditional trader networks. Technical service capabilities and inventory positioning determine regional competitive positioning.
- Online Stores:Specialty chemical marketplaces serve small-batch research and sampling demand. Specification documentation and certificate of analysis availability constrain adoption for regulated applications.
- Retail:Limited to consumer-facing cleaning and maintenance product formulations. Downstream brand owner liability concerns restrict POTP-derived ingredient disclosure in mass-market channels.
Highest volume flow: Direct Sales. Gaining share fastest: Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province anchors POTP manufacturing concentration, with integrated petrochemical corridors in Zibo and Dongying feeding domestic phenolic resin complexes. Jiangsu and Zhejiang provinces downstream process volumes into surfactant and coating intermediates for Yangtze River Delta industrial consumers.
China
Domestic resin producers scale specialty chemical output through captive alkylation capacity in Shandong and Jiangsu provinces. MEE emission controls constrain greenfield additions despite construction sector pull for plywood bonding intermediates. Yangtze River Delta coatings manufacturers consolidate procurement through platform distributors, disintermediating traditional trader networks.
Germany
Automotive friction material compounders demand REACH-compliant lower-impurity grades for brake system formulations. ECHA substance evaluation obligations stretch regulatory affairs bandwidth for importers serving EU adhesive supply chains. Cologne-Düsseldorf industrial corridor hosts formulation partnerships between phenolic resin technology leaders and tier-one automotive suppliers.
United States
Industrial cleaning compounders reformulate emulsion stabilizers under EPA aquatic fate oversight of alkylphenol ethoxylates. Gulf Coast petrochemical infrastructure supports merchant alkylation economics exposed to C4 olefin cycle swings. Texas and Louisiana processors serve stabilizer applications with Fischer-Tropsch-derived feedstock differentiation.
India
Domestic phenolic resin producers under PLI scheme incentives qualify new intermediate suppliers for plywood and automotive friction formulations. BIS certification requirements shape import substitution strategies for construction adhesive applications. Gujarat and Maharashtra industrial clusters concentrate qualification activity for volume commitments from specialty chemical expansions.
Japan
Automotive OEM specifications integrate continuous process analytical chemistry to accelerate POTP qualification timelines. METI chemical management frameworks align with ECHA regulatory trajectories on endocrine-disrupting property evaluations. Chubu and Kansai manufacturing belts concentrate friction material and electronics encapsulant demand for ultra-low ionic impurity grades.
Para-Tert-Octylphenol (POTP) Market Competitive Landscape
The competitive structure tilts toward integrated petrochemical players with captive feedstock positions. Merchant alkylation operators face margin compression from diisobutylene volatility and emission control compliance costs. Three archetypes dominate: integrated resin technology partnerships, Fischer-Tropsch feedstock differentiators, and platform chemical distributors with technical service capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines compress.
Among Asia-Pacific integrated producers, Maruzen Petrochemical Co., Ltd. and Zibo Xujia Chemical Industry Co., Ltd. exemplify the captive feedstock archetype with Shandong province petrochemical corridor positioning. SI Group, Inc. represents the resin technology partnership model serving tier-one automotive supply chains. Sasol Limited occupies a Fischer-Tropsch differentiation position in stabilizer applications.
| Leading Market Players |
|---|
| SI Group, Inc. |
| Maruzen Petrochemical Co., Ltd. |
| Zibo Xujia Chemical Industry Co., Ltd. |
| Dover Chemical Corporation |
| Sasol Limited |
| DIC Corporation |
| ICC Industries Inc. |
| Prasol Chemicals Limited |
| Red Avenue New Materials Group |
| Others |
Value Network & Pricing Analysis
REACH certification tiers bifurcate POTP supply chains into qualified and commodity streams, with lower-impurity grades commanding sustained premiums while standard grades face margin compression from Shandong capacity constraints and diisobutylene volatility. This divergence concentrates pricing power among integrated producers with captive alkylation infrastructure, while merchant operators absorb feedstock cycle exposure.
Pricing Analysis
Value-based pricing anchors on antioxidant performance yields in rubber stabilization and friction material applications, where specification stringency limits qualified supplier lists. Three-tier pricing structure across premium REACH-compliant, standard technical-grade, and economy industrial grades differentiates margin pools. Cost compression in standard grades intensifies because China's MEE emission controls constrain Shandong-Jiangsu capacity additions. Tire manufacturers show least price sensitivity; plywood bonding compounders exhibit highest elasticity.
Supply Chain Analysis
Skilled technical workforce availability in Shandong and Jiangsu provinces anchors global alkylation capacity concentration, with Zibo-Dongying petrochemical corridors feeding integrated phenolic resin complexes. Feedstock draws from diisobutylene streams tethered to steam cracker operations, while sulfonic acid catalyst regeneration demands specialized handling infrastructure. Single-source vulnerability runs through concentrated Shandong manufacturing clusters exposed to environmental enforcement actions. Distribution runs through platform chemical distributors disintermediating traditional trader networks in Asia-Pacific demand centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play where REACH dossier maintenance burdens and continuous reactor capital requirements force smaller merchant alkylators toward exit or acquisition.
For Market Incumbents: Hedge regulatory exposure by deepening backward integration into captive diisobutylene supply and accelerating continuous alkylation reactor deployment for real-time impurity control. ECHA SVHC candidate list expansion threatens downstream surfactant volumes, making phenolic resin technology partnerships with tier-one automotive suppliers the priority defensive lever. For New Entrants and Emerging Players: Platform chemical distributors in India's Gujarat-Maharashtra clusters offer the most penetrable channel architecture for qualifying under PLI scheme incentives. Target rubber antioxidant grade premiumization where specification stringency compresses approved vendor lists, and pursue joint qualification programs with domestic phenolic resin producers seeking import substitution. For Investors and Strategic Acquirers: Re-rating potential sits with Fischer-Tropsch feedstock differentiators given stabilizer application margin resilience and limited qualified supplier competition. Long-term viability favors archetypes with integrated petrochemical positioning and REACH-compliant certification infrastructure. Watch ECHA authorization timeline acceleration on endocrine-disrupting properties as the inflection signal for downstream surfactant demand migration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive diisobutylene supply from steam cracker operations insulates margins from C4 olefin cycle volatility. |
| Continuous Reactor Deployment | Real-time process analytical chemistry reduces off-specification volumes and accelerates REACH qualification timelines. |
| Long-term Supply Agreement | Single-source relationships with Yangtze River Delta coatings manufacturers secure volume commitments amid procurement consolidation. |
| Green Manufacturing Transition | Dual carbon alignment through captive hydrogen and steam balances favors integrated producers over merchant operators. |
| Joint Venture | Partnerships with India's PLI scheme beneficiaries enable qualification for plywood and automotive friction formulations. |
Research Methodology
Independent corroboration across plant managers at Shandong alkylation facilities, procurement leads at tier-one automotive friction material compounders, distribution channel partners in Asia-Pacific platform networks, and technical R&D directors at phenolic resin formulators underwrites the qualitative findings. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K disclosures from listed chemical producers, and ECHA substance evaluation dossiers. Bottom-up volume builds and top-down market sizing triangulate to cross-verify segment-level outputs.
Comparable historical periods anchor the forecast window, with modeling extending across the projection horizon. Segmentation dimensions include purity grade tier, end-use application, regional production hub concentration, and regulatory compliance status. CAGRs derive from segment-level growth rate synthesis applied to base-year value allocations. Industry-specific inputs incorporate diisobutylene feedstock cost trajectories and REACH authorization timeline assumptions.
Caveats apply where ECHA SVHC list expansion, MEE emission control enforcement intensity, or automotive friction material specification revisions could materially shift the outlook. Forecasts embed assumptions about continuous reactor adoption rates and qualification timeline compression. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Global Carboxylic Acid Market
Organic Chemicals
Oxo Chemicals Market
Organic Chemicals
Organic Binders Market
Organic Chemicals
Benzyl Cyanide Market
Organic Chemicals
Gamma-Butyrolactone (GBL) Market
Organic Chemicals
2-Methylbutanoic Acid Market
Organic Chemicals
Azelaic Acid Market
Organic Chemicals
Crotonic Acid Market
Organic Chemicals
Soy Chemicals Market
Organic Chemicals
2-Fluorobenzotrifluoride Market
Organic Chemicals
Europe Lactic Acid Market
Organic Chemicals
Organic Chemicals Market
Organic Chemicals
4-Tert-Butylcyclohexanone Market
Organic Chemicals
Chloro -Dimethylsilane (CAS 1066-35-9) Market
Organic Chemicals
Methacrylic Acid Market
Organic Chemicals
N-Pentane Market