
 Cyclic Ketones Market | 2026-2036
Cyclic Ketones Market Size, Share, and Industry Trends Forecast 2026-2036
Cyclic Ketones Market Outlook
European specialty chemical capacity is hardening as producers respond to tighter solvent emission frameworks. Solvay S.A. leverages its integrated phenol-cyclohexanone chain to secure feedstock flexibility across Belgium and France. BASF SE anchors large-scale cyclohexanone output for captive caprolactam production at its Ludwigshafen complex. Zhejiang NHU Co., Ltd competes on vitamin and fragrance intermediate specialization, extending its reach into camphor derivatives for Asia-Pacific cosmetics formulators.
Cyclic ketones comprise carbonyl-functional compounds where the carbonyl group resides within a ring structure, typically manufactured through catalytic oxidation or dehydrogenation of corresponding cycloalkanes with purity thresholds exceeding 99.5% for electronic and pharmaceutical grades. These compounds serve primarily as chemical intermediates for nylon precursors, specialty solvents, and fragrance precursors where molecular stability and controlled evaporation profiles prove critical. Cyclohexanone dominates product type volumes as the principal feedstock for adipic acid and caprolactam synthesis, while camphor commands premium positioning in fragrance and pharmaceutical applications where natural-origin certification supports margin pools. Methylcyclopentanone represents the fastest-growing product type as solvent formulators seek lower-toxicity alternatives to traditional aromatic ketones in coatings and cleaning applications.
REACH registration requirements and the EU F-Gas Regulation constrain volatile organic compound content in solvent applications, compelling reformulation toward lower-emission cyclic ketone grades. EPA National Emission Standards for Hazardous Air Pollutants impose comparable solvent recovery mandates on U.S. paints and coatings manufacturers, while China's MEE enforces dual carbon goals that elevate energy efficiency benchmarks for cyclohexanone production. Stakeholders must monitor regulatory divergence between European purity mandates and Asia-Pacific volume scaling as they calibrate capacity investments and product certification strategies across regional qualification regimes.
Market Dynamics
Caprolactam producers in China are consolidating cyclohexanone offtake agreements, compressing spot market liquidity and forcing European specialty chemical houses to defend contract positions through backward integration into phenol feedstocks.
Growth Catalysts
- Textile polymer demand:Domestic caprolactam producers in China are scaling cyclohexanone consumption for nylon-6 supply chains serving synthetic fiber manufacturers.
- REACH purity mandates:ECHA registration requirements for fragrance-grade ketones are elevating technical barriers and rewarding producers with integrated quality systems.
- MEE dual carbon enforcement:China's Ministry of Ecology and Environment energy efficiency benchmarks are accelerating kiln retrofits at cyclohexanone plants.
Market Restraints
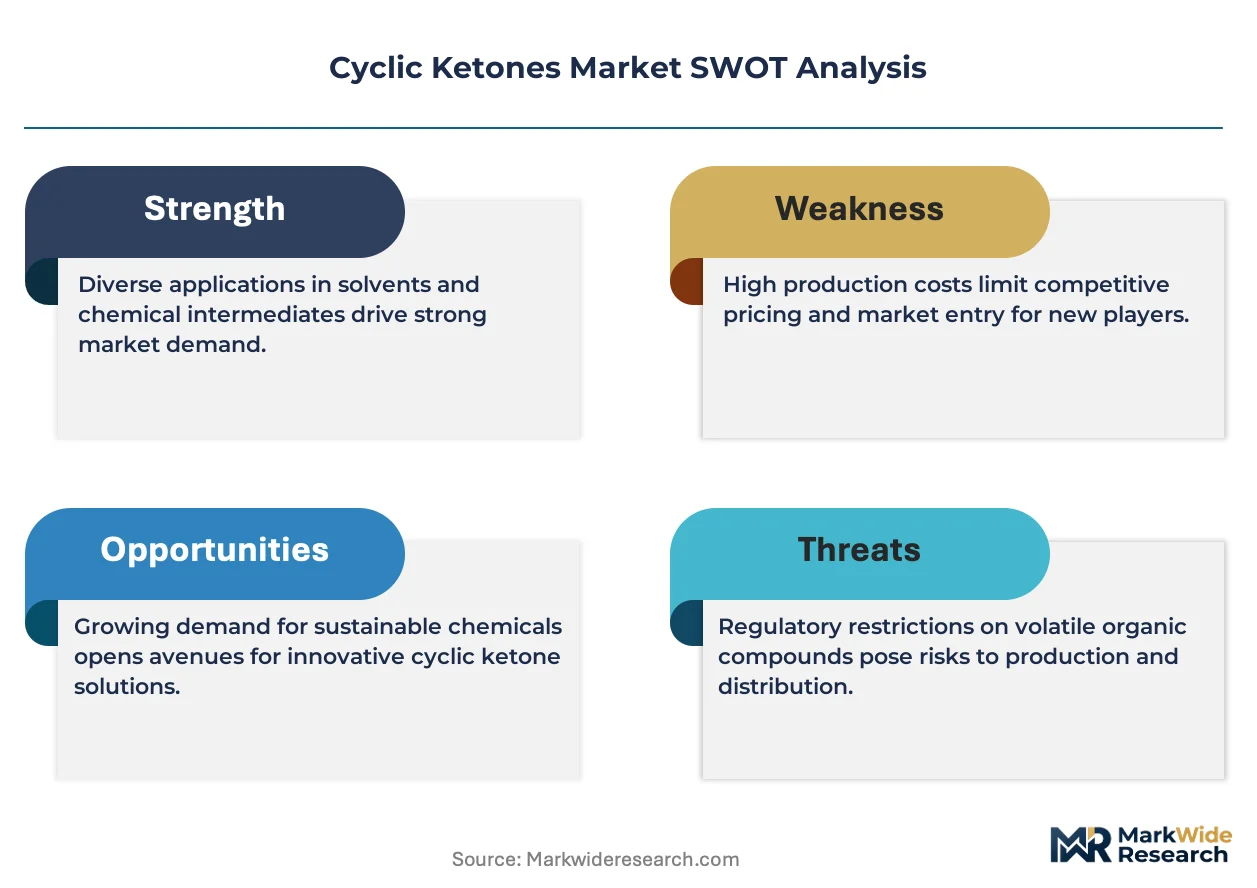
- Phenol-cyclohexanone margin compression:Integrated producers face benzene feedstock volatility that erodes cyclohexanone conversion economics.
- Caprolactam import substitution:China's self-sufficiency push reduces export market access for European and North American cyclohexanone volumes.
- Natural camphor harvest variability:Cinnamomum camphora supply from Southeast Asia creates raw material uncertainty for fragrance-grade producers.
Strategic Opportunities
- India specialty solvent penetration:BIS standards harmonization with REACH specifications creates qualification pathways for methylcyclopentanone in coatings.
- Electronic-grade ketone purification:Semiconductor wet chemical demand for 99.99% purity cyclohexanone enables premium positioning beyond commodity nylon feedstock.
- EU F-Gas solvent replacement:The regulation's volatile organic compound limits are opening formulation switches from fluorinated solvents to cyclic ketone alternatives.
Industry Challenges
- Catalytic dehydrogenation expertise scarcity:Plant operators with experience in selective cyclohexane-to-cyclohexanone conversion are concentrated at legacy installations.
- REACH registration timeline compression:The 2026 dossier update deadline for existing substances is forcing smaller producers to consolidate or exit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyclic Ketones Market |
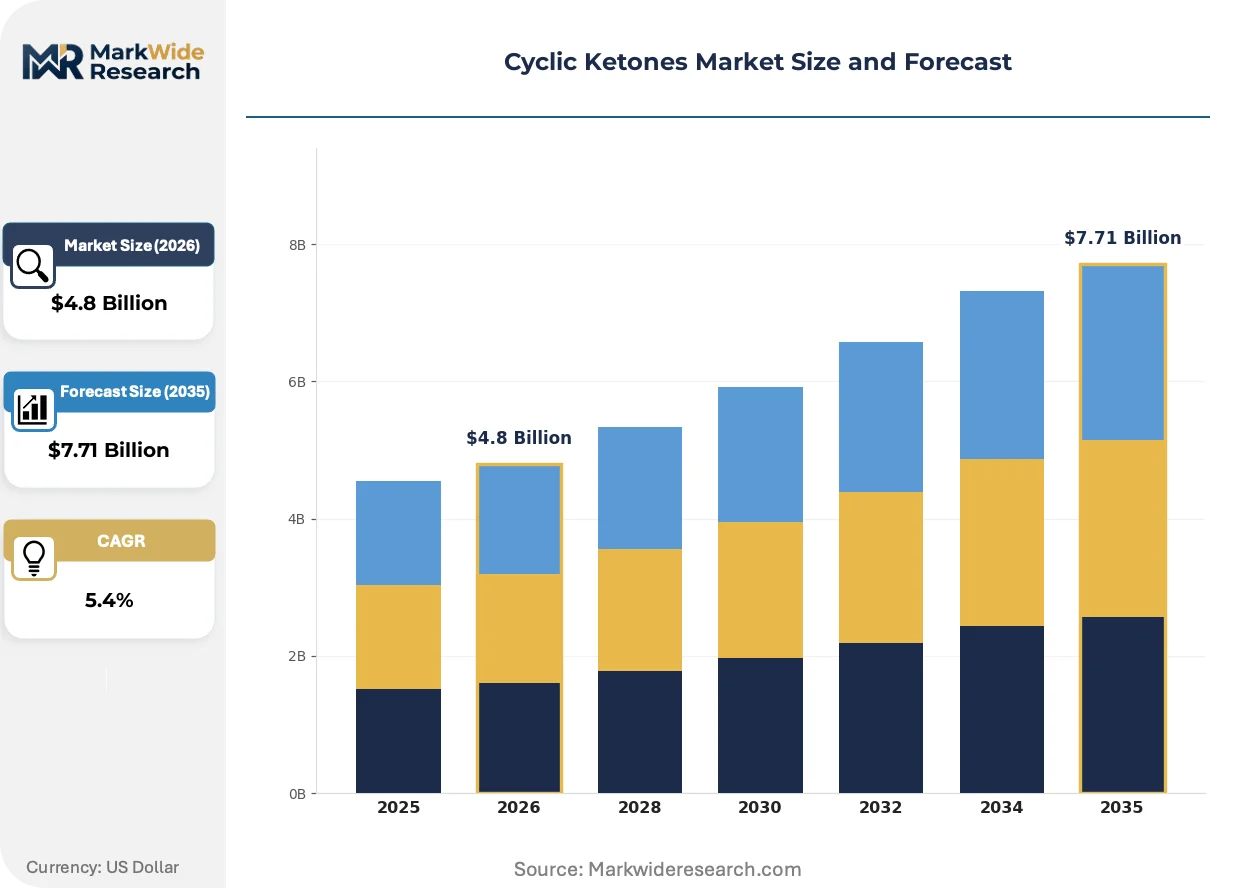
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cyclohexanone, Methylcyclopentanone, Decalin, Camphor Application: Solvent, Chemical Intermediate, Fragrance, Polymer End Use Industry: Automotive, Paints & Coatings, Cosmetics, Pharmaceuticals Distribution Channel: Direct Sales, Wholesale, Retail, Online |
| Companies Covered | Solvay S.A., Zhejiang NHU Co., Ltd, BASF SE, Caffaro Industrie S.p.A., ALTIVIA Ketones & Additives, Merck KGaA, Zeon Corporation, Shell Chemicals, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyclic Ketones Market Strategic Shifts
Process intensification and regulatory compliance automation are converging to reshape how cyclic ketone producers manage energy, purity, and certification costs simultaneously.
Membrane separation technology for cyclohexanone purification is unifying water removal and heavy fraction rejection into single-unit operations. Adipic acid producers in Germany and Belgium are retrofitting hybrid distillation-membrane trains to cut steam consumption. This convergence is compressing capital intensity for grassroots caprolactam-cyclohexanone complexes.
EPA National Emission Standards for Hazardous Air Pollutants are compelling U.S. coatings formulators to document solvent recovery rates above 95% for ketone-containing formulations. Paints and coatings manufacturers are requalifying methylcyclopentanone grades that demonstrate lower photochemical reactivity in air quality models. The standard is driving specification divergence between fragrance-grade and industrial-grade ketone pools.
Long-term offtake contracting is displacing spot purchasing among nylon intermediates buyers in China. Caprolactam producers are locking five-year cyclohexanone supply agreements with integrated phenol makers to secure volume certainty. This pattern is most visible in Zhejiang and Jiangsu provinces where textile polymer capacity is concentrating.
Cyclic Ketones Market Segmentation
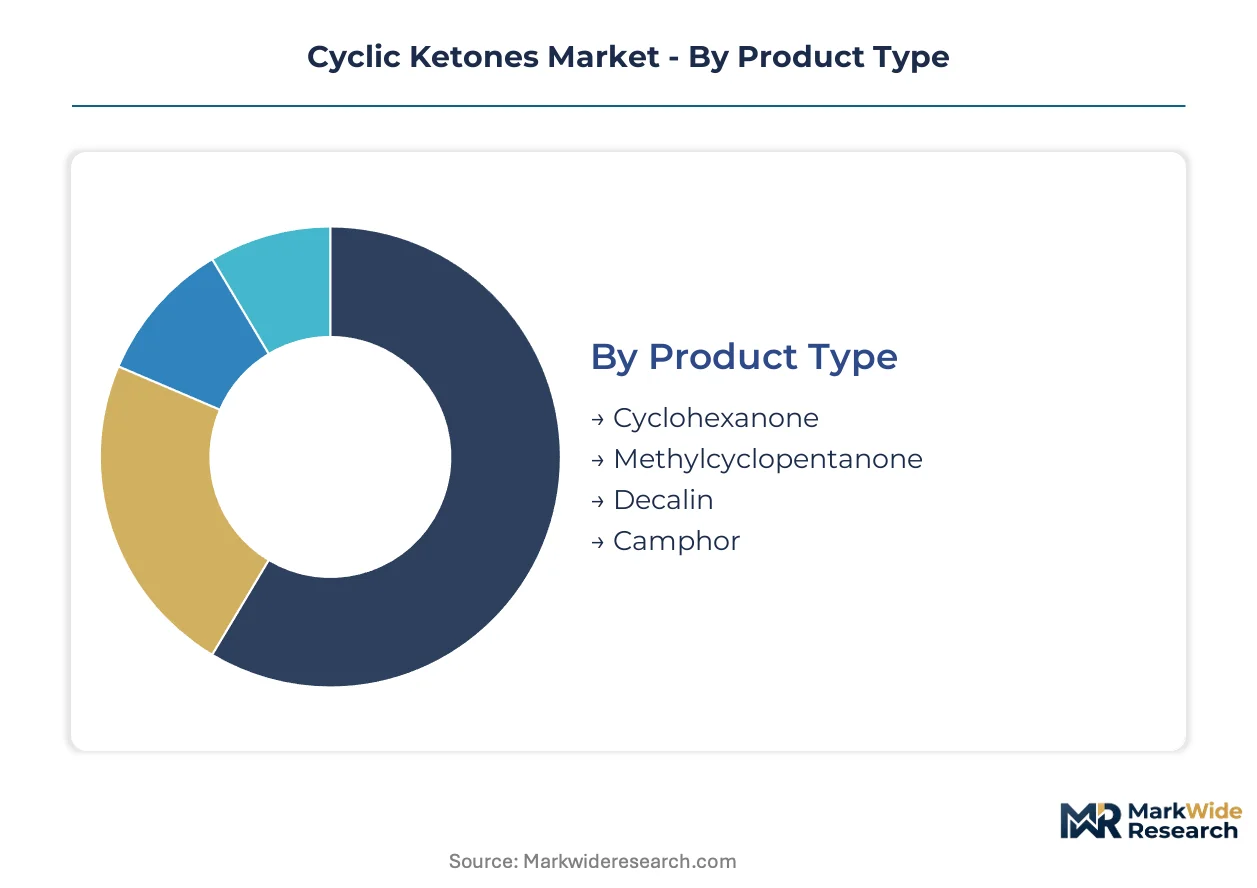
Cyclic ketones exhibit divergent margin profiles across molecular structures and purity grades. Segmentation reveals how capital deployment, regulatory thresholds, and customer concentration reshape profitability within each slice of the value chain.
Product Type:
Capital intensity peaks with cyclohexanone due to phenol feedstock integration and continuous dehydrogenation infrastructure. Methylcyclopentanone and camphor require less upfront fixed asset commitment but demand specialized catalytic expertise.
- Cyclohexanone:Six-membered ring ketone manufactured via phenol hydrogenation or cyclohexane oxidation, commanding 99.5% minimum purity for caprolactam synthesis. Demand concentrates in Zhejiang and Jiangsu provinces where domestic textile polymer producers are locking long-term offtake agreements to secure nylon-6 feedstock security.
- Methylcyclopentanone:Five-membered cyclic ketone with lower photochemical reactivity than aromatic alternatives, gaining traction in coatings reformulation. Expansion is steepest in India where BIS standards harmonization with REACH specifications opens qualification pathways for industrial solvent applications.
- Decalin:Bicyclic saturated hydrocarbon serving as hydrogen donor solvent in specialty chemical synthesis, requiring high-pressure hydrogenation capacity.
- Camphor:Bicyclic monoterpene ketone derived from Cinnamomum camphora distillation or synthetic pinene conversion, subject to natural harvest variability in Southeast Asian sourcing regions.
Most installed capacity flows through cyclohexanone. Expansion is steepest in methylcyclopentanone.
Application:
Application segmentation tracks how molecular stability and evaporation profiles determine addressable market size. Solvent and intermediate applications dominate volume, while fragrance and polymer segments capture premium pricing through certification barriers.
- Solvent:Cyclic ketones serve as reaction media and cleaning agents where controlled volatility and low surface tension prove critical. EPA National Emission Standards for Hazardous Air Pollutants now mandate documentation of recovery rates above 95% for ketone-containing formulations in U.S. paints and coatings manufacturing.
- Chemical Intermediate:Cyclohexanone feeds adipic acid and caprolactam production, anchoring nylon supply chains. REACH registration requirements for existing substances impose 2026 dossier update deadlines that are forcing smaller European producers to consolidate or exit.
- Fragrance:Camphor and methylcyclopentanone derivatives provide top-note character and fixative properties in fine perfumery.
- Polymer:High-purity cyclohexanone enables polycarbonate and polyurethane synthesis for automotive and electronics applications.
Solvent applications retain the largest installed base. Chemical intermediate demand is climbing fastest.
End Use Industry:
Customer concentration varies sharply across end-use industries. Automotive and paints sectors favor contract purchasing with integrated suppliers, while cosmetics and pharmaceuticals reward batch flexibility and certification depth.
- Automotive:Nylon-6 demand for under-hood components and fuel systems drives cyclohexanone consumption. China's caprolactam self-sufficiency push reduces export market access for European and North American producers.
- Paints & Coatings:Reformulation toward lower-VOC solvents is elevating methylcyclopentanone qualification. EU F-Gas Regulation limits on fluorinated compounds are opening formulation switches to cyclic ketone alternatives in industrial coating systems.
- Cosmetics:Natural-origin certification supports margin pools for fragrance-grade camphor in Asia-Pacific cosmetics formulators.
- Pharmaceuticals:Electronic-grade ketone purification for 99.99% purity cyclohexanone serves semiconductor wet chemical demand beyond commodity nylon feedstock.
Paints and coatings absorb the most volume. Pharmaceutical-grade qualification offers the steepest margin expansion.
Distribution Channel:
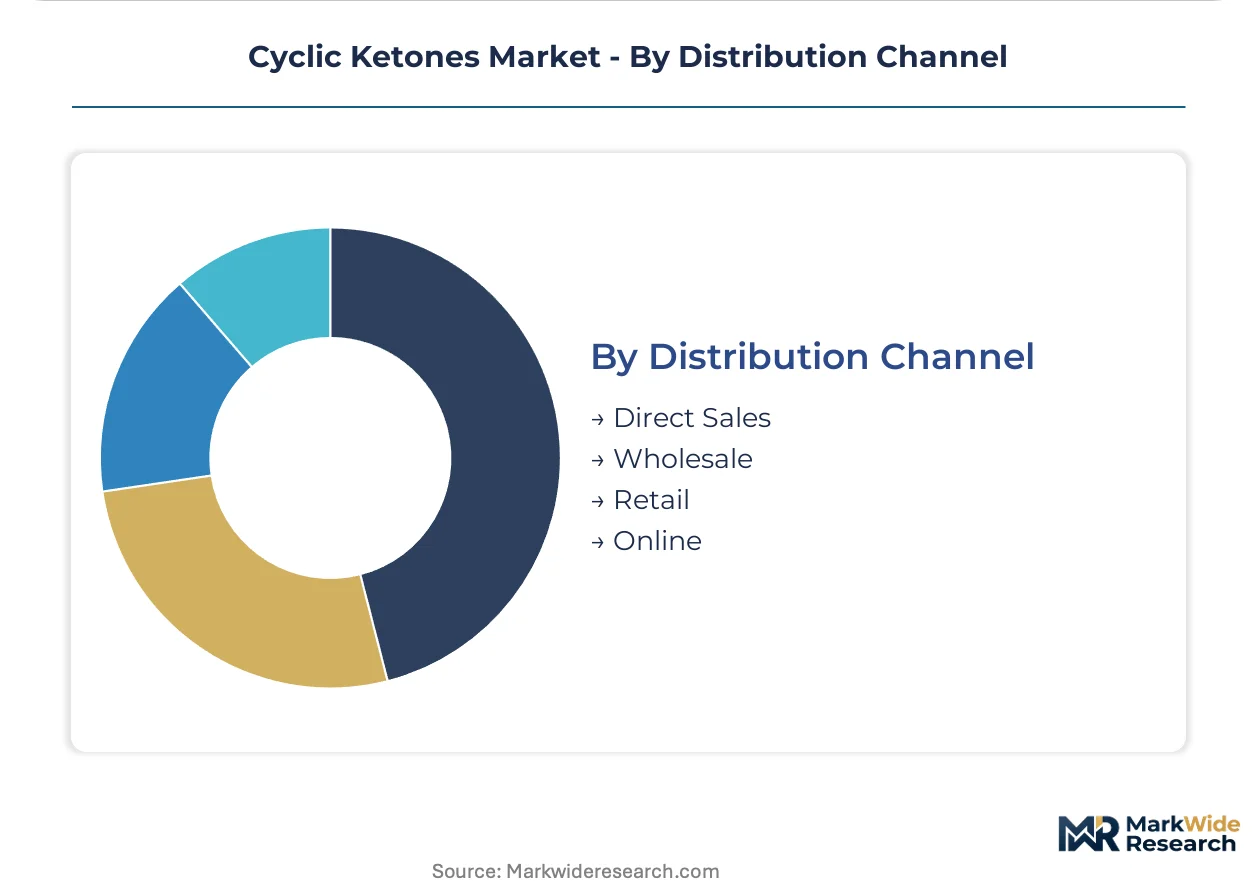
Channel selection reflects customer scale and specification complexity. Bulk chemical intermediates flow through direct sales, while specialty grades fragment across wholesale and qualified retail networks.
- Direct Sales:Long-term offtake agreements dominate cyclohexanone procurement for caprolactam producers. Five-year contracts with integrated phenol makers secure volume certainty against spot market liquidity compression.
- Wholesale:Industrial solvent distributors aggregate methylcyclopentanone and decalin volumes for mid-sized coatings manufacturers.
- Retail:Fragrance-grade camphor reaches cosmetics formulators through specialized chemical retailers with batch traceability systems.
- Online:Digital platforms serve small-batch pharmaceutical and research customers requiring rapid specification confirmation.
Direct sales capture the largest share of ketone volume. Online channels are expanding most quickly for specialty grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where cyclic ketone production migrates, as European REACH compliance costs widen the gap against Asian volume-scale economics. Producers calibrate capacity investments between purity mandates and feedstock integration advantages.
China
Domestic caprolactam producers in Zhejiang and Jiangsu provinces are locking five-year cyclohexanone offtake agreements to secure nylon-6 feedstock for textile polymer supply chains. MEE dual carbon enforcement is accelerating kiln retrofits at cyclohexanone plants. The Yangtze River Delta concentration is compressing spot market liquidity as integrated phenol makers absorb volume.
Germany
BASF SE anchors large-scale cyclohexanone output for captive caprolactam production at its Ludwigshafen complex, defending contract positions through backward integration into phenol feedstocks. REACH registration dossier deadlines are forcing smaller producers to consolidate or exit. The North Rhine-Westphalia chemical cluster is retrofitting hybrid distillation-membrane trains to cut steam consumption.
United States
EPA National Emission Standards for Hazardous Air Pollutants mandate solvent recovery rates above 95% for ketone-containing coatings formulations. ALTIVIA Ketones & Additives and Eastman Chemical Company occupy positions in the specialty solvent segment. The Gulf Coast petrochemical corridor leverages integrated refinery-chemical complexes for feedstock flexibility.
Belgium
Solvay S.A. leverages its integrated phenol-cyclohexanone chain to secure feedstock flexibility across Belgium and France. ECHA purity mandates for fragrance-grade ketones elevate technical barriers for market entry. The Antwerp-Rotterdam chemical hub is concentrating adipic acid producer demand for membrane-separated cyclohexanone grades.
India
BIS standards harmonization with REACH specifications is creating qualification pathways for methylcyclopentanone in coatings applications. Domestic pharmaceutical formulators are sourcing camphor derivatives for regional cosmetics markets. The Gujarat chemical belt is emerging as a specialty solvent formulation center for South Asian industrial coatings demand.
Cyclic Ketones Market Competitive Environment
European producers anchor one tier through integrated phenol-cyclohexanone chains and REACH-certified quality systems; Asian specialists hold volume-scale positions in textile-grade polymer feedstocks. The vendor base splits between consolidated multinational chemical houses and regional mid-cap operators. Three archetypes dominate: backward-integrated phenol makers, fragrance-grade purification specialists, and solvent-focused formulation suppliers. Competitive moves center on long-term offtake contracting and catalytic dehydrogenation technology licensing.
Within the integrated chemical house tier, Solvay S.A., BASF SE, and Shell Chemicals exemplify producers with captive feedstock control and multi-regional manufacturing footprints. These entities occupy positions where phenol integration and caprolactam captive consumption insulate margin structures from benzene volatility. Zhejiang NHU Co., Ltd represents the Asia-Pacific specialist archetype, with a structure suggesting vitamin and fragrance intermediate specialization. Merck KGaA and Zeon Corporation sit within the high-purity electronic-grade segment, where 99.99% purity thresholds command premium positioning beyond commodity nylon feedstock applications.
| Leading Market Players |
|---|
| Solvay S.A. |
| Zhejiang NHU Co., Ltd |
| BASF SE |
| Caffaro Industrie S.p.A. |
| ALTIVIA Ketones & Additives |
| Merck KGaA |
| Zeon Corporation |
| Shell Chemicals |
| Eastman Chemical Company |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracting by caprolactam producers in Zhejiang and Jiangsu provinces is compressing spot market liquidity, forcing supply response through backward integration into phenol feedstocks and widening the bid-ask spread for uncommitted volumes.
Pricing Analysis
Distributor margins on fragrance-grade camphor reach their widest spread at the specialized chemical retailer tier, where batch traceability systems command premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates electronic-grade cyclohexanone from textile-grade and solvent-grade pools. Cost compression in commodity cyclohexanone is intensifying because benzene feedstock volatility erodes conversion economics for non-integrated producers. Chemical intermediate buyers exhibit the highest price sensitivity due to volume scale and contract concentration, while pharmaceutical-grade purchasers prioritize certification depth over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian Cinnamomum camphora harvests, where natural-origin certification requirements tether fragrance-grade production to unpredictable biomass yields. Manufacturing concentrates in China, Germany, and Belgium, with cyclohexanone output anchored in integrated phenol-cyclohexanone chains. Feedstock dependencies center on benzene, cyclohexane, and pinene derivatives. Tariff exposure on phenol imports into the European Union creates margin risk for non-integrated European producers. Distribution runs through direct sales contracts for bulk intermediates, with wholesale channels aggregating specialty solvent volumes for mid-sized coatings manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cyclic ketones market rewards geographic arbitrage between European REACH compliance costs and Asian volume-scale economics, with the widest cost differential appearing in purity certification and energy efficiency benchmarks.
For Market Incumbents: Anticipate margin compression from China's caprolactam self-sufficiency push by securing captive phenol supply through backward integration into refinery-chemical complexes. Defend contract positions through membrane separation technology licensing that cuts steam consumption and qualifies for MEE dual carbon incentives. Prioritize REACH registration dossier completion before the 2026 deadline to force smaller competitors into consolidation or exit. For New Entrants and Emerging Players: Electronic-grade ketone purification technology offers the most penetrable wedge, with semiconductor wet chemical demand for 99.99% purity cyclohexanone enabling premium positioning beyond commodity nylon feedstock. Target India's methylcyclopentanone coatings segment where BIS standards harmonization with REACH specifications creates qualification pathways without incumbent lock-in. Lead with catalytic dehydrogenation expertise licensing as the go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap fragrance-grade purification specialists holding natural-origin certification relationships with Asia-Pacific cosmetics formulators. Long-term viability hinges on 5-10 year offtake contract visibility rather than spot market exposure. Watch for caprolactam import substitution velocity in China as the inflection indicator for European export market access contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive phenol supply insulates BASF and Solvay from benzene volatility at Ludwigshafen and Antwerp. |
| Long-term Supply Agreement | Five-year cyclohexanone offtake contracts in Zhejiang secure volume certainty against spot liquidity compression. |
| Green Manufacturing Transition | Hybrid distillation-membrane trains at North Rhine-Westphalia plants cut steam consumption for MEE compliance. |
| Capacity Expansion | Electronic-grade purification capacity buildout captures semiconductor wet chemical demand beyond textile polymer feedstock. |
| Joint Venture | India specialty solvent partnerships leverage BIS-REACH harmonization for methylcyclopentanone coatings penetration. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with plant managers, procurement leads at caprolactam producers, distribution channel partners, and technical R&D directors with secondary validation through customs/trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA registration databases. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity across purity grades and regional production hubs.
Input-output matrices map cyclohexanone consumption to nylon-6 polymer output, camphor demand to cosmetics formulation volumes, and methylcyclopentanone uptake to coatings reformulation trends across the analysis window. Segmentation dimensions include grade tier, end-use industry, and regional production hub. CAGRs derive from trend extrapolation of historical consumption patterns adjusted for regulatory enforcement timelines and capacity addition schedules. Forecast inputs incorporate MEE dual carbon benchmark stringency and REACH dossier deadline compliance rates.
The model holds under sustained enforcement of existing purity mandates and energy efficiency benchmarks; deviation in regulatory timeline acceleration or feedstock price volatility would shift volume trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Triethylene Glycol Market
Organic Chemicals
Gamma-Butyrolactone (GBL) Market
Organic Chemicals
Aliphatic Amines Market
Organic Chemicals
Cyclopentanone Market
Organic Chemicals
North America Phenol Market
Organic Chemicals
Para-Tert-Octylphenol (POTP) Market
Organic Chemicals
Chlorocyclopentane Market
Organic Chemicals
Organic Matting Agent Market
Organic Chemicals
Oxo Chemicals Market
Organic Chemicals
Phenolic Board Market
Organic Chemicals
2-Amino-5-Nitrobenzophenone Market
Organic Chemicals
Oryzenin Market
Organic Chemicals
North America Cycloalkanes Market
Organic Chemicals
Chloro -Dimethylsilane (CAS 1066-35-9) Market
Organic Chemicals
Cycloalkanes Market
Organic Chemicals
Terephthalic Aldehyde Market