
 Nonylphenol Market | 2026-2036
Nonylphenol Market Size, Share, and Industry Trends Forecast 2026-2036
Nonylphenol Market Intelligence
Formulation support services, bundled with nonylphenol ethoxylate sales, are consolidating supplier relationships in the detergents sector. Huntsman Corporation leverages its significant scale in performance products to serve this segment. Dow Chemical Company specializes in surfactant chemistry for specific industrial applications, while SI Group competes on the basis of its specialized alkylphenol resin offerings.
Nonylphenol is an organic compound produced via the acid-catalyzed alkylation of phenol with nonene. It primarily serves as a chemical intermediate in the manufacturing of nonylphenol ethoxylates, which function as non-ionic surfactants. The nonylphenol ethoxylates product segment constitutes the largest share of overall consumption. While detergents represent a mature application, demand from agrochemical producers for use in pesticide formulations faces significant regulatory headwinds.
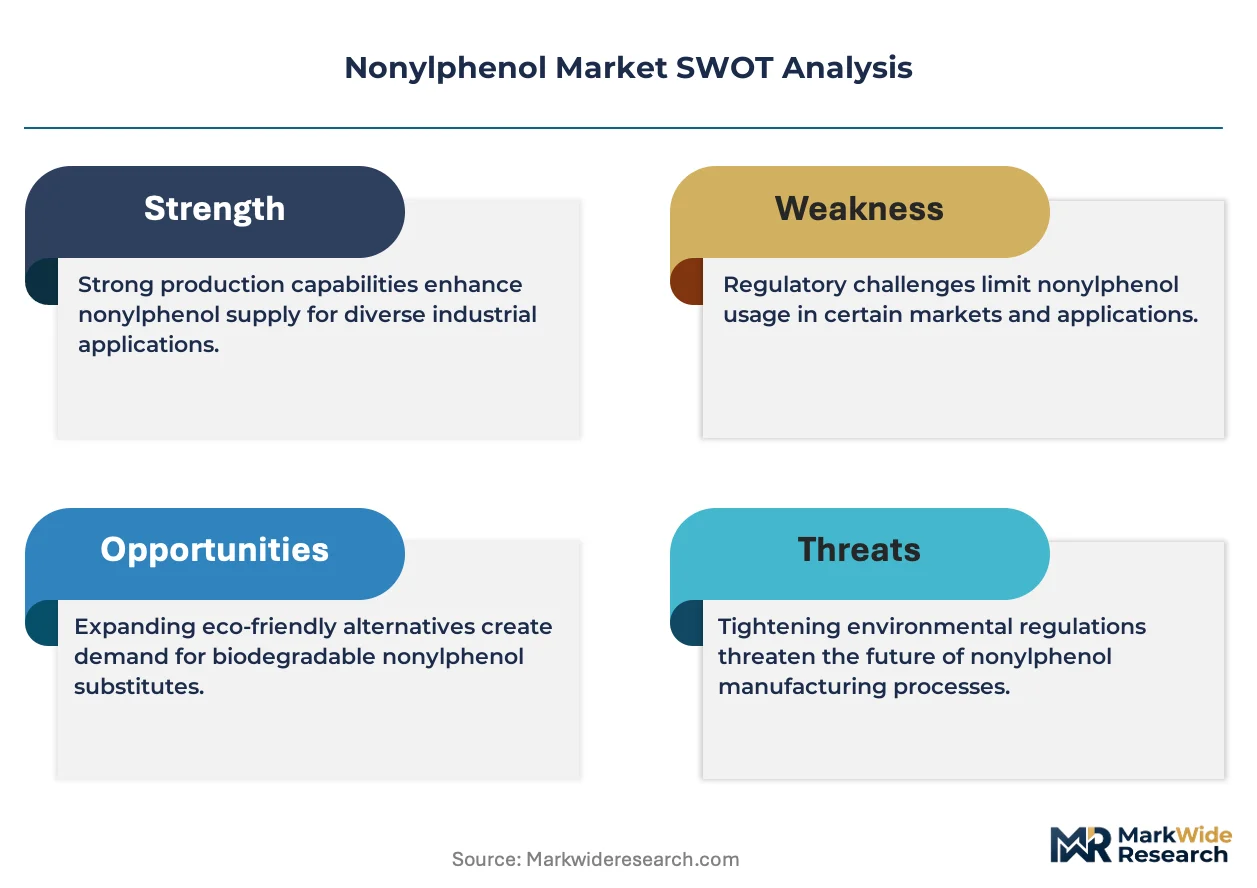
Strict regulations from Europe's ECHA under the REACH framework and scrutiny from the U.S. EPA severely limit market access due to environmental toxicity concerns. These rules mandate substitution in many consumer-facing applications, including household detergents and textiles. The key decision for downstream users is how to balance the functional cost-effectiveness of nonylphenol derivatives against the mounting pressure to adopt greener, albeit more expensive, alternatives.
Market Dynamics
The central structural force shaping the nonylphenol market is regulatory bifurcation, which segregates global demand. Strict limitations under Europe's REACH framework and U.S. EPA scrutiny are pushing consumption into industrial applications within less regulated Asian economies like China and India.
Growth Catalysts
- Agrochemical Demand in Asia:The use of nonylphenol ethoxylates as cost-effective surfactants and wetting agents in pesticide formulations remains a significant driver, particularly in large agricultural economies such as India and China seeking to maximize crop yields.
- Industrial Surfactant Performance:In specialized industrial applications, including oilfield chemicals, lubricants, and institutional cleaners, the unique surfactant properties and performance of nonylphenol derivatives continue to drive consumption where alternatives are less effective.
- Cost-Effectiveness vs. Alternatives:For many price-sensitive industrial end-users, nonylphenol and its derivatives offer a functional cost advantage over greener substitutes like alcohol ethoxylates, preserving their demand base in applications not facing direct regulatory bans.
Market Restraints
- Regulatory Restrictions:The European Union's REACH regulation, administered by ECHA, severely restricts or bans nonylphenol in numerous applications due to its environmental toxicity, effectively closing a major geographic market for many end-uses.
- Substitution by Greener Alternatives:Growing pressure from both regulators and corporate sustainability mandates is forcing formulators to replace nonylphenol ethoxylates with alternatives like alcohol ethoxylates, particularly in consumer-facing products.
- Feedstock Price Volatility:The market is exposed to price fluctuations in its primary feedstocks, phenol and nonene, which are derived from crude oil. This volatility creates margin pressure and complicates long-term cost planning for producers.
Strategic Opportunities
- High-Performance Resin Development:There is an opportunity in developing and marketing specialized alkylphenol resins for niche industrial uses like high-performance adhesives, coatings, and tires, where their specific functional properties are difficult to replicate.
- Expansion in Unregulated Industrial Niches:Producers can target specific industrial sectors, such as mining and oilfield services, in geographies across Southeast Asia and Latin America where environmental regulations on nonylphenol are less stringent.
- Closed-Loop System Applications:Marketing nonylphenol for use exclusively within closed-loop industrial manufacturing processes presents an opportunity to mitigate environmental release concerns, potentially creating a defensible market segment with a higher compliance barrier.
Industry Challenges
- Complex Compliance Management:Downstream users face the operational challenge of managing complex and divergent regulatory requirements, such as those from the U.S. EPA, which necessitates costly and time-consuming product re-formulation and testing.
- Reputational Risk Management:The classification of nonylphenol as an endocrine disruptor creates significant reputational risk, complicating stakeholder relations and making it difficult to attract investment even for legally permitted applications.
- Supply Chain Fragmentation:Producers must manage increasingly fragmented and complex supply chains to serve distinct, geographically separated markets with different regulatory standards, adding significant logistical overhead and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonylphenol Market |
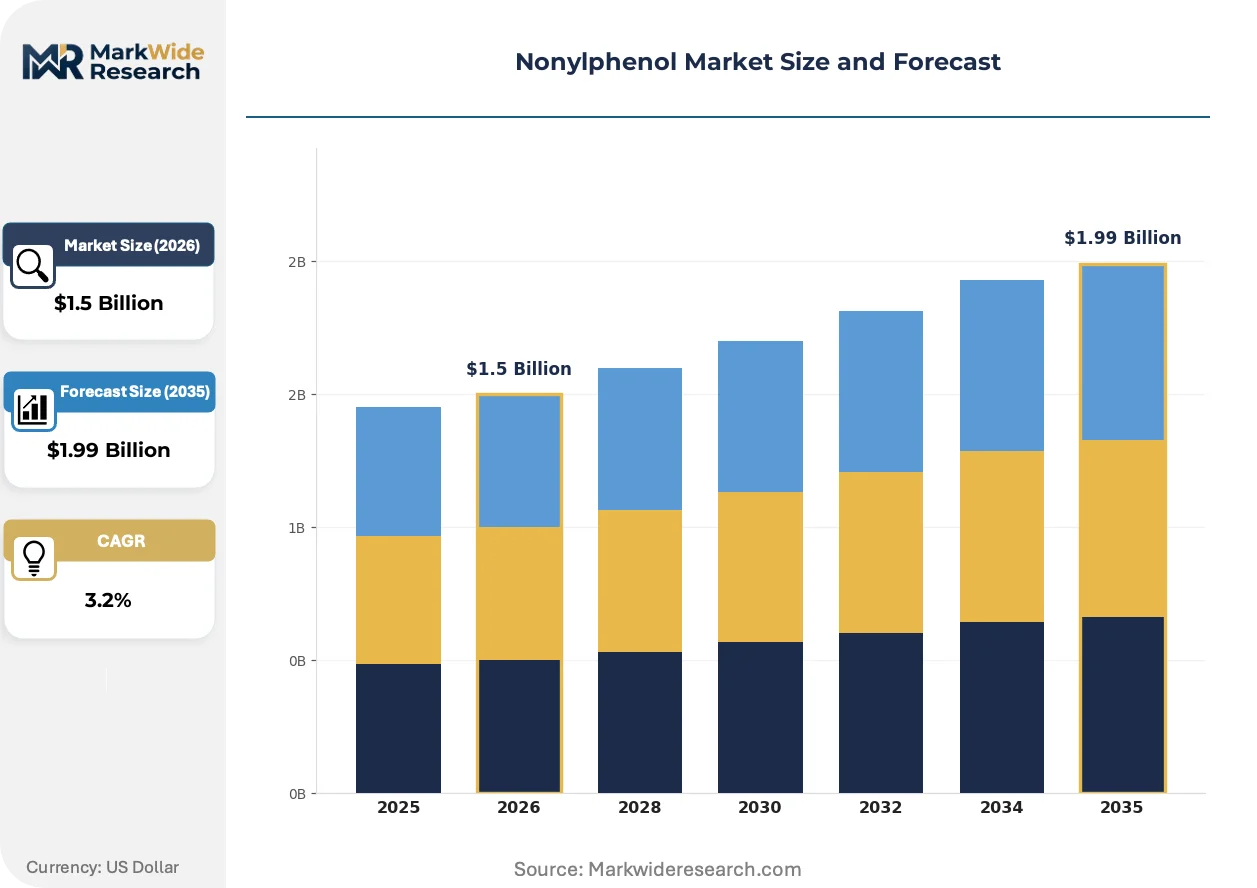
| Market Size in 2026 | $1.5 Billion |
| Market Size in 2035 | $1.99 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nonylphenol Ethoxylates, Nonylphenol, Alkylphenol Resins, Nonylphenol Disulphide Application: Detergents, Pesticides, Paints & Coatings, Rubber Processing, Textile Processing, Adhesives End User: Household Care Manufacturers, Agrochemical Producers, Paint Manufacturers, Textile Processors Packaging Type: Drums, Bags, Bulk Containers, Intermediate Bulk Containers |
| Companies Covered | Huntsman Corporation, BASF SE, Dow Chemical Company, Solvay SA, Stepan Company, Sasol Limited, SI Group, SABIC, India Glycols Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonylphenol Market Strategic Shifts & Innovations
The market's evolution is defined by adaptation to severe regulatory pressure rather than breakthrough molecular innovation. This environment prioritizes process refinement, strategic repositioning, and service-based competition to maintain relevance in shrinking addressable markets and concentrate on industrial strongholds.
Process intensification using technologies like microreactors represents a key evolution in nonylphenol synthesis. Chemical producers are adopting these methods to achieve superior reaction control, increase yield, and minimize the formation of unwanted byproducts. This focus on cleaner synthesis is electrifying the conversation around creating specialized, lower-impact grades for niche industrial uses where performance is critical.
The U.S. EPA's ongoing risk assessments for nonylphenols and their ethoxylates under the Toxic Substances Control Act (TSCA) are a pivotal regulatory trend. This heightened scrutiny compels downstream formulators in sectors like agrochemicals and industrial coatings to proactively identify and validate viable alternatives. The paints and coatings segment is most affected, accelerating its shift to APE-free formulations to preempt future restrictions.
A key demand-side shift involves the bundling of technical formulation support with chemical sales, particularly in the industrial detergents and agrochemical sectors. This model moves the supplier relationship beyond a simple commodity transaction, embedding suppliers more deeply into their customers' product development cycles. This trend is most visible in China and India, where local formulators leverage supplier expertise to meet performance targets.
Nonylphenol Market Segmentation
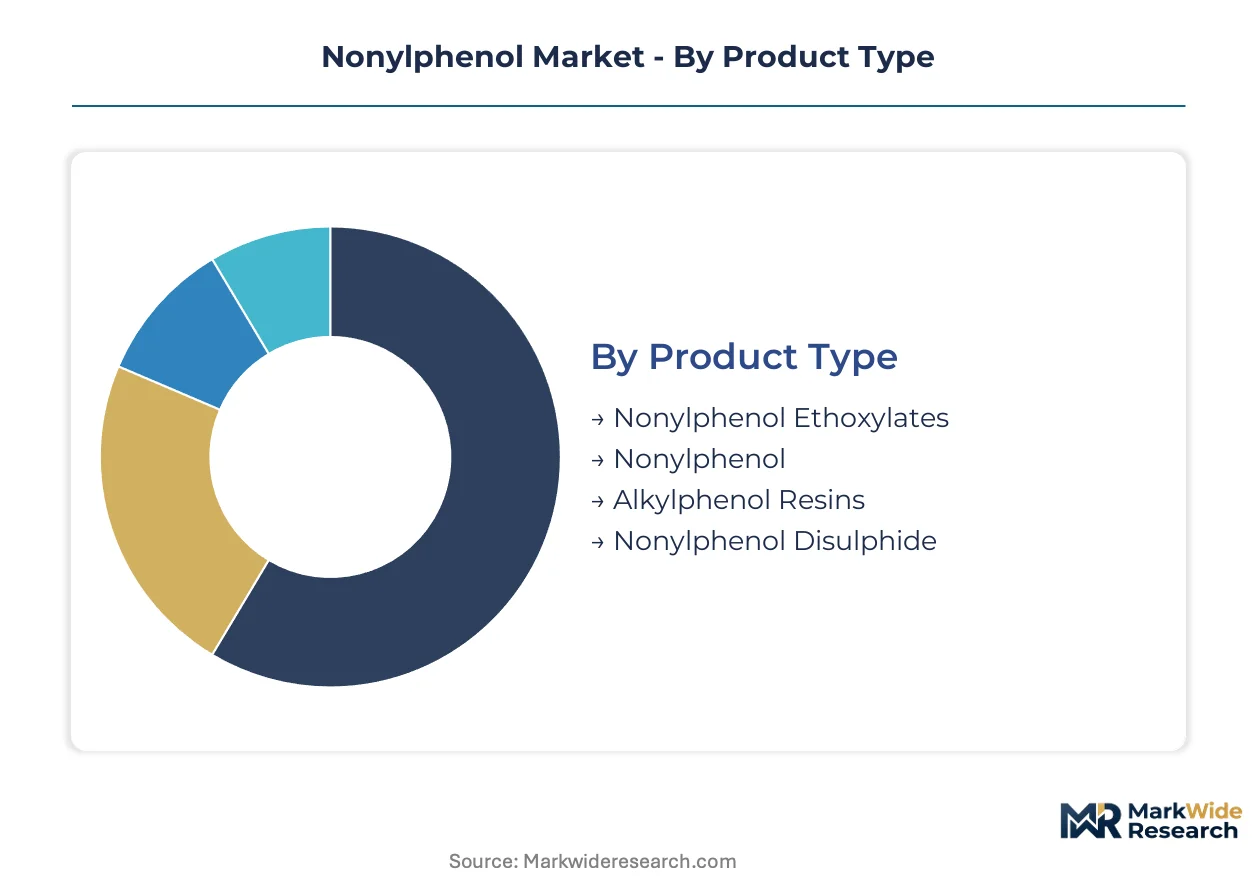
Understanding the nonylphenol market through segmentation reveals the diverse chemical forms and end-use applications driving its consumption. Regulatory pressures and distinct industrial requirements define where specific nonylphenol derivatives find their niche, influencing demand patterns across different sectors.
Product Type:
Buyers in this category differentiate based on the specific chemical properties and downstream utility of each nonylphenol derivative, impacting their suitability for various industrial processes.
- Nonylphenol Ethoxylates:These are non-ionic surfactants produced by ethoxylating nonylphenol, offering excellent emulsifying, wetting, and dispersing properties. Demand concentrates in agrochemical formulations in India and China, where they serve as cost-effective wetting agents for pesticides.
- Nonylphenol:This organic compound serves primarily as a chemical intermediate in the synthesis of nonylphenol ethoxylates and other derivatives. Its consumption is foundational to the production of surfactants and resins, particularly in industrial manufacturing hubs in Asia.
- Alkylphenol Resins:These specialized resins are derived from nonylphenol and offer unique properties for high-performance applications like adhesives, coatings, and tires. Their specific functional characteristics drive demand in niche industrial sectors.
- Nonylphenol Disulphide:This derivative finds applications in specific industrial processes, often as an additive or intermediate where its sulfur-containing structure provides distinct chemical benefits.
Volume sits with Nonylphenol Ethoxylates; growth tilts toward Alkylphenol Resins.
Application:
Application demand for nonylphenol derivatives varies significantly by regulatory environment and performance requirements, influencing their adoption rates across industrial and consumer-facing sectors.
- Pesticides:Nonylphenol ethoxylates function as cost-effective surfactants and wetting agents within pesticide formulations, improving their efficacy and spread. This application remains a significant driver in large agricultural economies like India and China, aiming to maximize crop yields.
- Detergents:This represents a mature application for nonylphenol ethoxylates, leveraging their surfactant properties for cleaning and emulsification. However, demand in household detergents faces significant regulatory headwinds from Europe's ECHA, mandating substitution.
- Paints & Coatings:Nonylphenol derivatives provide critical emulsifying and dispersing functions in paint and coating formulations, enhancing product stability and performance. The U.S. EPA's scrutiny compels this segment to proactively identify and validate viable APE-free alternatives.
- Rubber Processing:Nonylphenol derivatives serve as processing aids and antioxidants in the rubber industry, contributing to material stability and workability.
- Textile Processing:These compounds act as wetting agents and detergents in textile manufacturing, facilitating dyeing and finishing processes. Regulatory mandates severely limit their use in consumer-facing textile applications.
- Adhesives:Alkylphenol resins, derived from nonylphenol, contribute specific bonding and performance characteristics to various adhesive formulations.
Pesticides represent a primary demand segment, while regulatory shifts are accelerating substitution in Paints & Coatings.
End User:
End-user segments reflect distinct business models and regulatory exposures, shaping their procurement strategies and willingness to adopt alternative chemistries.
- Agrochemical Producers:These manufacturers utilize nonylphenol ethoxylates as crucial adjuvants in pesticide formulations to enhance product performance. Their demand is particularly strong in Asian markets, where agricultural output is a priority.
- Household Care Manufacturers:This segment integrates nonylphenol derivatives into various cleaning products, leveraging their surfactant properties for effective dirt removal. Regulatory pressures from the European Union's REACH framework are forcing significant reformulation efforts.
- Paint Manufacturers:Companies in this sector incorporate nonylphenol derivatives for their emulsifying and dispersing capabilities in paint and coating products. They are increasingly seeking APE-free formulations to preempt future restrictions.
- Textile Processors:These industrial users employ nonylphenol-based chemicals for various stages of textile production, including scouring and dyeing. They face considerable pressure to adopt greener alternatives due to environmental concerns.
Agrochemical Producers drive substantial volume, and Paint Manufacturers are actively reformulating towards APE-free alternatives.
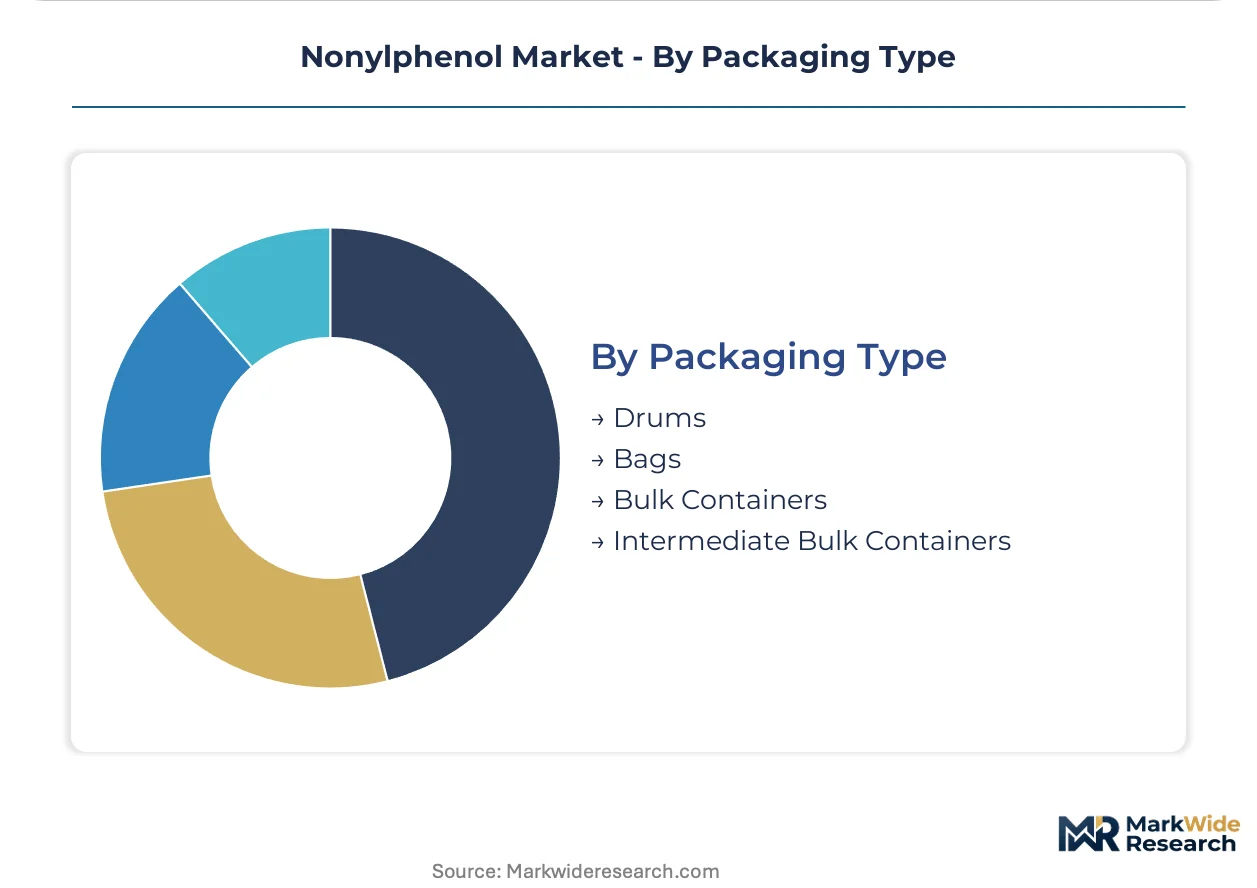
Packaging Type:
The choice of packaging for nonylphenol products is primarily driven by order volume and logistical efficiency for industrial clients, impacting storage and transportation costs.
- Bulk Containers:These large-volume containers, such as tank trucks and railcars, are used for high-volume industrial shipments, providing the most cost-effective transport for major chemical producers. They facilitate direct supply to large-scale manufacturing facilities.
- Drums:Standard 55-gallon drums are a common packaging choice for industrial chemicals, offering a balance between volume and ease of handling for mid-sized orders. They are widely used for distribution to various industrial end-users.
- Bags:This packaging type is typically used for solid forms of nonylphenol derivatives or specific granular products, offering convenience for smaller quantities.
- Intermediate Bulk Containers:IBCs offer a versatile solution for transporting and storing liquid or semi-solid nonylphenol products in volumes larger than drums but smaller than bulk tanks. They provide flexibility for diverse industrial applications.
Bulk Containers facilitate large-scale industrial supply, with Intermediate Bulk Containers offering flexibility for mid-sized requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta, a key industrial hub in China, drives significant nonylphenol consumption within its chemical manufacturing and agrochemical sectors. This region benefits from established infrastructure and a robust demand base for industrial intermediates. Regulatory frameworks in China influence local production and usage patterns.
China
China's agricultural sector demands nonylphenol ethoxylates as cost-effective pesticide adjuvants, enhancing crop yield across vast farming regions. The Ministry of Ecology and Environment (MEE) implements policies for cleaner synthesis processes. Industrial clusters in Shandong and Jiangsu provinces host major chemical producers and formulators.
India
India's agrochemical producers rely on nonylphenol ethoxylates for their surfactant properties in pesticide formulations, crucial for food security. The Bureau of Indian Standards (BIS) sets quality benchmarks for chemical intermediates, guiding local manufacturing practices. Chemical processing zones like Gujarat and Maharashtra serve as production hubs.
United States
The United States market sees nonylphenol derivatives primarily in specialized industrial applications, including oilfield chemicals and high-performance resins. The U.S. Environmental Protection Agency (EPA) conducts risk assessments under TSCA, mandating substitution in many consumer products. Gulf Coast chemical complexes remain centers for industrial chemical production.
Germany
Germany's chemical industry utilizes alkylphenol resins for niche applications in high-performance adhesives and coatings, where specific functional properties are critical. The European Chemicals Agency (ECHA) under REACH strictly regulates nonylphenol use, forcing widespread substitution. Chemical parks in the Rhine-Main region innovate around compliant specialty chemicals.
Japan
Japan maintains demand for nonylphenol derivatives in select industrial applications, such as rubber processing and specialized lubricants, valued for their performance characteristics. The Ministry of Economy, Trade and Industry (METI) oversees industrial chemical management, promoting responsible manufacturing. Industrial zones around Tokyo Bay and Osaka Bay are key sites for advanced chemical production.
Nonylphenol Market Key Industry Players
Capital-heavy integrated chemical manufacturers compete with specialty formulators and regional distributors in the nonylphenol market. This structure creates a tiered competitive environment, where scale players dominate feedstock supply and large-volume production. Strategic archetypes include global chemical giants, specialized resin manufacturers, and localized agrochemical additive suppliers. Dominant competitive moves involve geographic expansion into less regulated Asian markets and portfolio diversification towards greener alternatives.
Specialists in formulation support, like Huntsman Corporation, exemplify how suppliers embed themselves into customer product development cycles, particularly in detergents and agrochemicals. Dow Chemical Company occupies a position as a leading surfactant chemistry provider for specific industrial applications, adapting to evolving performance needs. SI Group, with its focus on specialized alkylphenol resins, anchors a segment requiring high-performance material science for niche industrial uses. These companies collectively demonstrate the industry's strategic shift towards specialized offerings and service-based competition in a challenging regulatory environment.
| Leading Market Players |
|---|
| Huntsman Corporation |
| BASF SE |
| Dow Chemical Company |
| Solvay SA |
| Stepan Company |
| Sasol Limited |
| SI Group |
| SABIC |
| India Glycols Limited |
| Others |
Cost & Logistics Intelligence
Regulatory mandates for APE-free formulations in paints and coatings are forcing chemical producers to re-evaluate their offerings. This shift impacts pricing strategies as suppliers balance development costs with market acceptance for alternatives.
Pricing Analysis
Pricing pressure intensifies in the nonylphenol market as regulatory restrictions in key regions drive substitution towards more expensive alternatives. The market largely operates on a contract-based long-term offtake model for large industrial users, while smaller volumes trade at commodity spot prices. Price differentiation stems from volume scale, specialized formulation support, and geographic delivery costs. Agrochemical producers in Asia exhibit high price sensitivity, contrasting with buyers of high-performance alkylphenol resins who prioritize functional properties over cost.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks facilitate the movement of nonylphenol derivatives to diverse industrial clients. Supply concentration for nonylphenol production centers on chemical manufacturing hubs in China, India, and the United States. The supply chain draws heavily from raw materials like phenol and nonene, making it vulnerable to crude oil price volatility. Large industrial users receive direct bulk shipments, while smaller formulators rely on regional distributors for drums and Intermediate Bulk Containers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nonylphenol market is evolving into a consolidation play, as stringent environmental regulations and the shift to greener alternatives pressure smaller, less diversified producers. Strategic adaptation is essential for long-term viability.
For Market Incumbents: Lock in customer relationships by deepening technical formulation support, particularly in agrochemicals and industrial detergents in Asia. Expand capacity and distribution networks within less regulated industrial niches in Southeast Asia and Latin America to counter regulatory substitution pressures in developed markets. Invest in R&D for high-performance alkylphenol resins, offering superior functional properties that justify their cost. This strategy mitigates reputational risk while preserving market share.
For New Entrants and Emerging Players: A price-point gap exists between highly regulated premium alternatives and cost-effective nonylphenol derivatives in specific industrial applications. Target specialized industrial sectors like oilfield chemicals or mining in China and India, where performance and cost-effectiveness remain paramount. Offer nonylphenol derivatives for closed-loop industrial systems, emphasizing controlled usage and reduced environmental exposure. This go-to-market angle addresses regulatory concerns while serving critical performance needs.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized chemical manufacturers focused on high-performance alkylphenol resins given their difficult-to-replicate functional properties. Consider integrated producers with strong market positions in unregulated industrial segments within Asian economies for long-term viability. Focus on companies demonstrating robust compliance management and R&D for niche applications. A signal to watch is the increased adoption of nonylphenol in closed-loop industrial processes, indicating a defensible market segment.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Supports growing agrochemical demand and industrial applications in less regulated markets. |
| Green Manufacturing Transition | Reduces environmental footprint and enhances product appeal for sustainability-conscious buyers. |
| Long-term Supply Agreement | Secures consistent feedstock supply for producers and stable pricing for industrial customers. |
| Joint Venture for Specialty Resins | Accelerates innovation and market penetration in high-performance niche applications. |
| Product Launch of APE-Free Alternatives | Addresses regulatory pressures and expands market access in consumer-facing segments. |
Research Approach
Document review covered customs and trade data, chemical industry association reports, and SEC 10-K filings, complemented by interviews with plant managers, procurement leads at downstream OEMs, and technical R&D directors. This approach integrated primary insights with secondary validation to build a robust understanding of market dynamics. Bottom-up data aggregation and top-down market sizing ensured comprehensive coverage and accuracy.
Historical market performance was cross-referenced with expert panel input to project future trends across the analysis window. The analytical framework modeled market demand by product type, application, end user, and packaging type, incorporating regional regulatory clusters. Compound annual growth rates were derived from a weighted average of historical trends and anticipated shifts in regulatory enforcement timelines. Feedstock price trends also informed volume projections.
Inputs from regulatory agency publications and industry reports were available through the study window; gaps in real-time supply chain data introduce uncertainty bands. Forecasts reflect stated assumptions regarding regulatory stability and feedstock availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Organic Chemicals Market
Organic Chemicals
2-Amino-5-Nitrobenzophenone Market
Organic Chemicals
Organic Rheological Modifiers Market
Organic Chemicals
Dioxolane Market
Organic Chemicals
1,3-Dioxolane Market
Organic Chemicals
Isophthalic Acid Market
Organic Chemicals
Acrylic Acid Market
Organic Chemicals
Mercaptopropionic Acid Market
Organic Chemicals
Ethylamine Market
Organic Chemicals
Pentachlorophenol Market
Organic Chemicals
4-Tert-Amylphenol Market
Organic Chemicals
Europe Lactic Acid Market
Organic Chemicals
Trimethylcyclohexanone Market
Organic Chemicals
Organic Hydrosols Market
Organic Chemicals
Global Biphenyl Market
Organic Chemicals
Cyclopentanone Market