
 Global Benzoic Acid Market | 2026-2036
Global Benzoic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Benzoic Acid Market Foresight
A shift from outsourced to in-house toluene oxidation capacity is hardening among major benzoic acid suppliers. BASF SE anchors European production through backward integration into petrochemical feedstocks. Wuhan Youji Industries dominates Chinese output with captive supply of raw materials. Lanxess AG competes on pharmaceutical-grade specialization with tight purity controls.
Benzoic acid is an aromatic carboxylic acid (C₇H₆O₂) synthesized via liquid-phase catalytic oxidation of toluene, serving primarily as a preservative and chemical intermediate across food, pharmaceutical, and industrial applications. Food-grade material sustains the largest volume share as processors seek label-friendly preservation against yeast and mold. Pharmaceutical-grade benzoic acid registers the fastest expansion as parenteral and topical formulation standards tighten. Plasticizer applications occupy a mature demand pocket tied to phthalate-alternative flexible PVC compounds.
FDA food additive regulations under 21 CFR 184.1021 govern permissible levels in beverages and baked goods, while REACH restricts residual toluene content in EU-sourced material. China's GB 2760 national food safety standard and India's FSSAI preservative limits create a fragmented compliance landscape for exporters. Stakeholders must monitor evolving purity thresholds and regional certification requirements to sustain cross-border supply relationships.
Market Dynamics
Backward integration into petrochemical feedstocks is consolidating production control among major benzoic acid suppliers, compressing margins for merchant-market participants dependent on spot toluene purchases.
Growth Catalysts
- Pharmaceutical-grade purity standards:Parenteral and topical formulation requirements are tightening across FDA and EMA jurisdictions, pulling high-purity benzoic acid into sterile drug manufacturing.
- China's dual carbon goals:MIIT efficiency mandates are accelerating cleaner toluene oxidation technology adoption, reducing unit energy consumption in coastal production zones.
- Phthalate-alternative plasticizers:REACH restrictions on conventional plasticizers are redirecting flexible PVC compounders toward benzoic acid-derived esters for medical tubing and food-contact films.
Market Restraints
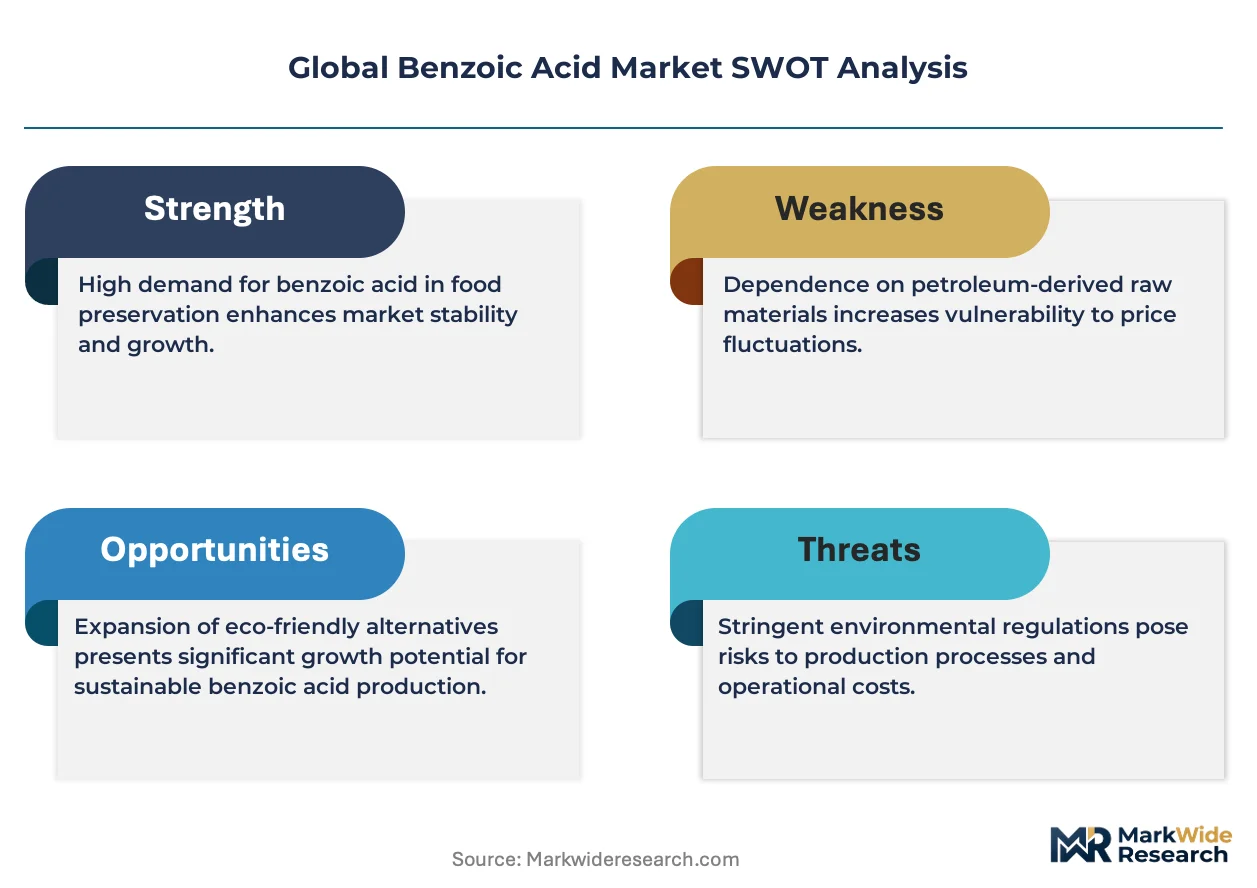
- Toluene price volatility:Crude-linked aromatic feedstock costs swing with refinery operating rates, squeezing margin predictability for non-integrated processors.
- Supply concentration in East Asia:Over sixty percent of merchant capacity sits within 500 kilometers of Wuhan, exposing buyers to single-point logistics disruptions.
- Benzoate salt substitution:Sodium benzoate pre-dissolved solutions are capturing ready-to-drink beverage preservation, displacing acid crystalline form in liquid formulations.
Strategic Opportunities
- India's FSSAI enforcement expansion:Rural food processing formalization is creating first-time preservative demand among packaged snack manufacturers in Maharashtra and Gujarat.
- Biobased toluene pathways:Pyrolysis oil upgrading and lignin depolymerization are converging with conventional oxidation, offering carbon-accounted material for EU Green Deal-aligned buyers.
- Direct-to-formulator e-procurement:Specialty chemical platforms are disintermediating traditional distributors for pharmaceutical-grade volumes below container-load thresholds.
Industry Challenges
- Process safety engineering talent:Liquid-phase oxidation hazard management expertise is scarce outside legacy petrochemical regions, constraining brownfield expansion timelines.
- Multi-jurisdiction certification lag:Simultaneous FDA, REACH, and FSSAI food-grade approvals require twelve-to-eighteen-month documentation cycles, delaying new entrant market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Benzoic Acid Market |
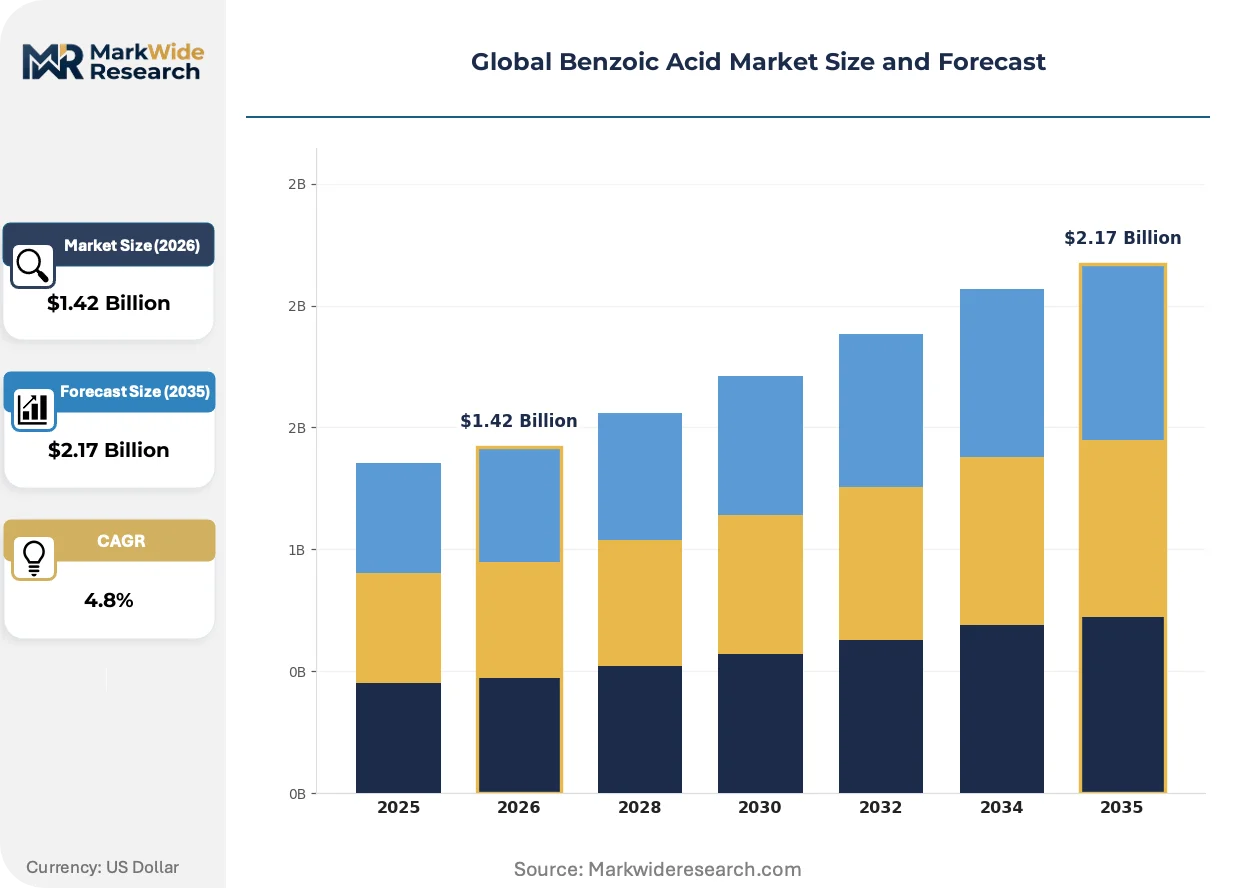
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Cosmetic Grade Application: Preservatives, Plasticizers, Dyes & Pigments, Flavoring Agents, Corrosion Inhibitors End User Industry: Food & Beverage, Pharmaceuticals, Personal Care, Paints & Coatings, Chemical Manufacturing Packaging Type: Drums, Bags, Bulk Containers, Carboys |
| Companies Covered | Merck KGaA, Eastman Chemical Company, BASF SE, Lanxess AG, IG Petrochemicals Ltd, Emerald Performance Materials, Novaphene, Wuhan Youji Industries, Chemcrux Enterprises Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Benzoic Acid Market Shifts & Advancements
Continuous processing technology and regulatory alignment pressures are compressing batch-cycle economics while elevating quality assurance investments across the benzoic acid value chain.
Membrane-based toluene recovery systems are unifying oxidation reactor effluent treatment with solvent loop closure. Pharmaceutical manufacturers in Germany and Switzerland are adopting these units to meet tightening residual hydrocarbon limits. The technology is unifying environmental compliance with yield protection, reducing purge losses by half versus conventional distillation.
REACH Annex XVII amendments on residual toluene content are forcing EU-sourced material toward sub-50 ppm specifications. Downstream food-contact film producers must now certificate every lot through accredited laboratories. Italian and Spanish compounders are responding by locking multi-year supply agreements with integrated producers holding in-house analytical capabilities.
Formulator procurement teams are consolidating vendor panels from six suppliers to two, favoring integrated producers with captive oxidation capacity and redundant quality systems. This concentration is displacing spot-market purchasing in Western European pharmaceutical applications. The shift is most visible among German generic drug manufacturers seeking supply security for FDA-inspected facilities.
Global Benzoic Acid Market Segmentation
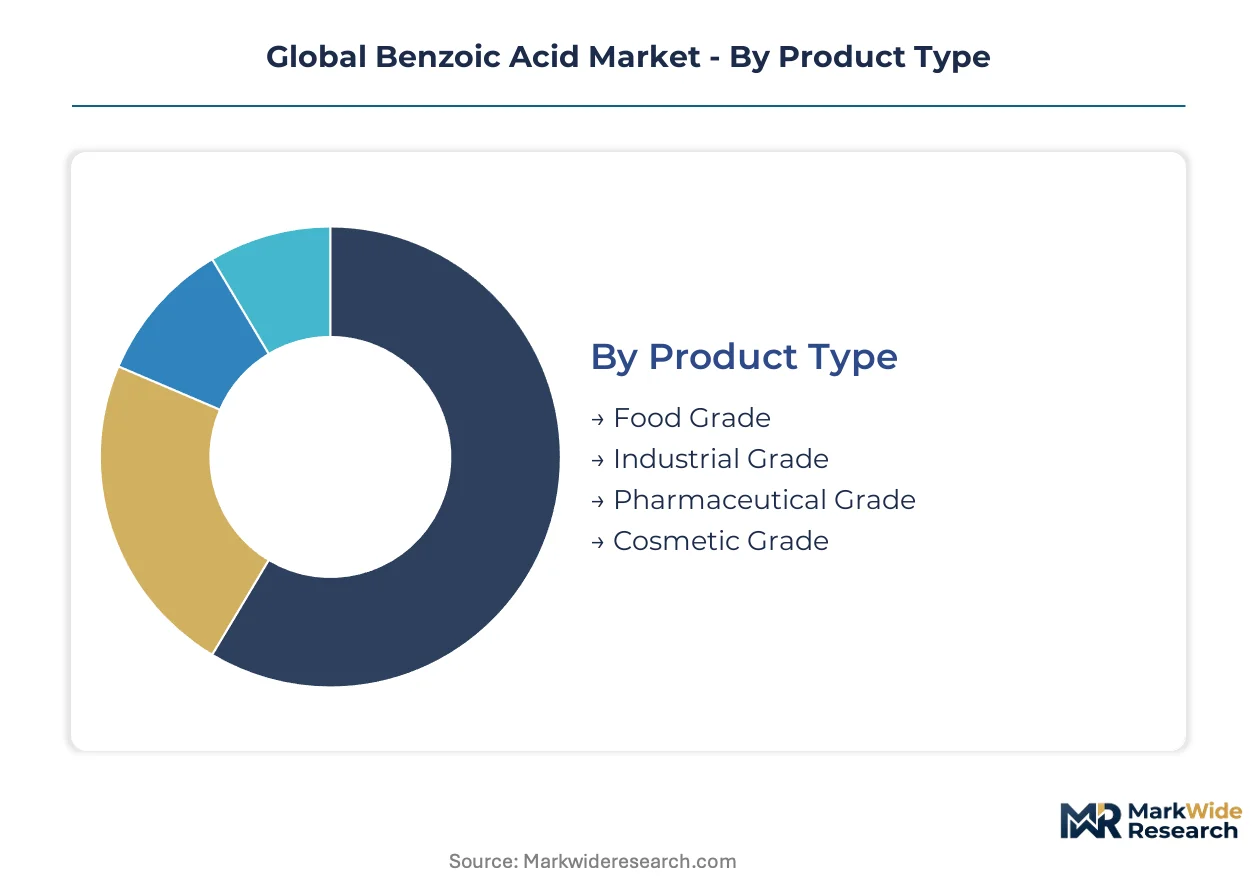
Benzoic acid segmentation reflects divergent purity specifications and regulatory pathways across end-use industries. Food-grade material operates under direct additive regulations, while pharmaceutical and industrial grades follow compound-specific certification regimes. Understanding these segment boundaries clarifies margin structures and competitive positioning for suppliers.
Product Type:
Integration depth varies sharply: food and pharmaceutical grades demand standalone quality systems, while industrial grades embed into broader chemical manufacturing workflows.
- Food Grade:Crystalline material meeting FDA 21 CFR 184.1021 and EFSA purity thresholds for direct food contact. Demand concentrates in beverage preservation and baked goods across Germany and the United States, where processors seek mold inhibition without sensory impact. Substitution pressure from sodium benzoate pre-solutions constrains crystalline acid volumes in ready-to-drink formulations.
- Pharmaceutical Grade:Material exceeding USP-NF and EP monograph specifications for parenteral, topical, and oral drug applications. Demand concentrates in sterile manufacturing facilities in Switzerland and India, driven by tightening endotoxin and heavy metal limits for injectable formulations. EMA and FDA inspection intensity elevates documentation burdens for suppliers.
- Industrial Grade:Standard-purity feedstock for chemical synthesis and alkyd resin production. Captive consumption dominates among integrated toluene oxidation operators.
- Cosmetic Grade:Low-odor material meeting EU Cosmetics Regulation preservative limits. Niche volumes serve formulation houses in France and Italy.
Food Grade leads volumes today; Pharmaceutical Grade is gaining share fastest.
Application:
Application segmentation tracks cost tier differentiation, with premium-priced pharmaceutical and food preservatives separating from commodity industrial uses.
- Preservatives:Direct antimicrobial application in food, beverages, and cosmetics. Demand concentrates in carbonated soft drinks and acidic sauces across China and Mexico, where pH-dependent efficacy aligns with formulation requirements. FSSAI enforcement expansion in rural India is creating first-time packaged food preservation demand.
- Plasticizers:Benzoic acid esters serve as phthalate alternatives in flexible PVC for medical tubing and food-contact films. REACH Annex XVII restrictions on conventional plasticizers redirect compounder procurement in Italy and Spain toward certified benzoate esters.
- Dyes & Pigments:Intermediate for benzoyl chloride and subsequent pigment synthesis. Mature demand tied to textile and printing ink production.
- Flavoring Agents:Precursor for benzaldehyde and synthetic flavor compounds. Limited volumes serve confectionery and beverage flavor houses.
- Corrosion Inhibitors:Metalworking fluid additive and antifreeze formulation component. Industrial maintenance cycles drive cyclical demand.
Preservatives dominate current offtake; Plasticizers show the steepest expansion trajectory.
End User Industry:
Customer type segmentation reveals volume-maturity divergence, with food processors representing established scale and pharmaceutical buyers driving specification intensity.
- Food & Beverage:Largest consumption sector spanning processors of sauces, beverages, and preserved fruits. Demand concentrates in multinational manufacturing facilities in China and Brazil, where centralized procurement favors qualified supplier lists. GB 2760 compliance requirements shape supplier selection for export-oriented facilities.
- Pharmaceuticals:Sterile and non-sterile drug manufacturers requiring certificate-of-analysis documentation per lot. Demand concentrates in FDA-inspected facilities in Germany and India, where generic drug volume growth elevates excipient consumption. Multi-jurisdiction approval timelines constrain new supplier entry.
- Personal Care:Cosmetic and toiletry formulators using benzoic acid as a preservative system component. EU Cosmetics Regulation Article 15 concentration limits govern formulation practices.
- Paints & Coatings:Alkyd resin and coating additive applications. Industrial construction cycles influence regional demand patterns.
- Chemical Manufacturing:Captive consumption for benzoyl chloride, phenol, and other derivative synthesis. Integrated producers internalize this demand.
Food & Beverage anchors volume scale; Pharmaceuticals commands the highest purity premiums.
Packaging Type:
Packaging segmentation follows supply concentration geography, with bulk formats dominating integrated production zones and smaller units serving dispersed formulation customers.
- Drums:Standard 200-liter steel or polyethylene containers for pharmaceutical and food-grade shipments. Preferred by mid-scale processors in Europe and North America requiring manageable batch sizes.
- Bags:Multi-layer paper or woven polypropylene sacks for industrial-grade material. Common in Chinese domestic distribution to compounders and resin manufacturers.
- Bulk Containers:ISO tanks and flexitanks for high-volume intercontinental shipment. Favored by multinational food processors with dedicated unloading infrastructure.
- Carboys:Smaller-volume glass or plastic containers for laboratory and pilot-scale pharmaceutical use. Limited volumes serve R&D and quality control functions.
Drums and Bulk Containers split volume leadership; Bag shipments are climbing fastest in Asian domestic trade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wuhan anchors global benzoic acid production capacity through clustered toluene oxidation facilities serving export markets. Regulatory fragmentation across FDA, REACH, and FSSAI jurisdictions shapes supplier qualification requirements. Industrial buyers in Germany and India concentrate procurement among backward-integrated producers with captive feedstock control.
China
Food-grade preservation demand from carbonated beverage manufacturers in Guangdong and Zhejiang sustains domestic offtake volumes. MIIT dual carbon mandates accelerate cleaner oxidation technology adoption in coastal production zones. Wuhan Youji Industries anchors the Yangtze River Delta cluster with integrated toluene supply chains serving pharmaceutical exporters.
Germany
Pharmaceutical-grade specifications from EMA tighten endotoxin and heavy metal thresholds for parenteral drug applications. REACH Annex XVII residual toluene limits below 50 ppm force compounders toward certified suppliers with in-house analytical capabilities. BASF SE anchors production in Ludwigshafen through backward integration into petrochemical feedstocks.
India
FSSAI enforcement expansion into Maharashtra and Gujarat rural processing zones creates first-time preservative demand among packaged snack manufacturers. CDSCO pharmaceutical excipient standards align with USP-NF monographs for generic drug exports. Mumbai-Pune corridor facilities concentrate sterile formulation manufacturing for FDA-inspected facilities.
United States
FDA 21 CFR 184.1021 governs permissible benzoic acid levels in beverages and baked goods across multinational processor facilities. EPA residual hydrocarbon discharge permits influence toluene oxidation plant siting decisions. Texas Gulf Coast petrochemical infrastructure supports integrated production economics for domestic food-grade supply.
Switzerland
Swissmedic pharmaceutical manufacturing standards exceed EP monograph baselines for sterile drug applications. Basel-Rhine corridor facilities specialize in high-purity excipient production for parenteral formulations. Novartis and Roche supplier qualification programs demand redundant quality systems and multi-jurisdiction certification documentation.
Global Benzoic Acid Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade specialization and biobased feedstock pathways. The vendor base stratifies between integrated petrochemical operators with captive toluene supply and merchant-market processors exposed to aromatic feedstock volatility. Three archetypes dominate: backward-integrated chemical conglomerates, regional specialty chemical manufacturers, and pharmaceutical-grade purity specialists. Capacity consolidation and multi-jurisdiction certification investments represent the dominant competitive moves compressing margins for non-integrated participants.
Among German chemical conglomerates, BASF SE and Lanxess AG exemplify divergent strategic positioning within European production. BASF SE anchors standard-grade volume leadership through Ludwigshafen petrochemical integration. Lanxess AG occupies pharmaceutical-grade specialization with tight purity controls serving Swiss and German sterile drug manufacturers. Wuhan Youji Industries represents Chinese production consolidation with clustered oxidation capacity serving export markets.
| Leading Market Players |
|---|
| Merck KGaA |
| Eastman Chemical Company |
| BASF SE |
| Lanxess AG |
| IG Petrochemicals Ltd |
| Emerald Performance Materials |
| Novaphene |
| Wuhan Youji Industries |
| Chemcrux Enterprises Ltd |
| Others |
Supply & Pricing Matrix
Process safety engineering talent scarcity in the Texas Gulf Coast and Ludwigshafen corridors widens labor-cost spreads between pharmaceutical-grade and industrial-grade production tiers. REACH Annex XVII residual toluene limits below 50 ppm compress margins for non-integrated compounders while rewarding backward-integrated operators with captive analytical capabilities.
Pricing Analysis
Toluene feedstock pass-through mechanics dominate benzoic acid pricing, with crude-linked aromatic costs swinging contract negotiations between integrated producers and merchant-market buyers. Three-tier pricing structure across pharmaceutical, food, and industrial grades separates USP-NF certified material from standard-grade crystalline acid. Pricing pressure stems from sodium benzoate pre-solution substitution in ready-to-drink beverages, eroding crystalline acid premiums. Food processors in China and Mexico exhibit highest price sensitivity, while Swiss sterile drug manufacturers accept purity premiums for endotoxin-controlled supply.
Supply Chain Analysis
Benzoic acid supply rests on toluene oxidation capacity concentrated in China, Germany, and India, with over sixty percent of merchant volume originating within 500 kilometers of Wuhan. Aromatic feedstock, cobalt-manganese-bromide catalyst systems, and membrane-based solvent recovery units constitute critical input dependencies. Single-point logistics exposure in the Yangtze River Delta presents structural vulnerability to buyers seeking supply security. Distribution runs through ISO tank intercontinental shipment for multinational food processors and 200-liter drum delivery for mid-scale pharmaceutical compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The benzoic acid market functions as a regulatory compounder where REACH Annex XVII amendments on residual toluene content are accelerating demand migration toward certified integrated suppliers.
For Market Incumbents: Anticipate sodium benzoate pre-solution substitution by locking multi-year supply agreements with German and Swiss generic drug manufacturers seeking FDA-inspected facility qualification. Deepen backward integration into petrochemical feedstocks to compress toluene price volatility exposure. Prioritize membrane-based toluene recovery technology deployment to meet tightening EMA hydrocarbon discharge limits.
For New Entrants and Emerging Players: Begin with India's FSSAI enforcement expansion into Maharashtra and Gujarat rural processing zones, where first-time packaged snack preservation demand outruns qualified supplier availability. Target pharmaceutical-grade specialization for parenteral formulation applications, as endotoxin and heavy metal documentation burdens constrain incumbent capacity expansion. Pursue direct-to-formulator e-procurement channel entry for sub-container-load volumes below traditional distributor thresholds.
For Investors and Strategic Acquirers: Specialty chemical conglomerates with captive oxidation capacity are the most active acquirer in this space, seeking pharmaceutical-grade certification assets. Long-term viability hinges on multi-jurisdiction approval infrastructure spanning FDA, REACH, and FSSAI compliance windows. Watch biobased toluene pathway commercialization as the inflection signal for EU Green Deal-aligned buyer procurement shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive toluene supply insulates BASF and Wuhan Youji from aromatic feedstock volatility. |
| Pharmaceutical-Grade Certification | USP-NF and EP monograph compliance opens sterile drug manufacturing revenue pools. |
| Membrane-Based Solvent Recovery | Italian compounders adopt these units to meet REACH Annex XVII residual hydrocarbon limits. |
| Direct-to-Formulator E-Procurement | Specialty chemical platforms disintermediate distributors for sub-container-load pharmaceutical volumes. |
| Biobased Toluene Pathway Development | Pyrolysis oil upgrading offers carbon-accounted material for EU Green Deal procurement mandates. |
Research Methodology
Bottom-up food and pharmaceutical processor demand modeling reconciled against top-down toluene oxidation capacity tracking forms the analytical core of this study. Primary interviews with plant managers at German and Chinese production facilities, procurement leads at downstream beverage and drug manufacturers, distribution channel partners serving European compounders, and technical R&D directors developing membrane recovery systems combined with secondary validation from customs and trade data, Cefic chemical industry reports, SEC 10-K filings of listed producers, and FDA food additive regulation databases. Triangulation between consumption-side qualification requirements and supply-side certification capabilities anchored volume and value estimates.
Historical trendline analysis of pharmaceutical-grade purity standard escalation and food preservative substitution patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include grade tier differentiation, end-use industry application, packaging format selection, and regional production hub concentration. CAGRs derived from regression analysis of capacity expansion announcements, regulatory milestone timelines, and processor procurement survey responses. Forecast inputs incorporated MIIT dual carbon efficiency mandates and FSSAI rural enforcement expansion trajectories.
Several conditions sit outside the modeled scope, including abrupt toluene supply disruptions from refinery outages, unanticipated REACH Annex XVII amendment acceleration, and breakthrough biobased feedstock cost parity achievement. Forecasts reflect documented assumptions regarding regulatory implementation pacing and processor qualification cycle durations. Feedstock price volatility, single-point logistics concentration, and multi-jurisdiction certification lag represent specific risk factors warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Europe Lactic Acid Market
Organic Chemicals
1,3-Dichloroacetone Market
Organic Chemicals
1,3-Dioxolane Market
Organic Chemicals
Gamma-Butyrolactone (GBL) Market
Organic Chemicals
Ethyl Levulinate Market
Organic Chemicals
North America Phenol Market
Organic Chemicals
Organic Acids Market
Organic Chemicals
Anisole Derivatives Market
Organic Chemicals
Synthetic and Bio-Based Aniline Market
Organic Chemicals
North America Cycloalkanes Market
Organic Chemicals
Organic Chemicals Market
Organic Chemicals
Acetaldehyde Market
Organic Chemicals
N-Hexyl Chloride Market
Organic Chemicals
Alanine Market
Organic Chemicals
Absolute Ethanol Market
Organic Chemicals
2-Iodophenol Market