
 Europe Lactic Acid Market | 2026-2036
Europe Lactic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Lactic Acid Market Foresight
CE marking under the EU Medical Devices Regulation is reorganizing which suppliers can serve pharmaceutical-grade lactic acid buyers across the continent. Corbion N.V. anchors its position through captive fermentation capacity in the Netherlands and backward integration into sugar feedstock sourcing. Jungbunzlauer Suisse AG differentiates via Swiss manufacturing precision and sustained certification depth for food-grade and cosmetic-grade streams. Galactic competes from its Belgian base with specialized liquid-form logistics serving French and German food preservation clients.
Lactic acid is a chiral alpha-hydroxy acid produced through carbohydrate fermentation, typically achieving purity thresholds from 80 percent for industrial uses to 99.5 percent-plus for injectable pharmaceutical applications, functioning primarily as a pH regulator, preservative, and polymer precursor. Food Grade lactic acid dominates volume flows across Southern Europe's packaged food sector, where preservation demand remains structurally entrenched. Pharmaceutical Grade commands the steepest margin pool due to EMA batch-release requirements and limited qualified fermentation capacity. Bioplastics application growth within the broader segment is reshaping procurement patterns as polymer producers seek long-term industrial-grade offtake agreements.
EMA guidelines on excipient quality and REACH registration obligations for industrial chemical uses are tightening purity documentation requirements, effectively raising capital barriers for new fermentation entrants. The EU Green Deal's biodegradability mandates and France's AGEC anti-waste law are channeling food packaging demand toward polylactic acid substitutes, directly amplifying lactic acid offtake. Stakeholders must monitor how ECHA's evolving microplastics restriction proposals redefine competitive boundaries between petrochemical and bio-based feedstock pathways.
Market Dynamics
The EU Green Deal's biodegradability mandates are compressing petrochemical polymer timelines and forcing lactic acid producers to scale fermentation capacity ahead of polylactic acid offtake commitments.
Growth Catalysts
- AGEC Anti-Waste Law:France's packaging substitution requirements are accelerating polylactic acid adoption in food contact applications, pulling industrial-grade lactic acid volumes northward.
- Bioplastics Feedstock Contracts:German chemical processors are locking multi-year supply agreements with fermentation operators to secure polymer precursor streams.
- F-Gas Regulation Phase-Down:The EU's fluorinated gas restrictions are eliminating conventional refrigerant foams, expanding polylactic acid's addressable market in thermal insulation.
Market Restraints
- Sugar Feedstock Volatility:European beet sugar price swings directly compress fermentation margins, with Dutch and French producers most exposed to agricultural commodity cycles.
- Qualified Fermentation Capacity Scarcity:Pharmaceutical-grade output remains concentrated among Benelux operators with EMA-certified facilities, creating supply bottlenecks for injectable applications.
- Petrochemical Polypropylene Cost Parity:Low-cost fossil-based alternatives continue to undercut polylactic acid in non-mandated packaging segments, particularly in Southern Europe.
Strategic Opportunities
- Portuguese Industrial-Grade Expansion:Underdeveloped Iberian fermentation infrastructure presents greenfield entry points for bioplastics-focused capacity.
- Cosmetic-Grade Premium Streams:Swiss and Austrian personal care formulators are sourcing high-purity lactic acid for microbiome-friendly product lines, commanding price premiums over food-grade equivalents.
- Carbon Border Adjustment Mechanism:The EU CBAM's phased implementation advantages European fermentation-based production against imported petrochemical lactate esters.
Industry Challenges
- EMA Batch-Release Backlogs:Pharmaceutical-grade certification timelines stretch 18-24 months, freezing capacity allocation decisions for multi-product fermentation plants.
- Retrofitting Legacy Infrastructure:Converting first-generation ethanol fermentation facilities to lactic acid requires specialized strain engineering and contamination control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Lactic Acid Market |
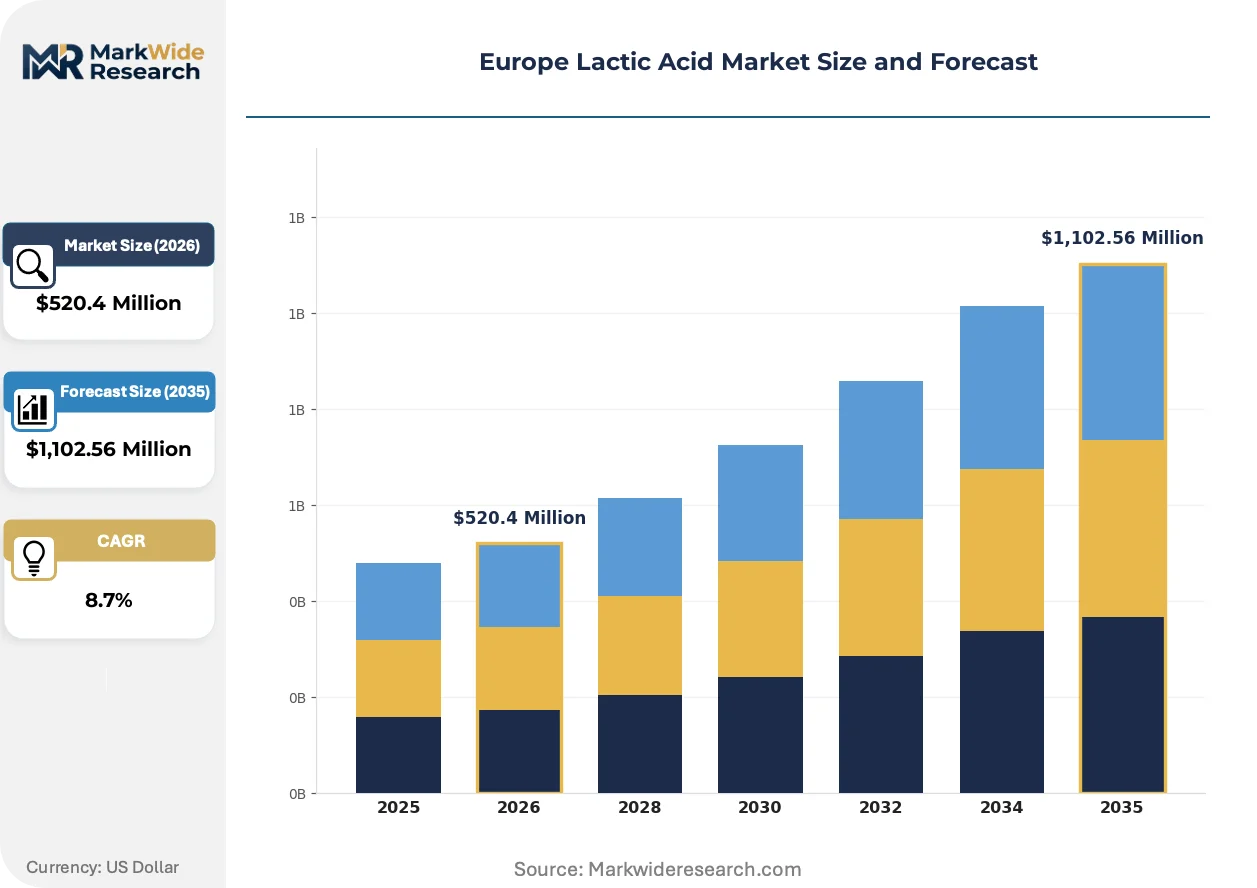
| Market Size in 2026 | $520.4 Million |
| Market Size in 2035 | $1,102.56 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Cosmetic Grade, Pharmaceutical Grade Application: Food Preservation, Bioplastics, Personal Care, Pharmaceuticals Form: Liquid, Powder, Granule, Paste End User: Food & Beverage, Cosmetics, Healthcare, Textile |
| Companies Covered | BASF SE, Jungbunzlauer Suisse AG, Corbion N.V., Vigon International, Inc., Gremount International Company Limited, DuPont de Nemours, Inc., Futerro, Decachimie S.A., Galactic, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Lactic Acid Market Shifts & Advancements
Continuous fermentation systems and cell-free enzymatic conversion are compressing unit economics while regulatory chemistry is rewriting which production pathways qualify for green procurement preferences.
Second-generation lignocellulosic fermentation is displacing first-generation starch-based routes in pilot-scale European facilities. Nordic biorefinery operators are deploying enzymatic hydrolysis of forestry residues to bypass food-versus-fuel competition. The technology is displacing beet sugar dependency in industrial-grade supply contracts, though pharmaceutical purity thresholds remain unattainable without refined carbohydrate feedstocks.
REACH registration obligations for polymer precursors are tightening substance documentation requirements across the value chain. ECHA's evolving microplastics restriction proposals are forcing brand owners to accelerate biodegradable packaging transitions ahead of enforcement deadlines. Food-contact material manufacturers in Germany and France are front-loading polylactic acid qualification programs to secure regulatory headroom.
Long-term offtake contracting is replacing spot-market purchasing among bioplastics compounders seeking supply security. German automotive suppliers and French food packaging converters are negotiating five-year minimum volume agreements directly with fermentation operators. This pattern concentrates procurement leverage among scaled polymer producers while marginalizing distributor intermediaries in the Benelux corridor.
Europe Lactic Acid Market Segmentation
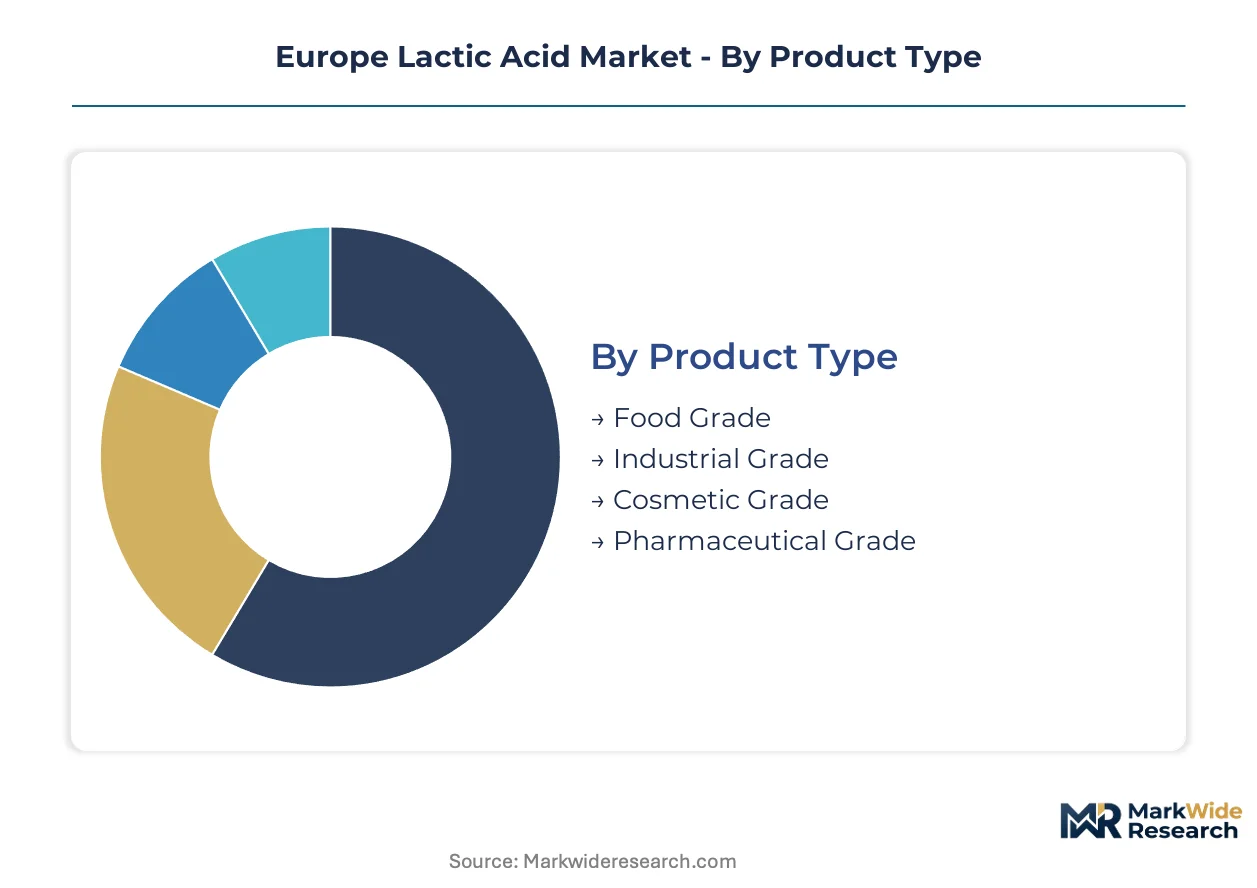
Segmentation in the Europe lactic acid market reflects divergent purity thresholds, each triggering distinct regulatory pathways and margin structures. Food-grade volumes dominate procurement flows while pharmaceutical-grade streams command certification premiums. Bioplastics applications are compressing traditional boundaries between industrial and polymer precursor specifications.
Product Type:
EMA batch-release requirements and EFSA food additive codes create tiered compliance burdens that stratify manufacturing investments across purity bands.
- Food Grade:Specifications align with EFSA additive codes for pH regulation and preservation in packaged goods. Southern European dairy and meat processors in Spain and Italy drive sustained procurement volumes for shelf-life extension applications.
- Pharmaceutical Grade:Injectable purity thresholds demand EMA-certified fermentation facilities with 99.5 percent-plus specifications. Benelux producers with qualified capacity capture margin premiums while supply bottlenecks persist for parenteral formulation clients.
- Industrial Grade:80-85 percent purity streams supply polymer precursor contracts for German and French bioplastics compounders.
- Cosmetic Grade:Microbiome-friendly formulations from Swiss and Austrian personal care brands favor high-purity acid for pH balancing.
Established volume favors Food Grade; emerging adoption favors Pharmaceutical Grade.
Application:
End-use demand concentrates where EU regulatory mandates directly substitute petrochemical alternatives with bio-based feedstocks.
- Bioplastics:Polylactic acid precursor demand from German automotive suppliers and French food packaging converters is locking multi-year offtake agreements. The EU Green Deal's biodegradability mandates and France's AGEC law are accelerating polymer qualification programs ahead of enforcement deadlines.
- Food Preservation:Acidification and antimicrobial functions in cured meats and fermented dairy maintain structural demand across Mediterranean processing clusters.
- Personal Care:Austrian and Swiss formulators source cosmetic-grade streams for exfoliant and pH-buffer applications in microbiome-positioned product lines.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient uses face EMA documentation requirements that limit qualified supplier pools.
Bioplastics climbs the fastest; Food Preservation retains the deepest volume base.
Form:
Logistics economics and handling requirements determine format selection across downstream processing configurations.
- Liquid:Bulk tanker deliveries dominate French and German food manufacturing corridors where direct injection systems minimize handling costs. Belgian suppliers specialize in temperature-controlled liquid logistics for just-in-time preservation lines.
- Powder:Spray-dried formats serve pharmaceutical tablet compression and powder blend applications requiring extended shelf stability.
- Granule:Free-flowing agglomerates reduce dust exposure in industrial polymer compounding operations.
- Paste:High-concentration semisolids target niche cosmetic formulation and specialized adhesive applications.
Liquid commands the procurement majority; Powder captures the steepest per-kilogram premiums.
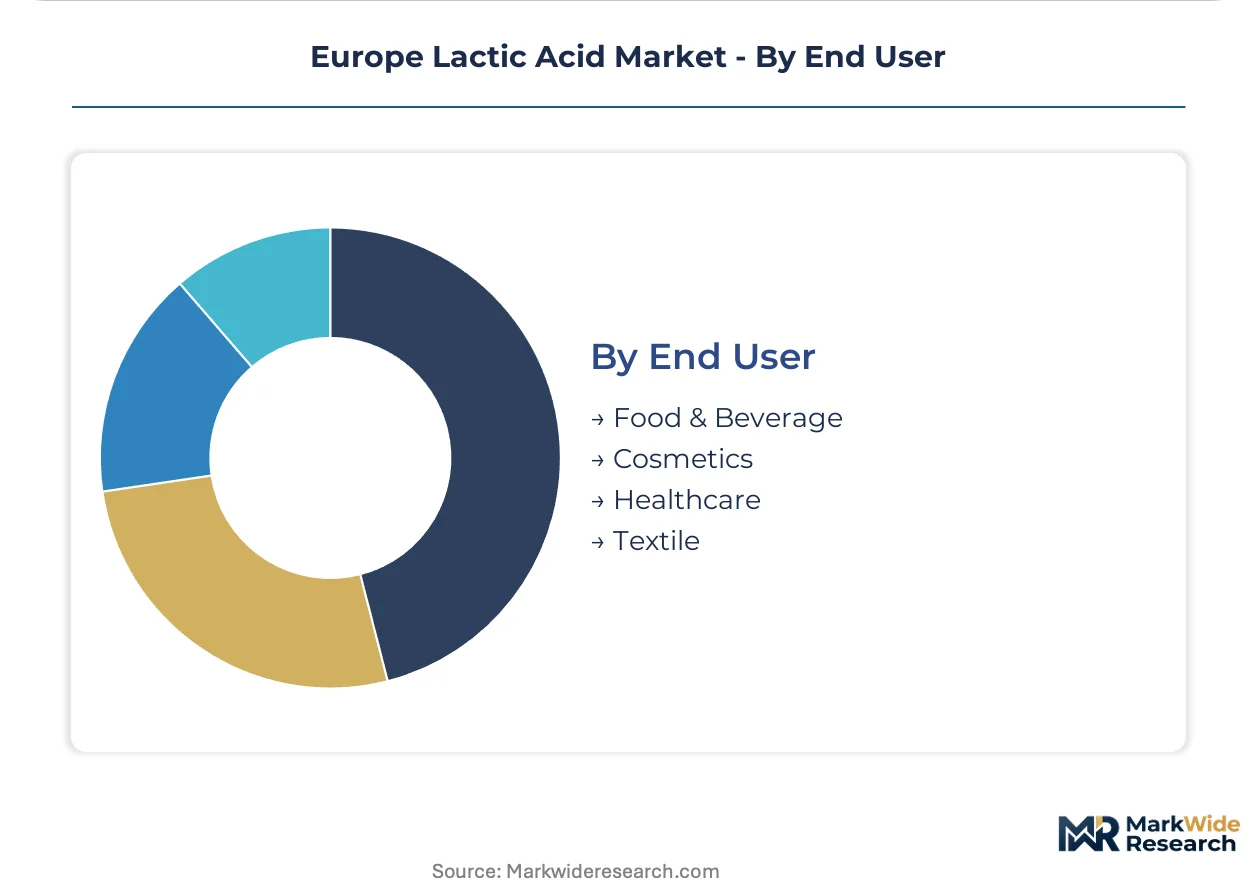
End User:
Customer concentration patterns track regional industrial clustering and regulatory enforcement intensity.
- Food & Beverage:Mediterranean meat curing and dairy fermentation operations in Spain, Italy, and southern France constitute the largest volume sink. EFSA additive compliance remains the primary procurement filter.
- Healthcare:German pharmaceutical manufacturers and Benelux injectable formulators drive pharmaceutical-grade demand. EMA batch-release backlogs extending 18-24 months constrain capacity allocation flexibility.
- Cosmetics:Swiss and Austrian premium personal care brands favor high-purity acid for positioning around skin microbiome compatibility.
- Textile:Dyeing auxiliary and finishing applications in Portuguese and Italian fabric processing represent a contracting industrial segment.
Food & Beverage anchors procurement scale; Healthcare commands margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's biodegradability mandates and France's AGEC anti-waste law are channeling investment toward fermentation capacity expansion across the continent. National implementation timelines vary, creating differentiated procurement pressures from Germany's chemical corridor to Iberian packaging converters.
Germany
Automotive suppliers and food packaging compounders in the Rhine-Ruhr and Bavarian chemical belts are locking multi-year industrial-grade offtake agreements. The national implementation of EU Single-Use Plastics Directive accelerates polylactic acid substitution timelines. Stuttgart-based automotive tier-1 suppliers are qualifying biopolymer feedstocks for interior component applications.
France
AGEC law packaging substitution requirements are pulling industrial-grade volumes toward food-contact polymer production. ECHA microplastics restriction proposals intensify biodegradable qualification programs. The Grand Est and Hauts-de-France regions host expanding fermentation capacity serving Northern European bioplastics demand.
Netherlands
Rotterdam-Antwerp corridor logistics and backward integration into sugar beet feedstock sourcing anchor Benelux fermentation economics. EMA-certified facilities concentrate pharmaceutical-grade output for injectable formulation clients. Dutch biorefinery pilots are testing second-generation lignocellulosic routes to reduce agricultural commodity exposure.
Belgium
Temperature-controlled liquid logistics infrastructure specializes in just-in-time preservation deliveries to French and German food manufacturers. Galactic's Belgian base exemplifies regional distribution optimization for acidification applications. Walloon industrial zones are attracting polymer precursor investment from German compounders seeking supply security.
Switzerland
Jungbunzlauer Suisse AG's Swiss manufacturing precision serves cosmetic-grade and food-grade streams with sustained certification depth. Austrian and Swiss personal care formulators source high-purity acid for microbiome-friendly positioning. Basel-Zurich corridor regulatory expertise supports pharmaceutical excipient documentation requirements.
Europe Lactic Acid Market Competitive Landscape
Player mix skews toward integrated fermentation specialists with captive sugar feedstock sourcing and Benelux-based logistics optimization. Three structural tiers operate: multinational chemical conglomerates with diversified bioproduct portfolios, mid-cap fermentation specialists with regional certification depth, and emerging bioplastics-focused operators securing polymer precursor contracts. Competitive moves concentrate on backward integration into agricultural feedstock control and long-term offtake contracting with automotive and packaging compounders.
Among Netherlands-based integrated specialists, Corbion N.V. anchors the fermentation capacity tier through captive supply chain configuration. Swiss precision manufacturing is represented by Jungbunzlauer Suisse AG, which occupies a position emphasizing certification depth for food-grade and cosmetic-grade streams. Belgian logistics specialization is exemplified by Galactic, sitting within the regional distribution optimization archetype for liquid-form acid delivery.
| Leading Market Players |
|---|
| BASF SE |
| Jungbunzlauer Suisse AG |
| Corbion N.V. |
| Vigon International, Inc. |
| Gremount International Company Limited |
| DuPont de Nemours, Inc. |
| Futerro |
| Decachimie S.A. |
| Galactic |
| Others |
Supply & Pricing Matrix
Long-term offtake contracting between German bioplastics compounders and Benelux fermentation operators locks in both supply access and multi-year price visibility, insulating polymer producers from sugar feedstock volatility while compressing margin flexibility for fermentation specialists.
Pricing Analysis
Certification level creates the primary spread across the European lactic acid market, with EMA-certified pharmaceutical-grade streams commanding substantial premiums over industrial-grade polymer precursors. Three-tier pricing structure separates injectable-grade specifications from food-grade preservation applications from bulk industrial streams. Pricing pressure stems from beet sugar cost volatility, which directly compresses fermentation margins for Dutch and French producers. Food & Beverage buyers exhibit highest price sensitivity due to commoditized preservation applications, while pharmaceutical formulators absorb premiums to secure qualified capacity.
Supply Chain Analysis
Rotterdam-Antwerp port congestion and container availability constraints on North Sea trade lanes periodically disrupt liquid-form acid deliveries to German food manufacturing corridors. Supply concentrates in the Netherlands, Belgium, and France, with Dutch producers leveraging backward integration into sugar beet feedstock sourcing. Raw material dependencies center on European beet sugar, lignocellulosic forestry residues, and specialized fermentation nutrients. Single-source vulnerability persists for pharmaceutical-grade output, where EMA-certified capacity remains limited to qualified Benelux facilities. Distribution runs through temperature-controlled tanker networks serving just-in-time preservation lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities are emerging across the European lactic acid market as bioplastics demand diversifies procurement patterns beyond traditional food preservation buyers, creating niches for specialized grade suppliers and regional logistics optimizers.
For Market Incumbents: Consolidate backward integration into sugar feedstock sourcing to defend margin position against agricultural commodity volatility, while expanding EMA-certified pharmaceutical capacity to capture injectable-grade premiums before batch-release backlogs worsen. Priority investments should target fermentation strain engineering for lignocellulosic conversion, reducing exposure to food-versus-fuel competition. For New Entrants and Emerging Players: Cosmetic-grade microbiome-friendly formulations represent an underserved service layer where Swiss and Austrian personal care brands pay premiums for high-purity acid with sustained certification documentation. Portuguese industrial-grade greenfield capacity offers the most penetrable geography, with Iberian packaging converters seeking supply security outside Benelux concentration. Go-to-market positioning should emphasize carbon footprint differentiation under EU CBAM implementation. For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors fermentation specialists with captive feedstock control and qualified certification depth. Long-term viability hinges on polymer precursor contract duration and regulatory headroom for biodegradable substitution. Acquisition targets should demonstrate multi-year offtake visibility with German automotive or French packaging compounders. Signal to monitor: ECHA microplastics restriction enforcement timelines accelerating polylactic acid qualification programs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sugar Feedstock | Dutch producers anchor margin stability through captive beet supply contracts. |
| EMA Certification Investment | Benelux facilities capture injectable-grade premiums amid qualified capacity scarcity. |
| Lignocellulosic Fermentation Scale-Up | Nordic biorefinery pilots reduce food-versus-fuel exposure via forestry residue conversion. |
| Long-term Supply Agreement | German automotive suppliers lock polymer precursor security through five-year minimum volume contracts. |
| Portuguese Greenfield Capacity | Iberian fermentation infrastructure addresses bioplastics demand outside Benelux supply concentration. |
Research Methodology
Cross-validation between primary interviews with fermentation plant managers, bioplastics procurement leads at German compounders, EMA regulatory affairs specialists, and Dutch distribution channel partners anchors the qualitative findings, while secondary validation draws from Cefic chemical industry reports, EU customs trade data, SEC filings of listed fermentation operators, and ECHA substance registration databases. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates.
Sensitivity analysis around sugar feedstock price scenarios, polymer substitution rates under EU Green Deal mandates, and pharmaceutical-grade capacity expansion timelines informs the analytical framework across the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use application, liquid versus powder form factor, and regional production hub concentration. CAGRs derive from fitted growth curves incorporating bioplastics offtake contract velocity and EMA batch-release queue dynamics.
Underlying assumptions cover sustained EU biodegradability mandate enforcement, functional REACH registration continuity, and sugar beet harvest stability, with deviation risk concentrated in ECHA microplastics restriction acceleration or lignocellulosic technology breakthroughs disrupting feedstock economics. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Crotonic Acid Market
Organic Chemicals
Global Carboxylic Acid Market
Organic Chemicals
Global Biphenyl Market
Organic Chemicals
Chlorinated Isocyanurates Market
Organic Chemicals
Chlorocyclopentane Market
Organic Chemicals
1,3-Dioxolane Market
Organic Chemicals
High Purity Metal Organics Market
Organic Chemicals
Organic Coating Market
Organic Chemicals
North America Biphenyl Market
Organic Chemicals
Acetylacetone Market
Organic Chemicals
N-Hexyl Chloride Market
Organic Chemicals
DMDM Hydantoin Market
Organic Chemicals
Benzethonium Chloride Market
Organic Chemicals
Dioctyl Maleate (DOM) Market
Organic Chemicals
Triethylene Glycol Market
Organic Chemicals
Phenol Market