
 Orange Wine Market | 2026-2036
Orange Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Orange Wine Market Outlook
Premium amphora-fermented expressions is rotating toward the center of Orange Wine Market positioning. Frank Cornelissen leverages volcanic Sicilian terroir to sustain limited-production credibility. Gérard Bertrand Group anchors Languedoc-Roussillon distribution through controlled on-premise placement. Primosic specializes in Ribolla Gialla skin-contact methods that dominate northeastern Italian supply.
Orange wine denotes white grape varieties fermented with extended skin contact, yielding amber pigmentation, phenolic texture, and tannic structure absent in conventional white winemaking. Skin contact durations range from several days to multiple months, with amphora fermentation preserving native yeast character and oxidative stability. Natural orange wine occupies the fastest-growing quality tier as low-intervention protocols attract sommelier and collector interest, while commercial orange wine remains margin-thin and supermarket-dependent. Barrel aging segments concentrate value in aged inventory positions, and specialty wine shops channel the highest per-bottle realization across distribution pathways.
EU Green Deal sustainability targets and EFSA organic certification standards shape vineyard practice and labeling claims across European production zones. REACH chemical compliance and CE marking requirements govern equipment and packaging material access for cellar operations. Stakeholders must monitor how tightening EU organic wine regulations intersect with consumer willingness to absorb certified-premium pricing.
Market Dynamics
Skin-contact fermentation protocols are decomposing traditional white wine category boundaries, as amphora-aged expressions command sommelier attention and displace conventional bottle lists across premium on-premise channels in Italy, Slovenia, and Georgia.
Growth Catalysts
- EU Green Deal vineyard subsidies:EFSA-aligned organic certification incentives accelerate conversion of conventional white grape acreage to low-intervention orange wine production across northeastern Italian cooperatives.
- Natural wine bar proliferation:Specialty retail channels in Tbilisi, Ljubljana, and Milan create dedicated shelf space for extended maceration bottlings, bypassing supermarket distribution entirely.
- Georgia's qvevri heritage registration:UNESCO-recognized clay vessel traditions attract enotourism investment and establish technical credibility for ancestral fermentation methods.
Market Restraints
- Ribolla Gialla supply concentration:Friuli-Venezia Giulia's limited acreage constrains scalable production of benchmark northeastern Italian orange expressions.
- Amphora import logistics:Georgian qvevri and Sicilian clay vessel procurement faces REACH compliance costs and extended EU customs clearance timelines.
- Conventional white wine substitution:Unoaked Chardonnay and Albariño retain price-positioning advantages in casual dining segments resistant to phenolic texture.
Strategic Opportunities
- Austrian skin-contact expansion:Styrian producers leveraging Blaufränkisch and Zweigelt white variants create new Central European supply nodes beyond Italian dominance.
- Direct-to-consumer subscription channels:Natural wine clubs bypass three-tier distribution constraints and capture full margin from collector segments in Copenhagen and Berlin.
- EFSA organic label tiering:Stricter EU certification standards create premium price anchoring for certified bottlings against uncertified competitor claims.
Industry Challenges
- Amphora fabrication skill scarcity:Master qvevri craftsmen in Kakheti and Caltagirone cannot expand production capacity to match cellar equipment demand from new market entrants.
- Oxidative stability batch variance:Native yeast fermentation without temperature control produces inconsistent phenolic extraction, complicating vintage-to-vintage quality standardization.
- Sommelier education gaps:Front-of-house staff in secondary markets lack technical vocabulary to communicate skin-contact duration and terroir differentiation to skeptical consumers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orange Wine Market |
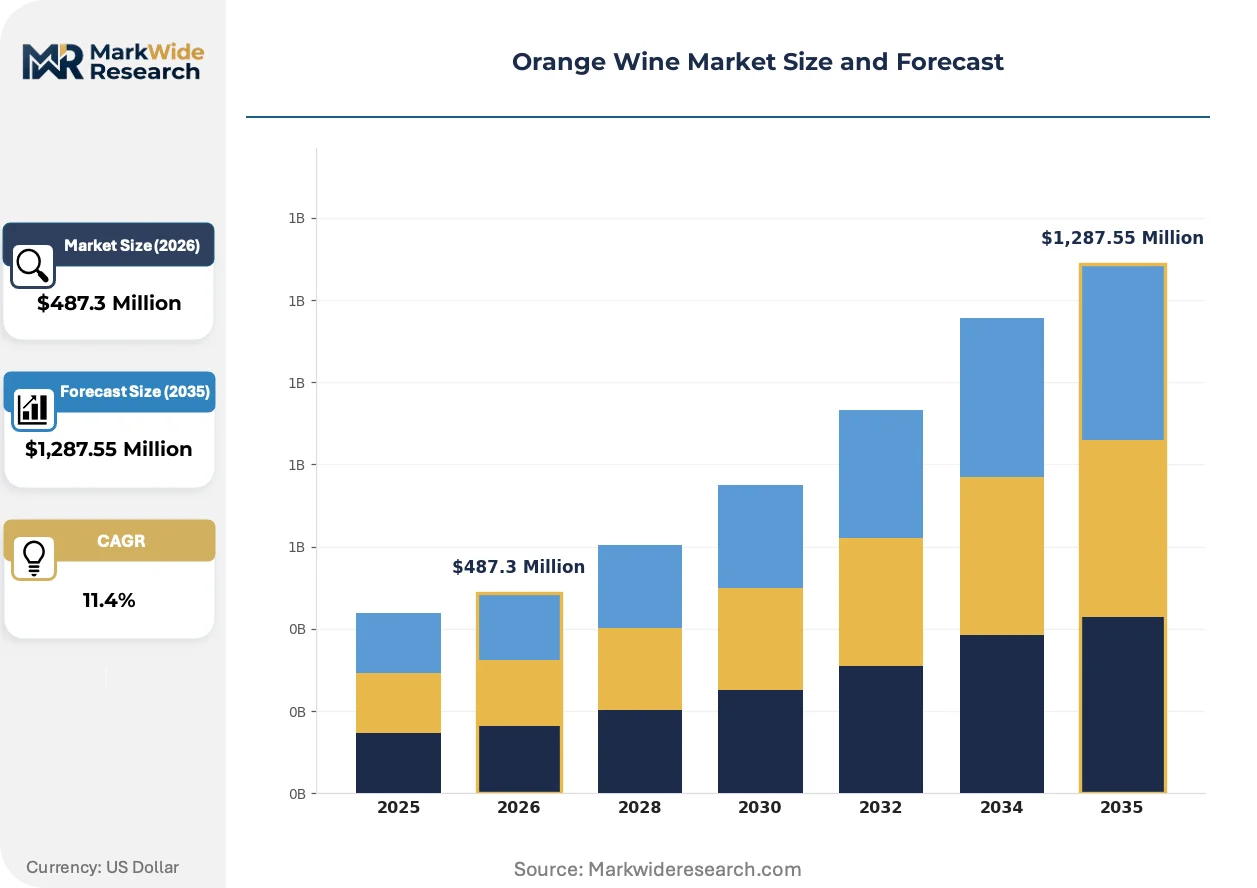
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,287.55 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Orange Wine, Organic Orange Wine, Traditional Orange Wine, Commercial Orange Wine Grape Variety: Pinot Grigio, Sauvignon Blanc, Chardonnay, Ribolla Gialla Production Method: Skin Contact, Amphora Fermentation, Barrel Aging, Carbonic Maceration Distribution Channel: Online Retail, Specialty Wine Shops, Restaurants, Supermarkets |
| Companies Covered | Frank Cornelissen, Primosic, Gérard Bertrand Group, Rallo, Sandi Skerk, La Stoppa, Tinto Amorio, Vigne di San Lorenzo, Gut Oggau, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orange Wine Market Strategic Shifts
Amphora fermentation is displacing stainless steel dominance as winemakers pursue oxidative complexity and native yeast expression. Three interconnected developments are compressing traditional production timelines and reshaping competitive positioning.
Clay vessel technology is decomposing the barrier between white and red wine production methodologies. Extended skin contact in buried qvevri or above-ground tinaja vessels enables phenolic extraction previously exclusive to red grape processing. Premium restaurant buyers in Copenhagen and Tokyo are accelerating adoption of these expressions, compressing the timeline for conventional white wine category erosion.
REACH chemical compliance and EU Green Deal sustainability reporting obligations are tightening cellar equipment procurement standards. ECHA-registered materials now govern amphora sealing compounds and fermentation vessel coatings, raising capital requirements for facility upgrades. Small producers in Kakheti and Goriška Brda face disproportionate compliance burdens relative to scaled Languedoc-Roussillon operations.
Collector purchasing patterns are rotating toward vintage-dated, single-vineyard expressions with documented skin-contact duration. Specialty wine shops in Berlin and Brooklyn are displacing restaurant allocation as the primary channel for limited-production releases. This behavioral shift concentrates value realization in retail environments with educated staff capable of communicating oxidative stability and terroir specificity.
Orange Wine Market Segmentation
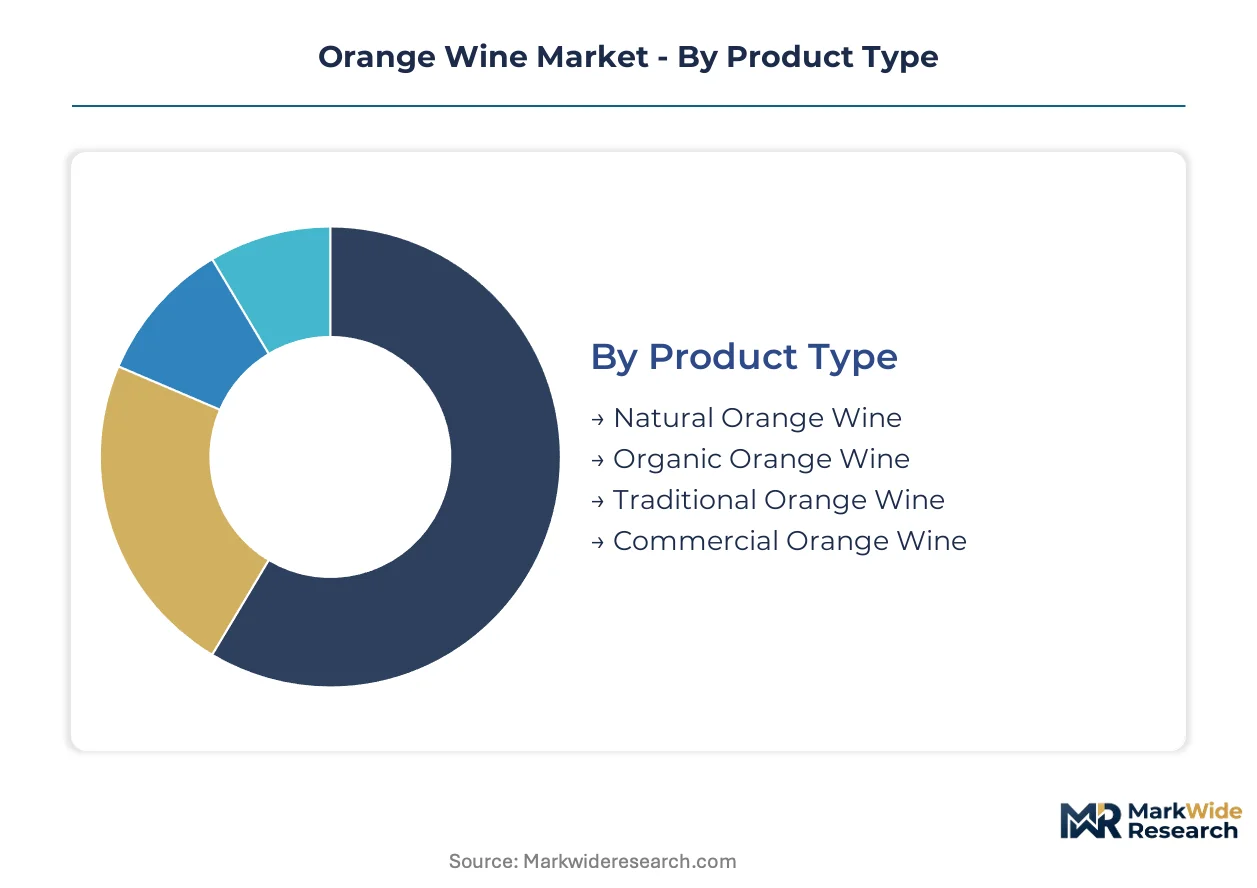
Orange wine segmentation tracks how production philosophy, grape provenance, and channel access stratify pricing power across distinct consumer cohorts. Category boundaries blur as skin-contact methods migrate from natural wine subculture toward mainstream restaurant placement.
Product Type:
Domestic consumption concentrates in traditional and commercial tiers, while export demand flows disproportionately toward natural and organic certifications that command shelf space in Copenhagen, Berlin, and Tokyo specialty channels.
- Natural Orange Wine:Fermented with native yeasts, zero sulfur additions, and unfiltered bottling preserves oxidative complexity and phenolic texture. Collector demand in Brooklyn and Melbourne natural wine bars absorbs limited-production releases before restaurant allocation, with EFSA organic certification amplifying price anchoring in EU markets.
- Organic Orange Wine:Certified vineyard fruit processed under EU Green Deal-aligned protocols with documented skin-contact duration. German and Austrian import channels prioritize these bottlings for Bioland and Demeter retail placement, though conversion costs burden small Kakheti producers seeking EU market access.
- Traditional Orange Wine:Ancestral methods from Georgia, Slovenia, and Friuli-Venezia Giulia using qvevri or extended maceration in neutral vessels.
- Commercial Orange Wine:Scaled production with temperature-controlled fermentation, filtration, and supermarket distribution targeting price-sensitive casual dining segments.
Traditional orange wine holds the largest share; momentum sits with natural orange wine.
Grape Variety:
Cost tier stratification separates heritage varieties commanding premium allocation from internationally recognized grapes enabling volume expansion.
- Pinot Grigio:Northeastern Italian macerated expressions from Alto Adige and Friuli leverage pink-skinned phenolic potential for amber color extraction. Sommelier programs in Milan and Rome prioritize these bottlings for by-the-glass programs, though Friuli acreage constraints limit scalable supply.
- Ribolla Gialla:The benchmark variety for Collio and Brda orange wine production, with thick skins enabling extended maceration without excessive tannin extraction. Primosic and Radikon allocations concentrate in Tokyo and New York collector markets, with single-vineyard expressions achieving highest per-bottle realization.
- Sauvignon Blanc:Loire Valley skin-contact experiments and New World adaptations expanding production volume.
- Chardonnay:Burgundian-inspired maceration gaining traction in Jura and Australia.
Pinot Grigio dominates volume throughput; Ribolla Gialla captures steepest price appreciation.
Production Method:
Application context determines method selection: restaurants prioritize oxidative complexity, while export-oriented producers seek batch consistency.
- Skin Contact:White grapes fermented with extended pomace immersion ranging from days to months, extracting color, tannin, and phenolic compounds absent in conventional white winemaking. Duration transparency—72 hours versus six months—drives sommelier purchasing decisions in Copenhagen and Ljubljana natural wine bars.
- Amphora Fermentation:Buried qvevri or above-ground tinaja vessels enable oxidative aging with native yeast populations, producing stability without sulfur. Georgian Kakheti and Sicilian Caltagirone supply chains face REACH compliance costs for EU export, compressing margins for small producers.
- Barrel Aging:Neutral oak or acacia wood maturation following skin contact, concentrating value in aged inventory positions.
- Carbonic Maceration:Whole-grape fermentation under carbon dioxide pressure, yielding lighter phenolic extraction for entry-tier positioning.
Skin contact commands broadest adoption; amphora fermentation shows sharpest share gain.
Distribution Channel:
Customer type fragmentation splits between education-dependent specialty channels and convenience-oriented mass retail.
- Specialty Wine Shops:Staff-trained environments in Berlin, Brooklyn, and Melbourne communicate skin-contact duration, vineyard provenance, and oxidative stability to collector segments. These channels capture highest per-bottle margins and receive allocation priority for limited-production releases from Frank Cornelissen and Gérard Bertrand portfolios.
- Restaurants:Sommelier-led placement in premium on-premise channels across Italy, Slovenia, and Georgia drives category legitimacy and by-the-glass trial. Natural wine bar proliferation in Tbilisi and Ljubljana creates dedicated shelf space bypassing supermarket distribution entirely.
- Online Retail:Direct-to-consumer subscription models and natural wine clubs capturing full margin from repeat purchasers.
- Supermarkets:Commercial-tier orange wine with standardized labeling and price positioning for casual consumers.
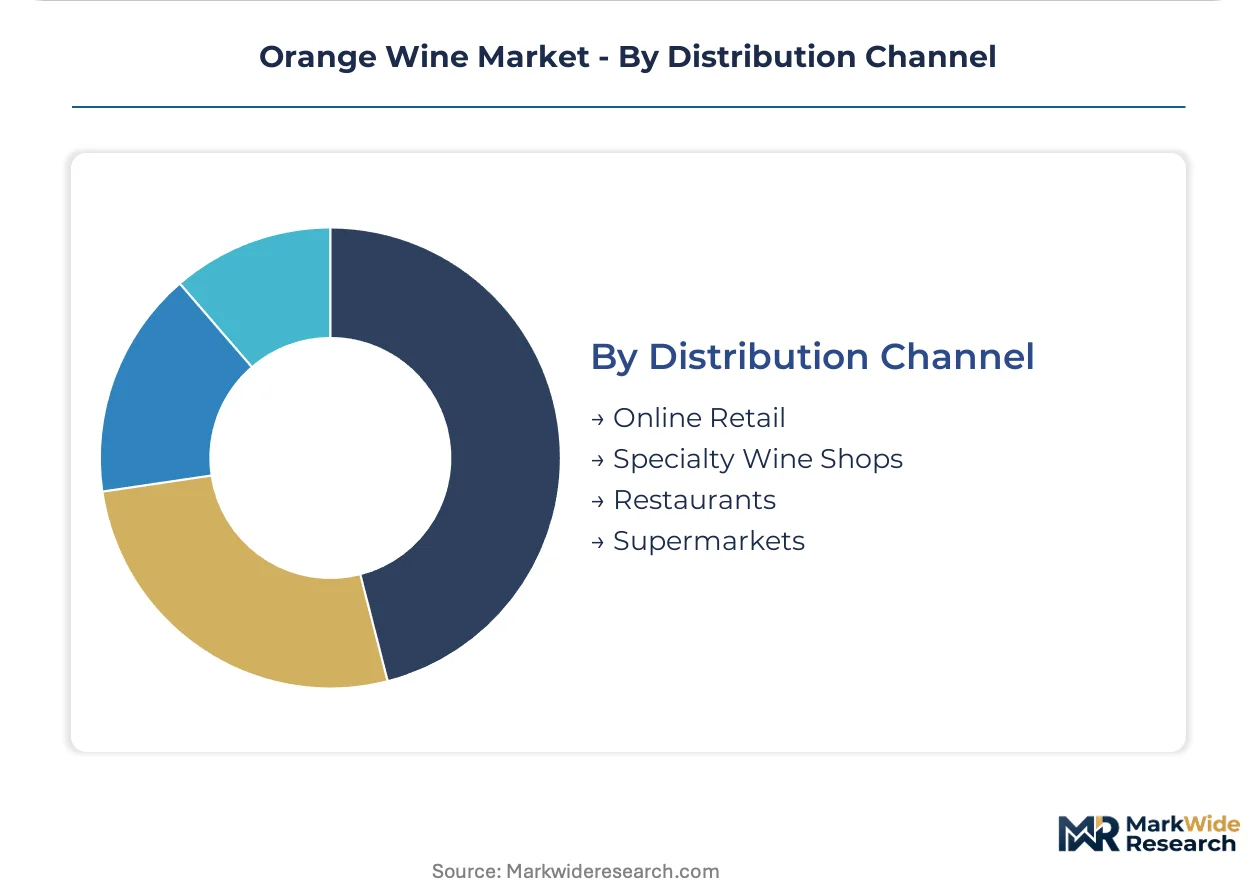
Restaurants anchor volume throughput; specialty wine shops deliver strongest margin realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from traditional production zones in Italy, Slovenia, and Georgia now exceed import absorption in emerging consumption markets across Northern Europe and East Asia. Trade imbalances favor origin countries with UNESCO-recognized heritage methods and established sommelier networks. Freight logistics and REACH compliance costs increasingly determine which producers capture shelf space in Copenhagen, Berlin, and Tokyo specialty channels.
Italy
Friuli-Venezia Giulia and Sicily anchor domestic production volume, with Collio and Etna sub-regions supplying benchmark skin-contact expressions to Milan and Rome restaurant channels. EFSA organic certification requirements under EU Green Deal protocols tighten labeling standards for export-bound bottlings. Alto Adige cooperatives convert conventional Pinot Grigio acreage to extended maceration protocols, capturing premium placement in German and Austrian import markets.
Slovenia
Goriška Brda producers leverage cross-border terroir continuity with Friuli to access Italian distribution infrastructure while maintaining distinct national branding. REACH compliance costs for amphora sealing compounds burden small cellar operations seeking EU market expansion. Ljubljana natural wine bars create dedicated consumption nodes that bypass three-tier supermarket distribution entirely, concentrating value in on-premise channels.
Georgia
Kakheti qvevri craftsmen face capacity constraints as global demand for ancestral fermentation methods outpaces traditional vessel production timelines. UNESCO heritage registration attracts enotourism investment to Tbilisi and Telavi, establishing technical credibility for export markets. Georgian producers navigate extended EU customs clearance timelines for clay vessel imports, compressing margins relative to European competitors with domestic amphora supply chains.
Germany
Styrian producers in Südsteiermark and Vulkanland experiment with Blaufränkisch and Zweigelt white variants, creating Central European supply alternatives to Italian dominance. Bioland and Demeter retail channels prioritize EFSA-aligned organic certifications for shelf placement in Berlin and Hamburg specialty shops. Natural wine subscription services based in Copenhagen and Berlin capture full margin from German collector segments, bypassing traditional import distribution.
Japan
Tokyo and Osaka sommelier programs drive category legitimacy through by-the-glass placement of benchmark Italian and Slovenian expressions. Import regulations through the country's national food safety regulator require documented skin-contact duration and sulfur levels for customs clearance. Specialty wine shops in Shibuya and Ginza displace restaurant allocation as primary channels for limited-production releases, concentrating value realization in retail environments with educated staff.
Orange Wine Market Competitive Environment
Listed leaders compete with private specialists across production scale and channel access dimensions, creating tiered competitive pressure. Family-owned estates in Friuli and Kakheti maintain limited-production credibility through controlled allocation, while diversified beverage groups leverage existing distribution infrastructure for commercial-tier placement. Three archetypes dominate: heritage qvevri specialists, volcanic terroir minimalists, and organic-certified scale operators. Competitive moves concentrate on direct-to-consumer subscription expansion and strategic on-premise placement in Copenhagen, Berlin, and Tokyo.
Within the heritage-method tier, Frank Cornelissen anchors volcanic Sicilian positioning through Etna-based production, while Primosic exemplifies Collio specialization in Ribolla Gialla skin-contact protocols. Gérard Bertrand Group occupies the diversified operator position with Languedoc-Roussillon distribution reach. These three represent distinct competitive vectors—terroir-specific minimalism, single-varietal mastery, and regional portfolio scale—each capturing different margin structures across restaurant, retail, and direct channels.
| Leading Market Players |
|---|
| Frank Cornelissen |
| Primosic |
| Gérard Bertrand Group |
| Rallo |
| Sandi Skerk |
| La Stoppa |
| Tinto Amorio |
| Vigne di San Lorenzo |
| Gut Oggau |
| Others |
Value Chain & Pricing Dynamics
Amphora vessel substitution for stainless steel tanks simultaneously shifts procurement geography toward Kakheti and Caltagirone clay craftsmen while compressing per-unit economics through REACH compliance costs and extended EU customs timelines for Georgian qvevri imports.
Pricing Analysis
Sommelier-led restaurant buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on EFSA organic certification tier and documented skin-contact duration, with certified natural bottlings commanding shelf-space premiums in Berlin and Tokyo specialty channels. Cost compression in commercial-tier supermarket positioning intensifies as unoaked Chardonnay substitutes retain casual-dining price advantages. Collector segments demonstrate lowest price sensitivity, absorbing allocation premiums for single-vintage Ribolla Gialla expressions before restaurant release.
Supply Chain Analysis
Port congestion on Black Sea-to-Mediterranean trade lanes extends lead times for Georgian qvevri vessel deliveries into EU cellar operations. Geographic supply concentrates in Italy, Slovenia, and Georgia, with raw material dependencies spanning Kakheti clay deposits, Friuli-Venezia Giulia Ribolla Gialla acreage, and Sicilian volcanic terroir. Single-source vulnerability from master qvevri craftsman scarcity in Kakheti and Caltagirone threatens capacity expansion timelines. Distribution runs through specialty wine shops and sommelier-led restaurants, bypassing supermarket channels for premium-tier realization.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal subsidy acceleration and tightening EFSA organic certification standards create a regulatory inflection that rewards early compliance investment while penalizing conventional conversion laggards.
For Market Incumbents: Secure qvevri craftsman apprenticeship programs in Kakheti and Caltagirone to defend vessel supply access against new entrant demand surges. Anchor controlled allocation protocols for limited-production releases through direct-to-consumer subscription channels, capturing full margin from Copenhagen and Berlin collector segments rather than ceding value to three-tier distributors.
For New Entrants and Emerging Players: EFSA organic certification fast-tracks through Bioland and Demeter equivalency pathways unlock premium shelf placement in German and Austrian retail channels. Target Austrian Styrian skin-contact experimentation with Blaufränkisch white variants as the most penetrable geography beyond Italian supply dominance. Launch natural wine club subscription models to bypass established distributor relationships entirely.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Languedoc-Roussillon diversified beverage groups seeking portfolio rationalization. Five-to-ten year viability favors acquisition targets with UNESCO-recognized heritage methods and established sommelier network relationships in Tokyo and Copenhagen. Monitor EFSA organic certification conversion rates across Friuli cooperatives as inflection indicator for pricing power migration.
| Strategic Initiative | Industry Significance |
|---|---|
| Qvevri Craftsman Apprenticeship Program | Addresses amphora fabrication skill scarcity threatening Kakheti producer capacity expansion timelines. |
| EFSA Organic Certification Fast-Track | Enables premium price anchoring against uncertified competitors in German Bioland retail channels. |
| Direct-to-Consumer Subscription Launch | Captures full margin from Brooklyn and Melbourne collector segments bypassing three-tier constraints. |
| Styrian Skin-Contact Expansion | Creates Central European supply alternatives to Italian Ribolla Gialla acreage limitations. |
| Sommelier Education Partnership | Closes technical vocabulary gaps impeding skin-contact duration communication in secondary markets. |
Study Parameters
A standing panel of winemakers, sommelier program directors, natural wine bar operators, and EFSA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from EU Green Deal implementation documents, ECHA REACH registration databases, UNESCO heritage method filings, and customs trade records for Georgian qvevri vessel imports. Bottom-up production volume estimates from Friuli, Goriška Brda, and Kakheti cellars triangulated against top-down consumption absorption data from Copenhagen, Berlin, and Tokyo specialty channels.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning production philosophy tiers, grape variety provenance, skin-contact duration categories, and distribution channel access patterns. CAGRs were derived from vintage-to-vintage allocation velocity and collector purchasing pattern shifts toward single-vineyard expressions with documented oxidative stability parameters.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal subsidy continuity and stable REACH compliance cost structures; material deviation would warrant model refresh. Specific risk factors include abrupt EFSA organic certification requirement changes, qvevri craftsman mortality without apprentice pipeline maturation, and substitution acceleration toward conventional white wine in price-sensitive casual dining segments. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Alcohol Enzymes Market
Alcoholic Beverages
Alcoholic Drinks Market
Alcoholic Beverages
South America Craft Beer Market
Alcoholic Beverages
Spirit-Based RTD Mixes Market
Alcoholic Beverages
Global Soju Market
Alcoholic Beverages
Cocktail Mixers Market
Alcoholic Beverages
Australia and New Zealand Tequila Market
Alcoholic Beverages
Wine Bottle Sterilizer Market
Alcoholic Beverages
Moonshine Market
Alcoholic Beverages
Sake Market
Alcoholic Beverages
Gluten Free Alcoholic Drinks Market
Alcoholic Beverages
Global Premium Gin Market
Alcoholic Beverages
Mead Beverage Market
Alcoholic Beverages
Alcohol Market
Alcoholic Beverages
United States Tequila Market
Alcoholic Beverages
Uganda Spirits Market