
 United States Tequila Market | 2026-2036
United States Tequila Market Size, Share, and Industry Trends Forecast 2026-2036
United States Tequila Market Intelligence
Subscription-based cocktail ingredient kits and membership-driven tasting experiences is pivoting how tequila reaches consumers beyond traditional retail. Diageo PLC leverages its vast distribution infrastructure to sustain shelf dominance in off-premise channels. Constellation Brands anchors its portfolio through vertical control over agave supply and production facilities in Jalisco. Proximo Spirits differentiates via targeted positioning of craft and celebrity-affiliated labels in urban nightlife corridors.
Tequila denotes a distilled spirit produced from Weber blue agave, with regulations mandating minimum agave content and specific geographic origin in Mexican states; the liquid undergoes cooking, crushing, fermentation, and distillation before aging in oak or resting in stainless steel. Blanco expressions occupy the highest volume tier due to mixology versatility and lower price entry points, while Extra Añejo commands concentrated margin pools among collectors and luxury hospitality accounts. Super Premium price tier segments expand fastest as affluent consumers trade upward from mid-range Reposado offerings.
The Alcohol and Tobacco Tax and Trade Bureau enforces labeling standards and import documentation that determine market access for Mexican producers, while FDA oversight applies to additive disclosures and allergen protocols. State-level ABC boards in California, Texas, and New York impose additional distribution tier requirements that shape wholesale route-to-market economics. Stakeholders must monitor evolving tariff structures on distilled spirits imports and state legislative movements toward direct-to-consumer shipping permissions.
Market Dynamics
Agave supply concentration in Jalisco's highlands is compressing raw material availability for US-bound production, forcing distillers to secure long-term estate contracts or face margin erosion from spot-market volatility.
Growth Catalysts
- TTB Labeling Modernization:Revised standards for additive disclosure and geographic certification are elevating consumer trust in authentic 100% agave expressions, accelerating trade-up from mixto alternatives.
- Texas and California Hispanic Demographics:Population density in Houston, Dallas, Los Angeles, and Miami creates concentrated demand corridors where cultural consumption patterns drive premiumization faster than national averages.
- On-Premise Mixology Renaissance:Craft cocktail programs in metropolitan bars are elevating aged tequila into sipping categories previously dominated by brown spirits, expanding occasion-based consumption.
Market Restraints
- Agave Price Volatility:Seven-year maturation cycles for Weber blue agave create supply inelasticity that amplifies cost spikes when harvest shortages coincide with demand surges.
- Jalisco Production Concentration:Over 90% of certified tequila originates in a single Mexican state, exposing the entire value chain to regional climate events and water access disputes.
- State ABC Distribution Tiers:Three-tier systems in Texas, California, and New York impose margin-stacking requirements that limit direct producer-to-retailer economics and inflate shelf prices.
Strategic Opportunities
- Direct-to-Consumer Shipping Liberalization:Legislative movements in Florida and New York toward producer-direct sales could bypass wholesale markups and capture full retail margin on allocated expressions.
- Subscription Cocktail Kits:Membership-driven tasting experiences and curated ingredient deliveries are opening channel access beyond controlled-state retail monopolies.
- Extra Añejo Collector Segment:Ultra-aged expressions with extended oak residency are penetrating luxury hospitality accounts and private collections at price points unreachable by standard bottlings.
Industry Challenges
- Master Distiller Talent Scarcity:Deep expertise in tahona milling, wild yeast fermentation, and barrel blending remains concentrated among aging specialists in Jalisco, constraining quality-scaled expansion.
- Certification Timeline Compression:CRT (Consejo Regulador del Tequila) approval processes for new production facilities and label registrations create 18-to-24-month delays for market entry.
- Additive Transparency Compliance:FDA disclosure requirements for glycerin, caramel coloring, and oak extract demand reformulated testing protocols that smaller craft importers struggle to resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Tequila Market |
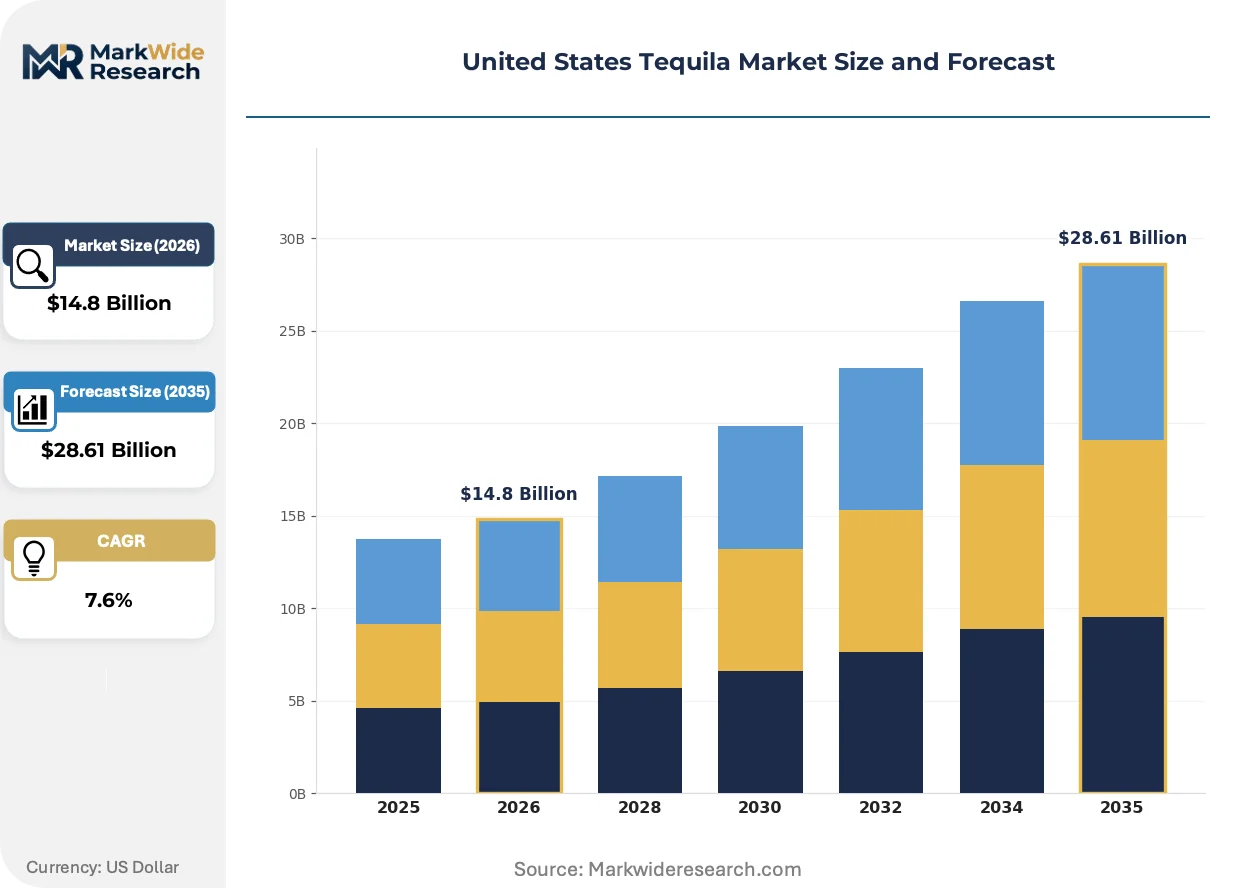
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $28.61 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blanco, Reposado, Añejo, Extra Añejo Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Liquor Stores Consumer Demographics: Millennials, Gen Z, Baby Boomers, Affluent Consumers Price Range: Premium, Mid-range, Super Premium, Economical |
| Companies Covered | Diageo PLC, Constellation Brands, Inc., Pernod Ricard, Bacardi and Company Ltd., Suntory Holdings Limited, Campari Group, Proximo Spirits, Brown-Forman Corporation, Heaven Hill Distilleries, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Tequila Market Strategic Shifts & Innovations
Automation and precision agriculture are penetrating agave cultivation and distillation workflows, while regulatory disclosure mandates and experiential consumption models are redefining how value accrues across the supply chain.
Sensor-guided ripeness detection and mechanical jimador assistance are automating harvest timing decisions that previously relied on generational field knowledge. Large estate producers in the Jalisco highlands are deploying these systems to reduce labor dependency and standardize sugar content consistency. The technology is automating quality gatekeeping that once required human judgment, compressing the variance between premium and super-premium batches.
The FDA's updated guidance on distilled spirits allergen labeling and additive disclosure is forcing reformulation of traditionally opaque mixto products. Importers must now substantiate claims of "100% agave" with chain-of-custody documentation or face detention at port. Super-premium and craft segments are responding fastest, leveraging transparency as a competitive wedge against established value-tier brands.
Experiential retail and membership-driven access models are displacing traditional off-premise discovery for affluent consumers. Tasting room subscriptions, allocated bottle lotteries, and producer-hosted estate visits are capturing loyalty before retail shelf interaction occurs. This behavioral pivot is most visible in California and Texas, where direct engagement programs now drive allocation decisions for limited Extra Añejo releases.
United States Tequila Market Segmentation
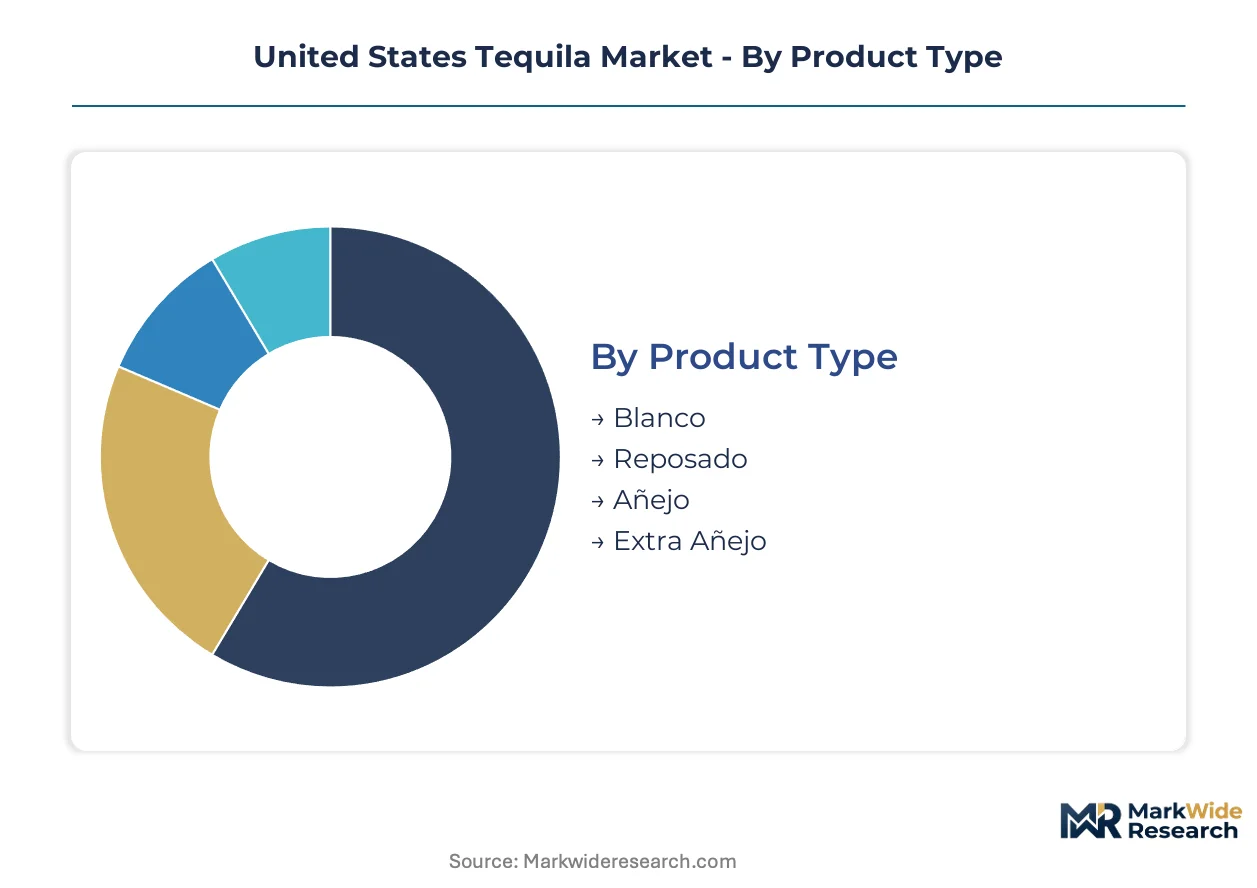
Tequila's diverse consumption occasions—from high-volume mixology to luxury sipping—demand precise segmentation strategies. Producers align production methods, aging protocols, and channel investments to capture distinct margin pools across these divides.
Product Type:
Supply concentration in Jalisco's highlands shapes how each expression reaches American consumers, with estate-controlled agave allocation determining which tiers expand.
- Blanco:Unaged spirit rested in stainless steel or bottled immediately after distillation, preserving raw agave character and peppery brightness. Bartenders in Houston, Los Angeles, and Miami drive volume through margarita programs and paloma builds, though spot-market agave volatility compresses margins for non-estate producers.
- Reposado:Two-to-twelve months of oak contact introduces vanilla and caramel notes without sacrificing mixology versatility. Texas and California account for disproportionate share as Hispanic consumption patterns and craft cocktail adoption intersect in Dallas-Fort Worth and Orange County.
- Añejo:One-to-three years of barrel aging develops sipping complexity comparable to premium whiskey. Demand concentrates in metropolitan on-premise accounts where brown-spirit converts seek agave alternatives.
- Extra Añejo:Ultra-aged expressions exceeding three years in oak command collector premiums and luxury hospitality placement. Limited releases from estate producers bypass traditional wholesale through direct allocation lists in California and Florida.
Today's leader: Blanco. Tomorrow's challenger: Extra Añejo.
Distribution Channel:
Route-to-market economics vary sharply across controlled-state hierarchies and emerging direct-access models, with margin capture driving channel prioritization.
- Supermarkets:High-velocity off-premise placement for Blanco and value-tier Reposado in suburban Texas and California markets. TTB labeling compliance and state ABC tier requirements inflate shelf prices versus direct alternatives.
- Convenience Stores:Impulse-oriented volume for standard Blanco in Hispanic-density corridors. Limited aged-expression presence reflects inventory turn requirements and space constraints.
- Online Retail:Subscription cocktail kits and allocated bottle lotteries are gaining share fastest among affluent Millennials and Gen Z in New York and Florida. Legislative movements toward producer-direct shipping threaten traditional three-tier economics.
- Liquor Stores:Specialty retailers anchor Super Premium discovery through staff education and tasting events. Independent operators in California and Texas control access to limited Extra Añejo releases.
Online Retail climbs the fastest, though Liquor Stores retain allocation control for luxury tiers.
Consumer Demographics:
Generational and income divides determine occasion-based consumption patterns, from high-frequency mixology to low-volume collector acquisition.
- Millennials:Core volume driver for craft cocktail culture and premium-at-home consumption. Urban coastal markets show highest per-capita spend on Super Premium expressions.
- Gen Z:Emerging trial segment gravitating toward additive-transparent, celebrity-affiliated brands and experiential retail discovery. Price entry points favor Blanco and mid-range Reposado.
- Baby Boomers:Established sipping segment with loyalty to traditional Añejo and Extra Añejo producers. Estate visit participation and direct-to-consumer engagement rates exceed younger cohorts.
- Affluent Consumers:Discretionary spend concentrates on allocated Extra Añejo and limited single-estate releases. Membership-driven tasting programs in California and Texas capture loyalty before retail interaction.
Millennials anchor current volume. Affluent Consumers shape tomorrow's margin expansion.
Price Range:
Raw material sourcing and aging duration stratify pricing architecture, with estate agave contracts and extended oak residency creating defendable premium tiers.
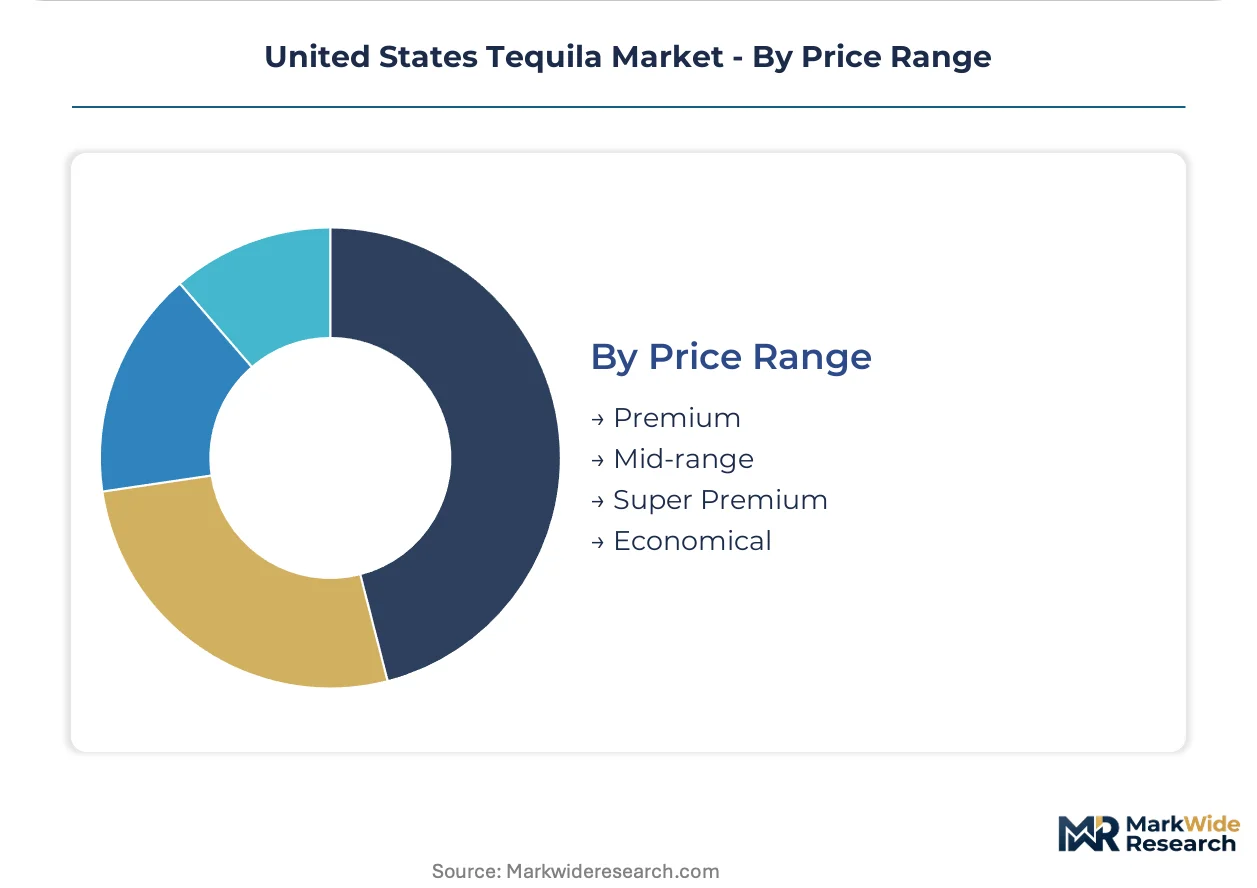
- Premium:100% agave expressions with moderate aging, positioned between value-tier mixto and Super Premium estate offerings. Volume concentrates in Texas and California off-premise.
- Mid-range:Entry-level 100% agave Blanco and young Reposado serving high-frequency mixology occasions. Price sensitivity is acute among Gen Z and suburban convenience-store purchasers.
- Super Premium:Estate-sourced agave with extended barrel programs and additive-free certification. Fastest-expanding tier as affluent consumers trade upward from Premium Reposado.
- Economical:Mixto products with minimum agave content facing TTB disclosure pressure and consumer trade-down risk. Share erosion accelerates as additive transparency mandates elevate 100% agave preference.
Super Premium commands steepest expansion trajectory, while Economical faces structural decline from regulatory and preference shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States absorbs tequila volumes at rates exceeding Canada and Mexico combined, though Mexican production regulations shape what crosses the border. State-level distribution frameworks and demographic clustering determine where premiumization accelerates fastest.
California
Hispanic population concentration in Los Angeles and Orange County sustains baseline consumption, while affluent coastal enclaves drive Super Premium trial. The California Department of Alcoholic Beverage Control enforces strict three-tier distribution requirements that inflate wholesale markups. San Diego's proximity to Tijuana creates cross-border tasting tourism that converts visitors into direct-to-consumer subscribers.
Texas
Houston and Dallas-Fort Worth metropolitan areas generate the highest per-capita tequila consumption outside Mexico, with mixology programs in Austin elevating aged expressions. The Texas Alcoholic Beverage Commission maintains controlled-state provisions that limit direct producer shipments. Border cities from El Paso to McAllen channel cultural consumption patterns into sustained volume demand for Blanco and Reposado tiers.
Florida
Miami's nightlife economy and Cuban-American cocktail culture concentrate on-premise demand for premium pours in South Beach and Brickell districts. The Florida Division of Alcoholic Beverages and Tobacco is reviewing legislative proposals for direct-to-consumer shipping liberalization that would bypass traditional wholesale tiers. Orlando's tourism corridor moves significant volume through hotel and resort accounts seeking additive-certified expressions.
New York
Manhattan and Brooklyn craft cocktail dens drive discovery of Extra Añejo and limited estate releases among finance and media professionals. The New York State Liquor Authority enforces stringent label registration requirements that delay new product launches by six to nine months. Hudson Valley tasting rooms and subscription services are capturing affluent suburban consumers before retail shelf interaction occurs.
Illinois
Chicago's restaurant and bar density supports diverse tequila programming across West Loop and River North entertainment districts. The Illinois Liquor Control Commission maintains franchise protections that limit supplier flexibility in distributor relationships. Emerging demand in secondary markets like Naperville and Evanston reflects suburban premiumization trends trailing coastal adoption curves.
United States Tequila Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with estate producers commanding allocation premiums while volume players rely on third-party distillation arrangements. Market structure tilts toward consolidation at the premium tier and fragmentation among craft entrants seeking celebrity affiliation differentiation. Two strategic archetypes dominate: vertically integrated agave estate holders and brand-marketing specialists outsourcing production. Competitive moves center on long-term raw material contracting and direct-to-consumer channel development.
Among multinational spirits conglomerates, Diageo PLC and Constellation Brands, Inc. exemplify contrasting approaches to tequila portfolio construction. Diageo leverages its North American distribution infrastructure to sustain off-premise shelf dominance across multiple price tiers. Constellation Brands anchors market position through captive agave supply and production facility ownership in Jalisco. Proximo Spirits occupies a distinct tier as a specialist operator targeting urban nightlife corridors with craft-positioned and celebrity-affiliated label strategies.
| Leading Market Players |
|---|
| Diageo PLC |
| Constellation Brands, Inc. |
| Pernod Ricard |
| Bacardi and Company Ltd. |
| Suntory Holdings Limited |
| Campari Group |
| Proximo Spirits |
| Brown-Forman Corporation |
| Heaven Hill Distilleries, Inc. |
| Others |
Cost & Logistics Intelligence
Agave spot-market indices in Jalisco's highlands transmit volatility directly into US-bound pricing tiers, with seven-year maturation cycles amplifying cost spikes that cascade from raw material procurement through estate-controlled production into shelf-price stratification across American distribution channels.
Pricing Analysis
Capacity additions in Jalisco's Los Altos region are reshaping price floors for Super Premium expressions as estate producers secure long-term agave contracts. Three-tier pricing structure across premium, standard, and economy levels separates additive-certified 100% agave from mixto alternatives, with certification grade and barrel residency duration driving differentiation. Cost compression in mid-range Reposado is intensifying because spot-market agave purchases expose non-integrated distillers to margin erosion. Gen Z purchasers in suburban Texas and California convenience channels exhibit acute price sensitivity, while affluent collectors in Miami and Los Angeles direct-to-consumer programs show minimal elasticity for allocated Extra Añejo releases.
Supply Chain Analysis
CRT certification requirements for production facilities and label registrations create 18-to-24-month gating delays that constrain new entrant capacity and reinforce incumbent allocation control. Geographic supply concentrates in Mexico's Jalisco state, with secondary sourcing from limited highland estates in Nayarit and Michoacán. Raw material dependencies center on Weber blue agave cultivation, American white oak barrel procurement, and specialized tahona milling equipment. Single-source vulnerability from Jalisco's 90%-plus production concentration exposes the value chain to regional drought and water access disputes. Distribution runs through state ABC-controlled three-tier systems in Texas, California, and New York, with emerging direct-to-consumer channels threatening traditional wholesale economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Tequila Market functions as a stable compounder, with generational trade-up from mid-range to Super Premium expressions generating sustained margin expansion across the analysis window.
For Market Incumbents: To counter agave price volatility and spot-market dependency, Diageo PLC and Constellation Brands should deepen backward integration into highland estate ownership and secure 10-year agave supply contracts. Channel control through direct-to-consumer shipping infrastructure in Florida and New York represents the priority defensive investment, insulating allocation economics from state ABC tier markups. For New Entrants and Emerging Players: The gap between Super Premium and Economical pricing tiers opens white-space opportunity for craft-positioned, additive-transparent Reposado expressions targeting Hispanic-density corridors in Houston and Dallas-Fort Worth. Celebrity-affiliated label strategies penetrate fastest among Gen Z trial segments in urban nightlife accounts, with subscription cocktail kit partnerships offering channel access beyond controlled-state retail monopolies. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated estate producers holding captive agave supply and CRT-certified production facilities in Jalisco's highlands. Long-term viability across a 5-to-10-year window favors acquisition targets with established direct-to-consumer subscriber bases and allocated Extra Añejo release programs. The signal to watch is legislative movement toward producer-direct shipping permissions in Florida and New York state assemblies.| Strategic Initiative | Industry Significance |
|---|---|
| Estate Agave Supply Contracting | Long-term contracts with Jalisco highland growers lock in raw material cost predictability against spot-market swings. |
| Direct-to-Consumer Shipping Infrastructure | Bypassing Texas and California ABC tiers captures full retail margin on allocated Super Premium releases. |
| Additive-Free Certification Investment | TTB-compliant transparency protocols differentiate craft entrants from opaque mixto competitors in affluent coastal markets. |
| Extra Añejo Barrel Program Expansion | Extended oak residency commands collector premiums and luxury hospitality placement unreachable by standard bottlings. |
| Subscription Cocktail Kit Partnerships | Membership-driven access models capture Millennial and Gen Z loyalty before traditional retail shelf interaction occurs. |
Research Approach
Coverage spans California, Texas, Florida, New York, and Illinois, with primary inputs from each state's alcoholic beverage control authorities and metropolitan market clusters. The research combines structured interviews with master distillers, brand portfolio managers, ABC licensing officers, and on-premise beverage directors with secondary validation from CRT production databases, TTB label approval records, and state-level import documentation. Nielsen retail audit data, customs import manifests, and SEC 10-K filings from publicly traded spirits conglomerates anchor quantitative triangulation. Bottom-up volume modeling across product tiers and top-down value reconciliation from producer-reported shipments ensure cross-verified outputs.
Granularity extends to individual state regulatory frameworks, with price-tier dynamics, distribution channel economics, and demographic consumption patterns modeled at metropolitan statistical area resolution. Segmentation dimensions include product type expression, aging duration, price tier positioning, and channel route-to-market structure. CAGRs derive from trend extrapolation of historical volume trajectories adjusted for identified catalysts and restraints. Agave supply cycle modeling and TTB regulatory timeline assumptions inform projection boundaries.
The model assumes a particular technology adoption path; alternative pathways for mechanical jimador assistance and sensor-guided ripeness detection would alter the outlook for labor cost structures and batch consistency variance. Forecasts reflect documented assumptions regarding CRT certification timeline compression, state ABC tier persistence, and Hispanic demographic growth trajectories. Deviation in agave harvest yields, tariff structures on distilled spirits imports, or direct-to-consumer shipping legislative outcomes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
GCC Beer Market
Alcoholic Beverages
Arak Market
Alcoholic Beverages
Moscato Wine Market
Alcoholic Beverages
Wine Bags Market
Alcoholic Beverages
Built-In Wine Coolers Market
Alcoholic Beverages
South America Fermented Drinks Market
Alcoholic Beverages
Chardonnay Market
Alcoholic Beverages
Chocolate Liqueur Market
Alcoholic Beverages
North America Spirits Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
Asia-Pacific Wine Market
Alcoholic Beverages
RTD Bottled Cocktails Market
Alcoholic Beverages
US Wine Cooler Market
Alcoholic Beverages
Malt Whiskey Market
Alcoholic Beverages
Hip Flask Market
Alcoholic Beverages
India Tequila Market