
 Alcohol Market | 2026-2036
Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
Alcohol Market Analysis
On-premise hospitality consumption is expanding as post-pandemic social dining patterns normalize across developed and emerging economies. Anheuser-Busch InBev leverages its brewing infrastructure to dominate mass-market beer volumes across multiple continents. Diageo sustains premiumization momentum through its Scotch and tequila portfolios. Kweichow Moutai anchors ultra-premium baijiu demand within China's ceremonial gifting culture.
Alcohol denotes ethyl alcohol (ethanol, C₂H₅OH) produced through fermentation of sugars by yeast or via distillation, typically at concentrations ranging from 4% ABV in standard beers to 40% or higher in distilled spirits, serving social, recreational, and ceremonial consumption purposes across consumer and commercial settings. The spirits category captures the highest margin pools due to aging requirements and brand equity premiums. Beer remains volume-dominant but faces margin compression from input cost volatility. Cider occupies a niche growth trajectory in North American and European markets as gluten-free alternatives expand.
The US TTB and FDA jointly govern labeling, taxation, and interstate commerce standards, while the EU's CSRD and F-Gas Regulation shape packaging sustainability mandates and carbon disclosure requirements for producers operating across member states. India's FSSAI enforces strict manufacturing licensing and quality standards for domestic and imported alcoholic beverages. Stakeholders must monitor evolving excise structures and health-warning regulations that increasingly determine market access and portfolio profitability across jurisdictions.
Market Dynamics
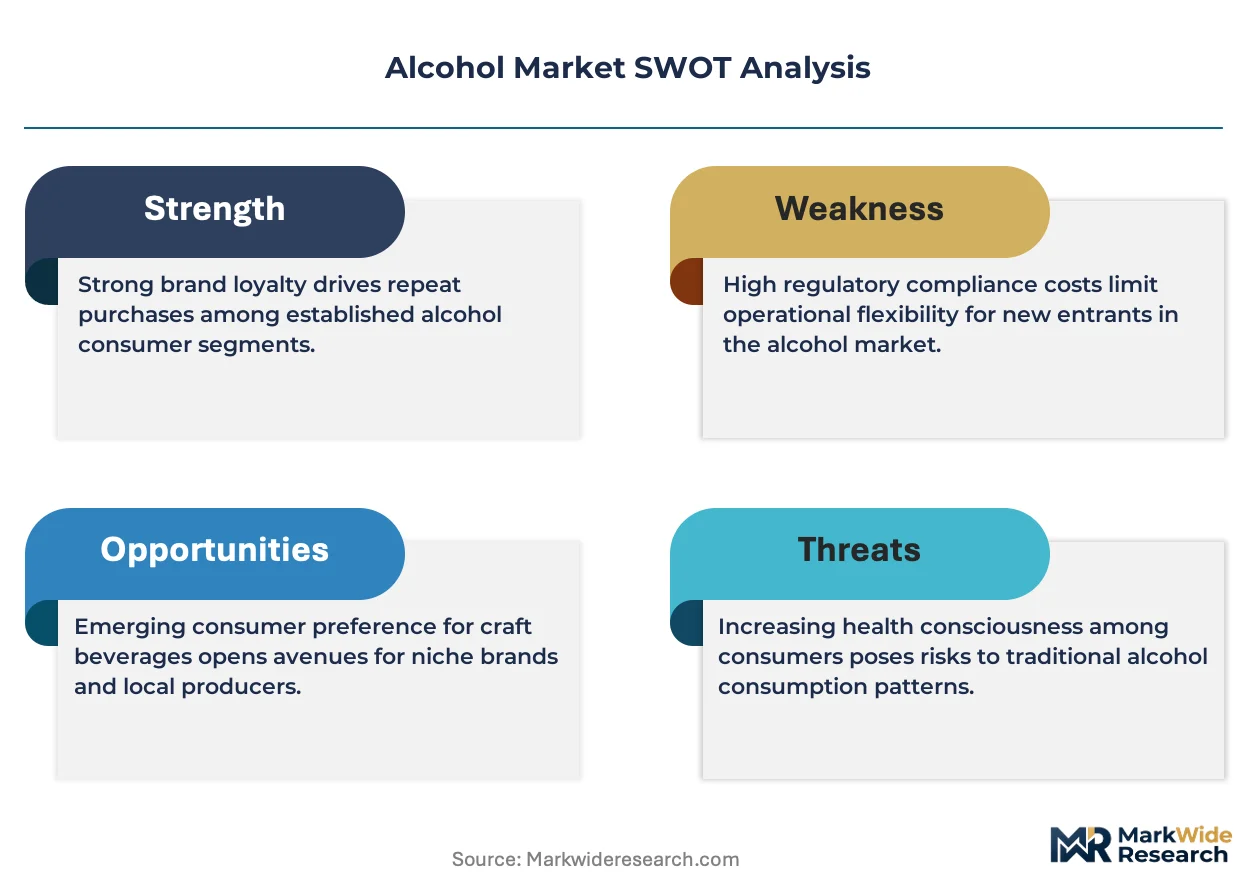
Premiumization pressure and regulatory tightening on packaging sustainability are restructuring profit pools across the alcohol value chain, forcing producers to rebalance volume against margin extraction.
Growth Catalysts
- India's FSSAI labeling mandates:Standardized quality disclosures are reducing information asymmetry and accelerating formalization of the country's fragmented spirits retail.
- Ceremonial gifting in China:Baijiu maintains embedded demand within business relationship protocols, insulating ultra-premium price tiers from cyclical consumption swings.
- Post-pandemic on-premise normalization:Hospitality channel recovery in developed economies is restoring higher-margin draft and by-the-glass serving formats.
Market Restraints
- Barley and grain input volatility:Brewing and distilling margins compress when commodity prices spike, with limited pass-through elasticity in mass-market segments.
- EU REACH-compliant packaging standards:Compliance costs for glass and label material substitutions fall disproportionately on smaller regional producers.
- Non-alcoholic beverage substitution:Functional drinks and zero-proof spirits are capturing occasions previously dominated by light beer and aperitifs.
Strategic Opportunities
- India's premium whisky category:Underpenetrated relative to per-capita income growth, with urban professional cohorts trading up from mass-market labels.
- EU CSRD carbon disclosure requirements:Early compliance creates differentiation for producers able to document supply chain emissions reductions.
- Direct-to-consumer channel expansion:E-commerce platforms and subscription models bypass traditional three-tier distribution constraints in permissive jurisdictions.
Industry Challenges
- Master distiller and blender talent scarcity:Aging expertise in Scotch and Cognac appellations outpaces apprenticeship pipeline replenishment.
- Aging inventory capital intensity:Spirits producers must finance multi-year maturation cycles before revenue realization, straining balance sheets during rate volatility.
- Cross-border excise harmonization friction:Divergent national tax structures complicate regional portfolio optimization and transfer pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcohol Market |
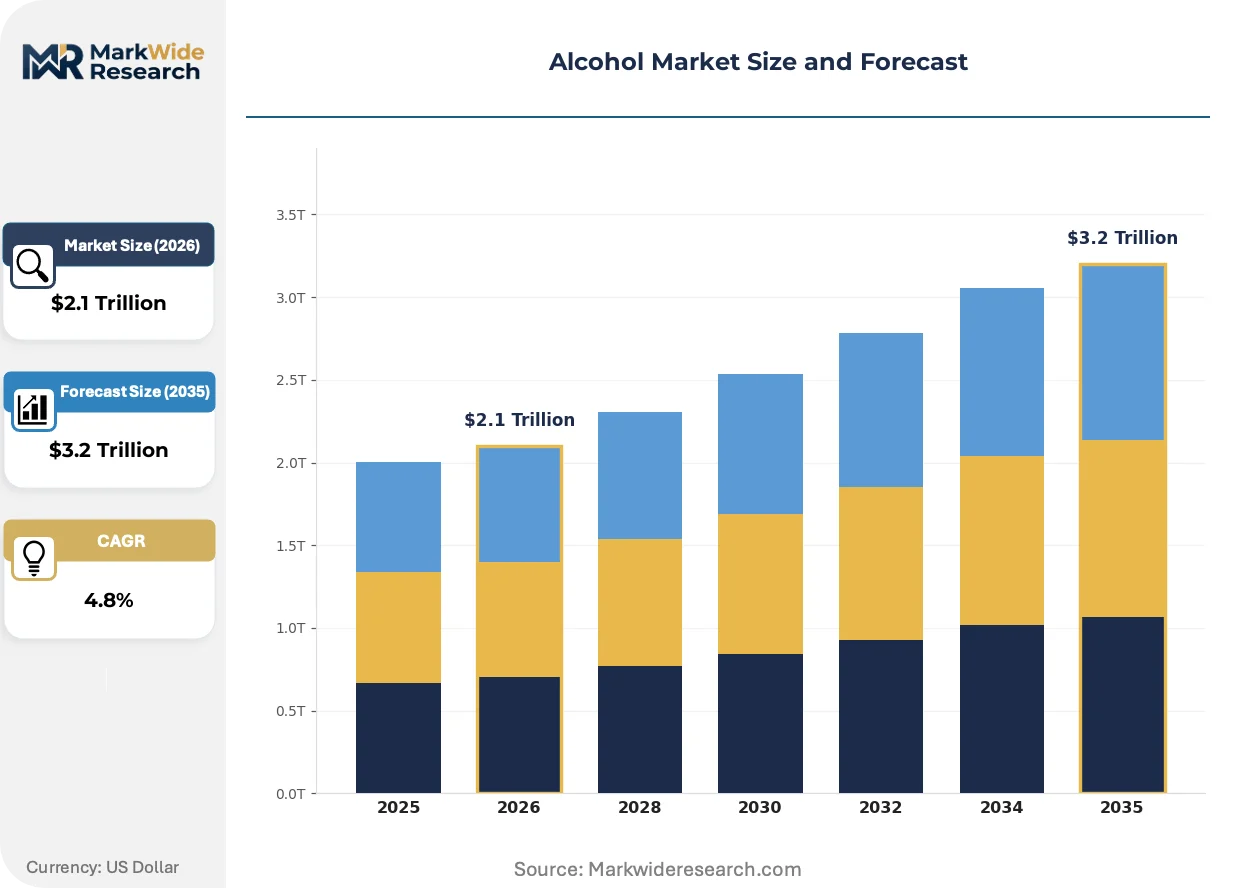
| Market Size in 2026 | $2.1 Trillion |
| Market Size in 2035 | $3.2 Trillion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer, Wine, Spirits, Cider Consumer Type: Millennials, Baby Boomers, Gen Z, Professionals Distribution Channel: Retail, Online, Wholesale, Bar Packaging Type: Bottles, Cans, Kegs, Pouches |
| Companies Covered | Anheuser-Busch InBev, Diageo, Pernod Ricard, Heineken, Constellation Brands, Suntory Holdings, Carlsberg Group, Kweichow Moutai, Brown-Forman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcohol Market Emerging Trajectories
Digital traceability and fermentation biotechnology are converging to reshape production transparency and ingredient sourcing, while regulatory pressure on packaging waste accelerates material substitution across the value chain.
Precision fermentation for flavor compounds is consolidating supply chain control for spirits producers seeking to reduce agricultural commodity exposure. Mid-tier distilleries in North America and Europe are adopting biosynthesized esters and terpenes to standardize batch consistency. This biotechnology is consolidating traditional supplier relationships between grain cooperatives and distillers into captive bioreactor operations.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in cold chain logistics, forcing refrigerated transport and warehouse operators serving beverage distribution to retrofit equipment. Compliance deadlines are compressing capital expenditure timelines for third-party logistics providers. Sparkling wine and beer segments with temperature-sensitive quality requirements face the steepest cost adjustments in Germany and France.
Certification-driven purchasing is elevating organic and biodynamic credentials from niche positioning to mainstream procurement criteria among hospitality buyers. Restaurant groups in Scandinavian markets now require documented sustainable viticulture certifications as table stakes for list placement. This preference shift is most visible in Copenhagen and Stockholm, where sommelier influence over beverage programs remains concentrated.
Alcohol Market Segmentation
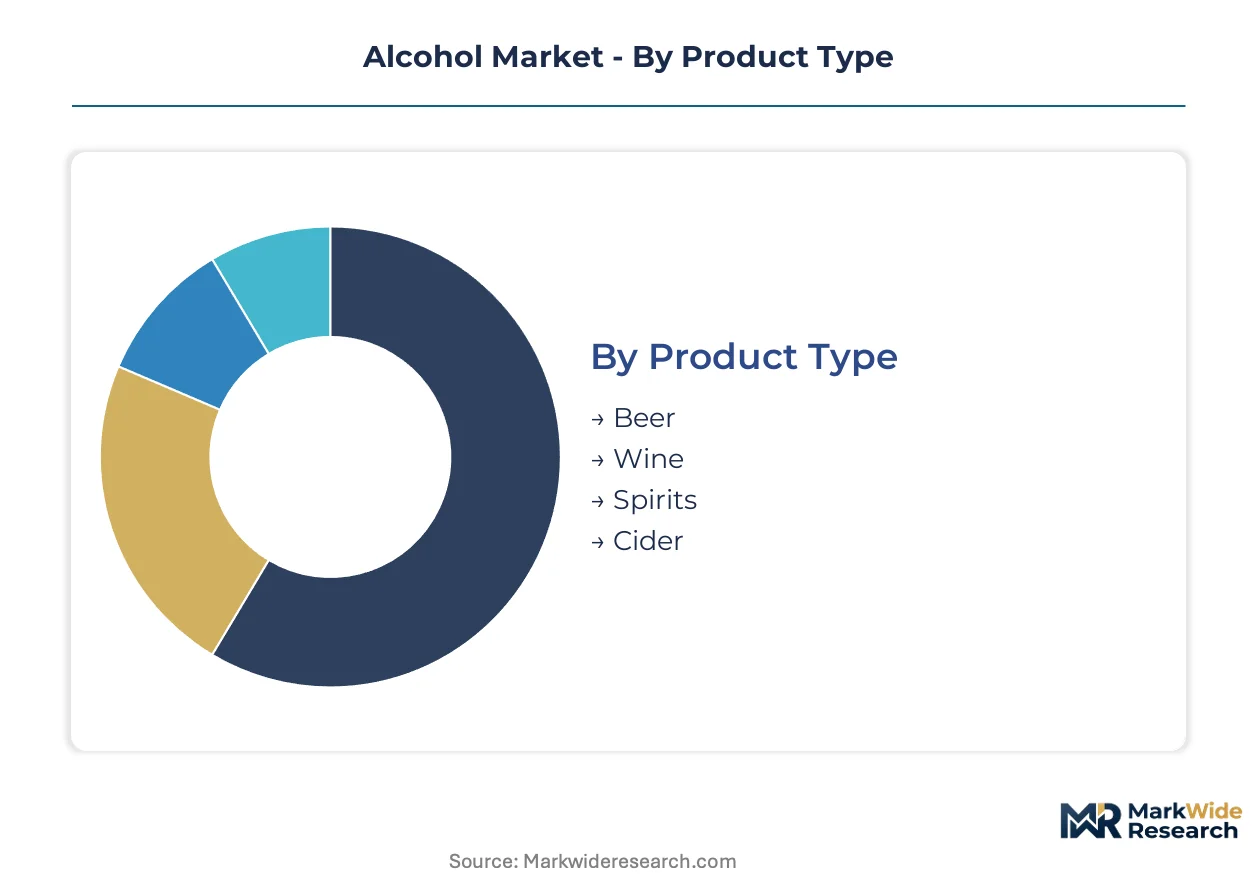
Alcohol producers segment portfolios to balance volume extraction against margin capture across divergent consumption occasions. Distinct packaging, channel, and generational strategies determine profitability within each tier.
Product Type:
Spirits command the widest premium-to-standard price spreads, while beer dominates physical volume throughput across brewing infrastructure.
- Spirits:Distilled beverages at 40%+ ABV including whisky, vodka, rum, and baijiu. Aging requirements and appellation controls create scarcity premiums. Demand concentrates in China's ceremonial gifting protocols and India's urban professional whisky upgrade cycle, insulated from mass-market price elasticity.
- Beer:Fermented grain beverages at 4-6% ABV produced through lager and ale processes. Draft and packaged formats split between on-premise hospitality and retail takeaway. Volume concentrates in mass-market lagers, though craft sub-segments extract premiums through localized brewing narratives.
- Wine:Fermented grape products spanning still, sparkling, and fortified categories. Certification-driven purchasing in Scandinavian hospitality elevates organic and biodynamic credentials from niche to table stakes.
- Cider:Apple or pear-based fermented beverages occupying gluten-free positioning in North American and European markets. Niche growth trajectory reflects dietary substitution rather than category expansion.
Mature deployment sits with Beer. Newer deployment is concentrated in Spirits.
Consumer Type:
Generational cohorts diverge sharply in channel preference, with professionals driving premium spirits trade-up and Gen Z showing substitution sensitivity.
- Professionals:Urban employed consumers aged 25-45 with discretionary income for premium and ultra-premium spirits. India's whisky category sees concentrated trading-up from this cohort as formalization reduces information asymmetry.
- Millennials:Consumers aged 28-43 exhibiting channel fluidity across e-commerce and on-premise discovery. Experience-driven consumption favors craft positioning and direct-to-consumer engagement models.
- Gen Z:Consumers aged 18-27 demonstrating elevated price sensitivity and health-conscious substitution toward zero-proof alternatives.
- Baby Boomers:Consumers aged 60-78 maintaining brand loyalty in established whisky and wine portfolios with lower channel-switching propensity.
Established loyalty patterns concentrate with Baby Boomers. Fastest category switching appears among Gen Z.
Distribution Channel:
Channel selection determines margin capture, with on-premise formats recovering post-pandemic and e-commerce bypassing traditional three-tier constraints.
- Bar:On-premise hospitality venues including independent establishments and managed chains. Draft beer and by-the-glass wine formats restore higher-margin serving economics as social dining normalizes.
- Retail:Licensed off-premise outlets including supermarkets, specialty stores, and convenience formats. Mass-market beer and standard spirits volumes flow through this channel with price-promotional sensitivity.
- Online:E-commerce platforms and subscription services operating within permissive regulatory frameworks. Direct-to-consumer models circumvent distributor markups where interstate shipping laws permit.
- Wholesale:Tier-two distributors managing state-level allocation in regulated markets such as the US three-tier system.
Traditional volume flows through Retail. Channel innovation concentrates in Online.
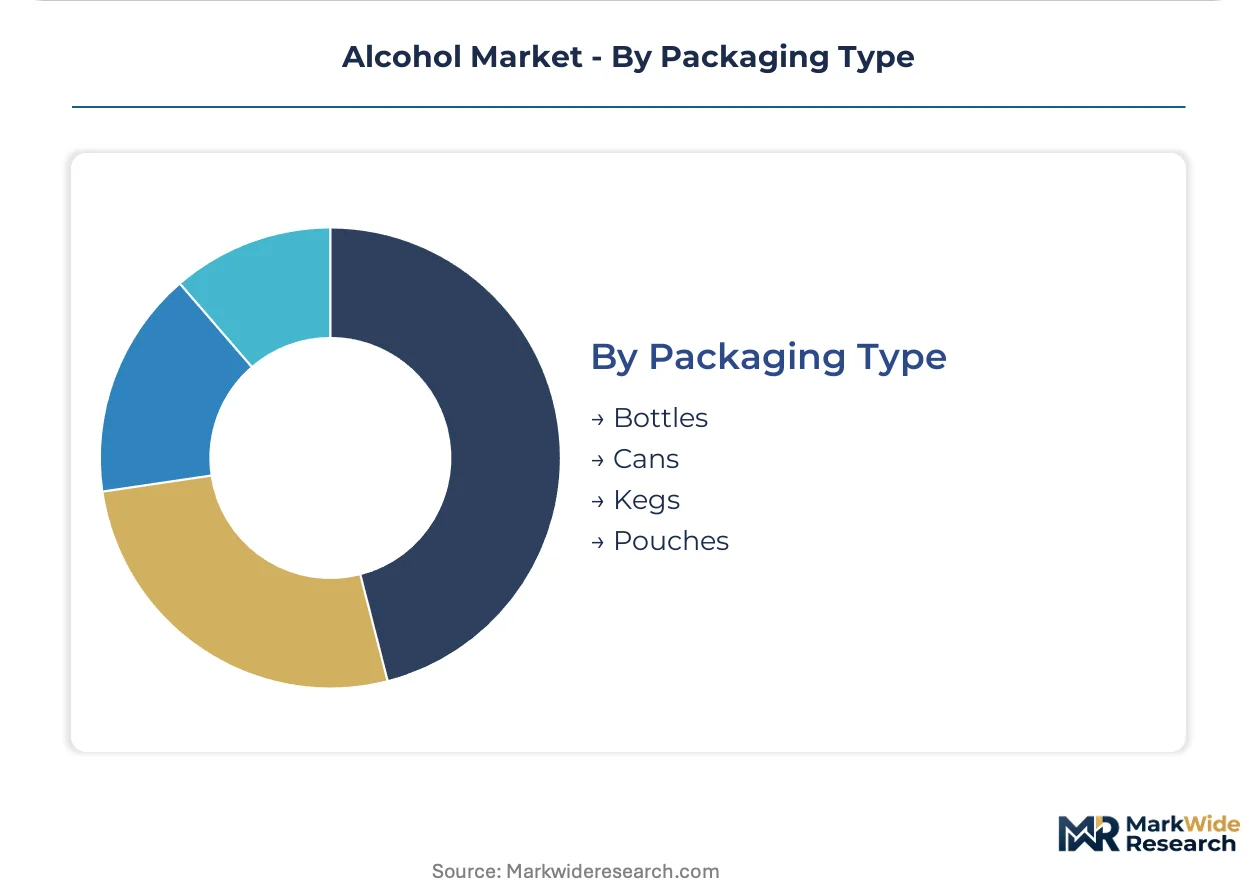
Packaging Type:
Material selection responds to EU REACH compliance costs and sustainability disclosure requirements under CSRD carbon accounting rules.
- Bottles:Glass containers dominating spirits and wine with established recycling infrastructure. EU packaging standards force material substitutions that disproportionately burden smaller regional producers.
- Cans:Aluminum formats capturing beer and ready-to-drink spirits growth. Lightweight logistics reduce transport emissions for carbon disclosure compliance.
- Kegs:Stainless steel returnable containers for on-premise draft beer. Cold chain requirements face F-Gas Regulation retrofit pressures in Germany and France.
- Pouches:Flexible film formats occupying niche positions in outdoor and festival consumption occasions.
Established infrastructure sits with Bottles. Format innovation concentrates in Cans.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Guizhou province anchors ultra-premium spirits production through tax-advantaged distilling zones. Concentrated baijiu manufacturing clusters in Maotai town generate ceremonial gifting demand insulated from cyclical swings. The region's embedded business relationship protocols sustain pricing power at the top tier.
China
Ceremonial baijiu gifting drives ultra-premium volume within business relationship protocols. SAMR enforces anti-monopoly oversight on dominant distiller pricing power. Maotai town in Guizhou province concentrates heritage production infrastructure serving state banquet and corporate procurement channels.
United States
Craft spirits revival and RTD innovation attract millennial discovery-driven consumption. TTB labeling mandates and FDA interstate commerce standards govern distribution compliance. Kentucky's Bourbon Trail and Tennessee's Lynchburg cluster anchor whiskey tourism and heritage brand positioning.
India
Urban professional cohorts trade up from mass-market whisky toward premium labels as formalization accelerates. FSSAI manufacturing licensing and quality standards reduce information asymmetry in fragmented retail. Maharashtra's Mumbai-Pune corridor and Karnataka's Bangalore cluster concentrate premium spirits consumption and imported brand distribution.
Germany
Beer purity tradition and craft brewing resurgence sustain domestic volume despite demographic headwinds. EU F-Gas Regulation cold chain compliance pressures refrigerated logistics serving temperature-sensitive segments. Bavaria's Munich-Upper Palatinate belt anchors mass-market lager production and Oktoberfest-driven seasonal demand.
United Kingdom
Scotch whisky exports and gin craft revival drive premium spirits trade balance. ECHA REACH packaging standards and CSRD carbon disclosure requirements shape sustainability compliance costs. Scotland's Speyside and Islay regions concentrate aged malt inventory and tourism-linked distillery visitor economics.
Alcohol Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with heritage distillers commanding scarcity premiums and mass-market brewers extracting volume through brewing infrastructure scale. The vendor base organizes into three strategic archetypes: ultra-premium heritage houses with generational inventory, multinational brewers with continental distribution networks, and regional craft specialists with localized narrative positioning. Competitive moves concentrate on portfolio diversification into adjacent categories and geographic expansion through acquisition-led market entry.
Within the ultra-premium heritage tier, Kweichow Moutai and Diageo exemplify divergent approaches to scarcity value creation—one through appellation-locked ceremonial positioning, the other through aged spirits portfolio breadth. Anheuser-Busch InBev occupies a position at the scale-driven end, representing the brewing infrastructure archetype that dominates mass-market volume across multiple continents through production network density.
| Leading Market Players |
|---|
| Anheuser-Busch InBev |
| Diageo |
| Pernod Ricard |
| Heineken |
| Constellation Brands |
| Suntory Holdings |
| Carlsberg Group |
| Kweichow Moutai |
| Brown-Forman |
| Others |
Supply Flow & Price Mechanics
Precision fermentation for biosynthesized flavor compounds is consolidating traditional supplier relationships into captive bioreactor operations, simultaneously reducing agricultural commodity exposure for spirits producers and concentrating supply control among integrated manufacturers with capital to deploy biotechnology infrastructure.
Pricing Analysis
Aging-inventory financing creates lead-time-driven pricing stratification across premium, standard, and economy tiers, with ultra-premium spirits commanding scarcity premiums for extended maturation while mass-market beer faces spot-price volatility in barley and grain inputs. Brand equity and appellation certification separate pricing tiers most sharply in Scotch whisky and baijiu segments. Pricing pressure stems from input cost pass-through limitations in volume-dominated beer categories. Mass-market consumers exhibit highest price sensitivity; ceremonial gifting buyers in China show lowest elasticity.
Supply Chain Analysis
Direct-to-retail and wholesale three-tier channels handle mass-market volume, while direct-to-consumer platforms bypass distributor markups in permissive jurisdictions. Manufacturing concentrates in China for baijiu, Scotland for aged malt whisky, and India for domestic spirits production. Supply chains draw from barley cooperatives, grape harvests, and biotechnology feedstocks. Single-source vulnerability runs through heritage distillery expertise and master blender talent pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH-compliant packaging standards and FSSAI labeling mandates are accelerating consolidation by raising compliance costs that fragment smaller regional producers.
For Market Incumbents: Deepen backward integration into biotechnology feedstocks to reduce agricultural commodity exposure and standardize batch consistency. Expand direct-to-consumer channel infrastructure in permissive jurisdictions to capture margin otherwise lost to three-tier distributor markups. Master distiller talent scarcity threatens aging inventory quality; apprenticeship pipeline investment defends long-term scarcity positioning.
For New Entrants and Emerging Players: Capture India's premium whisky upgrade cycle by targeting urban professional cohorts trading up from mass-market labels as FSSAI formalization reduces information asymmetry. Enter through e-commerce subscription models that circumvent traditional distribution constraints where interstate shipping laws permit. Position against zero-proof substitution threat with functional low-ABV alternatives.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier distilleries adopting precision fermentation given biotechnology's consolidation of traditional supplier relationships. Long-term viability favors producers with documented carbon disclosure compliance under EU CSRD requirements ahead of mandatory disclosure windows. Monitor F-Gas Regulation retrofit deadlines in Germany and France as inflection indicators for cold chain logistics cost structures affecting temperature-sensitive segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Adoption | Biosynthesized flavor compounds reduce barley and grain commodity exposure for spirits producers. |
| Direct-to-Consumer Channel Expansion | E-commerce platforms bypass three-tier distributor markups where interstate shipping laws permit. |
| Carbon Disclosure Compliance Investment | Early CSRD documentation creates differentiation ahead of mandatory EU sustainability reporting. |
| Master Distiller Apprenticeship Programs | Talent pipeline replenishment defends aging inventory quality in Scotch and Cognac appellations. |
| Biodynamic Certification Acquisition | Organic credentials become table stakes for hospitality procurement in Scandinavian markets. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with master distillers, brewery operations directors, F&B procurement managers at hospitality groups, and spirits distribution executives. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the analysis window. Secondary sources included TTB label approvals, EU ECHA substance registrations, FSSAI manufacturing licenses, and national excise revenue disclosures.
Data-stream reconciliation aligned production volume surveys with consumption tracking and trade flow analysis. Segmentation dimensions spanned product type, consumer cohort, distribution channel, and packaging format alongside regional regulatory cluster variations. CAGRs derived from trend extrapolation with cross-validation against input cost trajectories and demographic consumption pattern shifts. Industry-specific forecast inputs incorporated aging inventory cycle timing and biotechnology adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to excise tax harmonization friction and climate volatility affecting barley and grape harvests. Practitioners should monitor FSSAI enforcement intensity and EU packaging material substitution deadlines for early signals of compliance cost redistribution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Spain Alcohol E-Commerce Market
Alcoholic Beverages
Single Serve Wine Market
Alcoholic Beverages
Cooking Wine Market
Alcoholic Beverages
Spirit-Based RTD Mixes Market
Alcoholic Beverages
Pinot Meunier Market
Alcoholic Beverages
Malt Whiskey Market
Alcoholic Beverages
Global Beer Market
Alcoholic Beverages
Automated Brewing System Market
Alcoholic Beverages
Mushroom Beer Market
Alcoholic Beverages
Bahrain Alcoholic Beverages Market
Alcoholic Beverages
South Korea Tequila Market
Alcoholic Beverages
RTD Cocktails Market
Alcoholic Beverages
High-End Chinese Spirits Market
Alcoholic Beverages
Global Craft Vodka Market
Alcoholic Beverages
Hard Tea Market
Alcoholic Beverages
Dark Beer Market