
 Moonshine Market | 2026-2036
Moonshine Market Size, Share, and Industry Trends Forecast 2026-2036
Moonshine Market Outlook
Appalachian craft distillers is decoupling from legacy supply constraints as copper pot still capacity expands across eastern Tennessee and western North Carolina. Ole Smoky Distillery anchors its position through vertical integration from grain sourcing to retail tasting rooms in Gatlinburg. Sugarlands Distilling Company leverages direct-to-consumer channels at its Pigeon Forge facility. Midnight Moon differentiates through flavored moonshine innovation that broadens appeal beyond traditional whiskey drinkers.
Moonshine denotes unaged or minimally aged distilled spirits typically produced from corn mash at proofs ranging from 80 to 190, historically associated with illicit Appalachian production but now manufactured under federal license for legal commercial sale. The spirit serves mixologists seeking high-proof bases for craft cocktails and consumers pursuing authentic regional heritage experiences. Traditional variants occupy mature shelf positions at established liquor retailers, while flavored moonshine captures expanding trial among younger legal-age drinkers. Organic moonshine commands premium positioning as clean-label preferences extend into spirits, though certified organic grain supply limits scaling. Distribution through on-premise bars and restaurants generates higher margins per case than wholesale retail channels.
The U.S. TTB governs formula approval, label certification, and excise tax collection for all legal moonshine production, while state alcohol beverage control boards administer retail licensing that varies across jurisdictions. FDA food safety standards apply to flavored and infused variants containing non-alcoholic ingredients. Producers must navigate the tension between heritage storytelling and evolving state regulations governing distillery tasting room operations and direct shipping permissions. Stakeholders should monitor pending federal excise tax reforms and state-level direct-to-consumer shipping expansions that could reshape competitive access.
Market Dynamics
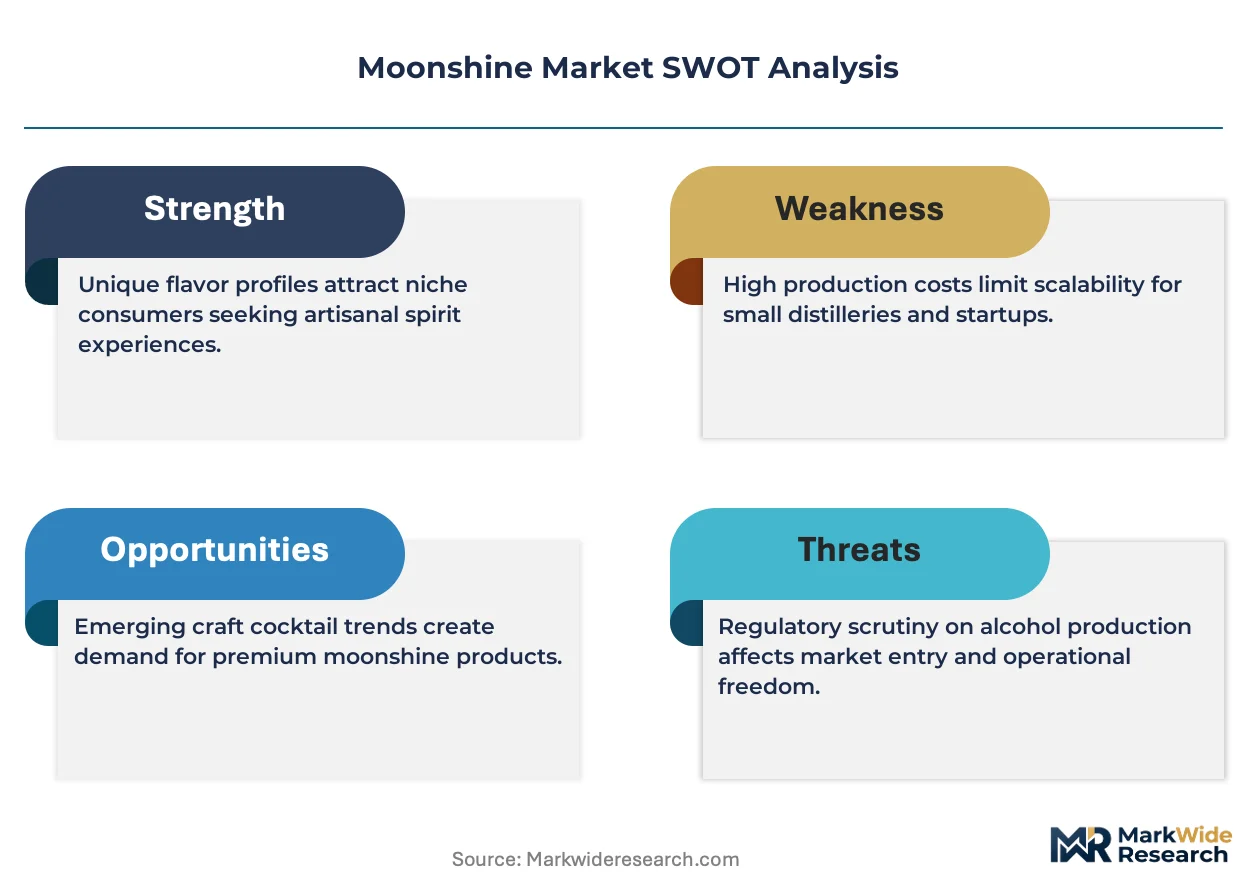
Copper pot still capacity expansion across eastern Tennessee and western North Carolina is decoupling Appalachian craft distillers from legacy supply constraints, reshaping competitive access to high-proof unaged spirits production.
Growth Catalysts
- TTB Licensing Clarity:The U.S. Alcohol and Tobacco Tax and Trade Bureau's streamlined formula approval process reduces compliance timelines for legal moonshine producers entering commercial distribution.
- Craft Cocktail Bar Demand:Mixologists in Nashville and Austin are driving adoption of flavored and infused moonshine variants as high-proof bases for heritage-inspired cocktails.
- Grain Belt Proximity:Corn mash supply concentration across the Appalachian corridor lowers input logistics costs for Tennessee and North Carolina distillers.
Market Restraints
- Organic Grain Scarcity:Certified organic corn supply limitations constrain scaling of premium clean-label moonshine variants despite consumer preference shifts.
- State Licensing Fragmentation:Alcohol beverage control boards administer inconsistent retail licensing and direct shipping permissions across U.S. jurisdictions, complicating multi-state distribution.
- Whiskey Substitution:Aged bourbon and rye whiskey from established Kentucky distilleries compete for shelf space and consumer trial among heritage-seeking drinkers.
Strategic Opportunities
- Direct-to-Consumer Channels:Distillery tasting room operations and state-level shipping expansions offer margin advantages over wholesale retail distribution.
- Flavored Innovation White Space:Fruit-infused and spice-modified moonshine variants attract younger legal-age drinkers outside traditional whiskey demographics.
- Heritage Tourism Integration:Appalachian distillery trail positioning captures experiential spending from visitors seeking authentic regional production narratives.
Industry Challenges
- Copper Still Fabrication Bottlenecks:Skilled artisan capacity for custom pot still construction limits rapid production scale-up for emerging distillers.
- FDA Flavor Compliance Complexity:Food safety standard navigation for infused variants containing non-alcoholic ingredients extends product development timelines.
- Excise Tax Reform Uncertainty:Pending federal tax structure revisions create planning friction for capital deployment and pricing strategy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moonshine Market |
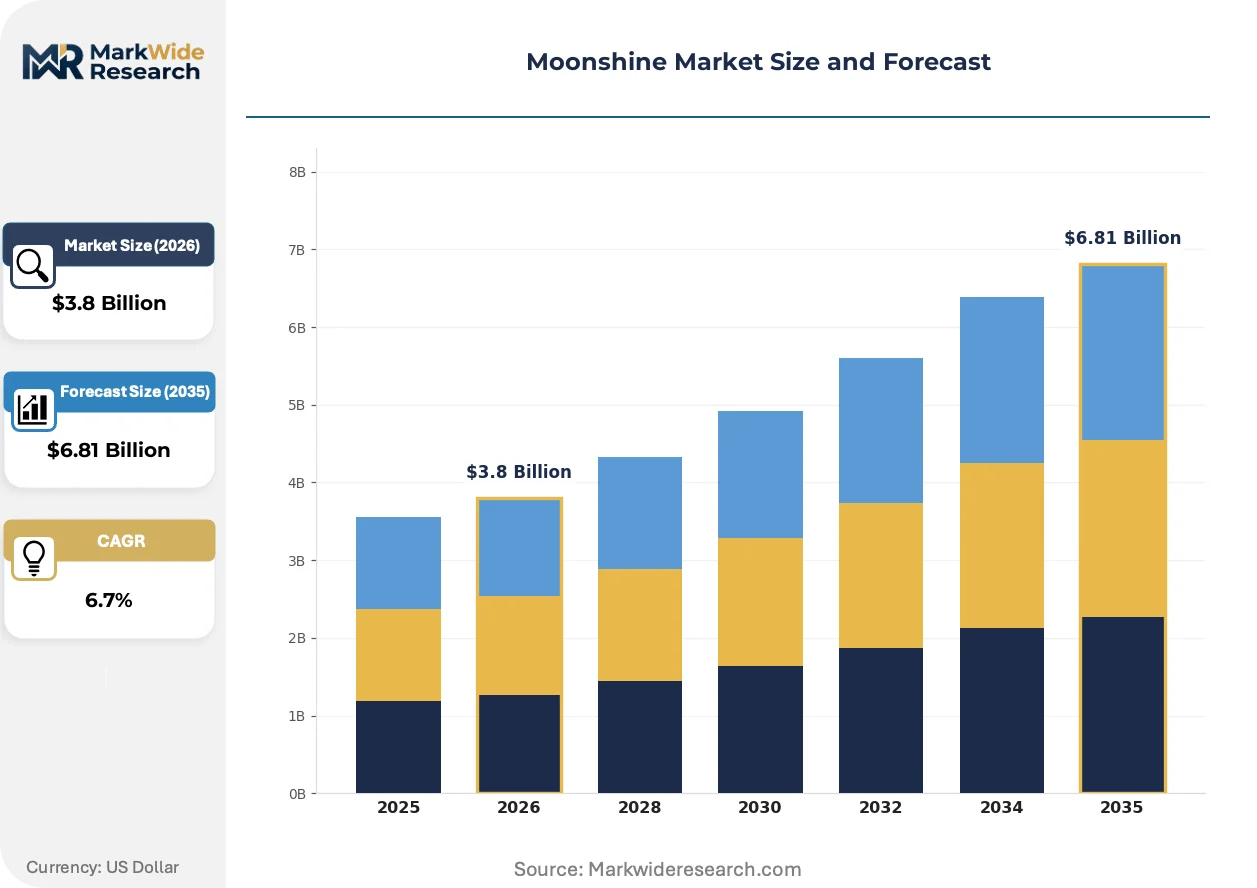
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Flavored, Organic, Infused End User: Bars, Restaurants, Retail Stores, Events Distribution Channel: Online, Wholesale, Direct Sales, Export Packaging Type: Bottles, Cans, Kegs, Tubs |
| Companies Covered | Tennessee Shine Company, Stillhouse Spirits Co., Ole Smoky Distillery, Blue Ridge Distilling Co., Mason Jar Distillery, Sugarlands Distilling Company, Hooch Distillery, Neeley Family Distillery, Midnight Moon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moonshine Market Strategic Shifts
Heritage storytelling is converging with production technology modernization and channel diversification to reshape how unaged spirits reach legal-age consumers seeking authentic regional experiences.
Continuous column still adoption is overtaking traditional batch copper pot methods among mid-scale Appalachian producers seeking throughput gains without sacrificing mash bill character. Nashville craft cocktail bars are adopting these higher-volume outputs for house-made infusions. The technology is overtaking artisan-only positioning as a viable middle path between heritage authenticity and commercial viability.
State direct-to-consumer shipping permissions are expanding tasting room sales beyond physical visitation, with Virginia and North Carolina legislatures advancing distillery-to-doorstep frameworks. This regulatory loosening compresses three-tier distribution dependence for small producers. Appalachian craft distillers are responding by building in-house fulfillment capabilities parallel to wholesale retail relationships.
Younger legal-age drinkers are rotating toward flavor-forward, lower-proof sipping occasions that displace traditional high-proof shot consumption. Pigeon Forge and Gatlinburg retail tasting rooms are capturing this shift through guided sampling experiences that emphasize mixology versatility over potency. The behavioral pivot is most visible in Tennessee corridor tourism markets where experience-driven purchase decisions dominate.
Moonshine Market Segmentation
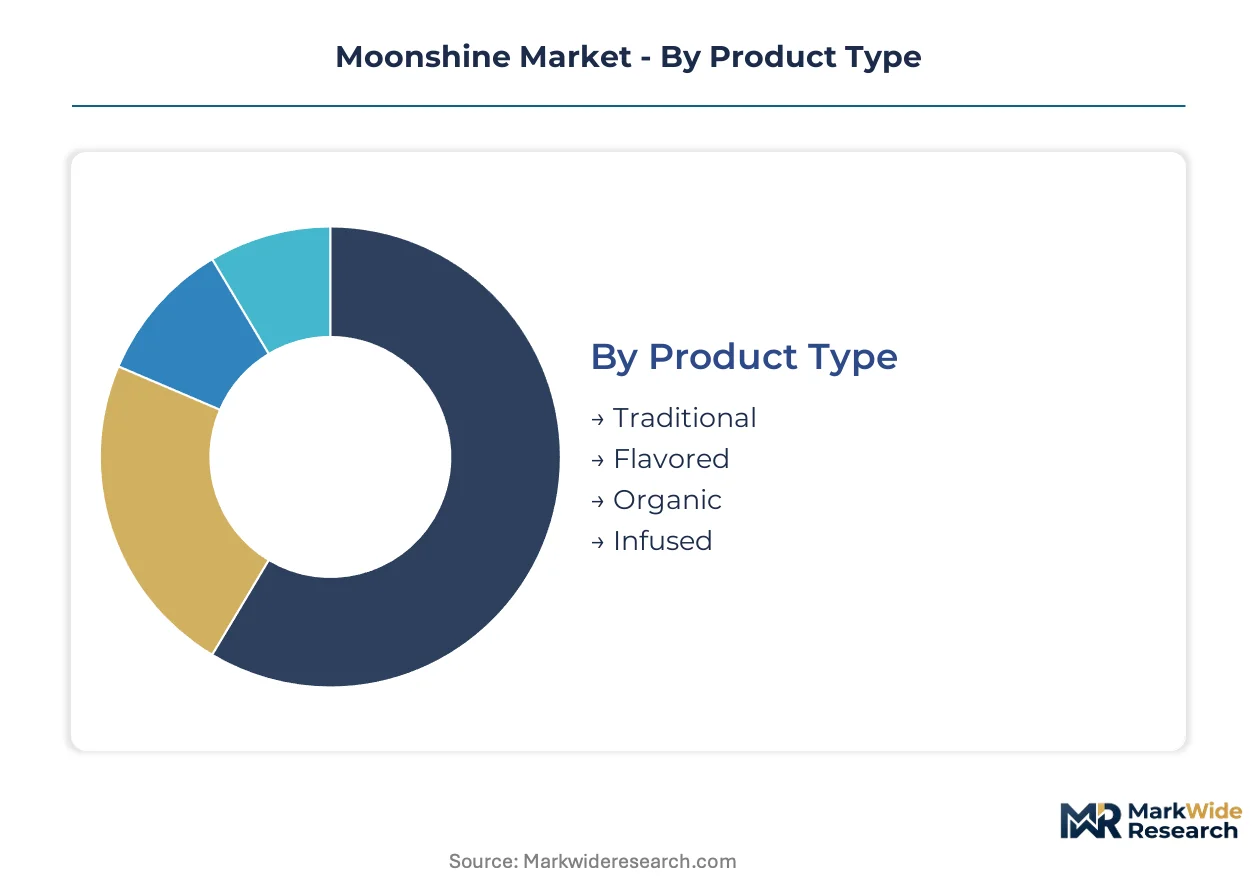
Moonshine producers configure product portfolios around proof levels, flavor innovation cycles, and channel access permissions. Distinct segment economics govern margin capture across unaged traditional variants versus infused offerings requiring FDA compliance overhead.
Product Type:
Supply concentration in eastern Tennessee and western North Carolina tilts production capacity toward corn-forward mash bills with minimal barrel aging requirements.
- Traditional:Unaged or minimally aged spirits distilled from corn mash at 80-190 proof, preserving the clear high-proof character that defines Appalachian heritage positioning. Nashville craft cocktail bars deploy these expressions as cocktail bases where potency carries the flavor profile.
- Flavored:Fruit and spice infusions broadening trial among legal-age drinkers outside whiskey-native demographics. Pigeon Forge and Gatlinburg tasting rooms capture tourism-driven sampling demand for these accessible variants.
- Organic:Certified organic grain inputs command premium shelf positioning as clean-label preferences extend into spirits, though certified corn supply constraints limit producer scaling.
- Infused:Non-alcoholic ingredient additions requiring FDA food safety navigation that extends development timelines for producers seeking differentiated flavor profiles.
Traditional moonshine absorbs the bulk of installed copper pot still capacity; flavored variants are expanding most quickly among younger legal-age trialists.
End User:
Cost tier stratification separates on-premise accounts capturing experience-driven spending from retail channels competing on case velocity.
- Bars:Mixology-forward accounts in Austin and Nashville driving heritage-cocktail innovation with high-proof bases. These operators generate superior per-case margins through premium pour positioning.
- Restaurants:Table-service establishments incorporating moonshine into dessert pairings and regional cuisine menus, particularly across the Appalachian corridor where heritage storytelling resonates.
- Retail Stores:Established liquor retailers where traditional variants hold mature shelf positions against bourbon and rye substitution pressure.
- Events:Festival and private function placements capturing impulse trial through guided tasting formats.
Bars command the highest margin per case served; restaurants are climbing the fastest as heritage cuisine integration accelerates.
Distribution Channel:
Volume concentration favors wholesale three-tier relationships, though margin structure favors direct access models where state permissions allow.
- Online:State-level direct-to-consumer shipping expansions in Virginia and North Carolina compress distributor dependence for small producers building in-house fulfillment.
- Wholesale:Dominant pathway through licensed distributors to retail accounts, carrying margin compression but enabling multi-state footprint expansion.
- Direct Sales:Distillery tasting room operations and door-to-door shipping where permitted, capturing full retail margin on visitor conversions.
- Export:Limited international placement constrained by TTB export certification requirements and destination market spirits regulations.
Wholesale channels absorb the bulk of case volume; direct sales are gaining share fastest where state legislatures advance shipping permissions.
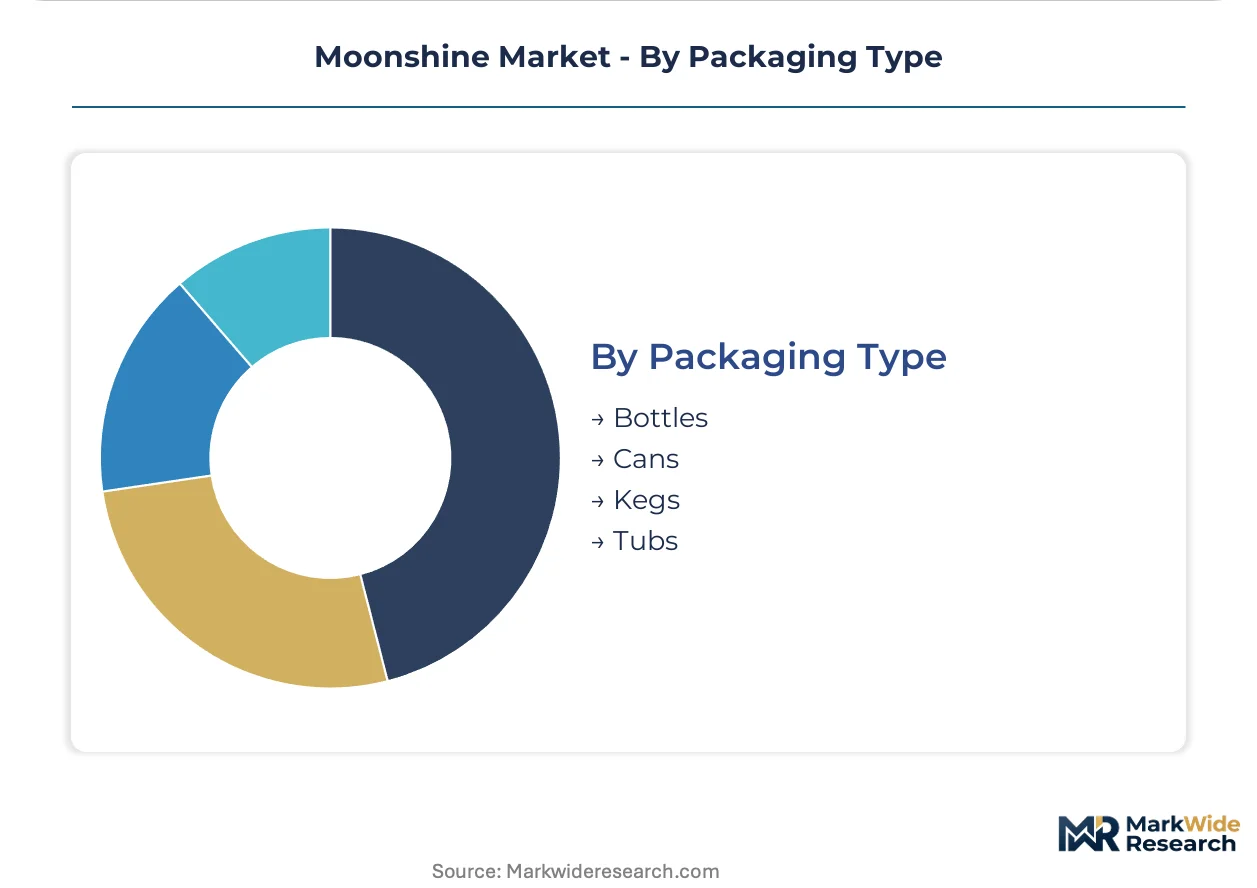
Packaging Type:
Customer type differentiation separates experience-driven tourism purchases from convenience-oriented retail takeaway formats.
- Bottles:Standard 750ml and 1-liter glass formats dominating retail shelf presence and home consumption occasions across licensed liquor stores.
- Cans:Single-serve ready-to-drink formats capturing outdoor and casual consumption scenarios with lower trial barriers.
- Kegs:On-premise draft formats serving high-volume bar accounts seeking efficient pour economics for house-made infusions.
- Tubs:Large-format souvenir containers targeting Gatlinburg and Pigeon Forge tourism corridors where experiential purchase decisions dominate.
Bottles carry the bulk of production volume; cans are expanding most quickly among younger legal-age drinkers seeking portable consumption formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corn belt proximity across the Appalachian corridor anchors legal moonshine production geography, with eastern Tennessee and western North Carolina hosting the densest concentration of licensed distillers.
United States
The TTB governs formula approval and excise tax collection for all legal production, while craft cocktail bars in Nashville and Austin drive flavored variant adoption. State alcohol beverage control boards administer inconsistent retail licensing across jurisdictions. Gatlinburg and Pigeon Forge in eastern Tennessee concentrate tourism-driven tasting room traffic.
Canada
Provincial liquor monopolies in Ontario and Quebec control distribution access for American moonshine imports, constraining market penetration. Health Canada regulates food safety standards for flavored variants containing non-alcoholic ingredients. Alberta's privatized retail system offers more flexible shelf placement for heritage spirits positioning.
Germany
Steinhäger and other unaged grain spirits traditions create cultural receptivity for American moonshine imports among experimental mixologists. The BfR (Federal Institute for Risk Assessment) evaluates flavor additive safety for infused variants entering the market. Berlin's craft cocktail scene generates niche demand through heritage-inspired bar programs.
United Kingdom
HMRC excise duty structures favor lower-proof flavored spirits over traditional high-proof unaged variants in retail pricing. The FSA (Food Standards Agency) administers ingredient safety compliance for fruit-infused expressions. London's Shoreditch and Soho bar clusters trial American heritage spirits in seasonal cocktail menus.
Australia
State-based liquor licensing authorities in New South Wales and Victoria regulate direct-to-consumer shipping permissions for international craft distillers. FSANZ (Food Standards Australia New Zealand) governs additive safety for flavored imports. Melbourne's Brunswick and Sydney's Surry Hills neighborhoods host mixology-forward accounts experimenting with high-proof cocktail bases.
Moonshine Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue flavored innovation and direct-to-consumer channel expansion. The vendor base clusters around Appalachian craft distillers with federal TTB licensing and multi-state distribution relationships. Three archetypes dominate: heritage storytellers leveraging regional authenticity, flavor innovators capturing younger legal-age trialists, and vertically integrated operators controlling grain-to-glass production. Capacity expansion through copper pot still fabrication and state-level direct shipping permissions represent the dominant competitive moves.
Among Appalachian heritage specialists, Ole Smoky Distillery and Sugarlands Distilling Company exemplify the vertically integrated archetype through Gatlinburg and Pigeon Forge tasting room operations. Midnight Moon occupies a position within the flavor innovation tier, representing the broader shift toward fruit-infused variants that broaden demographic appeal beyond traditional whiskey consumers. These three anchors illustrate the competitive tension between authenticity positioning and accessibility expansion that shapes portfolio strategy across the category.
| Leading Market Players |
|---|
| Tennessee Shine Company |
| Stillhouse Spirits Co. |
| Ole Smoky Distillery |
| Blue Ridge Distilling Co. |
| Mason Jar Distillery |
| Sugarlands Distilling Company |
| Hooch Distillery |
| Neeley Family Distillery |
| Midnight Moon |
| Others |
Value Chain & Pricing Dynamics
Continuous column still adoption across eastern Tennessee and western North Carolina simultaneously lowers per-unit production costs and concentrates distilling capacity among mid-scale producers capable of financing equipment upgrades. This technology transition compresses pricing power for traditional copper pot still operators while rewarding operators achieving throughput gains without sacrificing mash bill character.
Pricing Analysis
Tasting room experience bundling versus unbundled wholesale pricing creates the dominant pricing architecture across the category. Three-tier pricing structure across premium, standard, and economy levels separates organic certified variants from flavored expressions and traditional unaged spirits. Price differentiation rests on grain sourcing transparency and TTB formula approval tier. Cost compression in standard-tier traditional moonshine is intensifying because continuous still operators are expanding output. Retail liquor stores exhibit highest price sensitivity; craft cocktail bars in Nashville and Austin show lowest sensitivity due to premium pour positioning.
Supply Chain Analysis
Rail and trucking freight costs from corn belt elevators to Appalachian distilleries constitute the dominant logistics expense component in landed grain costs. Supply concentrates in the United States, specifically eastern Tennessee, western North Carolina, and Virginia. Raw material dependencies include yellow dent corn, copper still components from specialized fabricators, and oak adjuncts for minimal aging programs. Single-source vulnerability sits with artisan copper pot still construction capacity. Distribution runs through three-tier wholesale networks to retail accounts, with direct-to-consumer channels gaining share where state permissions allow.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vertically integrated operators with tasting room footprints, as TTB licensing complexity and copper still fabrication bottlenecks force undercapitalized entrants toward exit.
For Market Incumbents: Lock in grain supply contracts with Appalachian corn growers before harvest season pricing volatility accelerates. Secure exclusive relationships with artisan copper still fabricators in eastern Tennessee to constrain competitor capacity expansion. The threat of continuous column still operators achieving cost parity while scaling output demands defensive positioning through backward integration into grain sourcing. For New Entrants and Emerging Players: Capture flavored moonshine white space targeting legal-age drinkers outside traditional whiskey demographics through fruit-forward innovation pipelines. The most penetrable segment is ready-to-drink canned formats for outdoor consumption scenarios. Go-to-market execution should prioritize direct-to-consumer shipping permissions in Virginia and North Carolina before building wholesale relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by beverage conglomerates seeking heritage spirits portfolios. Long-term viability favors operators controlling grain-to-glass production with established tasting room economics. The acquisition target archetype is vertically integrated Appalachian distillers with TTB licensing and direct shipping permissions. Watch state-level excise tax reform proposals as the inflection signal for valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Copper Pot Still Capacity Expansion | Custom fabrication relationships in eastern Tennessee secure production scalability against competitor constraints. |
| Direct-to-Consumer Channel Buildout | In-house fulfillment capabilities in Virginia and North Carolina compress three-tier margin dependence. |
| Flavored Variant Pipeline Development | Fruit and spice infusions broaden trial among legal-age drinkers outside traditional whiskey demographics. |
| Organic Grain Supply Contracting | Certified corn sourcing agreements with Appalachian growers command premium shelf positioning. |
| Tasting Room Experience Integration | Gatlinburg and Pigeon Forge tourism corridors capture experiential spending through guided sampling formats. |
Study Parameters
Document review covered TTB formula approval databases, state alcohol beverage control board filings, and SEC disclosures from publicly traded beverage conglomerates, complemented by interviews with distillery operations managers, craft cocktail bar proprietors in Nashville and Austin, copper still fabricators, and grain elevator procurement leads. Secondary sources included customs trade data, state tourism authority visitor statistics, and FDA food safety guidance documents. Bottom-up production capacity estimates triangulated against top-down consumption projections.
Model outputs generated volume and value trajectories across the projection horizon through segmented demand modeling. Segmentation dimensions included product type, end user channel, distribution pathway, and packaging format. CAGRs were derived from historical trend extrapolation adjusted for regulatory inflection points. Industry-specific forecast inputs incorporated state direct shipping permission expansions and pending federal excise tax reform scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to organic grain supply constraints and copper still fabrication capacity bottlenecks. Forecasts reflect documented assumptions about TTB licensing timelines and state legislative trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Global Malt Market
Alcoholic Beverages
Canned Alcoholic Beverages Market
Alcoholic Beverages
Guerbet Alcohols Market
Alcoholic Beverages
Light-Flavor Liquor Market
Alcoholic Beverages
Global Shortenings Market
Alcoholic Beverages
Fruit Beer Market
Alcoholic Beverages
Beer Stabilizers Market
Alcoholic Beverages
Bioalcohols Market
Alcoholic Beverages
Wine Enzymes Market
Alcoholic Beverages
Champagne Market
Alcoholic Beverages
Balsam Bottle Market
Alcoholic Beverages
Asia Pacific Wine Coolers Market
Alcoholic Beverages
Beer Keg System Market
Alcoholic Beverages
Alcohol Market
Alcoholic Beverages
Spain Alcohol E-Commerce Market
Alcoholic Beverages
Sake Market