
 Chronic Obstructive Pulmonary Disease Drugs Market | 2026-2036
Chronic Obstructive Pulmonary Disease Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Obstructive Pulmonary Disease Drugs Market Intelligence
MDR compliance is pivoting the cost-of-entry calculus for COPD device-drug combinations across European markets. AstraZeneca leverages its biologics platform to sustain leadership in exacerbation-focused therapies. Boehringer Ingelheim anchors its position through deep inhaler engineering capabilities and pulmonary specialist channel control.
Chronic obstructive pulmonary disease drugs comprise pharmacological agents targeting airflow limitation, including long-acting beta-agonists, anticholinergics, corticosteroids, and phosphodiesterase-4 inhibitors formulated for bronchodilation and anti-inflammatory action. These therapies function primarily to reduce acute exacerbation frequency, improve forced expiratory volume, and slow disease progression in patients with persistent respiratory symptoms. Bronchodilators occupy the largest volume share due to universal first-line prescribing protocols, while combination drugs capture accelerating share as physicians favor simplified regimens with improved adherence profiles. Inhalers dominate value pools through premium device technology, though nebulizers retain structural importance in severe disease and institutional settings.
The FDA maintains stringent bioequivalence standards for generic dry powder inhalers, while the EMA enforces MDR device-drug combination rules that elevate documentation burdens. Japan's PMDA applies distinct clinical bridging requirements for foreign-originated respiratory products, shaping regional launch sequencing. Stakeholders must monitor how payer consolidation and real-world evidence mandates reshape reimbursement dynamics for novel triple-therapy entrants.
Market Dynamics
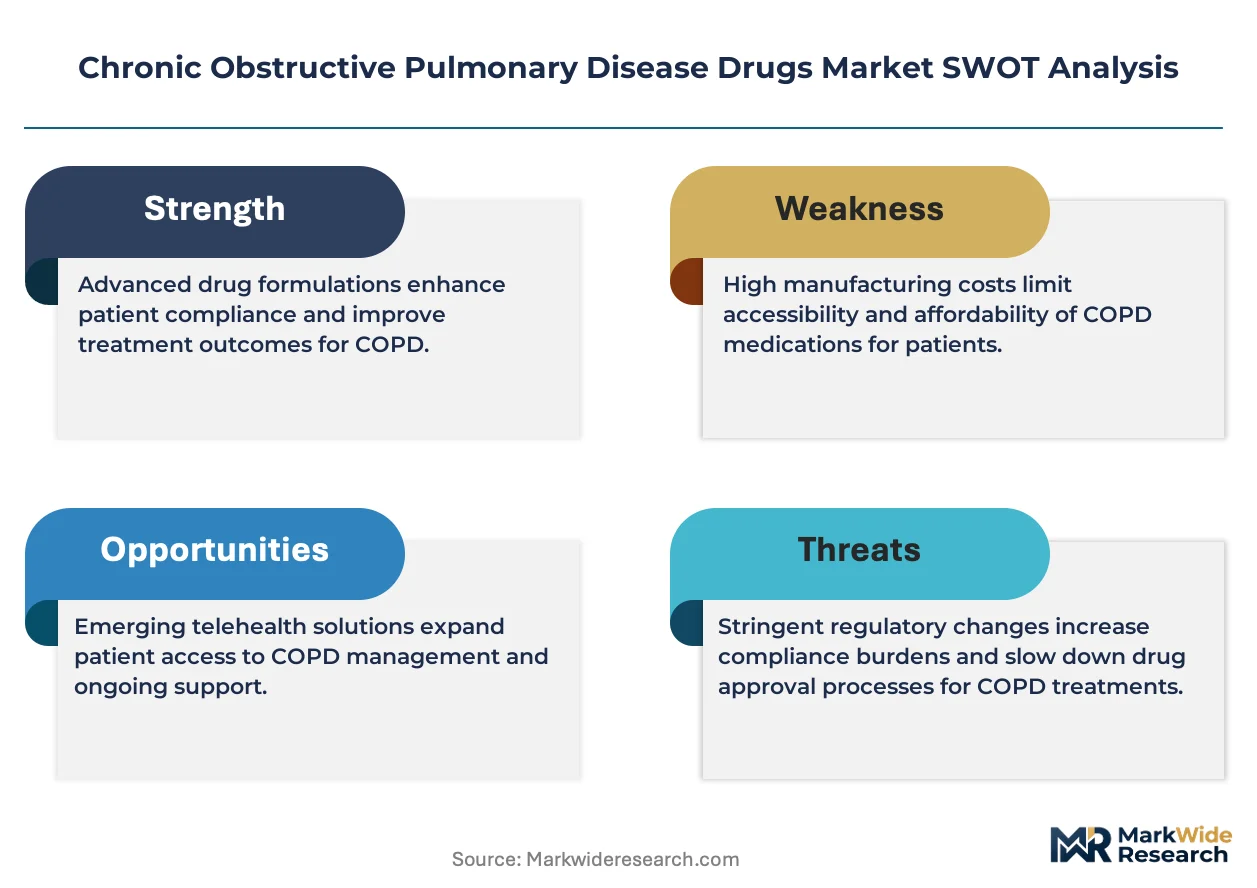
Hospital formulary committees are expanding access to combination inhalers as payers tighten prior authorization requirements, reshaping prescribing authority and access dynamics across developed markets. This structural shift elevates the influence of pharmacy benefit managers while compressing margins for single-agent therapies.
Growth Catalysts
- Aging demographics:Populations aged 65 and above in the United States, Germany, and Japan are expanding diagnostic pools and driving prescription volumes for maintenance therapies.
- EMA MDR acceleration:The European Medical Device Regulation is streamlining approval pathways for triple-therapy fixed-dose combinations, reducing time-to-market for device-drug products.
- Diagnostic expansion:Spirometry screening programs in primary care settings are identifying previously undiagnosed patients and converting them to pharmaceutical intervention.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for inhaled corticosteroids concentrates in Indian and Chinese facilities, exposing formulators to geopolitical and quality disruption risks.
- FDA bioequivalence barriers:Stringent standards for generic dry powder inhalers limit substitutability and protect originator pricing power, constraining payer cost-containment efforts.
- Device engineering complexity:Precision manufacturing requirements for breath-actuated mechanisms create technical moats that deter new entrants and sustain incumbent oligopoly structures.
Strategic Opportunities
- Rural underpenetration:Community health centers in the United States and comparable primary care networks in Germany offer expansion vectors for nebulized therapy delivery.
- Real-world evidence mandates:Payer consolidation is creating demand for post-market outcome databases that reward manufacturers with differentiated value demonstration capabilities.
- Digital inhaler convergence:Bluetooth-enabled adherence monitoring is integrating with electronic health records, opening subscription revenue models alongside pharmaceutical sales.
Industry Challenges
- Inhaler engineering talent scarcity:Cross-disciplinary expertise combining aerosol physics, mechanical design, and regulatory science remains concentrated among a narrow specialist cohort.
- Legacy system integration:Hospital pharmacy information systems require substantial reconfiguration to accommodate connected device data streams and prior authorization workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Obstructive Pulmonary Disease Drugs Market |
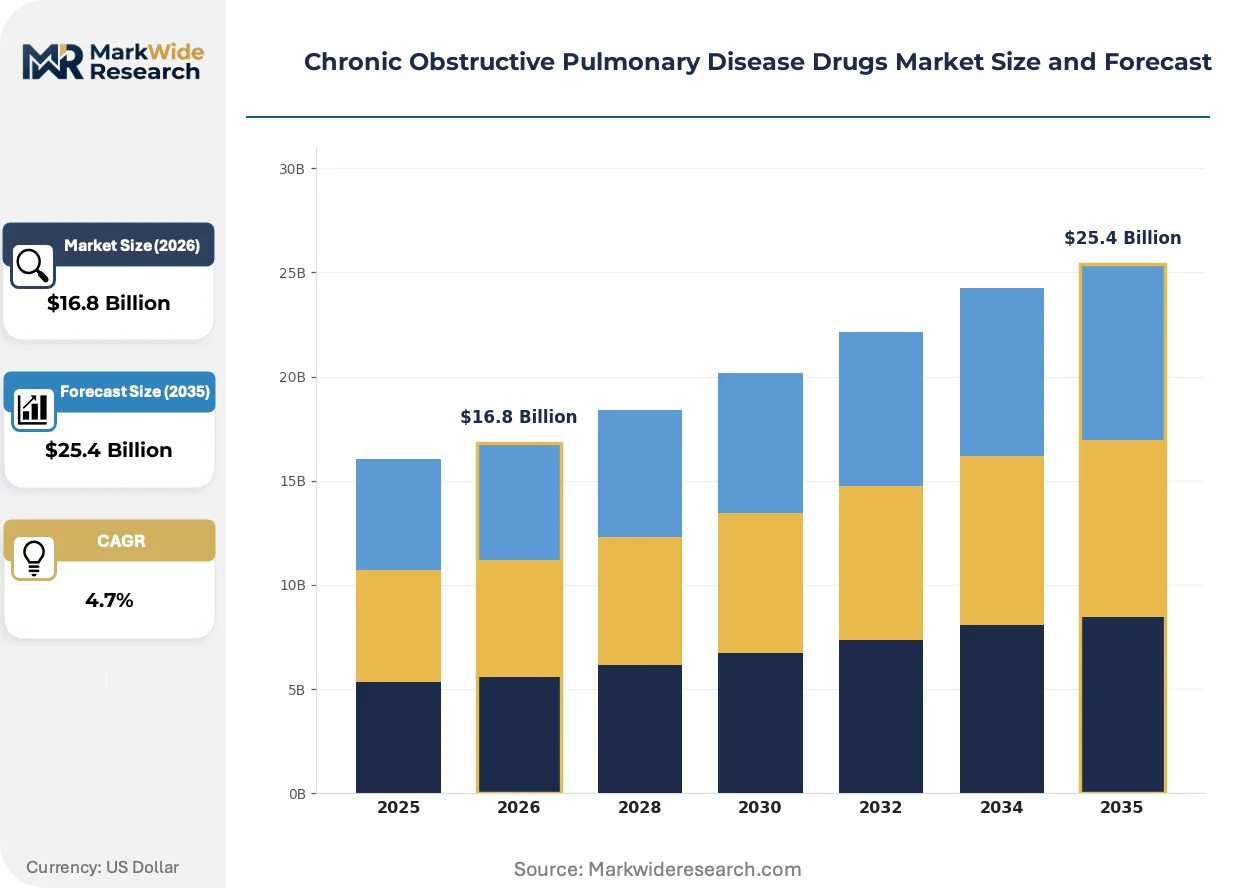
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $25.4 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bronchodilators, Corticosteroids, Phosphodiesterase-4 Inhibitors, Combination Drugs Therapy Area: Dyspnea Relief, Exacerbation Reduction, Inflammation Control, Mucus Clearance End User: Respiratory Clinics, Pulmonary Rehabilitation Centers, Specialized Hospitals, Home Care Providers Delivery Mode: Oral Tablets, Inhalers, Nebulizers, Injectable Formulations |
| Companies Covered | GlaxoSmithKline plc, AstraZeneca, Boehringer Ingelheim, Pfizer Inc., Novartis AG, Teva Pharmaceutical Industries Ltd, Sanofi, Chiesi Farmaceutici S.p.A., Viatris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Obstructive Pulmonary Disease Drugs Market Strategic Shifts & Innovations
Triple-therapy fixed-dose combinations are displacing sequential add-on prescribing, compressing treatment algorithms while simplifying patient adherence. This convergence of bronchodilator and anti-inflammatory mechanisms is redefining product development priorities across the respiratory portfolio.
Connected inhaler technology is expanding into severe disease management protocols, transmitting adherence data to pulmonology clinics in real time. Medicare Advantage plans in the United States are piloting these devices for high-utilization patient cohorts. The structural consequence is a shift from pharmaceutical-only revenue toward integrated care contracts that bundle hardware, software, and drug supply.
The FDA is maintaining elevated bioequivalence thresholds for complex generic inhalers, preserving originator market positions while delaying cost competition. This regulatory stance forces generic developers toward alternative device platforms rather than therapeutic equivalence pathways. The segment most affected is long-acting muscarinic antagonist combinations, where substitutability remains limited despite patent expirations.
Specialist channel consolidation is compressing the physician audience for respiratory therapies, concentrating influence among pulmonary and critical care group practices. Hospital-employed specialists in the United States and comparable integrated networks in Germany are standardizing on preferred formularies. This pattern is most visible in exacerbation-prevention protocols, where committee-driven purchasing overrides individual physician preference.
Chronic Obstructive Pulmonary Disease Drugs Market Segmentation
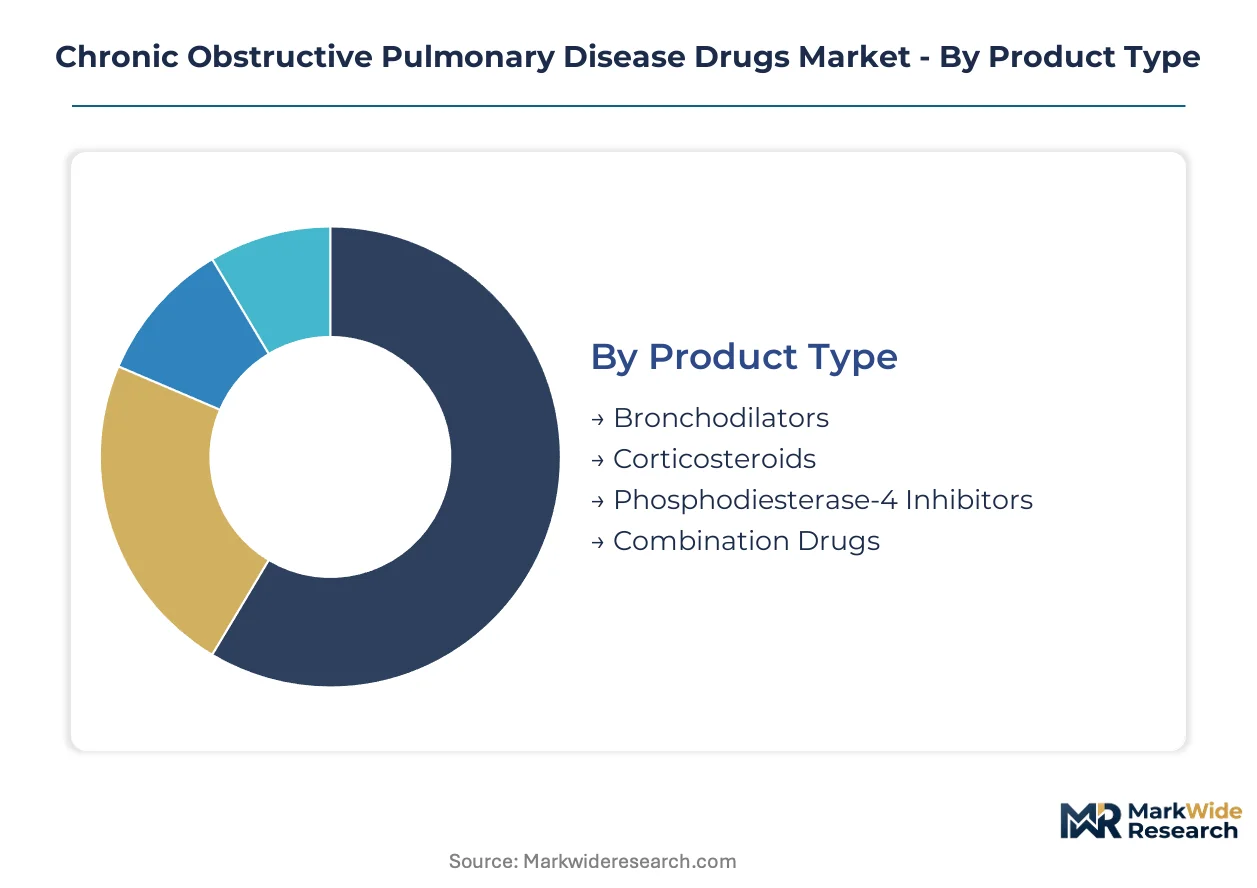
COPD drug segmentation reveals how prescribing protocols, reimbursement tiers, and device engineering capabilities fragment commercial opportunity. Manufacturers must align portfolio investments with where formulary committees concentrate influence and where patient adherence profiles favor specific delivery technologies.
Product Type:
Prescribing economics drive product-type selection, with formulary positioning and prior authorization burden shaping physician behavior.
- Bronchodilators:Long-acting beta-agonists and anticholinergics constitute the universal first-line intervention for persistent airflow limitation. Demand concentrates in Germany and Japan, where primary care spirometry expansion converts newly diagnosed patients to maintenance therapy protocols.
- Combination Drugs:Fixed-dose pairings of bronchodilators with corticosteroids simplify adherence through reduced inhaler count and unified dosing schedules. United States hospital formularies are accelerating access as Medicare Advantage plans tighten step-therapy requirements.
- Corticosteroids:Inhaled anti-inflammatory agents target eosinophilic inflammation patterns in frequent exacerbator phenotypes.
- Phosphodiesterase-4 Inhibitors:Oral roflumilast formulations address chronic bronchitis-dominant disease with systemic anti-inflammatory action.
Bronchodilators lead on scale; combination drugs lead on momentum.
Therapy Area:
Clinical outcome targets determine reimbursement tiering and real-world evidence investment priorities.
- Exacerbation Reduction:Hospitalization prevention commands premium pricing through avoided cost economics. United States pulmonology group practices prioritize these therapies as Medicare readmission penalties tighten.
- Dyspnea Relief:Symptom alleviation through bronchodilation remains the entry point for pharmaceutical intervention. German primary care networks emphasize functional capacity improvement as a quality metric.
- Inflammation Control:Biomarker-guided corticosteroid targeting addresses eosinophilic-driven disease progression.
- Mucus Clearance:Secretolytic agents serve chronic bronchitis phenotypes with productive cough dominance.
Exacerbation reduction leads on scale; dyspnea relief leads on momentum.
End User:
Site-of-care economics and patient acuity determine device selection and service bundling opportunities.
- Specialized Hospitals:Academic medical centers manage severe disease with triple-therapy initiation and exacerbation protocols. Japan's tertiary respiratory centers drive volume for nebulized delivery in acute settings.
- Home Care Providers:Long-term oxygen therapy and nebulizer services extend pharmaceutical reach beyond clinic walls. United States Medicare Advantage pilots are integrating connected inhaler monitoring for high-utilization cohorts.
- Respiratory Clinics:Outpatient pulmonology practices concentrate maintenance therapy prescribing authority.
- Pulmonary Rehabilitation Centers:Exercise-based programs incorporate bronchodilator optimization as part of functional recovery.
Specialized hospitals lead on scale; home care providers lead on momentum.
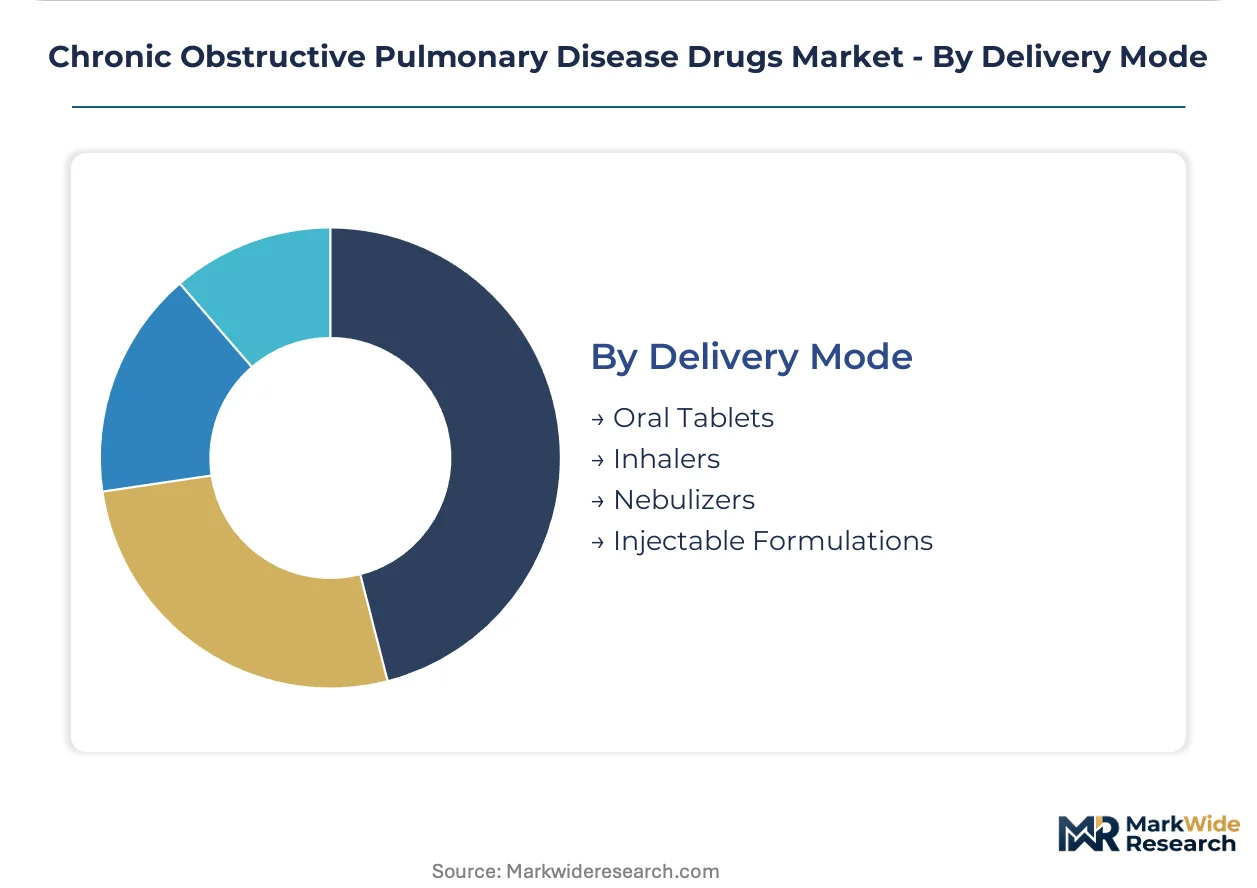
Delivery Mode:
Device engineering complexity and patient dexterity requirements segment manufacturing capability and market access pathways.
- Inhalers:Dry powder and metered-dose devices dominate maintenance therapy through portability and rapid onset. FDA bioequivalence standards protect originator positions while limiting generic substitution.
- Nebulizers:Compressor and mesh systems serve severe disease and institutional settings where breath coordination fails. German hospital pharmacy committees standardize on specific device brands for exacerbation protocols.
- Oral Tablets:Systemic agents bypass inhalation technique requirements for patients with cognitive or physical limitations.
- Injectable Formulations:Biologic delivery for eosinophilic phenotypes requires specialist administration and cold-chain infrastructure.
Inhalers lead on scale; nebulizers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The COPD drugs industry traces its commercial roots to post-war pharmaceutical manufacturing clusters in the United States and Germany, where respiratory therapy innovation first achieved industrial scale. Today prescription volumes concentrate where aging demographics intersect with established reimbursement infrastructure and specialist care networks.
United States
Medicare Advantage expansion and hospital readmission penalty programs drive demand for exacerbation-prevention therapies. The FDA maintains stringent bioequivalence standards for generic dry powder inhalers that protect originator pricing. Massachusetts and North Carolina host concentrated pulmonary specialist networks that standardize on preferred formularies.
Germany
Primary care spirometry screening programs convert undiagnosed patients to maintenance therapy at rates exceeding European peers. The EMA's Medical Device Regulation elevates documentation burdens for device-drug combinations entering European markets. Bavaria's medical technology corridor supplies precision-engineered inhaler components to global formulators.
Japan
PMDA clinical bridging requirements for foreign-originated respiratory products shape regional launch sequencing and partnership structures. Tertiary respiratory centers in Tokyo and Osaka manage severe disease with nebulized delivery protocols. METI industrial policy supports domestic inhaler manufacturing capacity.
United Kingdom
NICE technology appraisals concentrate prescribing authority on cost-effective combination therapies. The MHRA operates post-Brexit regulatory autonomy with continued EMA alignment on device-drug combination standards. The Cambridge-London corridor anchors respiratory clinical trial infrastructure.
India
Active pharmaceutical ingredient manufacturing for inhaled corticosteroids concentrates in Gujarat and Maharashtra, exposing formulators to quality disruption risks. CDSCO accelerated approval pathways target unmet respiratory disease burden. Domestic generic inhaler production scales for emerging market export.
Chronic Obstructive Pulmonary Disease Drugs Market Key Industry Players
The competitive structure tilts toward integrated respiratory specialists with device engineering capabilities. Originators with in-house inhaler platforms command pricing power through FDA bioequivalence barriers that limit generic substitution. Three archetypes dominate: biologics-focused exacerbation specialists, precision device engineers, and portfolio diversifiers with respiratory as one vertical. Consolidation concentrates among pulmonary specialist channel controllers and connected inhaler technology platforms.
Among UK-based pharmaceutical conglomerates, GlaxoSmithKline plc occupies a position exemplifying portfolio-scale respiratory commitment. AstraZeneca represents the biologics-specialist archetype with exacerbation-focused development priorities. Boehringer Ingelheim anchors the precision-engineering tier through deep inhaler platform capabilities. These three entities collectively illustrate how competitive advantage in this market derives from cross-disciplinary integration of aerosol science, clinical development, and regulatory navigation rather than therapeutic innovation alone.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| AstraZeneca |
| Boehringer Ingelheim |
| Pfizer Inc. |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd |
| Sanofi |
| Chiesi Farmaceutici S.p.A. |
| Viatris |
| Others |
Cost & Logistics Intelligence
Hospital formulary committee consolidation in the United States and Germany is forcing device-drug combination manufacturers toward bundled service contracts that wrap adherence monitoring, patient education, and outcomes guarantees into per-patient pricing, compressing margins on standalone pharmaceutical supply while rewarding integrated care platform investments.
Pricing Analysis
Bundled service contracts are displacing per-unit inhaler pricing across Medicare Advantage and statutory health insurance systems, with three-tier pricing structure across premium, standard, and economy levels stratifying by connected device capability and real-world evidence generation commitment. FDA bioequivalence barriers protect originator premium tiers from generic erosion, while price differentiation hinges on breath-actuated mechanism precision and electronic health record integration depth. Cost compression in economy-tier dry powder inhalers is intensifying because Indian and Chinese API suppliers are consolidating volume contracts. Hospital systems exhibit highest price sensitivity; specialized respiratory clinics with outcomes-based contracts show lowest.
Supply Chain Analysis
Active pharmaceutical ingredient manufacturing for inhaled corticosteroids draws from Indian, Chinese, and limited United States specialty chemical facilities, with micronized particle engineering and breath-actuated valve mechanisms resting on German and Japanese precision component suppliers. Raw material dependencies span lactose carriers, hydrofluoroalkane propellants, and stainless steel aerosol canisters. Single-source vulnerability concentrates in mesh nebulizer piezoelectric elements sourced from East Asian electronics manufacturers. Distribution runs through hospital pharmacy committees and pulmonary specialist group purchasing organizations rather than retail pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play: EMA MDR compliance costs in Germany run substantially higher than CDSCO accelerated pathway investments in India, creating divergent capital efficiency profiles for device-drug combination development.
For Market Incumbents: Anchor formulary positioning through backward integration into connected inhaler hardware manufacturing, neutralizing emerging entrant threats from digital health platforms. Deepen clinical trial infrastructure in Japan to satisfy PMDA bridging requirements ahead of regional launch sequencing. Prioritize pharmacy benefit manager contracting scale to defend against step-therapy displacement.
For New Entrants and Emerging Players: Rural community health centers in the United States present the most penetrable buyer archetype, with nebulized therapy delivery gaps and limited pulmonologist density creating white-space opportunity. Target German primary care spirometry networks for diagnostic-expansion partnerships. Pursue white-label connected device supply to established pharmaceutical portfolios as the fastest go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with precision aerosol engineering specialists possessing cross-disciplinary talent combining mechanical design, regulatory science, and pharmaceutical formulation expertise. Long-term viability centers on platform consolidation across the respiratory portfolio over the mid-term horizon. Watch FDA generic bioequivalence guidance revisions as the critical inflection signal for originator pricing power erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Connected Inhaler Platform Development | Bluetooth-enabled adherence monitoring integrates with Medicare Advantage pilot programs for high-utilization cohorts. |
| EMA MDR Compliance Investment | Device-drug combination documentation capabilities determine European market access timelines for triple-therapy entrants. |
| Real-World Evidence Database Construction | Post-market outcome repositories satisfy payer consolidation demands for differentiated value demonstration in Germany. |
| API Supply Diversification | Geographic distribution of inhaled corticosteroid manufacturing reduces exposure to Indian and Chinese quality disruption risks. |
| Pulmonary Specialist Channel Partnership | Hospital-employed physician network standardization in Massachusetts and North Carolina concentrates formulary influence. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up prescription volume modeling and top-down pharmaceutical revenue triangulation anchored segment-level estimates.
Segment-weighting approaches distributed analytical emphasis across bronchodilator, combination drug, and corticosteroid product types, with therapy area segmentation modeling exacerbation reduction, dyspnea relief, and inflammation control priorities throughout the forecast period. CAGRs derived from patient population epidemiology, diagnostic expansion rates, and formulary access trajectory analysis. Inhaler engineering talent scarcity and API supply concentration served as industry-specific forecast sensitivity inputs.
Underlying measurement precision varies by segment; combination drug and connected device forecasts carry tighter precision than oral tablet and nebulizer categories due to more visible pipeline and regulatory milestones. Forecasts reflect documented assumptions regarding payer consolidation velocity, MDR implementation timing, and generic bioequivalence pathway evolution. Material deviation in FDA guidance, EMA device-drug combination enforcement, or Indian API facility inspection outcomes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Musculoskeletal Disorders Drugs Market
Pharmaceuticals
Global Exocrine Pancreatic Insufficiency (EPI) Market
Pharmaceuticals
US Intravenous Immunoglobulin Market
Pharmaceuticals
Omeprazole and Antihistamine Market
Pharmaceuticals
Oral & Topical Anaesthetics Market
Pharmaceuticals
Hepatitis Therapeutics Market
Pharmaceuticals
Biguanides Market
Pharmaceuticals
Acne Therapeutics Market
Pharmaceuticals
Emergency Contraceptive Pills Market
Pharmaceuticals
Global Anthrax Vaccine Market
Pharmaceuticals
Fusion Inhibitors Market
Pharmaceuticals
Global Meningitis Vaccine Market
Pharmaceuticals
Global Orphan Drugs Market
Pharmaceuticals
Multiple System Atrophy (MSA) Therapeutics Market
Pharmaceuticals
Indapamide Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market