
 Constipation Laxative Market | 2026-2036
Constipation Laxative Market Size, Share, and Industry Trends Forecast 2026-2036
Constipation Laxative Market Analysis
The pool of qualified gastroenterology formulation chemists is collapsing across North American contract manufacturing organizations, forcing branded players to internalize capabilities or accept longer development timelines. Johnson & Johnson sustains consumer loyalty through decades of pediatric positioning and pharmacy shelf dominance. Sanofi S.A. leverages its European regulatory heritage to navigate complex OTC-to-prescription switches in multiple jurisdictions. Takeda Pharmaceutical Company Ltd anchors its portfolio in prescription-grade osmotic agents that command tighter physician relationships.
Constipation laxatives comprise pharmacological agents that increase stool water content, accelerate intestinal transit, or soften fecal consistency through osmotic, stimulant, bulk-forming, or surfactant mechanisms, with active ingredients ranging from polyethylene glycol 3350 to senna glycosides and docusate sodium. Their primary commercial purpose is to restore bowel function in acute or chronic constipation across ambulatory, institutional, and self-care settings. Bulk-forming agents occupy the largest volume share due to their favorable safety profile and suitability for long-term geriatric use, while osmotic laxatives represent the fastest-growing category as prescription-grade polyethylene glycol formulations expand into direct-to-consumer channels. Stimulant laxatives face structural margin compression from regulatory scrutiny of anthraquinone derivatives and growing clinician preference for gentler alternatives.
The FDA's OTC monograph reform process and the EMA's pharmacovigilance requirements for bowel preparation agents jointly elevate compliance costs and reshape product labeling across major markets. BIS certification in India and CDSCO stability-testing mandates further fragment market access for multinational suppliers seeking to serve Asia-Pacific manufacturing hubs. Stakeholders must monitor how evolving gut microbiome research influences regulatory classification of osmotic agents and whether prescription-to-OTC reclassification waves alter competitive dynamics in pharmacy channels.
Market Dynamics
The FDA's tightening OTC monograph requirements for stimulant laxatives is forcing manufacturers to reformulate around osmotic and bulk-forming mechanisms, compressing margins for legacy anthraquinone suppliers while elevating polyethylene glycol as the clinical standard.
Growth Catalysts
- Home Care Demand Surge:Geriatric patients in the United States are transitioning from institutional to self-administered bowel management, expanding pharmacy channel volumes for direct-to-consumer osmotic agents.
- REACH Compliance Advantage:European manufacturers leveraging pre-registered polymer safety dossiers are capturing shelf space as competitors face re-authorization bottlenecks for surfactant excipients.
- Microbiome Research Momentum:Gut microbiome studies linking chronic constipation to dysbiosis are driving physician preference toward osmotic agents perceived as microbiome-neutral versus stimulant alternatives.
Market Restraints
- API Supply Concentration:Polyethylene glycol 3350 production clusters in Texas and Louisiana petrochemical corridors, exposing formulations to hurricane-season disruption and force majeure risk.
- CDSCO Stability Mandates:India's 36-month accelerated stability testing requirements for imported laxatives are extending registration timelines and freezing market entry for mid-tier European suppliers.
- Plant-Based Substitution:Psyllium husk and flaxseed fiber supplements are capturing preventive health consumers seeking food-grade alternatives to pharmacological intervention.
Strategic Opportunities
- Prescription-to-OTC Switches:EMA's streamlined reclassification pathway for established osmotic agents is enabling branded players to migrate hospital-formulated polyethylene glycol into pharmacy channels without full new-drug applications.
- Subscription Pharmacy Models:Direct-to-consumer platforms in Germany are bundling bulk-forming laxatives with dietitian consultations, capturing recurring revenue from chronic constipation patients.
- Pediatric Formulation Gaps:Palatable, low-volume liquid osmotic formulations for children remain underdeveloped relative to adult markets, presenting white space for taste-masked polymer solutions.
Industry Challenges
- Gastroenterology Chemist Scarcity:North American contract manufacturing organizations face collapsing pools of formulation specialists capable of optimizing polymer hydration kinetics for extended-release profiles.
- Dual-Label Compliance Burden:Simultaneous FDA monograph adherence and EMA pharmacovigilance reporting for bowel preparation agents is fragmentating packaging workflows and extending artwork approval cycles.
- Legacy System Integration:ERP migrations for track-and-trace compliance with the Drug Supply Chain Security Act are disrupting batch record management at mid-sized manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Constipation Laxative Market |
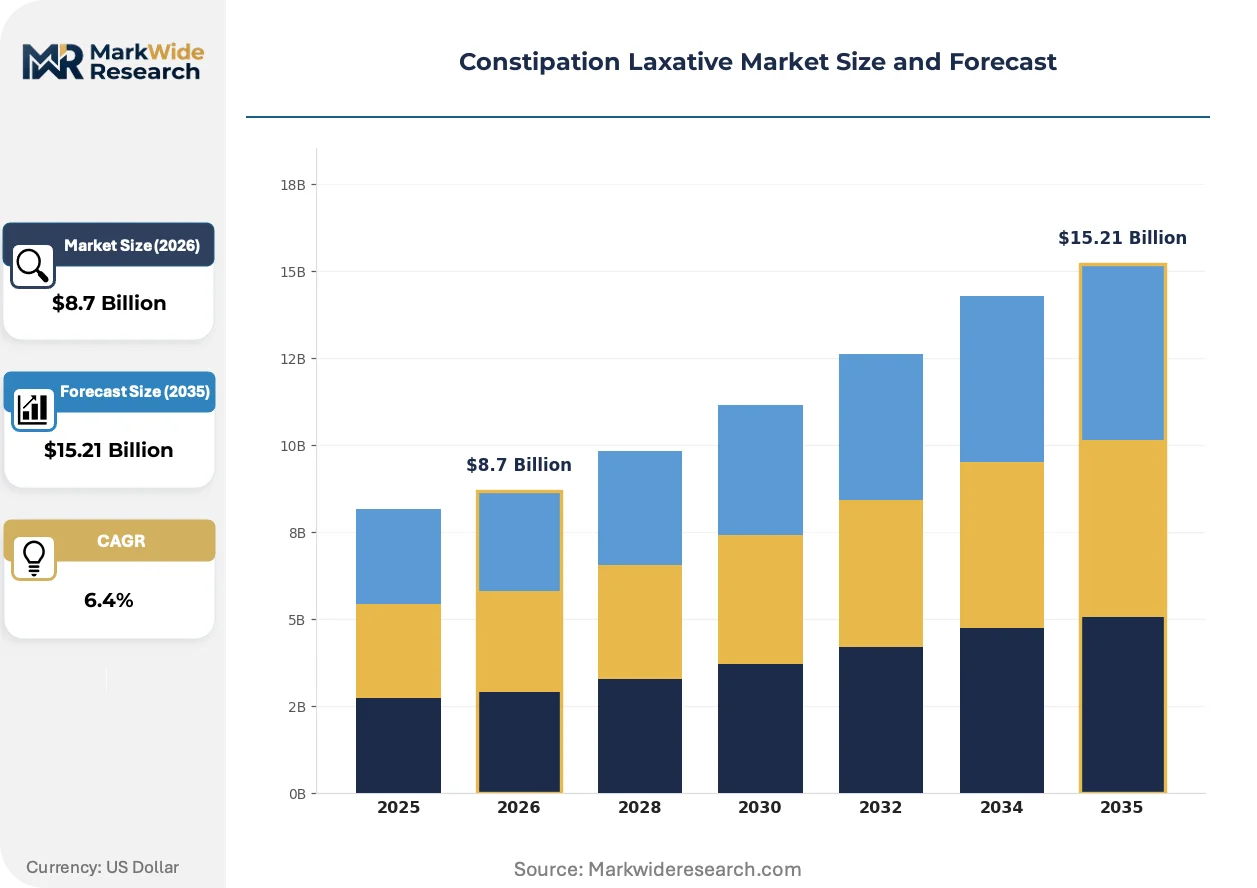
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk-forming Agents, Stool Softeners, Stimulant Laxatives, Osmotic Laxatives End User: Hospitals, Clinics, Home Care, Pharmacies Form: Liquid, Tablet, Powder, Suppository Administration Route: Oral, Rectal, Intravenous, Subcutaneous |
| Companies Covered | Sanofi S.A., Johnson & Johnson, Takeda Pharmaceutical Company Ltd, GlaxoSmithKline Plc, AbbVie Inc, Ironwood Pharmaceuticals Inc, Bausch Health Companies Inc, Procter & Gamble Co, AstraZeneca Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Constipation Laxative Market Emerging Trajectories
Formulation science and distribution architecture are converging to reshape how constipation therapies reach patients, with polymer engineering and regulatory science driving competitive differentiation ahead of traditional marketing investment.
Low-dose polyethylene glycol powder sachets are replacing large-volume liquid bottles in European pharmacy channels. German and French retailers are prioritizing shelf-stable, travel-format packaging for ambulatory geriatric buyers. This format shift is miniaturizing supply chain footprints and enabling direct-mail subscription models that bypass wholesale distribution markups.
The FDA's ongoing OTC monograph reform for stimulant laxatives is mandating revised labeling for senna glycoside products, requiring cardiovascular warnings and duration limits. Reformulation costs are compressing private-label margins while favoring established osmotic brands with compliant grandfathered status. United States pharmacy buyers are responding by reallocating planogram space toward polyethylene glycol 3350 SKUs.
Hospital discharge protocols are embedding bowel management into transitional care bundles, with Medicare Advantage plans in the United States reimbursing 90-day laxative supplies for post-acute patients. Home health agencies are replacing ad-hoc retail purchases with centralized procurement from specialty distributors. California and Florida health systems are piloting this model most aggressively, capturing pharmacy spend previously fragmented across retail channels.
Constipation Laxative Market Segmentation
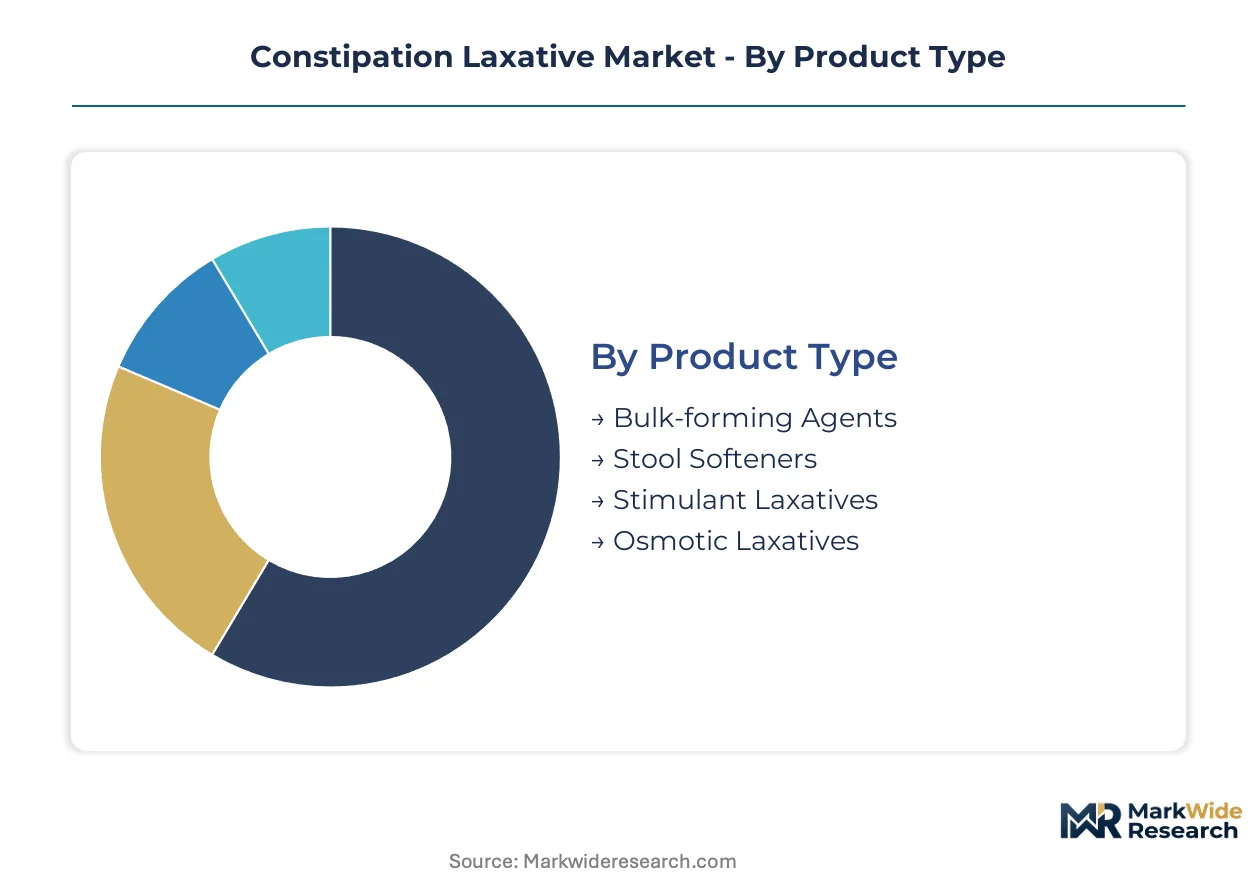
Constipation laxatives fragment across four distinct classification axes, each carrying divergent regulatory burdens and channel economics. Product type determines reimbursement eligibility and OTC monograph compliance. End user and form factor dictate packaging specifications and shelf-life requirements.
Product Type:
FDA monograph reform and EMA pharmacovigilance create asymmetric compliance costs across mechanism classes, privileging grandfathered osmotic formulations while forcing stimulant repositioning.
- Bulk-forming Agents:Psyllium husk and methylcellulose formulations absorb intestinal water to increase stool mass and promote peristalsis through mechanical distension. Geriatric home care demand in the United States concentrates here due to favorable long-term safety profiles and Medicare Advantage bundle reimbursement. Established volume favors bulk-forming agents; emerging adoption favors osmotic laxatives.
- Osmotic Laxatives:Polyethylene glycol 3350 and lactulose draw water into the intestinal lumen through osmotic gradient formation. Prescription-to-OTC switches in Germany and France are accelerating pharmacy channel penetration for sachet-format polyethylene glycol powders.
- Stimulant Laxatives:Senna glycosides and bisacodyl trigger colonic contraction through direct mucosal irritation. FDA cardiovascular warning mandates are compressing planogram space and forcing label reformulation.
- Stool Softeners:Docusate sodium reduces surface tension to permit water penetration into fecal matter. Pediatric positioning in United States retail pharmacies sustains residual demand despite inferior efficacy data.
Established volume favors bulk-forming agents; emerging adoption favors osmotic laxatives.
End User:
Procurement authority and reimbursement pathways diverge sharply across care settings, with institutional buyers demanding unit-dose compliance and retail channels prioritizing direct-to-consumer convenience.
- Home Care:Self-administered bowel management dominates volume as aging populations transition from skilled nursing facilities. United States Medicare reimbursement patterns favor 90-day supply dispensing through specialty pharmacy networks.
- Pharmacies:Retail and mail-order channels capture recurring chronic constipation patients through subscription models in Germany and automated refill programs in United States chains. Established volume favors pharmacies; emerging adoption favors home care.
- Hospitals:Inpatient bowel preparation for surgical and endoscopic procedures demands rapid-onset osmotic agents with electrolyte balance specifications.
- Clinics:Ambulatory gastroenterology practices prescribe prescription-grade polyethylene glycol for refractory cases requiring prior authorization navigation.
Procurement concentration tilts toward pharmacy and home care as hospital discharge protocols externalize ongoing bowel management.
Form:
Patient adherence and supply chain resilience trade off across physical formats, with liquid formulations carrying higher freight costs and powder sachets enabling direct-mail distribution.
- Powder:Single-dose polyethylene glycol sachets dominate European pharmacy shelves due to shelf stability and travel-format convenience. German retailers are prioritizing compact footprint packaging for ambulatory geriatric buyers.
- Liquid:Large-volume bottles retain United States institutional preference for precise dose titration in acute care settings. Established volume favors liquid; emerging adoption favors powder.
- Tablet:Solid oral dosage forms suit stimulant laxatives requiring precise anthraquinone content control under tightening FDA monograph specifications.
- Suppository:Rectal administration formats serve acute fecal impaction and pre-procedural bowel evacuation where oral route contraindications exist.
Format innovation concentrates in powder miniaturization as supply chains optimize for last-mile direct-to-consumer fulfillment.
Administration Route:
Clinical indication severity and patient functional status determine route selection, with oral formulations commanding economies of scale and rectal administration serving niche acute indications.
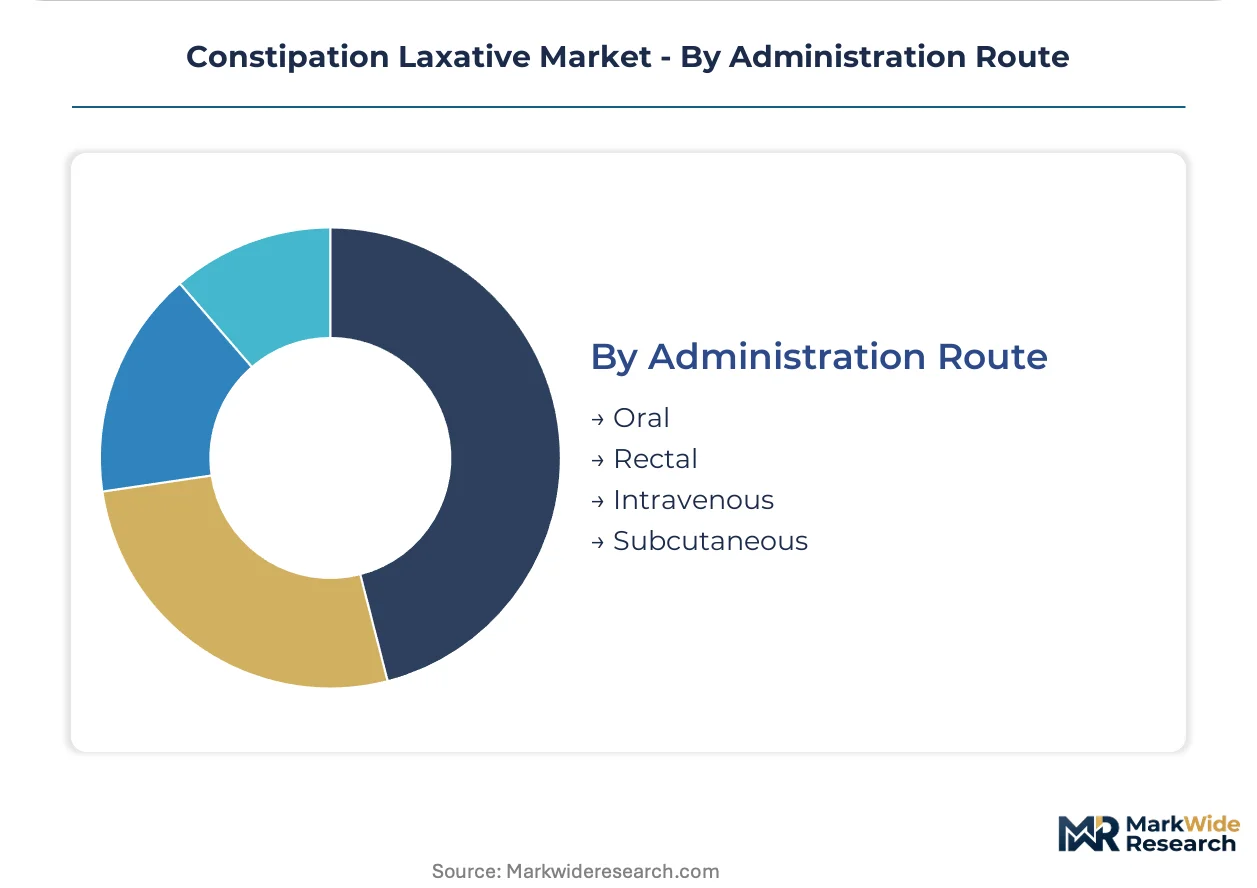
- Oral:Swallowed tablets, powders, and liquids constitute the overwhelming volume share across all care settings. Polyethylene glycol 3350 oral solutions anchor prescription and OTC portfolios for Takeda and established generic suppliers.
- Rectal:Suppository and enema formats address fecal impaction, pre-operative preparation, and patients with impaired swallowing function. Established volume favors oral; emerging adoption favors rectal.
- Intravenous:Hospital-only formulations for severe ileus and post-operative paralytic conditions represent minimal commercial volume.
- Subcutaneous:Investigational and specialty applications for neurogenic bowel dysfunction in spinal cord injury populations.
Route diversification remains constrained by formulation stability and patient acceptance barriers outside oral and rectal categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA monograph reform in the United States is reshaping formulation standards across developed markets, while regulatory divergence between the FDA and EMA creates asymmetric compliance burdens for multinational suppliers.
United States
Medicare Advantage plans in California and Florida are piloting 90-day laxative supply bundles for post-acute patients transitioning to home care. The FDA's cardiovascular warning mandates for senna glycoside products are compressing retail planogram space for stimulant laxatives. Houston and New Orleans petrochemical corridors concentrate polyethylene glycol 3350 API production, exposing formulations to Gulf Coast weather disruption.
Germany
EMA's streamlined prescription-to-OTC reclassification pathway is enabling pharmacy channel migration for established osmotic agents. REACH pre-registered polymer safety dossiers grant domestic manufacturers shelf-space advantages as competitors face surfactant excipient re-authorization bottlenecks. Frankfurt and Munich retailers are prioritizing compact powder sachet formats for ambulatory geriatric buyers.
India
CDSCO's 36-month accelerated stability testing requirements for imported laxatives are extending registration timelines and freezing market entry for mid-tier European suppliers. Domestic bulk-forming psyllium husk production in Gujarat and Rajasthan is capturing preventive health consumers seeking food-grade alternatives. Mumbai specialty distributors are consolidating procurement for hospital discharge protocols.
Japan
PMDA's pharmacovigilance requirements for bowel preparation agents are elevating compliance costs for osmotic laxative labeling. Aging demographics in Tokyo and Osaka are driving self-administered bowel management demand in pharmacy channels. Kanto region manufacturers are developing palatable low-volume liquid formulations for pediatric gaps.
United Kingdom
NHS England's transitional care bundles are embedding bowel management into post-discharge protocols, concentrating procurement through specialty pharmacy networks. London and Manchester health systems are externalizing ongoing bowel management from hospital settings. UK retailers are responding to FDA-aligned label pressure by reallocating space toward osmotic brands.
Constipation Laxative Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding physician relationships through prescription-grade portfolios while the lower tier competes on pharmacy shelf presence and pediatric positioning. The market structure rewards regulatory heritage and grandfathered monograph status over pure marketing spend. Three archetypes dominate: legacy consumer health conglomerates with decades of pharmacy dominance, European-origin pharmaceutical specialists leveraging OTC-to-prescription switch expertise, and prescription-focused players anchoring hospital discharge protocols. Competitive moves concentrate on portfolio diversification into microbiome-neutral formulations and strategic partnerships with home health agencies for centralized procurement.
Within the integrated leader tier, Johnson & Johnson and Sanofi S.A. exemplify divergent geographic anchoring strategies, with the former occupying decades of U.S. pediatric positioning and pharmacy shelf dominance while the latter leverages European regulatory heritage across multiple jurisdictions. Takeda Pharmaceutical Company Ltd sits within the prescription-specialist archetype, anchoring tighter physician relationships through hospital-formulated osmotic agents. These three players collectively represent the spectrum of competitive positioning: consumer loyalty, regulatory navigation, and clinical institutional penetration.
| Leading Market Players |
|---|
| Sanofi S.A. |
| Johnson & Johnson |
| Takeda Pharmaceutical Company Ltd |
| GlaxoSmithKline Plc |
| AbbVie Inc |
| Ironwood Pharmaceuticals Inc |
| Bausch Health Companies Inc |
| Procter & Gamble Co |
| AstraZeneca Plc |
| Others |
Supply Flow & Price Mechanics
Polyethylene glycol 3350's displacement of anthraquinone-based stimulant laxatives simultaneously shifts API sourcing toward Gulf Coast petrochemical corridors and compresses margin structures for legacy formulation suppliers facing reformulation costs.
Pricing Analysis
Long-term offtake contracts between hospital systems and specialty distributors anchor pricing stability for prescription-grade osmotic agents, while spot-market powder sachets in European pharmacy channels exhibit greater volatility. Price differentiation rests on FDA monograph compliance status and REACH-registered polymer dossiers, with grandfathered osmotic formulations commanding premiums over reformulating stimulant suppliers. Cost compression in private-label stimulant tiers is intensifying because cardiovascular warning mandates force label redesign and artwork cycles. Medicare Advantage bundles demonstrate lowest price sensitivity; retail private-label buyers exhibit highest.
Supply Chain Analysis
Port congestion on Houston-Galveston trade lanes elevates inbound logistics costs for polyethylene glycol 3350 shipments to East Coast formulation facilities. API production clusters in Texas and Louisiana, with secondary sourcing from German polymer specialists. Raw material dependencies include ethylene oxide feedstock, purified water for hydration kinetics, and pharmaceutical-grade packaging films. Single-source vulnerability concentrates in Gulf Coast hurricane exposure. Distribution runs through specialty pharmacy networks for institutional buyers and direct-mail platforms for subscription-based home care patients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against plant-based fiber substitutes capturing preventive health consumers seeking food-grade alternatives to pharmacological intervention.
For Market Incumbents: Secure grandfathered FDA monograph status for osmotic formulations to maintain pricing power as stimulant laxatives face regulatory compression. Deepen backward integration into polyethylene glycol 3350 polymer engineering to control hydration kinetics specifications and reduce Gulf Coast supply disruption exposure. For New Entrants and Emerging Players: EMA streamlined prescription-to-OTC reclassification serves as the fastest certification pathway for hospital-formulated osmotic agents seeking pharmacy channel migration. Target pediatric formulation gaps with palatable low-volume liquid solutions, leveraging taste-masked polymer technology as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturing organizations facing gastroenterology chemist scarcity and extended development timelines. Five-to-ten year viability favors players with captive prescription-to-OTC switch capabilities and home health agency procurement relationships. Watch FDA microbiome research classification shifts as the signal for osmotic agent regulatory resegmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Prescription-to-OTC Switch Execution | EMA streamlined reclassification enables pharmacy channel expansion without full new-drug applications. |
| Pediatric Formulation Development | Palatable low-volume liquid osmotic solutions address underserved children versus saturated adult markets. |
| Home Health Agency Partnership | Medicare Advantage 90-day supply bundles capture pharmacy spend from fragmented retail channels. |
| Backward Integration into Polymer Engineering | In-house polyethylene glycol 3350 hydration kinetics control reduces Gulf Coast supply disruption risk. |
| Subscription Pharmacy Platform Launch | German direct-to-consumer models bundle bulk-forming laxatives with dietitian consultations for recurring revenue. |
Methodological Framework
Cross-validation between primary interviews with formulation chemists, regulatory affairs specialists, hospital procurement managers, and pharmacy benefit directors anchors the qualitative findings against secondary validation from FDA OTC monograph filings, EMA reclassification submissions, ClinicalTrials.gov bowel preparation studies, and CMS Medicare reimbursement databases. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing triangulate demand estimates.
Sensitivity analysis around regulatory timeline scenarios and API supply disruption probabilities shapes the analytical framework across the projection horizon. Segmentation dimensions include mechanism class, end-user care setting, physical form factor, and administration route, with patient age demographics as an industry-specific overlay. CAGRs derive from polynomial trend fitting to historical prescription and OTC volume trajectories, incorporating microbiome research influence coefficients and Medicare Advantage bundle penetration assumptions.
Decision-makers should treat outputs as directional under stable FDA monograph reform timelines and intact Gulf Coast petrochemical infrastructure; material deviation would warrant model refresh. Specific risk factors include EMA pharmacovigilance reclassification waves, CDSCO stability mandate enforcement, and plant-based fiber substitute adoption acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Global Anti-Fungal Drugs Market
Pharmaceuticals
Global Muscle Relaxant Drugs Market
Pharmaceuticals
Bevacizumab Market
Pharmaceuticals
Global Nizatidine Market
Pharmaceuticals
Nicorandil Market
Pharmaceuticals
Hyoscine Market
Pharmaceuticals
Roflumilast API Market
Pharmaceuticals
Global Zika Vaccines Market
Pharmaceuticals
Flunarizine Hydrochloride Market
Pharmaceuticals
Topical Corticosteroids Market
Pharmaceuticals
Urinary Retention Drugs Market
Pharmaceuticals
Global Cholera Vaccines Market
Pharmaceuticals
Global Corticosteroids Market
Pharmaceuticals
Global Anti-Suicide Drugs Market
Pharmaceuticals
Oral Solid Dosage Contract Manufacturing Market