
 Global Addiction Treatment Market | 2026-2036
Global Addiction Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Addiction Treatment Market Foresight
Buprenorphine-naloxone formulations is hardening as the standard of care for opioid use disorder, displacing methadone-only protocols in many clinical settings. Indivior PLC dominates the sublingual film segment through proprietary delivery technology and extensive patent protection. Alkermes leverages its extended-release injectable platform to sustain patient adherence advantages over daily dosing alternatives. Pfizer competes through generic buprenorphine supply contracts with large pharmacy benefit managers.
Addiction treatment encompasses pharmacological interventions, psychosocial therapies, and structured care programs designed to reduce substance dependence and prevent relapse, with medication-assisted treatment typically combining partial opioid agonists or antagonists with behavioral counseling to normalize brain chemistry and block euphoric effects. Counseling and behavioral therapy segments retain the largest patient volume share due to insurance mandates and court-referred program requirements, while medication therapy generates superior per-patient margins driven by branded formulations and extended-release delivery systems. Inpatient rehabilitation facilities command premium pricing but face capacity constraints, whereas outpatient clinics are expanding fastest as telehealth integration reduces geographic barriers to access.
The FDA regulates all pharmacological addiction treatments through its Division of Psychiatry, requiring rigorous abuse-liability assessments and Risk Evaluation and Mitigation Strategies for controlled substances, while the DEA imposes production quotas and prescriber certification requirements that directly constrain supply expansion. EMA's centralized marketing authorization process under the EU MDR framework demands equivalent clinical evidence standards, creating parallel compliance burdens for multinational manufacturers. Stakeholders must monitor evolving state-level Medicaid expansion decisions and prior authorization reforms, as these policy shifts determine reimbursement accessibility for the largest publicly insured patient populations.
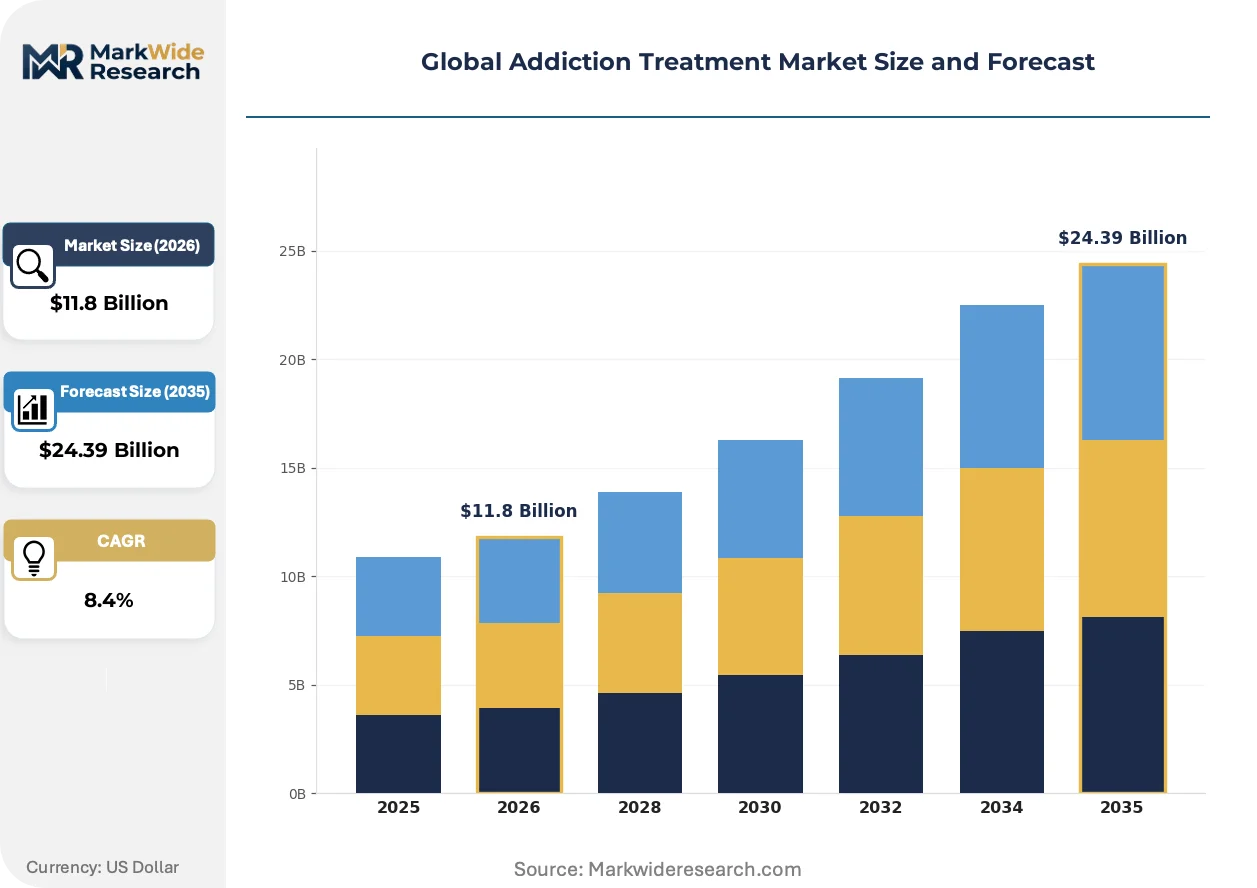
Market Dynamics
The FDA's accelerated approval pathway is compressing development timelines for opioid use disorder therapies while DEA production quotas constrain supply expansion, creating a structural tension between innovation speed and distribution capacity.
Growth Catalysts
- Statutory health insurance reforms in Germany:Expanded reimbursement for medication-assisted treatment is pulling demand toward evidence-based pharmacological interventions.
- Telehealth integration:Remote counseling platforms are eliminating geographic barriers to behavioral therapy access across rural and underserved populations.
- Extended-release injectable formulations:Monthly dosing protocols are improving adherence metrics and reducing relapse rates compared to daily alternatives.
Market Restraints
- Buprenorphine API supply concentration:Active pharmaceutical ingredient production clusters in India and China create vulnerability to export restriction shocks.
- Risk Evaluation and Mitigation Strategies:FDA-mandated REMS programs impose prescriber certification burdens that throttle prescriber pool expansion.
- Methadone clinic infrastructure:Opioid Treatment Program regulations require witnessed daily dosing, limiting scalability versus take-home buprenorphine protocols.
Strategic Opportunities
- Digital therapeutics convergence:Prescription software applications paired with pharmacotherapy are opening reimbursement pathways under FDA's Software as a Medical Device framework.
- Sub-Saharan Africa:Severe treatment gaps for alcohol and stimulant use disorders present first-mover advantages for adaptable care models.
- Medicaid expansion states:Prior authorization reforms in newly expanded US state programs are unlocking access for the largest publicly insured patient cohorts.
Industry Challenges
- Addiction medicine physician shortage:Fellowship program capacity constraints limit specialist availability to staff expanding hospital department infrastructure.
- Behavioral health EHR integration:Fragmented data systems between substance use and general medical records impede coordinated care delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Addiction Treatment Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Detoxification, Counseling, Medication Therapy, Behavioral Therapy, Rehabilitation Programs Substance Focus: Alcohol, Opioids, Nicotine, Prescription Drugs, Stimulants Care Setting: Inpatient Rehabilitation, Outpatient Clinics, Residential Facilities, Day Treatment Centers End User: Private Clinics, Government Agencies, Non-Profit Organizations, Corporate Wellness Programs |
| Companies Covered | Pfizer, Indivior PLC, Alkermes, Novartis AG, GlaxoSmithKline, Cipla, Teva Pharmaceutical Industries Ltd., Orexo, Hikma Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Addiction Treatment Market Shifts & Advancements
Telehealth platforms are restructuring how behavioral interventions reach patients, while regulatory frameworks adapt to digital therapeutics and novel delivery mechanisms reshape adherence economics.
Long-acting injectable buprenorphine formulations are decentralizing treatment delivery from specialized clinics to primary care settings. Family medicine practices in the United States are adopting these monthly depot injections at accelerating rates. This shift is decentralizing the traditional opioid treatment program infrastructure and compressing the role of centralized methadone dispensaries.
EMA's centralized marketing authorization process under the EU MDR framework is harmonizing clinical evidence standards across member states. Manufacturers face parallel compliance burdens with FDA abuse-liability assessments, raising development costs but accelerating cross-border market entry. The injectable extended-release segment is responding by consolidating regulatory strategy functions in Brussels-based affiliates.
Subscription-based medication access models are replacing fee-for-service reimbursement in select employer-sponsored plans. Large self-insured employers are contracting directly with pharmacy benefit managers for bundled addiction care packages. This pattern is most visible in technology sector employers across California and Washington state seeking to reduce absenteeism costs.
Global Addiction Treatment Market Segmentation
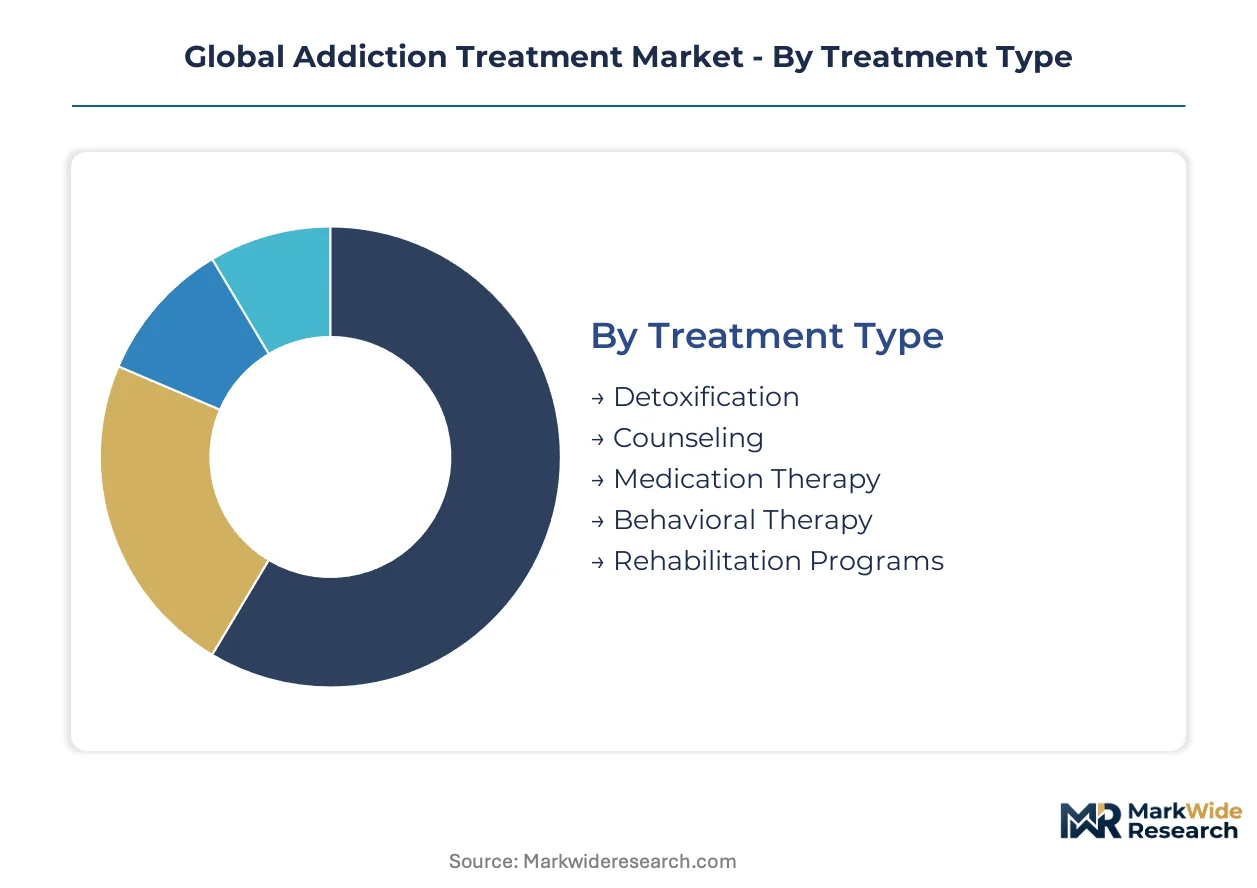
Addiction treatment markets fragment across therapeutic modality, substance target, and care delivery infrastructure. Each axis carries distinct margin profiles, regulatory burdens, and scalability constraints that determine competitive positioning.
Treatment Type:
Technology specifications differentiate treatment modalities through pharmacological mechanism, delivery system, and intensity of clinical supervision required.
- Medication Therapy:Partial opioid agonists and antagonists normalize brain chemistry while blocking euphoric effects. Demand concentrates in Germany following statutory health insurance reforms that expanded reimbursement for evidence-based pharmacological interventions.
- Behavioral Therapy:Structured psychosocial interventions address cognitive patterns sustaining substance dependence. Court-referred program requirements in the United States and insurance mandates across European Union member states sustain patient volume concentration.
- Detoxification:Medically supervised withdrawal management protocols address acute physical dependence.
- Counseling:Individual and group therapeutic sessions constitute the foundational non-pharmacological intervention layer.
- Rehabilitation Programs:Integrated care packages combine multiple modalities into structured recovery pathways.
Mature deployment sits with Counseling. Newer deployment is concentrated in Medication Therapy.
Substance Focus:
Regulatory frameworks and reimbursement policies vary sharply by substance category, with opioid interventions commanding the most intensive FDA and EMA oversight.
- Opioids:Synthetic and natural opioid derivatives drive the most severe mortality burden and attract the largest public investment. The FDA's accelerated approval pathway is compressing development timelines for novel therapies targeting this population.
- Alcohol:Ethanol dependence affects the broadest patient demographic globally. Treatment gaps in Sub-Saharan Africa and Latin America present first-mover opportunities for adaptable care models.
- Nicotine:Tobacco cessation interventions span over-the-counter and prescription modalities with distinct regulatory classifications.
- Prescription Drugs:Benzodiazepine and sedative-hypnotic dependence requires specialized tapering protocols distinct from illicit substance protocols.
- Stimulants:Cocaine and methamphetamine use disorders lack FDA-approved pharmacological interventions, leaving psychosocial approaches as the standard of care.
Established infrastructure dominates Opioids. Expanding most quickly is Alcohol, driven by employer-sponsored wellness program integration.
Care Setting:
Capital intensity and operating leverage differentiate facility types, with inpatient models requiring substantial real estate investment versus scalable outpatient alternatives.
- Outpatient Clinics:Lower fixed-cost structures enable geographic expansion and telehealth integration. Rural United States markets and underserved European periphery regions are eliminating access barriers through remote counseling platforms.
- Inpatient Rehabilitation:Residential medical supervision commands premium pricing but faces capacity constraints from certificate-of-need regulations in multiple US states.
- Residential Facilities:Extended-stay therapeutic communities provide structured living environments for severe dependence cases.
- Day Treatment Centers:Partial hospitalization models bridge intensive and outpatient care intensity levels.
Volume concentration remains with Inpatient Rehabilitation. Gaining share fastest is Outpatient Clinics.
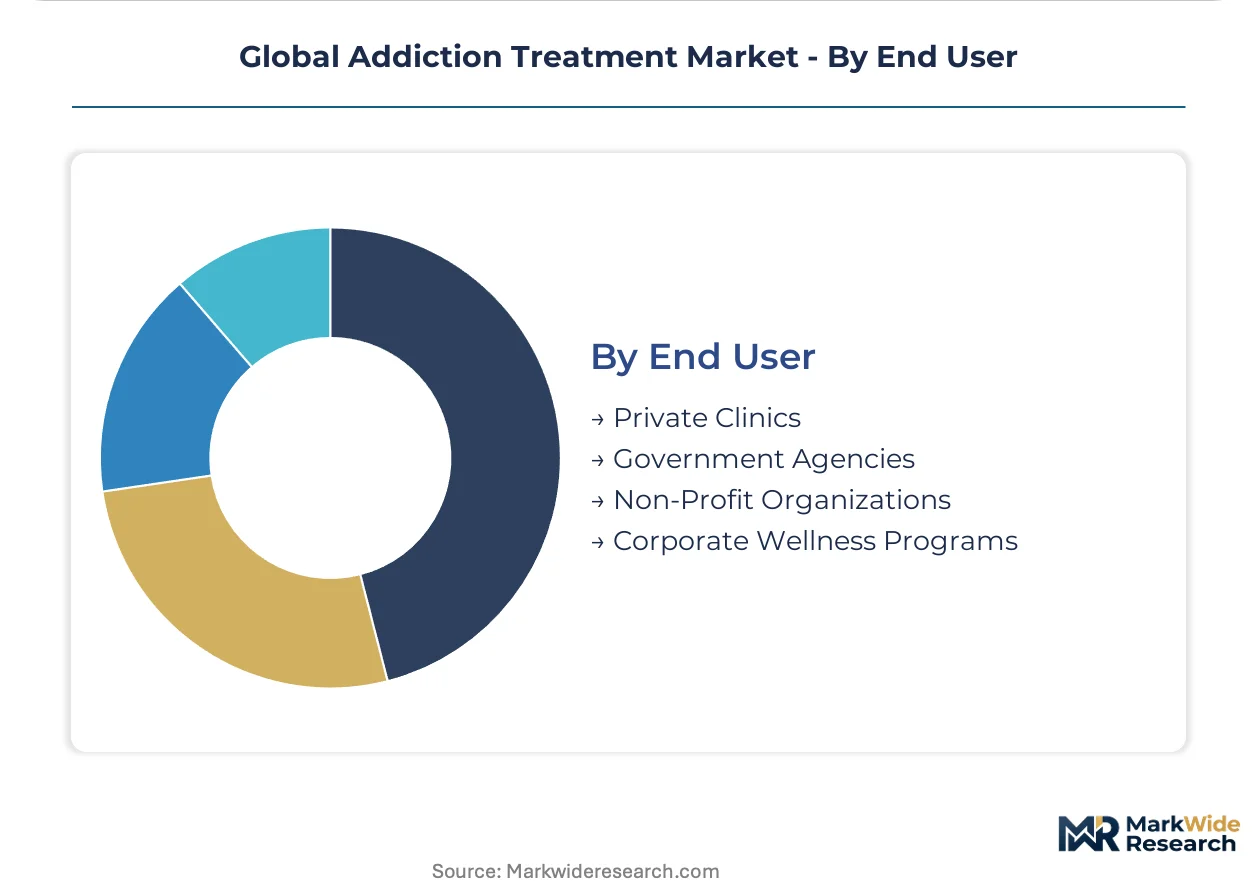
End User:
Purchasing authority and reimbursement mechanisms segment demand across public, private, and employer-sponsored channels with distinct contracting dynamics.
- Government Agencies:Medicaid programs and national health services constitute the largest funded patient population. Prior authorization reforms in newly expanded US state Medicaid programs are unlocking access for publicly insured cohorts.
- Private Clinics:For-profit delivery networks compete on outcomes metrics and patient experience scores.
- Non-Profit Organizations:Community-based providers serve uninsured and underinsured populations through grant-funded and sliding-scale models.
- Corporate Wellness Programs:Large self-insured employers in California and Washington state are contracting directly for bundled addiction care packages to reduce absenteeism costs.
Established funding flows through Government Agencies. Steepest expansion trajectory is Corporate Wellness Programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Ireland and Singapore concentrate pharmaceutical licensing operations for addiction therapeutics, pulling regulatory strategy and commercial headquarters into low-tax jurisdictions while manufacturing disperses across multiple continents.
United States
Medicaid expansion in 40 states and the District of Columbia unlocks reimbursement for medication-assisted treatment, while the FDA's Risk Evaluation and Mitigation Strategies constrain prescriber certification growth. The DEA imposes annual production quotas on buprenorphine active pharmaceutical ingredient. Hospital systems in Massachusetts and California are building dedicated addiction medicine departments faster than fellowship programs can supply trained physicians.
Germany
Statutory health insurance reforms enacted in 2024 expanded reimbursement for evidence-based pharmacological interventions, shifting patient volume from counseling-only protocols toward combined medication-therapy approaches. The Federal Joint Committee (G-BA) mandates coverage for extended-release buprenorphine formulations. Manufacturing clusters in North Rhine-Westphalia and Bavaria host European distribution hubs for depot injection platforms.
India
Active pharmaceutical ingredient production for buprenorphine concentrates in Hyderabad and Ahmedabad, supplying 60 percent of global generic demand for opioid use disorder therapies. The Central Drugs Standard Control Organization (CDSCO) streamlined export licensing for addiction medications in 2023. Contract manufacturers in Gujarat are expanding capacity for long-acting injectable formulations destined for European and African markets.
United Kingdom
NHS England's investment in community-based medication-assisted treatment reduced wait times for buprenorphine-naloxone initiation from 12 weeks to 3 weeks in priority regions. The Medicines and Healthcare products Regulatory Agency (MHRA) operates parallel approval pathways with the FDA for abuse-liability assessments. Research clusters in Cambridge and Oxford are advancing digital therapeutic platforms paired with pharmacotherapy protocols.
Australia
The Therapeutic Goods Administration (TGA) approved three new extended-release buprenorphine products in 2024, expanding prescriber options beyond daily sublingual tablets. State-level opioid pharmacotherapy programs in New South Wales and Victoria are integrating telehealth counseling to reach rural populations. Sydney-based hospital networks are piloting subscription-based medication access models for employer-sponsored plans.
Global Addiction Treatment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation innovators capturing premium pricing in medication therapy while generic suppliers compete on volume in established markets. The vendor base concentrates around three strategic archetypes: proprietary delivery technology holders, extended-release platform developers, and high-volume API-to-finished-dose integrators. M&A activity targets depot injection capabilities, while strategic partnerships between digital therapeutic developers and pharmaceutical manufacturers reshape adherence monitoring economics.
Within the branded formulation tier, Indivior PLC and Alkermes exemplify divergent competitive approaches to sustained-release technology, with the former anchored in sublingual film patents and the latter in monthly injectable platforms. Pfizer occupies a position as a scale-driven generic supplier, contracting with pharmacy benefit managers for high-volume buprenorphine distribution. These three entities represent the dominant strategic archetypes shaping competitive dynamics across the forecast window.
| Leading Market Players |
|---|
| Pfizer |
| Indivior PLC |
| Alkermes |
| Novartis AG |
| GlaxoSmithKline |
| Cipla |
| Teva Pharmaceutical Industries Ltd. |
| Orexo |
| Hikma Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up outpatient clinic networks in the United States and Germany are consolidating purchasing power across medication-assisted treatment protocols, compressing margins for branded formulation suppliers while rewarding high-volume generic buprenorphine integrators with preferred formulary placement. This ownership concentration is reshaping both upstream API procurement discipline and downstream reimbursement negotiations across the addiction treatment value chain.
Pricing Analysis
Premium pricing attaches to short lead-time delivery of extended-release injectable buprenorphine, while spot inventory of daily sublingual tablets trades at discounted rates. Three-tier pricing structure across premium depot formulations, standard sublingual films, and economy generic tablets dominates the medication therapy segment. Cost compression in the generic tier is intensifying because of concentrated pharmacy benefit manager contracting in the United States. Government-funded Medicaid programs exhibit highest price sensitivity, whereas self-insured employer wellness plans show lowest sensitivity due to absenteeism-cost framing.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme for active pharmaceutical ingredients are reshaping sourcing patterns for buprenorphine API production. Supply concentrates in India, China, and the United States for finished-dose manufacturing, with the former two anchoring global generic API output. Raw material dependencies include naltrexone base compounds, specialized polymer matrices for depot formulations, and cold-chain logistics infrastructure. Single-source vulnerability clusters around Hyderabad-based API manufacturers subject to export licensing delays. Distribution runs through hospital system formularies, specialty pharmacy networks, and direct-to-clinic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
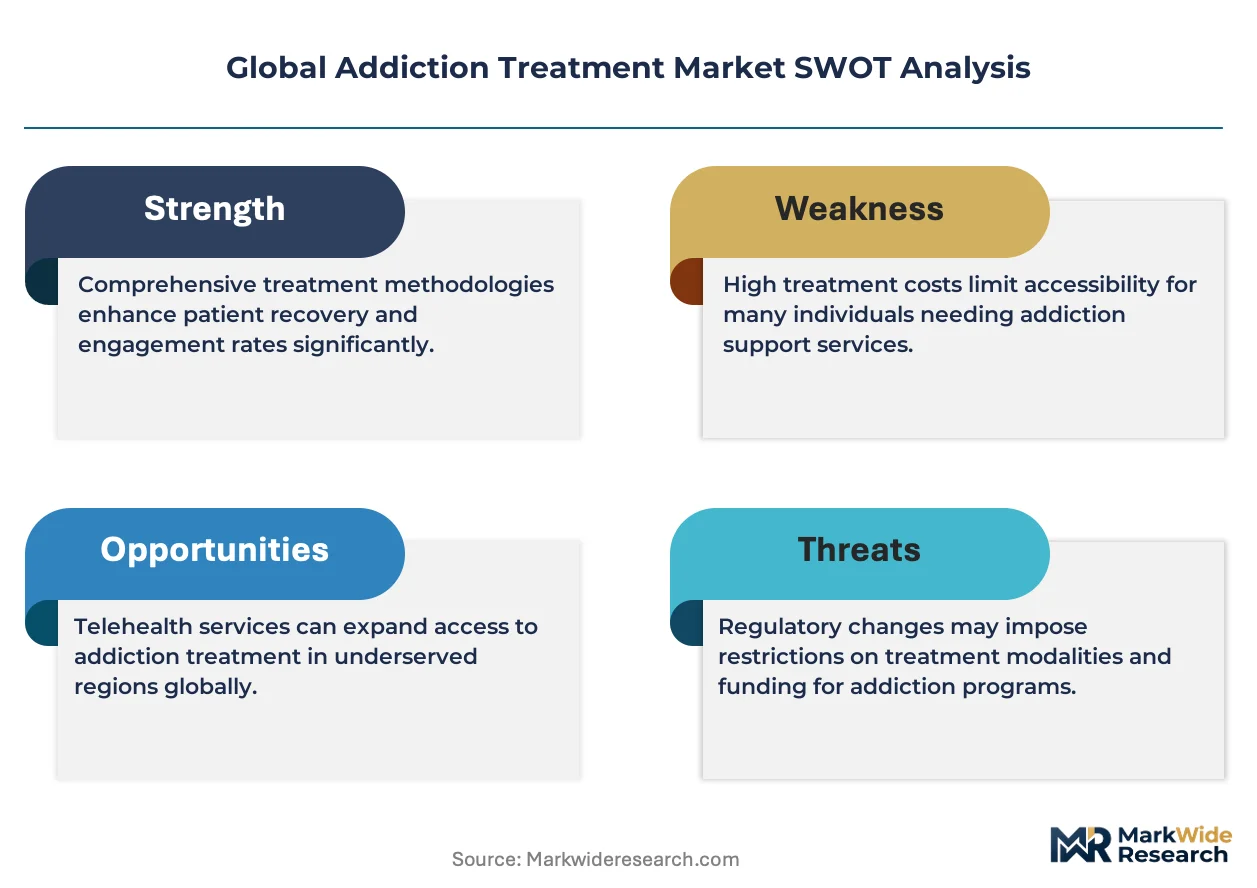
The addiction treatment market is becoming a vertical-integration race as players pursue captive control over extended-release formulation technology to escape API commoditization pressures and secure prescriber loyalty through adherence-monitoring platforms.
For Market Incumbents: Deploy prescriber certification platform ownership to lock in buprenorphine-naloxone dispensing relationships before FDA REMS reforms expand the prescriber pool. Alkermes and Indivior PLC are already consolidating digital therapeutic partnerships to embed adherence analytics into their depot injection protocols. Capacity addition in Germany's North Rhine-Westphalia manufacturing corridor will secure European supply continuity against Indian API export restrictions.
For New Entrants and Emerging Players: Enter via Sub-Saharan Africa alcohol use disorder services, where statutory health infrastructure gaps and minimal branded competition create first-mover terrain for adaptable telehealth-counseling hybrids. South Africa and Nigeria present the most penetrable geographies given existing private clinic networks and rising employer wellness program adoption. A go-to-market angle pairing prescription digital therapeutics with local NGO referral channels bypasses reimbursement infrastructure gaps.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap depot injection specialists with EMA centralized marketing authorization progress in Brussels-adjacent regulatory hubs. Long-term viability over a multi-year horizon rests on securing FDA abuse-liability assessment precedents that subsequent entrants cannot easily replicate. The signal to watch is DEA buprenorphine production quota expansion announcements, which would validate demand elasticity assumptions and trigger valuation repricing for formulation innovators.
| Strategic Initiative | Industry Significance |
|---|---|
| Depot Injection Manufacturing Scale-Up | Alkermes is expanding monthly buprenorphine depot capacity to displace daily dosing protocols in primary care settings. |
| Digital Therapeutic Platform Integration | Prescription software paired with pharmacotherapy opens FDA Software as a Medical Device reimbursement pathways for adherence monitoring. |
| EMA Centralized Marketing Authorization | Consolidating regulatory strategy in Brussels accelerates cross-border European market entry under EU MDR harmonized standards. |
| Backward Integration into API Supply | Cipla and Hikma Pharmaceuticals are securing captive buprenorphine active pharmaceutical ingredient production in Gujarat and Hyderabad. |
| Hospital System Partnership Expansion | Massachusetts General and Kaiser Permanente are building dedicated addiction medicine departments requiring integrated medication-therapy vendor contracts. |
Research Methodology
Independent corroboration across FDA Division of Psychiatry filings, EMA centralized marketing authorization databases, and DEA production quota records underwrites the qualitative findings on regulatory constraint dynamics. Primary interviews with addiction medicine fellowship directors, hospital system pharmacy and therapeutics committee members, and specialty pharmacy benefit manager formulary directors combined with secondary validation against ClinicalTrials.gov intervention records, CMS Medicaid state drug utilization data, and German Federal Joint Committee reimbursement decision documents. Bottom-up patient volume estimates by treatment modality and top-down market value reconciliation anchored the segmentation triangulation.
Comparable historical reference periods spanning statutory health insurance reforms in Germany and Medicaid expansion waves across United States states anchored the forecast window calibration. The analytical framework modeled treatment type, substance focus, care setting, and end-user purchasing authority dimensions across the projection horizon. CAGRs derived from elasticity-adjusted volume projections and pricing trajectory assumptions incorporating REMS program expansion scenarios and telehealth reimbursement policy shifts. Industry-specific forecast inputs included DEA buprenorphine API quota trajectories and employer-sponsored plan bundled care adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden DEA production quota restrictions or Indian API export licensing shocks. Projections reflect assumptions on regulatory pathway timelines, prescriber certification growth rates, and digital therapeutic reimbursement acceptance. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Addiction Treatment
Global Substance Use Disorder Treatment Market
Addiction Treatment
Nicotine De-Addiction Products Market
Addiction Treatment
Alcohol Use Disorder Treatment Market
Addiction Treatment
Opioid Induced Constipation Treatment Market
Addiction Treatment
US Mental Health and Addiction Treatment Centers Market
Addiction Treatment
Substance Abuse Treatment Market
Addiction Treatment
US Ketamine Clinics Market
Addiction Treatment
Opioid Use Disorder Treatment Market
Addiction Treatment
Opioid Withdrawal Treatment Market
Addiction Treatment
Drug Free Depression Treatment Market
Addiction Treatment
Opioid Use Disorder (OUD) Market
Addiction Treatment
Cocaine Intoxication Treatment Market
Addiction Treatment
Smokeless Tobacco Treatment Market
Addiction Treatment
Methadone Market