
 Global Substance Use Disorder Treatment Market | 2026-2036
Global Substance Use Disorder Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Substance Use Disorder Treatment Market Foresight
Subscription-based medication management is restructuring how treatment providers monetize ongoing care. Ria Health leverages telehealth infrastructure to deliver alcohol use disorder programs directly to consumers, bypassing traditional facility requirements. BayMark Health Services sustains geographic dominance through its network of opioid treatment programs across multiple states. Confidant Health differentiates via employer-sponsored virtual coaching that integrates behavioral health with primary care workflows.
Substance use disorder treatment encompasses clinical interventions combining pharmacological agents, psychosocial therapies, and care coordination to reduce dependency and prevent relapse. Medication-assisted therapy employs FDA-approved partial agonists and antagonists that block euphoric effects while mitigating withdrawal severity. Behavioral therapy commands the largest share of treatment modality revenue due to mandated coverage under the US Mental Health Parity and Addiction Equity Act. Telehealth providers represent the fastest-expanding service provider type, capitalizing on DEA flexibilities for controlled substance prescribing via remote platforms. Outpatient clinics maintain mature margin pools through recurring reimbursement for intensive outpatient programs.
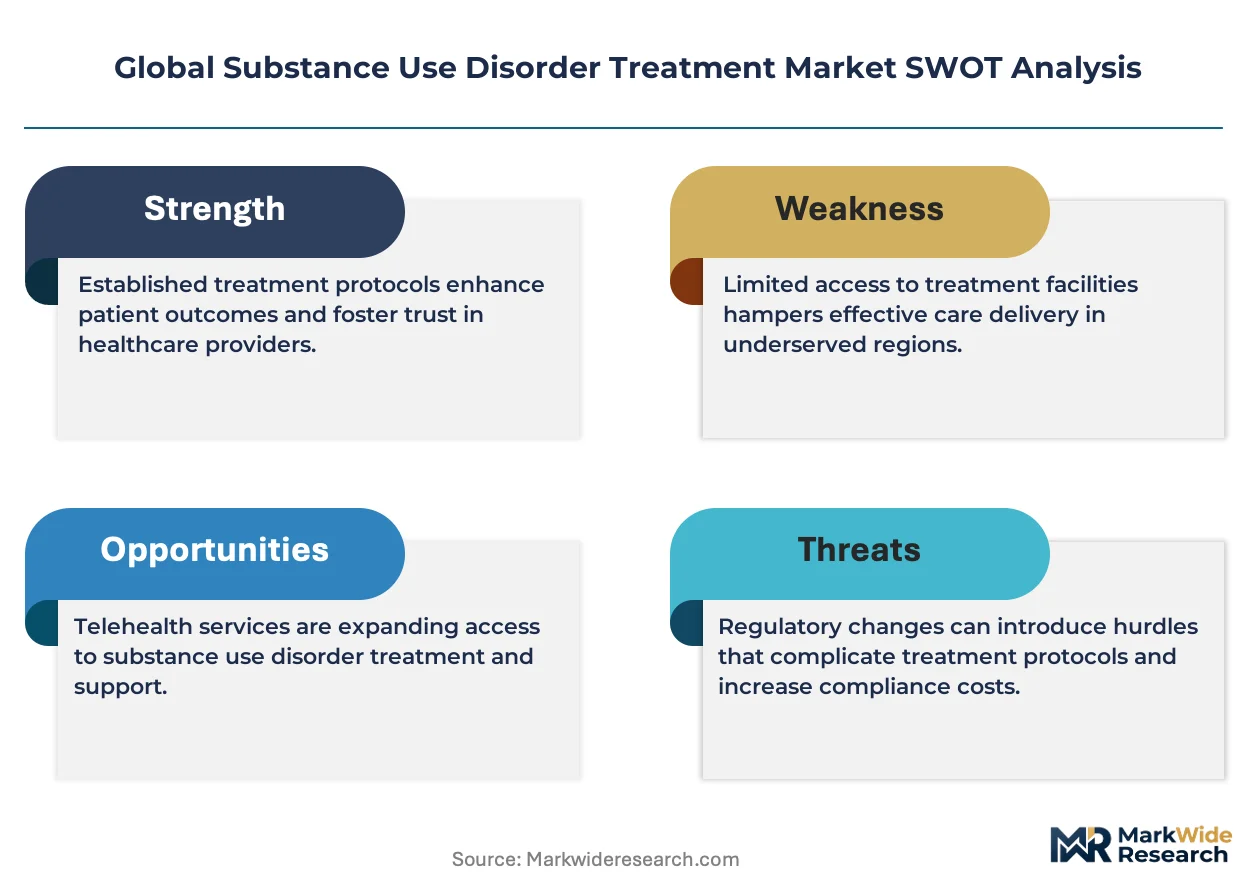
FDA, DEA, and SAMHSA collectively govern product approval, controlled substance scheduling, and program certification standards that determine market access. The FDA's breakthrough device pathway for digital therapeutics is accelerating clearance timelines for app-based interventions, while SAMHSA's accreditation requirements constrain facility expansion. Stakeholders must monitor evolving state-level licensing reciprocity agreements that could either amplify or fragment telehealth service delivery across jurisdictions.
Market Dynamics
Telehealth infrastructure expansion is restructuring patient access pathways, compressing geographic barriers between specialized providers and underserved populations while forcing traditional outpatient clinics to compete on convenience metrics they cannot match.
Growth Catalysts
- Medicaid Expansion:US federal parity mandates under the Mental Health Parity and Addiction Equity Act obligate commercial insurers to cover substance use disorder services at parity with medical benefits, eliminating prior authorization barriers that previously blocked treatment entry.
- DEA Flexibilities:Controlled substance prescribing via remote platforms allows buprenorphine providers to reach rural counties lacking brick-and-mortar opioid treatment programs, extending medication-assisted therapy to populations previously excluded by travel distance.
- Digital Therapeutics:FDA breakthrough device pathway acceleration is compressing clearance timelines for app-based interventions, enabling software-only treatments to secure reimbursement codes previously reserved for in-person clinical encounters.
Market Restraints
- Workforce Concentration:Addiction medicine specialists cluster in urban academic medical centers, leaving rural counties with ratios below one provider per 100,000 residents and forcing reliance on telehealth substitutes with limited physical examination capability.
- Reimbursement Fragmentation:State Medicaid programs apply divergent prior authorization requirements for extended-release naltrexone, creating administrative friction that delays treatment initiation and increases no-show rates for induction appointments.
- Facility Certification:SAMHSA accreditation standards for opioid treatment programs impose capital-intensive physical plant requirements that constrain entry in markets where real estate costs exceed clinical revenue potential.
Strategic Opportunities
- Employer Channel:Self-insured corporations in the United States are contracting directly with virtual coaching platforms to reduce absenteeism costs, bypassing health plan intermediaries and capturing medical cost savings through integrated behavioral-primary care models.
- India Market Entry:India's National Mental Health Programme expansion creates reimbursement infrastructure for substance use services previously delivered through informal networks, opening regulated revenue streams for standardized outpatient protocols.
- Digital-Pharmacology Convergence:Prescription digital therapeutics paired with medication-assisted therapy are securing bundled reimbursement codes, enabling outcome-based contracts that tie provider payment to verified abstinence metrics rather than service volume.
Industry Challenges
- Data Interoperability:Electronic health record fragmentation between telehealth platforms and traditional health systems prevents care coordination, forcing manual reconciliation of controlled substance prescribing histories across state prescription monitoring databases.
- Credentialing Velocity:Interstate licensing reciprocity agreements remain incomplete, requiring providers to maintain separate licenses in each state where patients reside and delaying service expansion into adjacent markets by 6-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Substance Use Disorder Treatment Market |
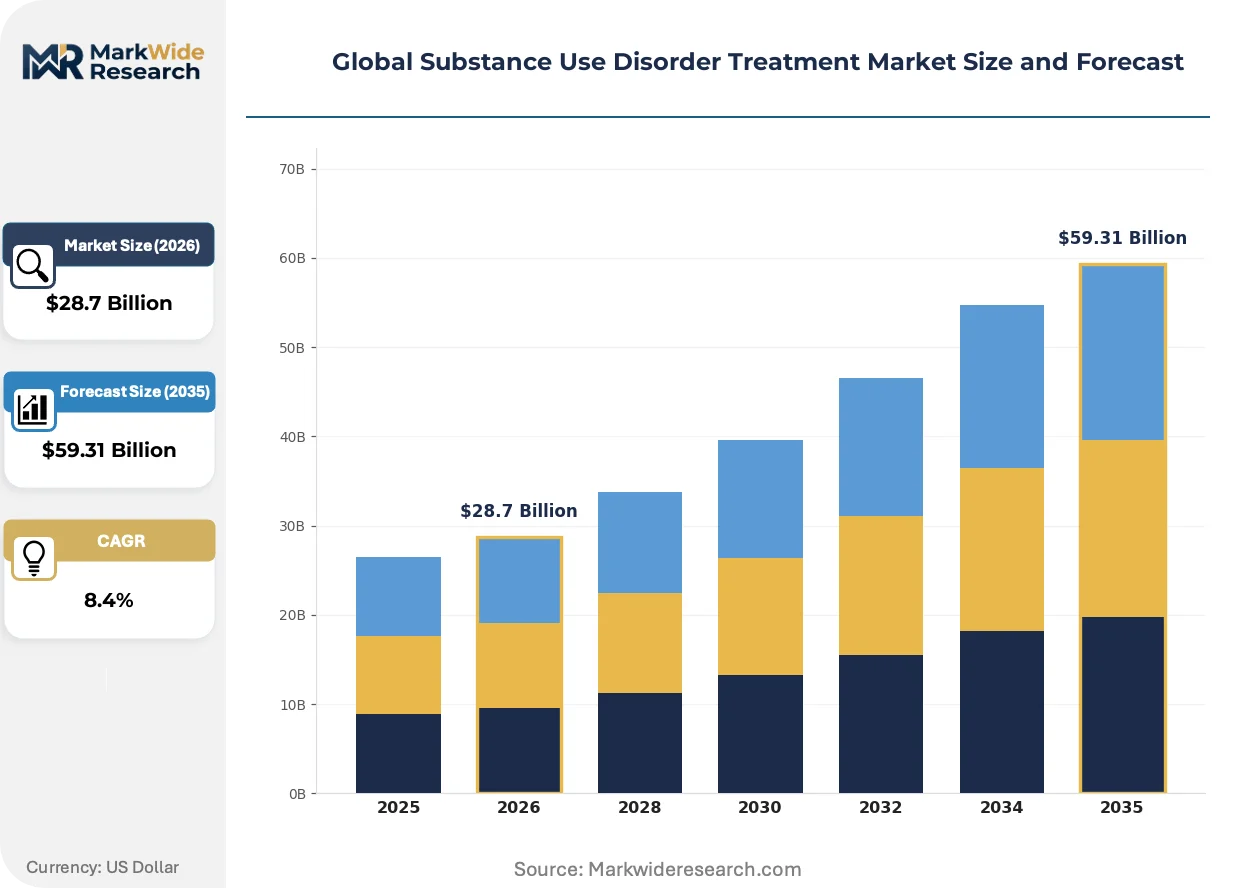
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Modality: Medication-Assisted Therapy, Behavioral Therapy, Detoxification, Therapeutic Communities, Peer Support, Holistic Therapy Patient Demographic: Adolescents, Adults, Veterans, Pregnant Women, Seniors, LGBTQ+ Population Service Provider Type: Inpatient Rehabilitation Centers, Outpatient Clinics, Private Practitioners, Community Health Services, Telehealth Providers, Faith-Based Organizations Form of Care Delivery: Individual Counseling, Group Therapy, Family Therapy, Mobile Health Solutions, Intensive Outpatient Programs, Sober Living Houses |
| Companies Covered | Ria Health, Confidant Health, BayMark Health Services, Nest Health, Rosecrance Behavioral Health, Centerstone, PursueCare, Ashley Addiction Treatment, Eleanor Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Substance Use Disorder Treatment Market Shifts & Advancements
Artificial intelligence is penetrating clinical decision support, regulatory frameworks are adapting to software-as-medical-device models, and payment systems are migrating from fee-for-service toward value-based structures that reward verified patient outcomes.
Machine learning algorithms trained on electronic health record data are unifying predictive risk stratification with real-time dosing recommendations for medication-assisted therapy. Large hospital systems in the United States are deploying these tools to identify patients at elevated overdose risk before discharge from emergency departments. The technology is unifying previously siloed data streams—prescription monitoring, toxicology results, and behavioral health encounters—into single-screen clinical workflows that compress decision time from hours to minutes.
The FDA's breakthrough device designation pathway is accelerating digital therapeutic approvals, compressing traditional 510(k) timelines by 40-60% for software interventions targeting substance use disorders. Manufacturers are responding by front-loading clinical trial investment to secure predicate device status for subsequent indications. European regulators at EMA are observing this acceleration, with draft guidance expected to align software qualification criteria more closely with US precedents to prevent market fragmentation.
Employers are consolidating behavioral health purchasing through direct contracts with integrated care vendors, displacing traditional employee assistance program intermediaries that lacked outcome accountability. Large self-insured plans in the United States are requiring verified abstinence metrics—confirmed toxicology or digital reporting—as payment triggers rather than session counts. This shift is most visible in manufacturing and transportation sectors where safety-sensitive positions mandate substance-free certification and medical cost inflation has exceeded general trend rates by 200-300 basis points annually.
Global Substance Use Disorder Treatment Market Segmentation
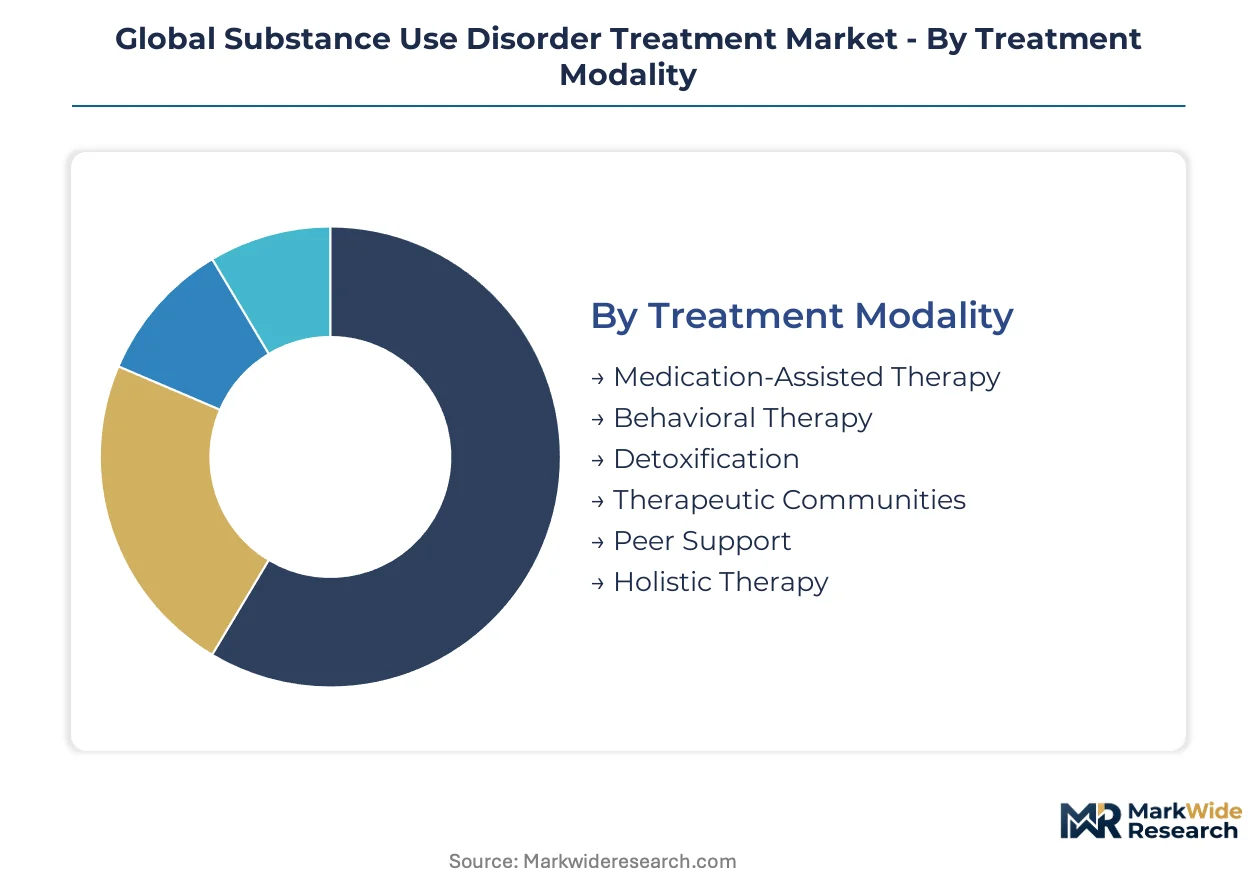
Segmentation in substance use disorder treatment reveals divergent margin structures and regulatory burdens across service delivery models. Understanding these divisions exposes where capital flows concentrate and where reimbursement friction creates competitive moats.
Treatment Modality:
Supply concentration in medication-assisted therapy production centers on a handful of FDA-approved partial agonist manufacturers, while behavioral therapy delivery fragments across thousands of independent practitioners.
- Medication-Assisted Therapy:Buprenorphine, methadone, and naltrexone formulations block euphoric effects while mitigating withdrawal severity. Demand clusters in rural United States counties where DEA flexibilities enable remote prescribing, though workforce gaps limit induction capacity.
- Behavioral Therapy:Cognitive-behavioral and contingency management interventions command the largest revenue share due to mandated coverage under the US Mental Health Parity and Addiction Equity Act. Urban academic medical centers in Boston, New York, and San Francisco concentrate specialist training programs.
- Detoxification:Medically supervised withdrawal management requires SAMHSA-certified facilities with 24-hour nursing coverage.
- Therapeutic Communities:Residential rehabilitation models emphasize peer accountability and structured daily routines.
- Peer Support:Certified recovery coaches deliver non-clinical mentorship through state Medicaid waiver programs.
- Holistic Therapy:Mindfulness, yoga, and acupuncture supplements attract private-pay patients seeking alternatives to pharmacological approaches.
Behavioral therapy absorbs the bulk of installed capacity; medication-assisted therapy is expanding most quickly through telehealth distribution channels.
Patient Demographic:
Cost tier stratification separates commercially insured adults from Medicaid-dependent populations, with veterans accessing dedicated federal funding streams through the US Department of Veterans Affairs.
- Adults:Ages 18-64 represent the core commercially insured population driving outpatient clinic revenue. Employer-sponsored coverage in the United States funds intensive outpatient programs with minimal cost-sharing requirements.
- Adolescents:Specialized pediatric addiction services face severe workforce shortages, with fewer than 100 board-certified adolescent addiction specialists nationwide.
- Veterans:Federal funding through VA medical centers sustains dedicated substance use treatment infrastructure.
- Pregnant Women:Priority access to medication-assisted therapy is mandated under federal block grant requirements.
- Seniors:Medicare Part B covers outpatient behavioral health with 20% coinsurance, creating affordability barriers.
- LGBTQ+ Population:Culturally competent providers concentrate in urban coastal markets with established community health center networks.
Adults generate the majority of reimbursed encounters; veterans are climbing the fastest due to expanded VA community care contracting.
Service Provider Type:
Volume concentration in outpatient clinics reflects Medicaid reimbursement density, while telehealth platforms are displacing geographic constraints through DEA-controlled substance prescribing authority.
- Outpatient Clinics:Intensive outpatient programs deliver structured group therapy three to five days weekly. These facilities dominate Medicaid-reimbursed volume in states with expanded eligibility.
- Telehealth Providers:Virtual platforms leverage DEA flexibilities to prescribe buprenorphine across state lines. California, Texas, and Florida host the largest concentration of venture-backed telehealth entrants.
- Inpatient Rehabilitation Centers:Residential programs require state licensing and Joint Commission accreditation for commercial insurance contracts.
- Private Practitioners:Solo and small-group practices face reimbursement rate compression from managed care carve-outs.
- Community Health Services:Federally qualified health centers integrate substance use treatment with primary care under Section 330 funding.
- Faith-Based Organizations:Religious recovery programs operate outside insurance networks, relying on charitable donations and sliding-scale fees.
Outpatient clinics retain the deepest volume base; telehealth providers are gaining share fastest through employer direct contracting.
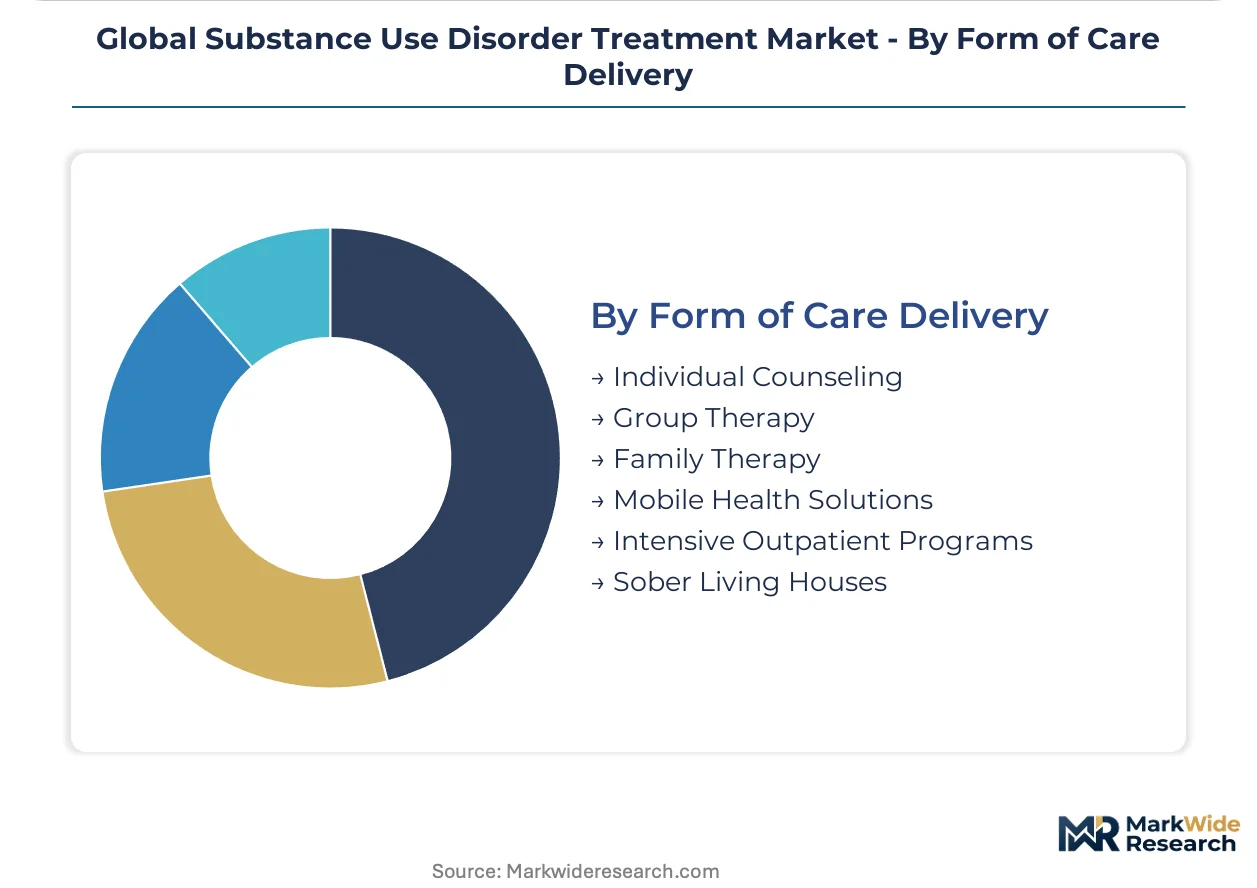
Form of Care Delivery:
Margin profiles diverge sharply between high-touch individual counseling and scalable group formats, with intensive outpatient programs capturing the most favorable reimbursement-to-cost ratios.
- Intensive Outpatient Programs:Structured group therapy delivered nine or more hours weekly qualifies for higher reimbursement tiers under commercial and Medicaid plans. These programs concentrate in metropolitan United States markets with sufficient population density to fill cohorts.
- Mobile Health Solutions:Smartphone applications and SMS-based interventions deliver continuous support between clinical encounters. FDA breakthrough device designations are accelerating clearance for prescription digital therapeutics paired with medication-assisted therapy.
- Individual Counseling:One-on-one psychotherapy sessions command premium rates but face utilization management restrictions.
- Group Therapy:Cost-efficient format enables higher patient-to-clinician ratios.
- Family Therapy:Systems-based interventions address relational triggers for relapse.
- Sober Living Houses:Peer-run residential environments provide transitional housing without clinical services.
Intensive outpatient programs absorb the bulk of program-level profitability; mobile health solutions are expanding most quickly through software-as-medical-device reimbursement pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the majority of reimbursed substance use disorder services while India and Germany build regulatory frameworks to formalize previously informal care networks. Production of clinical capacity clusters in urban academic medical centers, leaving rural areas dependent on telehealth distribution channels.
United States
Medicaid expansion and federal parity mandates drive demand concentration in states with broadened eligibility. The DEA maintains flexibilities for remote buprenorphine prescribing that extend medication-assisted therapy to rural counties lacking brick-and-mortar facilities. Boston, New York, and San Francisco anchor specialist training programs that supply addiction medicine physicians to national markets.
Germany
Statutory health insurance integration of substance use services creates predictable reimbursement streams for outpatient clinics. EMA alignment with FDA digital therapeutic precedents accelerates software-based intervention approvals. Berlin and Munich concentrate university-affiliated addiction research centers that influence treatment protocol standardization across German-speaking Europe.
India
National Mental Health Programme expansion establishes reimbursement infrastructure for standardized outpatient protocols previously delivered through informal networks. CDSCO oversight of pharmacological imports shapes medication-assisted therapy availability. Maharashtra and Karnataka host emerging telehealth platforms targeting employer-sponsored corporate wellness contracts in Bangalore and Mumbai technology corridors.
United Kingdom
NHS England commissioning frameworks consolidate substance use funding through integrated care systems that merge physical and behavioral health budgets. NICE technology appraisals determine digital therapeutic reimbursement eligibility. London and Manchester concentrate opioid substitution therapy capacity while regional trusts experiment with outcome-based payment models.
Australia
Pharmaceutical Benefits Scheme subsidies for naltrexone and buprenorphine formulations reduce patient cost barriers in rural communities. TGA expedited pathways for prescription digital therapeutics align with FDA breakthrough device momentum. Sydney and Melbourne anchor clinical trial networks that generate evidence for Asia-Pacific regulatory submissions.
Global Substance Use Disorder Treatment Market Competitive Landscape
Capital-heavy facility operators compete with asset-light telehealth platforms for patient acquisition and reimbursement access. The market structures around three tiers: national brick-and-mortar networks with SAMHSA-certified opioid treatment programs, venture-backed virtual platforms leveraging DEA prescribing flexibilities, and regional community health centers integrating substance use with primary care workflows. Dominant competitive moves include employer direct contracting that bypasses traditional health plan intermediaries, and bundled outcome-based pricing that ties provider payment to verified abstinence metrics rather than service volume.
Within the telehealth platform archetype, Ria Health and Confidant Health exemplify the direct-to-consumer and employer-sponsored virtual coaching models respectively. BayMark Health Services anchors the facility-based tier through its multi-state opioid treatment program network. These three entities represent divergent strategic bets on whether substance use disorder care migrates toward decentralized digital delivery or retains physical site-of-service requirements for controlled substance management and intensive outpatient programming.
| Leading Market Players |
|---|
| Ria Health |
| Confidant Health |
| BayMark Health Services |
| Nest Health |
| Rosecrance Behavioral Health |
| Centerstone |
| PursueCare |
| Ashley Addiction Treatment |
| Eleanor Health |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up outpatient clinic networks anchor supply-side concentration in the United States, enabling subscription-based pricing discipline for medication-assisted therapy while compressing margins for independent practitioners competing against scaled SAMHSA-certified facilities.
Pricing Analysis
Cost-down pressure on telehealth platforms accelerates because employer-sponsored virtual coaching contracts bundle behavioral health with primary care workflows. Three-tier pricing structure across premium concierge, standard insured, and economy Medicaid-reimbursed levels separates cash-pay patients seeking privacy from those dependent on federal parity mandates. Price differentiation traces to DEA prescribing authority and state-level licensing reciprocity completion. Medicaid-dependent populations exhibit highest price sensitivity; self-insured corporations demonstrate lowest sensitivity when absenteeism reduction justifies premium spend.
Supply Chain Analysis
FDA and SAMHSA certification gating constrains opioid treatment program expansion, with DEA-registered manufacturers in the United States, India, and Germany supplying buprenorphine and naltrexone formulations. Active pharmaceutical ingredient production draws from Indian CDSCO-regulated facilities and European EMA-aligned plants. Single-source vulnerability concentrates in extended-release naltrexone depot formulations. Distribution runs through specialty pharmacy channels for controlled substances, with telehealth platforms disintermediating traditional brick-and-mortar induction sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telehealth infrastructure is replacing legacy facility-based delivery, compressing geographic barriers and forcing traditional outpatient clinics to compete on convenience metrics they cannot match.
For Market Incumbents: Lock in DEA prescribing flexibilities through multi-state licensing reciprocity agreements before interstate compacts fragment. Defend against venture-backed virtual platforms by acquiring telehealth capabilities rather than building organically. Vertical integration into employer direct contracting channels preserves margin pools threatened by health plan intermediaries. For New Entrants and Emerging Players: Begin with India's National Mental Health Programme expansion, where reimbursement infrastructure formalizes previously informal care networks. Target employer-sponsored corporate wellness contracts in Bangalore and Mumbai technology corridors. Pursue FDA breakthrough device designation for prescription digital therapeutics paired with medication-assisted therapy. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional community health centers with Section 330 funding and integrated behavioral-primary care workflows in United States Medicaid expansion states. Long-term viability hinges on outcome-based contract penetration tying payment to verified abstinence metrics. Watch for DEA flexibilities expiration as inflection indicator for telehealth platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| DEA Multi-State Licensing Expansion | Enables buprenorphine prescribing across state lines under federal flexibilities. |
| FDA Breakthrough Device Submission | Accelerates clearance timelines for app-based substance use interventions. |
| Employer Direct Contracting | Bypasses health plan intermediaries to capture medical cost savings. |
| SAMHSA Accreditation Investment | Satisfies capital-intensive physical plant requirements for opioid treatment programs. |
| Outcome-Based Payment Structuring | Ties provider reimbursement to verified toxicology-confirmed abstinence metrics. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with addiction medicine physicians, telehealth platform executives, state Medicaid formulary directors, and SAMHSA accreditation specialists. FDA 510(k) submissions, DEA controlled substance manufacturing quotas, CMS Medicare reimbursement databases, and state prescription monitoring program records provided validation. Bottom-up service provider capacity modeling and top-down expenditure flow analysis enabled triangulation.
Reconciliation across patient encounter volumes, reimbursement rate schedules, and platform subscription revenue streams supported value projections across the analysis window. Segmentation dimensions encompassed treatment modality, patient demographic, service provider type, and form of care delivery, with geographic regulatory cluster as an additional modeled layer. CAGRs derived from fitted growth curves applied to Medicaid expansion enrollment trajectories and employer-sponsored behavioral health spending patterns.
Underlying measurement precision varies by segment; telehealth platform revenue carries tighter precision than informal peer support services. Forecasts reflect documented assumptions regarding DEA flexibilities continuation and state-level licensing reciprocity progression. A model refresh is warranted upon material change in federal parity enforcement or digital therapeutic reimbursement coding.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Addiction Treatment
US Ketamine Clinics Market
Addiction Treatment
Methadone Market
Addiction Treatment
Opioid Withdrawal Treatment Market
Addiction Treatment
Smokeless Tobacco Treatment Market
Addiction Treatment
Substance Abuse Treatment Market
Addiction Treatment
Nicotine De-Addiction Products Market
Addiction Treatment
Opioid Induced Constipation Treatment Market
Addiction Treatment
Drug Free Depression Treatment Market
Addiction Treatment
Alcohol Use Disorder Treatment Market
Addiction Treatment
Opioid Use Disorder (OUD) Market
Addiction Treatment
US Mental Health and Addiction Treatment Centers Market
Addiction Treatment
Cocaine Intoxication Treatment Market
Addiction Treatment
Global Addiction Treatment Market
Addiction Treatment
Opioid Use Disorder Treatment Market