
 Alcohol Use Disorder Treatment Market | 2026-2036
Alcohol Use Disorder Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Alcohol Use Disorder Treatment Market Analysis
Pharmacotherapy-grade naltrexone and acamprosate formulations is collapsing the historical gap between abstinence-only and harm-reduction protocols, reshaping prescriber confidence in medication-assisted treatment. Alkermes leverages its extended-release injectable platform to sustain recurring revenue from long-acting formulations. Teva Pharmaceutical Industries anchors the generics segment for oral disulfiram and naltrexone tablets, competing on manufacturing scale across multiple geographies. Eli Lilly and Company differentiates through psychiatric comorbidity research, positioning its neuroscience pipeline adjacent to addiction medicine.
Alcohol use disorder treatment encompasses pharmacological interventions, psychosocial therapies, and digital health tools designed to reduce alcohol consumption, prevent relapse, and manage withdrawal symptoms through receptor-targeting medications such as opioid antagonists and glutamate modulators. The primary purpose is restoring functional capacity in patients while reducing healthcare system burdens from liver disease, trauma, and mental health crises. Medications and behavioral therapy dominate current revenue pools, with teletherapy and mobile apps representing the fastest-expanding delivery mode as reimbursement frameworks adapt to remote care. Rehabilitation centers and hospitals capture the deepest margin pools due to bundled payment structures for residential and acute detoxification services.
FDA approval standards for addiction pharmacotherapies, EMA's centralized marketing authorization for central nervous system agents, and HIPAA privacy requirements for digital therapeutics collectively shape product development timelines and market access conditions for new entrants. The DEA's scheduling classifications for controlled substances used in withdrawal management further constrain formulation choices and distribution channels. Stakeholders must monitor evolving state-level parity enforcement and telehealth prescribing rules to anticipate reimbursement shifts that will determine which delivery modes achieve sustainable scale.
Market Dynamics
Integrated care mandates and reimbursement parity reforms are compressing the traditional separation between psychiatric and addiction services, forcing hospital systems to reconfigure service lines around bundled behavioral health episodes.
Growth Catalysts
- Insurance Parity Enforcement:The Mental Health Parity and Addiction Equity Act in the United States is eliminating coverage caps that previously restricted medication-assisted treatment duration, expanding addressable patient populations for pharmacotherapy providers.
- Long-Acting Injectable Formulations:Extended-release depot injections for opioid antagonists are reducing adherence failures that plagued oral regimens, creating sustainable revenue streams for specialty pharmaceutical manufacturers.
- Telehealth Infrastructure:Remote prescribing platforms are dismantling geographic access barriers to behavioral therapy, particularly in rural counties where specialist psychiatrist density remains critically low.
Market Restraints
- DEA Scheduling Friction:Controlled substance classifications for withdrawal management medications impose burdensome storage, tracking, and prescriber certification requirements that inflate operational costs for outpatient clinics.
- Generic Concentration:Oral disulfiram and naltrexone tablet supply chains center on Indian and Chinese active pharmaceutical ingredient manufacturers, creating vulnerability to export restriction shocks.
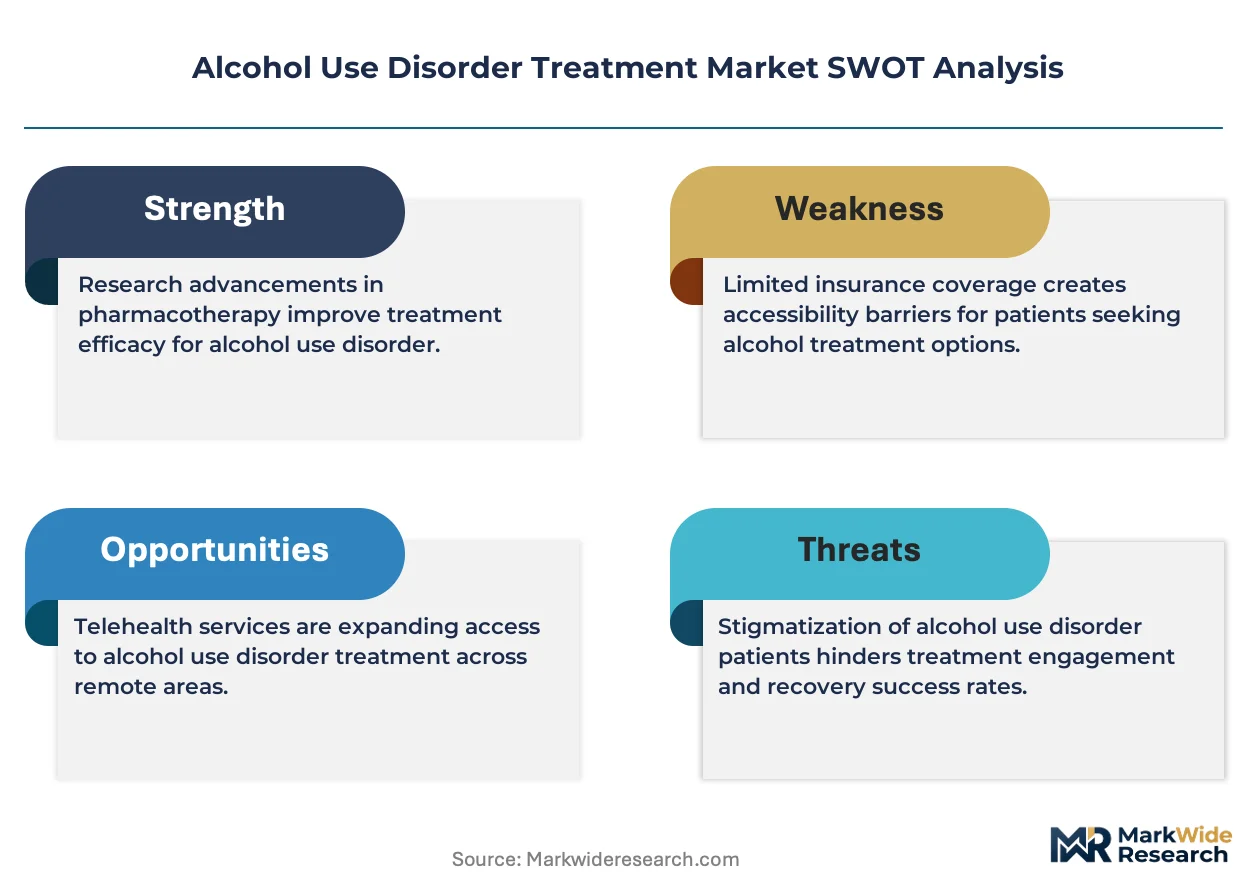
- Stigma-Induced Underdiagnosis:Patient reluctance to disclose alcohol use in primary care settings depresses treatment initiation rates below epidemiological prevalence estimates, constraining market expansion independent of clinical efficacy.
Strategic Opportunities
- Digital Therapeutic Reimbursement:Germany's DiGA fast-track approval pathway for prescription digital health applications is establishing precedent for software-based interventions to achieve pharmacy-benefit coverage alongside traditional medications.
- Co-Occurring Disorder Integration:Psychiatric comorbidity screening protocols in emergency departments are identifying untreated alcohol use disorder among depression and anxiety presentations, creating referral funnel expansion for integrated treatment programs.
- Employer-Sponsored Programs:Large self-insured corporations are contracting directly with specialized addiction medicine networks, bypassing traditional payer intermediaries and capturing productivity-loss reductions through confidential workplace intervention channels.
Industry Challenges
- Addiction Medicine Workforce Scarcity:Fellowship-trained specialists remain concentrated in academic medical centers, leaving community hospitals dependent on general psychiatrists with limited substance use disorder exposure.
- EHR Interoperability Gaps:Behavioral health data segmentation under HIPAA and state-level privacy statutes fragments patient records across psychiatric, addiction, and primary care settings, complicating coordinated care protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcohol Use Disorder Treatment Market |
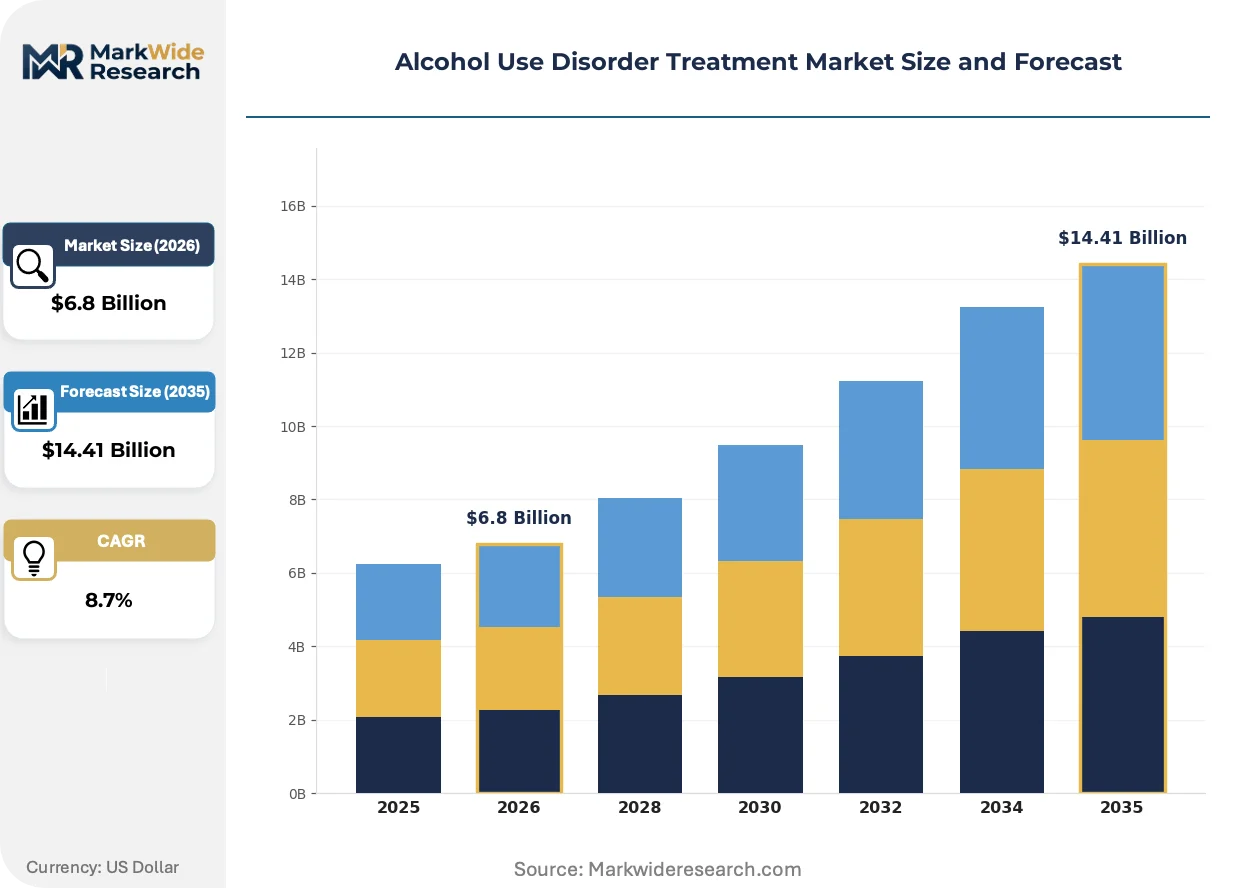
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Psychotherapy, Behavioral Therapy, Support Groups Delivery Mode: In-Person, Teletherapy, Online Programs, Mobile Apps End User: Clinics, Rehabilitation Centers, Hospitals, Private Practices Age Group: Adults, Adolescents, Elderly, Seniors |
| Companies Covered | Alkermes, Teva Pharmaceutical Industries, Adial Pharmaceuticals, BioCorRx, Otsuka Pharmaceutical, Eli Lilly and Company, Novartis, Lundbeck, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcohol Use Disorder Treatment Market Emerging Trajectories
Technology convergence between biometric monitoring and adaptive dosing algorithms is restructuring how pharmacotherapy adherence gets measured and reinforced outside clinical settings.
Continuous transdermal alcohol biosensors is bifurcating the remote patient monitoring landscape between court-mandated abstinence verification and voluntary recovery support applications. Criminal justice systems in the United States are deploying ankle-worn devices for probation compliance, while employer wellness programs and family-initiated interventions favor wrist-worn consumer formats. This divergence is compressing single-purpose device margins while expanding platform subscription revenues for data-integrated care management systems.
The European Medicines Agency's centralized marketing authorization for central nervous system agents is harmonizing pharmacovigilance requirements across member states, reducing duplicate safety reporting burdens for multi-national sponsors. Post-authorization study mandates now explicitly incorporate real-world evidence collection through electronic health record networks. Smaller biotechnology developers are responding by prioritizing EMA-first filing strategies to leverage streamlined mutual recognition pathways into national reimbursement negotiations.
Patient-initiated switching between abstinence-oriented and harm-reduction treatment goals is fragmenting historical program loyalty and compressing average episode lengths. Residential rehabilitation facilities are losing census to outpatient medication management as relapse definitions broaden to include controlled consumption rather than strict sobriety. This behavioral shift is most visible in Australia and Canada, where government-funded services have explicitly adopted low-risk drinking guidelines alongside traditional abstinence pathways.
Alcohol Use Disorder Treatment Market Segmentation
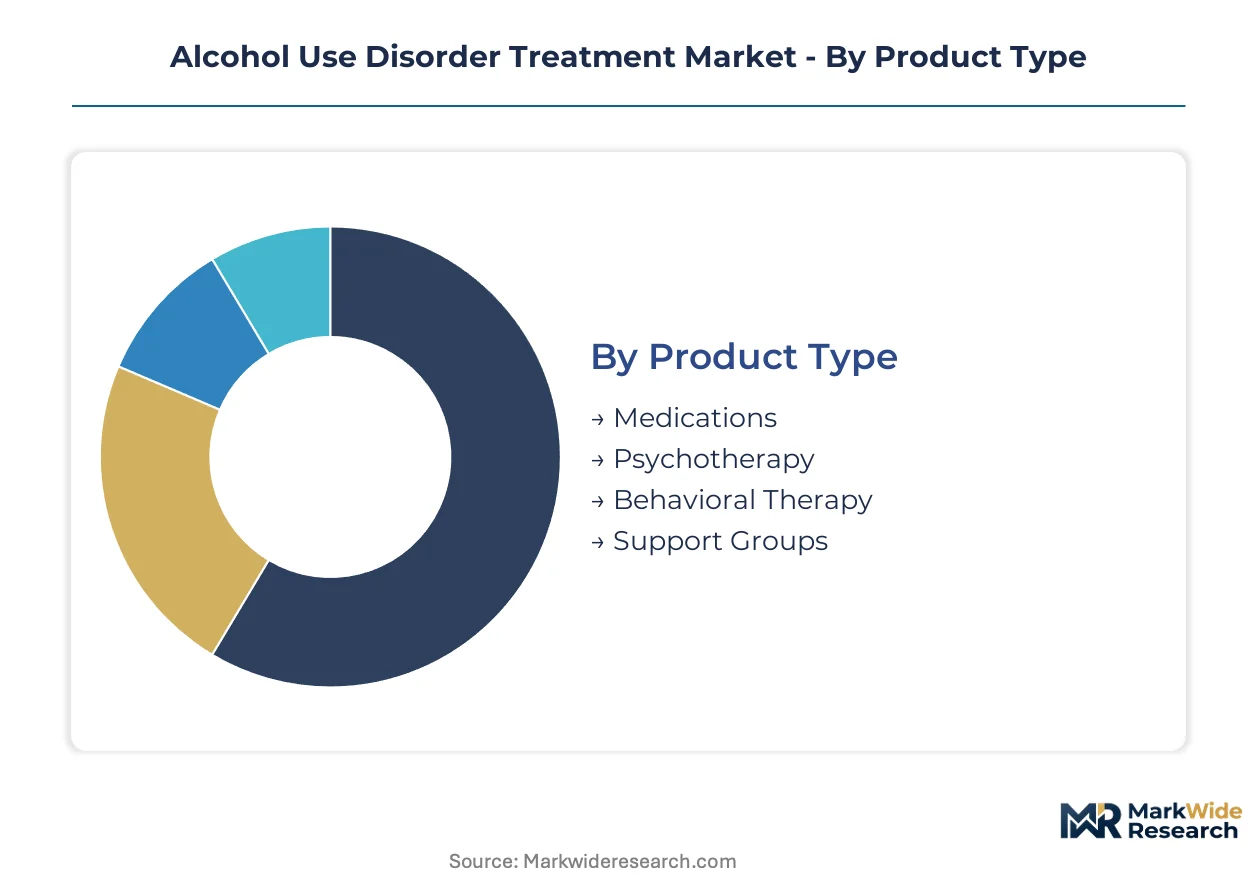
Alcohol use disorder treatment segments diverge sharply by reimbursement eligibility and clinical setting. Product type determines prescriber authority and insurance coverage depth. Delivery mode selection reflects patient geography, stigma tolerance, and comorbidity severity.
Product Type:
Medications and psychotherapy concentrate revenue in the United States and Western Europe where FDA and EMA approvals unlock pharmacy benefit coverage. Behavioral therapy and support groups spread more evenly across middle-income markets with limited pharmacotherapy infrastructure.
- Medications:Opioid antagonists and glutamate modulators require FDA or EMA marketing authorization for reimbursement access. United States demand concentrates around extended-release naltrexone injectables where Medicare Part B covers administration costs. Generic oral disulfiram and acamprosate tablets compete on manufacturing scale across India and China supply chains.
- Psychotherapy:Cognitive-behavioral and motivational enhancement protocols deliver through licensed practitioners in Germany, the United Kingdom, and Australia where national health systems fund standardized session counts. Private insurance in the United States imposes prior authorization requirements that fragment episode continuity.
- Behavioral Therapy:Contingency management and relapse prevention training deploy in outpatient settings across Brazil and South Africa where medication access remains uneven.
- Support Groups:Peer-facilitated mutual aid operates outside reimbursement frameworks, expanding fastest in low-resource settings from Southeast Asia to Eastern Europe.
Medications holds the largest share; momentum sits with psychotherapy as integrated care mandates expand behavioral health funding.
Delivery Mode:
Cost tier stratification separates high-touch clinical encounters from automated digital interventions. Premium reimbursement attaches to in-person encounters requiring specialist credentialing. Economy-tier access expands through software subscriptions and asynchronous content libraries.
- In-Person:Residential rehabilitation and intensive outpatient programs capture bundled payments from commercial insurers and Medicaid in the United States. Physical facility requirements limit geographic penetration to urban corridors and medical tourism destinations.
- Teletherapy:Synchronous video counseling exploded following COVID-19 regulatory waivers that relaxed interstate licensing restrictions across the United States. Germany's DiGA pathway now reimburses prescription digital health applications at parity with face-to-face sessions.
- Online Programs:Asynchronous modules and virtual support communities scale across Canada and Australia where government portals distribute standardized cognitive-behavioral content.
- Mobile Apps:Consumer-facing craving trackers and sobriety counters proliferate on app stores with minimal clinical validation, though Japan's PMDA is piloting formal approval pathways for software-as-medical-device.
In-person retains the deepest margins; teletherapy is climbing the fastest as licensure compacts and reimbursement parity spread across OECD markets.
End User:
Volume concentration varies by care acuity and regulatory environment. High-complexity cases flow toward hospital-based programs with detoxification capabilities. Stable maintenance patients distribute across outpatient clinics and private practices.
- Clinics:Federally qualified health centers and community mental health centers in the United States serve Medicaid populations under 42 CFR Part 2 privacy regulations that restrict information sharing.
- Rehabilitation Centers:Residential facilities in Thailand and South Africa market medical tourism packages to European and Middle Eastern patients seeking confidential treatment outside home health systems.
- Hospitals:Emergency departments in the United States, France, and Australia deploy systematic alcohol screening and brief intervention protocols that identify untreated disorder during trauma and psychiatric admissions.
- Private Practices:Addiction medicine specialists in academic medical centers concentrate in Boston, Baltimore, and San Francisco where fellowship programs produce board-certified practitioners.
Hospitals anchor volume through emergency department screening mandates; private practices gain share as telehealth licensing expands specialist reach into rural counties.
Age Group:
Application context determines intervention design and regulatory scrutiny. Adult populations drive commercial revenue through employer-sponsored coverage and commercial insurance. Pediatric and geriatric segments face stricter safety monitoring and distinct comorbidity profiles.
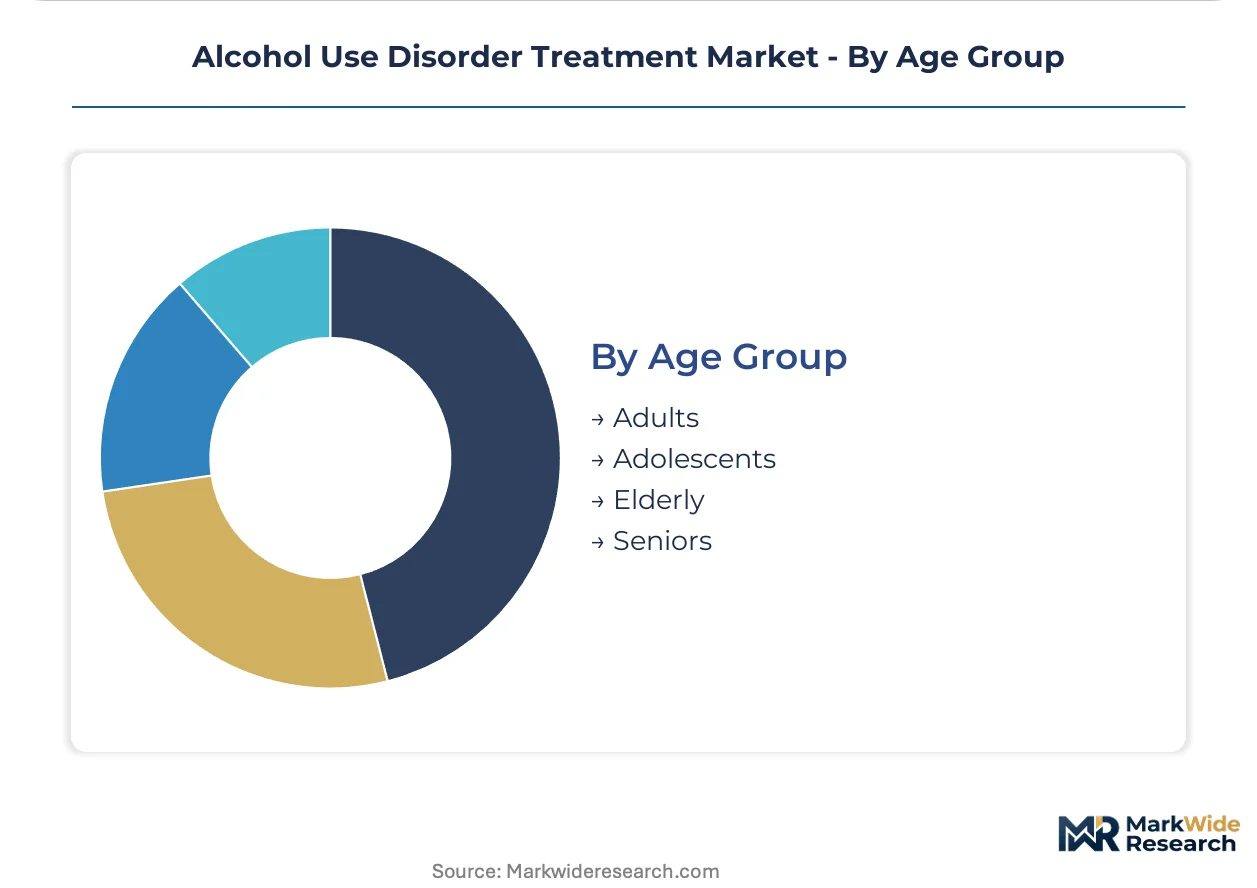
- Adults:Adults aged 25-54 constitute the primary addressable population for pharmacotherapy and employer wellness programs across the United States, Germany, and Japan where workplace productivity losses justify intervention investment.
- Adolescents:Pediatric treatment protocols in the United Kingdom and Netherlands emphasize family-based therapy over medication due to limited FDA and EMA approval data for subjects under 18.
- Elderly:Adults aged 55-64 present rising prevalence as baby-boom cohorts age, with Medicare Advantage plans in the United States expanding behavioral health carve-outs.
- Seniors:Patients over 65 require modified dosing and drug-drug interaction surveillance in France and Sweden where polypharmacy complicates alcohol-medication interactions.
Adults dominate commercial value; seniors represent the steepest expansion trajectory as demographic aging reshapes demand across OECD health systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity for alcohol use disorder treatment varies sharply by geography. Patients in Germany and Australia face minimal out-of-pocket costs under universal coverage, while those in India and Brazil absorb substantial private-pay burdens that constrain medication access.
United States
Employer-sponsored wellness programs and Medicare Advantage behavioral health carve-outs drive commercial demand. The Mental Health Parity and Addiction Equity Act eliminates coverage caps that previously restricted medication-assisted treatment duration. Boston, Baltimore, and San Francisco concentrate fellowship-trained addiction medicine specialists in academic medical center clusters.
Germany
National health system funding for standardized psychotherapy sessions sustains cognitive-behavioral and motivational enhancement protocols. The DiGA fast-track approval pathway for prescription digital health applications establishes reimbursement parity for software-based interventions. Berlin and Hamburg anchor teletherapy platform development within the European regulatory framework.
Australia
Government-funded services explicitly adopt low-risk drinking guidelines alongside traditional abstinence pathways, fragmenting historical program loyalty. Emergency departments deploy systematic alcohol screening and brief intervention protocols during trauma and psychiatric admissions. Sydney and Melbourne lead outpatient medication management adoption as residential rehabilitation census declines.
Japan
Workplace productivity-loss calculations justify employer investment in intervention programs for adults aged 25-54. The PMDA pilots formal approval pathways for software-as-medical-device, regulating consumer-facing craving trackers. Tokyo and Osaka concentrate psychiatric comorbidity research adjacent to addiction medicine pipelines.
India
Oral disulfiram and naltrexone tablet supply chains center on domestic active pharmaceutical ingredient manufacturers serving price-sensitive markets. Export restrictions from Chinese suppliers create vulnerability shocks that inflate operational costs for outpatient clinics. Mumbai and Hyderabad anchor generic manufacturing scale competing across multiple geographies.
Alcohol Use Disorder Treatment Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the alcohol use disorder treatment market. Specialty pharmaceutical manufacturers command premium pricing through extended-release injectable platforms and novel receptor-targeting mechanisms. Generic tablet producers compete on manufacturing scale and active pharmaceutical ingredient sourcing efficiency. The market structure rewards portfolio diversification into psychiatric comorbidity adjacencies and geographic expansion through centralized marketing authorization pathways.
Within the specialty pharmaceutical tier, Alkermes and Otsuka Pharmaceutical exemplify platform-based revenue sustainability through long-acting formulation development. Eli Lilly and Company occupies a position bridging neuroscience pipeline investment with addiction medicine adjacency. Among generic-scale manufacturers, Teva Pharmaceutical Industries anchors oral disulfiram and naltrexone tablet supply across multiple geographies.
| Leading Market Players |
|---|
| Alkermes |
| Teva Pharmaceutical Industries |
| Adial Pharmaceuticals |
| BioCorRx |
| Otsuka Pharmaceutical |
| Eli Lilly and Company |
| Novartis |
| Lundbeck |
| Pfizer |
| Others |
Supply Flow & Price Mechanics
FDA and EMA marketing authorization tiers simultaneously gate supply qualification and price differentiation, creating a bifurcated market where extended-release injectables command premium reimbursement while oral generics compete on manufacturing scale.
Pricing Analysis
After-sales revenue from long-acting depot administration and medication management programs drives lifetime value for specialty pharmaceutical manufacturers. Pricing stratifies across premium, standard, and economy tiers based on formulation complexity and prescriber certification requirements. Cost compression in oral generic tablets intensifies as Indian and Chinese API manufacturers expand capacity. Employer-sponsored wellness programs demonstrate lowest price sensitivity, while Medicaid-funded community clinics face strict prior authorization constraints.
Supply Chain Analysis
Inventory lead times for extended-release naltrexone injectables extend substantially longer than oral tablet replenishment cycles due to cold-chain requirements and specialty distribution networks. Active pharmaceutical ingredient production concentrates in India and China, with finished formulation capacity distributed across the United States and Western Europe. Supply chains draw from synthetic chemistry inputs, polymer depot matrices, and sterile manufacturing equipment. Single-source vulnerability for long-acting injectable platforms creates concentration risk. Distribution runs through specialty pharmacy networks and hospital outpatient clinics rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The alcohol use disorder treatment market exhibits cyclical recovery characteristics as insurance parity enforcement and telehealth infrastructure investment create successive waves of addressable patient expansion.
For Market Incumbents: Compound defensive positioning through backward integration into API manufacturing to insulate against export restriction shocks from Indian and Chinese suppliers. Expand capacity in extended-release formulation platforms to capture recurring revenue from medication management programs. Reinforce formulary access through real-world evidence generation that satisfies Medicare Advantage behavioral health carve-out requirements. For New Entrants and Emerging Players: Anchor in digital therapeutic development targeting Germany's DiGA fast-track pathway, where software-based interventions achieve pharmacy-benefit parity with face-to-face sessions. Focus initial deployment on employer-sponsored wellness channels that bypass traditional payer intermediaries. Pursue strategic partnerships with telehealth platforms to accelerate prescriber network access. For Investors and Strategic Acquirers: DEA scheduling reclassification for withdrawal management medications reshapes the acquisition landscape by altering storage and certification cost structures for outpatient clinic networks. Five-to-ten year viability favors platforms with psychiatric comorbidity adjacencies and long-acting formulation capabilities. Target specialty pharmaceutical developers with EMA-first filing strategies. Monitor state-level parity enforcement litigation as inflection indicator for reimbursement expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Acting Formulation Development | Extended-release depot platforms reduce adherence failures and sustain recurring revenue for Alkermes and Otsuka. |
| Digital Therapeutic Reimbursement Strategy | Germany's DiGA pathway establishes precedent for software interventions achieving pharmacy-benefit coverage parity. |
| API Manufacturing Scale-Up | Indian and Chinese active pharmaceutical ingredient expansion intensifies cost competition in oral generic tablets. |
| Telehealth Platform Integration | Remote prescribing infrastructure dismantles geographic access barriers in rural counties with low psychiatrist density. |
| Psychiatric Comorbidity Pipeline Diversification | Eli Lilly's neuroscience research adjacent to addiction medicine captures integrated care mandate expansion. |
Methodological Framework
The analysis maps pharmacotherapy, psychotherapy, behavioral therapy, and digital health sub-sectors, each validated through addiction medicine specialists, formulary directors at commercial payers, hospital procurement managers, and telehealth platform executives. Primary interviews combined with secondary validation from FDA filings, EMA centralized marketing authorization records, ClinicalTrials.gov, and CMS Medicare Part B claims data. Bottom-up patient volume estimates and top-down expenditure analysis triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end-user setting, and age group cohort, with regional regulatory clusters as an additional cross-cutting dimension. CAGRs derived from epidemiological prevalence trends, reimbursement expansion trajectories, and formulation adoption curves. Forecast inputs incorporate DEA scheduling classifications and state-level parity enforcement patterns.
Decision-makers should treat outputs as directional under assumptions of sustained insurance parity enforcement and stable API supply chains; material deviation in regulatory timelines or export restrictions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Addiction Treatment
Drug Free Depression Treatment Market
Addiction Treatment
Opioid Withdrawal Treatment Market
Addiction Treatment
Global Substance Use Disorder Treatment Market
Addiction Treatment
Global Addiction Treatment Market
Addiction Treatment
Opioid Use Disorder (OUD) Market
Addiction Treatment
Cocaine Intoxication Treatment Market
Addiction Treatment
Substance Abuse Treatment Market
Addiction Treatment
Smokeless Tobacco Treatment Market
Addiction Treatment
Opioid Use Disorder Treatment Market
Addiction Treatment
US Mental Health and Addiction Treatment Centers Market
Addiction Treatment
Methadone Market
Addiction Treatment
Opioid Induced Constipation Treatment Market
Addiction Treatment
US Ketamine Clinics Market
Addiction Treatment
Nicotine De-Addiction Products Market