
 Smokeless Tobacco Treatment Market | 2026-2036
Smokeless Tobacco Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Smokeless Tobacco Treatment Market Analytics
Digital therapeutics integration is fragmenting traditional smokeless tobacco treatment delivery, splitting patient journeys between in-person clinical protocols and app-supported remote programs. Pfizer Inc. leverages its established nicotine replacement therapy infrastructure to sustain pharmacy channel dominance. Achieve Life Sciences anchors its position through specialized cytisine-based pharmacotherapy development for smokeless tobacco users.
Smokeless tobacco treatment encompasses pharmacological and behavioral interventions designed to reduce dependence on non-combustible tobacco products such as snuff, chewing tobacco, and dissolvables, typically employing nicotine replacement at controlled dosages or receptor partial agonists to manage withdrawal. The therapy area spans cessation programs combining pharmacotherapy with structured counseling, while delivery mode increasingly favors oral formats including lozenges and gum for their discrete patient use. Patches within transdermal delivery occupy mature, high-volume positioning, whereas behavioral therapy segments are gaining structural importance as payers demand documented quit outcomes.
The FDA regulates nicotine replacement therapies as drug products under its Center for Drug Evaluation and Research, while the WHO Framework Convention on Tobacco Control establishes international cessation protocol standards that influence national program design. These frameworks shape demand by determining prescription status, reimbursement eligibility, and clinical trial endpoints required for market access. Stakeholders must monitor how emerging digital health regulations will redefine which delivery modes qualify for insurance coverage and provider prescribing workflows.
Market Dynamics
The smokeless tobacco treatment market restructures around digital therapeutics integration, which fragments patient journeys between clinical pharmacotherapy protocols and app-supported remote cessation programs. Healthcare providers now split resources across in-person counseling and asynchronous digital monitoring, creating parallel demand channels that reshape reimbursement and service delivery architectures.
Growth Catalysts
- Medicaid coverage expansions:US state-level mandates for tobacco cessation services drive clinic-based adoption of combined pharmacotherapy and behavioral interventions. Rehabilitation centers expand dedicated smokeless tobacco dependence programs.
- Nicotine replacement therapy infrastructure:Established pharmacy distribution networks for oral formats—lozenges and gum—enable discrete patient use and sustained retail channel penetration.
- WHO Framework Convention on Tobacco Control:International cessation protocol standards influence national program design and create harmonized regulatory pathways for product approval across multiple jurisdictions.
Market Restraints
- Transdermal patch maturity:Patches occupy saturated, high-volume positioning with limited innovation headroom, compressing margin expansion for manufacturers dependent on this delivery mode.
- FDA approval pathway complexity:The Center for Drug Evaluation and Research's evolving nicotine regulation framework creates extended clinical trial endpoint requirements that delay market access for novel cessation therapies.
- Behavioral therapy documentation burden:Payer demands for documented quit outcomes impose structural cost increases on providers, limiting program scalability.
Strategic Opportunities
- Digital health qualification pathways:Emerging regulations redefining insurance coverage for app-supported remote programs create reimbursement eligibility for software-based cessation interventions.
- Cytisine-based pharmacotherapy:Specialized receptor partial agonist development targets unmet need among smokeless tobacco users with distinct withdrawal profiles versus combustible tobacco populations.
- Provider prescribing workflow integration:Electronic health record embedded cessation tools streamline clinical decision support and capture quality metrics demanded by value-based care contracts.
Industry Challenges
- Digital-clinical integration complexity:Health systems struggle to synchronize asynchronous remote monitoring data with in-person pharmacotherapy dosing protocols, creating care coordination gaps.
- Behavioral health workforce scarcity:Structured counseling capacity constraints limit expansion of combined intervention programs despite reimbursement availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smokeless Tobacco Treatment Market |
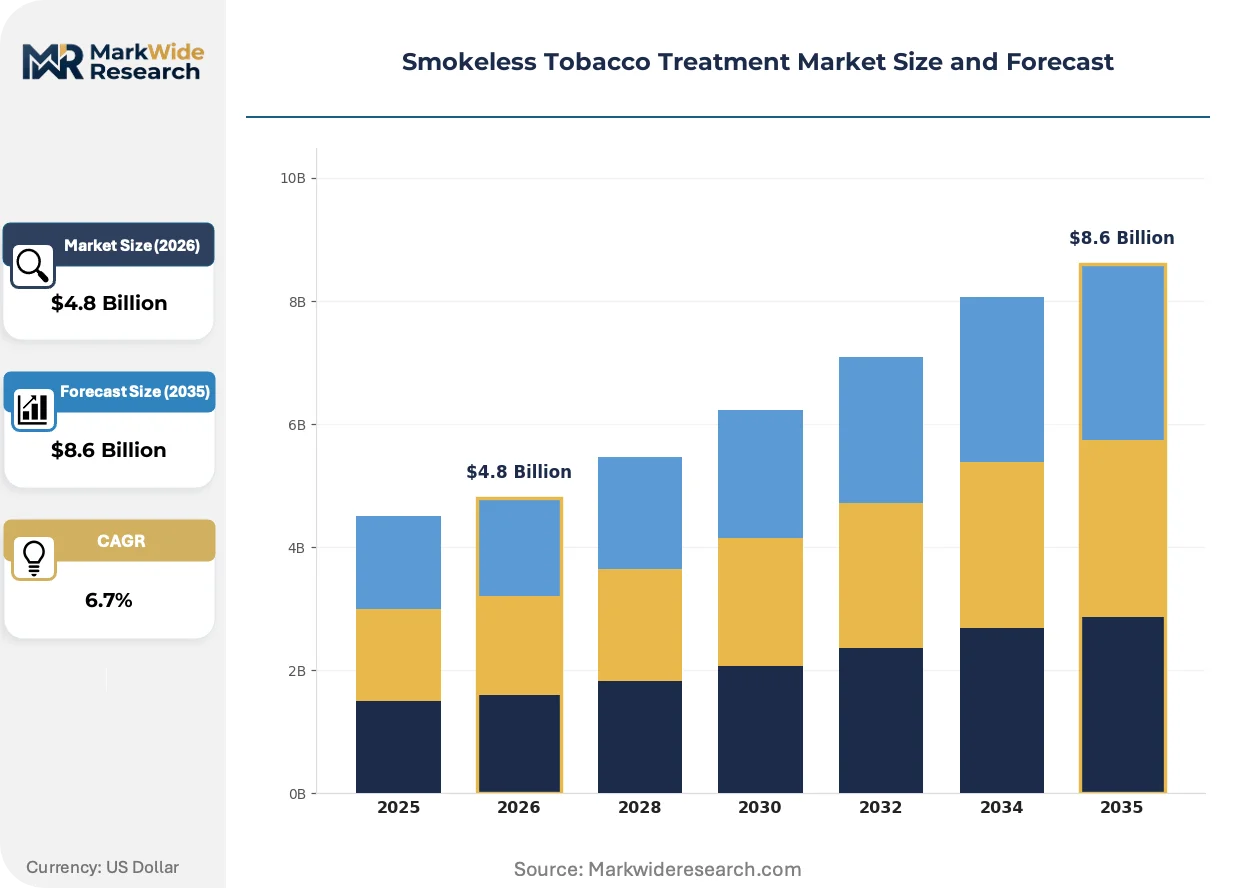
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nicotine Gum, Patches, Lozenges, Inhalers Therapy Area: Cessation, Behavioral Therapy, Pharmacotherapy, Counseling Delivery Mode: Oral, Transdermal, Inhalation, Subcutaneous End User: Clinics, Hospitals, Rehabilitation Centers, Home Care |
| Companies Covered | Pfizer Inc., Johnson & Johnson Services Inc., Achieve Life Sciences, Axsome Therapeutics, NFL Biosciences, Embera NeuroTherapeutics Inc., Currax Pharmaceuticals LLC, Omeros Corporation, Otsuka Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smokeless Tobacco Treatment Market Evolving Landscape
Digital therapeutics platforms actively compress the traditional smokeless tobacco treatment value chain, eliminating intermediate care coordination layers between patients and pharmacotherapy management. Remote monitoring capabilities now embed directly into consumer-facing applications, bypassing conventional clinical gatekeeping functions.
Machine learning algorithms applied to withdrawal pattern prediction is collapsing the distinction between reactive symptom management and preemptive dose adjustment. Telehealth providers deploy these tools to automate nicotine replacement timing recommendations. The technology compresses required clinical touchpoints while maintaining cessation efficacy benchmarks.
The FDA's evolving nicotine regulation framework reclassifies certain digital cessation applications as drug-device combination products, triggering enhanced premarket review requirements. Manufacturers must now generate clinical trial evidence for software-mediated behavioral interventions. Product developers with existing pharmacotherapy portfolios adapt regulatory strategies to accommodate this expanded oversight scope.
Patients increasingly initiate smokeless tobacco cessation through direct-to-consumer digital channels rather than physician referral pathways. Pharmacy benefit managers respond by carving out standalone digital therapeutic coverage from traditional medical benefit structures. This channel disintermediation concentrates in the United States, where high smartphone penetration and fragmented primary care access accelerate adoption of app-first treatment models.
Smokeless Tobacco Treatment Market Segmentation
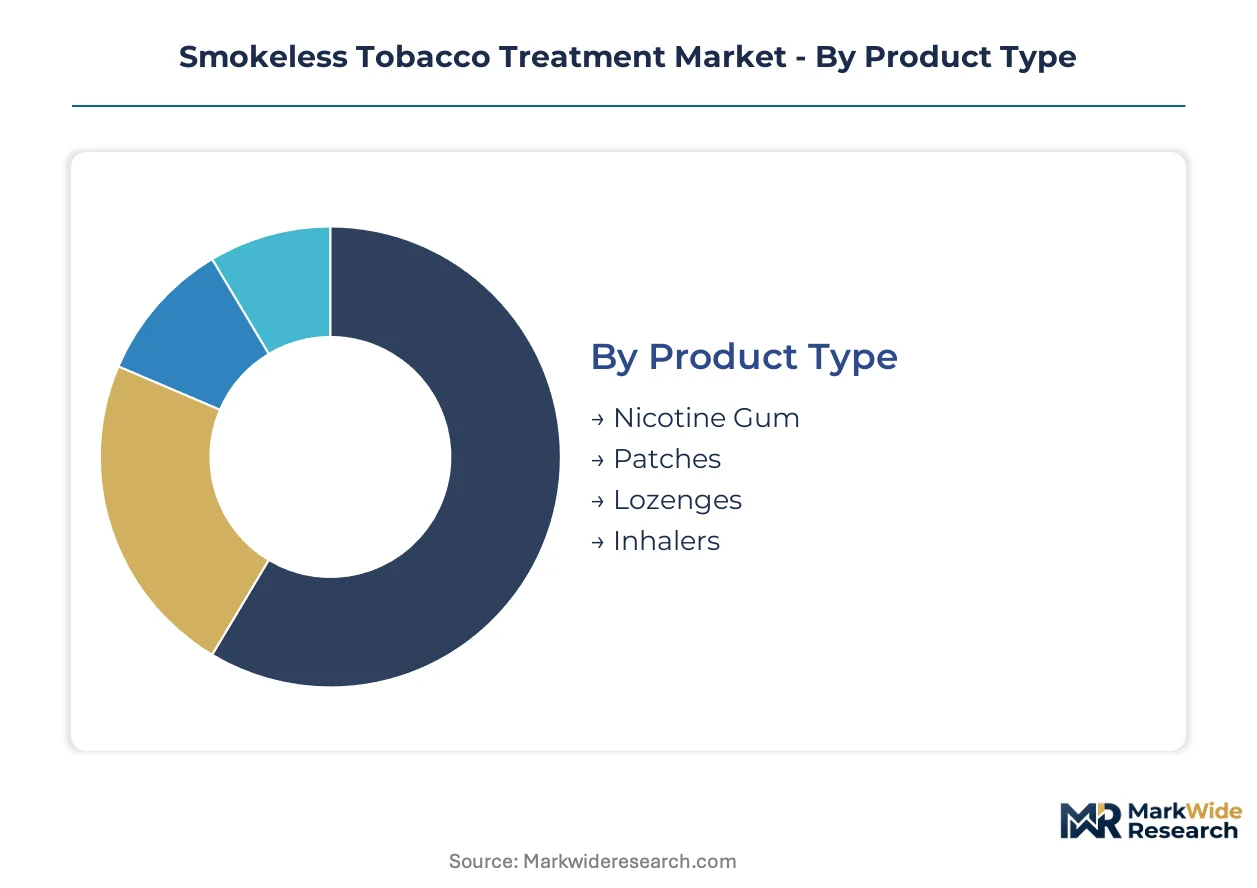
Segmentation in smokeless tobacco treatment reveals how product form factors, clinical settings, and delivery technologies compete for patient adherence and reimbursement dollars. Understanding these divisions exposes where pharmacy channels dominate versus where digital therapeutics are displacing traditional care models.
Product Type:
Cost tier determines patient out-of-pocket exposure and pharmacy benefit manager formulary positioning across nicotine replacement formats.
- Patches:Transdermal systems deliver controlled nicotine release over 16-24 hours through skin absorption. Demand concentrates in retail pharmacy chains across the United States where Medicaid coverage mandates drive bulk procurement for clinic dispensing programs. The format's maturity limits margin expansion despite high prescription volumes.
- Lozenges:Dissolvable oral formats provide discrete, on-demand nicotine delivery with flexible dosing intervals. Rehabilitation centers in states with expanded tobacco cessation benefits favor lozenges for their portability and patient compliance advantages during structured programs.
- Nicotine Gum:Chewing-based delivery combines mechanical oral substitution with buccal absorption, requiring specific technique instruction.
- Inhalers:Handheld devices simulate hand-to-mouth behavioral rituals while delivering metered nicotine aerosol.
Patches hold installed capacity. Lozenges is rotating up the share rankings.
Therapy Area:
Application focus separates medication-only interventions from combined protocols that insurers increasingly require for reimbursement eligibility.
- Pharmacotherapy:Drug-based interventions employ nicotine replacement or receptor partial agonists to manage physiological dependence. The FDA's Center for Drug Evaluation and Research regulates these as drug products with specific clinical trial endpoint requirements. United States demand clusters where state Medicaid programs cover combined pharmacotherapy and counseling.
- Behavioral Therapy:Structured counseling protocols address psychological triggers and habit formation through cognitive-behavioral techniques. Payer demands for documented quit outcomes impose cost structures that constrain program scalability despite reimbursement availability.
- Cessation:Comprehensive programs integrate pharmacological and behavioral components into unified treatment protocols.
- Counseling:Individual or group-based therapeutic support supplements medication regimens with motivational interviewing techniques.
Pharmacotherapy dominates prescription volume. Behavioral Therapy is climbing the fastest as value-based care contracts mandate outcome documentation.
Delivery Mode:
Patient convenience and discretion requirements drive technology selection between visible and hidden administration methods.
- Oral:Lozenges, gum, and dissolvable formats enable self-administration without medical supervision. United States retail pharmacies stock extensive oral format inventories where discrete use appeals to workplace and social settings.
- Transdermal:Patch-based systems require single daily application with sustained release kinetics.
- Inhalation:Aerosol or vapor delivery mimics behavioral aspects of smokeless tobacco use itself.
- Subcutaneous:Implant or injectable depot formulations provide extended-release nicotine or antagonist delivery.
Oral formats hold installed capacity. Inhalation is rotating up the share rankings.
End User:
Customer type determines reimbursement pathway complexity and whether treatment integrates into broader medical care or remains pharmacy-retail transactional.
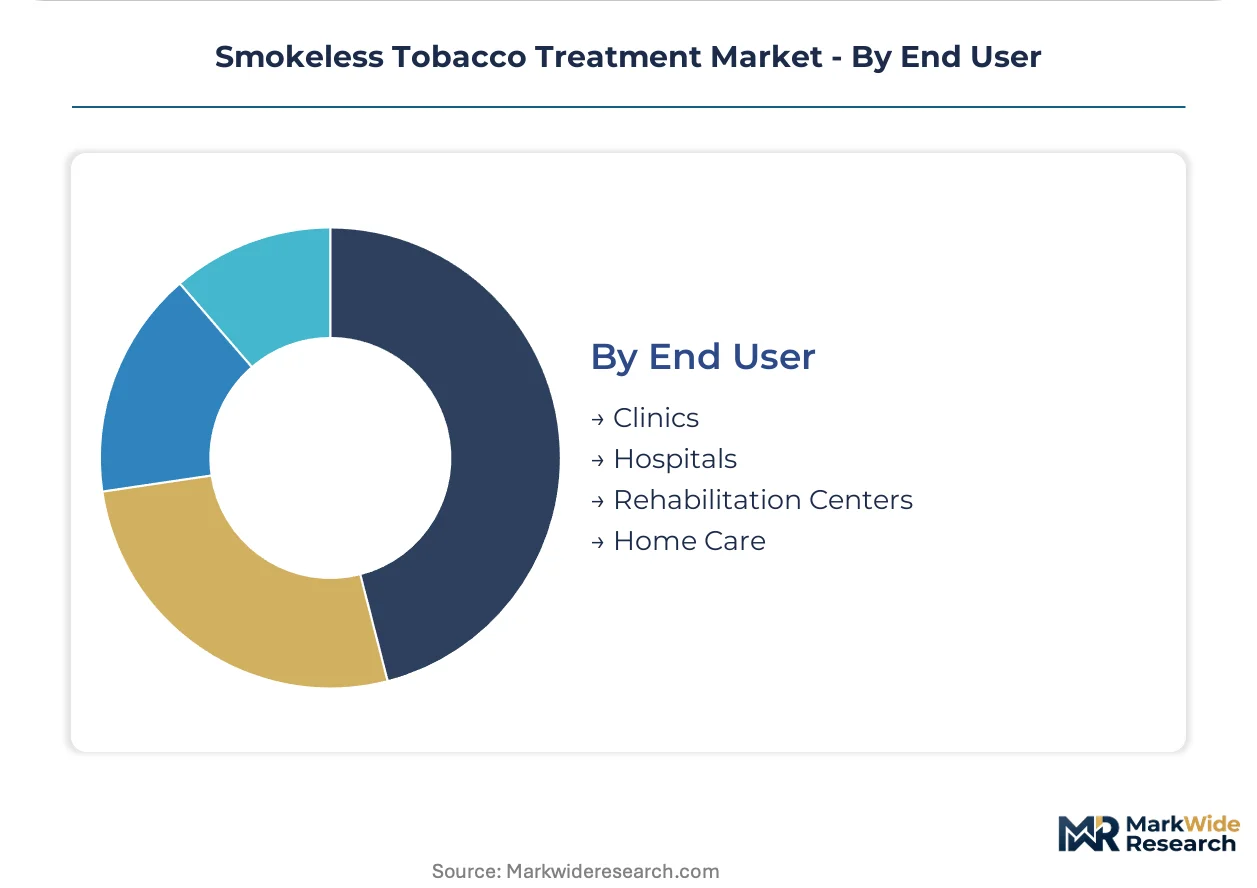
- Rehabilitation Centers:Dedicated facilities for substance use disorders increasingly incorporate smokeless tobacco cessation into comprehensive addiction treatment. United States facilities in states with Medicaid expansion leverage dedicated program funding to combine pharmacotherapy with structured counseling.
- Clinics:Outpatient settings provide primary care-integrated cessation services with electronic health record documentation.
- Hospitals:Inpatient settings initiate cessation during acute care episodes with post-discharge referral protocols.
- Home Care:Direct-to-consumer channels bypass clinical gatekeeping through telehealth and digital therapeutic platforms.
Clinics hold installed capacity. Rehabilitation Centers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rehabilitation centers and Medicaid-funded clinics concentrate demand in the United States, while European markets respond to harmonized cessation protocols under WHO frameworks. Emerging economies in Asia-Pacific show rising clinic-based adoption as national health programs expand tobacco dependence services.
United States
State-level Medicaid expansions drive clinic-based pharmacotherapy adoption across rehabilitation centers and outpatient settings. The FDA's Center for Drug Evaluation and Research regulates nicotine replacement therapies as drug products, determining prescription status and reimbursement pathways. Demand clusters in the Southeast and Midwest, where tobacco use prevalence sustains dedicated cessation program funding.
Germany
Statutory health insurance funds cover combined pharmacotherapy and behavioral interventions, expanding access through general practitioner networks. The EMA's centralized marketing authorization procedure streamlines product approval across EU member states. Industrial concentration centers on Frankfurt and Munich, where pharmaceutical distributors maintain extensive nicotine replacement therapy inventories.
United Kingdom
NHS Stop Smoking Services integrate smokeless tobacco cessation into broader tobacco dependence frameworks, driving demand in primary care settings. MHRA operates as the national regulator under EMA frameworks, with post-Brexit retained EU law maintaining aligned standards. London and Manchester host specialized addiction treatment centers with dedicated smokeless tobacco protocols.
India
National Tobacco Control Programme expansion increases clinic-based cessation service availability in tier-1 cities. CDSCO regulates nicotine replacement products under the Drugs and Cosmetics Act, with state-level pharmacy councils enforcing distribution standards. Demand concentrates in Maharashtra and Karnataka, where oral tobacco use prevalence supports specialized dependence programs.
Japan
PMDA's pharmaceutical approval pathways govern nicotine replacement therapy market access, with national health insurance covering approved cessation medications. METI's health promotion initiatives support workplace-based tobacco cessation programs. Tokyo and Osaka metropolitan areas concentrate specialized addiction clinics with integrated smokeless tobacco treatment protocols.
Smokeless Tobacco Treatment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across pharmacy, digital therapeutic, and clinical service delivery vectors. Market structure consolidates around established nicotine replacement therapy infrastructure, with fragmentation emerging in digital health and specialized pharmacotherapy segments. Three archetypes dominate: diversified pharmaceutical conglomerates with pharmacy network control, cytisine-based development specialists, and digital therapeutic platform operators. Competitive moves center on regulatory pathway navigation for novel delivery modes and electronic health record integration for provider workflow capture.
Within the diversified pharmaceutical tier, Pfizer Inc. and Johnson & Johnson Services Inc. anchor positions through established nicotine replacement therapy distribution infrastructure. Achieve Life Sciences occupies the specialized pharmacotherapy vector, exemplifying cytisine-based development focus for distinct smokeless tobacco withdrawal profiles. These three entities represent contrasting strategic postures: pharmacy channel dominance versus targeted receptor partial agonist innovation versus emerging digital-clinical integration.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson Services Inc. |
| Achieve Life Sciences |
| Axsome Therapeutics |
| NFL Biosciences |
| Embera NeuroTherapeutics Inc. |
| Currax Pharmaceuticals LLC |
| Omeros Corporation |
| Otsuka Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
New Jersey's pharmaceutical manufacturing corridor anchors nicotine replacement therapy production capacity, with Pfizer's established infrastructure and Johnson & Johnson's distribution networks translating concentrated supply into downstream pricing power across retail pharmacy chains. Medicaid procurement volumes in this cluster reinforce contract-based pricing stability, while digital therapeutic entrants from San Francisco and Boston disrupt traditional cost structures through software-based delivery models.
Pricing Analysis
Cost-plus contracts with Medicaid indexation dominate institutional procurement, locking in predictable margins for transdermal patch and oral format manufacturers. Price differentiation hinges on FDA approval tier and pharmacy benefit manager formulary placement, with branded formulations commanding premium positioning over authorized generics. Pricing pressure stems from digital therapeutic carve-outs that unbundle behavioral components from pharmacotherapy reimbursement. Rehabilitation centers exhibit highest price sensitivity due to fixed program budgets, while hospital systems demonstrate lowest sensitivity where bundled payment structures obscure line-item costs.
Supply Chain Analysis
Contract manufacturing concentrates among Patheon, Catalent, and Thermo Fisher Scientific, with specialized capacity for nicotine gum and lozenge production concentrated in Puerto Rico and Ireland facilities. Active pharmaceutical ingredient sourcing draws from India and Switzerland for nicotine base materials, while excipient supply rests on German and US chemical suppliers. Single-source vulnerability pervades cytisine API production, where Achieve Life Sciences maintains exclusive supplier relationships. Distribution runs through McKesson and Cardinal Health wholesale networks to retail pharmacy chains, with direct-to-consumer digital channels bypassing traditional wholesale entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Behavioral health workforce scarcity constrains combined pharmacotherapy-counseling program expansion, creating a structural bottleneck that limits scaled deployment of reimbursed cessation protocols despite favorable Medicaid coverage tailwinds.
For Market Incumbents: Entrench pharmacy channel control through exclusive formulary contracts with CVS Caremark and Express Scripts, while embedding nicotine replacement products into electronic health record prescribing workflows to capture clinician decision points. Digital therapeutic entrants threaten to disintermediate traditional distribution by seeking standalone reimbursement codes, making EHR integration the priority defensive lever for maintaining script volume. For New Entrants and Emerging Players: Build out cytisine-based pharmacotherapy development for smokeless tobacco-specific withdrawal profiles, targeting the underserved segment of oral tobacco users in Southeast US states where Medicaid expansion has created reimbursement availability without established treatment protocols. Telehealth-enabled remote monitoring partnerships with regional health systems offer the most penetrable go-to-market angle for bypassing entrenched pharmacy distribution. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical parents seeking to divest mature nicotine replacement therapy portfolios with declining R&D investment but stable cash generation. Long-term viability centers on digital-clinical integration capabilities rather than standalone pharmacotherapy assets. Watch FDA digital health guidance evolution as the signal indicating whether software-based interventions achieve drug-device combination classification, which would reshape competitive moats and capital requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Therapeutic FDA Submission | Positions app-based cessation for reimbursement parity with pharmacotherapy under evolving CDER guidance. |
| Electronic Health Record Integration | Captures clinician prescribing workflows at Cerner and Epic installations to secure quality metric documentation. |
| Cytisine Manufacturing Scale-Up | Addresses API supply bottleneck for specialized smokeless tobacco withdrawal pharmacotherapy development. |
| Medicaid State Plan Amendment | Expands tobacco cessation benefit coverage to include digital therapeutic interventions in expansion states. |
| Rehabilitation Center Partnership | Establishes dedicated smokeless tobacco dependence programs within substance use disorder treatment facilities. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with regulatory affairs leads at nicotine replacement therapy manufacturers, formulary directors at pharmacy benefit managers, and clinical program directors at rehabilitation centers; and secondary validation through FDA 510(k) filings, CMS state Medicaid director letters, ClinicalTrials.gov cessation study registrations, and WHO Framework Convention implementation reports. Bottom-up prescription volume modeling triangulated against top-down market sizing from pharmacy distribution data.
Forecast inputs considered therapy area segmentation across pharmacotherapy, behavioral therapy, and combined cessation protocols; delivery mode splits between oral, transdermal, and emerging inhalation formats; and end-user channel dynamics spanning clinics, rehabilitation centers, and direct-to-consumer digital platforms. CAGRs were derived from Medicaid enrollment projections, digital therapeutic adoption curves, and cytisine development timeline assumptions across the modeling period. Regulatory pathway complexity and behavioral health workforce availability served as key sensitivity variables.
Stress conditions across FDA digital health reclassification timing, state-level Medicaid reimbursement policy shifts, and cytisine clinical trial enrollment rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision if behavioral therapy documentation requirements intensify or digital therapeutic evidence standards tighten unexpectedly. Quarterly review of FDA guidance publication cadence and state Medicaid plan amendment filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Addiction Treatment
Drug Free Depression Treatment Market
Addiction Treatment
US Ketamine Clinics Market
Addiction Treatment
US Mental Health and Addiction Treatment Centers Market
Addiction Treatment
Alcohol Use Disorder Treatment Market
Addiction Treatment
Opioid Induced Constipation Treatment Market
Addiction Treatment
Nicotine De-Addiction Products Market
Addiction Treatment
Global Substance Use Disorder Treatment Market
Addiction Treatment
Methadone Market
Addiction Treatment
Opioid Use Disorder (OUD) Market
Addiction Treatment
Substance Abuse Treatment Market
Addiction Treatment
Opioid Use Disorder Treatment Market
Addiction Treatment
Opioid Withdrawal Treatment Market
Addiction Treatment
Cocaine Intoxication Treatment Market
Addiction Treatment
Global Addiction Treatment Market